
 Distributed Cloud System Market | 2026-2036
Distributed Cloud System Market Size, Share, and Industry Trends Forecast 2026-2036
Distributed Cloud System Market Analysis
Market Context
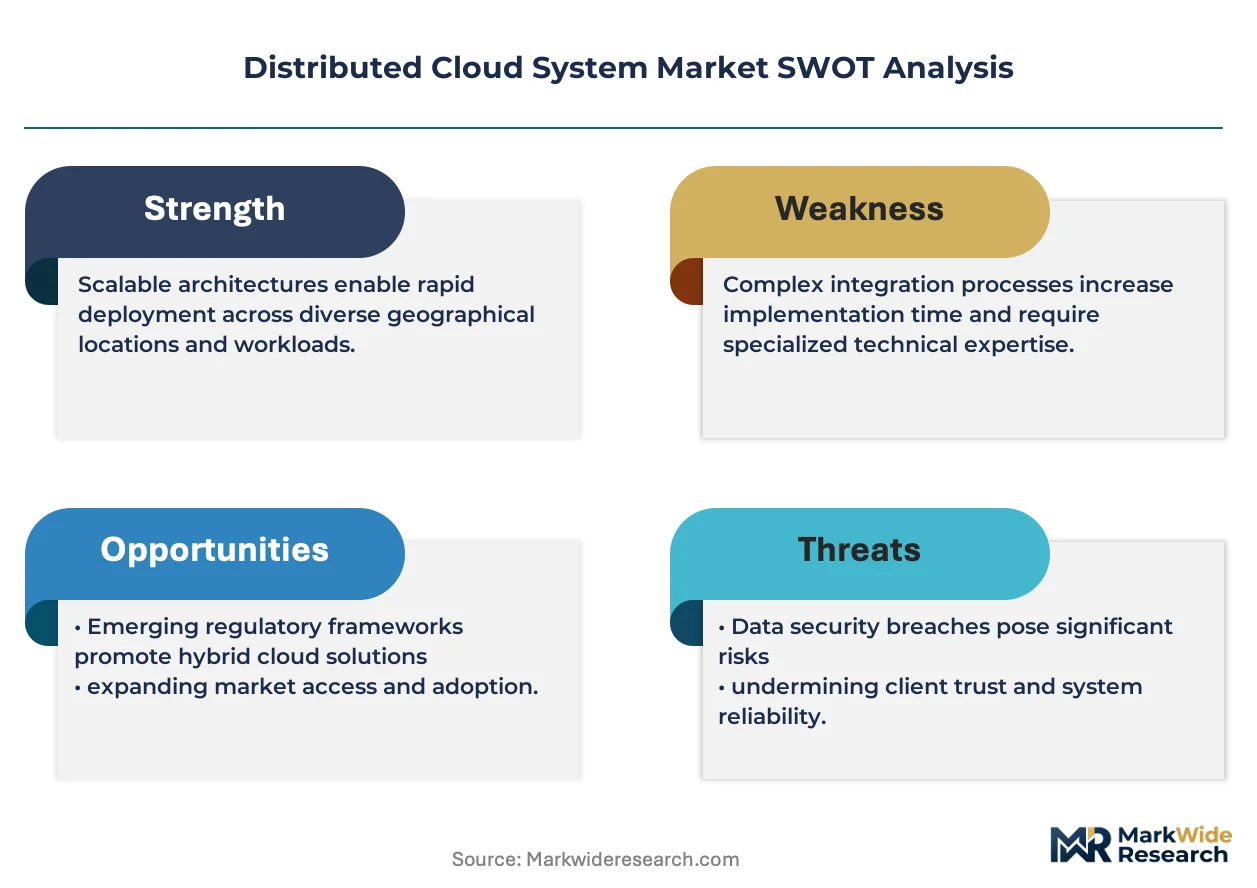
The capital-intensity divergence between hyperscale builders and software-centric operators is redrawing competitive boundaries in distributed cloud infrastructure. Amazon Web Services leverages its custom silicon and fiber backbone to sustain edge-node density across multiple continents. Microsoft Corporation anchors enterprise trust through Azure Arc's unified control plane, while Google LLC differentiates via planet-scale network engineering and carbon-aware compute scheduling.
Technical Definition and Segment Structure
A distributed cloud system deploys compute, storage, and networking resources across geographically dispersed nodes while maintaining centralized orchestration and unified policy management, typically operating with sub-100 millisecond latency thresholds between edge locations and regional hubs. Its primary commercial purpose is to place data processing and application workloads proximate to end-users, devices, and operational sites while preserving cloud-native operational models. Hybrid cloud deployments now capture the largest margin pools as enterprises straddle on-premises sovereignty requirements with burst capacity needs. Platform as a Service offerings represent the fastest-expanding service category because developers demand abstracted infrastructure for distributed application patterns. Content delivery applications mature into baseline expectations, while cloud gaming drives fresh capacity investments in GPU-dense edge nodes.
Regulatory Frame and Outlook
The EU GDPR and AI Act compel providers to implement data residency controls and algorithmic transparency audits within each operational jurisdiction, directly shaping node placement and software architecture decisions. The US FCC and state-level privacy frameworks add fragmented compliance obligations that increase operational complexity for cross-border service delivery. Stakeholders must monitor emerging sovereign cloud mandates and decide whether to pursue national operator partnerships or absorb direct infrastructure ownership in regulated territories.
Market Dynamics
Data sovereignty mandates are forcing distributed cloud providers to replicate control planes across national jurisdictions, multiplying infrastructure footprints while fragmenting operational economics. The EU AI Act's algorithmic audit requirements and China's data localization rules now dictate node placement decisions more than latency optimization alone.
Growth Catalysts
- EU AI Act compliance:Automated decision-making systems in financial services and healthcare now require jurisdictional data processing, creating mandatory demand for in-country edge nodes with transparent governance controls.
- Industrial automation clusters:German automotive and precision manufacturing facilities demand sub-50 millisecond latency for robotic coordination, driving dedicated edge deployments in Bavaria and Baden-Württemberg.
- 5G network slicing:Telecommunications operators are reserving dedicated bandwidth slices for enterprise distributed cloud traffic, enabling guaranteed quality-of-service contracts that were previously impossible.
Market Restraints
- Subsea cable concentration:Transatlantic and Asia-Pacific data routes depend on a handful of consortia-controlled fiber paths, creating single-point-of-failure risks for intercontinental distributed cloud synchronization.
- GPU supply constraints:AI inference workloads at the edge require specialized accelerators where foundry capacity remains captive to hyperscale reservation contracts, limiting edge node density expansion.
- GDPR extraterritorial friction:Cross-border data transfers to non-adequacy jurisdictions now require binding corporate rules or standard contractual clauses that add legal overhead and delay deployment timelines.
Strategic Opportunities
- Sovereign cloud partnerships:National telecom operators in France, Germany, and Italy seek technology transfers to build domestically controlled distributed cloud stacks, opening joint venture structures for infrastructure providers.
- Carbon-aware compute scheduling:Google's planet-scale network engineering demonstrates demand-shifting to renewable-heavy grids, creating premium pricing tiers for sustainability-conscious enterprise buyers.
- Cloud gaming edge nodes:GPU-dense micro data centers in urban proximity zones serve interactive streaming workloads that central clouds cannot support, representing a greenfield capacity category.
Industry Challenges
- Site acquisition velocity:Urban real estate scarcity and permitting delays in London, Frankfurt, and Amsterdam constrain the physical expansion timeline for latency-critical edge locations.
- Multi-cloud orchestration complexity:Enterprise IT teams struggle to maintain policy consistency across AWS, Azure, and Google Cloud distributed deployments, fragmenting security postures and operational visibility.
Report Scope
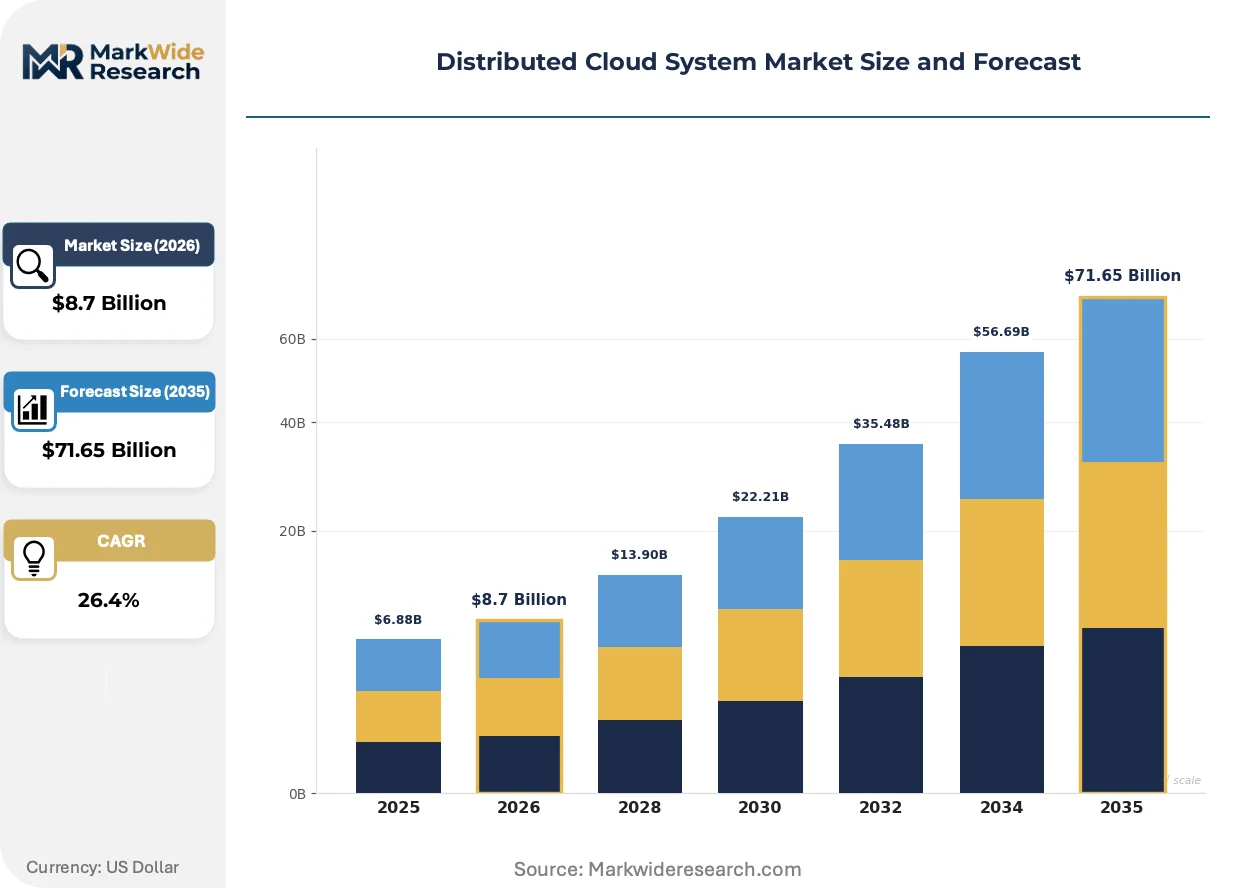
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distributed Cloud System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $71.65 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Data Storage Solutions End User: Enterprises, Government Agencies, Educational Institutions, Healthcare Providers Application: Data Backup, Disaster Recovery, Content Delivery, Cloud Gaming |
| Companies Covered | Amazon Web Services, Inc., Microsoft Corporation, Google LLC, IBM Corporation, Oracle Corporation, VMware, Inc., Salesforce, Inc., Alibaba Group, Rackspace Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distributed Cloud System Market Emerging Trajectories
Workload portability requirements are dissolving the boundaries between centralized hyperscale regions and distributed edge infrastructure, creating new architectural patterns that treat geographic dispersion as a software-defined property rather than a physical constraint.
Confidential computing using hardware-based trusted execution environments is fragmenting the security perimeter for sensitive workloads. Financial services firms in Switzerland and Singapore now process encrypted data within processor-secured enclaves at edge locations. This technology compresses the traditional trade-off between data locality and computational trust, enabling regulated industries to adopt distributed architectures previously blocked by compliance officers.
The EU CSRD's Scope 3 emissions disclosure rules now capture cloud infrastructure supply chains, forcing providers to document carbon intensity per workload-hour by geography. Data center operators in Ireland and the Netherlands face pressure to retire fossil-fuel backup systems. Renewable energy certificates and hourly carbon matching are becoming standard contract terms for enterprise procurement teams.
Enterprise buyers are consolidating vendor relationships around unified control planes that span on-premises, edge, and hyperscale resources. Azure Arc's Kubernetes-based management model now competes with AWS Outposts and Google Distributed Cloud for multi-environment orchestration contracts. Manufacturing and retail verticals in the United States and Germany show the strongest preference for single-pane operational consistency over best-of-breed point solutions.
Distributed Cloud System Market Segmentation
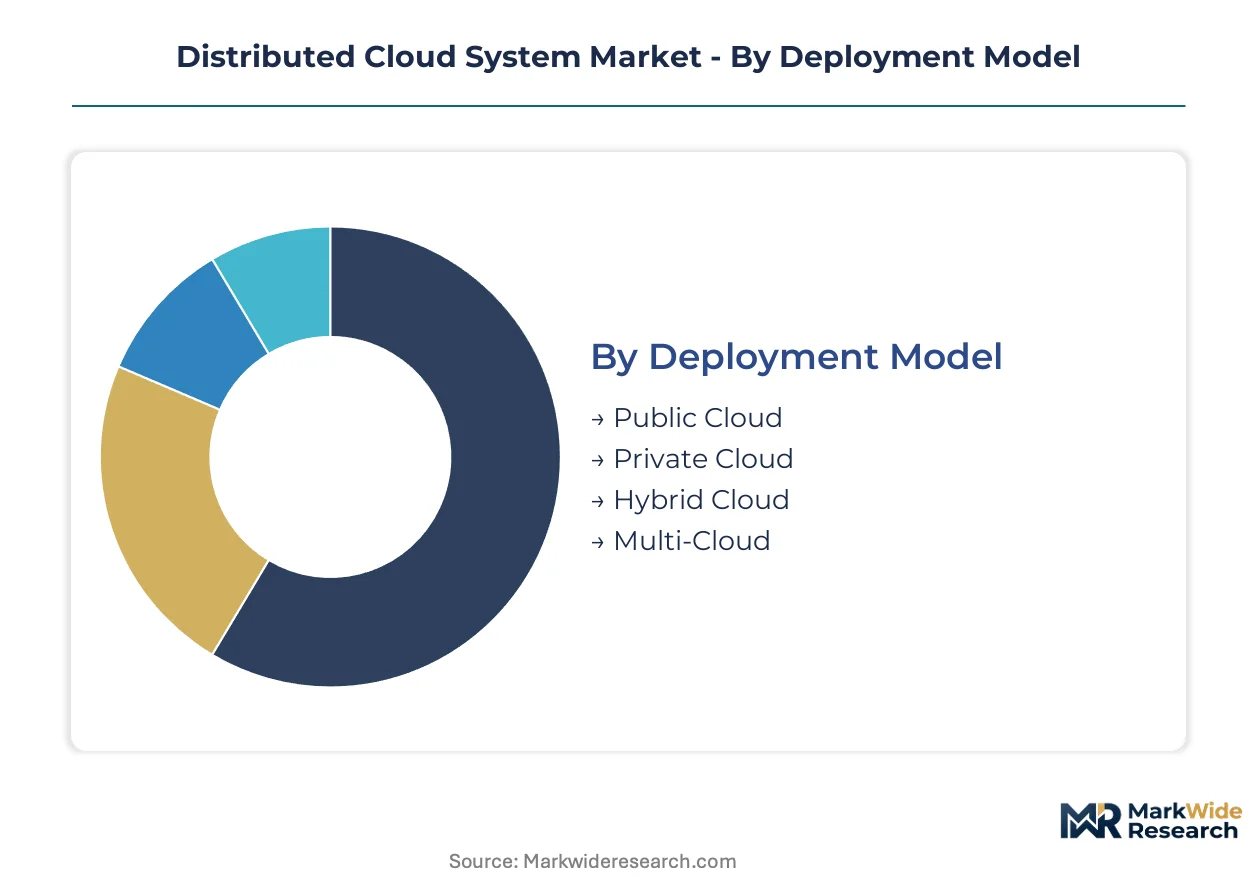
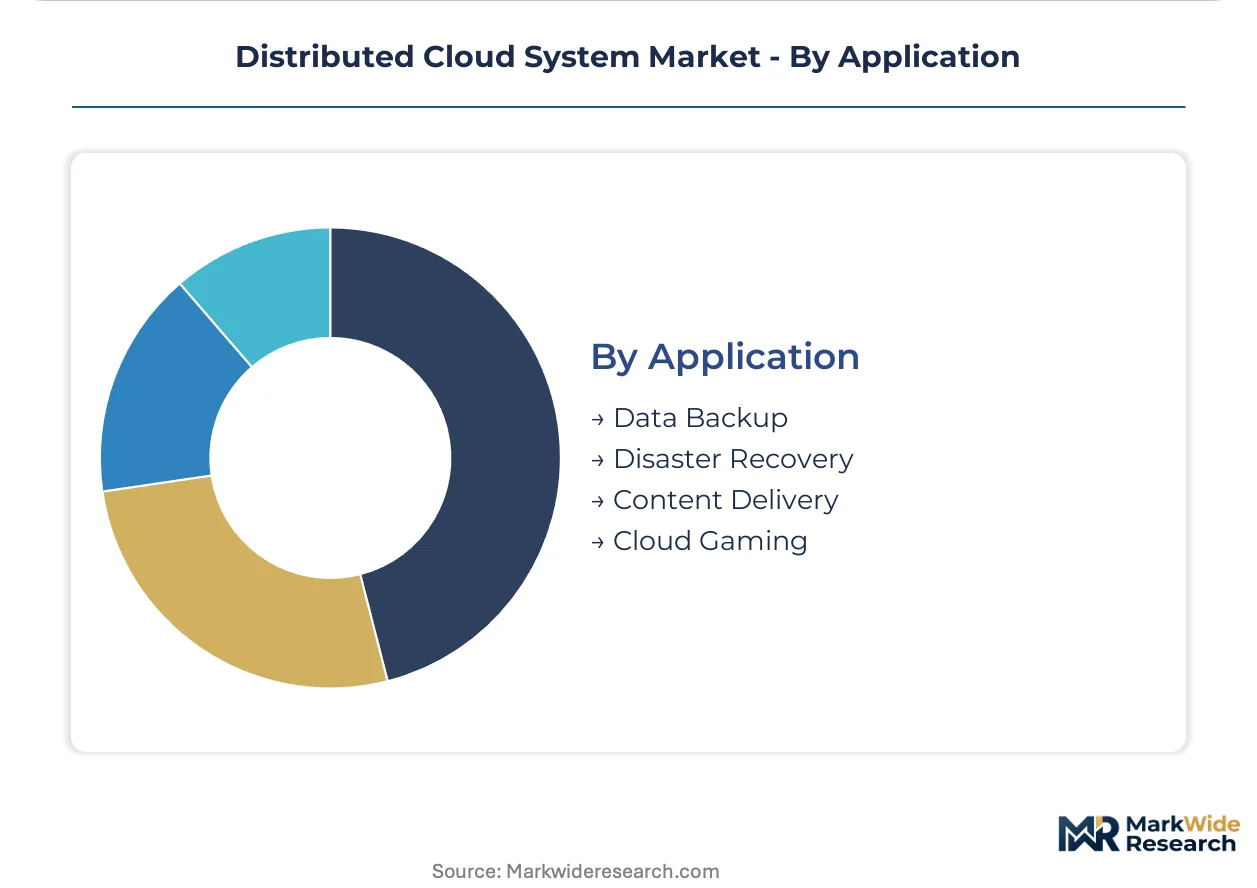
Distributed cloud architecture fragments across deployment topologies, service abstractions, and latency-sensitive applications. Procurement teams segment investments by sovereignty requirements, developer abstraction preferences, and end-user proximity mandates.
Deployment Model:
Margin pools concentrate where enterprises straddle regulatory compliance with burst elasticity needs, creating premium pricing for orchestration layers that unify disparate environments.
- Hybrid Cloud:Combines on-premises infrastructure with public cloud burst capacity through unified control planes. German automotive manufacturers and Swiss financial institutions deploy hybrid stacks to satisfy GDPR data residency while accessing hyperscale compute for training workloads.
- Multi-Cloud:Distributes workloads across AWS, Azure, and Google Cloud to avoid vendor lock-in and optimize price-performance by service type. Enterprise IT teams in the United States and United Kingdom prioritize multi-cloud strategies to negotiate contract terms and mitigate single-provider outage risks.
- Public Cloud:Shared infrastructure delivering economies of scale for standardized workloads without sovereignty constraints.
- Private Cloud:Dedicated resources serving defense contractors and national healthcare systems with classified or patient-critical data.
The dominant share belongs to Hybrid Cloud, while Multi-Cloud is closing the gap fastest.
Service Type:
Platform abstractions command expanding margins as developers demand Kubernetes-native tooling without infrastructure management overhead.
- Platform as a Service:Abstracts server provisioning, scaling, and patching through container orchestration and managed database services. Retail and logistics enterprises in the United States adopt PaaS for distributed order management systems requiring rapid deployment across hundreds of edge locations.
- Infrastructure as a Service:Delivers raw compute, storage, and networking resources through API-driven provisioning. IaaS retains stronghold in regulated industries where compliance teams mandate bare-metal visibility for audit trails.
- Software as a Service:End-user applications hosted entirely by vendors, reducing operational burden for mid-market enterprises.
- Data Storage Solutions:Object, block, and file storage services with geographic replication policies for disaster recovery.
Platform as a Service captures the steepest expansion trajectory as developer productivity becomes the primary procurement criterion.
End User:
Enterprise procurement volumes dwarf public sector contracts, though government tenders carry longer terms and stricter localization requirements.
- Enterprises:Multinational corporations operating distributed manufacturing, retail, and financial services networks. Manufacturing clusters in Bavaria and Baden-Württemberg drive dedicated edge deployments for robotic coordination with sub-50 millisecond latency guarantees.
- Government Agencies:National defense, tax administration, and critical infrastructure operators with classified data mandates. EU member states increasingly require sovereign cloud stacks with domestic control plane ownership.
- Educational Institutions:Research universities processing sensitive student records and high-performance computing workloads.
- Healthcare Providers:Hospital systems and telemedicine platforms subject to HIPAA in the United States and GDPR health data provisions in Europe.
Enterprises maintain the dominant share, while Government Agencies are expanding fastest under sovereign cloud mandates.
Application:
Latency-critical interactive workloads generate the highest infrastructure premiums per compute-hour.
- Cloud Gaming:GPU-dense micro data centers in urban proximity zones stream interactive video to low-latency endpoints. Telecom operators in Japan and South Korea reserve 5G network slices for cloud gaming traffic, enabling guaranteed quality-of-service contracts.
- Content Delivery:Caches static and dynamic content at edge nodes to reduce origin server load and improve page load times. Media streaming platforms deploy content delivery networks across Brazilian and Indian metropolitan zones to serve expanding subscriber bases.
- Data Backup:Geographic replication of enterprise datasets for ransomware recovery and archival compliance.
- Disaster Recovery:Automated failover systems maintaining application availability during regional outages.
Content Delivery holds the dominant share, while Cloud Gaming is gaining share fastest through GPU-edge capacity investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland demonstrate the lowest price elasticity, absorbing premium pricing for sub-50 millisecond latency guarantees and sovereign control planes. United States and Chinese enterprises negotiate aggressively on unit economics, prioritizing burst capacity over dedicated edge infrastructure.
United States
Financial services firms in New York and Chicago drive real-time transaction processing deployments with strict latency requirements. The FCC's network neutrality frameworks and state-level privacy laws fragment compliance obligations across operational jurisdictions. Silicon Valley hyperscalers anchor control plane development while Texas and Virginia host dense fiber interconnection hubs.
Germany
Industrial automation clusters in Bavaria and Baden-Württemberg mandate sub-50 millisecond latency for robotic coordination systems. The EU AI Act and GDPR compel providers to replicate governance controls within national borders, multiplying infrastructure footprints. Frankfurt anchors continental data exchange with dedicated edge nodes serving automotive and precision manufacturing facilities.
China
MIIT's data localization rules and dual carbon goals dictate node placement and energy sourcing decisions for domestic operators. Yangtze River Delta manufacturing hubs demand edge processing for smart factory implementations. Beijing and Shanghai concentrate hyperscale development with provincial governments mandating sovereign control plane ownership.
United Kingdom
London's financial services sector requires jurisdictional data processing for algorithmic trading and risk management systems. Post-Brexit regulatory divergence from EU frameworks creates parallel compliance obligations for cross-border service delivery. The Midlands and Scotland host emerging edge deployments serving manufacturing and energy sector clients.
Japan
METI's digital infrastructure investments support 5G network slicing for enterprise distributed cloud traffic with guaranteed quality-of-service. Tokyo and Osaka metropolitan zones concentrate cloud gaming and content delivery edge nodes. Kyushu and Tohoku regions develop renewable-powered facilities under national decarbonization mandates.
Distributed Cloud System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where custom silicon and fiber backbone investments separate hyperscale builders from software-centric orchestrators. The market consolidates around three strategic archetypes: vertically integrated infrastructure owners, control plane software specialists, and national sovereign cloud partners. Dominant competitive moves include strategic partnerships with telecommunications operators and geographic expansion through localized joint ventures.
Among hyperscale infrastructure owners, Amazon Web Services, Microsoft Corporation, and Google LLC occupy positions defined by capital intensity and network engineering differentiation. AWS exemplifies the custom silicon archetype with proprietary chip development and continental fiber deployments. Microsoft anchors enterprise trust through unified control plane architectures. Google represents planet-scale network engineering with carbon-aware compute scheduling capabilities.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Oracle Corporation |
| VMware, Inc. |
| Salesforce, Inc. |
| Alibaba Group |
| Rackspace Technology |
| Others |
Supply Flow & Price Mechanics
EU AI Act algorithmic audit requirements gate distributed cloud provider qualification while simultaneously enabling price premiums for sovereign-compliant deployments. Financial services and healthcare buyers in Germany and Switzerland absorb substantial premiums for jurisdictional data processing guarantees, whereas United States and Chinese enterprises negotiate aggressively on unit economics.
Pricing Analysis
Managed services and extended governance contracts drive lifetime value in distributed cloud procurement. Three-tier pricing structure across premium sovereign-compliant, standard multi-cloud, and economy public cloud levels stratifies the market. Pricing pressure stems from GPU supply constraints and hyperscale reservation contracts that limit edge node density expansion. Manufacturing clusters in Bavaria show the lowest price sensitivity, absorbing premiums for sub-50 millisecond latency guarantees, while mid-market retail buyers in the United States prioritize burst capacity over dedicated edge infrastructure.
Supply Chain Analysis
Transpacific container availability and port congestion at Los Angeles and Long Beach elevate inbound logistics costs for custom silicon and networking equipment. Supply concentrates in Taiwan for advanced semiconductors, South Korea for memory components, and China for server assembly and battery systems. Foundry capacity for AI accelerators rests on hyperscale reservation contracts that constrain independent edge node deployment. Tariff exposure on networking gear and single-source vulnerability for custom ASICs create structural supply chain risk. Distribution runs through hyperscale direct sales teams and telecommunications operator partnerships for sovereign cloud stacks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Distributed cloud infrastructure represents high-growth disruption as EU AI Act and GDPR mandates force jurisdictional replication of control planes across national borders. The regulatory inflection creates mandatory demand for sovereign-compliant edge deployments that legacy centralized architectures cannot satisfy.
For Market Incumbents: Compound fiber backbone density and custom silicon development to sustain edge-node expansion against emerging national operator partnerships. Prioritize Azure Arc-style unified control plane investments to defend enterprise trust against multi-cloud orchestration fragmentation. Absorb GPU supply constraints through hyperscale reservation contracts that limit competitor edge density expansion. For New Entrants and Emerging Players: Anchor in sovereign cloud joint ventures with French, German, and Italian national telecom operators seeking technology transfers. Target carbon-aware compute scheduling as a white-space premium tier for sustainability-conscious enterprise buyers in the Netherlands and Nordic markets. Lead with hourly carbon matching and renewable energy certificate bundling as a differentiated procurement angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across GPU-dense edge node deployments as foundry capacity constraints persist. Long-term viability favors vertically integrated infrastructure owners with captive silicon supply over software-centric orchestrators dependent on third-party hardware. Monitor hyperscale capex disclosure patterns for edge node buildout velocity as the primary inflection indicator for capacity-led pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Joint Venture | Enables EU AI Act compliance through domestic control plane ownership in France and Germany. |
| Custom Silicon Development | AWS Graviton-style processors reduce edge node power consumption and hyperscale dependency. |
| Carbon-Aware Compute Scheduling | Google's demand-shifting model captures premium pricing from CSRD-compliant enterprise buyers. |
| 5G Network Slicing Partnership | Telecom operator bandwidth reservations enable guaranteed quality-of-service contracts in Japan. |
| Confidential Computing Deployment | Hardware-secured enclaves unlock financial services workloads in Switzerland and Singapore. |
Methodological Framework
Desk research of hyperscaler capex disclosures, telecommunications regulatory filings, and EU legislative databases preceded structured interviews with cloud infrastructure executives, enterprise IT procurement officers, and sovereign cloud program directors. Primary fieldwork validated secondary projections against operational deployment timelines and edge node utilization rates. Bottom-up node count modeling and top-down enterprise spend analysis were triangulated against telecommunications operator 5G investment disclosures.
Variance decomposition across deployment model, service abstraction layer, end-user vertical, and latency-critical application category informed segment-level growth trajectories. The analytical framework projected demand across the analysis window using industrial automation cluster expansion, financial services real-time transaction processing requirements, and cloud gaming subscriber growth as primary inputs. CAGRs were derived from infrastructure investment run-rates and enterprise procurement pipeline visibility.
Underlying assumptions cover sustained GPU supply constraints, stable EU regulatory frameworks, and continued hyperscale edge node buildout, with deviation risk concentrated in subsea cable disruptions and sovereign cloud mandate acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Directory Services Software Market
Cloud Computing
North America Mobile Cloud Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
Philippines ICT Market
Cloud Computing
GPU Virtualization Market
Cloud Computing
Cloud IDE Market
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Global Cloud Computing Iaas in Life Science Market
Cloud Computing
Global Cloud High-Performance Computing Market
Cloud Computing
Cloud Applications Market
Cloud Computing
Cloud Backup Market
Cloud Computing
Hybrid Cloud Computing Market
Cloud Computing
Israel Cloud Computing Market
Cloud Computing
Canada Cloud Computing Market
Cloud Computing
Hyperscale Cloud Market
Cloud Computing
Public Cloud Application Services Market