

Bare Metal Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Bare Metal Cloud Market Insights
Modular server bundling is recalibrating procurement patterns across enterprise buyers. Oracle leverages its integrated hardware-software stack to anchor high-performance database workloads on dedicated silicon. Amazon Web Services sustains broad geographic coverage through its Nitro-based bare metal instances. IBM differentiates via mainframe-compatible bare metal offerings for regulated financial clients.
Bare metal cloud provisions single-tenant physical servers without virtualization overhead, delivering direct access to CPU, RAM, and NVMe storage with deterministic performance isolation. Its primary purpose serves workloads requiring kernel-level control, custom hypervisor deployment, or hardware security module integration. Hybrid cloud deployment configurations capture the largest margin pools as enterprises straddle on-premises and off-premises infrastructure. Artificial intelligence application segments are expanding fastest, driven by GPU-dense training clusters that bypass hypervisor tax. Colocation solution offerings remain mature, with pricing pressure from wholesale data center operators.
FCC regulations govern cross-border data transmission compliance for US-hosted bare metal workloads, while EU GDPR and the EU AI Act mandate data residency and algorithmic transparency for European deployments. ISO 27001 certification shapes vendor selection criteria for financial institutions and telecommunications providers. Stakeholders must evaluate sovereign cloud requirements against latency optimization when selecting regional deployment footprints.
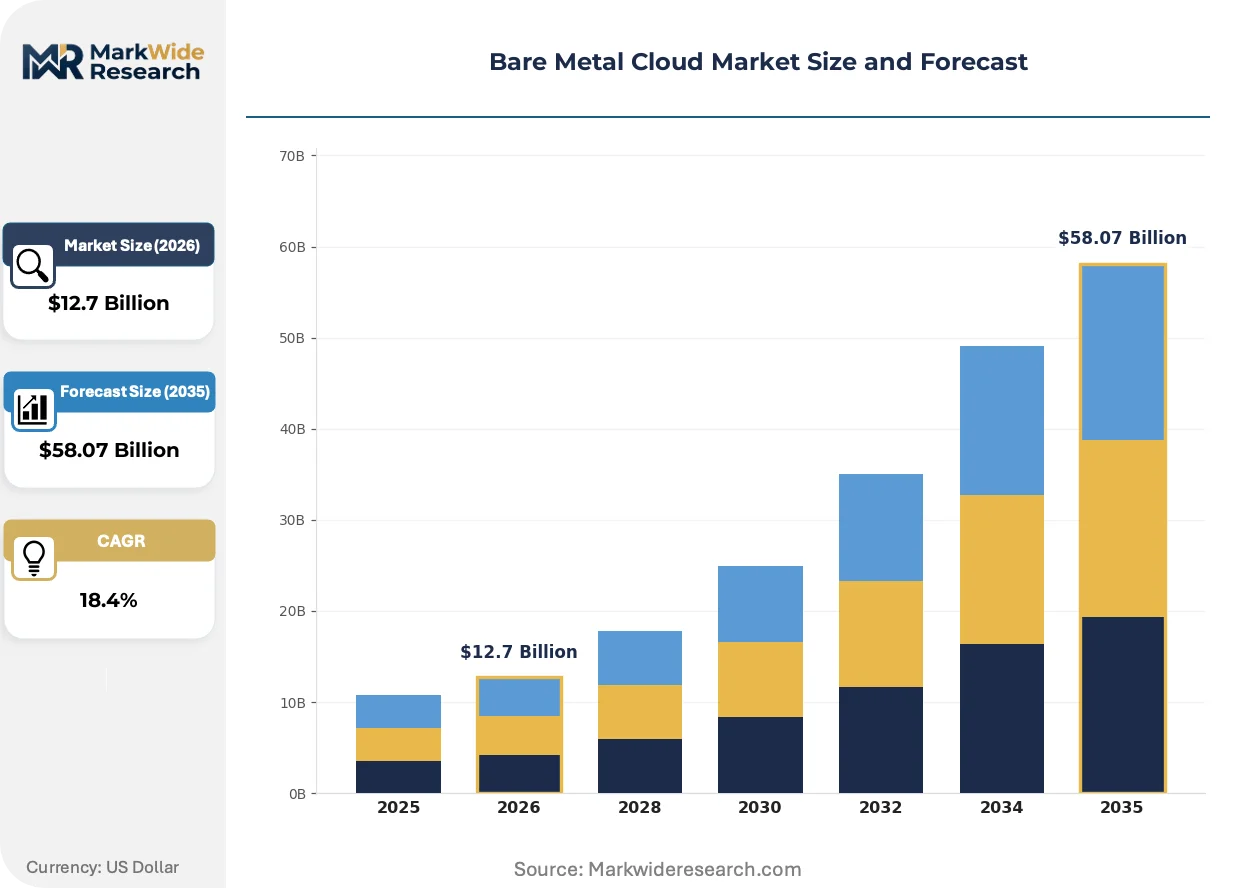
Market Dynamics
GPU-dense AI training clusters are compressing procurement cycles as financial services and sovereign cloud buyers bypass hypervisor layers for deterministic latency. The EU AI Act's algorithmic transparency mandates are forcing infrastructure decisions toward single-tenant physical deployments.
Growth Catalysts
- EU AI Act Compliance:European enterprises facing algorithmic audit requirements are migrating sensitive inference workloads to sovereign bare metal footprints that satisfy data residency and explainability mandates.
- NVMe-Over-Fabric Adoption:Low-latency storage networking is enabling disaggregated rack-scale architectures that pool GPU and NVMe resources across physical boundaries without virtualization overhead.
- Frankfurt Data Center Cluster:Germany's continental hub status is attracting hyperscale and colocation investment that expands bare metal capacity for latency-sensitive trading and AI workloads.
Market Restraints
- Copper and Silicon Supply Concentration:Taiwan-based foundry capacity constraints and Chilean copper mining disruptions are inflating server component lead times and bare metal provisioning costs.
- GDPR Cross-Border Friction:EU data localization requirements are fragmenting deployment footprints and preventing unified global capacity pools for multinational enterprises.
- Serverless Container Substitution:Managed Kubernetes and function-as-a-service platforms are capturing stateless workloads that previously considered dedicated physical infrastructure.
Strategic Opportunities
- India's PLI Scheme for Data Centers:Production-linked incentives for semiconductor and server manufacturing are creating domestic bare metal supply capacity for financial services and government workloads.
- Confidential Computing Convergence:Trusted execution environments and hardware security modules are merging with bare metal provisioning to serve regulated healthcare and defense applications.
- Edge Bare Metal Nodes:Distributed 5G radio access networks and autonomous vehicle infrastructure are creating demand for micro-data center deployments in secondary cities.
Industry Challenges
- Kernel-Level Security Expertise Gap:Shortage of engineers capable of hardening custom hypervisors and bare metal firmware is extending deployment timelines for regulated clients.
- ISO 27001 Certification Burden:Financial institutions require 12-18 month audit cycles for bare metal providers, compressing vendor switching flexibility and locking in incumbent relationships.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bare Metal Cloud Market Trends and Innovations
SmartNIC offloading and composable infrastructure are dissolving the boundary between physical server ownership and cloud-like consumption flexibility. These shifts are compressing the traditional tradeoff between control and convenience.
SmartNIC-based I/O virtualization is unifying network, storage, and security functions onto programmable silicon that sits between host CPU and physical resources. Financial trading firms and AI labs are adopting Nitro-style architectures at the fastest clip. This unification is collapsing the performance penalty that previously justified on-premises ownership over cloud bare metal.
The EU AI Act's risk-based classification system is mandating documentation trails for high-risk automated decision systems. European cloud providers are retrofitting bare metal offerings with integrated logging and audit APIs. German automotive and French healthcare AI deployments are driving the earliest compliance-driven infrastructure refreshes.
Consumption-based billing for dedicated physical resources is displacing traditional colocation leases with term commitments. Enterprise buyers are negotiating metered GPU-hour contracts that preserve capital flexibility. This pattern is most pronounced in Singapore and London financial services clusters where trading desk budgets face quarterly scrutiny.
Bare Metal Cloud Market Segmentation
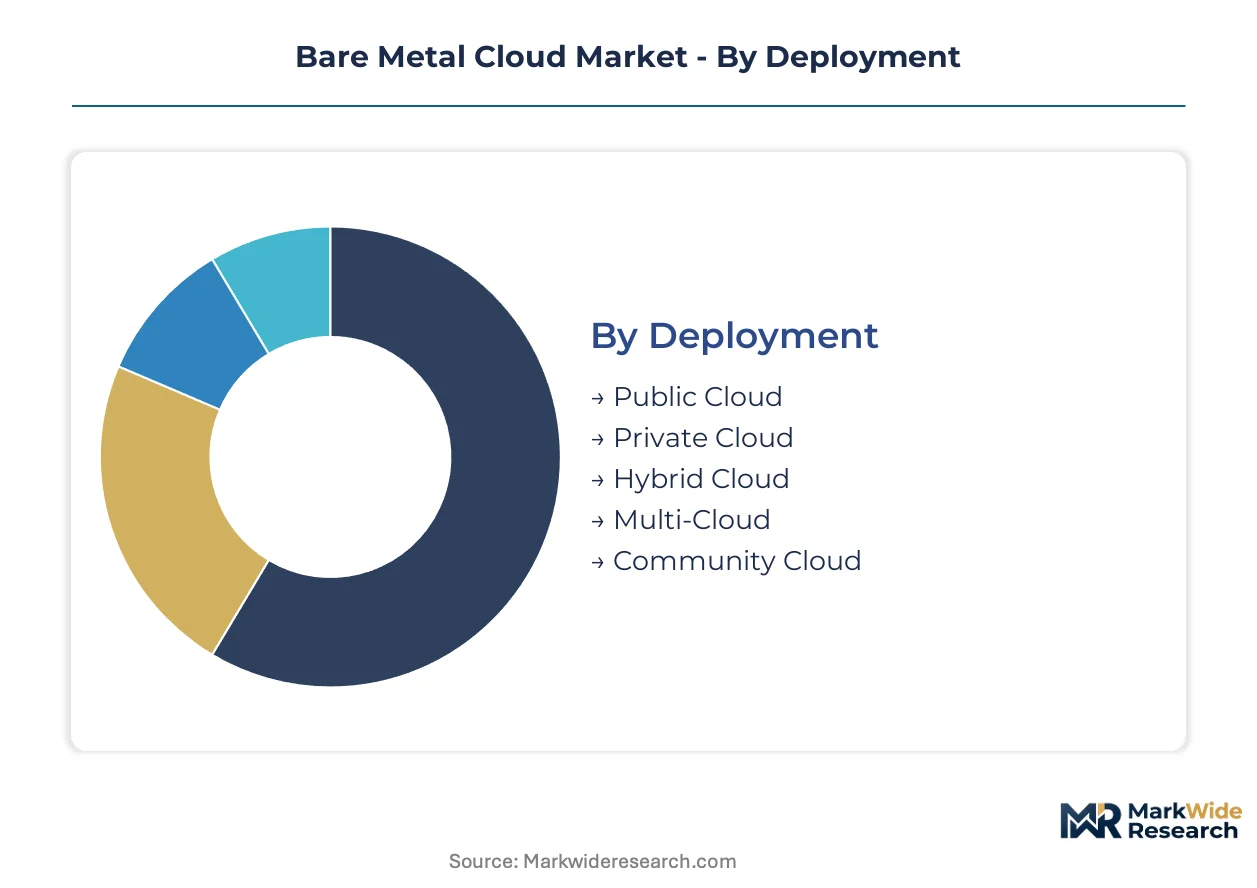
Bare metal cloud procurement patterns diverge sharply across deployment architectures and workload types. Financial institutions and AI labs drive specification requirements that reshape vendor product roadmaps.
Deployment:
Physical server provisioning models range from fully shared infrastructure to sovereign single-tenant environments.
- Public Cloud:Shared data center facilities deliver on-demand physical server allocation without long-term capital commitment. Demand concentrates among startups and mid-market enterprises in Singapore and London seeking GPU-hour flexibility for quarterly budget cycles.
- Private Cloud:Dedicated data center suites with exclusive power, cooling, and network infrastructure serve regulated workloads. German automotive manufacturers and French healthcare AI deployments are driving compliance-driven infrastructure refreshes under EU AI Act mandates.
- Hybrid Cloud:Interconnected on-premises and off-premises bare metal pools enable workload portability across security boundaries. Financial trading firms in Frankfurt leverage this architecture for latency-sensitive order execution.
- Multi-Cloud:Orchestrated bare metal deployments across independent provider footprints reduce vendor lock-in. Sovereign cloud buyers in Europe fragment workloads across domestic and regional providers to satisfy GDPR cross-border constraints.
- Community Cloud:Shared infrastructure serving specific industry verticals with common compliance requirements. Research consortia and defense contractors utilize these deployments for classified collaborative computing.
Mature deployment sits with Hybrid Cloud. Newer deployment is concentrated in Multi-Cloud as fragmentation accelerates.
Solution Offering:
Service layer abstractions determine operational responsibility boundaries and customization depth.
- Infrastructure as a Service:Raw compute, storage, and networking resources with full customer control over operating system and middleware. GPU-dense AI training clusters in financial services and sovereign cloud segments bypass hypervisor layers for deterministic latency.
- Platform as a Service:Pre-configured runtime environments with automated patching and scaling. Managed Kubernetes on bare metal silicon is displacing self-managed container orchestration for stateless workloads.
- Software as a Service:Application-level consumption of bare metal performance without infrastructure management. Database-as-a-service offerings from Oracle anchor high-performance transactional workloads on dedicated silicon.
- Managed Services:Vendor-operated bare metal with customer workload isolation and SLAs. ISO 27001 certification requirements from financial institutions lock in 12-18 month vendor relationships.
- Colocation:Customer-owned equipment in third-party data center facilities with power and cross-connect provisioning. Wholesale data center operators in Frankfurt and Singapore are compressing pricing through scale economies.
Revenue concentration favors Infrastructure as a Service. Margin expansion is strongest in Managed Services.
Application:
Workload characteristics dictate server density, network topology, and storage architecture specifications.
- Big Data Analytics:Distributed processing frameworks requiring high-memory nodes and fast interconnects. NVMe-over-Fabric adoption enables disaggregated rack-scale architectures that pool resources without virtualization overhead.
- High Performance Computing:Tightly coupled parallel workloads with low-latency MPI communication. Research organizations in Germany and France deploy these clusters for climate modeling and pharmaceutical simulation.
- Content Delivery:Geographically distributed edge nodes serving cached media with minimal origin round-trips. SmartNIC offloading unifies network, storage, and security functions onto programmable silicon.
- Web Hosting:Standardized server configurations for traffic-serving applications with variable load patterns. Serverless container substitution is capturing stateless workloads that previously considered dedicated infrastructure.
- Artificial Intelligence:GPU-dense training and inference clusters requiring direct hardware access. EU AI Act algorithmic transparency mandates are forcing infrastructure decisions toward single-tenant physical deployments.
Volume leadership belongs to Web Hosting. Steepest expansion trajectory is in Artificial Intelligence.
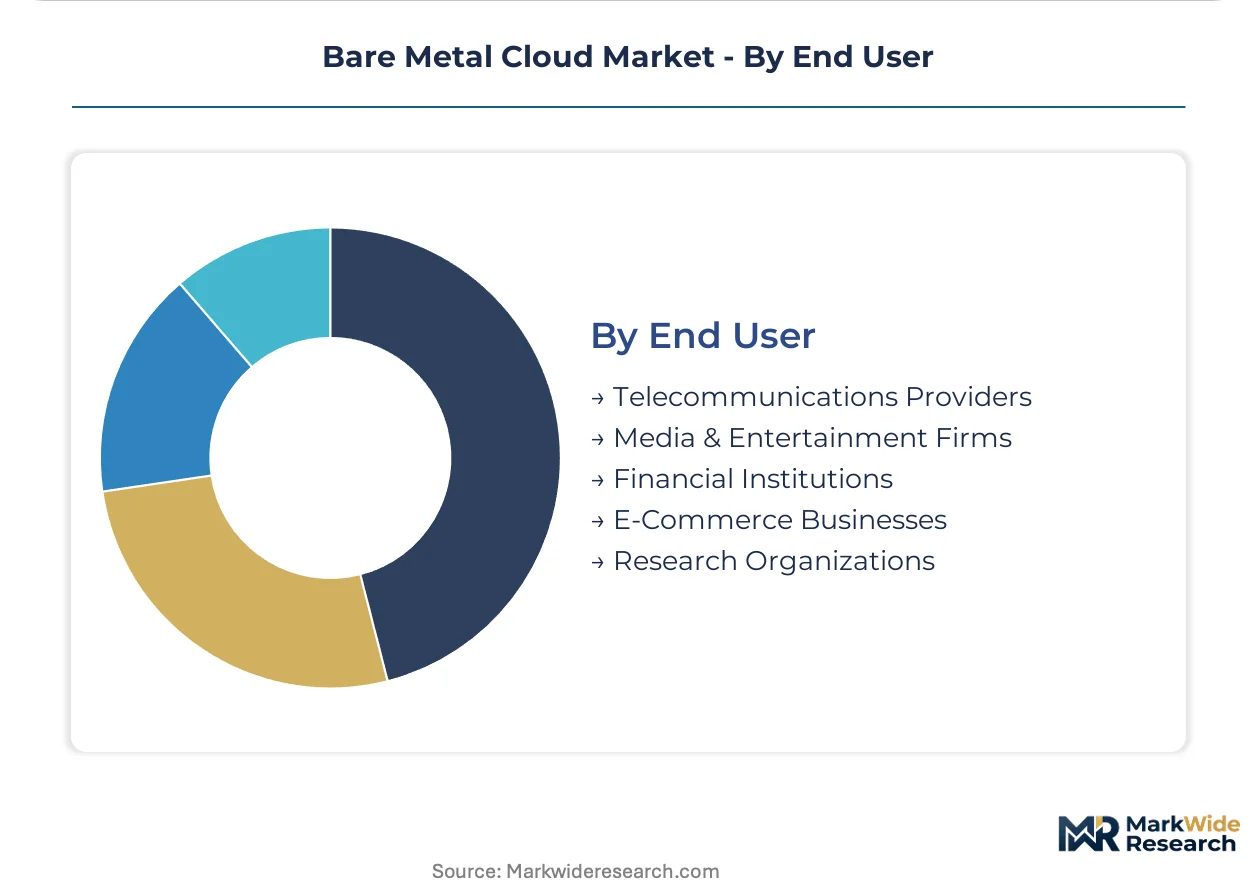
End User:
Industry verticals impose distinct security, latency, and compliance requirements on bare metal specifications.
- Telecommunications Providers:5G core network functions and edge computing infrastructure with carrier-grade reliability. India's PLI scheme for data centers is creating domestic supply capacity for these workloads.
- Media & Entertainment Firms:Rendering farms and real-time streaming infrastructure with burst capacity needs. Consumption-based billing for GPU-hour contracts preserves capital flexibility for quarterly budget scrutiny.
- Financial Institutions:Latency-sensitive trading systems and risk analytics with regulatory audit trails. FCC regulations govern cross-border data transmission compliance for US-hosted workloads.
- E-Commerce Businesses:Transaction processing and recommendation engines with seasonal demand spikes. Confidential computing convergence with trusted execution environments serves payment security requirements.
- Research Organizations:Grant-funded computational science with intermittent supercomputing needs. Edge bare metal nodes in secondary cities support distributed scientific instrumentation networks.
Procurement maturity is highest among Financial Institutions. Fastest budget growth is occurring in Research Organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bare metal cloud infrastructure concentrates production in Taiwan and South Korea, while consumption clusters in Germany, the United States, and Singapore. This geographic split creates supply chain exposure for latency-sensitive workloads.
United States
Financial institutions in New York and Chicago drive demand for sub-millisecond trading infrastructure. FCC regulations govern cross-border data transmission compliance for bare metal workloads hosted domestically. Northern Virginia's data center corridor anchors continental capacity expansion for AI training clusters.
Germany
Automotive manufacturers and healthcare AI deployers require sovereign infrastructure under EU AI Act mandates. GDPR data localization requirements fragment deployment footprints across federal states. Frankfurt's Rhine-Main cluster hosts the densest bare metal concentration for continental trading workloads.
United Kingdom
London financial services firms procure GPU-dense instances for risk analytics and algorithmic trading. The UK Information Commissioner's Office enforces data residency standards post-Brexit. Slough and Docklands data center zones attract hyperscale investment for bare metal expansion.
Singapore
Quantitative hedge funds and commodity trading houses seek deterministic latency for Asia-Pacific market access. The Monetary Authority of Singapore imposes operational resilience requirements on critical financial infrastructure. One-North and Tanjong Kling industrial parks concentrate server deployment for regional workloads.
India
Domestic banks and securities exchanges are migrating core systems to physical servers under RBI data localization directives. The PLI scheme for data centers incentivizes domestic server manufacturing and assembly. Mumbai's BKC and Hyderabad's HITEC City emerge as primary bare metal deployment zones.
Bare Metal Cloud Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the bare metal cloud landscape. Hyperscale cloud divisions of technology conglomerates leverage existing data center footprints and enterprise relationships. Independent infrastructure providers differentiate through geographic specialization and compliance certifications. Competitive moves center on sovereign cloud partnerships and GPU cluster capacity expansion.
Within the integrated technology tier, Oracle and IBM exemplify hardware-software stack convergence. Oracle leverages its database heritage to anchor high-performance transactional workloads on dedicated silicon. IBM occupies a position serving regulated financial clients through mainframe-compatible bare metal offerings. Among independent infrastructure specialists, Equinix represents the interconnection-centric archetype with global colocation integration.
| Leading Market Players |
|---|
| Oracle |
| Amazon Web Services |
| Microsoft |
| IBM |
| Dell Technologies |
| Equinix |
| OVHcloud |
| Vultr |
| Scaleway |
| Others |
Pricing and Supply Chain Analysis
Copper pricing volatility from Chilean mining disruptions cascades through server motherboard fabrication into bare metal cloud provisioning tiers, compressing margins for mid-market providers while hyperscalers absorb shocks through captive supply agreements with Taiwanese foundries.
Pricing Analysis
Margin tightening in the mid-tier provider segment reflects Taiwan-based foundry capacity constraints and extended GPU component lead times. Three-tier pricing structure across premium certified, standard enterprise, and economy developer levels separates ISO 27001-audited financial services deployments from unregulated startup workloads. Cost compression accelerates as wholesale data center operators in Frankfurt and Singapore scale rack-density economics. Financial institutions exhibit lowest price sensitivity due to compliance lock-in, while e-commerce businesses drive hardest bargain negotiation for seasonal burst capacity.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Singapore, and Northern Virginia anchor hub-and-spoke fulfillment patterns for bare metal server deployment. Supply concentrates in Taiwan for advanced silicon, South Korea for memory components, and China for power supply units and chassis assembly. Raw material dependencies span Chilean copper, Mongolian rare earth elements, and Japanese high-purity silicon substrates. Single-source vulnerability around TSMC foundry capacity creates systemic risk for GPU-dense AI training clusters. Distribution runs through hyperscale-owned captive logistics networks and third-party electronics distributors serving regional colocation markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bare metal cloud infrastructure operates under acute foundry capacity constraints, with Taiwan-based semiconductor fabrication bottlenecks propping pricing power for providers with secured wafer allocations.
For Market Incumbents: To counter serverless container substitution threatening stateless workload capture, anchor defensive positioning through backward integration into SmartNIC silicon design and exclusive GPU cluster reservations in the Frankfurt Rhine-Main corridor. Prioritize ISO 27001 certification maintenance to extend financial institution lock-in against emerging sovereign cloud competitors. For New Entrants and Emerging Players: Launch via edge bare metal node deployments in secondary Indian cities under RBI data localization directives, targeting domestic bank core system migrations underserved by hyperscale presence. Penetrate research organization segments through grant-funded consumption-based billing models that bypass incumbent term commitment structures. For Investors and Strategic Acquirers: India's PLI scheme disbursement acceleration is the leading indicator that domestic assembly capacity will reshape Asia-Pacific supply economics within the coming decade. Position acquisition screening toward mid-scale providers with established sovereign cloud partnerships and confidential computing hardware integration capabilities. Monitor EU AI Act audit trail mandate enforcement as the signal for compliance-driven infrastructure refresh spending inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Integration | Trusted execution environment deployment captures regulated healthcare and defense contract flows. |
| GPU Cluster Capacity Expansion | Dedicated NVIDIA H100 reservations in Frankfurt satisfy EU AI Act algorithmic transparency mandates. |
| Sovereign Cloud Partnership | German automotive manufacturer data residency requirements drive private cloud suite commitments. |
| SmartNIC Architecture Adoption | Nitro-style offloading collapses performance penalties justifying on-premises ownership retention. |
| Edge Node Geographic Extension | 5G radio access network micro-data centers penetrate secondary city autonomous vehicle infrastructure. |
Research Methodology
Hyperscaler capex disclosures, SEC 10-K infrastructure segment filings, and EU regulatory compliance databases formed the secondary backbone, cross-referenced with primary interviews involving data center procurement officers, cloud platform engineers, financial services infrastructure leads, and colocation sales directors. Bottom-up triangulation against top-down semiconductor trade flow analysis validated deployment volume estimates across the analysis window.
Bottom-up modeling of server unit economics and rack-density pricing combined with top-down absorption of foundry capacity allocation data. Segmentation dimensions spanned deployment architecture, solution offering tier, application workload type, and regional regulatory cluster. CAGRs derived from fitted adoption curves incorporating GPU-hour consumption trajectories and sovereign cloud mandate implementation schedules.
Taiwan foundry disruption events, EU AI Act enforcement timing, and copper commodity price spikes are the dominant revision risks that could compress or extend projected capacity expansion timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.