
 Cloud and Data Center Transformation Market | 2026-2036
Cloud and Data Center Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud and Data Center Transformation Market Insights
Hyperscaler facility construction across Northern Virginia, Oregon, and Iowa is shifting capital allocation patterns across the entire infrastructure supply chain. Amazon Web Services leverages its regional fiber backbone and power interconnect agreements to sustain deployment velocity at scale. Microsoft Azure anchors enterprise hybrid demand through direct sovereign cloud partnerships with European governments. Schneider Electric differentiates on integrated power and cooling architectures that reduce facility-level energy intensity.
Cloud and data center transformation encompasses the architectural modernization, workload migration, and infrastructure automation required to transition enterprise IT from legacy on-premises systems to distributed, software-defined environments, typically involving virtualization layers, container orchestration platforms, and API-driven resource provisioning with sub-millisecond latency targets for edge nodes. The primary purpose is enabling elastic compute consumption, operational cost optimization, and resilience against localized hardware failures. Migration services and managed services together capture the majority of professional services margin pools as enterprises lack internal cloud-native expertise. Hybrid cloud and multi-cloud deployment models are expanding fastest as organizations distribute workloads across public hyperscalers and private facilities to satisfy data residency constraints.
Regulators in the United States enforce SEC climate disclosure rules and FERC interconnection standards that shape facility siting timelines and capital recovery mechanisms. European operators navigate ECHA REACH chemical restrictions on cooling fluids alongside EU Green Deal energy efficiency benchmarks that mandate power usage effectiveness thresholds. Stakeholders must monitor evolving sovereign data localization requirements and carbon accounting standards that will determine which facility architectures qualify for enterprise and government procurement.
Market Dynamics
Hyperscaler facility construction timelines now determine enterprise cloud adoption velocity, as power interconnection queues and fiber backbone deployment create multi-year bottlenecks that compress migration windows for financial services and sovereign cloud customers.
Growth Catalysts
- Operational resilience mandates:Financial services regulators in the United States and European Union now require geographically distributed infrastructure, forcing banks and insurers to accelerate multi-region deployments.
- Container orchestration platforms:Kubernetes-native workload portability reduces vendor lock-in friction, enabling enterprises to distribute compute across hyperscalers and private facilities without re-architecture.
- Liquid cooling adoption:Power density requirements above 50kW per rack in Northern Virginia and Singapore facilities are driving immersion and direct-to-chip cooling retrofits that extend facility lifespan.
Market Restraints
- Power interconnection queues:FERC Order 2023 interconnection reforms have not cleared backlogs in PJM and ERCOT territories, delaying facility energization by 18-36 months.
- Fluorinated gas restrictions:ECHA REACH and EU F-Gas Regulation are phasing out conventional refrigerants, forcing cooling system redesigns and refrigerant reclamation infrastructure investment.
- Specialized labor scarcity:Electrical trades and fiber splicing expertise concentrates in legacy telecom markets, creating wage inflation in secondary data center clusters.
Strategic Opportunities
- Edge node densification:Sub-10ms latency requirements for autonomous systems and industrial IoT are creating distributed micro-facility demand in Germany, Japan, and South Korea manufacturing corridors.
- Carbon-aware compute scheduling:EU Green Deal carbon accounting standards create procurement preference for facilities with hourly-matched renewable energy, differentiating new builds with on-site solar and battery storage.
- Sovereign cloud partnerships:National governments in France, Germany, and the Netherlands are mandating domestic data residency for public sector workloads, requiring localized facility architectures.
Industry Challenges
- Legacy system integration:Mainframe and AS/400 workload refactoring requires specialized COBOL and RPG expertise that commands premium contracting rates and extends migration timelines.
- Skills certification gaps:Multi-cloud architecture and platform engineering certifications lag demand, forcing enterprises to rely on managed service providers for Kubernetes and Terraform implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud and Data Center Transformation Market |
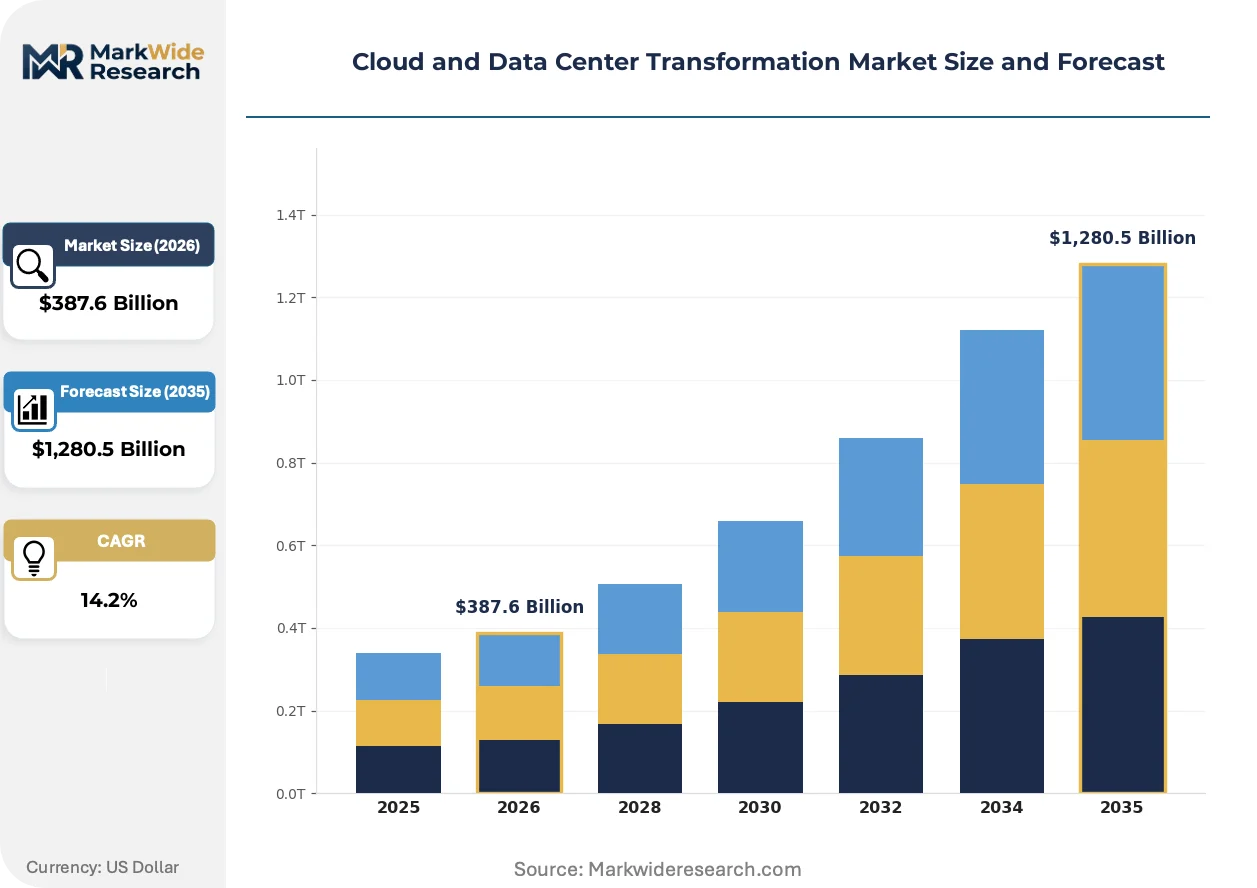
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,280.5 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Managed Services, Migration Services, Infrastructure Deployment Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Technology: Virtualization, Containers, Serverless Computing, Edge Computing End User: SMBs, Enterprises, Government, Telecommunications |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud Platform, IBM Corporation, Cisco Systems, Dell Technologies, Schneider Electric, Equinix, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud and Data Center Transformation Market Trends and Innovations
Software-defined infrastructure is collapsing traditional hardware refresh cycles, as programmable power distribution and composable compute enable facility operators to reconfigure capacity without physical intervention.
Prefabricated modular data centers are modularizing facility construction by shifting assembly from job sites to factory floors. Colocation operators in Northern Virginia and Frankfurt are deploying standardized 2-8MW power modules that compress commissioning from 18 months to 6 months. This compression is modularizing capital deployment, allowing hyperscalers to match facility capacity to customer commitments with reduced stranded asset risk.
The EU AI Act and CSRD are mandating algorithmic transparency and embodied carbon disclosure for high-risk AI systems and large facilities. European operators must now document training data provenance and facility construction emissions, creating compliance infrastructure costs that favor established providers with dedicated sustainability teams. Financial services and healthcare verticals face the steepest documentation burdens, driving procurement toward certified sovereign cloud offerings.
Consumption-based pricing models are displacing traditional colocation leases across enterprise segments. Retail and logistics buyers now prefer metered compute and storage with automatic scaling triggers rather than fixed-cage commitments. This preference shift is most visible in United States e-commerce and last-mile delivery operations, where seasonal demand volatility makes committed infrastructure uneconomical.
Cloud and Data Center Transformation Market Segmentation
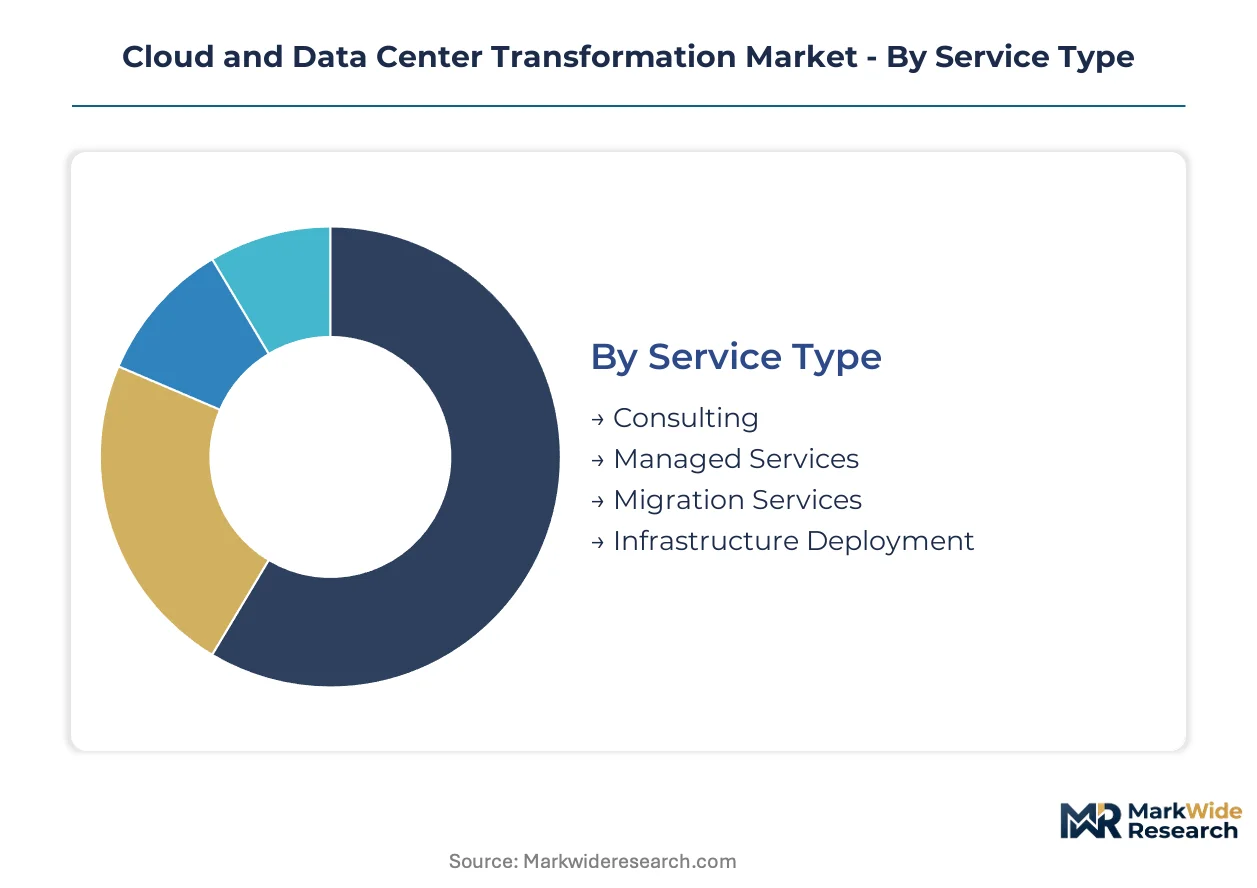
Cloud and data center transformation defies one-size-fits-all procurement. Buyers configure service bundles, deployment architectures, and technology stacks based on workload criticality, compliance exposure, and internal capability gaps. Segmentation reveals where margin pools concentrate and which combinations command premium pricing.
Service Type:
Customization intensity spans from commodity infrastructure deployment to highly bespoke consulting engagements, with managed services occupying the middle ground where recurring revenue locks in customer relationships.
- Migration Services:Workload assessment, replatforming, and cutover orchestration for legacy mainframe and monolithic applications. Financial services firms in the United States and European Union drive demand as SEC and ECB operational resilience deadlines compress transformation windows. Skills scarcity in COBOL refactoring extends project timelines and inflates day rates.
- Managed Services:Ongoing platform operations, cost optimization, and security monitoring delivered under multi-year contracts. Hybrid and multi-cloud environments generate the strongest attach rates as enterprises lack internal Kubernetes and Terraform expertise. Providers differentiate through sovereign cloud certifications and carbon-aware SLAs.
- Consulting:Strategic roadmapping, cloud-native architecture design, and FinOps implementation. Engagements typically precede migration decisions.
- Infrastructure Deployment:Physical rack-and-stack, network provisioning, and power interconnect coordination. Prefabricated modular approaches are compressing commissioning timelines.
Leading the category by volume: Managed Services. Growing fastest: Migration Services.
Deployment Model:
Cost tier separation distinguishes capex-heavy private facilities from opex-metered public consumption, with hybrid architectures commanding integration premiums.
- Hybrid Cloud:Distributed workloads across on-premises private infrastructure and public hyperscaler capacity with unified orchestration. German automotive and Japanese manufacturing verticals prioritize this model to keep proprietary design data on-premises while bursting compute to public cloud. Data residency requirements and latency-sensitive IoT workloads reinforce demand.
- Multi-Cloud:Deliberate distribution across two or more hyperscalers to mitigate vendor concentration risk. Container orchestration platforms enable workload portability without re-architecture. Financial services procurement policies increasingly mandate multi-cloud to satisfy operational resilience mandates.
- Public Cloud:Shared infrastructure with metered consumption and automatic scaling. Retail and logistics buyers favor this for seasonal demand volatility.
- Private Cloud:Dedicated single-tenant infrastructure with full control over hardware and security stack. Government and defense workloads dominate this segment.
Volume leader: Hybrid Cloud. Steepest expansion trajectory: Multi-Cloud.
Technology:
Maturity curves separate established virtualization from emerging serverless and edge paradigms, with containers now mainstream enough to drive platform consolidation.
- Containers:Operating-system-level virtualization enabling portable, lightweight application packaging. Kubernetes has become the de facto orchestration standard, with managed Kubernetes services capturing significant platform revenue. Developer productivity gains and microservices adoption sustain enterprise investment.
- Edge Computing:Distributed compute nodes positioned within 10 milliseconds of end devices for autonomous systems and industrial IoT. Manufacturing corridors in Germany, Japan, and South Korea are deploying micro-facilities to process sensor data locally. Sub-millisecond latency requirements for autonomous vehicles and robotic control systems are accelerating node densification.
- Virtualization:Hardware abstraction through hypervisors, now legacy infrastructure in mature markets but still expanding in regulated industries with extended refresh cycles.
- Serverless Computing:Event-driven execution without persistent infrastructure management. Event-driven workloads and sporadic compute needs favor this model.
Technology with largest installed base: Virtualization. Gaining share fastest: Edge Computing.
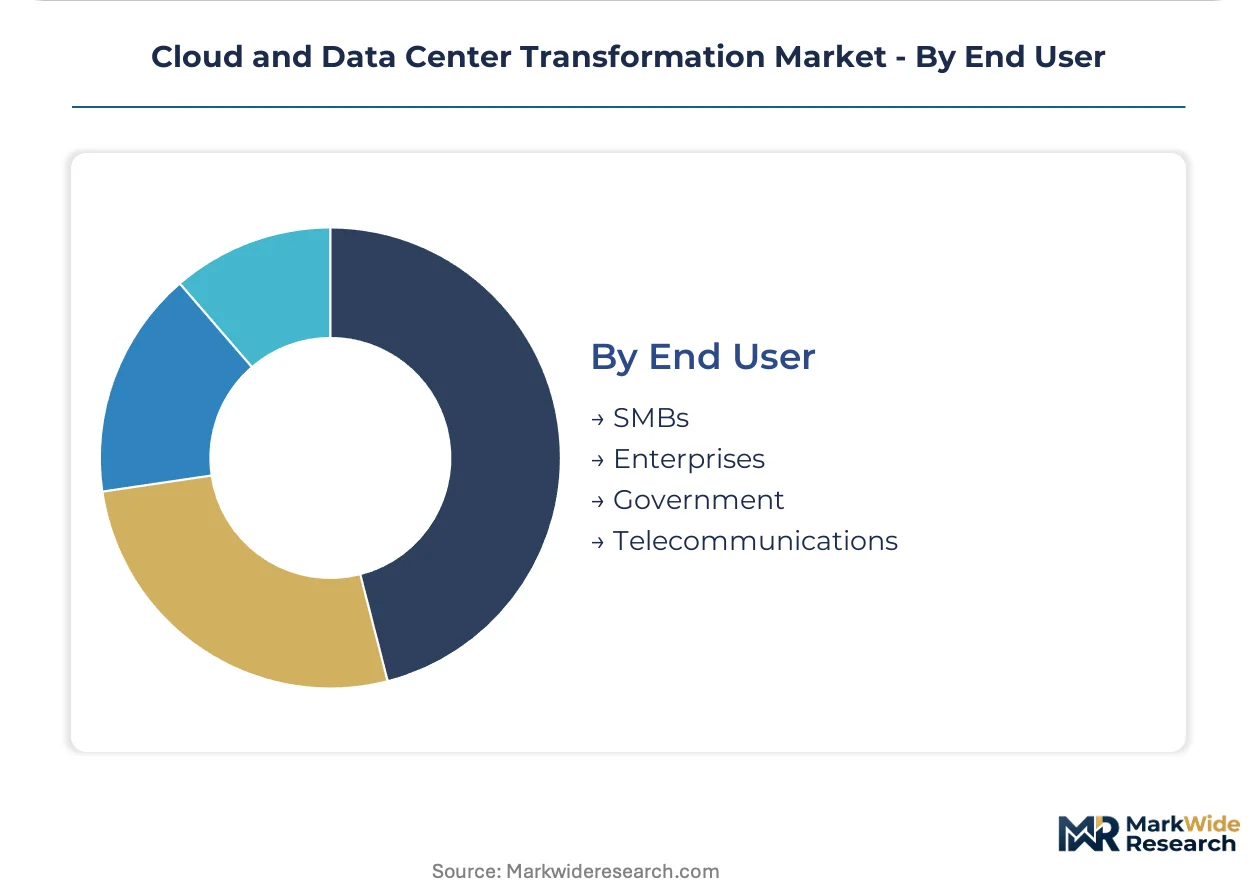
End User:
Customer type determines procurement sophistication, with enterprises and government buyers driving complex RFP processes while SMBs favor standardized consumption bundles.
- Enterprises:Large organizations with heterogeneous legacy estates, global operations, and dedicated procurement functions. Multi-year transformation programs span thousands of workloads across multiple geographies. Sovereign cloud requirements in France, Germany, and the Netherlands are mandating localized facility architectures for public sector-facing business units.
- Government:National and sub-national agencies with classified and unclassified workload requirements. Domestic data residency mandates and FedRAMP-style certification programs create high barriers to entry. Certified sovereign cloud offerings capture procurement preference.
- SMBs:Small and medium businesses with limited IT staff and straightforward workload profiles. Consumption-based pricing and managed services reduce operational burden.
- Telecommunications:Network operators building edge infrastructure and cloud-native network functions. 5G core deployments and Open RAN initiatives drive specialized requirements.
Category leader by spend: Enterprises. Expanding most quickly: Government.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley venture capital and Northern Virginia fiber corridors anchor cloud infrastructure deployment velocity across multiple continents. Facility construction timelines and power interconnection queues now determine regional competitive positioning.
United States
Financial services operational resilience mandates from the SEC and FERC interconnection standards compress migration windows for banks and insurers. PJM and ERCOT power queue backlogs delay facility energization by 18-36 months despite Order 2023 reforms. Northern Virginia's Ashburn-Dulles corridor hosts the densest hyperscaler concentration globally, with Amazon Web Services and Microsoft Azure sustaining deployment velocity through regional fiber backbone agreements.
Germany
Automotive manufacturers demand hybrid architectures to retain proprietary design data on-premises while bursting compute to public cloud. EU AI Act algorithmic transparency requirements and ECHA REACH chemical restrictions on cooling fluids reshape facility design standards. Frankfurt's Rhine-Main region anchors sovereign cloud partnerships as the federal government mandates domestic data residency for public sector workloads.
Singapore
Power density requirements above 50kW per rack drive immersion and direct-to-chip cooling retrofits across tropical facilities. The Infocomm Media Development Authority enforces sustainability benchmarks that mandate power usage effectiveness thresholds for new builds. The Jurong Innovation District concentrates edge node deployments for maritime logistics and autonomous port systems requiring sub-10ms latency.
Japan
Manufacturing corridors in Aichi and Osaka prefectures deploy micro-facilities for industrial IoT sensor processing and robotic control systems. METI energy efficiency directives and carbon accounting standards create procurement preference for hourly-matched renewable energy. The Kanto region around Tokyo sustains multi-cloud demand from financial services firms navigating Bank of Japan operational resilience guidance.
Netherlands
Data localization requirements for EU public sector workloads concentrate sovereign cloud investment in Amsterdam and Eindhoven corridors. EU Green Deal carbon disclosure mandates for large facilities favor providers with dedicated sustainability teams and on-site solar generation. The AMS-IX internet exchange anchors interconnection density that reduces latency for multi-cloud deployments across European financial services.
Cloud and Data Center Transformation Market Competitive Landscape
Global majors compete with regional champions across sovereign cloud certification and power interconnect negotiation. The market structure consolidates around hyperscaler platforms with captive fiber and energy agreements, while specialized infrastructure vendors occupy niches in liquid cooling and modular construction. Three archetypes dominate: hyperscalers with vertical integration into facility development, systems integrators with legacy workload expertise, and component specialists in power and thermal management. Competitive moves concentrate on strategic partnerships for sovereign cloud localization and prefabricated modular facility deployment to compress commissioning timelines.
Among hyperscaler platforms, Amazon Web Services, Microsoft Azure, and Google Cloud Platform exemplify the vertically integrated archetype with regional fiber backbone control and direct government partnerships. These entities occupy positions where facility construction velocity and power interconnect queue management determine enterprise customer acquisition. Their competitive positioning rests on sovereign cloud certifications and carbon-aware SLA differentiation rather than commodity compute pricing.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud Platform |
| IBM Corporation |
| Cisco Systems |
| Dell Technologies |
| Schneider Electric |
| Equinix |
| Hewlett Packard Enterprise |
| Others |
Pricing and Supply Chain Analysis
Prefabricated modular data center assembly is compressing commissioning timelines from eighteen months to six months while simultaneously concentrating procurement leverage among hyperscalers with multi-facility deployment programs. This production-method transition reduces stranded asset risk for colocation operators but intensifies price competition in standardized power and cooling modules as factory-scale output displaces job-site customization premiums.
Pricing Analysis
Warranty and service bundling separates premium managed services from commodity infrastructure deployment, with multi-year uptime guarantees and carbon-aware SLAs commanding substantial markups over rack-and-stack provisioning. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with sovereign cloud certifications and FedRAMP authorization driving top-tier premiums. Cost compression in standard colocation tiers is intensifying because consumption-based metered models displace fixed-cage leases. SMB buyers exhibit highest price sensitivity, while financial services procurement teams prioritize resilience guarantees over unit economics.
Supply Chain Analysis
Direct-to-hyperscaler channels handle the majority of power distribution unit and cooling system volume, bypassing traditional distribution layers for multi-megawatt facility commitments. Manufacturing concentrates in the United States, Germany, and Taiwan for precision power electronics, with China and South Korea dominating battery storage and memory component supply. Raw material dependencies span high-purity copper for busbars, specialized aluminum alloys for heat exchangers, and rare earth elements for high-efficiency transformers. Single-source vulnerability in advanced chip-based power management controllers creates concentration risk. Distribution runs through certified systems integrators for enterprise and government segments requiring compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container orchestration platforms are displacing legacy virtualization stacks as the foundational infrastructure layer, compressing transformation timelines for enterprises with heterogeneous workload estates.
For Market Incumbents: Anchor defensive positioning through captive fiber backbone investments in Northern Virginia and Frankfurt corridors to sustain deployment velocity against power interconnection queue bottlenecks. Deepen backward integration into liquid cooling system manufacturing to capture margin pools from power density requirements exceeding fifty kilowatts per rack. Prioritize sovereign cloud certification investment to satisfy EU AI Act and domestic data residency mandates that are reshaping procurement criteria for European public sector workloads. For New Entrants and Emerging Players: EU Green Deal carbon accounting standards in the Netherlands and Germany open a window for specialized facility operators with hourly-matched renewable energy and on-site battery storage configurations. Target edge node densification in Japan's Aichi and Osaka manufacturing corridors where sub-millisecond latency requirements for robotic control systems outstrip incumbent hyperscaler footprint. Pursue sovereign cloud partnership structures with national governments as the primary go-to-market angle, leveraging regulatory tailwinds that mandate domestic data residency. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler platform acquisitions of modular construction specialists and liquid cooling technology vendors. Long-term viability favors providers with demonstrated power interconnect queue management capabilities and established sovereign cloud certifications across multiple European jurisdictions. Acquisition target archetype: mid-scale colocation operators with stranded capacity in secondary clusters that can be retrofitted for AI training workloads. Monitor FERC interconnection reform implementation velocity and PJM queue clearance rates as the critical inflection indicator for facility energization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | EU AI Act mandates domestic data residency for French and German public sector procurement. |
| Prefabricated Modular Deployment | Standardized power modules compress commissioning timelines for Northern Virginia hyperscaler expansions. |
| Liquid Cooling Retrofit | Immersion systems extend facility lifespan as Singapore power density thresholds exceed fifty kilowatts per rack. |
| Carbon-Aware SLA Differentiation | Hourly-matched renewable energy creates procurement preference under EU Green Deal disclosure mandates. |
| Edge Node Densification | Sub-ten-millisecond latency requirements in Japan's manufacturing corridors drive micro-facility demand. |
Research Methodology
Multi-period observation of hyperscaler capital expenditure disclosures, power interconnection queue filings, and facility energization timelines anchored the trend analysis, supplemented by interviews with data center facility directors, cloud platform engineers, enterprise IT procurement officers, and colocation sales executives. Secondary validation drew from FERC interconnection databases, SEC 10-K infrastructure investment disclosures, EU ETS carbon accounting registries, and national energy regulator filings. Bottom-up triangulation across service type and deployment model segments converged with top-down macroeconomic scenario weighting.
Segment-weighting approaches applied differential growth assumptions across hybrid cloud, multi-cloud, public cloud, and private cloud deployment architectures, with additional stratification by technology maturity and end-user sophistication. Container orchestration adoption curves, edge computing node densification patterns, and sovereign cloud certification velocity informed the analytical framework across the projection horizon. CAGR derivation incorporated facility construction timeline compression effects and power density evolution assumptions.
The model assumes a particular technology adoption path; alternative pathways for liquid cooling and direct-to-chip thermal management would alter the outlook for facility retrofit investment cycles. Forecasts reflect assumptions regarding FERC interconnection reform efficacy and EU chemical restriction implementation timelines. Practitioners should monitor PJM and ERCOT queue clearance rates, EU F-Gas Regulation enforcement intensity, and hyperscaler modular deployment scale-up for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Public Cloud Application Services Market
Cloud Computing
Cloud Data Warehouse Market
Cloud Computing
Cloud Database Market
Cloud Computing
VM Service Market
Cloud Computing
Cloud Microservice and Application Market
Cloud Computing
Global Server Virtualization Market
Cloud Computing
Telecom Cloud Market
Cloud Computing
Cloud CDN Market
Cloud Computing
North America Cloud Microservices Platform Market
Cloud Computing
Cloud Services Brokerage (CSB) Market
Cloud Computing
Multi-Cloud Optimization Tools Market
Cloud Computing
Automotive Cloud Based Solutions Market
Cloud Computing
Global Cloud Office Services Market
Cloud Computing
Global Distributed Cloud Market
Cloud Computing
Asia Pacific Multi-Cloud Management Market
Cloud Computing
Cloud Managed Networking Market