
 Israel Cloud Computing Market | 2026-2036
Israel Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Cloud Computing Market Insights
Asset-light consumption models and pay-as-you-expand leasing frameworks is reconfiguring competitive entry barriers for domestic providers. Microsoft Corporation leverages its established government cloud accreditation to anchor sovereign workload contracts. Cato Networks competes through edge-native security specialization that differentiates its SASE architecture from commodity infrastructure plays.
Cloud computing denotes the on-demand delivery of compute, storage, and networking resources over IP-based networks with service-level agreements governing latency, uptime, and data durability parameters, enabling organizations to shift capital expenditure to operational expenditure while maintaining elastic capacity alignment with workload fluctuations. Public Cloud deployments lead volume absorption due to hyperscale economics, though Hybrid Cloud architectures represent the fastest-expanding configuration as regulated Israeli enterprises segment sensitive operations from general workloads. SaaS delivery models capture the deepest margin pools by embedding recurring revenue and reducing customer switching friction across IT Enterprises and Healthcare Providers.
The Israel National Cyber Directorate and Bank of Israel jointly enforce data localization and incident reporting standards that shape procurement requirements for financial services and critical infrastructure operators. BIS-equivalent certification protocols and the Privacy Protection Regulations align product compliance costs with security tier classifications, filtering market access for non-compliant foreign suppliers. Stakeholders must monitor evolving sovereign cloud mandates and cross-border data flow restrictions that will determine architecture investment priorities.
Market Dynamics
Sovereign data residency mandates from the Israel National Cyber Directorate are compressing procurement cycles for domestic cloud infrastructure, forcing hyperscale providers to localize compute capacity and security certifications.
Growth Catalysts
- Defense workload migration:Israeli defense contractors are accelerating classified system transitions to accredited sovereign environments. This creates captive demand for air-gapped infrastructure with domestic cryptographic controls.
- Financial services localization:The Bank of Israel's data residency requirements for payment systems and customer records mandate domestic processing. Compliance-driven procurement now dominates enterprise cloud roadmaps.
- Tel Aviv corridor density:Hyperscale availability zones cluster within the metropolitan technology corridor. Geographic concentration reduces latency to enterprise R&D facilities and enables low-latency AI training pipelines.
Market Restraints
- Skilled security architect scarcity:Domestic talent pools for zero-trust architecture and confidential computing remain shallow. Compensation inflation for cleared personnel compresses provider margins.
- Energy input cost volatility:Israel's grid reliance on natural gas imports exposes data center operators to fuel price swings. Power purchase agreements now carry significant basis risk.
- Hardware supply concentration:Advanced GPU and custom AI accelerator supply chains concentrate with Taiwan Semiconductor Manufacturing and NVIDIA. Delivery lead times for training clusters extend 40-52 weeks.
Strategic Opportunities
- Negev desert renewable-powered regions:The southern district offers solar-rich land parcels for carbon-neutral data center development. Grid interconnection projects now prioritize this corridor.
- Healthcare AI inference at edge:Hospital systems require HIPAA-equivalent processing for diagnostic imaging. Edge-native deployments within medical campuses bypass core network latency constraints.
- Quantum-resistant cryptography mandates:The National Cyber Directorate's post-quantum transition timeline creates upgrade cycles for encryption infrastructure. Providers with NIST-compliant implementations capture first-mover positioning.
Industry Challenges
- Cross-domain security clearance pipelines:Personnel vetting for defense-adjacent cloud operations requires 12-18 month processing windows. Talent acquisition velocity constrains service expansion.
- Legacy mainframe integration complexity:Government ministries operate COBOL-dependent core systems. API abstraction layers for hybrid connectivity demand specialized system integrator partnerships.
- Multi-cloud orchestration standardization gaps:Proprietary management interfaces across hyperscale platforms fragment operational tooling. Interoperability middleware adds 15-22% to total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Cloud Computing Market |
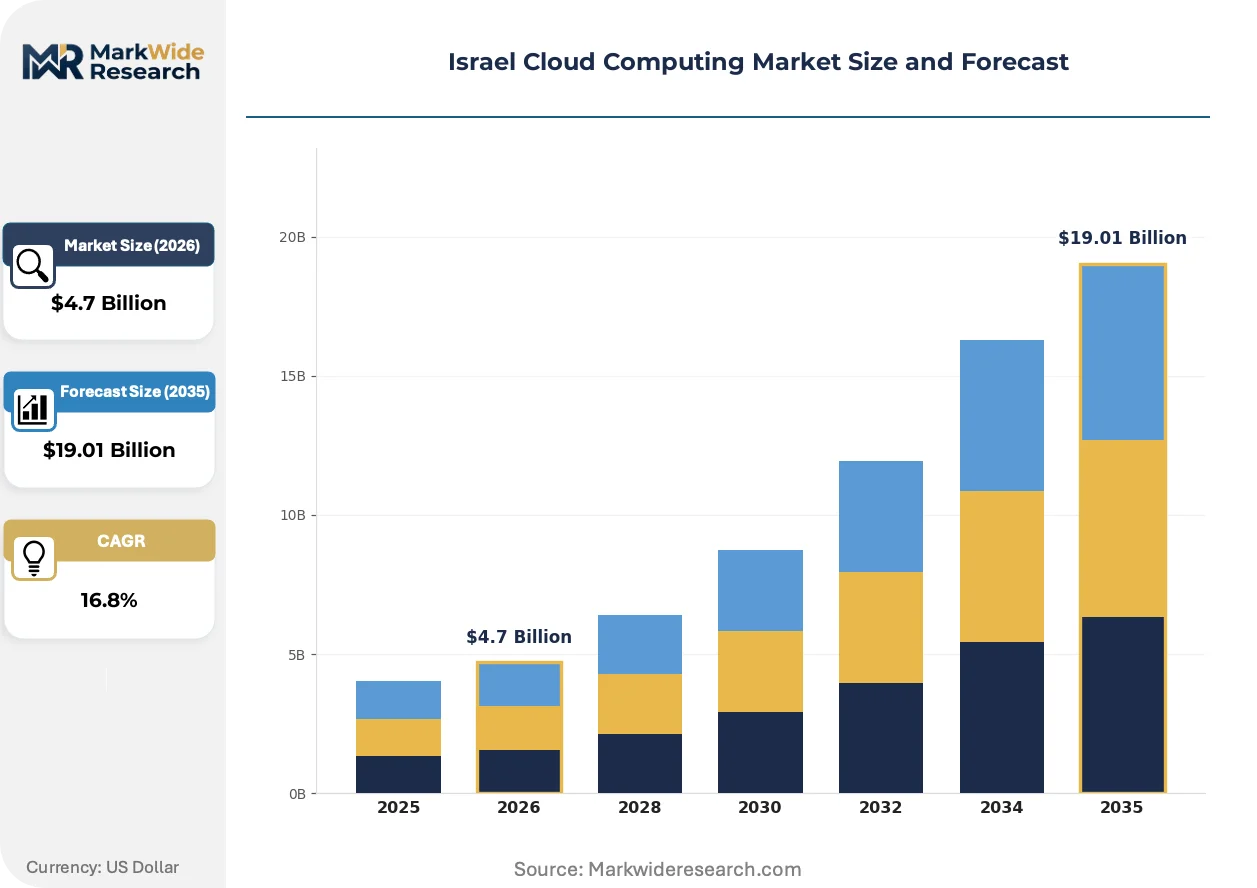
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $19.01 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, DaaS End User: IT Enterprises, Government Agencies, Educational Institutions, Healthcare Providers Solution: Data Storage, Disaster Recovery, Virtual Desktop, Cloud Security |
| Companies Covered | Amazon Web Services (AWS), Microsoft Corporation, Google LLC, IBM Corporation, Alibaba Group Holding Limited, Cato Networks, Stream Security, MedOne Ltd, JFrog, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Cloud Computing Market Trends and Innovations
Workload portability and sovereign control requirements are fragmenting architectural decisions across Israeli enterprises, elevating hybrid orchestration and confidential computing to strategic procurement criteria.
Confidential computing using hardware-based trusted execution environments is hybridizing security architectures for regulated workloads. Financial institutions and healthcare providers now demand memory encryption for AI training data. This capability compresses the acceptable risk perimeter for multi-tenant infrastructure, enabling defense contractors to evaluate previously excluded public cloud services.
The Israel National Cyber Directorate's sector-specific security tier classifications are reshaping vendor qualification pathways. Providers must demonstrate continuous compliance monitoring rather than point-in-time certification. Critical infrastructure operators in energy and water now embed these requirements into RFP technical specifications, filtering market access for non-compliant foreign suppliers.
Consumption-based capacity reservations are displacing traditional committed use discounts among mid-market enterprises. Buyers now prefer hourly metering with monthly spend caps over three-year instance reservations. This pattern concentrates in SaaS-native startups within Tel Aviv's venture corridor, where cash flow predictability outweighs marginal cost optimization.
Israel Cloud Computing Market Segmentation
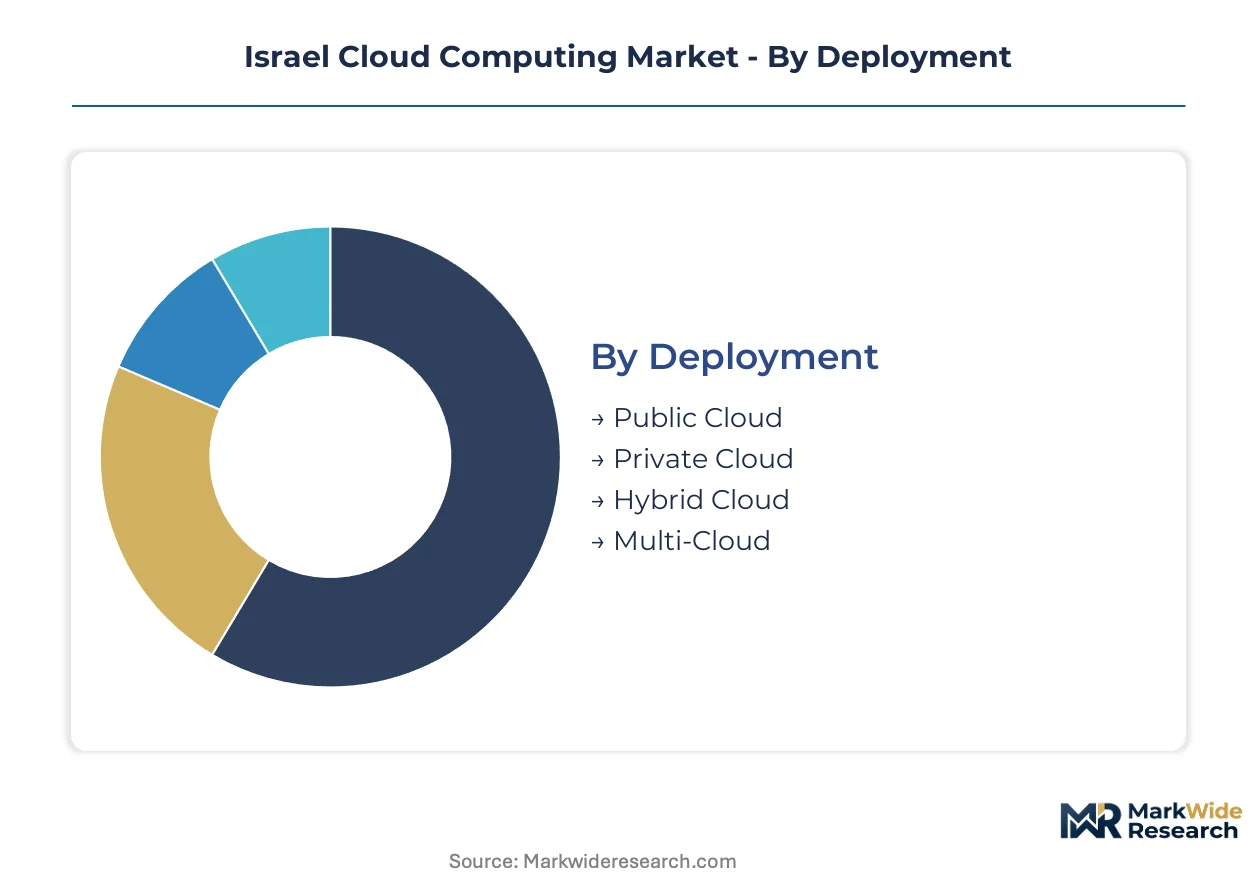
Israeli cloud procurement patterns reflect sovereign compliance mandates and workload sensitivity tiers. Buyers segment infrastructure choices across deployment models, service abstractions, end-user verticals, and solution stacks to align regulatory exposure with operational requirements.
Deployment:
Use-case spectrum spans air-gapped defense workloads to elastic startup environments, with compliance posture determining architecture selection.
- Public Cloud:Multi-tenant infrastructure delivers hyperscale economics through metered compute and storage pools. Demand concentrates among Tel Aviv venture-backed startups seeking rapid provisioning without capital deployment. The Israel National Cyber Directorate's tier-1 security classification permits certain non-sensitive workloads.
- Hybrid Cloud:Split architectures segment regulated data onto private nodes while bursting variable loads to public capacity. Financial institutions and healthcare providers favor this configuration to satisfy Bank of Israel data residency without sacrificing elasticity. Steepest expansion trajectory as enterprises navigate sovereign mandates.
- Private Cloud:Dedicated single-tenant environments host classified defense contractor systems with domestic cryptographic controls. Procurement cycles compress as the National Cyber Directorate accelerates accredited facility certification.
- Multi-Cloud:Orchestrated workloads across heterogeneous provider platforms reduce vendor concentration risk. Mid-market enterprises adopt this pattern to avoid single-provider lock-in and satisfy diverse contractual requirements.
Established volume favors Public Cloud; emerging adoption favors Hybrid Cloud.
Service Type:
Margin structure varies dramatically across abstraction layers, with higher-level services capturing recurring revenue premiums.
- IaaS:Raw compute, storage, and networking resources delivered as virtualized infrastructure. Defense contractors and systems integrators prefer this layer for maximum control over security configurations and compliance boundaries.
- PaaS:Application development and deployment environments abstract underlying infrastructure management. Tel Aviv software vendors leverage these tools to accelerate product release cycles without operational overhead.
- SaaS:Fully managed application delivery captures the deepest margin pools through subscription economics. Healthcare Providers and Educational Institutions drive volume for productivity, collaboration, and electronic medical record platforms.
- DaaS:Desktop virtualization streams secure workspaces to distributed endpoints. Government Agencies adopt this model to centralize sensitive data while enabling remote workforce flexibility.
Revenue concentration sits with SaaS; infrastructure expansion centers on IaaS.
End User:
Customer type determines procurement authority, budget scale, and compliance stringency.
- IT Enterprises:Technology sector buyers span startups to established software vendors with cloud-native architectures. Tel Aviv metropolitan corridor density creates geographic clustering of demand with low-latency requirements for AI training pipelines.
- Government Agencies:Public sector procurement operates under National Cyber Directorate security tier classifications with mandatory domestic data residency. Ministry-level buyers face legacy mainframe integration complexity that shapes hybrid connectivity requirements.
- Educational Institutions:Universities and research centers consume compute for scientific workloads and remote learning platforms. Budget constraints favor consumption-based pricing over committed use discounts.
- Healthcare Providers:Hospital systems and diagnostic facilities require HIPAA-equivalent processing for patient data. Edge-native deployments within medical campuses address latency constraints for real-time imaging analysis.
Procurement velocity is fastest among IT Enterprises; compliance rigor peaks with Government Agencies.
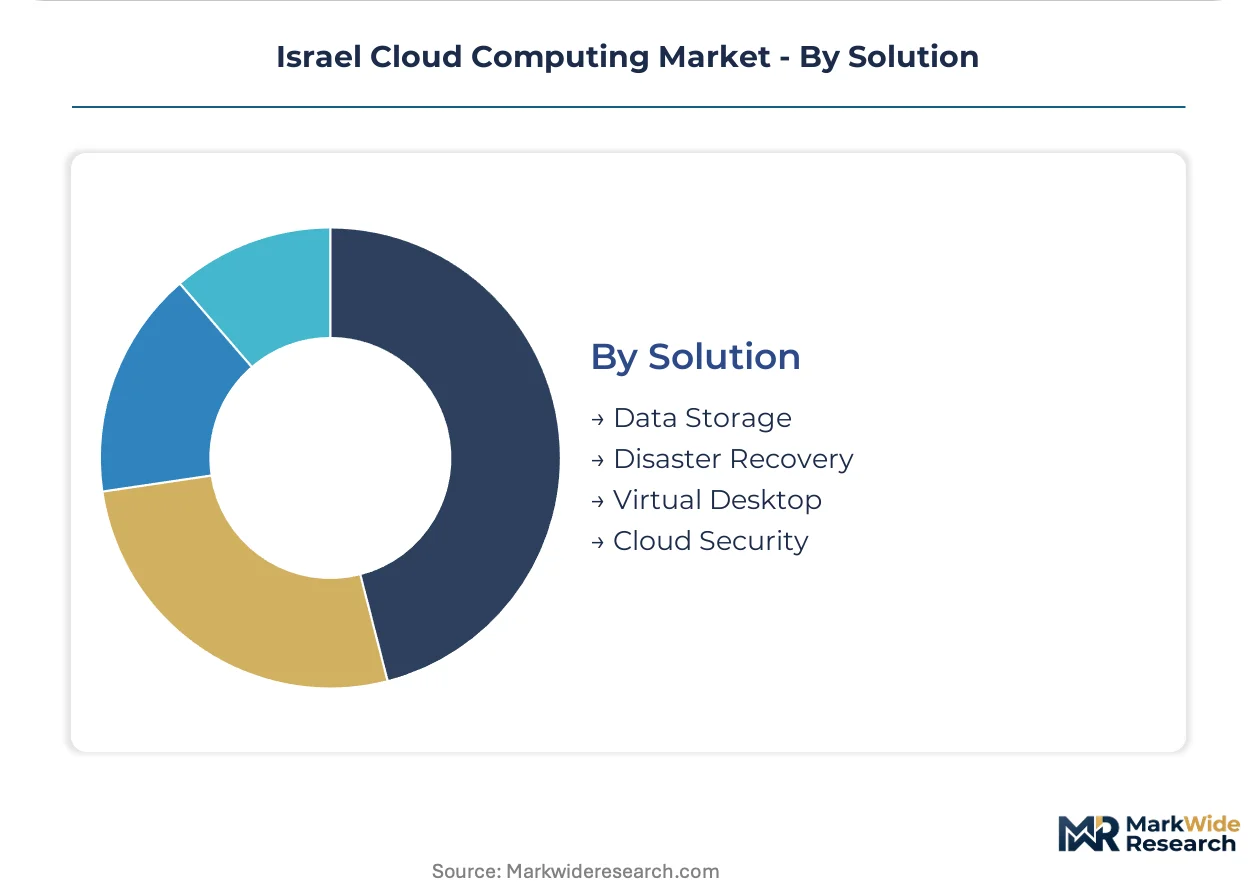
Solution:
Functional capabilities align with risk mitigation priorities and operational continuity requirements.
- Data Storage:Object, block, and file services with durability guarantees and geographic redundancy. Financial services localization mandates drive demand for encrypted domestic replication.
- Disaster Recovery:Automated failover and backup orchestration ensuring business continuity. Critical infrastructure operators in energy and water embed these capabilities into technical specifications.
- Virtual Desktop:Centralized workspace delivery with data leakage prevention. Government Agencies and Healthcare Providers adopt this solution to maintain control over sensitive information endpoints.
- Cloud Security:Zero-trust architecture, confidential computing, and continuous compliance monitoring. The National Cyber Directorate's post-quantum transition timeline accelerates encryption infrastructure upgrade cycles.
Spending gravity centers on Data Storage; emerging priority attaches to Cloud Security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Israel National Cyber Directorate's data residency mandates are compressing procurement cycles across domestic cloud infrastructure, forcing hyperscale providers to localize compute capacity and security certifications within sovereign boundaries.
Tel Aviv Metropolitan Corridor
Venture-backed startups and enterprise R&D facilities cluster within this technology corridor, driving demand for low-latency AI training pipelines. The National Cyber Directorate's tier-1 security classification permits certain non-sensitive workloads in multi-tenant environments. Hyperscale availability zones concentrate here alongside defense contractor facilities seeking elastic capacity.
Central District
Government ministries and financial institutions anchor demand for hybrid cloud architectures in this administrative hub. Bank of Israel data residency requirements mandate domestic processing for payment systems and customer records. Legacy mainframe integration complexity shapes procurement specifications for public sector buyers.
Haifa Bay Area
Industrial technology and maritime logistics operators consume cloud infrastructure for supply chain optimization and predictive maintenance. The northern port city's universities contribute research computing demand for scientific workloads. Local data center development addresses latency requirements for real-time industrial control systems.
Jerusalem
Healthcare providers and educational institutions drive consumption of HIPAA-equivalent cloud services for patient data management. Hospital systems require edge-native deployments within medical campuses for diagnostic imaging analysis. Academic medical centers anchor research collaboration networks with specific data sovereignty requirements.
Negev Desert Region
Solar-rich land parcels in the southern district attract carbon-neutral data center development proposals. Grid interconnection projects now prioritize this corridor for renewable-powered compute infrastructure. Defense-adjacent facilities evaluate air-gapped deployments with domestic cryptographic controls in this geographically isolated zone.
Israel Cloud Computing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that consolidates around government accreditation and sovereign compliance capabilities. The vendor base stratifies into three tiers: hyperscale platforms with established security certifications, domestic specialists with edge-native architectures, and regional systems integrators with legacy modernization expertise. Dominant competitive moves include strategic partnerships with defense contractors and geographic expansion through localized availability zone deployment.
Within the hyperscale tier, Microsoft Corporation occupies a position anchored by government cloud accreditation, while Amazon Web Services exemplifies the scale-driven archetype with established sovereign workload contracts. Cato Networks represents the specialization vector through edge-native security architecture that differentiates from commodity infrastructure plays. These three entities collectively illustrate the competitive tension between compliance depth and operational breadth that shapes procurement outcomes in regulated verticals.
| Leading Market Players |
|---|
| Amazon Web Services (AWS) |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Alibaba Group Holding Limited |
| Cato Networks |
| Stream Security |
| MedOne Ltd |
| JFrog |
| Others |
Pricing and Supply Chain Analysis
Haifa Bay maritime corridor freight dynamics amplify cost differentials between imported GPU clusters and domestically assembled infrastructure, concentrating pricing power with Taiwan Semiconductor Manufacturing and NVIDIA while forcing Israeli providers to tier offerings around National Cyber Directorate certification grades.
Pricing Analysis
Certification level (National Cyber Directorate tier-1 through tier-3) creates the primary spread between commodity public cloud instances and sovereign-accredited private deployments. Subscription-based SaaS models dominate healthcare and education verticals, while project-based licensing persists for defense-adjacent workloads requiring air-gapped infrastructure. Price differentiation hinges on domestic data residency guarantees and zero-trust architecture depth. Margins are tightening due to compensation inflation for cleared security architects. Early-stage Tel Aviv startups exhibit highest price sensitivity; government ministries and defense contractors demonstrate lowest elasticity given mandate-driven procurement.
Supply Chain Analysis
Tariff exposure between Taiwan and the United States dominates supply chain risk calculations for advanced AI training hardware. Geographic concentration centers on Taiwan for GPU fabrication, the United States for chip design and hyperscale orchestration software, and China for rare earth processing in permanent magnet cooling systems. Raw material dependencies include NVIDIA H100/H200 accelerators, custom AI training clusters, and domestic cryptographic modules meeting BIS-equivalent standards. Single-source vulnerability persists at the foundry layer where Taiwan Semiconductor Manufacturing controls advanced node production. Distribution runs through direct hyperscale procurement contracts with defense contractors and systems integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israel's cloud market operates as a regulatory-moat arena where National Cyber Directorate accreditation creates defensible incumbent positions through high switching costs and multi-year certification cycles.
For Market Incumbents: Build regulatory entrenchment through accelerated tier-3 facility certification before post-quantum cryptography mandates harden compliance barriers. Expand sovereign availability zone footprint in the Negev Desert corridor to capture renewable-powered demand from carbon-conscious European defense contractors. Vertical integration into confidential computing hardware partnerships with domestic system integrators defends against edge-native specialists like Cato Networks. For New Entrants and Emerging Players: Establish a beachhead in healthcare edge inference where HIPAA-equivalent processing requirements and hospital campus latency constraints favor nimble deployment models over hyperscale footprint gaps. Target mid-market financial services institutions navigating Bank of Israel localization mandates without legacy mainframe integration burdens. Lead with consumption-based metering and monthly spend caps rather than committed-use discounts to match Tel Aviv venture-backed startup procurement preferences. For Investors and Strategic Acquirers: Carve-out targets emerge from defense contractor cloud divisions seeking to monetize accredited infrastructure assets without core systems integration complexity. Long-term viability favors providers with demonstrated continuous compliance monitoring capabilities rather than point-in-time certification. Monitor National Cyber Directorate post-quantum transition timeline acceleration as inflection signal for encryption infrastructure upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Accreditation | National Cyber Directorate tier-3 certification unlocks classified defense workload contracts with 12-18 month vetting pipelines. |
| Negev Renewable Data Center Buildout | Solar-rich southern district land parcels attract carbon-neutral compute investment aligned with European defense contractor ESG mandates. |
| Confidential Computing Partnership | Hardware-based trusted execution environments enable financial institutions to evaluate previously excluded multi-tenant public cloud services. |
| Healthcare Edge Native Deployment | Hospital campus inference clusters bypass core network latency for real-time diagnostic imaging analysis. |
| Post-Quantum Cryptography Transition | NIST-compliant encryption implementations capture first-mover positioning ahead of National Cyber Directorate mandate deadlines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cloud infrastructure procurement officers at Israeli defense contractors, Bank of Israel compliance leads, National Cyber Directorate certification auditors, Tel Aviv venture capital technical due diligence partners, and hospital system CIOs managing edge deployments. Secondary validation drew from hyperscaler capex disclosures, Israel National Cyber Directorate security tier classification documentation, Bank of Israel data residency regulatory circulars, and customs records for GPU import flows. Bottom-up sizing of accredited facility capacity was triangulated against top-down expenditure estimates from enterprise IT budget surveys.
Calibration across the analysis window employed scenario-weighted projections for sovereign mandate acceleration versus relaxation. Segmentation dimensions modeled include deployment architecture, service abstraction layer, end-user vertical, and solution stack functional capability. CAGRs were derived from elasticity-adjusted adoption curves fitted to historical procurement cycle data. Industry-specific forecast inputs incorporated defense budget allocation patterns for classified system modernization and healthcare AI inference workload growth trajectories.
Stress conditions across energy price volatility, GPU supply lead time extension, and National Cyber Directorate certification processing delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and hyperscale localization commitment durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Spain Cloud Computing Market
Cloud Computing
Containers As a Service (Caas) Market
Cloud Computing
Cloud Based-Batch Processing Market
Cloud Computing
Global Cloud High-Performance Computing Market
Cloud Computing
Cloud Infrastructure-As-A-Service Market
Cloud Computing
Cloud Computing Stack Layers Market
Cloud Computing
Indonesia Cloud Market
Cloud Computing
Hadoop-As-A-Service (Haas) Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
Cloud Directory Services Software Market
Cloud Computing
Saudi Arabia Cloud Services Market
Cloud Computing
North America Mobile Cloud Market
Cloud Computing
Android Cloud Phone Market
Cloud Computing
Cloud Orchestration Market
Cloud Computing
Government Cloud Market
Cloud Computing
Healthcare Cloud Infrastructure Market