
 North America Cloud Computing Market | 2026-2036
North America Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cloud Computing Market Insights
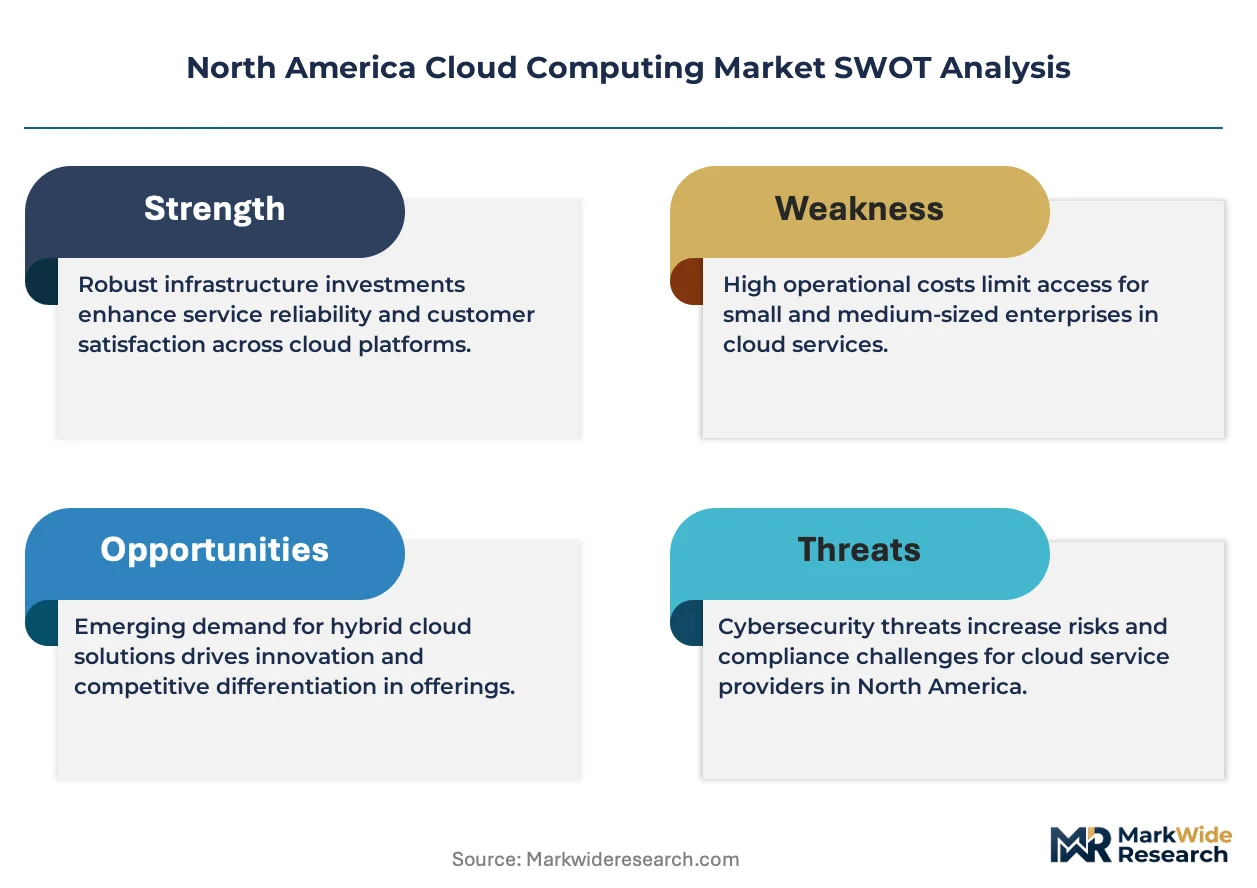
The US Inflation Reduction Act is realigning the cost-of-entry calculus for data center operators across North America by embedding clean energy tax credits into facility economics. Amazon Web Services leverages its utility-scale renewable power purchasing to sustain margin advantage in carbon-intensive markets. Microsoft Azure anchors its competitive position through direct liquid cooling R&D intensity, while Google Cloud differentiates via custom tensor processing unit specialization in AI inference workloads.
Cloud computing denotes the on-demand delivery of IT resources over a network using pooled, configurable computing assets that scale elastically without direct active management by users, typically orchestrated through hypervisor-based virtualization with service level agreements guaranteeing uptime between 99.9% and 99.999%. Its primary commercial purpose is converting capital-intensive infrastructure into operational expenditure while enabling burst capacity for variable workloads. Public cloud infrastructure dominates absolute spend across deployment models, though hybrid cloud architectures capture the fastest expansion as enterprises retain sensitive data on-premises while bursting analytics to off-site resources. Within service types, platform-as-a-service margin pools exceed infrastructure-as-a-service due to developer tooling stickiness and multi-year contract structures.
FERC interconnection queue reform and EPA power plant emissions standards are tightening siting requirements for new hyperscale facilities across the United States. The Canadian federal carbon pricing backstop and provincial clean electricity regulations in Ontario and Quebec are similarly constraining expansion timelines for cloud providers seeking low-carbon baseload. CSA Group cybersecurity certification for cloud services adds a compliance layer specific to Canadian government procurement. Stakeholders must monitor whether state-level renewable portfolio standards in Texas, Virginia, and Arizona outpace federal minimums to determine optimal facility placement sequencing.
Market Dynamics
Hyperscale facility clustering in Texas, Virginia, and Arizona is compressing regional power grid capacity and forcing operators to resequence expansion timelines around interconnection queue positions.
Growth Catalysts
- Healthcare EHR migration:Hospital systems across the United States are accelerating cloud-based electronic health record deployments to satisfy HIPAA interoperability mandates and reduce on-premise infrastructure maintenance burdens.
- IRA clean energy tax credits:The US Inflation Reduction Act embeds production and investment tax credits into facility economics, lowering effective power costs for renewable-powered data centers in carbon-intensive grid regions.
- AI inference workload expansion:Specialized tensor processing architectures are pulling compute demand toward cloud-native deployment models, displacing on-premise GPU clusters in enterprise machine learning pipelines.
Market Restraints
- Interconnection queue congestion:FERC reform timelines lag behind hyperscale demand, extending facility energization delays to 36-48 months in Texas and Virginia transmission zones.
- Liquid cooling capex premiums:Direct-to-chip thermal management systems require 40-60% higher upfront infrastructure investment versus traditional air-cooled designs, compressing project IRRs.
- Cross-border data sovereignty:Canadian CSA Group cybersecurity certification creates procurement friction for US-based providers seeking federal government contracts in Ontario and Quebec.
Strategic Opportunities
- Quebec hydroelectric baseload:Provincial clean electricity regulations and abundant low-carbon power from Hydro-Québec offer carbon-negative positioning for AI training clusters serving US enterprise demand.
- Edge computing node dispersion:Micro-data center deployment in secondary US metros—Columbus, Salt Lake City, Phoenix—is reducing latency for autonomous vehicle telemetry and industrial IoT workloads.
- Carbon accounting convergence:EPA power plant emissions standards and state renewable portfolio standards are creating compliance-driven demand for real-time Scope 2 reporting tools integrated with cloud billing APIs.
Industry Challenges
- Electrical trades scarcity:Medium-voltage substation commissioning and busbar installation expertise is concentrating among aging contractor pools in Dallas-Fort Worth and Northern Virginia, extending construction timelines.
- Legacy mainframe integration:Financial services and insurance verticals maintain COBOL-dependent core systems that resist API-native refactoring, forcing expensive middleware layers for hybrid cloud orchestration.
- Water stress exposure:Evaporative cooling dependence in Arizona and Texas facilities faces escalating municipal water use restrictions and reclaimed water quality variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cloud Computing Market |
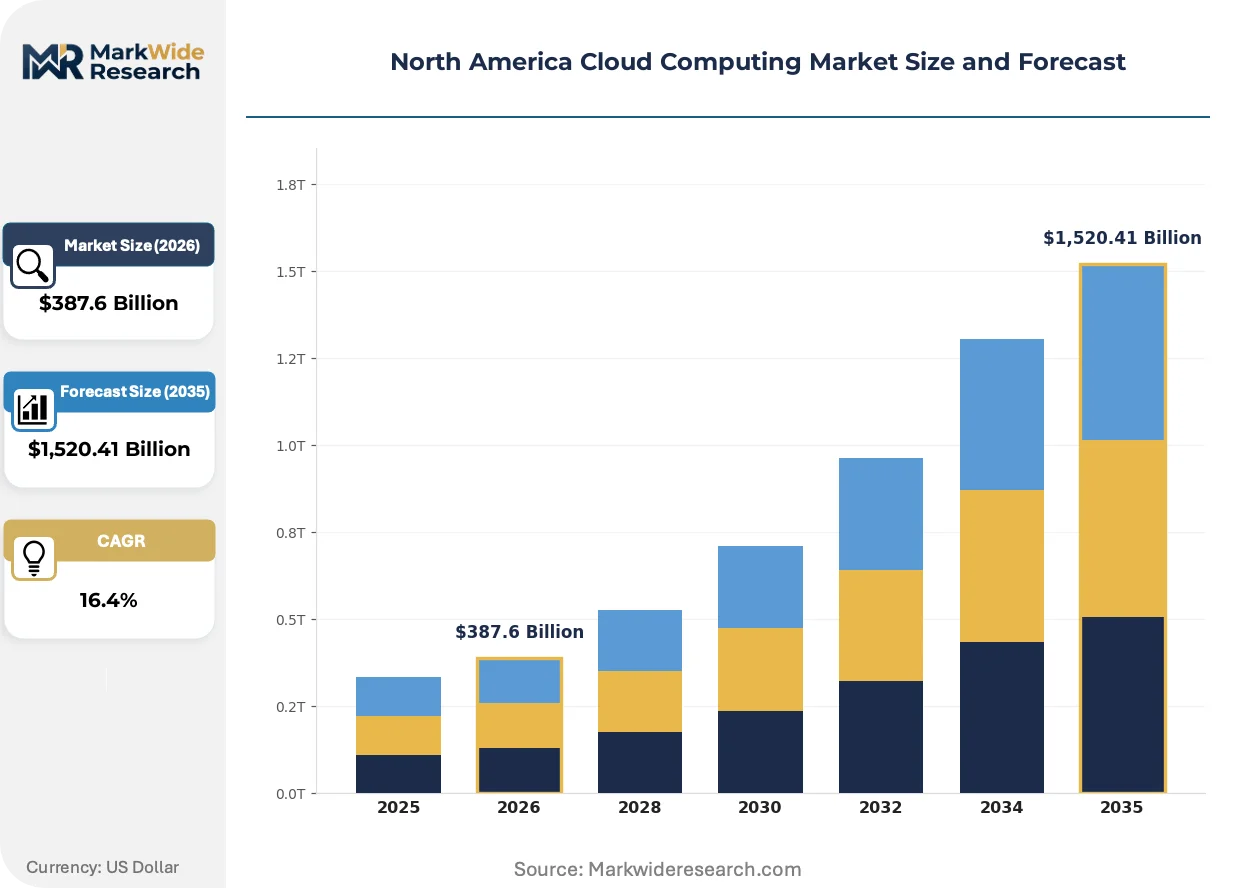
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,520.41 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Service Type: IaaS, PaaS, SaaS, BaaS End User: BFSI, Healthcare, Retail, Government Technology: Virtualization, APIs, Containers, Microservices |
| Companies Covered | Oracle Cloud, DigitalOcean, Amazon Web Services, CoreWeave, Vultr, Microsoft Azure, IBM Cloud, Salesforce, Google Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cloud Computing Market Trends and Innovations
Containerized and modular infrastructure architectures are displacing traditional stick-built construction, compressing facility deployment cycles from 24 months to under 12 months in competitive markets.
Direct liquid cooling is modularizing thermal management design across hyperscale facilities. Cold plate and immersion systems separate heat capture from heat rejection, enabling independent scaling of compute and mechanical infrastructure. Amazon Web Services and Microsoft Azure are standardizing modular cooling skids across Texas and Arizona deployments, reducing field engineering variance and accelerating commissioning timelines.
The US Inflation Reduction Act is embedding clean energy procurement into data center siting economics. Production tax credits for wind and solar power purchase agreements are reshaping competitive positioning between carbon-intensive and low-carbon grid regions. Operators in Texas are responding by anchoring new facilities near existing utility-scale renewable installations to capture marginal tax benefit.
Consumption-based billing models are displacing reserved instance commitments among mid-market enterprise buyers. FinOps tooling adoption is accelerating in healthcare and financial services verticals, where workload variability resists three-year capacity planning. This shift is most visible in US Midwest markets, where seasonal demand spikes from agricultural IoT and insurance analytics create burst-compute requirements.
North America Cloud Computing Market Segmentation
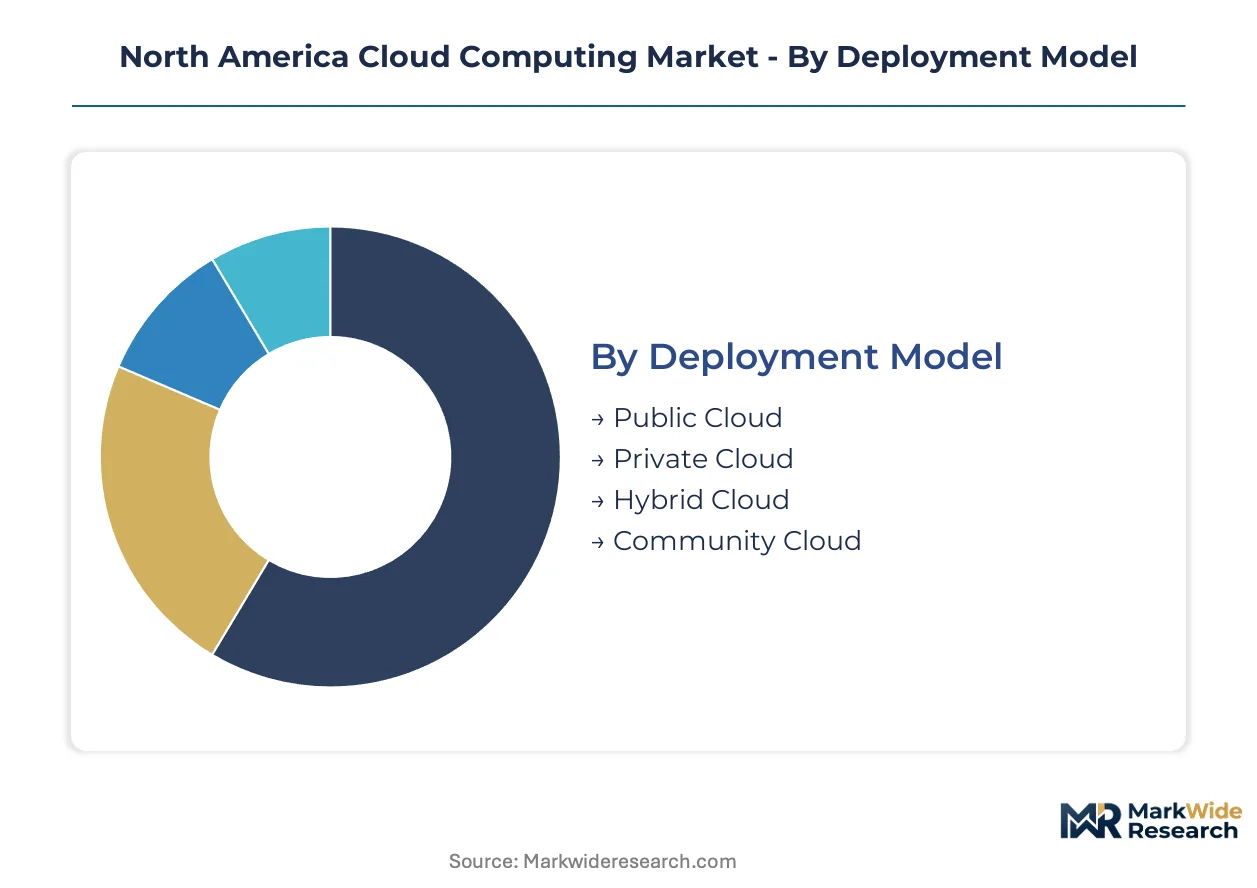
Cloud computing segmentation reveals how infrastructure economics, compliance requirements, and workload characteristics fragment purchasing behavior across North American enterprises. Deployment model selection directly determines capital intensity, energy procurement strategies, and regulatory exposure for facility operators.
Deployment Model:
Standardization dominates at the hyperscale public tier while customization intensity rises through private and hybrid architectures.
- Public Cloud:Multi-tenant infrastructure pools compute, storage, and networking resources across shared physical hardware with tenant isolation enforced through hypervisor virtualization. Demand concentrates in Texas and Virginia transmission zones where hyperscale operators leverage IRA production tax credits for renewable power purchase agreements. FERC interconnection queue delays now extend energization timelines to 36-48 months, compressing effective capacity expansion.
- Hybrid Cloud:Orchestrated workload portability between on-premises infrastructure and off-premises resources retains sensitive data locally while bursting analytics and AI training to cloud-native environments. Healthcare systems across the United States anchor demand here as HIPAA interoperability mandates force API-native connectivity between legacy EHR systems and cloud-based analytics platforms.
- Private Cloud:Single-tenant dedicated infrastructure delivers virtualization benefits with complete environmental control for regulated workloads. Financial services institutions in New York and Chicago maintain private deployments for core banking systems resisting public cloud migration due to FedRAMP compliance complexity.
- Community Cloud:Shared infrastructure serving specific industry verticals or regulatory jurisdictions with common compliance requirements. Canadian federal government procurement through CSA Group certification drives Ottawa and Toronto deployments for cross-border data sovereignty.
Most installed capacity flows through Public Cloud. Expansion is steepest in Hybrid Cloud.
Service Type:
Margin structures compress toward infrastructure commoditization while platform and software layers capture developer tooling stickiness.
- IaaS:Raw compute, storage, and networking resources delivered as metered utility services with minimal abstraction above physical infrastructure. Enterprise demand in Arizona and Nevada clusters around burst capacity for seasonal agricultural IoT and insurance analytics workloads.
- PaaS:Developer-centric environments abstracting infrastructure management through container orchestration, database automation, and CI/CD pipeline integration. Healthcare and retail verticals drive adoption as HIPAA and PCI-DSS compliance automation reduces security engineering overhead.
- SaaS:Fully managed application software delivered through browser interfaces or mobile endpoints with zero infrastructure visibility to subscribers. Government sector procurement in Washington DC and state capitals accelerates as FedRAMP authorization pathways mature.
- BaaS:Blockchain ledger infrastructure and smart contract execution environments delivered as managed services without node operation requirements. Financial services experimentation in Chicago and Toronto focuses on trade finance and cross-border settlement automation.
Revenue concentration sits with SaaS. PaaS is gaining share fastest among mid-market enterprises adopting FinOps tooling.
End User:
Risk tolerance and compliance burden stratify purchasing authority across verticals with diverging data sovereignty requirements.
- BFSI:Banking, financial services, and insurance institutions maintain the most stringent residency and encryption requirements, driving private cloud retention for core systems while edge-deploying customer-facing analytics. COBOL-dependent legacy infrastructure in Hartford and Charlotte resists API-native refactoring.
- Healthcare:Hospital systems and payers accelerate cloud-based EHR migration to satisfy interoperability mandates while reducing on-premise maintenance burdens. Texas Medical Center in Houston and Mayo Clinic in Minnesota anchor regional demand clusters.
- Retail:Omnichannel commerce platforms demand elastic compute for seasonal demand spikes with real-time inventory synchronization across distributed fulfillment networks. California and New York metro areas concentrate deployment for proximity to consumer density.
- Government:Federal, state, and municipal agencies require FedRAMP or equivalent certification with escalating supply chain security scrutiny under executive order directives. Virginia and Maryland benefit from physical proximity to Washington DC procurement authority.
BFSI retains the largest legacy infrastructure footprint. Healthcare is expanding most quickly as EHR consolidation accelerates.
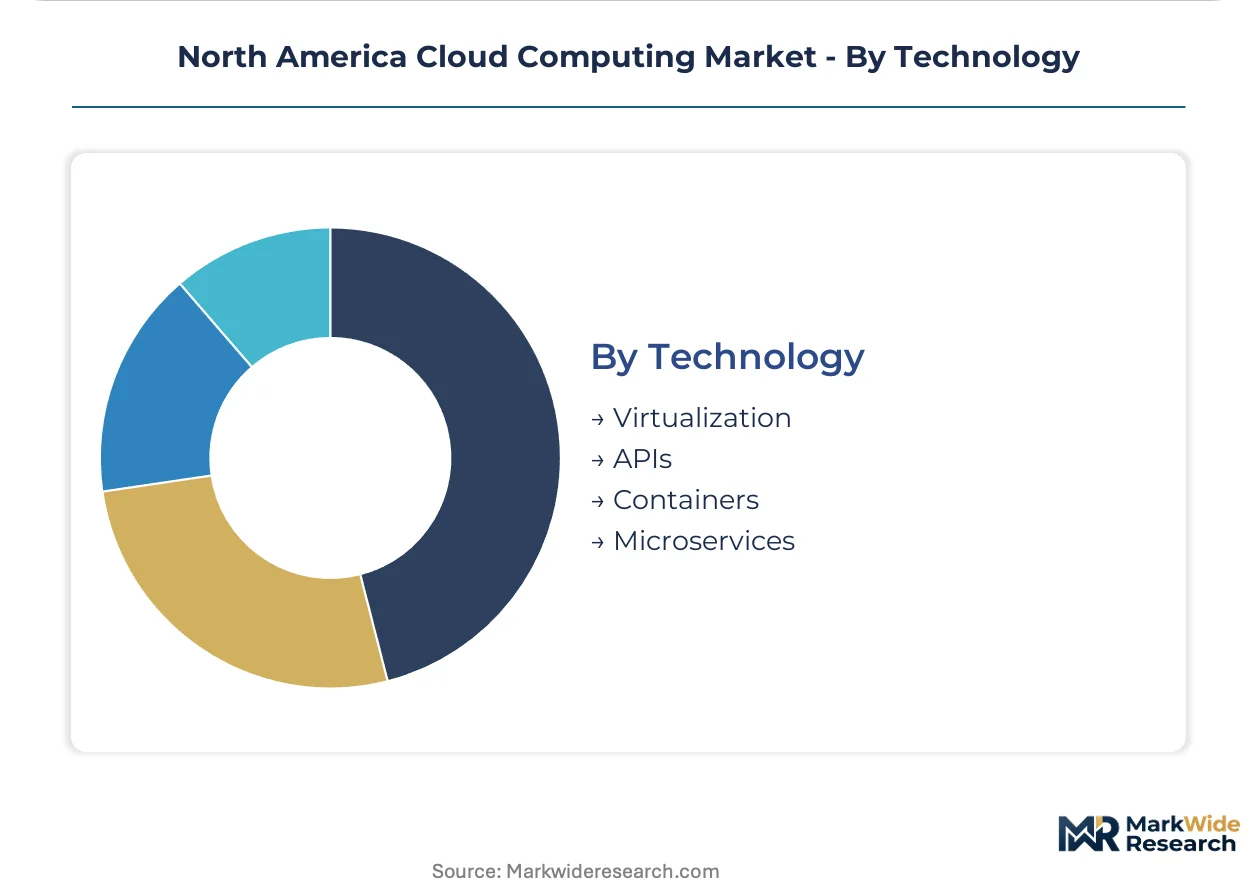
Technology:
Abstraction layer maturity determines operational efficiency gains and vendor lock-in exposure for enterprise architecture teams.
- Virtualization:Hypervisor-based server abstraction remains the foundational workload isolation mechanism across all deployment models, with VMware and KVM dominating enterprise private cloud stacks in Chicago and Dallas.
- Containers:Operating-system-level virtualization through Docker and Kubernetes enables microservice decomposition with faster startup and denser consolidation than hardware virtualization. Seattle and San Francisco engineering clusters drive tooling innovation adoption.
- Microservices:Architectural pattern decomposing applications into independently deployable services communicating through lightweight protocols. Financial services in New York and fintech startups in Austin lead refactoring initiatives.
- APIs:Application programming interfaces enable service interoperability and ecosystem integration with standardized authentication and rate limiting. Healthcare interoperability mandates under HIPAA accelerate demand for FHIR-compliant API gateways.
Virtualization underpins most legacy capacity. Containers are climbing the fastest as Kubernetes standardizes orchestration across hyperscale providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrical trades talent pools concentrate in Dallas-Fort Worth and Northern Virginia, anchoring hyperscale construction velocity across the continent. Canadian hydroelectric engineering expertise and Mexican manufacturing corridors complete the regional workforce triad.
United States
Hospital systems in Houston and Minneapolis drive healthcare cloud migration while FERC interconnection queue reforms reshape data center energization timelines. The US Inflation Reduction Act embeds production tax credits into renewable-powered facility economics. Virginia's Loudoun County hosts the densest hyperscale cluster globally, though queue delays now extend to 48 months.
Canada
Hydro-Québec's baseload capacity attracts AI training clusters seeking carbon-negative positioning for US enterprise demand. CSA Group cybersecurity certification creates procurement friction for federal government contracts in Ontario and Quebec. Montreal and Toronto anchor bilingual engineering talent pools serving cross-border data sovereignty requirements.
Mexico
Querétaro and Mexico City manufacturing corridors supply modular data center components with accelerated deployment cycles. The country's national energy regulator oversees interconnection standards for foreign-operated facilities. Monterrey emerges as a latency-optimized node for southwestern US enterprise backup workloads.
North America Cloud Computing Market Competitive Landscape
The competitive structure tilts toward hyperscale platform consolidation with three distinct strategic tiers operating in parallel. Vertically integrated infrastructure operators command interconnection queue priority through utility-scale power purchasing. Specialized GPU cloud providers capture AI training overflow from enterprise customers exceeding internal cluster capacity. Regional hosting specialists retain mid-market share through compliance automation and localized support density. Capacity expansion and renewable energy procurement constitute the dominant competitive moves across all tiers.
Within the hyperscale tier, Amazon Web Services, Microsoft Azure, and Google Cloud exemplify platform consolidation through utility-scale infrastructure deployment. These entities occupy positions defined by renewable power purchasing scale and direct liquid cooling R&D intensity rather than commodity compute pricing. Their competitive positioning derives from interconnection queue priority and tax credit capture velocity in Texas and Virginia transmission zones.
| Leading Market Players |
|---|
| Oracle Cloud |
| DigitalOcean |
| Amazon Web Services |
| CoreWeave |
| Vultr |
| Microsoft Azure |
| IBM Cloud |
| Salesforce |
| Google Cloud |
| Others |
Pricing and Supply Chain Analysis
Mid-market enterprise procurement teams accelerating FinOps tooling adoption are forcing hyperscale operators to unbundle reserved instance commitments into consumption-based billing. This shift compresses margin pools in infrastructure-as-a-service tiers while rewarding platform-as-a-service providers with developer tooling stickiness.
Pricing Analysis
Bundled long-term capacity commitments versus unbundled on-demand consumption splits pricing architecture across the North America Cloud Computing Market. Three-tier pricing structure across premium, standard, and economy levels stratifies by service level agreement guarantees and support response times. Cost compression in standard tiers is intensifying because hyperscale operators pass through IRA production tax credit benefits to capture market share. Healthcare systems exhibit highest price sensitivity due to constrained capital budgets, while financial services institutions prioritize compliance automation over unit economics.
Supply Chain Analysis
Reverse-logistics flows for server refurbishment and component recovery are concentrating in Mexico's Querétaro manufacturing corridor, where modular data center skids undergo remanufacturing for redeployment. Supply draws from Taiwan for advanced semiconductors, China for mechanical infrastructure components, and domestic US sources for electrical switchgear and medium-voltage transformers. Single-source vulnerability in liquid cooling cold plate manufacturing rests on concentrated German and Japanese precision machining capacity. Distribution runs through direct hyperscale procurement channels bypassing traditional IT distribution tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Cloud Computing Market functions as a geographic-arbitrage play where Quebec's hydroelectric baseload offers carbon-negative positioning against Texas grid carbon intensity, creating divergent cost structures for AI training cluster deployment.
For Market Incumbents: Deepen utility-scale renewable power purchasing in Virginia and Texas transmission zones to sustain interconnection queue priority against emerging GPU cloud specialists. Anchor direct liquid cooling R&D intensity in Arizona facilities to defend margin position as thermal management commoditizes. Capture IRA production tax credits through co-located solar and wind installations to offset carbon pricing exposure in cross-border Canadian contracts. For New Entrants and Emerging Players: Cloud-native FinOps tooling marketplaces offer the most penetrable entry vector for mid-market healthcare and agricultural IoT segments resisting three-year capacity planning. Target Columbus and Salt Lake City edge computing nodes where latency requirements for autonomous vehicle telemetry outpace hyperscale buildout timelines. Pursue CSA Group cybersecurity certification pathways to unlock Canadian federal procurement in Ottawa and Toronto. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized GPU cloud providers capturing AI training overflow from enterprise customers exceeding internal cluster capacity. Long-term viability hinges on interconnection queue position and renewable power purchase agreement tenure rather than commodity compute pricing. Monitor FERC reform implementation timelines and state renewable portfolio standard acceleration as inflection signals for facility placement sequencing.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Liquid Cooling Deployment | Modular thermal management in Texas and Arizona facilities reduces field engineering variance and accelerates commissioning timelines. |
| Utility-Scale Renewable PPA Execution | IRA production tax credit capture in Virginia transmission zones lowers effective power costs against carbon-intensive grid regions. |
| CSA Group Certification Investment | Cybersecurity compliance automation unlocks Canadian federal procurement in Ontario and Quebec government verticals. |
| Edge Node Dispersion | Micro-data center deployment in Columbus and Salt Lake City reduces latency for autonomous vehicle telemetry workloads. |
| FinOps Platform Integration | Consumption-based billing tooling adoption captures mid-market healthcare and agricultural IoT demand resisting reserved commitments. |
Research Methodology
Bottom-up enterprise workload modeling reconciled against top-down hyperscale capacity tracking forms the analytical core of this study. Primary interviews with cloud procurement officers, platform engineers, data center construction contractors, and utility interconnection planners combined with secondary validation from SEC capex disclosures, FERC interconnection queue databases, and state renewable portfolio standard filings. Triangulation across deployment model adoption rates and service type margin structures anchored volume and value estimates.
Input-output matrices mapping compute demand by vertical to facility energization timelines generated segment-specific growth trajectories across the analysis window. Segmentation dimensions modeled include deployment model, service type, end-user vertical, and regional grid carbon intensity. CAGRs derived from facility construction cycle compression and workload migration velocity assumptions. IRA tax credit capture rates and liquid cooling penetration curves served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for direct liquid cooling versus air-cooled designs would alter the outlook for thermal management infrastructure investment. Forecasts reflect assumptions about FERC reform implementation pace and state renewable portfolio standard stringency. Practitioners should monitor interconnection queue position auctions and municipal water use restriction escalations in Arizona and Texas for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Public Cloud Market
Cloud Computing
Cloud Managed Networking Market
Cloud Computing
Italy Cloud Computing Market
Cloud Computing
UK Cloud Backup Market
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
Retail Cloud Market
Cloud Computing
Global Personal Cloud Market
Cloud Computing
Latin America Cloud Computing Market
Cloud Computing
Cloud Computing Services Market
Cloud Computing
Global Cloud Management Software Market
Cloud Computing
UAE Cloud Computing Market
Cloud Computing
Israel Cloud Computing Market
Cloud Computing
North America Professional Cloud Services Market
Cloud Computing
Europe Mobile Cloud Market
Cloud Computing
Cloud Migration Services Market