
 Hadoop-As-A-Service (Haas) Market | 2026-2036
Hadoop-As-A-Service (Haas) Market Size, Share, and Industry Trends Forecast 2026-2036
Hadoop-As-A-Service (Haas) Market Foresight
Subscription-based software-defined storage tiers is shifting how Hadoop-as-a-Service providers monetize capacity, decoupling compute from storage commitments. Amazon Web Services leverages its managed EMR platform to dominate elastic workload provisioning across enterprise segments. Microsoft Corporation anchors hybrid deployments through Azure HDInsight integration with on-premises Active Directory forests. Google Inc. competes on price-performance for batch analytics through Cloud Dataproc's preemptible instance orchestration.
Hadoop-as-a-Service delivers distributed data processing through managed clusters running open-source Apache Hadoop, Spark, and Hive frameworks on virtualized infrastructure, typically provisioned with node counts scaling from three to thousands depending on workload parallelism requirements. The architecture serves organizations seeking to process petabyte-scale datasets without maintaining physical commodity server farms. Public cloud deployment captures the majority of new workload migrations due to minimal capital outlay and automatic version management, while hybrid cloud configurations attract regulated verticals requiring data residency controls. Data analytics services command premium pricing relative to raw storage provisioning, reflecting embedded machine learning pipeline tooling and pre-configured visualization integrations.
EU GDPR data-localization mandates, US HIPAA safeguards for healthcare workloads, and China's GB standards for cross-border data flows collectively shape provider infrastructure placement and customer certification requirements. The US FDA's guidance on clinical trial data integrity further constrains how pharmaceutical researchers configure audit trails in managed Hadoop environments. Stakeholders must evaluate whether provider-native encryption key management satisfies sector-specific compliance before committing to long-term reserved capacity contracts.
Market Dynamics
Cloud data sovereignty mandates under the EU AI Act and GDPR are forcing Hadoop-as-a-Service providers to rearchitect deployment models around regionally isolated infrastructure zones rather than centralized global pools.
Growth Catalysts
- EU AI Act data localization:German automotive and industrial engineering enterprises must migrate on-premise data lakes to sovereign cloud environments, creating immediate procurement pull for compliant managed clusters.
- Fraud detection workload expansion:Financial services firms across North America and Europe are scaling managed Hadoop capacity specifically for real-time risk analytics pipelines.
- Preemptible instance orchestration:Batch analytics users in technology and research verticals are exploiting spot pricing mechanisms to process petabyte-scale datasets at fractional compute cost.
Market Restraints
- Cross-border data flow restrictions:China's GB standards and comparable national frameworks fragment global workload portability, forcing redundant infrastructure duplication.
- Specialized talent scarcity:Shortage of engineers fluent in Spark optimization, Hive query tuning, and cloud-native security configuration limits cluster utilization efficiency.
- Legacy on-premise sunk costs:Enterprises with substantial existing commodity server investments face extended depreciation timelines that delay cloud migration decisions.
Strategic Opportunities
- Healthcare HIPAA expansion:US pharmaceutical researchers require FDA-aligned audit trail configurations in managed environments, opening specialized compliance-tier service offerings.
- Hybrid Active Directory integration:Microsoft Azure HDInsight's native forest connectivity enables seamless identity federation for regulated enterprises maintaining on-premises control planes.
- Machine learning pipeline convergence:Embedding TensorFlow and PyTorch orchestration directly within managed Hadoop clusters attracts data science teams seeking unified analytics-to-modeling workflows.
Industry Challenges
- Encryption key management certification:Providers must demonstrate sector-specific key custody compliance before pharmaceutical and financial buyers commit to reserved capacity contracts.
- Version fragmentation across open-source components:Incompatible Hadoop, Spark, and Hive release cycles force customers into complex upgrade orchestration or vendor lock-in trade-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hadoop-As-A-Service (Haas) Market |
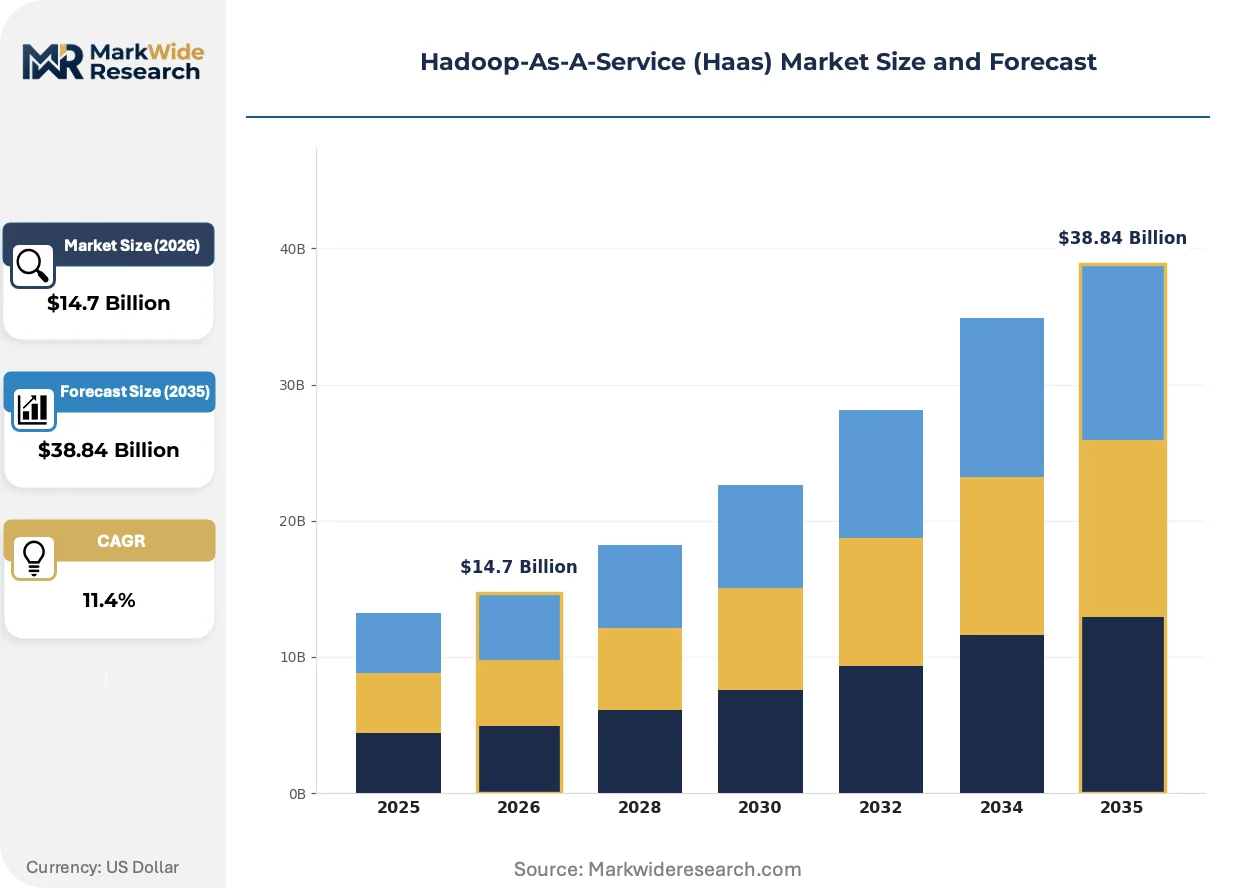
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Data Analytics, Data Management, Data Storage, Data Processing Industry Vertical: Healthcare, Retail, Finance, Telecommunications End User: Enterprises, SMEs, Government, Research Institutions |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google Inc., IBM Corporation, Cloudera Inc., Hortonworks, MapR Technologies, SAP SE, Altiscale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hadoop-As-A-Service (Haas) Market Shifts & Advancements
Software-defined storage architectures are decoupling compute from capacity commitments, enabling consumption models that align costs directly with query execution rather than provisioned hardware.
Kubernetes-native resource orchestration is unifying batch and streaming workload management under single control planes. Data platform teams at Fortune 500 enterprises are adopting containerized Hadoop distributions to collapse separate infrastructure silos. This convergence is compressing vendor differentiation around proprietary management interfaces.
REACH and RoHS substance restrictions in European manufacturing are extending compliance documentation requirements into cloud infrastructure supply chains. Industrial engineering buyers now audit server hardware provenance before selecting managed service providers. German automotive clusters are prioritizing providers with transparent circular economy certifications.
Consumption-based billing granularity has shifted from monthly reserved instances to per-query pricing with automatic scaling. Enterprise procurement functions are replacing three-year capacity commitments with dynamic budget allocation tied to actual data processing volumes. This pattern is most visible among North American technology firms with highly variable analytics workloads.
Hadoop-As-A-Service (Haas) Market Segmentation
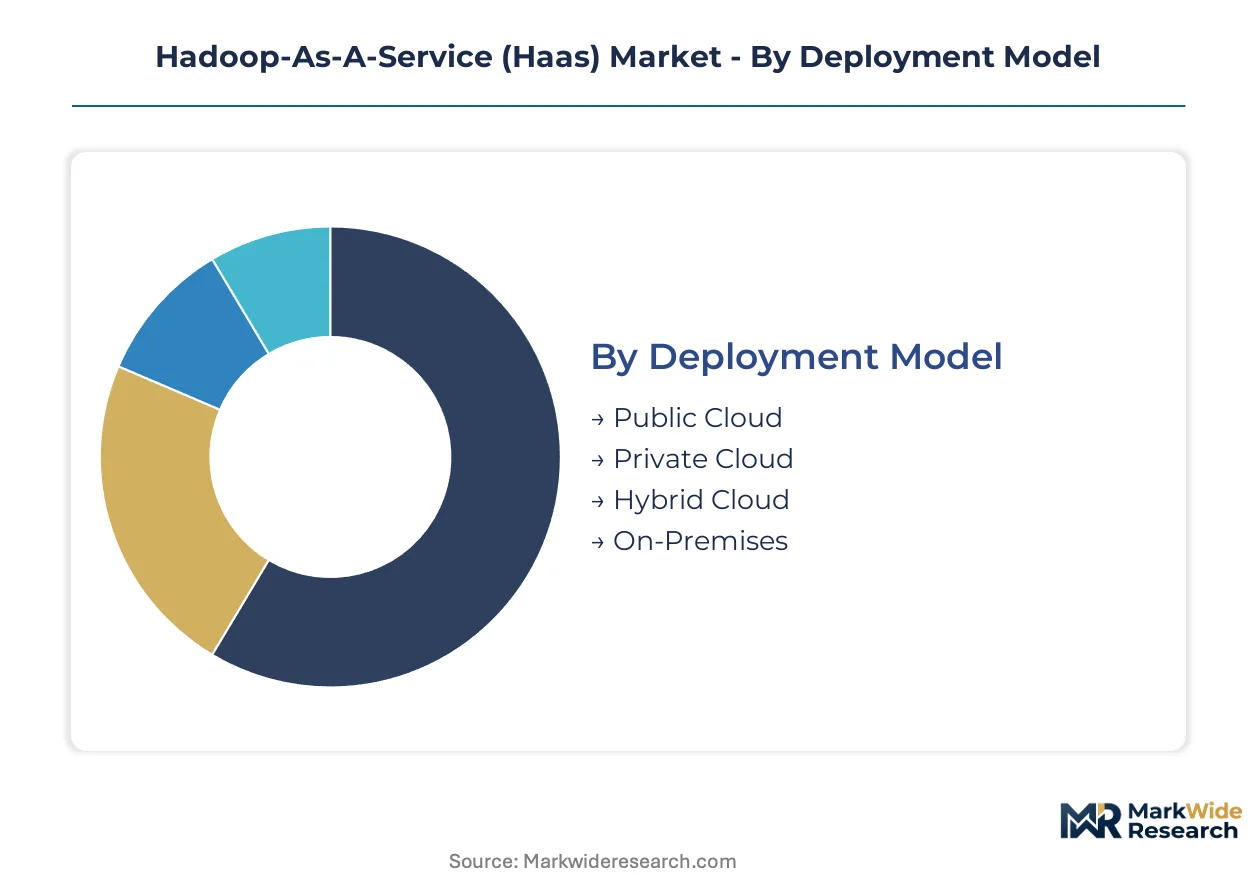
Haas procurement patterns diverge sharply between organizations seeking elastic burst capacity and those requiring fixed infrastructure control. Deployment model selection determines compliance posture, cost structure, and operational staffing requirements across buyer segments.
Deployment Model:
Standardization dominates public cloud offerings while private and hybrid configurations demand extensive customization for data residency and security integration.
- Public Cloud:Fully managed clusters provisioned across shared multi-tenant infrastructure with automatic scaling and version management. Financial services firms in North America and Germany are concentrating procurement here for fraud detection pipelines requiring elastic compute bursts during quarter-end risk calculations.
- Private Cloud:Single-tenant dedicated infrastructure with isolated networking and custom security boundaries. German automotive manufacturers migrating sovereign data lakes under EU AI Act mandates are driving demand for regionally isolated private deployments with hardware provenance documentation.
- Hybrid Cloud:Split workload orchestration across on-premises and cloud nodes with unified management planes. Microsoft Azure HDInsight's Active Directory forest integration enables seamless identity federation for regulated enterprises maintaining on-premises control planes.
- On-Premises:Self-managed clusters within customer data centers retaining full hardware and software stack control. Legacy commodity server investments and extended depreciation timelines delay migration for enterprises with substantial sunk infrastructure costs.
Most installed capacity flows through Public Cloud. Expansion is steepest in Hybrid Cloud.
Service Type:
Value capture concentrates in higher-margin analytics layers rather than raw storage provisioning, with pricing tiers reflecting embedded tooling depth.
- Data Analytics:Managed query engines with pre-configured visualization integrations and machine learning pipeline tooling. Healthcare researchers requiring FDA-aligned audit trail configurations are prioritizing analytics-tier services with embedded compliance documentation.
- Data Processing:Batch and stream compute orchestration including Spark optimization and preemptible instance management. Technology firms exploit spot pricing mechanisms to process petabyte-scale datasets at fractional compute cost.
- Data Management:Metadata governance, lineage tracking, and catalog services across distributed datasets. Enterprises with fragmented data silos adopt these services to unify discovery and access controls.
- Data Storage:Raw distributed file system capacity with replication and durability guarantees. Software-defined storage architectures are decoupling compute from capacity commitments, enabling consumption models that align costs directly with query execution.
Revenue concentrates in Data Analytics. Data Processing is gaining share fastest.
Industry Vertical:
Sector-specific compliance requirements fragment procurement patterns, with regulated verticals demanding certified configurations unavailable in standard tiers.
- Finance:Risk analytics and real-time fraud detection workloads requiring sub-second query latency and immutable audit logs. North American banks are scaling managed Hadoop capacity specifically for regulatory stress testing and transaction monitoring pipelines.
- Healthcare:Clinical trial data integrity and patient record analytics subject to HIPAA safeguards and FDA guidance. US pharmaceutical researchers require specialized encryption key management certification before committing to reserved capacity contracts.
- Retail:Customer behavior analytics and supply chain optimization across omnichannel transaction streams. Demand fluctuates seasonally with holiday shopping volume spikes driving temporary cluster expansion.
- Telecommunications:Network performance monitoring and subscriber churn prediction across billions of daily events. Carriers process call detail records and IoT sensor streams through geographically distributed clusters.
Finance accounts for the largest installed base. Healthcare shows the steepest expansion trajectory.
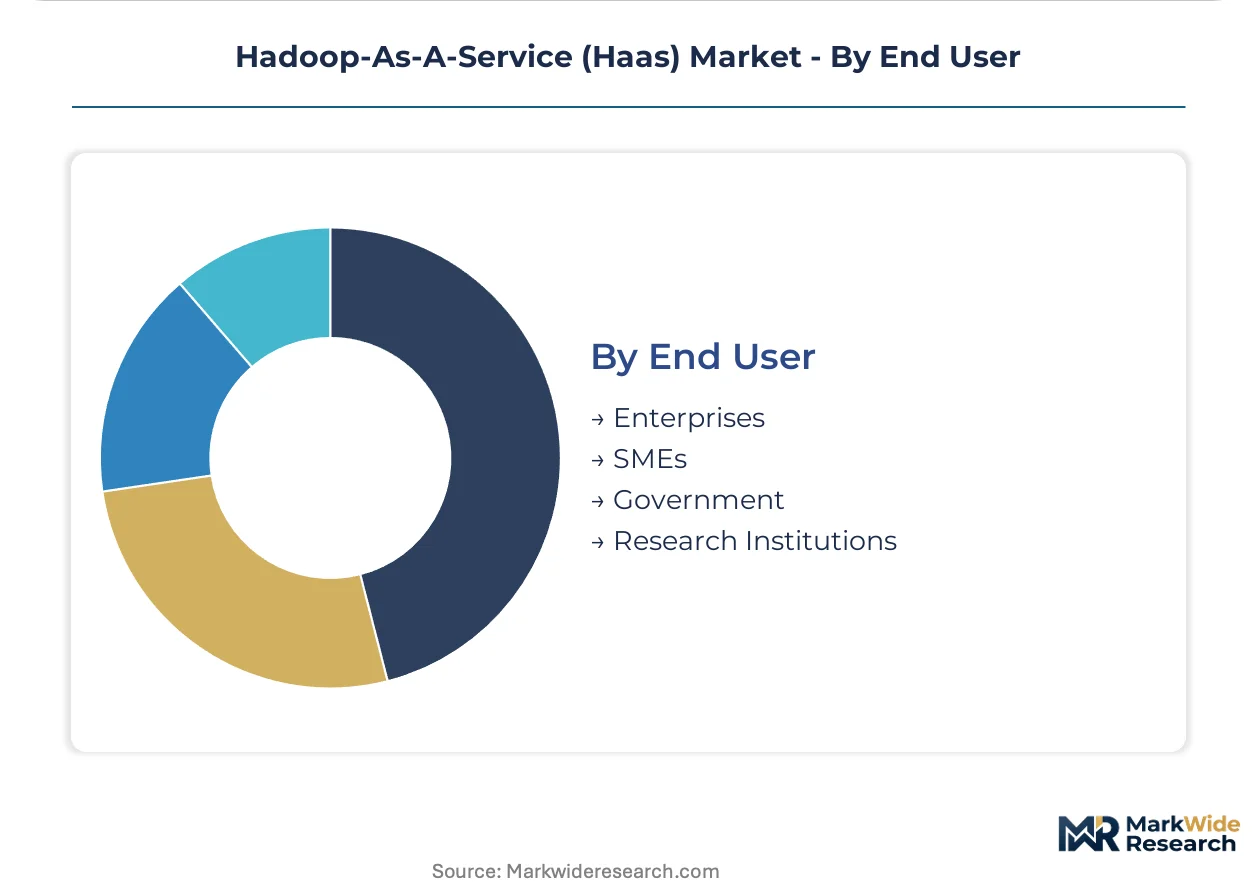
End User:
Procurement sophistication varies dramatically by organizational scale, with enterprises negotiating reserved capacity and smaller buyers accepting standard consumption terms.
- Enterprises:Fortune 500 data platform teams with dedicated cloud architecture functions and multi-year budget cycles. These buyers negotiate custom service level agreements and demand Kubernetes-native resource orchestration to collapse separate infrastructure silos.
- SMEs:Mid-market organizations without specialized Spark optimization or Hive query tuning expertise. Shortage of engineers fluent in cloud-native security configuration limits cluster utilization efficiency for this segment.
- Government:Public sector agencies with sovereign data requirements and mandatory competitive procurement processes. China's GB standards for cross-border data flows and comparable national frameworks fragment workload portability for multi-national government contracts.
- Research Institutions:Academic and non-profit organizations with grant-funded, unpredictable compute needs. Preemptible instance orchestration attracts batch analytics users in technology and research verticals seeking fractional compute cost.
Enterprises dominate committed capacity. Research Institutions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are steering Hadoop-as-a-Service procurement toward jurisdictions with clarified data-sovereignty frameworks, as compliance cost differentials between the EU, US, and Asia-Pacific reshape provider infrastructure placement strategies.
United States
Financial services firms in New York and Chicago are scaling managed EMR capacity for fraud detection pipelines requiring sub-second query latency. HIPAA safeguards and FDA guidance on clinical trial data integrity constrain pharmaceutical researchers configuring audit trails. The Boston-Cambridge biotech cluster demands specialized encryption key management certification before committing to reserved capacity contracts.
Germany
Automotive and industrial engineering enterprises in Stuttgart and Munich are migrating on-premise data lakes to sovereign cloud environments under EU AI Act mandates. REACH and RoHS substance restrictions extend compliance documentation requirements into cloud infrastructure supply chains. The Bavarian manufacturing corridor prioritizes providers with transparent circular economy certifications and hardware provenance documentation.
China
Technology firms in Beijing and Shanghai are processing petabyte-scale datasets through preemptible instance orchestration at fractional compute cost. GB standards for cross-border data flows fragment global workload portability, forcing redundant infrastructure duplication. The Yangtze River Delta industrial belt concentrates demand for regionally isolated private deployments with custom security boundaries.
United Kingdom
London-based financial institutions require hybrid Active Directory integration for seamless identity federation with on-premises control planes. GDPR data-localization mandates steer procurement toward regionally compliant deployments with isolated networking. The Thames Valley tech corridor attracts Kubernetes-native resource orchestration adoption among Fortune 500 data platform teams.
India
Research institutions in Bengaluru and Hyderabad exploit spot pricing mechanisms for grant-funded, unpredictable compute needs in batch analytics workloads. The country's national data protection framework shapes provider infrastructure placement for government contracts. The Maharashtra-Andhra Pradesh industrial belt concentrates SME demand lacking specialized Spark optimization expertise.
Hadoop-As-A-Service (Haas) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud providers capturing elastic workload provisioning while dedicated Hadoop vendors retain fixed-infrastructure control deployments. The vendor base concentrates around three strategic tiers: public cloud platforms with managed distribution services, enterprise software houses with hybrid integration capabilities, and pure-play analytics specialists with embedded machine learning tooling. Dominant competitive moves include strategic partnerships for sovereign cloud certification and portfolio diversification into Kubernetes-native orchestration layers.
Among US-based hyperscale platforms, Amazon Web Services, Microsoft Corporation, and Google Inc. occupy positions anchoring the public cloud tier through managed EMR, Azure HDInsight, and Cloud Dataproc offerings respectively. These entities exemplify the scale-driven archetype competing on elastic provisioning and preemptible instance orchestration for variable analytics workloads.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Google Inc. |
| IBM Corporation |
| Cloudera Inc. |
| Hortonworks |
| MapR Technologies |
| SAP SE |
| Altiscale |
| Others |
Supply & Pricing Matrix
Spot pricing indices for preemptible cloud compute instances cascade through Hadoop-as-a-Service cost structures, compressing margins on batch analytics tiers while amplifying differentiation premiums for sovereign-compliant private deployments. German automotive buyers absorbing REACH and RoHS documentation costs drive hardware provenance audits that propagate upstream into supplier certification requirements.
Pricing Analysis
Distributor margin compression in the hyperscaler channel pressures third-party managed service providers to differentiate through value-added layers. Consumption-based billing stratifies across premium analytics tiers with embedded machine learning tooling, standard data processing with spot instance orchestration, and economy storage-only provisioning. Cost compression in the standard tier intensifies as Google Cloud Dataproc and AWS EMR automate preemptible workload scheduling. Research institutions exhibit highest price sensitivity, while pharmaceutical enterprises under FDA audit requirements demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries supplying the server processors anchoring managed cluster infrastructure. Hardware assembly concentrates in China, Mexico, and the Czech Republic, with memory modules drawing from South Korean and Japanese component suppliers. Tariff exposure on Chinese-manufactured server chassis threatens cost structures for regionally isolated private deployments. Distribution runs through direct hyperscaler marketplaces and specialized systems integrators serving regulated verticals with customized compliance configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hadoop-as-a-Service procurement functions as a geographic-arbitrage play where EU AI Act compliance costs in Germany diverge sharply from spot-priced elastic capacity in North America, creating margin expansion opportunities for providers with dual-footprint architectures.
For Market Incumbents: Acquire Kubernetes-native orchestration platforms to collapse separate infrastructure silos before containerized distributions commoditize proprietary management interfaces. Threat substitution from unified analytics-to-modeling workflows embedding TensorFlow and PyTorch orchestration demands defensive consolidation. Certification investment in FDA-aligned audit trail configurations secures pharmaceutical reserved capacity contracts against emerging compliance-tier specialists. For New Entrants and Emerging Players: Begin with hybrid Active Directory integration capabilities targeting UK financial institutions requiring seamless identity federation with on-premises control planes. White-space concentration sits in SME segments lacking Spark optimization expertise, where managed query tuning services penetrate at lower acquisition cost than enterprise accounts. Go-to-market leverage through Microsoft Azure co-sell partnerships accelerates credibility with regulated buyers. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play analytics specialists possessing embedded machine learning tooling and healthcare HIPAA certification pathways. Long-term viability hinges on convergence toward unified batch-streaming control planes over the next decade. Watch sovereign cloud certification velocity in Germany as the inflection signal for compliance-tier provider valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Kubernetes-native orchestration targets collapse infrastructure silos for Fortune 500 data platform teams. |
| Strategic Partnership | Microsoft Azure co-sell agreements accelerate credibility with UK financial institutions requiring hybrid identity federation. |
| Geographic Expansion | Regionally isolated private deployments capture German automotive migration under EU AI Act mandates. |
| Product Launch | FDA-aligned audit trail configurations unlock pharmaceutical reserved capacity contracts with specialized encryption key management. |
| Platform Integration | Embedded TensorFlow and PyTorch orchestration attracts data science teams seeking unified analytics-to-modeling workflows. |
Research Methodology
Direct dialogue with cloud architects at Fortune 500 enterprises, Hadoop platform engineers at financial services firms, compliance officers at pharmaceutical researchers, and procurement leads at German automotive manufacturers grounded qualitative findings. Secondary validation drew from SEC filings of hyperscale providers, EU AI Act implementation guidance, FDA clinical trial data integrity documentation, and hyperscaler capex disclosures. Bottom-up cluster deployment estimates triangulated against top-down market sizing across deployment models and service tiers.
Bottom-up modeling of node-hour consumption patterns across public, private, hybrid, and on-premises configurations fed into value projections across the analysis window. Segmentation dimensions spanned deployment model, service type, industry vertical, and end-user scale. CAGRs derived from elasticity-adjusted growth curves incorporating sovereign cloud certification velocity and spot pricing mechanism adoption. Industry-specific inputs included EU AI Act implementation timelines and FDA audit trail configuration requirements.
Caveats apply where cross-border data flow restrictions under China's GB standards or accelerated GDPR enforcement could materially shift the outlook for global workload portability assumptions. Forecasts reflect documented assumptions about sovereign cloud certification adoption and preemptible instance orchestration penetration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Cloud Microservice and Application Market
Cloud Computing
VM Service Market
Cloud Computing
Canada Cloud Computing Market
Cloud Computing
Cloud Enterprise Content Management Market
Cloud Computing
Global Cloud Dictation Solution Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Hybrid Cloud Market
Cloud Computing
GPU As a Service (Gpuaas) Market
Cloud Computing
Asia Pacific Multi-Cloud Management Market
Cloud Computing
Retail Cloud Market
Cloud Computing
Cloud Computing Stack Layers Market
Cloud Computing
Containers As a Service (Caas) Market
Cloud Computing
Global Hybrid and Community Cloud As a Service Market
Cloud Computing
Cloud CDN Market
Cloud Computing
Dbaas and Cloud Database Market