
 Southeast Asia Aviation Market | 2026-2036
Southeast Asia Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Aviation Market Outlook
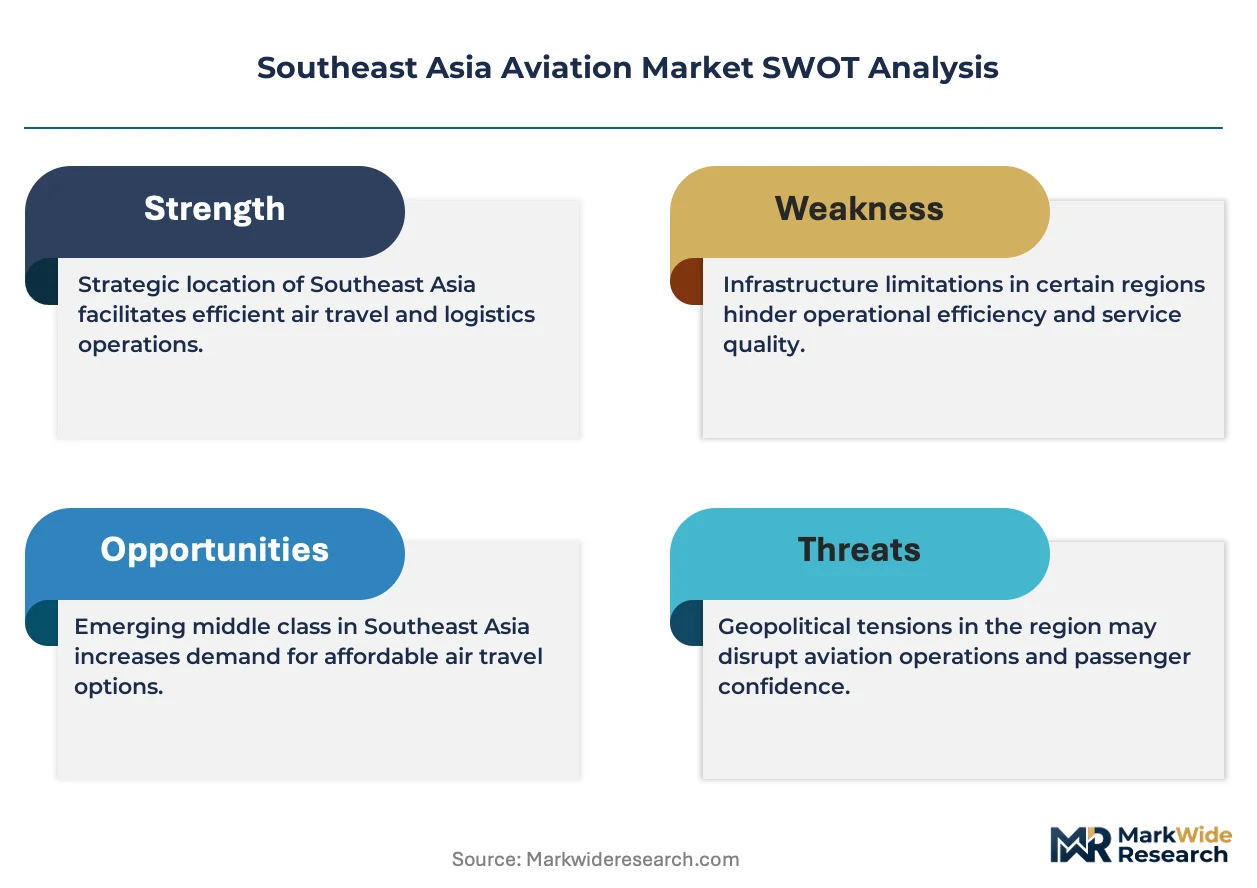
Airport slot allocation and ground handling agreements is reconfiguring competitive access across Southeast Asian hubs. Singapore Airlines leverages its Changi hub dominance to control premium long-haul connections. AirAsia anchors ultra-low-cost penetration across secondary cities in Malaysia, Thailand, and Indonesia. VietJet competes aggressively on price-sensitive domestic and cross-border routes within Vietnam and beyond.
Southeast Asia aviation encompasses commercial air transport operations across a tropical archipelago geography demanding extended-range twin-engine performance and high-cycle landing gear durability for short-haul, high-frequency deployment. The sector serves passenger mobility, cargo logistics, and tourism-dependent economies where aviation functions as critical trade and employment infrastructure. Commercial flights dominate service type revenue, while cargo aircraft represents the fastest-expanding aircraft type segment driven by e-commerce fulfillment networks across the Mekong region. Avionics systems within the technology dimension command concentrated investment as airlines retrofit aging fleets for required navigation performance and satellite-based communication mandates.
Indonesia's Directorate General of Civil Aviation, Malaysia's Civil Aviation Authority, and the ASEAN Transport Ministers' regulatory harmonization framework collectively shape air operator certification, safety audit protocols, and cross-border route licensing across the region. These bodies enforce ICAO-aligned standards while negotiating bilateral and multilateral traffic rights that determine market entry feasibility for new carriers. Stakeholders must monitor pending carbon offset integration into ASEAN aviation policy and the divergence between national safety regulator enforcement capacities as fleet expansion outpaces inspector training pipelines.
Market Dynamics
The ASEAN Single Aviation Market framework is dismantling bilateral route restrictions, triggering a scramble for slot control at constrained hubs like Jakarta Soekarno-Hatta and Manila Ninoy Aquino where infrastructure expansion lags fleet growth.
Growth Catalysts
- ASEAN Open Skies Protocols:The ASEAN Transport Ministers' multilateral agreements are eliminating fifth-freedom restrictions, enabling carriers to establish triangular routes between Singapore, Bangkok, and secondary Indonesian cities without multiple bilateral negotiations.
- E-commerce Cargo Networks:Mekong region fulfillment centers are demanding dedicated freighter capacity, pulling converted narrow-body aircraft into night-hour operations across Vietnam, Thailand, and the Philippines.
- Avionics Retrofit Mandates:Indonesia's Directorate General of Civil Aviation is enforcing required navigation performance authorization for all aircraft operating above FL290, compelling fleet-wide GPS and satellite communication upgrades.
Market Restraints
- Jet Fuel Price Volatility:Singapore jet kerosene benchmarks swing with Brent crude movements, compressing low-cost carrier margins on thin-yield domestic Indonesian and Vietnamese trunk routes.
- Pilot Training Pipeline Bottlenecks:CAE and L3Harris simulator capacity in Southeast Asia cannot match Indonesian and Vietnamese carrier fleet expansion schedules, extending first-officer upgrade timelines.
- Slot Coordination Rigidity:IATA Level 3 slot constraints at Jakarta Soekarno-Hatta and Manila Ninoy Aquino freeze new entrant access, entrenching incumbents with grandfathered morning departure banks.
Strategic Opportunities
- Secondary City Point-to-Point:Da Nang, Surabaya, and Cebu lack direct connectivity to tier-2 Chinese and Indian cities, creating white space for narrow-body long-range operations bypassing hub congestion.
- Sustainable Aviation Fuel Incentives:Singapore's carbon tax regime and proposed ASEAN SAF blending mandates are positioning Changi as a regional biofuel bunkering hub for transit carriers.
- Maintenance, Repair and Overhaul Regionalization:Airframe heavy check capacity shortages in Indonesia and Vietnam are pushing operators toward third-party MRO joint ventures in Malaysia and Thailand.
Industry Challenges
- Airworthiness Inspector Shortage:Indonesia's Directorate General of Civil Aviation and Vietnam's CAAV lack sufficient qualified personnel to certify new aircraft deliveries and oversee continuing airworthiness at expanded fleet scales.
- Legacy Reservation System Integration:Hybrid carriers attempting to merge low-cost operations with premium long-haul products face passenger service system fragmentation between Sabre, Amadeus, and in-house platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Aviation Market |
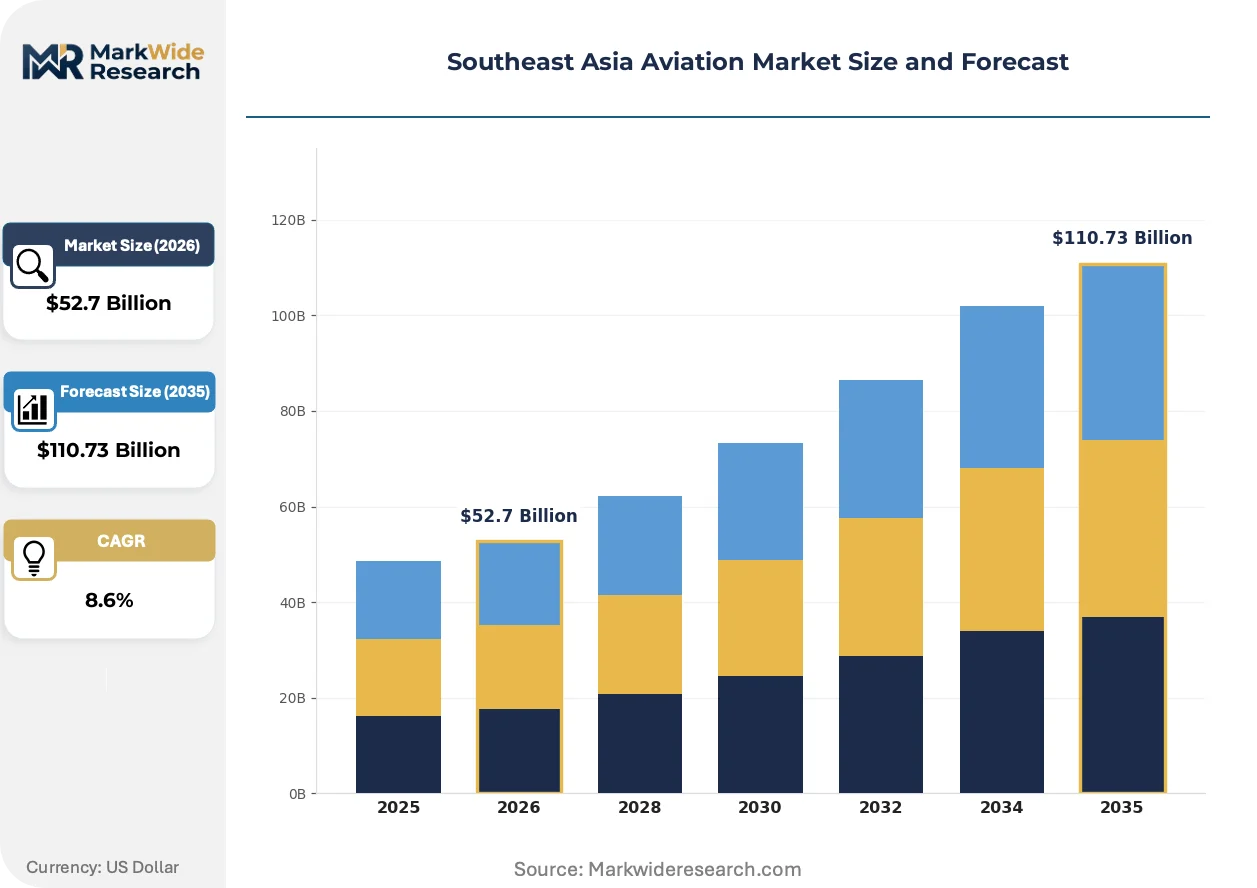
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Commercial Flights, Charter Services, Cargo Transport, VIP Services Aircraft Type: Passenger Aircraft, Cargo Aircraft, Business Jets, Helicopters End User: Airlines, Freight Forwarders, Private Owners, Government Agencies Technology: Avionics Systems, Engine Technologies, Navigation Aids, Communication Systems |
| Companies Covered | Malaysia Airlines, AirAsia, Singapore Airlines, VietJet, Lion Air, Philippine Airlines, Vietnam Airlines, Cebu Pacific Air, Thai Airways, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Aviation Market Strategic Shifts
Digital infrastructure is compressing operational decision cycles across Southeast Asian carriers, while regulatory pressure on emissions and safety data transparency is forcing technology adoption ahead of traditional replacement schedules.
Predictive maintenance platforms using engine sensor telemetry and machine learning algorithms are digitizing fleet reliability management for Garuda Indonesia and Vietnam Airlines. These systems process full-flight data downloads to flag component degradation before hard-time limits trigger removals. Maintenance planning departments are adopting these tools to reduce AOG incidents at outstations lacking spare part inventories.
Indonesia's Directorate General of Civil Aviation is mandating flight data monitoring and safety management system integration for all scheduled operators above thirty seats, aligning with ICAO Annex 19 standards. This regulatory push is compelling budget carriers to deploy cloud-based FOQA analytics rather than manual download processes. Smaller Indonesian operators without in-house safety departments are outsourcing compliance to third-party aviation consulting firms in Singapore.
Corporate travel procurement in Singapore and Kuala Lumpur is consolidating spend through managed travel platforms that unbundle ancillary services from base fares. Travel managers at financial services and technology firms are negotiating direct NDC connections with carriers to capture seat selection and baggage fees within expense systems. This behavioral shift is most pronounced in Singapore's central business district, where multinational headquarters dominate regional travel budgets.
Southeast Asia Aviation Market Segmentation
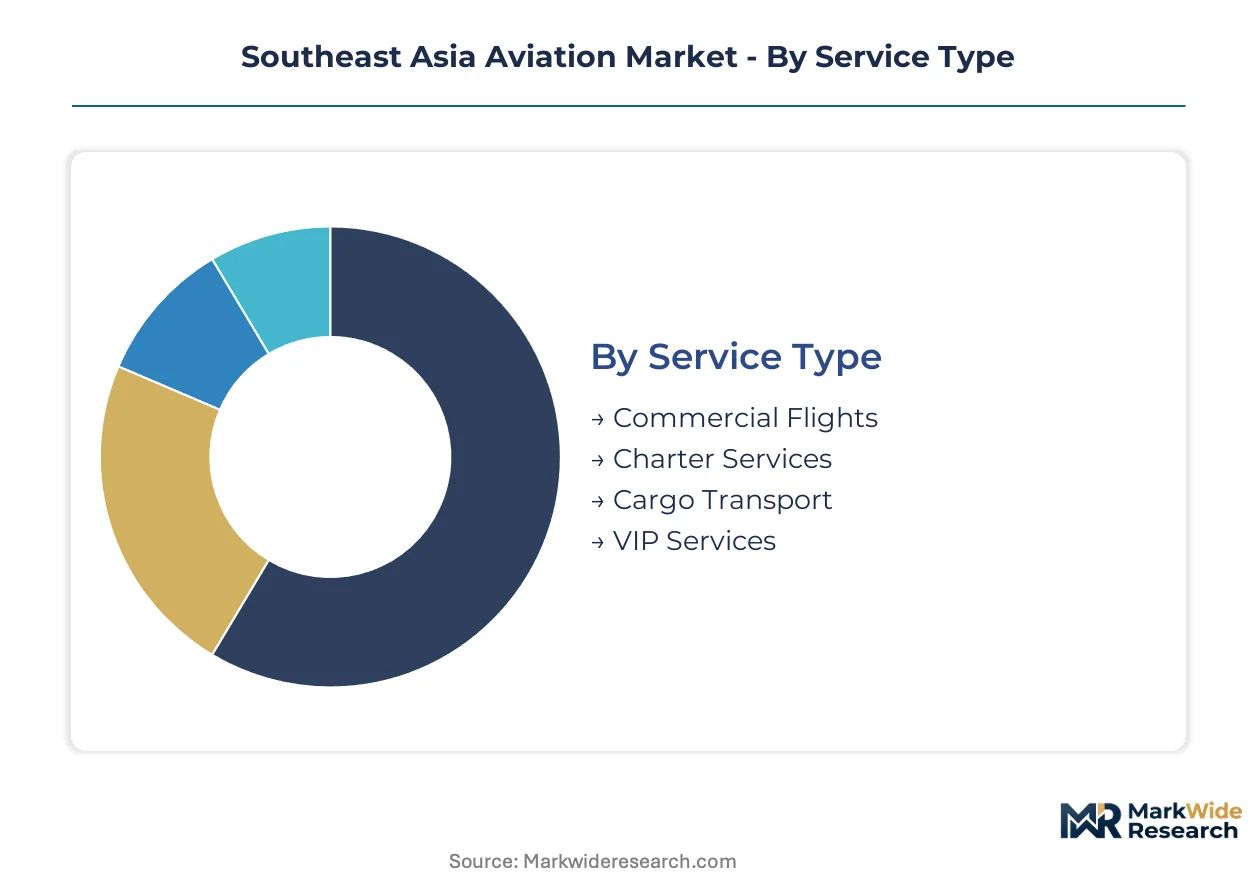
Southeast Asian aviation demand fragments across operational models shaped by archipelago geography, regulatory divergence, and infrastructure asymmetry. Fleet configuration and service tier selection determine carrier economics on thin-yield trunk routes and premium long-haul corridors alike.
Service Type:
Cost tier determines operational scale and margin structure across Southeast Asian air transport modes.
- Commercial Flights:Scheduled narrow-body and wide-body operations dominate seat capacity deployment across Jakarta, Bangkok, and Singapore hubs. Indonesian and Vietnamese low-cost carriers concentrate frequency on domestic trunk routes where airport slot scarcity constrains new entrant expansion.
- Cargo Transport:Converted freighter aircraft and belly-hold capacity serve Mekong region e-commerce fulfillment networks with night-hour scheduling. Vietnam and Thailand function as primary sorting nodes for cross-border parcel flows into China and India.
- Charter Services:Seasonal tourist movements and corporate shuttle contracts sustain ad-hoc operators in Bali and Phuket leisure corridors.
- VIP Services:Business jet and helicopter charter address executive mobility across archipelago jurisdictions with limited commercial frequency.
Commercial Flights holds installed capacity. Cargo Transport is rotating up the share rankings.
Aircraft Type:
Application dictates airframe selection for range, payload, and cycle durability requirements.
- Passenger Aircraft:Single-aisle platforms command Southeast Asian fleet orders for high-frequency short-haul deployment between secondary cities. Airbus A320neo and Boeing 737 MAX families anchor Indonesian and Vietnamese carrier expansion programs.
- Cargo Aircraft:Narrow-body conversions and dedicated wide-body freighters address express logistics demand from Ho Chi Minh City and Bangkok distribution centers. E-commerce volume growth is pulling retired passenger airframes into cargo modification pipelines.
- Business Jets:Long-range platforms serve inter-ASEAN executive travel bypassing commercial hub congestion.
- Helicopters:Rotary-wing assets support offshore energy logistics and emergency medical evacuation across Indonesian and Philippine island chains.
Passenger Aircraft holds installed capacity. Cargo Aircraft is climbing the fastest.
End User:
Customer type shapes procurement scale and fleet financing structures across the region.
- Airlines:Scheduled carriers in Indonesia, Vietnam, and Thailand drive fleet renewal through sale-leaseback arrangements and export credit agency financing. Jakarta and Ho Chi Minh City headquarters control multi-billion-dollar narrow-body order books.
- Freight Forwarders:Logistics integrators contract dedicated freighter capacity and block space agreements on passenger belly-hold networks. DHL and FedEx sortation hubs in Singapore and Bangkok determine regional cargo aircraft deployment patterns.
- Private Owners:High-net-worth individuals and corporate flight departments acquire business jets through Singapore and Kuala Lumpur registries.
- Government Agencies:Military and paramilitary operators procure maritime patrol and transport platforms for archipelago surveillance missions.
Airlines holds installed capacity. Freight Forwarders is gaining share fastest.
Technology:
Maturity gaps between legacy fleets and regulatory mandates create retrofit investment cycles.
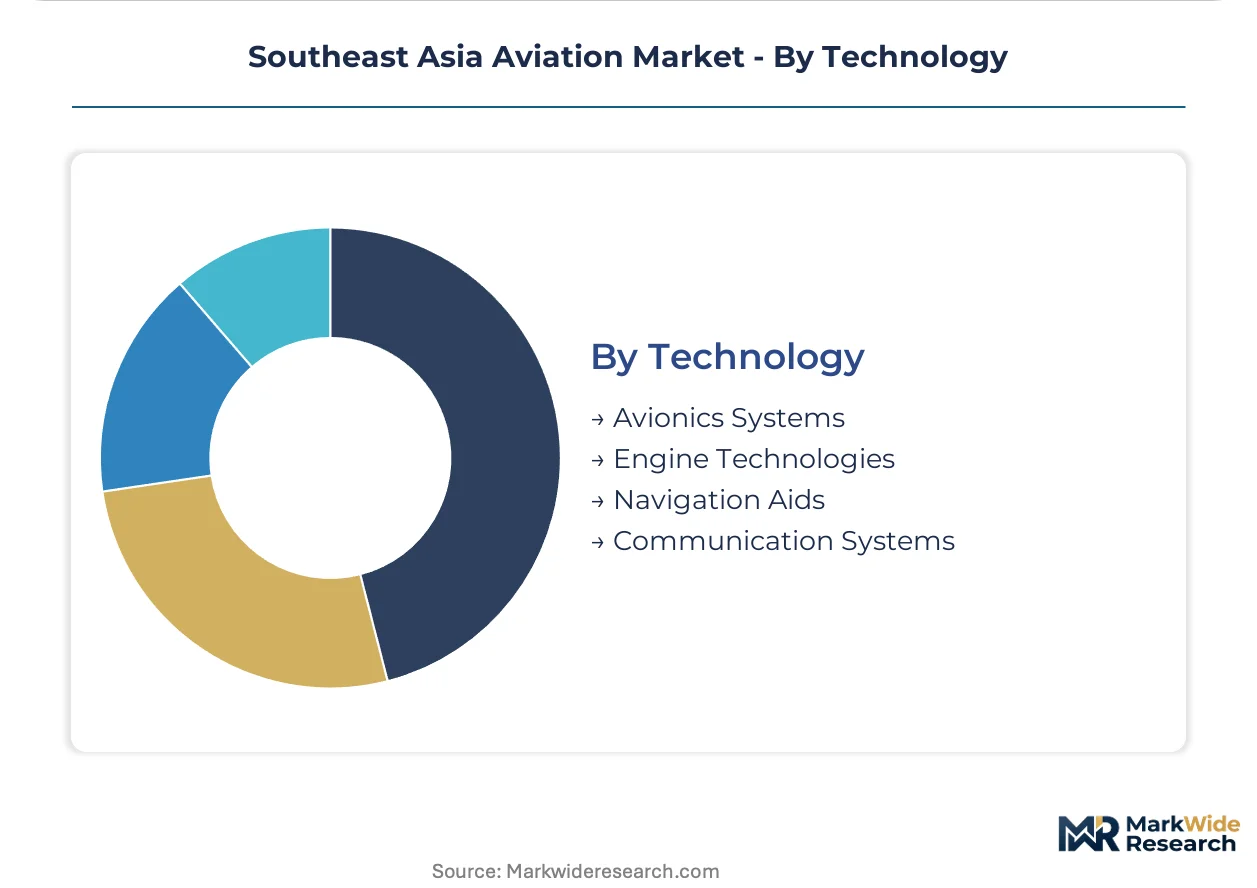
- Avionics Systems:Flight management computers, GPS navigation, and satellite communication suites require fleet-wide upgrades for required navigation performance authorization above FL290. Indonesia's Directorate General of Civil Aviation mandates equipage deadlines compressing installation schedules.
- Engine Technologies:High-bypass turbofans with improved fuel efficiency anchor new narrow-body deliveries from Airbus and Boeing. Leap and PW1100G powerplants dominate Indonesian and Vietnamese carrier order specifications.
- Navigation Aids:Ground-based augmentation and satellite-based landing systems enable precision approaches at secondary airports lacking instrument landing infrastructure.
- Communication Systems:C-band and L-band datalink equipage satisfies ICAO global air navigation mandates for controller-pilot data link communications.
Avionics Systems holds installed capacity. Engine Technologies is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Changi Airport's fifth terminal expansion underwrites Singapore's role as the primary aviation gateway for Southeast Asian connectivity. The ASEAN Single Aviation Market framework is liberalizing cross-border route rights across member states. This regional outlook examines five national markets driving fleet deployment and infrastructure investment.
Indonesia
Jakarta Soekarno-Hatta and Denpasar function as hub-and-spoke nodes for domestic and international traffic. The Directorate General of Civil Aviation enforces required navigation performance authorization for aircraft operating above FL290. Surabaya anchors secondary city point-to-point expansion as Lion Air and Garuda Indonesia add narrow-body frequency on trunk routes.
Vietnam
VietJet and Vietnam Airlines compete aggressively on price-sensitive domestic and cross-border routes. The Civil Aviation Authority of Vietnam struggles with airworthiness inspector shortages as fleet expansion outpaces certification capacity. Ho Chi Minh City and Hanoi concentrate e-commerce cargo demand pulling converted narrow-body aircraft into night-hour operations.
Singapore
Singapore Airlines leverages Changi hub dominance to control premium long-haul connections. The city-state's carbon tax regime and proposed SAF blending mandates position Changi as a regional biofuel bunkering hub. The Civil Aviation Authority of Singapore coordinates ASEAN regulatory harmonization for safety audit protocols.
Thailand
Thai Airways and low-cost operators serve leisure corridors from Bangkok Suvarnabhumi to Phuket and secondary destinations. The Department of Civil Aviation manages slot coordination at constrained airports where infrastructure expansion lags fleet growth. Bangkok functions as a primary sorting node for cross-border parcel flows into China and India.
Philippines
Cebu Pacific Air and Philippine Airlines operate from Manila Ninoy Aquino where IATA Level 3 slot constraints freeze new entrant access. The Civil Aviation Authority of the Philippines enforces ICAO-aligned standards for air operator certification. Cebu lacks direct connectivity to tier-2 Chinese and Indian cities, creating white space for narrow-body long-range operations.
Southeast Asia Aviation Market Competitive Environment
On the supply side, the industry is consolidating around hub-and-spoke network carriers and ultra-low-cost operators with divergent fleet strategies. Full-service airlines control premium long-haul connections through alliance memberships and slot dominance at primary airports. Three strategic archetypes define competitive positioning: legacy flag carriers with government shareholding, independent low-cost specialists, and hybrid operators attempting dual-class service tiers. Capacity expansion through narrow-body orders and strategic partnerships for maintenance, repair and overhaul regionalization represent dominant competitive moves.
Within the legacy flag carrier tier, Singapore Airlines, Vietnam Airlines, and Thai Airways exemplify government-influenced network operators balancing premium service delivery against low-cost encroachment on regional routes. These carriers occupy positions between global alliance integration and ASEAN intra-regional connectivity mandates, with fleet decisions reflecting tension between wide-body long-haul deployment and narrow-body frequency competition.
| Leading Market Players |
|---|
| Malaysia Airlines |
| AirAsia |
| Singapore Airlines |
| VietJet |
| Lion Air |
| Philippine Airlines |
| Vietnam Airlines |
| Cebu Pacific Air |
| Thai Airways |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Indonesian narrow-body MRO facilities compresses third-party maintenance rates while concentrating bargaining power with Singapore-based lessors and Jakarta-headquartered fleet managers. This utilization asymmetry shapes how carriers negotiate power-by-the-hour contracts and select between in-house heavy checks versus outsourced airframe services.
Pricing Analysis
Volume-discount tiering structures dominate aircraft leasing and engine maintenance agreements, with larger Indonesian and Vietnamese carriers extracting steeper discounts on narrow-body sale-leaseback arrangements than smaller charter operators. Price differentiation rests on fleet scale and credit rating tier, with flag carriers commanding preferred lessor terms over ultra-low-cost entrants. Cost compression in third-party MRO services is intensifying because Lion Air and AirAsia Group internalize heavy-check capacity through joint ventures. Freight forwarders exhibit highest price sensitivity on belly-hold block space, while government agencies show lowest sensitivity on maritime patrol platform procurement.
Supply Chain Analysis
Contract-manufacturing concentration for avionics retrofit kits sits with Thales and Honeywell regional distribution centers in Singapore and Kuala Lumpur, while engine assembly feeds from Pratt & Whitney and CFM International facilities in the United States and France. Geographic supply concentration centers on Singapore for component warehousing, Malaysia for airframe heavy maintenance, and Indonesia for line-station spare parts staging. Raw material dependencies span aerospace-grade aluminum from China, titanium forgings from Russia, and composite prepregs from Japan. Single-source vulnerability on Leap engine high-pressure turbine blades constitutes primary supply chain risk. Distribution runs through lessor-managed pooled spare programs and airline-owned consignment stocks at Jakarta and Bangkok hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Singapore-based aircraft lessors and Jakarta-headquartered fleet managers, with consolidation in sale-leaseback advisory squeezing regional carrier procurement flexibility.
For Market Incumbents: Harden slot portfolio defenses at Jakarta Soekarno-Hatta and Manila Ninoy Aquino through grandfathered morning departure banks and code-share alliances with secondary-city feeders. Deepen backward integration into MRO joint ventures in Malaysia and Thailand to capture maintenance margin and reduce airworthiness inspector dependency on third parties. For New Entrants and Emerging Players: Establish a beachhead in Surabaya-Cebu point-to-point routes bypassing hub congestion, where white space exists for narrow-body long-range operations to tier-2 Chinese cities. Target Da Nang and Clark as alternative bases with lower slot coordination rigidity. Pursue direct NDC connections with Singapore-based corporate travel managers to capture ancillary revenue within managed travel platforms. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because ASEAN Single Aviation Market liberalization will progressively dismantle bilateral restrictions and reward carriers with pre-positioned route authorities. Acquisition targets should emphasize hybrid operators with dual-class service tiers and fragmented reservation system infrastructure ripe for platform consolidation. Monitor Indonesia's Directorate General of Civil Aviation inspector training pipeline expansion as inflection signal for fleet delivery certification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Slot Portfolio Consolidation | Grandfathered morning banks at Jakarta Soekarno-Hatta entrench incumbents against new entrant expansion. |
| MRO Joint Venture Expansion | Third-party heavy-check capacity in Malaysia and Thailand addresses Indonesian airworthiness inspector shortages. |
| Avionics Retrofit Program Acceleration | Required navigation performance mandates above FL290 compel fleet-wide GPS and satellite communication upgrades. |
| Secondary City Point-to-Point Launch | Direct Surabaya and Da Nang connections bypass hub congestion and capture unserved demand to tier-2 Chinese markets. |
| Sustainable Aviation Fuel Bunkering Investment | Singapore's carbon tax regime positions Changi as regional biofuel hub for transit carrier refueling. |
Study Parameters
Operator-level perspectives from fleet planning directors, MRO procurement managers, slot coordination officers, and lessor asset managers anchored the qualitative base. Primary interviews combined with secondary validation against IATA slot coordination databases, ICAO safety audit reports, ASEAN Transport Ministers' regulatory filings, and carrier annual disclosures. Bottom-up fleet deployment models triangulated with top-down market sizing across service type, aircraft type, and technology segmentation dimensions.
Scenario-bracketing framed demand projections across the analysis window, with optimistic and conservative bounds reflecting ASEAN Open Skies implementation pace and jet fuel price volatility. Segmentation modeling incorporated service tier, aircraft platform generation, end-user procurement scale, and avionics retrofit compliance status. CAGRs derived from fleet order backlogs, delivery schedules, and retirement assumptions. Forecast inputs included CAE and L3Harris simulator capacity expansion timelines and Indonesia's Directorate General of Civil Aviation inspector training graduation rates.
Sensitivities concentrate around Brent crude price movements, CAAC and DGCA regulatory harmonization delays, and airworthiness certification bottlenecks. Forecasts embed assumptions on ASEAN Single Aviation Market progression and SAF blending mandate adoption without binding policy commitments. Quarterly review of Singapore jet kerosene benchmarks, Jakarta slot coordination level changes, and Indonesian simulator capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Flight Control System Market
Aircraft
Small Evtol Aircraft Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Aviation Market
Aircraft
Water Bomber Market
Aircraft
GCC Business Jet Market
Aircraft
Heavy-Lift Helicopter Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
North America Helicopters Market
Aircraft
Global Aircraft Design and Engineering Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
Asia-Pacific Business Jet Market
Aircraft
Afterburner Market
Aircraft
America Freighter Aircraft Market
Aircraft
India Aviation Market