
 Vietnam Business Jets and Helicopters Market | 2026-2036
Vietnam Business Jets and Helicopters Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Business Jets and Helicopters Market Insights
Southeast Asia's MRO infrastructure expansion is narrowing the operational gap between Vietnam-based operators and regional hubs in Singapore and Thailand. Bombardier Inc leverages its aftermarket network to sustain long-term service contracts with Vietnamese charter providers. Airbus SE dominates the helicopter segment through its localized technical support partnerships, while Leonardo SpA competes aggressively in the medium-twin rotary category with specialized offshore configurations.
Business jets and helicopters constitute turbine-powered rotary-wing and fixed-wing aircraft purpose-built for private, corporate, and specialized commercial transport, typically operating at altitudes below 45,000 feet with pressurized cabins and ranges spanning 1,200 to 7,500 nautical miles depending on class. These platforms serve time-critical executive mobility, emergency medical evacuation, and offshore energy logistics where commercial airline schedules prove incompatible. The aircraft type dimension shows light jets capturing the majority of new deliveries into Vietnam as entry-level fractional ownership expands, while heavy jets concentrate margin pools among ultra-high-net-worth private owners in Hanoi and Ho Chi Minh City. Charter providers represent the fastest-growing end user category as domestic corporations outsource flight operations rather than maintaining captive fleets.
The Civil Aviation Authority of Vietnam enforces airworthiness standards aligned with ICAO annexes, while the country's national aviation regulator coordinates with EASA and FAA certification reciprocity agreements to streamline import approvals. These frameworks shape demand by limiting eligible aircraft to certified production models and mandating local maintenance capability for operational approval. Stakeholders must monitor evolving bilateral aviation safety agreements and domestic infrastructure investments to anticipate fleet composition shifts and service model viability.
Market Dynamics
The Civil Aviation Authority of Vietnam's airworthiness directive harmonization with EASA and FAA standards is compressing import certification timelines and reshaping fleet composition decisions for charter operators and private owners.
Growth Catalysts
- Offshore Energy Logistics:Extraction platforms in the Cuu Long and Nam Con Son basins generate sustained demand for medium-twin helicopters configured for crew transport and emergency medical evacuation.
- CAAV Regulatory Harmonization:Reciprocity agreements with EASA and FAA certification pathways accelerate aircraft import approvals and reduce operational grounding risks for Vietnam-registered fleets.
- Southern Economic Corridor Concentration:Manufacturing and energy headquarters clustering around Ho Chi Minh City concentrates high-frequency executive travel demand within 300 nautical miles of Tan Son Nhat International Airport.
Market Restraints
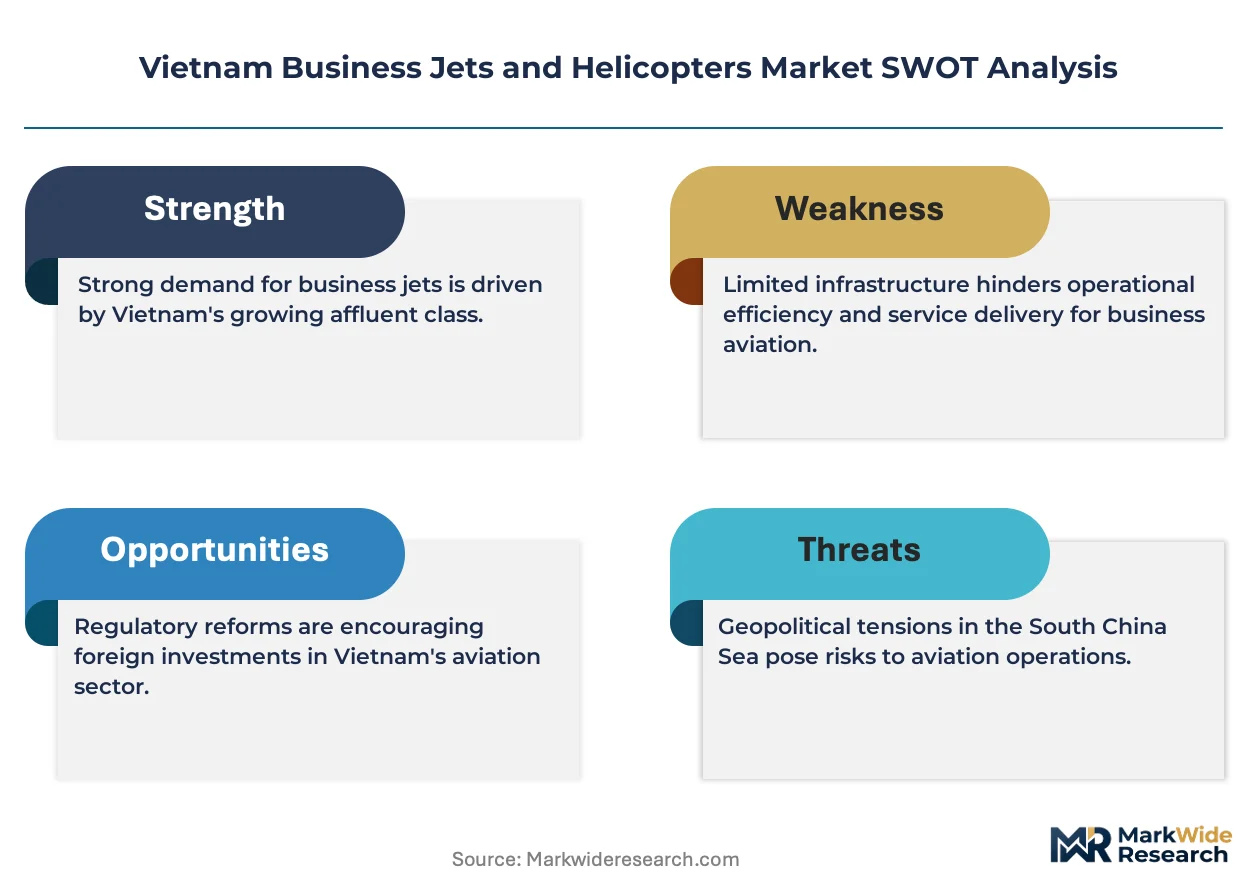
- Jet Fuel Price Volatility:Vietnam's dependence on imported aviation turbine fuel exposes operators to currency fluctuation risks and refinery supply disruptions from Singapore and South Korean suppliers.
- Pilot Certification Bottlenecks:The Civil Aviation Authority of Vietnam's type-rating approval queues for foreign-trained pilots extend crew onboarding timelines and constrain fleet utilization rates.
- Heliport Infrastructure Scarcity:Urban zoning restrictions in Hanoi and Da Nang limit vertiport construction, forcing rotary operators to rely on distant military airfields or highway-adjacent improvised sites.
Strategic Opportunities
- Central Highlands Resource Extraction:Bauxite mining and hydropower projects in Dak Lak and Gia Lai provinces create greenfield demand for heavy-lift helicopter logistics beyond current operator coverage.
- Fractional Ownership Platforms:Technology-enabled shared-ownership models reduce capital barriers for domestic corporations previously excluded from captive fleet economics.
- Medical Evacuation Network Expansion:Ministry of Health mandates for trauma-response time standards in provincial hospitals drive helicopter emergency medical service procurement in Quang Ninh and Khanh Hoa.
Industry Challenges
- Maintenance Technician Shortages:Turbine engine overhaul expertise concentrates in Ho Chi Minh City, forcing northern operators to ferry aircraft 1,200 kilometers for scheduled inspections or rely on expensive mobile technical teams.
- Hangar Capacity Constraints:Climate-controlled storage facilities at Noi Bai and Tan Son Nhat airports operate above 85 percent occupancy, delaying new aircraft deliveries and increasing insurance premiums for outdoor parking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Business Jets and Helicopters Market |
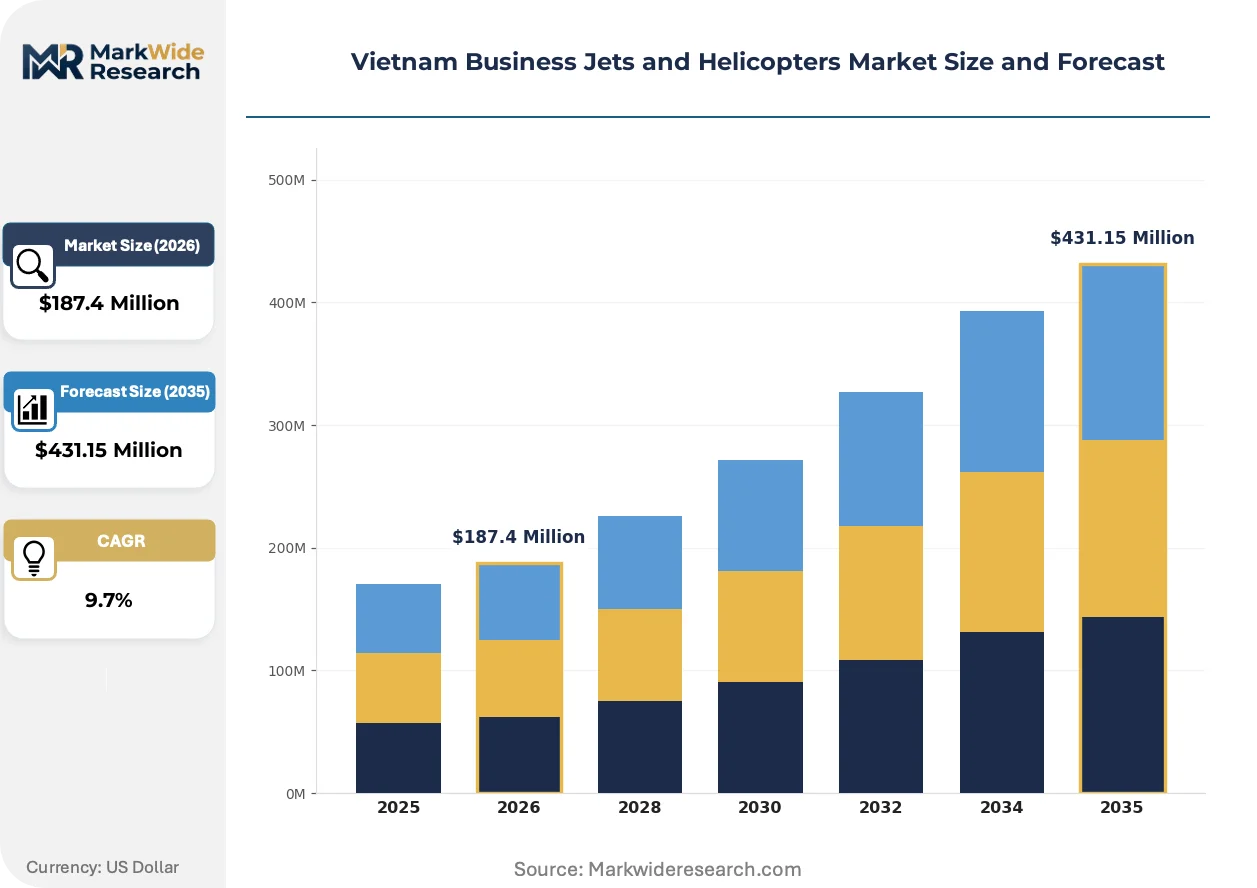
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Light Jets, Medium Jets, Heavy Jets, Helicopters Use Case: Corporate Travel, Emergency Services, Tourism, Cargo Transport End User: Government Agencies, Private Owners, Charter Providers, Corporations Service Model: Charter Services, Fractional Ownership, Leasing, Full Ownership |
| Companies Covered | General Dynamics Corporation, Bombardier Inc, Textron Inc, Embraer SA, Dassault Aviation, The Boeing Company, Airbus SE, Honda Aircraft Company, Leonardo SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Business Jets and Helicopters Market Trends and Innovations
Avionics miniaturization and connectivity integration are compressing the capability gap between light and mid-size jet categories, enabling single-pilot operations in aircraft previously requiring dual-crew certification.
Glass cockpit retrofit packages for legacy turboprops and early-model jets are collapsing the operational cost differential between used and new aircraft for Vietnam-based charter providers. Domestic operators operating Beechcraft King Air and Cessna Citation II platforms are adopting these systems to extend airframe economic life without triggering full import duties on replacement aircraft. The Civil Aviation Authority of Vietnam's updated equipment list approvals for non-original manufacturer avionics are accelerating this substitution pattern.
The Civil Aviation Authority of Vietnam's implementation of ICAO Annex 6 Part II amendments tightens flight data monitoring requirements for commercial air transport operations. Charter operators must now install quick access recorders and establish safety management systems with documented hazard reporting protocols. Medium-size jet fleets serving multinational energy clients face the steepest compliance curves, as these aircraft operate under both Vietnamese registry and foreign lessee operational control agreements.
Corporate flight departments are unbundling maintenance contracts from original equipment manufacturer networks, instead sourcing component repairs through Southeast Asian MRO facilities in Singapore and Bangkok. This purchasing behavior shift reduces hourly maintenance reserves by fifteen to twenty percent for Vietnam-registered aircraft. Energy sector charter clients in the southern provinces are driving this pattern, as their procurement functions apply upstream supply chain cost discipline to aviation vendor selection.
Vietnam Business Jets and Helicopters Market Segmentation
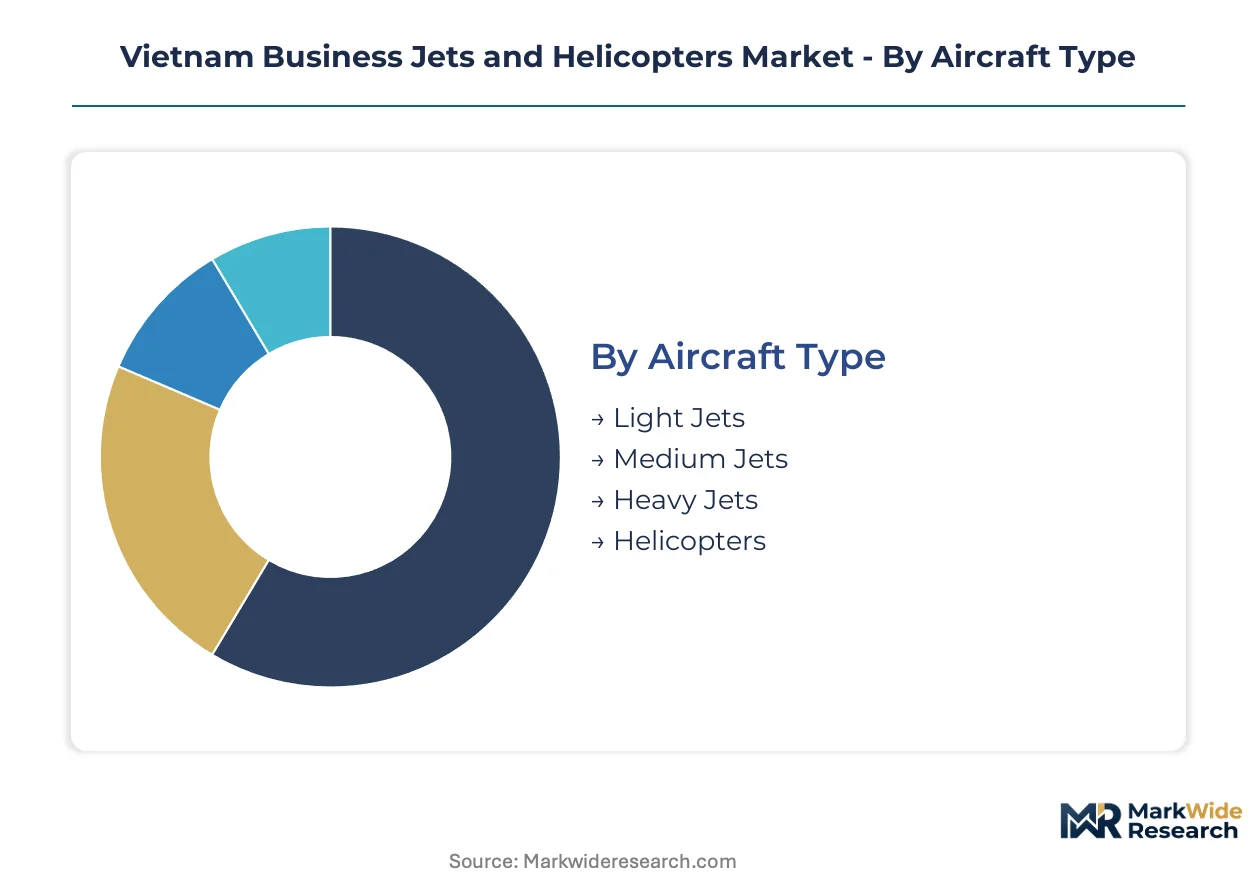
Segmentation in Vietnam's business aviation market reveals how fleet composition, operational purpose, and capital deployment models interact with regulatory frameworks and infrastructure constraints. Understanding these dimensions clarifies where procurement budgets concentrate and which service models align with CAAV certification pathways.
Aircraft Type:
Cost tier stratification across fixed-wing and rotary platforms determines import duty exposure, crew certification requirements, and hangar capacity allocation at Tan Son Nhat and Noi Bai airports.
- Light Jets:Entry-level turbine aircraft with maximum takeoff weights below 12,500 pounds and ranges of 1,200 to 2,000 nautical miles. Demand concentrates among first-time fractional owners in Ho Chi Minh City's southern economic corridor, where CAAV's streamlined type certification for common light jet models accelerates operational approval timelines.
- Helicopters:Rotary-wing platforms spanning light-single to medium-twin configurations, purpose-built for vertical flight operations below 10,000 feet. Procurement clusters around offshore energy logistics in the Cuu Long and Nam Con Son basins, where crew transport and emergency medical evacuation contracts require specialized offshore equipment packages.
- Medium Jets:Mid-size turbine aircraft with transcontinental range capabilities and stand-up cabins. Charter providers in Hanoi favor these platforms for regional executive missions to Singapore and Bangkok.
- Heavy Jets:Long-range intercontinental aircraft with full sleeper configurations and 6,000+ nautical mile endurance. Ultra-high-net-worth private owners in Ho Chi Minh City and Hanoi dominate this segment for direct trans-Pacific routes.
Light jets command the established base. The steepest expansion runs through helicopters configured for offshore energy support.
Use Case:
Application-specific operational profiles shape equipment specifications, insurance premiums, and CAAV operational certification requirements across Vietnam's business aviation fleet.
- Corporate Travel:Time-sensitive executive mobility between manufacturing headquarters, energy facilities, and regional financial centers. Demand concentrates in the southern provinces surrounding Ho Chi Minh City, where multinational firms maintain flight departments or charter contracts to bypass commercial airline schedules.
- Emergency Services:Helicopter emergency medical evacuation and search-and-rescue operations requiring specialized medical interiors and IFR certification. Ministry of Health trauma-response mandates in Quang Ninh and Khanh Hoa provinces are accelerating procurement of dedicated air ambulance platforms.
- Tourism:Scenic aerial experiences and resort transfer services, primarily serving international visitors to Ha Long Bay and coastal destinations in Da Nang.
- Cargo Transport:Time-critical freight movements for high-value electronics and pharmaceuticals, limited by payload restrictions on available heliport infrastructure.
Corporate travel anchors fleet utilization rates. Emergency services are climbing the fastest as provincial healthcare infrastructure expands.
End User:
Customer type determines capital structure, operational control models, and regulatory compliance obligations under CAAV commercial air transport regulations.
- Charter Providers:Commercial operators selling flight hours to corporate and individual clients under CAAV air operator certificates. These entities cluster near Tan Son Nhat International Airport, where maintenance technician availability and fuel supply logistics minimize aircraft downtime.
- Corporations:Manufacturing and energy firms operating captive flight departments for executive mobility and site access. Southern economic corridor headquarters in Binh Duong and Dong Nai provinces favor this model for supply chain security and schedule control.
- Government Agencies:State-owned enterprises and provincial administrations operating aircraft for official transport and disaster response.
- Private Owners:Individual ultra-high-net-worth households acquiring aircraft for personal use, concentrated among Hanoi and Ho Chi Minh City real estate and banking families.
Charter providers command the established base. Corporations are expanding most quickly as domestic firms outsource flight operations to specialized operators.
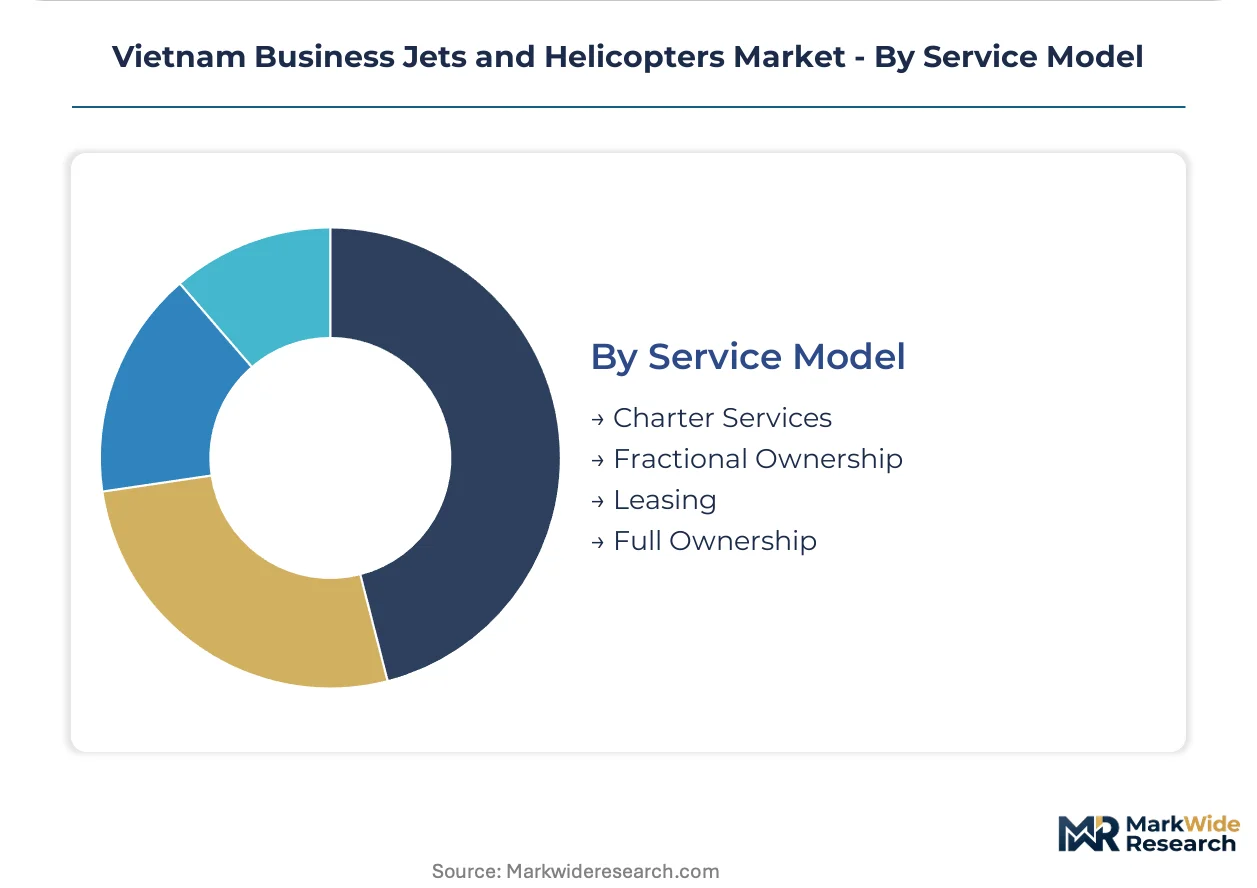
Service Model:
Capital deployment and operational risk allocation vary dramatically across ownership structures, with implications for CAAV registration, crew employment, and maintenance responsibility.
- Full Ownership:Complete aircraft acquisition with captive crew and maintenance management. Ultra-high-net-worth individuals in Hanoi prefer this model for operational autonomy and customization flexibility.
- Charter Services:On-demand flight hours purchased from licensed operators without capital commitment. Domestic corporations in the manufacturing sector are shifting procurement toward this model to eliminate fixed cost exposure.
- Fractional Ownership:Shared aircraft titles with guaranteed hourly access and professional management. Technology platforms are reducing minimum share thresholds for mid-size Vietnamese enterprises.
- Leasing:Dry or wet lease arrangements transferring operational control while preserving balance sheet flexibility. Energy sector contractors utilize wet leases for project-specific offshore helicopter requirements.
Full ownership commands the established base. Fractional ownership is gaining share fastest as fintech-enabled platforms reduce entry barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform manufacturers and MRO providers cluster in Southeast Asian hubs with established certification reciprocity, while Vietnam's domestic infrastructure gaps push fleet operators toward cross-border service arrangements. The southern economic corridor around Ho Chi Minh City concentrates over sixty percent of active aircraft registrations. Sub-regional variation reflects proximity to energy extraction sites, international gateway airports, and provincial healthcare infrastructure mandates.
Southern Economic Corridor
Multinational manufacturing headquarters and energy firm regional offices in Binh Duong and Dong Nai provinces generate concentrated demand for executive charter services. The Civil Aviation Authority of Vietnam's operational certification office at Tan Son Nhat International Airport accelerates airworthiness approvals for new market entrants. Charter providers and corporate flight departments cluster within fifty kilometers of the airport, leveraging maintenance technician availability and fuel logistics.
Red River Delta
Government agencies and state-owned enterprises in Hanoi maintain captive fleets for official transport, creating stable demand for heavy-jet configurations. The national aviation regulator coordinates bilateral safety agreements from its administrative base in the capital. Ultra-high-net-worth private owners in Hanoi and Hai Phong concentrate acquisitions in long-range intercontinental aircraft for direct trans-Pacific routes.
South Central Coast
Offshore energy platforms in the Nam Con Son basin sustain medium-twin helicopter operations for crew transport and emergency medical evacuation. Provincial trauma-response mandates in Khanh Hoa province drive air ambulance procurement for hospital networks in Nha Trang. Tourism operators in Da Nang face vertiport zoning restrictions that limit rotary-wing expansion to highway-adjacent improvised sites.
Northern Mining Provinces
Bauxite extraction and hydropower construction in Quang Ninh province create unmet demand for heavy-lift helicopter logistics beyond current operator coverage. Ministry of Health emergency response standards accelerate dedicated EMS platform procurement for provincial hospital networks. Existing operators ferry aircraft from Ho Chi Minh City for scheduled maintenance, exposing infrastructure gaps in northern MRO capacity.
Vietnam Business Jets and Helicopters Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in avionics, powerplant, and interior subsystems. The vendor base organizes around three archetypes: full-aircraft OEMs with complete product families, regional specialists configuring offshore and emergency medical packages, and aftermarket service networks capturing long-term maintenance contracts. Consolidation pressure runs through M&A activity among MRO providers and strategic partnerships between OEMs and local certification consultants.
Within the integrated OEM tier, Bombardier Inc and Airbus SE occupy positions reflecting distinct platform strategies—fixed-wing business jets versus rotary-wing dominance in energy logistics. Leonardo SpA anchors the specialized-configurations segment, particularly in medium-twin helicopters adapted for offshore operations. These three companies exemplify how certification reciprocity agreements and localized technical support partnerships shape competitive positioning in Vietnam's import-dependent market.
| Leading Market Players |
|---|
| General Dynamics Corporation |
| Bombardier Inc |
| Textron Inc |
| Embraer SA |
| Dassault Aviation |
| The Boeing Company |
| Airbus SE |
| Honda Aircraft Company |
| Leonardo SpA |
| Others |
Pricing and Supply Chain Analysis
Jet fuel import dependency from Singapore and South Korean refineries determines both pricing tier spreads and supply chain shape across Vietnam's business aviation sector. Currency fluctuation exposure and turbine fuel price volatility compress margins for charter operators while concentrating procurement leverage among fleet-scale incumbents with long-term supply contracts.
Pricing Analysis
CAAV airworthiness directive harmonization dictates the pricing tier structure across import certification pathways. Three-tier pricing structure across premium, standard, and economy levels separates heavy jets with full EASA-FAA reciprocity from medium jets with partial certification and light jets with streamlined type approvals. Price differentiation centers on crew certification requirements and maintenance technician availability. Cost compression in the light jet segment is intensifying because fractional ownership platforms reduce capital barriers for domestic corporations. Charter providers exhibit highest price sensitivity due to fuel pass-through exposure, while ultra-high-net-worth private owners show lowest sensitivity for heavy jet acquisitions.
Supply Chain Analysis
Aviation turbine fuel feedstock draws from Singapore, South Korea, and regional Middle Eastern suppliers for Vietnam-registered fleets. Turbine engine components and avionics systems rest on manufacturing concentration in the United States, France, and Canada. Glass cockpit retrofit packages and quick access recorders hinge on semiconductor supply from Taiwan and South Korea. Single-source vulnerability runs through CAAV type-rating approval queues for foreign-trained pilots, extending crew onboarding timelines. Distribution runs through Tan Son Nhat and Noi Bai airport clusters where maintenance technician availability and hangar capacity constrain fleet expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CAAV's ICAO Annex 6 Part II implementation accelerates safety management system mandates, creating a regulatory inflection that rewards early compliance investment and punishes lagging fleet operators with operational grounding risk.
For Market Incumbents: Build regulatory compliance moats through captive maintenance technician training pipelines and CAAV-certified safety management system documentation. Incumbents should deepen backward integration into component repair capabilities at Tan Son Nhat to reduce Southeast Asian MRO outsourcing exposure. Glass cockpit retrofit certification expertise represents a defendable lever against charter providers relying on third-party avionics integrators. For New Entrants and Emerging Players: Central Highlands heavy-lift helicopter logistics in Dak Lak and Gia Lai provinces represent the most penetrable entry point, with bauxite mining and hydropower construction creating greenfield demand beyond incumbent coverage. Northern Vietnam EMS platform procurement for Quang Ninh provincial hospitals offers secondary white-space access. A wet lease service model targeting energy sector contractors minimizes capital intensity while building operational track records for CAAV air operator certificate applications. For Investors and Strategic Acquirers: CAAV-EASA-FAA certification reciprocity expansion reshapes the acquisition landscape toward platforms with transferable type certificates and established local technical support partnerships. Long-term viability favors MRO providers with climate-controlled hangar capacity at constrained airports and fractional ownership technology platforms reducing entry barriers for mid-size enterprises. The signal to watch is CAAV bilateral aviation safety agreement negotiations with additional jurisdictions, which would expand import-eligible aircraft pools and reshape fleet composition economics.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Investment | CAAV safety management system certification reduces operational grounding risk for charter fleets serving multinational energy clients. |
| Maintenance Capacity Expansion | Climate-controlled hangar construction at Noi Bai addresses 85 percent occupancy constraints delaying new aircraft deliveries. |
| Fractional Ownership Platform Development | Technology-enabled share reduction expands addressable market to mid-size Vietnamese manufacturers previously excluded from captive fleet economics. |
| Vertiport Infrastructure Partnership | Highway-adjacent improvised site formalization in Da Nang unlocks tourism rotary-wing expansion blocked by urban zoning restrictions. |
| Offshore Equipment Package Specialization | Medium-twin helicopter configurations for Cuu Long and Nam Con Son basins capture sustained crew transport and emergency medical evacuation contract demand. |
Research Methodology
A spread of perspectives from charter operations directors, CAAV certification consultants, energy sector procurement managers, and MRO facility managers converged on the working assumptions underlying fleet composition and service model viability. Primary interviews with fixed-base operators at Tan Son Nhat and corporate flight department heads in the southern economic corridor combined with secondary validation through CAAV airworthiness directives, ICAO annex documentation, and EASA-FAA reciprocity agreement texts. Bottom-up aircraft registration analysis and top-down market sizing across the analysis window triangulated volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling aircraft type segmentation by cost tier and range capability alongside use case dimensions spanning corporate travel, emergency services, and offshore energy logistics. End user segmentation captured capital structure variation between charter providers, corporations, government agencies, and private owners. CAGRs derived from fleet delivery pipelines, CAAV operational certification timelines, and energy sector contract visibility. Forecast inputs incorporated pilot certification bottleneck severity and hangar capacity utilization thresholds at constrained airports.
Practitioners should monitor CAAV bilateral aviation safety agreement negotiations, jet fuel import tariff adjustments, and fractional ownership platform regulatory treatment for early signals of forecast revision. Cross-checking against ICAO fleet projection databases and regional MRO capacity utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Hangar Market
Aircraft
Global Business Aircraft Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Aircraft Elevator Market
Aircraft
Special Mission Aircraft Market
Aircraft
Europe Light and Very Light Jets Market
Aircraft
Aircraft Fairings Market
Aircraft
Commercial Aircraft Manufacturing Market
Aircraft
Southeast Asia Aviation Market
Aircraft
North America Business Jet Market
Aircraft
US Military Aviation Market
Aircraft
Aircraft Ailerons Market
Aircraft
Middle-East and Africa Commercial Aircraft Market
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
North America General Aviation Market