
 Air Speed Indicator Market | 2026-2036
Air Speed Indicator Market Size, Share, and Industry Trends Forecast 2026-2036
Air Speed Indicator Market Insights
Commercial aviation is pivoting toward glass cockpit retrofits, pulling demand toward electronic and digital air speed indicators. Honeywell International Inc. leverages its integrated avionics platform to dominate the retrofit channel for narrow-body fleets. Garmin Ltd. competes aggressively in the general aviation and flight training segments with cost-competitive digital displays. Collins Aerospace Inc. anchors the OEM supply chain for next-generation commercial platforms through long-term airframer contracts.
An air speed indicator measures differential pressure between pitot and static ports to compute indicated airspeed, typically displaying readings in knots with operational ranges from 40 to 600+ KIAS depending on aircraft class. The instrument serves as primary flight data for pilots during takeoff, climb, cruise, and approach phases across all powered aircraft categories. Digital product types lead installed value due to integration with modern flight management systems, while MEMS technology segments show the fastest trajectory as chip-scale sensors displace legacy mechanical bellows. Electro-mechanical indicators retain share in military trainer fleets where electromagnetic hardening requirements exceed commercial specifications.
FAA Part 23 and Part 25 certification standards govern airworthiness requirements for civil aircraft in the United States, while EASA CS-23 and CS-25 frameworks apply across European Union member states. Military procurement channels follow MIL-STD-810 environmental testing and MIL-PRF-28800 electronic reliability specifications through defense organizations. Stakeholders must monitor evolving UAV-type certification pathways as regulators develop dedicated standards for uncrewed platforms exceeding current weight and altitude thresholds.
Market Dynamics
Fleet modernization mandates from FAA and EASA are forcing operators to replace pneumatic air speed indicators with digital architectures, compressing upgrade cycles across narrow-body and regional aircraft segments.
Growth Catalysts
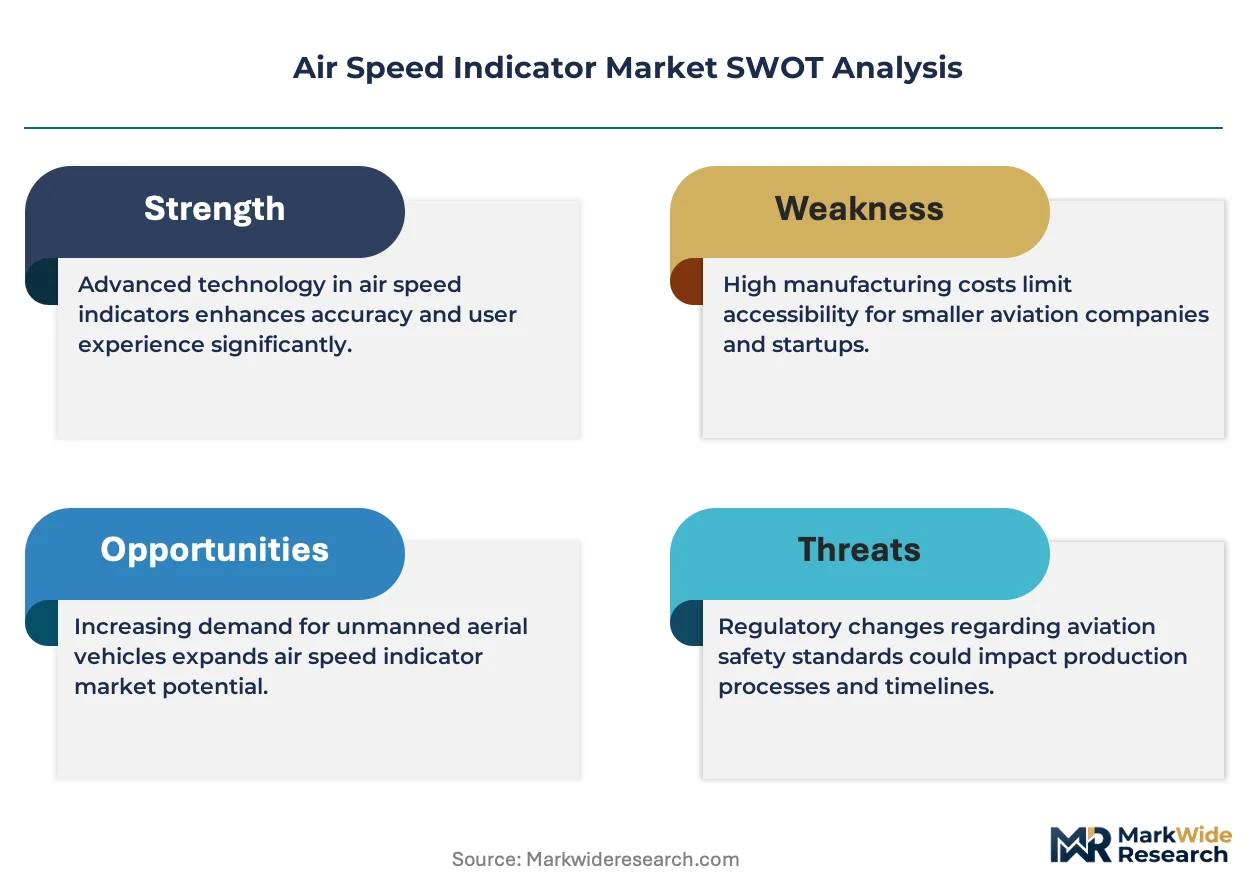
- FAA Part 25 Amendment 25-140:The revised airworthiness standard mandates enhanced pitot-static system redundancy for transport-category aircraft, compelling retrofit investments across aging commercial fleets.
- MEMS sensor miniaturization:Chip-scale differential pressure transducers are reducing instrument weight and power draw, enabling integration into electric vertical takeoff platforms and uncrewed systems.
- General aviation training expansion:Flight schools in the United States and Australia are upgrading instrument panels to meet insurance underwriter requirements for glass cockpit proficiency certification.
Market Restraints
- Precision machining capacity constraints:Domestic suppliers of Inconel pitot tubes face order backlogs exceeding 18 months, constraining OEM delivery schedules for new aircraft programs.
- Dual-use export control friction:ITAR classification of military-grade air data computers restricts technology transfer to maintenance facilities in non-allied jurisdictions, fragmenting aftermarket service networks.
- Calibration infrastructure scarcity:Certified wind tunnel facilities capable of validating supersonic airspeed ranges concentrate in three national laboratories, creating certification bottlenecks for next-generation designs.
Strategic Opportunities
- UAV-type certification pathways:Emerging regulatory frameworks for uncrewed aircraft exceeding 55 pounds are creating dedicated product categories for integrated air data systems without piloted-aircraft legacy constraints.
- India defense modernization:The country's indigenization push under Make in India procurement rules is opening offset partnerships for foreign sensor manufacturers establishing local production.
- Blockchain-enabled provenance tracking:Immutable component history records are reducing fraud in refurbished instrument markets, unlocking premium pricing for certified pre-owned digital indicators.
Industry Challenges
- Avionics software vulnerability assessment:DO-178C compliance for air data computer firmware requires specialized engineering talent pools concentrated at defense contractors, creating hiring competition.
- Legacy pneumatic system interoperability:Mixed-fleet operators face integration complexity when retrofitting electronic indicators onto aircraft retaining mechanical standby instruments, demanding custom adapter harnesses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Speed Indicator Market |
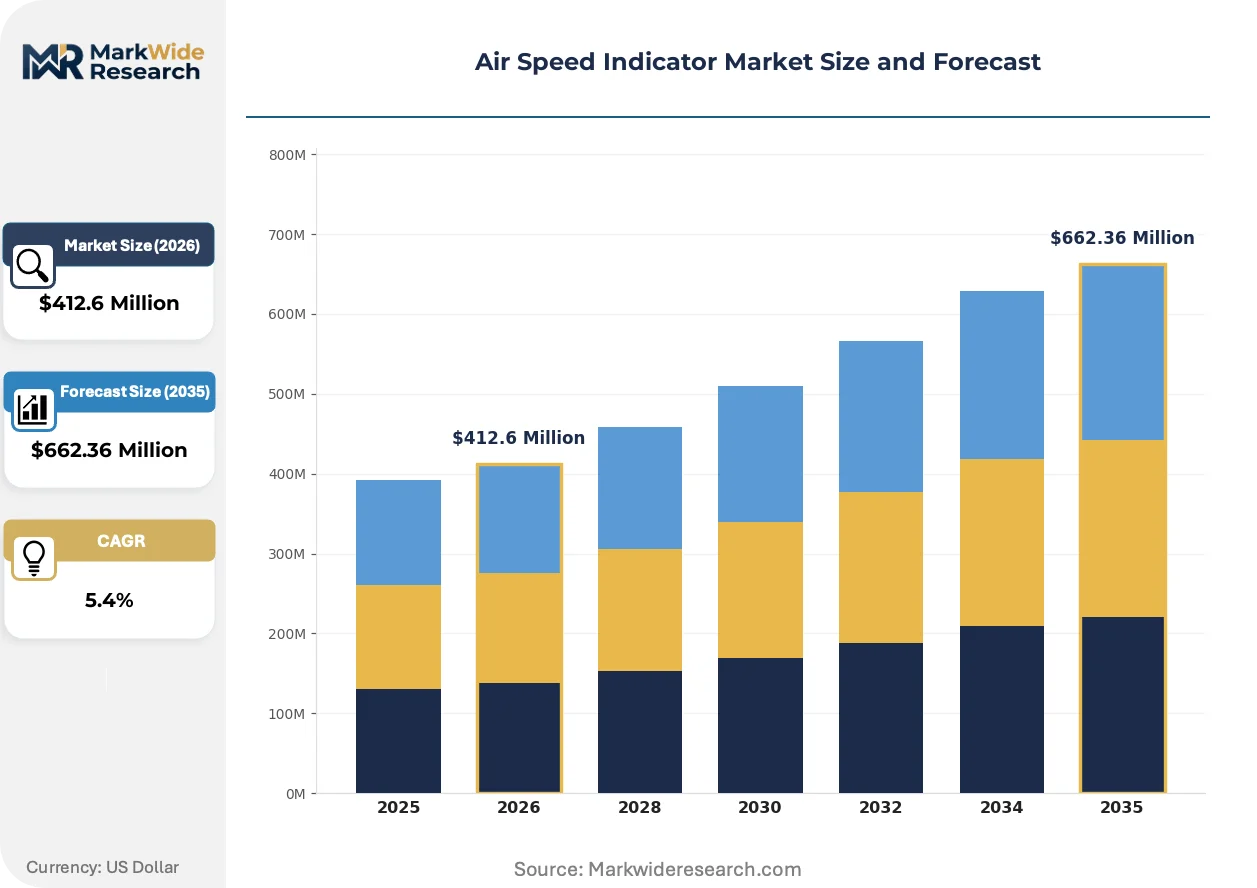
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $662.36 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Electro-Mechanical, Electronic, Pneumatic Technology: Gyroscopic, Pitot-Static, Ultrasonic, Laser-based, MEMS Application: Commercial Aviation, Military Aircraft, UAVs, Aerospace Research, Flight Training End User: Aircraft Manufacturers, Maintenance Service Providers, Flight Schools, Defense Organizations |
| Companies Covered | Honeywell International Inc., Garmin Ltd., Collins Aerospace Inc., Thales S.A., Mid-Continent Instruments & Avionics, Aspen Avionics, Inc., Aerosonic Corporation, L3Harris Technologies, Inc., Mikrotechna Praha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Speed Indicator Market Trends and Innovations
Sensor fusion architectures are collapsing discrete flight instruments into unified air data modules, eliminating standalone indicator configurations while demanding new calibration protocols and maintenance competencies across the installed base.
Solid-state differential pressure transducers employing MEMS resonant structures are consolidating pneumatic sensing functions previously distributed across multiple mechanical bellows assemblies. Regional airlines operating Bombardier and Embraer fleets are adopting these units at the fastest pace, driven by reduced unscheduled removal rates. The technology is consolidating supplier tiers as chip-scale manufacturing favors semiconductor foundries over precision mechanical shops.
EASA's proposed CS-25 amendment on synthetic air data validation is mandating redundant computational paths for primary flight displays, affecting certification timelines for integrated cockpit systems. The regulation compresses development cycles for manufacturers pursuing simultaneous FAA and EASA validation. Wide-body programs with 2027 service entry targets are most affected, accelerating hiring of certification specialists at European design organizations.
Power-by-the-hour maintenance contracts are displacing transactional parts sales in the commercial aftermarket, bundling air speed indicator replacement into fleet-wide avionics support agreements. Lessors and asset managers are driving this transition, seeking predictable cash flows over component-level revenue optimization. The shift is most visible in Ireland and Singapore, where major leasing platforms concentrate technical asset management functions.
Air Speed Indicator Market Segmentation
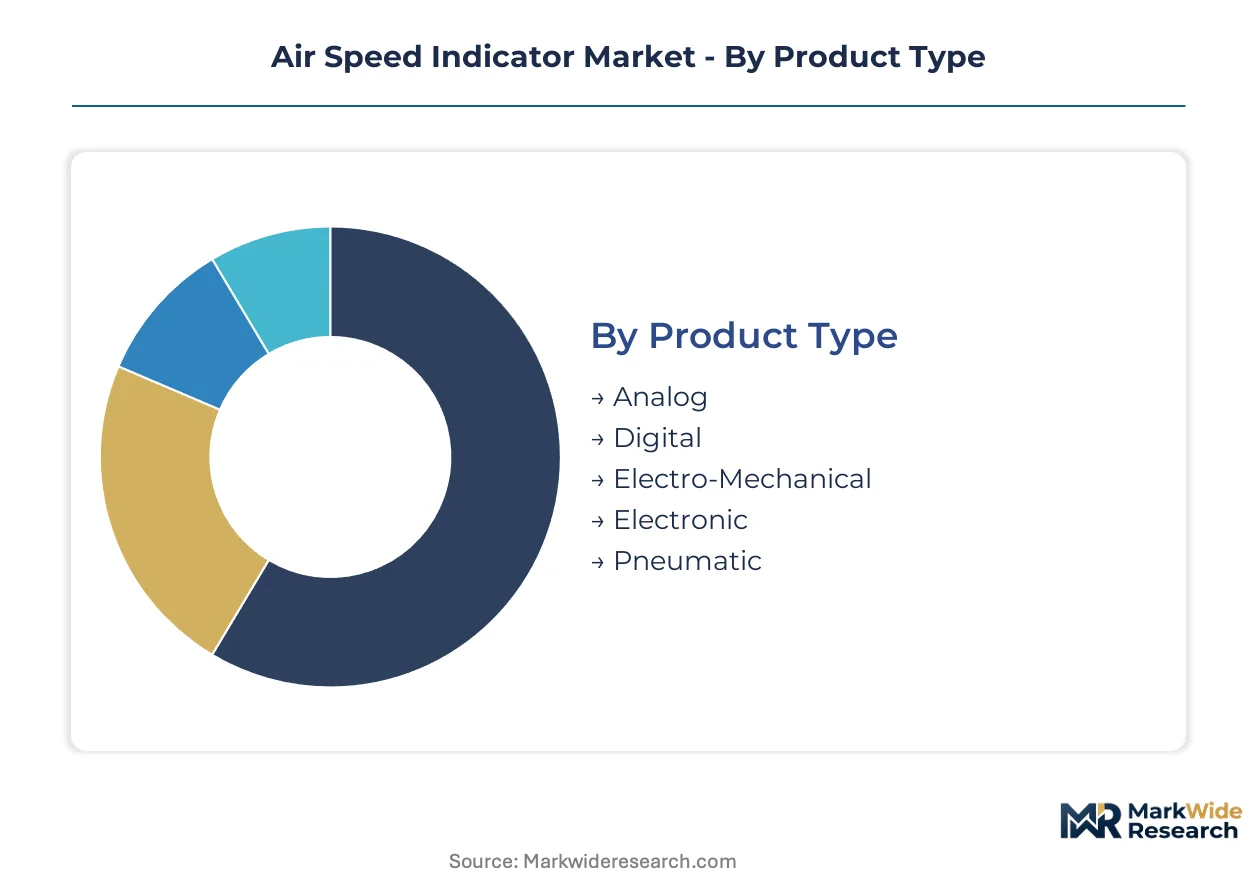
Air speed indicator procurement patterns diverge sharply across product architectures and operational domains. Fleet operators prioritize integration compatibility with existing avionics suites, while defense buyers emphasize electromagnetic hardening and environmental resilience specifications.
Product Type:
Technology sophistication determines installed value and replacement cycles across cockpit instrumentation tiers.
- Digital:Solid-state architectures integrate directly with flight management systems through ARINC 429 data buses. Commercial carriers in the United States and European Union mandate these for new narrow-body deliveries under FAA Part 25 and EASA CS-25 avionics upgrade timelines.
- Electronic:Hybrid designs retain analog display elements while incorporating digital sensing cores, serving regional airlines seeking phased modernization without full glass cockpit retrofits.
- Analog:Mechanical pointer instruments with pitot-static pressure diaphragms persist in legacy general aviation fleets where cost constraints limit upgrade investments.
- Electro-Mechanical:Servo-driven indicators combine electromechanical reliability with electronic signal conditioning, dominating military trainer applications where electromagnetic pulse tolerance exceeds commercial requirements.
- Pneumatic:Pure mechanical bellows systems face accelerated obsolescence as FAA maintenance directives tighten calibration intervals for aging transport-category aircraft.
Digital leads on scale; Electronic leads on momentum.
Technology:
Sensor physics governs accuracy, environmental tolerance, and integration complexity for air data acquisition.
- MEMS:Silicon resonant structures fabricated at semiconductor foundries enable chip-scale differential pressure measurement with sub-milliwatt power budgets. Electric vertical takeoff platforms in California and uncrewed systems manufacturers in Israel specify these for weight-critical applications.
- Pitot-Static:Differential pressure measurement between forward-facing pitot tubes and static ports remains the reference standard for certificated transport aircraft under FAA and EASA airworthiness protocols.
- Gyroscopic:Spinning mass sensors provide attitude-referenced air data in high-dynamics military platforms where GPS denial scenarios demand inertial augmentation.
- Ultrasonic:Time-of-flight measurement eliminates pneumatic plumbing, attracting urban air mobility developers in Germany and China seeking simplified airframe integration.
- Laser-based:Doppler LIDAR techniques enable non-intrusive airspeed measurement for aerospace research applications including supersonic boundary layer studies at national laboratories.
Pitot-Static retains installed base dominance; MEMS climbs the fastest.
Application:
Operational environment shapes certification pathways and performance specifications across user categories.
- Commercial Aviation:Scheduled carriers operating under FAA Part 121 and EASA Part-CAT rules drive volume demand for redundant digital architectures with automatic cross-check logic.
- Military Aircraft:Defense procurement through MIL-STD-810 environmental qualification mandates hardened packaging for tactical platforms operating in contested electromagnetic environments.
- UAVs:Uncrewed platforms exceeding 55 pounds face emerging type certification frameworks in the United States and European Union, creating dedicated product categories without piloted-aircraft legacy constraints.
- Flight Training:Flight schools in Florida, Arizona, and Victoria upgrade instrument panels to meet insurance underwriter glass cockpit proficiency requirements.
- Aerospace Research:Experimental flight test programs at NASA Armstrong, DLR Braunschweig, and JAXA Chofu specify custom-calibrated instruments for transonic and hypersonic regimes.
Commercial Aviation leads on scale; UAVs lead on momentum.
End User:
Procurement authority and technical integration capabilities vary sharply across buyer categories.
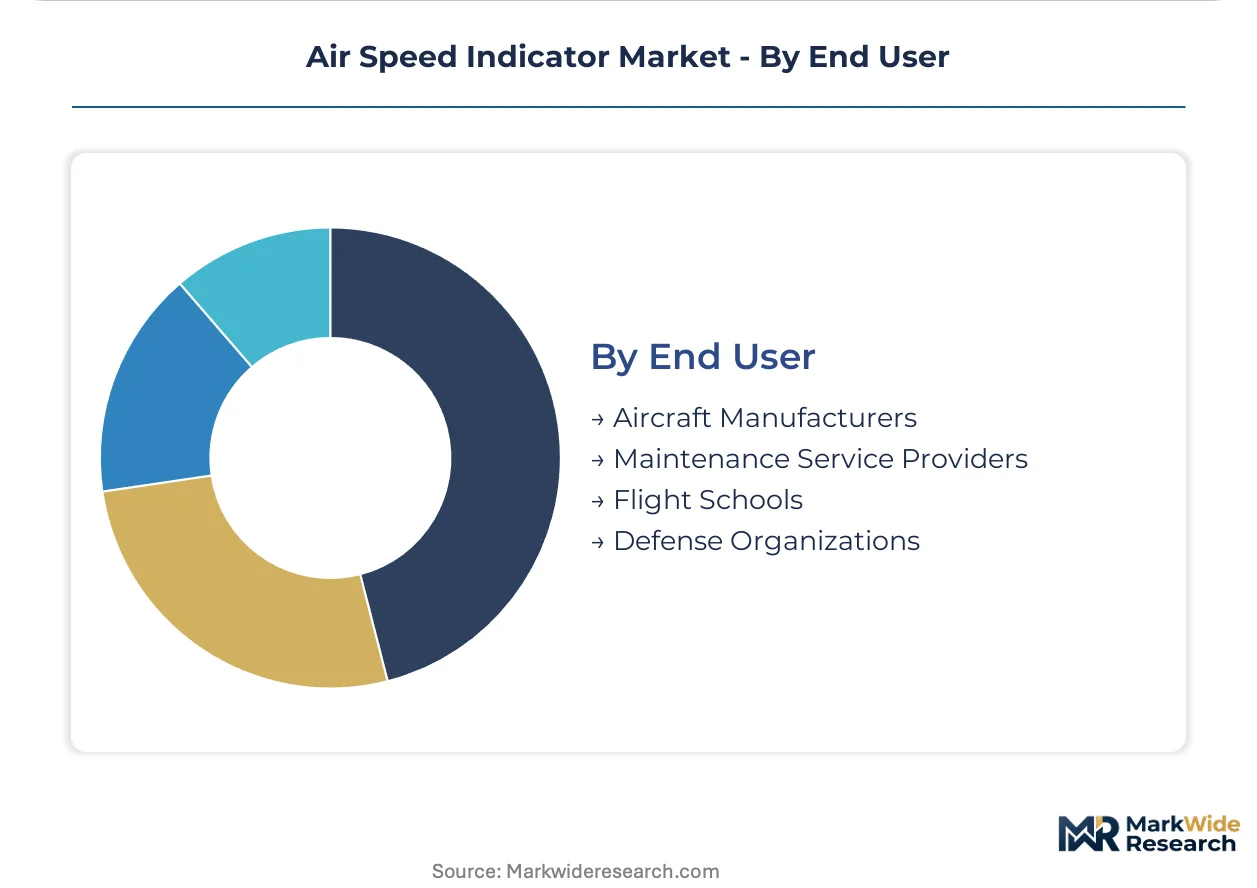
- Aircraft Manufacturers:Boeing, Airbus, Embraer, and COMAC specify integrated air data modules through long-term supply agreements with tier-one avionics suppliers.
- Maintenance Service Providers:Repair stations in Oklahoma, Singapore, and the Netherlands manage retrofit campaigns for aging fleets, sourcing both OEM and PMA-certified replacement instruments.
- Flight Schools:Independent training operators and university aviation programs in Texas, Ohio, and Queensland prioritize cost-competitive digital displays from secondary suppliers.
- Defense Organizations:Pentagon acquisition channels, UK Defence Equipment and Support, and India's Defence Research and Development Organisation mandate MIL-PRF-28800 reliability specifications with domestic content requirements.
Aircraft Manufacturers lead on scale; Maintenance Service Providers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita, Kansas anchors the global air speed indicator supply chain through its dense concentration of avionics manufacturing and MRO infrastructure serving commercial and general aviation fleets.
United States
FAA Part 25 Amendment 25-140 mandates enhanced pitot-static redundancy for transport-category aircraft, compelling fleet-wide retrofits. The FAA's updated airworthiness directives tighten calibration intervals for aging pneumatic systems. Wichita's integrated avionics cluster and Seattle's Boeing supply chain dominate OEM and aftermarket channels respectively.
France
EASA CS-25 synthetic air data validation proposals are compressing certification timelines for integrated cockpit systems. The country's national aviation regulator maintains stringent design organization approval standards for flight-critical instruments. Toulouse's Airbus engineering ecosystem and Paris-region certification specialists concentrate next-generation platform development.
Germany
Urban air mobility developers in Bavaria specify ultrasonic time-of-flight sensors for simplified airframe integration on electric vertical takeoff platforms. EASA's emerging UAV-type certification frameworks apply directly to uncrewed platforms exceeding 55 pounds. Munich's aerospace research corridor hosts DLR facilities validating transonic instrument calibration protocols.
India
Make in India procurement rules mandate domestic content thresholds for defense air data systems, opening offset partnerships for foreign sensor manufacturers. The country's national defense research organization specifies MIL-PRF-28800 reliability standards with local production requirements. Bangalore's aerospace cluster and Hyderabad's defense electronics corridor attract joint venture investments for indigenous manufacturing.
United Kingdom
UK Defence Equipment and Support procurement channels prioritize electromagnetic hardening specifications for tactical platforms operating in contested environments. The national military standards framework governs environmental qualification through defense acquisition pathways. Bristol's avionics engineering base and southeast England's certification consultancies support dual-use technology development.
Air Speed Indicator Market Competitive Landscape
Strategic partnerships dominate the current landscape as tier-one avionics suppliers secure long-term airframer contracts and retrofit channel alliances. The vendor base concentrates around integrated platform providers with full cockpit system capabilities, supplemented by specialized instrument manufacturers serving general aviation and training segments. Three archetypes prevail: diversified aerospace conglomerates with avionics divisions, dedicated flight display specialists, and precision sensor component suppliers. M&A activity and technology licensing agreements represent the primary competitive vectors as firms seek MEMS manufacturing capabilities and software certification competencies.
Among diversified aerospace conglomerates, Honeywell International Inc. and Collins Aerospace Inc. exemplify the integrated platform archetype through their positions within full avionics suites. Garmin Ltd. occupies a distinct position as a flight display specialist serving cost-sensitive general aviation and training markets. These three entities anchor the competitive structure by representing divergent strategic postures: conglomerate breadth versus specialist focus versus hybrid electronic-mechanical heritage.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Garmin Ltd. |
| Collins Aerospace Inc. |
| Thales S.A. |
| Mid-Continent Instruments & Avionics |
| Aspen Avionics, Inc. |
| Aerosonic Corporation |
| L3Harris Technologies, Inc. |
| Mikrotechna Praha |
| Others |
Pricing and Supply Chain Analysis
MEMS sensor miniaturization simultaneously collapses manufacturing cost curves and concentrates production among semiconductor foundries, shifting value capture from mechanical precision shops to chip-scale fabricators while compressing price premiums for legacy pneumatic instruments.
Pricing Analysis
Input-cost pass-through from Inconel pitot tube shortages and precision machining backlogs is intensifying cost compression in the pneumatic tier, while digital architectures command premium-mid-economy pricing differentiation based on ARINC 429 integration depth and DO-178C certification grade. Flight schools and regional carriers exhibit highest price sensitivity due to insurance-mandated upgrade cycles with constrained capital budgets, whereas major lessors accepting power-by-the-hour contracts show lowest sensitivity as they optimize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Freight cost volatility from semiconductor foundries in Taiwan and South Korea to avionics integration facilities in the United States and France is elevating landed cost uncertainty for MEMS-based instruments. The supply chain draws from Inconel superalloy suppliers in the United States, precision machining capacity in Germany and Japan, and semiconductor fabrication concentrated in East Asia, creating tariff exposure from dual-use export controls fragmenting aftermarket service networks. Distribution runs through OEM airframer contracts, authorized repair stations, and PMA-certified aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA Part 25 Amendment 25-140 functions as a regulatory compounder, forcing fleet-wide retrofit investments that expand addressable demand across aging narrow-body and regional aircraft segments regardless of underlying traffic growth.
For Market Incumbents: Hedge against MEMS commoditization by deepening software certification competencies around DO-178C compliance and synthetic air data validation, while locking long-term airframer contracts before EASA CS-25 amendments compress development timelines for wide-body programs. For New Entrants and Emerging Players: EASA's emerging UAV-type certification frameworks in Germany and France open a window for purpose-built integrated air data systems without piloted-aircraft legacy constraints, targeting urban air mobility developers in Bavaria and uncrewed platform manufacturers in Israel with weight-optimized MEMS architectures. For Investors and Strategic Acquirers: Valuations sit cheapest among precision sensor component suppliers lacking integrated cockpit platform capabilities, with long-term viability hinging on MEMS manufacturing scale and software certification talent pools; monitor EASA synthetic air data validation rulemaking as the inflection signal for consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Manufacturing Scale-Up | Semiconductor foundry partnerships in Taiwan and South Korea secure chip-scale sensor supply for electric vertical takeoff platforms. |
| DO-178C Certification Investment | Software engineering talent acquisition at defense contractors addresses firmware compliance bottlenecks for integrated air data modules. |
| Power-by-the-Hour Contract Expansion | Lessors in Ireland and Singapore bundle indicator replacement into fleet-wide avionics support agreements. |
| UAV-Type Certification Pathway Development | Dedicated product categories for uncrewed platforms exceeding 55 pounds bypass piloted-aircraft legacy constraints. |
| Offset Partnership Formation | Joint ventures in Bangalore and Hyderabad satisfy Make in India domestic content thresholds for defense procurement. |
Research Methodology
Multiple input streams — primary interviews with avionics engineering directors, fleet procurement managers at regional carriers, and certification specialists at design organizations; secondary validation through FAA airworthiness directives, EASA regulatory filings, and MIL-STD-810 environmental test standards; plus customs data on Inconel pitot tube trade flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product architecture segments, operational application categories, and geographic regulatory clusters anchored volume and value modeling throughout the forecast period. CAGRs were derived from installed base replacement cycles, fleet modernization mandates, and technology substitution curves for MEMS displacing mechanical bellows.
Revisions become necessary when EASA synthetic air data validation amendments accelerate, FAA maintenance directives expand beyond transport-category aircraft, or semiconductor foundry capacity constraints extend delivery timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Sailplane Market
Aircraft
Commercial Aerospace Market
Aircraft
Asia-Pacific Fighter Aircraft Market
Aircraft
Aircraft Galley Systems Market
Aircraft
Asia-Pacific Freighter Aircraft Market
Aircraft
Active Air Deflector Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
Aircraft Pushback Tugs Market
Aircraft
Global Business Aircraft Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Zero-Emission Aircraft Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Regional Jet Market
Aircraft
Aircraft Fairings Market
Aircraft
General Aviation Market
Aircraft
Evtol Aircraft Market