
 Domestic Aviation Market | 2026-2036
Domestic Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Domestic Aviation Market Intelligence
The expansion of Premium Economy service tiers is bifurcating the traditional cabin layout and airline revenue models. In the United States, Southwest Airlines leverages a high-frequency, single-aisle fleet model to dominate key domestic routes. InterGlobe Aviation (IndiGo) sustains its market leadership position in India through aggressive network expansion and strict cost control. In China, major carriers like China Southern Airlines and Air China compete on both massive scale and improving service within a highly regulated national system.
Domestic aviation encompasses all commercial air transport operations where departure and arrival occur within a single country's borders. It predominantly relies on single-aisle jets optimized for high-cycle operations on routes typically under three hours, serving as critical national transport infrastructure. The Leisure Travelers segment drives passenger volume, while the Corporate Travelers segment consistently provides higher per-seat revenue. Short Haul flight distance remains the dominant category, prioritizing network frequency and efficient aircraft turnaround times.
National bodies like the FAA in the United States, EASA across Europe, and India's DGCA set stringent safety, maintenance, and operational standards. Concurrently, environmental regulations including the EU's Emissions Trading System and China's national dual carbon goals are directly influencing fleet renewal decisions and alternative fuel choices. Airlines must now strategically balance post-pandemic network recovery against the capital-intensive demands of decarbonization and long-term fleet modernization.
Market Dynamics
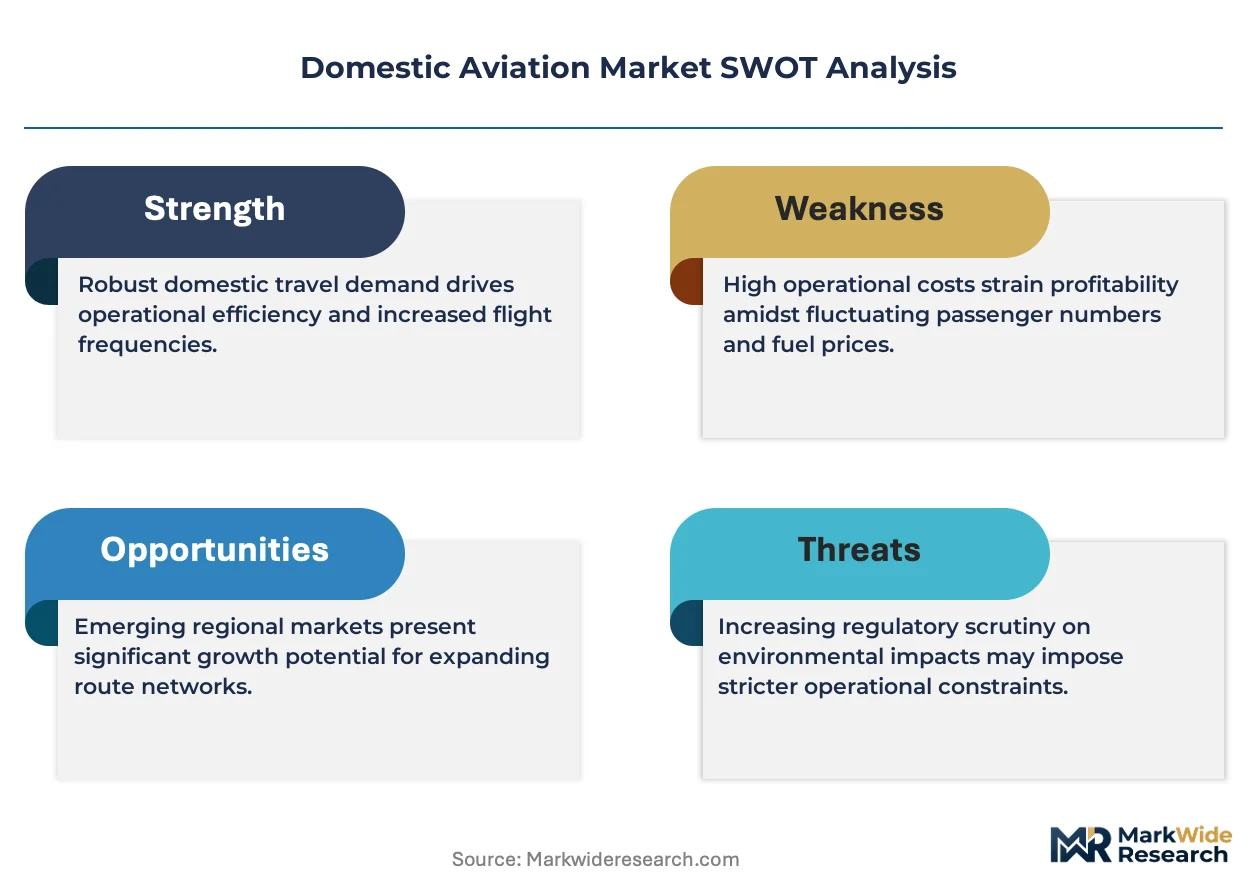
The central tension in domestic aviation is the financial imperative for post-pandemic network recovery clashing with the capital-intensive demands of long-term fleet modernization. This dynamic is sharpened by intensifying regulatory pressure for decarbonization, exemplified by frameworks like the EU Green Deal, which directly influence operational cost structures.
Growth Catalysts
- Infrastructure Expansion in India:Government-led development of new airports and modernization of existing ones, coupled with rising disposable income, unlocks air travel for a larger portion of the population in secondary cities.
- Corporate Traveler Demand:A persistent need from the business segment for high-frequency, point-to-point travel to minimize transit time continues to support higher-yield routes and premium cabin demand.
- Sustainable Aviation Fuel (SAF) Incentives:Policy support and mandates for SAF, such as those within the EU's Fit for 55 package, create a clear demand signal, stimulating investment in alternative fuel production and supply chains.
Market Restraints
- Volatile Input Costs:Airline profitability remains highly sensitive to the fluctuating prices of conventional jet fuel and the currently high production cost of Sustainable Aviation Fuel (SAF), creating significant operational uncertainty.
- Infrastructure Bottlenecks:Slot restrictions at major hub airports and outdated air traffic management systems in several key countries limit the ability of airlines to add frequency or launch new routes, constraining growth.
- Stringent Regulatory Hurdles:The lengthy and expensive aircraft and engine certification processes mandated by bodies like the FAA and EASA create high barriers to entry for new technologies and delay the deployment of more efficient assets.
Strategic Opportunities
- Regional and Short-Haul Electrification:The development of small-capacity electric and hybrid-electric aircraft presents an opportunity to serve short, thin routes with lower operational costs and zero direct emissions, connecting currently underserved communities.
- Advanced Ancillary Services:Leveraging passenger data and digital platforms allows for the creation of sophisticated, personalized ancillary revenue streams, moving beyond basic baggage fees to curated travel and retail experiences.
- Connectivity in Southeast Asia:Archipelagic nations like Indonesia and the Philippines feature vast, geographically dispersed populations with limited ground transport, representing a significant white space for domestic air network expansion.
Industry Challenges
- Critical Labor Shortages:A systemic lack of qualified pilots, aircraft maintenance engineers, and air traffic controllers across the industry constrains growth, increases labor costs, and leads to operational disruptions.
- Fleet Renewal Capital Intensity:The immense capital investment required to replace aging aircraft with newer, more fuel-efficient models that meet future environmental standards poses a significant financial challenge for many carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Domestic Aviation Market |
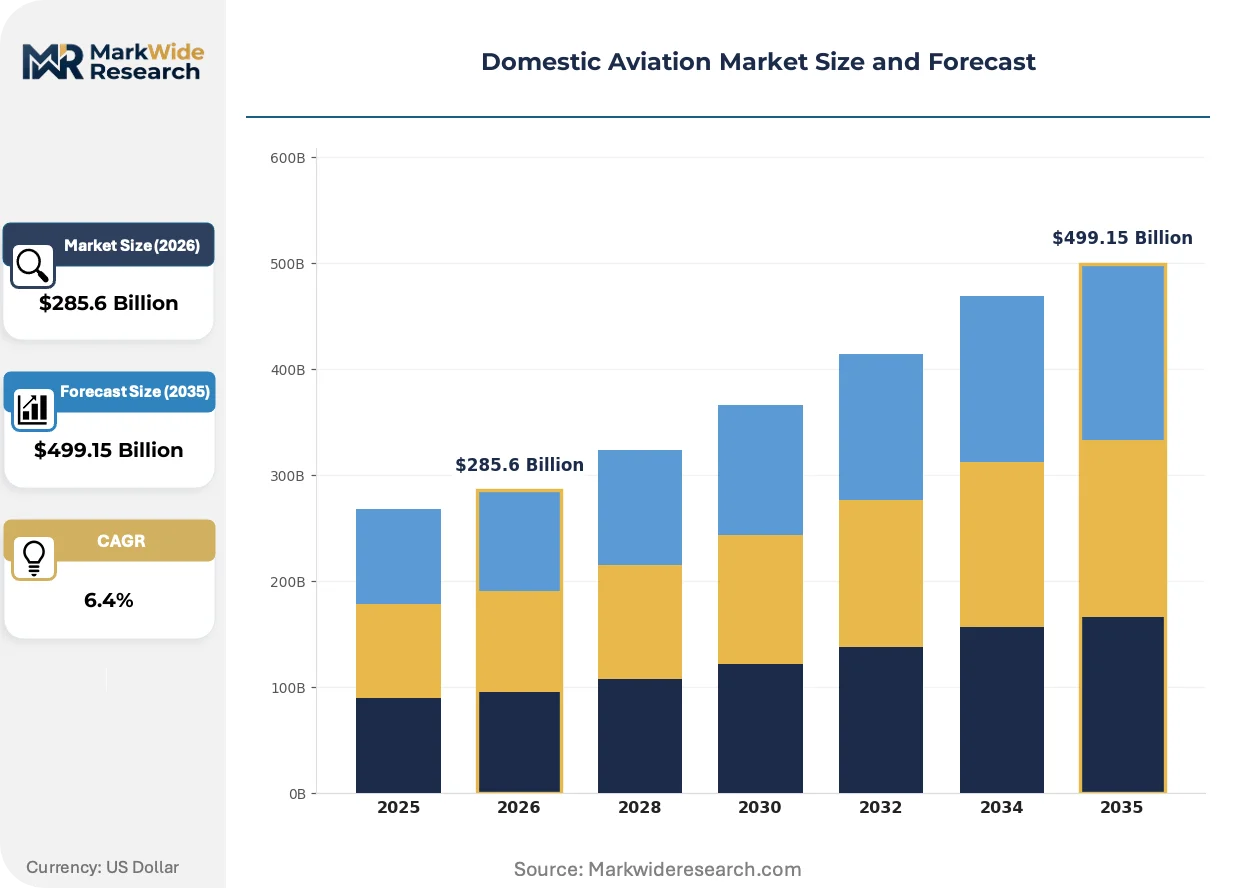
| Market Size in 2026 | $285.6 Billion |
| Market Size in 2035 | $499.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Single-Aisle Jets, Turboprop Planes, Regional Jets, Business Jets Service Class: Economy, Premium Economy, Business, First Class Flight Distance: Short Haul, Medium Haul, Long Haul, Ultra-Short Haul Customer Segment: Leisure Travelers, Corporate Travelers, Government Officials, Charter Operators |
| Companies Covered | Southwest Airlines, Air China, Delta Air Lines, China Eastern Airlines, China Southern Airlines, United Airlines Holdings, InterGlobe Aviation (IndiGo), All Nippon Airways, American Airlines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Domestic Aviation Market Strategic Shifts & Innovations
A fundamental re-evaluation of the passenger experience and operational efficiency defines the current market. Digital transformation and sustainability mandates are intertwined forces compelling airlines to innovate within the cabin, on the ground, and across their network planning strategies.
The introduction of Premium Economy seating is a defining product evolution. This cabin class offers a distinct service and comfort level positioned between traditional Economy and Business classes. Both corporate and leisure travelers are adopting this option, seeking an enhanced experience without the full expense of a premium flat-bed seat. This trend is bifurcating the conventional two-class aircraft layout, impacting airline revenue management models and airframe configuration choices.
Regulatory frameworks targeting emissions are directly altering airline cost structures and fleet strategies. The European Union's Emissions Trading System (EU ETS) requires airlines to surrender allowances for their carbon emissions, creating a direct financial incentive for decarbonization. This policy most heavily affects carriers operating older, less efficient aircraft on intra-European routes, accelerating decisions to invest in new-generation jets and alternative fuels like SAF.
Passenger booking behavior is shifting decisively toward airline-direct digital channels. This move, driven by sophisticated airline loyalty programs and mobile applications, challenges the historical dominance of third-party Online Travel Agencies (OTAs) and Global Distribution Systems (GDS). This trend is most advanced in the United States and parts of Europe, where major carriers are leveraging data to personalize offers and control the customer relationship directly.
Domestic Aviation Market Segmentation
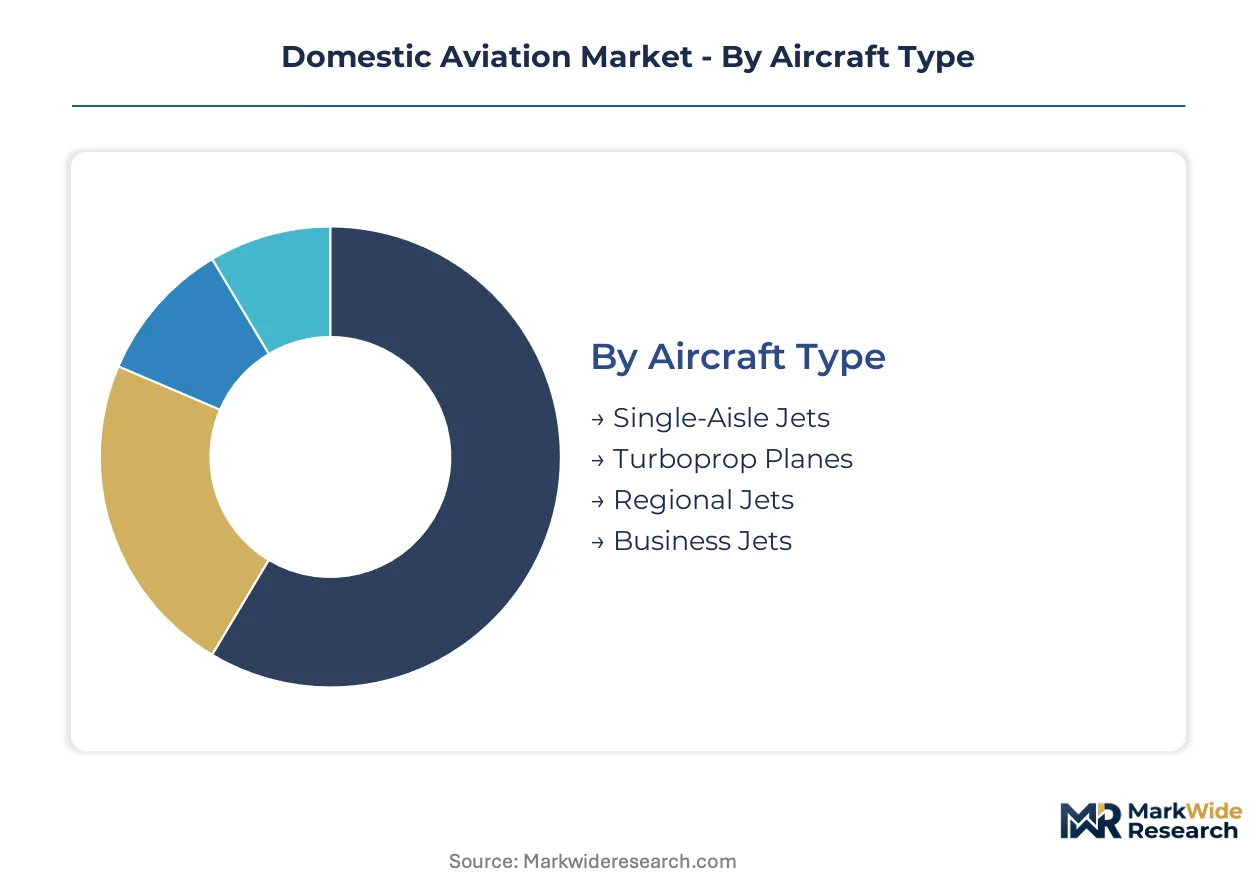
The domestic aviation market's intricate structure necessitates detailed segmentation to understand passenger flows and operational models. Airlines tailor services and aircraft types to specific route characteristics and traveler needs. This granular analysis reveals distinct revenue streams and competitive dynamics across various market dimensions.
Aircraft Type:
Margin pools within the aircraft type segment are heavily influenced by operational efficiency and passenger density.
- Single-Aisle Jets:These aircraft form the backbone of domestic networks, characterized by their high operational cycles and seating capacities typically ranging from 100 to 220 passengers. Demand concentrates on high-frequency routes between major city pairs in countries like the United States and India, driven by their cost-effectiveness per seat-mile.
- Regional Jets:Designed for shorter routes and lower passenger volumes, these aircraft typically seat 50 to 100 passengers and offer crucial connectivity to smaller airports. Demand is strong in geographically dispersed regions like Southeast Asia and across vast countries like China, where they link secondary cities to hubs.
- Turboprop Planes:These propeller-driven aircraft excel in short-field operations and fuel efficiency for short distances, connecting remote communities.
- Business Jets:Offering unparalleled flexibility and privacy, these aircraft cater to high-net-worth individuals and corporate executives for on-demand travel.
Single-Aisle Jets hold installed capacity. Regional Jets are rotating up the share rankings.
Service Class:
The service class segmentation reflects distinct pricing strategies and passenger expectations across different cost tiers.
- Economy:This class represents the largest passenger volume, offering basic amenities and standard seating configurations for budget-conscious travelers. Demand is universally high across all domestic markets, particularly in price-sensitive segments in India, fueling overall passenger volume.
- Premium Economy:Positioned between Economy and Business, this class provides enhanced comfort, more legroom, and upgraded services at a moderate price point. Demand is expanding rapidly in developed markets like the United States and Europe, appealing to both leisure travelers seeking more space.
- Business:This class targets corporate travelers with superior seating, priority services, and elevated in-flight experiences on key routes.
- First Class:Offering the highest level of luxury and personalized service, this exclusive class caters to ultra-premium domestic travel.
Economy class drives the highest passenger volume. Premium Economy is gaining share due to enhanced value propositions.
Flight Distance:
Flight distance dictates specific operational models and aircraft utilization strategies for airlines.
- Short Haul:These flights typically cover distances under 1,000 km, characterized by high frequency and quick turnaround times at airports. Demand dominates domestic networks globally, especially in dense regions like the European Union and coastal China, optimizing for business and commuter traffic.
- Medium Haul:Covering distances between 1,000 km and 3,000 km, these routes balance passenger volume with extended flight times. Demand is significant for connecting major economic centers within large countries like the United States and Australia, supporting both leisure and corporate travel.
- Long Haul:Domestic long-haul flights exceed 3,000 km, often requiring wide-body aircraft for transcontinental journeys within large nations like Russia or Canada.
- Ultra-Short Haul:These very brief flights, typically under 300 km, connect proximate cities or islands, prioritizing rapid transit and regional accessibility.
Short Haul flights are foundational for network frequency. Medium Haul routes enable broader national connectivity.
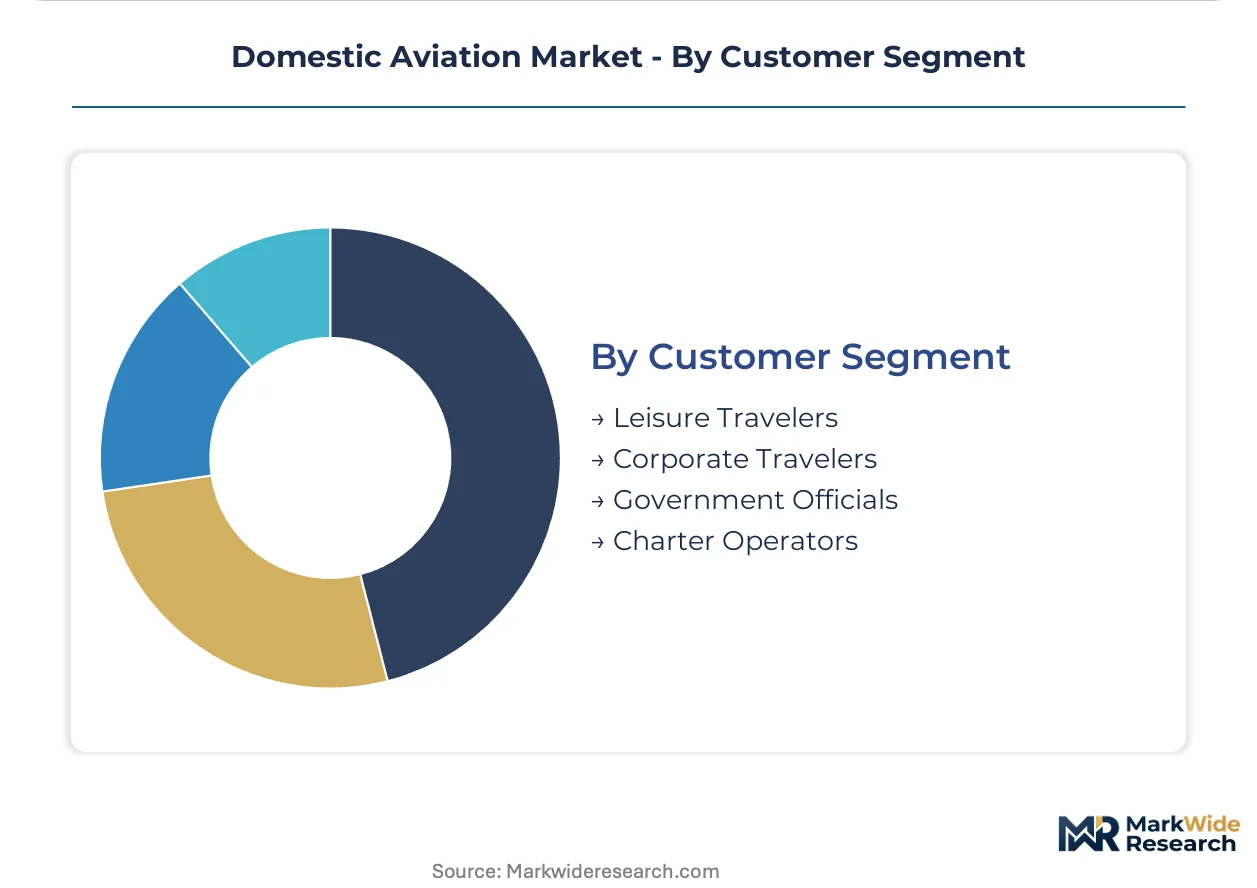
Customer Segment:
Each customer segment contributes uniquely to airline revenue and shapes service offerings.
- Leisure Travelers:This segment comprises individuals and families traveling for holidays, personal visits, or recreation, often driven by price sensitivity and seasonal demand. Demand is substantial across all domestic markets, particularly robust in countries with growing middle classes like India, fueling overall passenger volume.
- Corporate Travelers:Business professionals flying for work prioritize schedule flexibility, efficiency, and premium service, often generating higher yields per seat. Demand remains resilient for point-to-point connections in major business hubs globally, particularly in the United States and Germany, supporting premium cabin growth.
- Government Officials:This segment requires secure, reliable, and often flexible travel solutions for official duties, sometimes utilizing dedicated government contracts.
- Charter Operators:These entities provide customized, on-demand air travel for groups or specialized cargo, bypassing fixed schedules and routes.
Leisure Travelers drive significant volume fluctuations. Corporate Travelers provide a stable, high-yield revenue base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic aviation activity concentrates heavily in large, geographically diverse nations with significant economic centers and growing middle-class populations. These markets attract substantial investment in infrastructure and fleet modernization, driven by both commercial demand and strategic national development goals. Regulatory frameworks vary by region, influencing operational costs and market entry barriers for airlines.
United States
High corporate travel demand and a large leisure segment consistently drive passenger volumes across the expansive United States domestic network. The Federal Aviation Administration (FAA) sets stringent safety and operational standards, influencing fleet choices and maintenance protocols. Major hubs like Atlanta, Chicago, and Dallas-Fort Worth serve as critical connection points, facilitating high-frequency operations.
India
Rising disposable incomes and ambitious airport infrastructure expansion programs are unlocking significant air travel demand in India. The Directorate General of Civil Aviation (DGCA) oversees aviation safety and economic regulation, supporting aggressive network growth by carriers. Delhi and Mumbai anchor dense air traffic corridors, connecting a rapidly urbanizing population.
China
Massive scale and improving service within a highly regulated national system characterize China's domestic aviation landscape, catering to both business and leisure travelers. China's dual carbon goals directly influence fleet renewal decisions, pushing for more fuel-efficient aircraft. The Yangtze River Delta region, including Shanghai, represents a major economic and air transport cluster.
Germany
Corporate travelers provide a stable, high-yield revenue base in Germany, prioritizing efficiency and premium services for intra-European connections. The European Union Aviation Safety Agency (EASA) enforces comprehensive safety and environmental regulations, including the EU ETS, impacting operational costs. Frankfurt and Munich airports are central to the country's aviation network, linking key industrial centers.
Australia
Connecting major economic centers across vast distances creates significant demand for medium-haul domestic routes in Australia, supporting both leisure and corporate travel. The Civil Aviation Safety Authority (CASA) regulates aviation safety and airworthiness standards for domestic operations. Sydney and Melbourne are pivotal hubs, managing high passenger traffic between the country's largest cities.
Domestic Aviation Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the domestic aviation market. The industry structure shows consolidation among legacy carriers in mature markets, alongside fragmentation in emerging economies with numerous low-cost entrants. Strategic archetypes include full-service network airlines, ultra-low-cost carriers, and regional specialists.
Full-service network airlines, such as Delta Air Lines and China Southern Airlines, prioritize extensive route networks and premium amenities, often operating significant domestic and international services. Low-cost carriers, exemplified by Southwest Airlines and InterGlobe Aviation (IndiGo), focus on high-frequency, point-to-point routes with simplified service models to achieve cost efficiencies. These different models shape competitive dynamics across various geographic markets.
| Leading Market Players |
|---|
| Southwest Airlines |
| Air China |
| Delta Air Lines |
| China Eastern Airlines |
| China Southern Airlines |
| United Airlines Holdings |
| InterGlobe Aviation (IndiGo) |
| All Nippon Airways |
| American Airlines |
| Others |
Cost & Logistics Intelligence
The European Union Aviation Safety Agency (EASA) certification process gates both aircraft supply qualification and subsequent price differentiation for carriers operating within Europe. This regulatory oversight significantly influences fleet choices and operational cost structures across global domestic aviation.
Pricing Analysis
The EU's Emissions Trading System (EU ETS) dictates the pricing tier structure for intra-European flights, creating direct costs for carbon emissions. Pricing stratifies across premium, business, and economy tiers, driven by customer segment expectations for comfort and service. Corporate travelers consistently provide higher per-seat revenue, while leisure travelers exhibit greater price sensitivity. Pricing softness stems from intense competition on high-frequency routes and the volatility of conventional jet fuel costs.
Supply Chain Analysis
The United States and Europe anchor the supply of major single-aisle and regional jets, with manufacturers like Boeing and Airbus dominating. The domestic aviation supply chain draws from critical raw materials like jet fuel, specialized aircraft components, and increasingly, Sustainable Aviation Fuel (SAF) feedstocks. A structural supply chain risk is the single-source vulnerability for advanced aircraft engines from a few global manufacturers. Distribution runs through direct sales from OEMs to airlines and a network of MRO facilities for parts and servicing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story for established players, largely due to strong regulatory entrenchment and the significant capital barriers to entry for new aircraft types.
For Market Incumbents: Secure long-term supply agreements for Sustainable Aviation Fuel (SAF) to de-risk future operational costs and meet decarbonization mandates. Invest in comprehensive pilot and maintenance engineer training programs to mitigate critical labor shortages, preventing operational disruptions. Modernize existing fleets with new-generation, fuel-efficient aircraft to reduce emissions and enhance cost competitiveness against emerging technologies.
For New Entrants and Emerging Players: Differentiate on niche service models by targeting underserved regional routes with electric or hybrid-electric aircraft, offering lower operational costs. Focus on markets with limited ground transport infrastructure, such as archipelagic nations in Southeast Asia, as a penetrable segment. Develop direct-to-consumer digital booking platforms, leveraging personalized ancillary services to build customer loyalty.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the fleet modernization and decarbonization segments, creating opportunities for specialized infrastructure investments. Long-term viability hinges on carriers' ability to balance post-pandemic network recovery with capital-intensive demands for sustainable operations. Acquisition targets should include regional carriers with strong local network effects or technology firms developing advanced air mobility solutions. A signal to watch is the scaling of SAF production and the certification progress of electric aircraft prototypes.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Modernization Investment | Reduces operational costs and carbon emissions, aligning with environmental regulations. |
| Sustainable Aviation Fuel Partnerships | Secures future fuel supply, mitigating price volatility and regulatory compliance risks. |
| Digital Customer Experience Enhancement | Strengthens direct booking channels and personalizes ancillary revenue streams. |
| Regional Network Expansion | Connects underserved communities, unlocking new passenger volumes and revenue. |
| Advanced Workforce Training Programs | Addresses critical labor shortages for pilots and maintenance, ensuring operational stability. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary data anchors the qualitative findings. This study engaged airline executives, airport operations managers, MRO providers, and regulatory officials to gather nuanced perspectives. Secondary sources included reports from the FAA, EASA, IATA, company financial filings, and various aviation industry association publications, ensuring comprehensive data coverage. The analysis triangulates bottom-up market sizing with top-down validation.
Sensitivity analysis informs the forecast framework, evaluating the impact of various macroeconomic and industry-specific variables across the analysis window. The market segmentation dimensions modeled include aircraft type, service class, flight distance, customer segment, and key regional markets. Compound annual growth rates (CAGRs) were derived through a proprietary quantitative model, incorporating inputs such as disposable income growth, infrastructure development rates, and Sustainable Aviation Fuel (SAF) availability.
Decision-makers should treat outputs as directional under the named base assumptions for economic stability and regulatory continuity; material deviation would warrant model refresh. Forecasts reflect assumptions concerning global economic growth, geopolitical stability, and the pace of decarbonization efforts in aviation. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aviation and Defense Training and Simulation
Charter Jet Services Market
Aviation and Defense Training and Simulation
South-East Asia Civil Aviation Market
Aviation and Defense Training and Simulation
US Helicopter Services Market
Aviation and Defense Training and Simulation
Global Airlines Market
Aviation and Defense Training and Simulation
Digital Aviation Market
Aviation and Defense Training and Simulation
Helicopter Services Market
Aviation and Defense Training and Simulation
North America Charter Jet Services Market
Aviation and Defense Training and Simulation
Middle-East and Africa Jet Charter Services Market