
 Aircraft Door Market | 2026-2036
Aircraft Door Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Door Market Analysis
Narrow-body commercial aviation is decoupling from wide-body fleet renewal cycles as carriers optimize for frequency and fuel efficiency on short-haul routes. Safran Cabin leverages vertical integration across cabin interiors and door systems to secure long-term supply agreements with Airbus and Boeing. Latecoere anchors European aftermarket services through its MRO network, while Collins Aerospace differentiates via electromechanical door actuation technology that reduces maintenance intervals.
An aircraft door is a pressurized structural assembly comprising a frame, panel, sealing mechanism, and emergency evacuation system, typically manufactured through matched die forming or resin transfer molding to achieve weight targets below 45 kilograms for main cabin variants. Its primary function is to maintain cabin pressure integrity while enabling rapid egress and cargo loading operations. Composite material doors represent the fastest-growing segment as OEMs pursue airframe weight reduction, while aluminum retains dominance in retrofit channels where certification costs constrain material switching. Main cabin doors command the largest share of installed value, though emergency exit doors are gaining share with the rise of high-density narrow-body configurations.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements govern structural integrity, fire resistance, and emergency opening forces, compelling manufacturers to maintain dual-qualification testing protocols. The EU Green Deal's emissions trajectory is pressuring OEMs to specify lighter door assemblies, tightening material traceability through REACH compliance. Stakeholders must monitor evolving ICAO noise and emissions standards that could accelerate fleet replacement timelines and redirect aftermarket demand toward certified sustainable material options.
Market Dynamics
Composite material qualification requirements are reshaping supplier tier structures as FAA and EASA tighten airworthiness traceability standards, forcing tier-two fabricators to absorb certification costs or exit narrow-body supply chains.
Growth Catalysts
- REACH material traceability mandates:European OEMs now specify full supply chain documentation for thermoset resins, accelerating qualified supplier consolidation and locking in long-term contracts.
- Intra-ASEAN route densification:Low-cost carriers in Indonesia, Vietnam, and the Philippines are tripling narrow-body fleet commitments to capture rising middle-class mobility.
- Thermoplastic welding processes:Out-of-autoclave manufacturing is reducing door assembly cycle times by eliminating bonded joint curing bottlenecks.
Market Restraints
- Carbon fiber prepreg cost volatility:Aerospace-grade tow pricing fluctuates with energy feedstock markets, compressing margin visibility for door panel fabricators.
- Single-source titanium forging concentration:Critical door hinge castings rely on three North American foundries, creating geographic supply vulnerability.
- FAA Part 25.783 emergency opening force thresholds:Manual evacuation testing requirements limit electromechanical actuation adoption in retrofit channels.
Strategic Opportunities
- India's UDAN regional connectivity scheme:Subsidized turboprop and small jet procurement is creating demand for lightweight passenger and cargo door variants.
- Blockchain-enabled part pedigree tracking:Immutable material certification records reduce audit friction for MRO providers serving EU-registered fleets.
- Hydrogen-powered aircraft architectures:Revised fuselage pressure vessel designs require novel door sealing geometries absent from current product portfolios.
Industry Challenges
- Composite NDI technician scarcity:Ultrasonic and thermography inspection expertise for bonded door assemblies outpaces vocational training pipeline output.
- Dual FAA-EASA certification timeline compression:Harmonized test protocols remain misaligned on fire resistance duration standards, forcing redundant qualification campaigns.
- Legacy 737 and A320 door interchangeability:Proprietary fastener patterns and frame geometries obstruct third-party aftermarket entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Door Market |
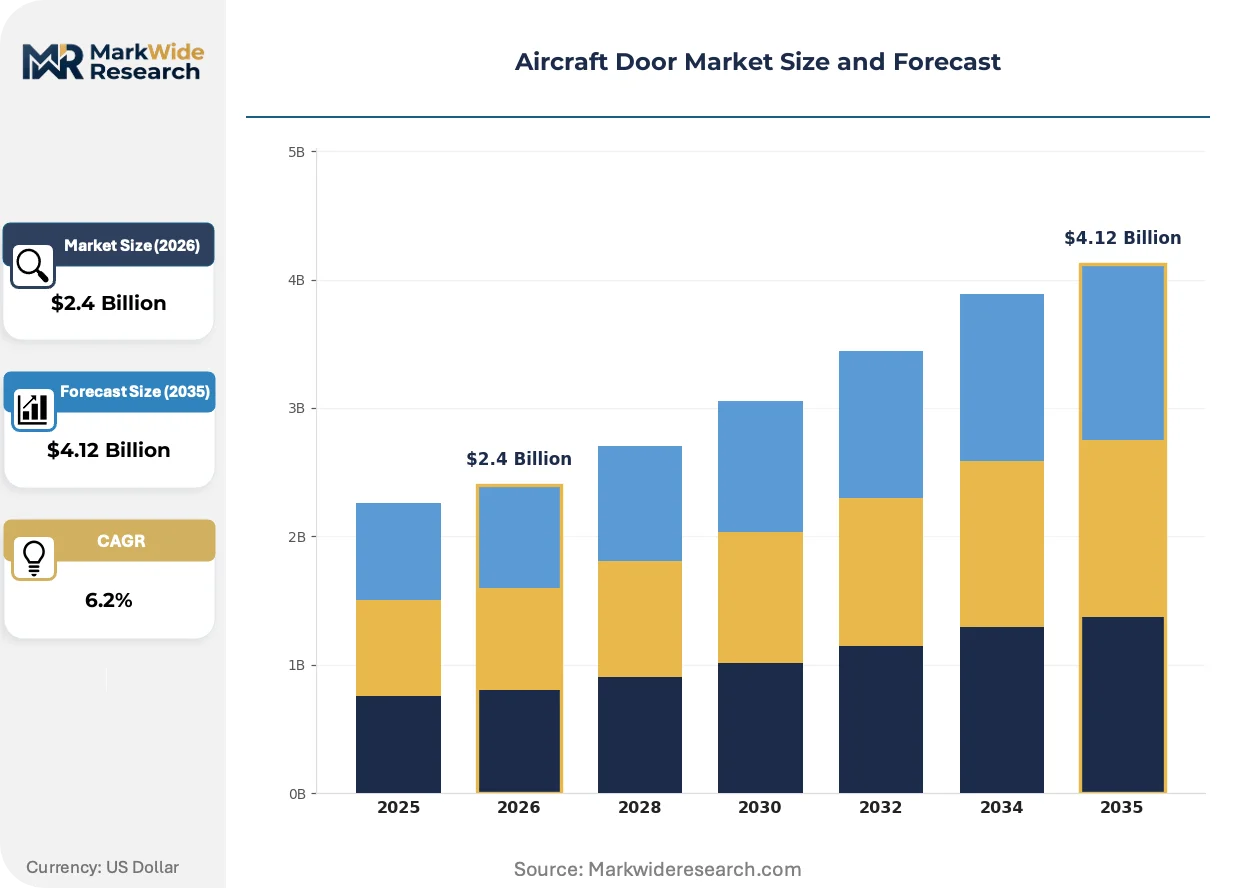
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Main Cabin Door, Emergency Exit Door, Service Door, Cargo Door Material: Aluminum, Composite, Steel, Plastic Installation: OEM, Retrofit, Aftermarket, Replacement End User: Commercial Aviation, Military Aviation, General Aviation, Cargo Operators |
| Companies Covered | Safran Cabin, Latecoere, Collins Aerospace, Spirit AeroSystems, Triumph Group, Elbit Systems, Mitsubishi Heavy Industries, Premium AEROTEC, Aernnova Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Door Market Emerging Trajectories
Electromechanical actuation architectures are displacing pneumatic systems across next-generation programs, while material traceability requirements and fleet densification strategies are compressing supplier decision timelines.
Thermoplastic composite door panels are expanding into main cabin applications previously reserved for thermoset constructions. Airbus and Boeing engineering teams have accelerated qualification timelines for polyaryletherketone-based structures in single-aisle programs. This material transition is expanding into emergency exit variants as OEMs pursue commonality across door families to reduce spare part complexity.
EASA's evolving CS-25 certification memos on structural health monitoring are mandating integrated sensor networks in door assemblies. Manufacturers must now embed fiber optic strain gauges and wireless data transmission modules to satisfy continuous airworthiness documentation. Wide-body programs serving European operators are absorbing these requirements first, with narrow-body retrofit mandates following within subsequent regulatory cycles.
Airline technical procurement teams are consolidating door system awards into airframe-level lifetime agreements rather than component-by-component sourcing. This bundling behavior concentrates specification influence with Airbus and Boeing engineering departments, marginalizing independent door suppliers from direct airline relationships. Southeast Asian low-cost carriers are pioneering this consolidated sourcing model, pressuring European and North American network carriers to follow.
Aircraft Door Market Segmentation
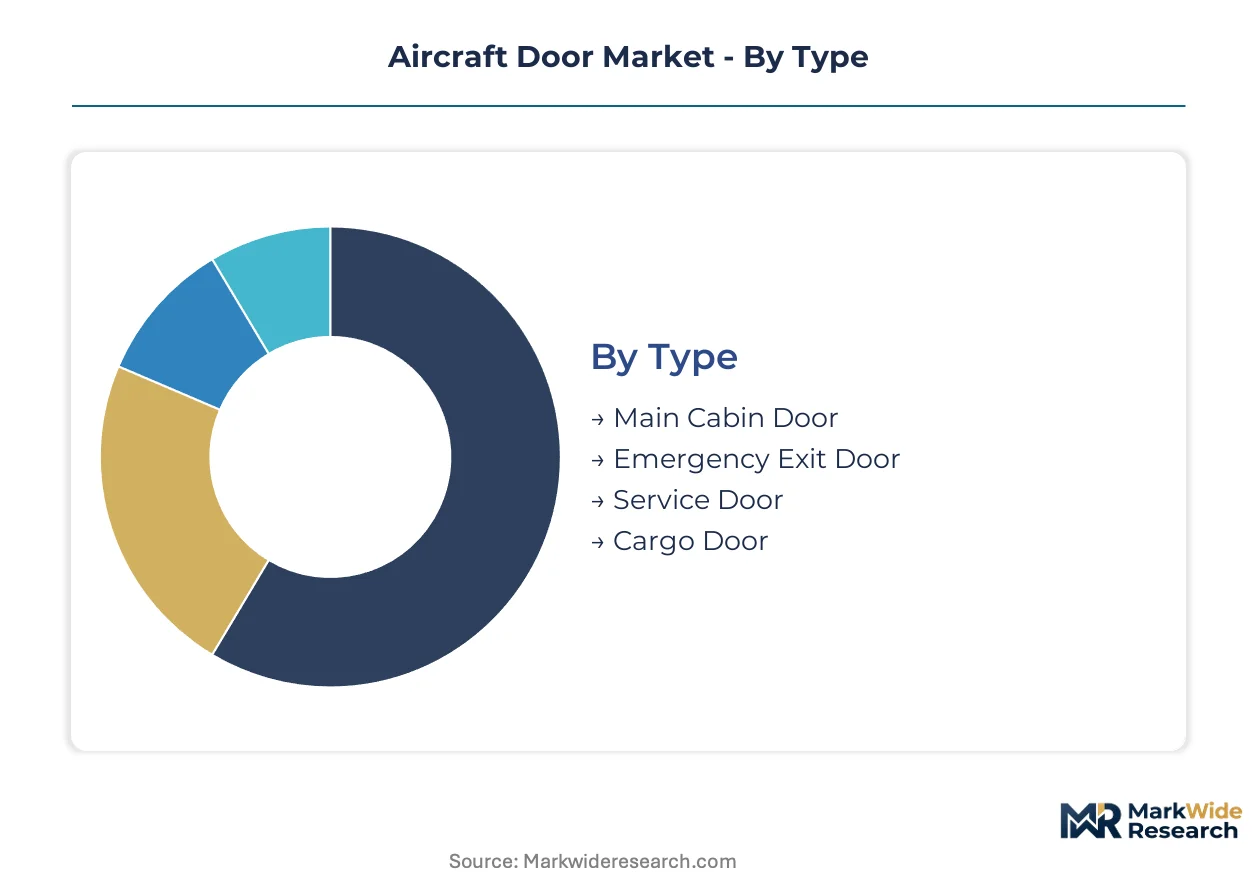
Door specification varies sharply across aircraft programs, with each segment carrying distinct certification burdens and margin profiles. Material and installation channel choices determine supplier qualification depth and contract duration.
Type:
Main cabin doors command premium installed value due to structural load-bearing requirements, while emergency exit variants scale on narrow-body fleet densification trends.
- Main Cabin Door:Pressurized structural assemblies integrating frame, panel, and emergency evacuation systems. Airlines in Indonesia and Vietnam specify these for high-cycle narrow-body deployments where door reliability directly affects dispatch rates. Composite variants are displacing aluminum in new-build programs as OEMs pursue weight targets.
- Emergency Exit Door:Compact plug-type assemblies certified for rapid manual opening under FAA Part 25.783 force thresholds. Demand concentrates with Southeast Asian low-cost carriers configuring high-density A320neo and 737 MAX cabins. Regulatory mandates for evacuation testing constrain electromechanical actuation adoption.
- Service Door:Non-pressurized utility access points for galley loading and maintenance access.
- Cargo Door:Large-format structural openings with reinforced hinge mechanisms for containerized freight loading.
Today's leader: Main Cabin Door. Tomorrow's challenger: Emergency Exit Door.
Material:
Cost tiers separate qualified aerospace-grade composites from commodity aluminum retrofit channels.
- Composite:Thermoset and thermoplastic matrices fabricated through resin transfer molding or out-of-autoclave welding. Airbus and Boeing engineering specifications now prioritize these for single-aisle programs under EU Green Deal emissions pressure. REACH traceability mandates lock in qualified resin suppliers.
- Aluminum:Legacy 7000-series and 2000-series alloys dominating retrofit channels where recertification costs block material switching. MRO providers in Europe retain extensive aluminum repair capabilities for aging narrow-body fleets.
- Steel:High-strength alloys for hinge castings and emergency exit door frames.
- Plastic:Interior trim and non-structural fairing components.
Composite adoption climbs fastest where OEMs control specification. Aluminum defends installed base through MRO inertia.
Installation:
Channel margins widen toward OEM line-fit, while aftermarket volume concentrates on aging fleet support.
- OEM:Factory-integrated door assemblies specified during airframe procurement. Boeing and Airbus engineering departments bundle these into lifetime supply agreements, marginalizing independent door suppliers from direct airline negotiations.
- Retrofit:Post-delivery modification programs for cabin reconfiguration or regulatory compliance upgrades.
- Aftermarket:Spare part provisioning and MRO services anchored by Latecoere's European network.
- Replacement:Damage-driven unscheduled component swaps.
OEM contracts capture specification power. Aftermarket channels absorb fleet age and accident-driven demand spikes.
End User:
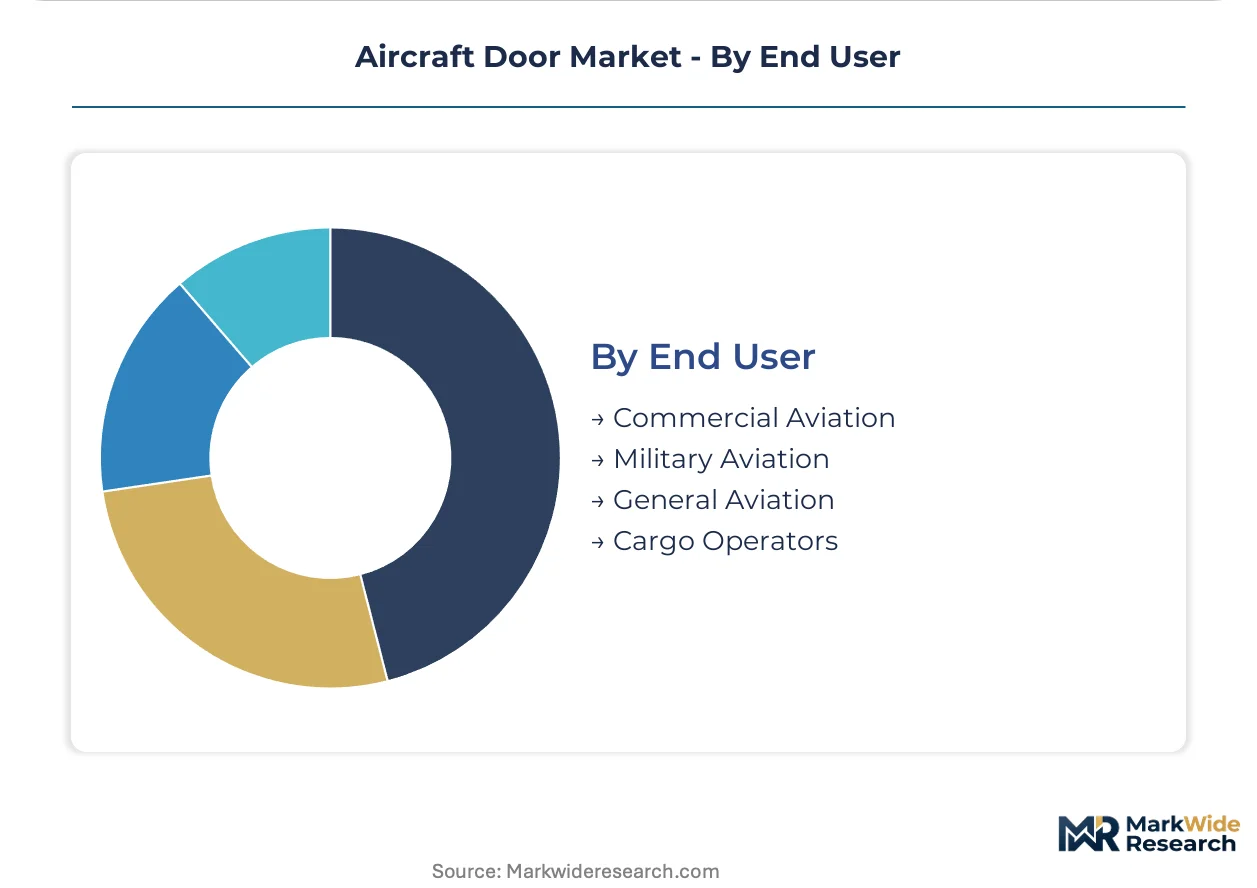
Commercial aviation volume dwarfs military and general aviation, with cargo operators driving specialized large-door requirements.
- Commercial Aviation:Narrow-body and wide-body operators specifying doors through airframe-level procurement. Intra-ASEAN route densification by Indonesian, Vietnamese, and Philippine low-cost carriers concentrates demand for lightweight, high-cycle door variants.
- Military Aviation:Specialized pressurized and unpressurized door systems for tactical transport and tanker programs.
- General Aviation:Business jet and regional turboprop door assemblies with lower certification stringency.
- Cargo Operators:Main deck and lower lobe cargo door configurations for converted freighter programs.
Commercial narrow-body fleets absorb production capacity. India's UDAN regional connectivity scheme opens turboprop door demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toulouse anchors the global aerospace corridor where Airbus final assembly lines concentrate door procurement specifications. France's Occitanie region hosts tier-one suppliers qualifying composite door structures under EASA CS-25 mandates. This study examines five national markets where narrow-body fleet expansion and regulatory divergence reshape supplier geography.
United States
Boeing's 737 MAX production surge in Renton drives composite door demand for high-cycle narrow-body deployments. FAA Part 25.783 emergency opening force standards constrain electromechanical actuation adoption in retrofit channels. Wichita's Spirit AeroSystems cluster supplies structural door assemblies integrated into Boeing's lifetime procurement agreements.
France
Airbus A320neo family ramp-up at Toulouse-Blagnac concentrates specification power for main cabin and emergency exit door variants. EU Green Deal emissions trajectories pressure OEMs to specify thermoplastic composite assemblies with full REACH resin traceability. Latecoere's Toulouse headquarters anchors European aftermarket MRO services for aging narrow-body fleets.
China
COMAC C919 certification progress and domestic narrow-body fleet expansion accelerate qualified supplier localization requirements. MIIT airworthiness standards for structural composites compel joint ventures between Western tier-one fabricators and Chinese state-owned aerospace groups. Tianjin's Airbus final assembly line imports door systems under technology transfer agreements pending full domestic qualification.
Indonesia
Lion Air and Garuda Indonesia low-cost subsidiaries triple narrow-body commitments to capture intra-ASEAN passenger growth. The country's national aviation regulator aligns with ICAO standards while developing domestic certification capacity for composite structural repairs. Batam's aerospace industrial zone hosts MRO facilities serving high-density A320 configurations with frequent door cycling demands.
Germany
Premium AEROTEC's Augsburg and Nordenham facilities supply carbon fiber door panels under Airbus engineering specifications. EASA REACH mandates for thermoset resin documentation lock in qualified supply chains against lower-cost Asian competitors. Bavaria's aerospace cluster concentrates automated fiber placement expertise for out-of-autoclave door manufacturing processes.
Aircraft Door Market Vendor Landscape
Backward integration into resin formulation and hinge forging dominates the current landscape as tier-two fabricators absorb certification costs or exit narrow-body supply chains. The vendor base splits between airframe-captive divisions and independent specialists, with specification influence concentrating at Airbus and Boeing engineering departments. Three archetypes define positioning: vertically integrated cabin systems providers, composite-focused tier-one fabricators, and aftermarket MRO anchors. M&A activity and long-term supply agreement consolidation represent the dominant competitive vectors reshaping tier structures.
Among French-origin integrated suppliers, Safran Cabin exemplifies the cabin-systems bundling archetype that captures specification influence through airframe-level lifetime agreements. Latecoere occupies the aftermarket anchor position with its European MRO network concentration. Collins Aerospace represents the electromechanical specialization vector, with its differentiated actuation technology reducing maintenance intervals for operator fleets. These three entities illustrate how geographic proximity to Airbus and Boeing engineering centers correlates with contract tenure and material qualification depth.
| Leading Market Players |
|---|
| Safran Cabin |
| Latecoere |
| Collins Aerospace |
| Spirit AeroSystems |
| Triumph Group |
| Elbit Systems |
| Mitsubishi Heavy Industries |
| Premium AEROTEC |
| Aernnova Aerospace |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists in aerospace component manufacturing anchor supply behavior through portfolio-company consolidation, translating scale advantages into pricing discipline that resists spot-market volatility for carbon fiber prepreg and titanium hinge castings. Their ownership structures prioritize long-term contract tenure over transactional margin capture, compressing tier-two fabricator exits into accelerated supplier consolidation.
Pricing Analysis
Direct-to-OEM discount structures dominate as Airbus and Boeing engineering departments bundle door assemblies into lifetime supply agreements, marginalizing independent pricing power. Price differentiation rests on certification grade—dual FAA-EASA qualification commands premium positioning against single-jurisdiction suppliers—and volume scale commitments from Southeast Asian low-cost carriers. Cost compression in composite panel fabrication is intensifying because REACH traceability mandates lock resin suppliers into fixed-cost documentation regimes. Retrofit channels exhibit highest price sensitivity due to recertification cost barriers blocking material switching, while OEM line-fit buyers absorb premium thermoplastic pricing under fleet densification timelines.
Supply Chain Analysis
Domestic-content mandates in China's MIIT airworthiness standards are reshaping sourcing, compelling joint ventures between Western tier-one fabricators and state-owned aerospace groups before full qualification transfers. Geographic supply concentration centers on France's Occitanie corridor, Germany's Bavarian aerospace cluster, and Wichita's Spirit AeroSystems hub in the United States. Raw material dependencies draw from aerospace-grade carbon fiber tow, titanium forging capacity concentrated in three North American foundries, and thermoset resin formulations subject to REACH documentation. Single-source vulnerability in hinge casting supply creates geographic risk exposure. Distribution runs through airframe-level lifetime procurement agreements rather than component spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through thermoplastic welding process adoption, which eliminates bonded joint curing bottlenecks and reduces assembly cycle times for door panel fabricators.
For Market Incumbents: Anticipate regulatory divergence between FAA Part 25.783 emergency opening force standards and EASA's evolving structural health monitoring mandates, which will force redundant qualification campaigns unless harmonized test protocols are negotiated proactively. Deepen backward integration into resin formulation to defend against REACH traceability cost absorption by tier-two suppliers. Lock long-term contracts with Indonesian and Vietnamese low-cost carriers before fleet densification procurement peaks. For New Entrants and Emerging Players: The price-point gap between premium thermoplastic composite assemblies and economy-grade aluminum retrofit channels offers entry leverage for qualified fabricators targeting India's UDAN regional connectivity scheme. Target turboprop and small jet door variants where certification stringency remains lower than narrow-body programs. Pursue blockchain-enabled part pedigree tracking as a differentiated service layer for European MRO providers facing audit friction. For Investors and Strategic Acquirers: Valuations sit cheapest among tier-two composite fabricators absorbing certification costs or exiting narrow-body supply chains, presenting consolidation opportunities before supplier tier structures stabilize. Focus on targets with dual FAA-EASA qualification depth and established relationships with Airbus or Boeing engineering departments. Watch electromechanical actuation adoption rates in next-generation programs as the inflection indicator for technology displacement of pneumatic systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | REACH traceability mandates lock in qualified suppliers against Asian competitors. |
| Long-term Supply Agreement Consolidation | Airframe-level lifetime contracts with Lion Air and Garuda Indonesia concentrate volume. |
| Joint Venture for Domestic Qualification | MIIT standards in China compel technology transfer before full market access. |
| Electromechanical Actuation R&D Investment | FAA Part 25.783 thresholds currently constrain retrofit adoption but enable next-generation positioning. |
| Blockchain-Enabled Pedigree Tracking | Immutable certification records reduce audit friction for Latecoere's European MRO network. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with airframe procurement executives, composite manufacturing engineers, MRO service managers, and regulatory certification specialists with secondary validation against FAA Part 25 docket filings, EASA CS-25 certification memos, COMAC type certificate progress disclosures, and customs trade data for aerospace-grade carbon fiber imports. Bottom-up build-ups from individual door program specifications were triangulated against top-down OEM delivery forecasts.
Comparable-period anchoring established historical reference baselines from narrow-body fleet renewal cycles preceding the analysis window, with projections extending across the modeling period through segmented demand modeling by door type, material matrix, installation channel, and end-user category. CAGRs were derived from installed base attrition rates and new-build delivery schedules. Industry-specific inputs incorporated EU Green Deal emissions trajectory pressure and intra-ASEAN route densification patterns.
The model assumes a particular technology adoption path; alternative pathways for hydrogen-powered aircraft architectures requiring novel door sealing geometries would alter the outlook. Forecasts reflect assumptions regarding regulatory harmonization timelines and composite material qualification cost absorption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aerobatic Aircraft Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
Aeronautic Propeller Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
United States Aerospace and Defense Market
Aircraft
GCC General Aviation Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Commercial Aircraft Landing Gear Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market
Aircraft
Asia-Pacific Freighter Aircraft Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
Military Trainer Aircraft Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market