
 India Aviation Market | 2026-2036
India Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
India Aviation Market Outlook
Composite materials are displacing aluminum alloys in narrow-body fuselage construction, which is rebalancing capital deployment across the supply chain. Airbus SE leverages its A320 family order backlog to anchor manufacturing partnerships with Indian suppliers. Boeing competes through technology leadership in fuel-efficient engine integration for next-generation platforms. IndiGo Airlines dominates domestic capacity with a single-airtype fleet strategy that sustains unit cost advantages.
India aviation encompasses the design, manufacture, operation, and maintenance of fixed-wing and rotary aircraft operating within Indian airspace, with turbine engines rated between 20,000 and 90,000 pounds thrust powering commercial narrow-body fleets. The sector serves passenger mobility, cargo logistics, national defense, and emergency response functions across a network of 150-plus operational airports. Commercial aircraft type leads installed base value given IndiGo and Air India fleet renewal cycles, while cargo type records faster growth from e-commerce freight forwarder demand. Ground handling service type captures concentrated margin pools due to regulatory licensing barriers and airport concession economics.
DGCA airworthiness directives and Bureau of Civil Aviation Security screening mandates shape operational compliance costs for all carriers. The PLI scheme for drone components and specialty aerospace alloys directs fresh capital toward domestic manufacturing scale. BIS certification requirements for avionics imports filter market access for foreign technology suppliers. Stakeholders must weigh UDAN route subsidy sustainability against the capital intensity of greenfield airport development in tier-two cities.
Market Dynamics
Fleet modernization cycles and UDAN regional connectivity mandates are compressing procurement timelines while rerouting capital toward narrow-body platforms and tier-two airport infrastructure.
Growth Catalysts
- UDAN Regional Connectivity Scheme:The government's route subsidy framework stimulates demand from underserved tier-two and tier-three cities, expanding addressable passenger base beyond trunk routes.
- PLI Scheme for Aerospace Components:Production-linked incentives for drone parts and specialty alloys attract fresh domestic manufacturing investment, reducing import dependency for critical airframe materials.
- Composite Material Adoption:Carbon fiber reinforced polymers are replacing aluminum in fuselage construction, enabling lighter airframes that extend range and improve fuel efficiency for low-cost carriers.
Market Restraints
- Jet Fuel Cost Volatility:Aviation turbine fuel constitutes the largest operating cost line item, with price swings directly compressing carrier margins and limiting fare flexibility.
- Airport Infrastructure Bottlenecks:Concentrated slot availability at Mumbai and Delhi chokepoints constrains frequency expansion even where demand exists.
- Pilot Training Pipeline Constraints:DGCA-certified training capacity lags fleet expansion timelines, creating licensed crew shortages that cap operational scaling.
Strategic Opportunities
- Cargo Conversion Programs:E-commerce freight forwarder demand is accelerating passenger-to-freighter conversions, opening secondary revenue streams for aging narrow-body assets.
- Drone Logistics Corridors:Beyond-visual-line-of-sight regulations under development enable last-mile delivery networks connecting peri-urban distribution centers.
- MRO Localization:Engine overhaul and component repair capabilities concentrated in Maharashtra and Karnataka capture margin pools currently flowing to Singapore and Dubai facilities.
Industry Challenges
- Airworthiness Certification Timelines:DGCA type certification processes for new avionics imports extend product launch windows, delaying technology refresh cycles.
- Legacy Fleet Integration Complexity:Mixed-generation aircraft operations require duplicate maintenance protocols and spare parts inventories that fragment operational efficiency.
- Skilled Technician Scarcity:Composite repair and advanced avionics troubleshooting capabilities outpace vocational training output, inflating labor costs for specialized functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Aviation Market |
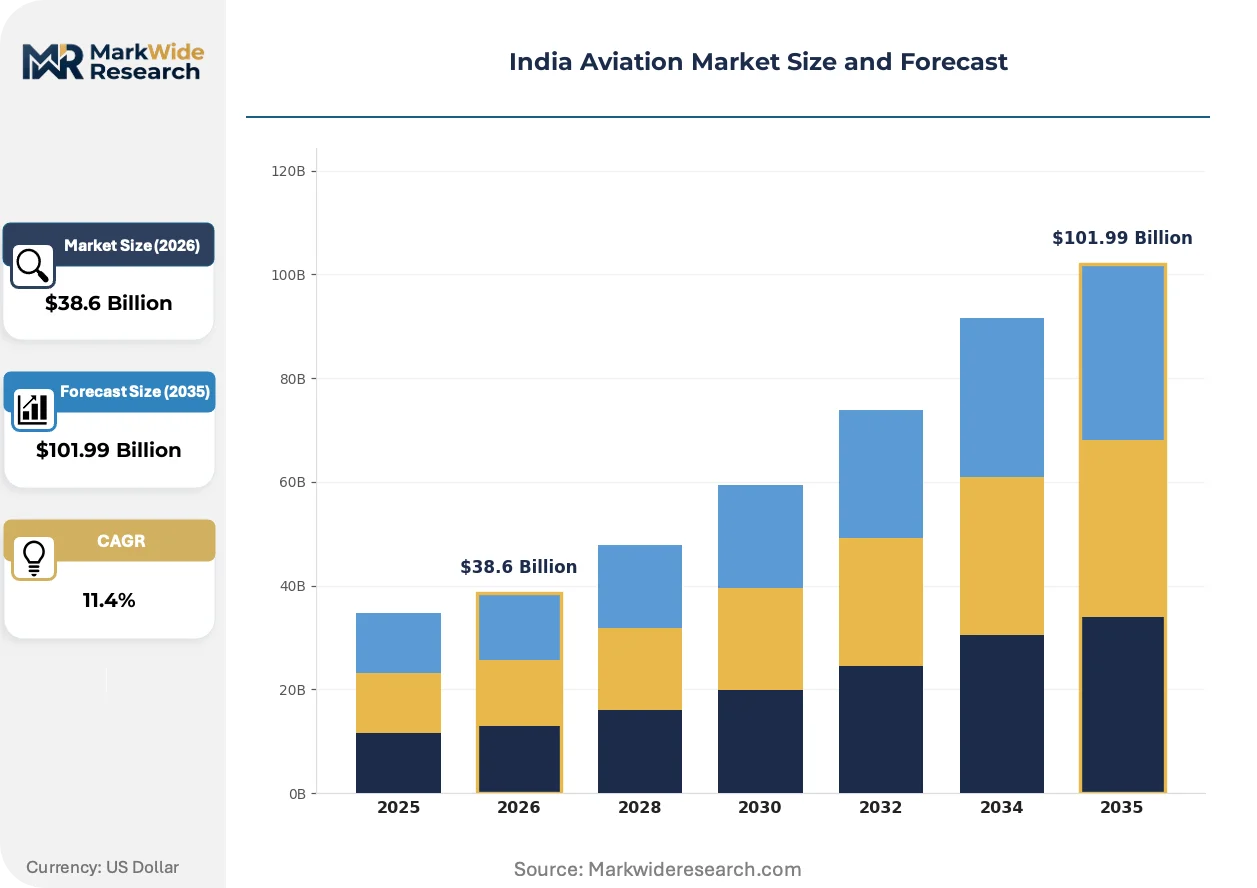
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Commercial, Cargo, Business Jet, Military Service Type: Ground Handling, Maintenance, Flight Operations, Air Traffic Control End User: Airlines, Charter Operators, Defense Services, Freight Forwarders Technology: Avionics, Navigation Systems, Engine Technology, Safety Equipment |
| Companies Covered | IndiGo Airlines, Air India, Air India Express, SpiceJet, Akasa Air, Hindustan Aeronautics Limited (HAL), Airbus SE, The Boeing Company, GMR Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Aviation Market Strategic Shifts
Digital flight operations and sustainable aviation fuels are restructuring cost allocation models while regulatory pressure on emissions intensifies technology substitution timelines across the value chain.
Advanced analytics platforms are decentralizing maintenance decision-making from centralized engineering departments to line stations. Low-cost carriers adopt predictive algorithms that flag component degradation before failure, compressing turnaround times at outstations. This shift is decentralizing MRO network topology toward distributed capability nodes rather than hub-and-spoke repair concentration.
DGCA mandates on sustainable aviation fuel blending percentages are forcing supply chain reconfiguration. Fuel suppliers must secure feedstock contracts with agricultural processors and waste oil aggregators to meet blending obligations. Domestic carriers operating Maharashtra and Karnataka trunk routes face the steepest compliance ramps given higher frequency density and fuel burn volumes.
Corporate travel procurement now prioritizes carbon accounting transparency over legacy loyalty program benefits. Travel management companies unbundle emissions data from ticket pricing, selling verified offset certificates as separate line items. This pattern concentrates among information technology and financial services verticals with published net-zero commitments, particularly in Bengaluru and Hyderabad corporate headquarters clusters.
India Aviation Market Segmentation
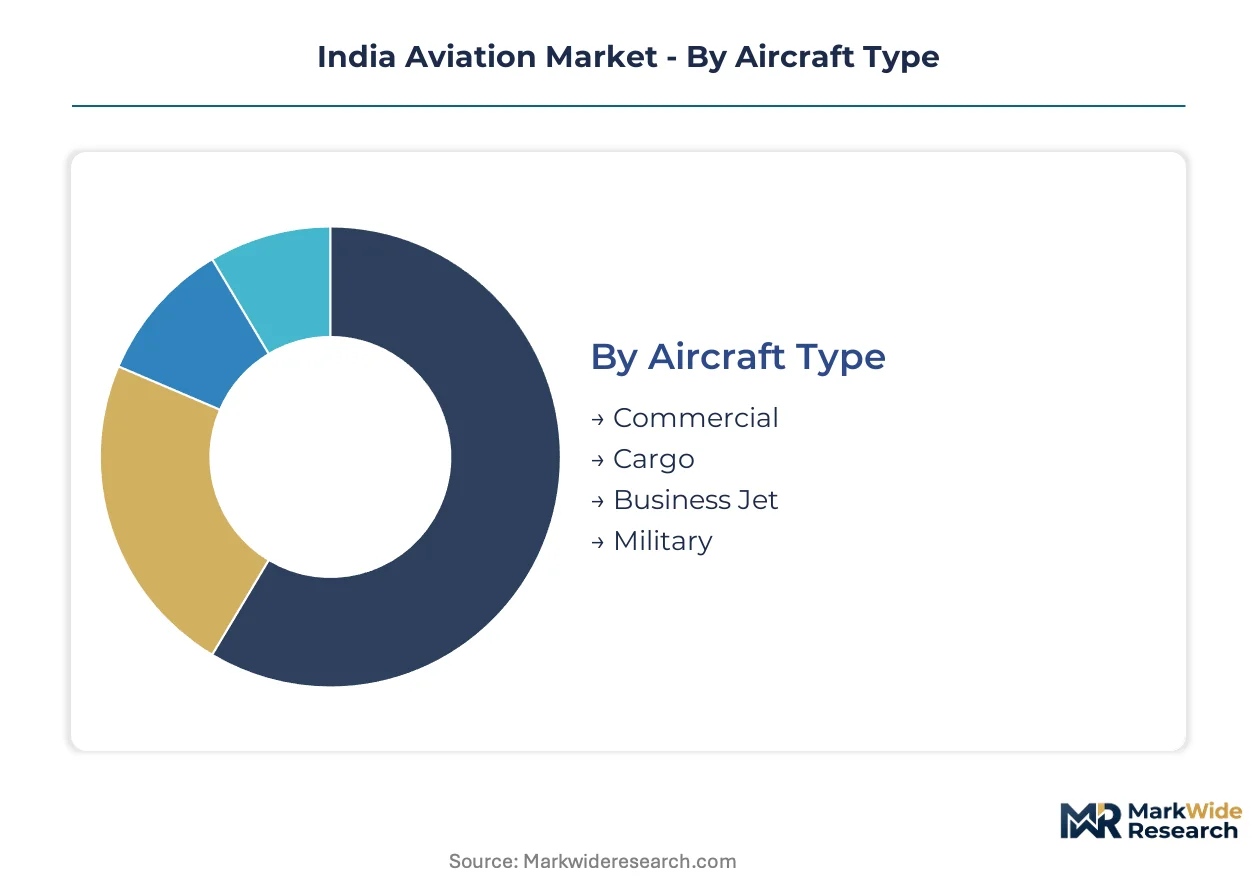
India's aviation market fragments along operational function and asset ownership models that dictate capital intensity, regulatory exposure, and margin structure. Understanding these divisions clarifies where UDAN subsidies, PLI incentives, and fleet renewal cycles concentrate value creation versus cost pressure.
Aircraft Type:
Standardization dominates at the low end through single-airtype fleet strategies, while customization persists in defense and VIP configurations where mission profiles vary.
- Commercial:Narrow-body platforms rated between 20,000 and 90,000 pounds thrust power the installed base, with IndiGo and Air India fleet renewal cycles channeling procurement toward A320 and 737 families. Maharashtra and Karnataka airport expansions absorb the highest delivery volumes as trunk route frequency intensifies.
- Cargo:Passenger-to-freighter conversions accelerate as e-commerce freight forwarders demand dedicated belly capacity; composite airframe compatibility extends conversion economics for aging narrow-body assets.
- Business Jet:Chartered VIP movements concentrate in Delhi-Mumbai corridors with BIS-certified import avionics filtering cabin configuration options.
- Military:Defense procurement operates through Ministry of Defence capital acquisition windows with indigenous platform development prioritized under Atmanirbhar Bharat directives.
Leading the category by volume: Commercial. Expanding most quickly: Cargo.
Service Type:
Margin pools concentrate where regulatory licensing erects barriers to entry, separating concession-protected ground operations from competitive technical services.
- Ground Handling:Airport concession economics grant exclusivity periods that protect pricing power at Mumbai and Delhi slot-constrained facilities. DGCA licensing requirements limit new entrant capacity.
- Maintenance:Engine overhaul and component repair capabilities cluster in Maharashtra and Karnataka, capturing margin pools previously flowing to Singapore and Dubai MRO facilities.
- Flight Operations:Digital dispatch platforms and predictive analytics decentralize decision-making from centralized engineering to line stations.
- Air Traffic Control:Bureau of Civil Aviation Security screening mandates shape staffing protocols and technology procurement timelines for tower modernization.
Generating highest margins: Ground Handling. Steepest capability buildout: Maintenance.
End User:
Customer scale determines procurement leverage, with scheduled carriers extracting volume discounts unavailable to fragmented charter and defense buyers.
- Airlines:Low-cost carriers deploy standardized narrow-body fleets to sustain unit cost advantages, while full-service operators balance wide-body long-haul exposure against trunk route density.
- Charter Operators:On-demand VIP and medical evacuation services operate from tier-two cities under UDAN route subsidy frameworks, expanding addressable passenger bases beyond trunk routes.
- Defense Services:Ministry of Defence capital budgets prioritize indigenous platform development with technology transfer requirements shaping vendor selection.
- Freight Forwarders:E-commerce logistics integrators drive dedicated freighter demand and accelerate passenger-to-cargo conversion programs for aging narrow-body assets.
Commanding procurement scale: Airlines. Gaining share fastest: Freight Forwarders.
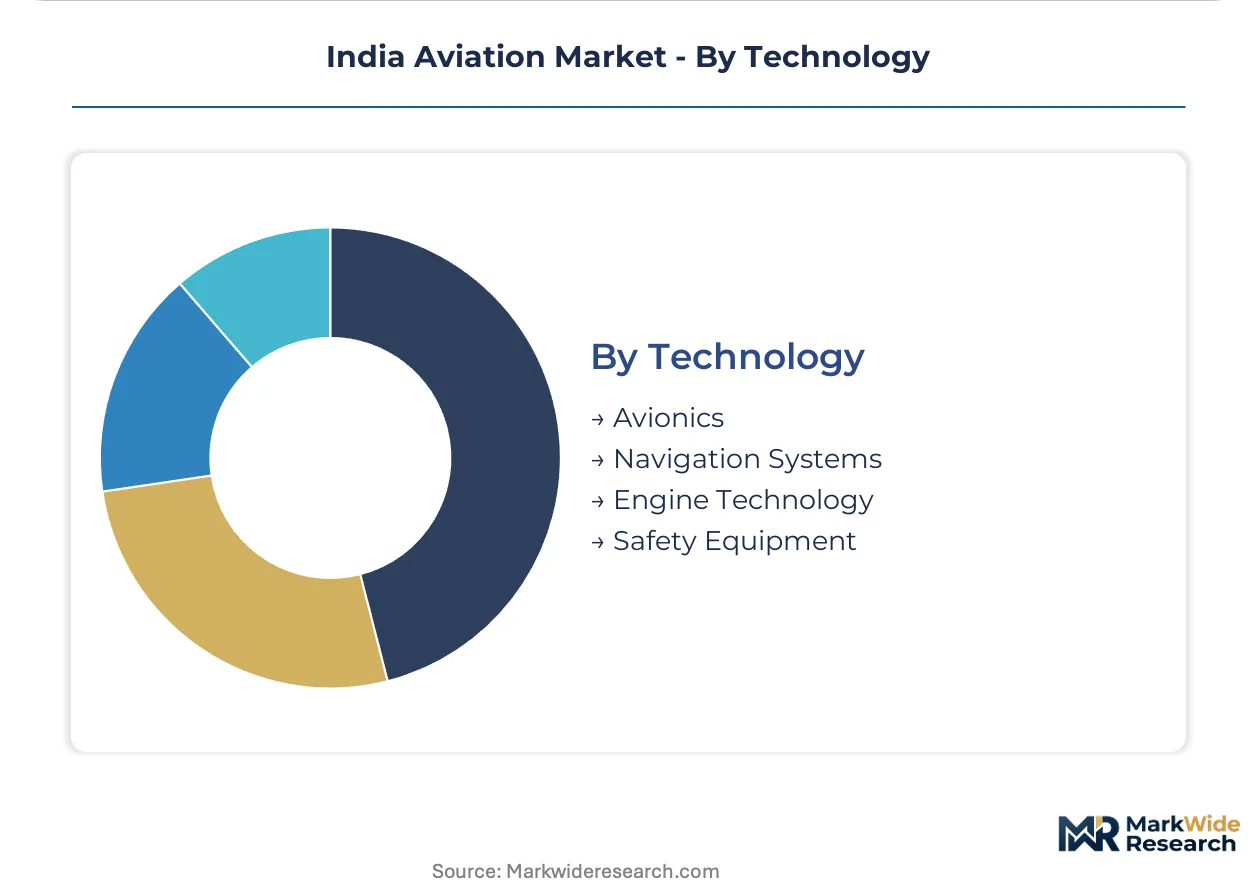
Technology:
Import dependency varies sharply across subsystems, with BIS certification timelines filtering avionics access while engine technology remains concentrated with foreign OEMs.
- Avionics:Flight management and communication systems face DGCA type certification delays that extend product launch windows for new technology introductions.
- Navigation Systems:GPS augmentation and ground-based precision approach infrastructure expansion concentrates in Maharashtra and Karnataka where airport modernization is most active.
- Engine Technology:Turbofan propulsion rated 20,000-90,000 pounds thrust remains import-dependent, with PLI schemes for specialty alloys targeting domestic manufacturing scale.
- Safety Equipment:Emergency evacuation systems and fire suppression hardware face Bureau of Civil Aviation Security screening mandates that shape compliance costs.
Most import-dependent: Engine Technology. Fastest localization progress: Avionics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Passenger traffic concentrates in Maharashtra and Karnataka where airport infrastructure expansion is most active, with tier-two cities emerging as the fastest-growing origin-destination pairs under UDAN subsidies.
Maharashtra
Mumbai's Chhatrapati Shivaji Maharaj International Airport handles the highest domestic passenger volumes, with slot constraints forcing frequency rationalization. The state's PLI scheme participation for aerospace components attracts specialty alloy manufacturers to the Pune industrial belt. Nagpur's cargo hub expansion captures e-commerce freight flows from central India distribution networks.
Karnataka
Bengaluru Kempegowda International Airport anchors south Indian aviation demand from technology sector corporate travel. DGCA mandates on sustainable aviation fuel blending impose steeper compliance costs on high-frequency trunk routes operating from this hub. The HAL manufacturing complex in Bangalore sustains defense and civilian helicopter production under Atmanirbhar Bharat directives.
Delhi-NCR
Indira Gandhi International Airport processes the highest passenger throughput nationally, with Bureau of Civil Aviation Security screening mandates shaping terminal modernization timelines. The region's pilot training academy concentration addresses DGCA-certified crew shortages constraining fleet expansion. Noida-Greater Noida corridor development targets MRO facility localization to capture margin pools flowing to Singapore.
Tamil Nadu
Chennai International Airport serves as the primary southern gateway for international narrow-body connections to Southeast Asia. The state's engineering workforce supplies avionics technicians to maintenance operations clustered around the airport zone. Coimbatore's tier-two airport expansion under UDAN frameworks stimulates manufacturing sector business travel demand.
Telangana
Rajiv Gandhi International Airport in Hyderabad ranks among the fastest-growing facilities by passenger volume, driven by pharmaceutical and IT corporate headquarters clusters. The state's drone corridor development under PLI scheme incentives positions Hyderabad for beyond-visual-line-of-sight logistics networks. Shamshabad aerotropolis planning integrates cargo terminals with e-commerce fulfillment infrastructure.
India Aviation Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with scheduled carriers commanding procurement scale unavailable to fragmented charter operators. The domestic passenger segment consolidates around single-airtype fleet strategists, while cargo conversion programs attract diversified asset owners. Three archetypes dominate: low-cost carriers with standardized narrow-body fleets, full-service operators balancing wide-body exposure, and state-supported aerospace manufacturers. Competitive moves center on fleet renewal cycles and airport concession bidding for ground handling exclusivity.
Within the carrier tier, IndiGo Airlines exemplifies the single-airtype cost discipline archetype through its A320 family concentration. Air India occupies a position bridging full-service international connectivity with domestic trunk route density. Hindustan Aeronautics Limited anchors the indigenous manufacturing vector under defense procurement frameworks with technology transfer requirements.
| Leading Market Players |
|---|
| IndiGo Airlines |
| Air India |
| Air India Express |
| SpiceJet |
| Akasa Air |
| Hindustan Aeronautics Limited (HAL) |
| Airbus SE |
| The Boeing Company |
| GMR Group |
| Others |
Value Chain & Pricing Dynamics
Composite material adoption in narrow-body fuselage construction simultaneously compresses unit manufacturing costs and concentrates supplier power among carbon fiber reinforced polymer specialists certified by DGCA airworthiness directives. This dual effect reshapes procurement negotiations as airlines balance fuel efficiency gains against long-term maintenance cost uncertainty from novel airframe technologies.
Pricing Analysis
Volume-driven low-cost carriers extract steep fleet discounts from Airbus and Boeing while full-service operators absorb premium pricing for wide-body customization and cabin configuration flexibility. Price differentiation hinges on delivery slot priority and engine selection tier, with fuel-efficient next-generation propulsion commanding material premiums. Cost compression in the narrow-body segment intensifies as IndiGo and Air India synchronize renewal cycles, though ground handling fees at Mumbai and Delhi slot-constrained facilities show pricing resilience due to regulatory licensing barriers. Charter operators exhibit highest price sensitivity given fragmented demand and limited bargaining scale against fixed airport concession costs.
Supply Chain Analysis
Single-source vulnerability sits with European and North American engine OEMs for turbofan propulsion rated 20,000-90,000 pounds thrust, with domestic carriers drawing from concentrated foreign manufacturing for core powerplant technology. Raw material dependencies include aerospace-grade aluminum alloys, carbon fiber prepregs, and specialty titanium components subject to Bureau of Civil Aviation Security import screening mandates. Tariff exposure on avionics imports filtered through BIS certification timelines creates procurement timeline risk for technology refresh cycles. Distribution runs through direct OEM-airline contracting for airframes, with tiered component sourcing via Maharashtra and Karnataka maintenance clusters for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pilot training pipeline constraints and DGCA-certified crew shortages prop pricing power for incumbent carriers despite aggressive fleet expansion, creating a supply-constrained market structure favoring established operators with captive training pipelines.
For Market Incumbents: Anchor fleet standardization advantages through deeper A320 or 737 family concentration, locking in maintenance protocol efficiencies and spare parts inventory optimization against emerging low-cost entrants with mixed-generation exposure. Defend slot portfolios at Mumbai and Delhi chokepoints through long-term airport concession renewals, while backward integration into pilot training academy capacity addresses licensed crew scarcity threatening operational scaling. For New Entrants and Emerging Players: Drone logistics corridors under evolving beyond-visual-line-of-sight regulations offer technology-first wedge opportunity with lighter regulatory burden and lower capital intensity than passenger operations. Target tier-two city cargo conversion programs for aging narrow-body assets, penetrating e-commerce freight forwarder demand with wet-lease operating models that sidestep aircraft ownership capital requirements. Position through MRO specialization in composite repair capabilities, where skilled technician scarcity inflates labor costs and creates service differentiation potential. For Investors and Strategic Acquirers: Exit pathways concentrate in regional ground handling concession acquisitions and maintenance facility roll-ups capturing margin pools flowing to Singapore and Dubai. Long-term viability favors assets with UDAN route subsidy exposure in tier-two cities, where infrastructure expansion lags demand growth and creates structural capacity premiums. Monitor DGCA sustainable aviation fuel blending mandate enforcement as inflection indicator for compliance cost restructuring and feedstock supply chain investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Airtype Fleet Standardization | IndiGo's A320 concentration sustains unit cost advantages through maintenance protocol simplification and pilot training efficiency. |
| Passenger-to-Freighter Conversion | E-commerce freight forwarder demand accelerates secondary revenue streams for aging narrow-body assets nearing retirement cycles. |
| MRO Localization Investment | Maharashtra and Karnataka maintenance clusters capture engine overhaul margin pools previously flowing to Singapore facilities. |
| UDAN Route Network Expansion | Government subsidy frameworks stimulate tier-two and tier-three city demand beyond trunk route saturation points. |
| Sustainable Aviation Fuel Supply Agreement | DGCA blending mandates force feedstock contract security with agricultural processors and waste oil aggregators. |
Study Parameters
Document review covered DGCA airworthiness directives, Bureau of Civil Aviation Security screening mandates, and PLI scheme documentation for aerospace components, complemented by interviews with airline fleet planning executives, MRO facility operations directors, airport concession managers, and aviation fuel procurement specialists. Secondary validation drew from customs import records for avionics and engine components, airport authority passenger throughput disclosures, and Ministry of Civil Aviation UDAN subsidy allocation data. Bottom-up aircraft delivery forecasts triangulated against top-down passenger traffic projections across the analysis window.
Installed base value outputs and fleet renewal cycle timing reflect segmentation by aircraft type, service function, end-user category, and technology subsystem across the modeling period. CAGRs derive from regression analysis of historical delivery patterns correlated with UDAN route expansion timelines and PLI incentive absorption rates. Industry-specific forecast inputs include turbine engine thrust rating demand distributions and composite airframe adoption curves by carrier segment.
Several conditions sit outside the modeled scope, including geopolitical disruption to engine OEM supply chains, abrupt DGCA regulatory revisions to pilot certification requirements, and sustained aviation turbine fuel price spikes beyond historical volatility bands. Deviation in sustainable aviation fuel blending mandate enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Galley Systems Market
Aircraft
Reusable Launch Vehicles Market
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Airship Market
Aircraft
Regional Jet Market
Aircraft
Freighter Aircraft Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Aviation Crew Management System Market
Aircraft
Middle-East and Africa Business Jet Market
Aircraft
Europe General Aviation Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Military Rotorcraft Market
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
Aircraft Exterior Mounts Market