
 Middle-East Aviation Market | 2026-2036
Middle-East Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East Aviation Market Outlook
The gap between premium long-haul services and low-cost regional operations is broadening across the Middle-East aviation sector. The Emirates Group leverages its Dubai hub dominance to sustain ultra-long-haul connectivity, while Qatar Airways Group Q.C.S.C. anchors Doha's position through oneworld alliance integration. Air Arabia PJSC competes aggressively on price, occupying the Sharjah-based low-cost tier that feeds secondary city pairs.
Middle-East aviation encompasses commercial air transport, cargo logistics, military aerospace, and business jet operations across a geographic zone stretching from Egypt to Iran, with aircraft typically configured for extreme heat performance exceeding standard ISA conditions. The commercial aircraft segment leads absolute seat capacity deployment, while cargo services capture disproportionate margin pools on Europe-Asia transshipment routes. Ground handling and maintenance services are growing fastest as third-party providers displace legacy airline-owned infrastructure at expanding airport clusters.
The General Authority of Civil Aviation in Saudi Arabia and the UAE's General Civil Aviation Authority jointly shape operational licensing, safety audits, and foreign carrier access rights across the Gulf. EASA and FAA bilateral recognition agreements determine airworthiness certification pathways for imported aircraft and component repairs. Stakeholders must monitor how open-skies negotiations between individual Gulf states and Asian economic partners reshape hub-and-spoke economics before committing to fleet or facility expansion decisions.
Market Dynamics
Vision 2030 tourism targets are compressing route authority timelines across Saudi Arabia, forcing carriers to accelerate fleet modernization before airport infrastructure at NEOM and the Red Sea Project reaches operational readiness. This regulatory velocity is colliding with extreme-heat engineering requirements that extend aircraft delivery cycles.
Growth Catalysts
- SFDA regulatory harmonization:The Saudi Food and Drug Authority's streamlined airworthiness certification pathways are reducing type-approval delays for imported commercial aircraft components.
- NEOM smart city aviation integration:Urban air mobility corridors and vertiport infrastructure are creating dedicated demand for electric vertical take-off and landing aircraft certification.
- Red Sea Project tourism flows:Luxury resort clusters are generating point-to-point charter demand that bypasses traditional hub-and-spoke routing through Dubai and Doha.
Market Restraints
- Jet fuel price volatility:Kerosene cost swings compress operating margins for long-haul carriers dependent on European and Asian connecting traffic.
- Airframe OEM concentration:Boeing and Airbus delivery slot scarcity extends fleet renewal timelines for Gulf carriers competing for production allocation.
- Extreme-heat performance limitations:ISA+30°C operational thresholds restrict payload capacity during summer months at Gulf hubs, forcing frequency reductions.
Strategic Opportunities
- Egypt secondary city connectivity:Alexandria and Sharm El-Sheikh remain underserved by direct long-haul services from Asian source markets.
- Sustainable aviation fuel mandates:The UAE's National Sustainable Aviation Fuel Roadmap creates offtake certainty for biofuel refinery investments.
- Blockchain cargo documentation:Distributed ledger systems are converging with IoT tracking to compress customs clearance times for perishable transshipments.
Industry Challenges
- Pilot training pipeline constraints:Flight school capacity in the Gulf lags carrier expansion plans, forcing reliance on expatriate crew with costly visa and housing burdens.
- Airport slot coordination complexity:IATA Level 3 slot constraints at Dubai International require precision scheduling that limits operational flexibility during disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East Aviation Market |
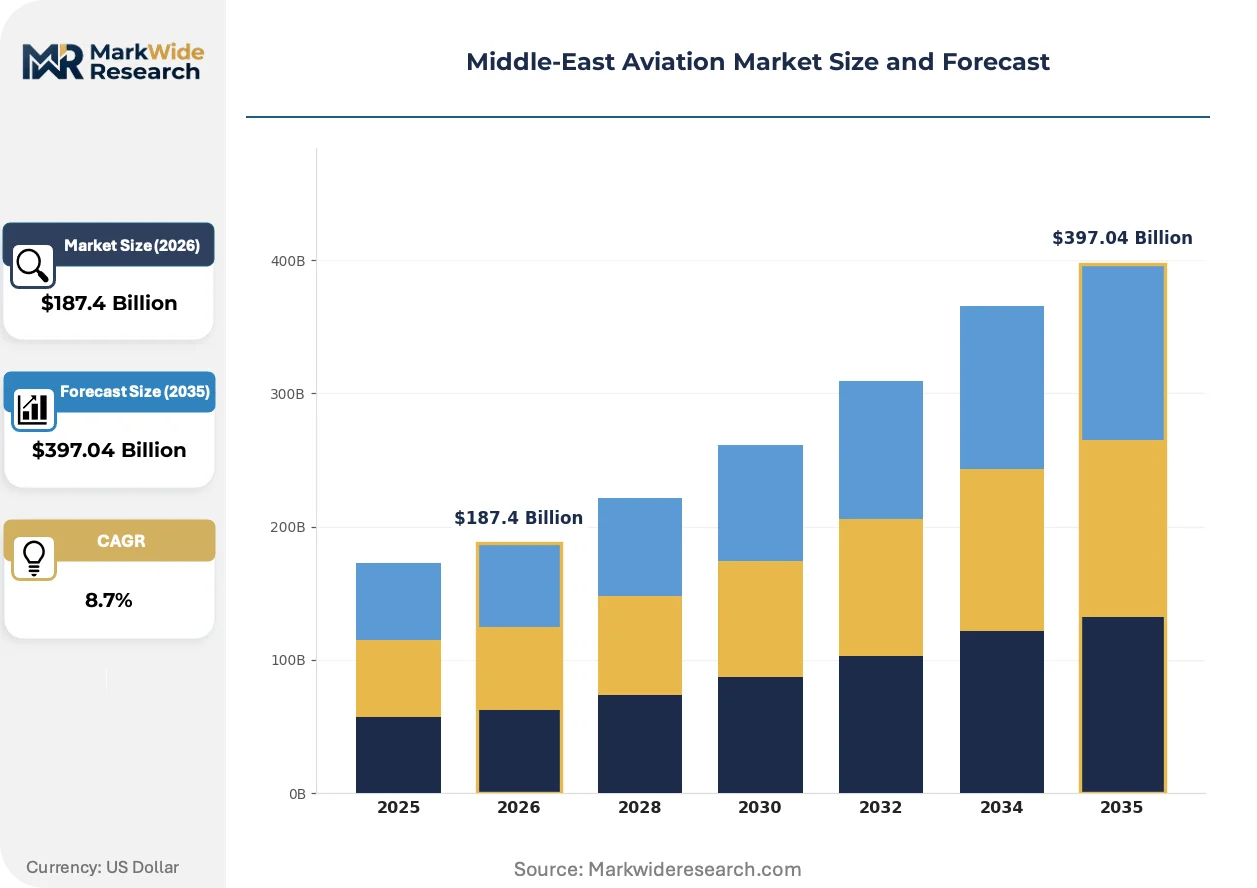
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Commercial, Cargo, Military, Business Service Type: Maintenance, Ground Handling, Flight Operations, Training End User: Airlines, Government, Private Owners, Charter Operators Technology: Avionics, Engine Systems, Navigation, Communication |
| Companies Covered | The Emirates Group, Qatar Airways Group Q.C.S.C., Air Arabia PJSC, Etihad Airways, Saudia, Gulf Air, Oman Air, flydubai, Airbus SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East Aviation Market Strategic Shifts
Aviation technology deployment across the Middle East is accelerating around sustainability mandates and digital infrastructure integration. Carriers are prioritizing solutions that reduce fuel burn while enabling real-time operational transparency for regulators and passengers.
Advanced engine architectures including geared turbofans and open-rotor prototypes are rewriting fuel efficiency benchmarks for routes exceeding 6,000 nautical miles. Emirates and Qatar Airways are embedding these powerplants into next-generation widebody orders. The structural consequence is a compression in per-seat operating costs that threatens older aircraft residual values.
The UAE's General Civil Aviation Authority has mandated automatic dependent surveillance-broadcast equipage across all commercial operators by 2026. This regulatory pressure is forcing avionics retrofits and fleet standardization investments. Narrow-body operators serving secondary GCC cities face the steepest compliance costs relative to fleet age.
Corporate travel procurement has fragmented from centralized global agreements toward property-level negotiations at Saudi hospitality developments. Individual resort complexes now source charter capacity directly rather than through legacy tour operators. This disintermediation is most visible along the Red Sea coastline where Giga-project developers operate captive aviation departments.
Middle-East Aviation Market Segmentation
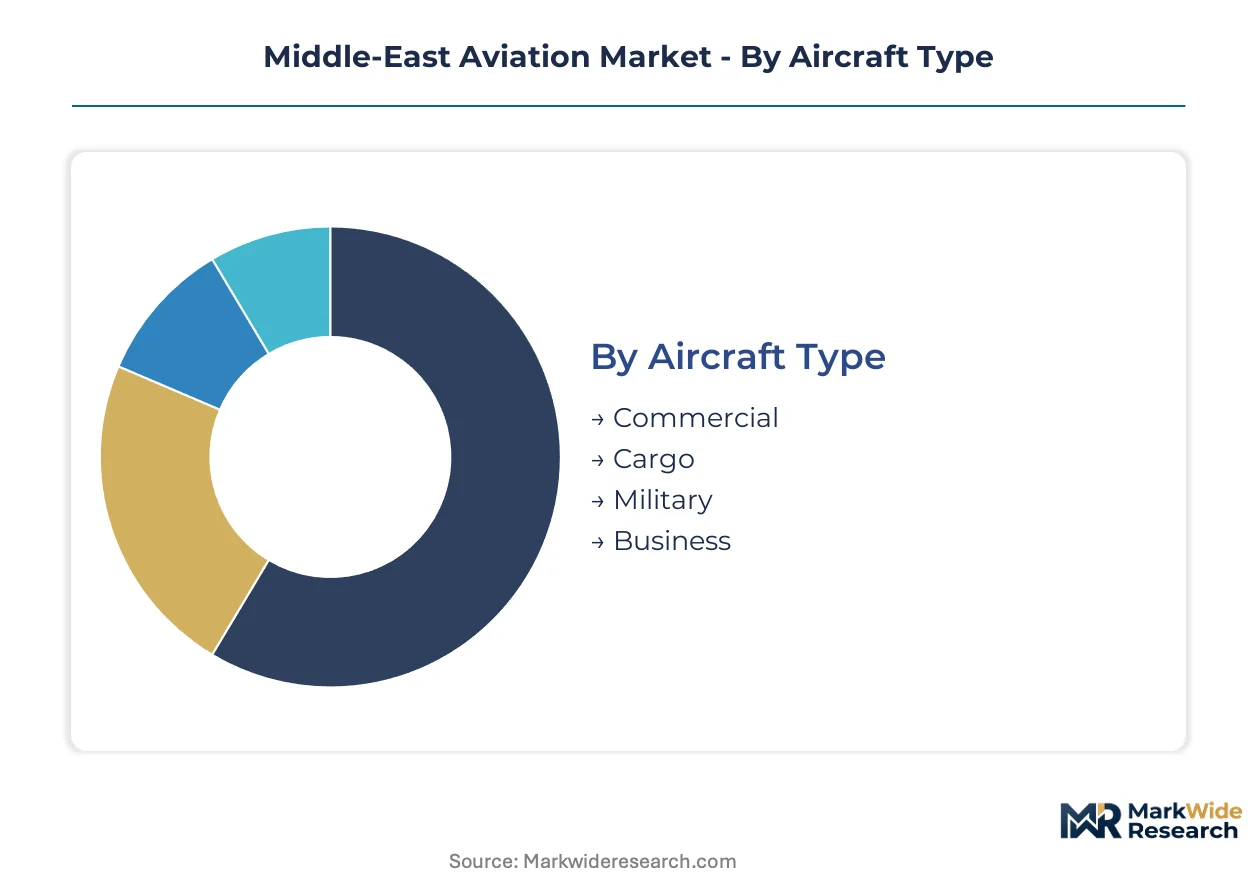
Aircraft configuration and service delivery models diverge sharply across Middle-East aviation, driven by extreme-heat operational requirements and hub-and-spoke economics. Fleet modernization cycles and regulatory mandates are compressing replacement timelines for legacy platforms across all four segmentation dimensions.
Aircraft Type:
Upgrade cycles for widebody platforms are accelerating as Gulf carriers pursue fuel efficiency gains on ultra-long-haul routes exceeding 6,000 nautical miles.
- Commercial:Twin-aisle aircraft dominate seat capacity deployment at Dubai and Doha hubs, configured for ISA+30°C performance thresholds that reduce payload during summer months. Emirates and Qatar Airways anchor demand for next-generation widebodies with geared turbofan architectures.
- Cargo:Dedicated freighter fleets capture disproportionate margin pools on Europe-Asia transshipment routes, with belly-hold capacity supplementing pure freighter operations at Gulf hubs. E-commerce flows from Asian manufacturing clusters drive freighter utilization rates above passenger-equivalent aircraft.
- Military:Fighter and transport platforms operate under national defense procurement frameworks separate from commercial aviation economics.
- Business:Long-range jets serve point-to-point charter demand from Red Sea Project luxury resorts, bypassing traditional hub connections.
Commercial aircraft sits at the top of the volume ranking, with cargo climbing the fastest as e-commerce transshipment expands.
Service Type:
Cost tier differentiation separates legacy airline-owned infrastructure from third-party providers competing on turnaround speed and regulatory compliance.
- Maintenance:Heavy checks and engine overhauls concentrate at Dubai and Doha facilities serving multinational carrier fleets, with SFDA harmonization reducing component approval delays for Saudi-registered aircraft.
- Ground Handling:Third-party providers displace legacy airline-owned operations at expanding airport clusters including NEOM and Red Sea Project terminals, competing on baggage system automation and fueling efficiency.
- Flight Operations:Dispatch and crew scheduling services face pilot training pipeline constraints across the Gulf, forcing reliance on expatriate crew with visa and housing cost burdens.
- Training:Flight school capacity lags carrier expansion plans, creating bottlenecks for type-rating certification on new-generation aircraft.
Ground handling is expanding most quickly as airport privatization accelerates, while maintenance retains the largest revenue pool.
End User:
Customer type fragmentation is reshaping procurement patterns, with centralized airline purchasing giving way to property-level negotiations at Saudi hospitality developments.
- Airlines:Full-service carriers in the Gulf Cooperation Council drive fleet renewal programs, while low-cost operators compete aggressively on secondary city pairs from Sharjah and secondary Saudi airports.
- Government:National aviation authorities including Saudi Arabia's General Authority of Civil Aviation and the UAE's General Civil Aviation Authority shape operational licensing and safety audit frameworks.
- Private Owners:Individual aircraft holdings concentrate in Dubai and Riyadh, serving executive travel demand from sovereign wealth and family office structures.
- Charter Operators:Resort complexes along the Red Sea coastline now source capacity directly rather than through legacy tour operators, operating captive aviation departments for guest transfers.
Airlines command the dominant volume position, with charter operators gaining share fastest as tourism project aviation departments mature.
Technology:
Application-driven procurement separates retrofits for regulatory compliance from greenfield installations on next-generation platforms.
- Avionics:Automatic dependent surveillance-broadcast equipage mandates from the UAE's General Civil Aviation Authority force retrofit investments across narrow-body fleets serving secondary GCC cities, with compliance deadlines compressing installation schedules.
- Engine Systems:Geared turbofan and open-rotor prototypes deliver fuel efficiency benchmarks for routes exceeding 6,000 nautical miles, embedding into Emirates and Qatar Airways widebody orders.
- Navigation:Precision approach systems support operations at expanding airport clusters where terrain and heat distortion challenge traditional instrument procedures.
- Communication:Satellite connectivity upgrades serve passenger connectivity expectations and real-time operational transparency requirements for regulators.
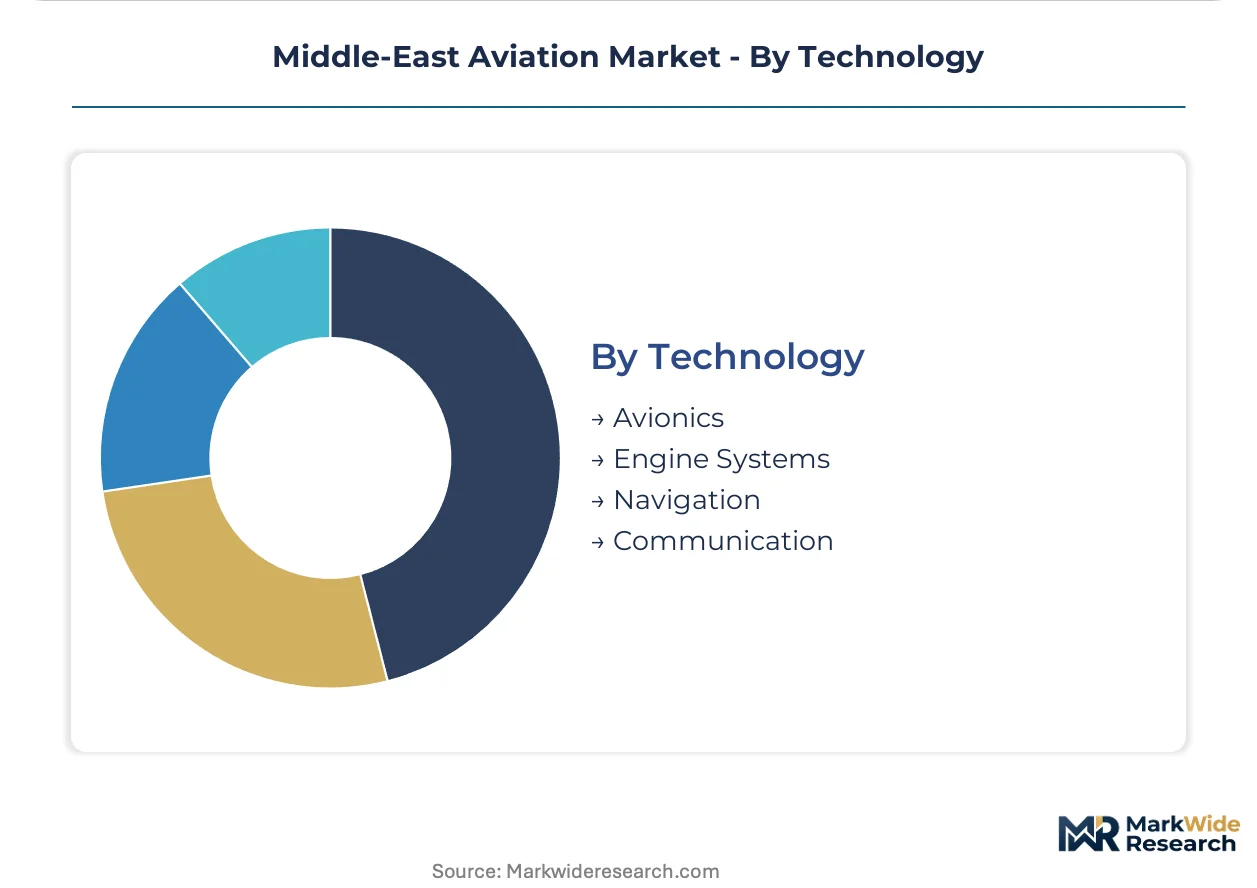
Engine systems lead technology segment volume, with avionics expanding most quickly under regulatory mandate pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilot training academies in the Gulf Cooperation Council states anchor workforce development for the broader Middle-East aviation sector, though expatriate crew dependence persists across Saudi Arabia, the UAE, Qatar, and Oman.
United Arab Emirates
Dubai International Airport's Level 3 slot constraints concentrate hub operations at Emirates and flydubai, while the General Civil Aviation Authority's ADS-B mandate compresses avionics retrofit timelines for narrow-body fleets. Al Maktoum International expansion and Dubai South aerotropolis development are absorbing maintenance and logistics investments away from the saturated DXB core.
Saudi Arabia
Vision 2030 tourism targets are accelerating fleet modernization ahead of NEOM and Red Sea Project airport readiness, with the General Authority of Civil Aviation reforming route authority allocations. Riyadh's King Khalid International and Jeddah's King Abdulaziz International are capturing domestic point-to-point growth as Saudia and flyadeal expand narrow-body networks.
Qatar
Hamad International's oneworld alliance integration anchors Qatar Airways' sixth-freedom traffic capture between Europe and Asia-Pacific, with the Qatar Civil Aviation Authority harmonizing safety audit frameworks with EASA bilateral recognition. Doha Free Zone clustering concentrates MRO and cargo logistics investments adjacent to the airport perimeter.
Oman
Muscat International's secondary hub positioning captures overflow traffic from Dubai and Doha during slot-constrained periods, with Oman Air's fleet renewal constrained by Boeing-Airbus delivery scarcity. The Public Authority for Civil Aviation is liberalizing fifth-freedom rights for cargo operators serving the Salalah transshipment corridor.
Middle-East Aviation Market Competitive Environment
Capital-heavy full-service carriers compete with asset-light low-cost operators across divergent network architectures. Market structure concentrates around three Gulf-based hub carriers with sixth-freedom dominance, while secondary flag carriers and hybrid operators fragment point-to-point segments. Strategic archetypes separate ultra-long-haul network builders from narrow-body price competitors and captive resort aviation departments. Dominant competitive moves include fleet renewal acceleration ahead of airport infrastructure completion and vertical integration into ground handling services at expanding airport clusters.
Within the full-service network carrier tier, The Emirates Group and Qatar Airways Group Q.C.S.C. exemplify hub-and-spoke architectures built on widebody fleet scale, while Air Arabia PJSC occupies the asset-light low-cost position anchored at Sharjah with secondary city pair specialization. These three entities collectively represent the spectrum from capital-intensive long-haul connectivity to price-driven regional fragmentation.
| Leading Market Players |
|---|
| The Emirates Group |
| Qatar Airways Group Q.C.S.C. |
| Air Arabia PJSC |
| Etihad Airways |
| Saudia |
| Gulf Air |
| Oman Air |
| flydubai |
| Airbus SE |
| Others |
Value Chain & Pricing Dynamics
Jet fuel procurement costs cascade through Middle-East aviation pricing tiers, with kerosene price volatility compressing margins at full-service carriers while low-cost operators offset exposure through unbundled ancillary revenue streams. The bundled premium service model at Emirates and Qatar Airways insulates against fuel spikes through long-haul yield premiums, whereas Air Arabia's unbundled structure transfers fuel risk directly to price-sensitive leisure travelers via dynamic seat pricing and baggage fees.
Pricing Analysis
The bundled-versus-unbundled service split defines competitive positioning across Gulf carriers. Three-tier pricing structure across premium, standard, and economy levels separates first-class long-haul suites from business flat-beds and dense economy cabins, with price differentiation driven by loyalty program tier and advance purchase windows. Pricing pressure stems from low-cost encroachment on secondary Saudi city pairs, where flyadeal and Air Arabia capture leisure demand with stripped-down base fares. Charter operators serving Red Sea Project resorts exhibit lowest price sensitivity due to captive guest transfer contracts, while independent leisure travelers booking through online travel agencies drive fiercest comparison shopping.
Supply Chain Analysis
Airframe OEM supply rests on Boeing's Everett and Charleston facilities plus Airbus's Toulouse and Hamburg assembly lines, with engine production concentrated at GE Aerospace's Cincinnati and Durham plants alongside Rolls-Royce's Derby and Singapore facilities. Titanium forgings from Russia's VSMPO-AVISMA and composite wing structures from Japan's Toray Industries feed final assembly, while avionics suites source from Honeywell's Phoenix and BAE Systems' Rochester operations. Single-source vulnerability concentrates in GE9X and Trent XWB powerplant allocations for next-generation widebodies. Distribution runs through direct OEM airline relationships for fleet orders, with spare parts flowing via Dubai's Jebel Ali Free Zone and Doha's Hamad International cargo terminals to regional MRO hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East aviation market functions as a stable compounder, with Vision 2030 tourism infrastructure spend providing durable demand visibility across the analysis window. Regulatory velocity around route authority allocations and airport privatization sustains investment momentum regardless of short-haul yield cycles.
For Market Incumbents: Extend fleet renewal timelines through sale-leaseback structures to preserve capital for NEOM and Red Sea Project slot pre-positioning. Deepen backward integration into ground handling services at expanding Saudi airport clusters to capture third-party provider margins. The threat of Air Arabia's price compression on domestic Saudi routes demands loyalty program enhancement and corporate contract lock-in at Riyadh and Jeddah.
For New Entrants and Emerging Players: Resort aviation departments along the Red Sea coastline represent an underserved buyer archetype with captive demand for point-to-point charter capacity. Secondary Egyptian markets including Alexandria and Sharm El-Sheikh offer white-space entry with limited direct Asian long-haul competition. A go-to-market angle targeting Giga-project developers with integrated flight operations and ground handling packages bypasses established tour operator intermediation.
For Investors and Strategic Acquirers: Consolidation pressure builds where third-party MRO providers face Boeing-Airbus delivery scarcity that extends airline fleet age and maintenance demand. Long-term viability favors asset-light charter operators with Red Sea Project contracts and technology-enabled ground handling platforms over capital-intensive full-service carriers. The signal to watch is NEOM airport operational readiness announcements, which will trigger route authority reallocation and hub capacity repricing across the Gulf.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Renewal Acceleration | Geared turbofan adoption at Emirates and Qatar Airways rewrites per-seat cost benchmarks on ultra-long-haul routes. |
| Ground Handling Privatization | Third-party providers displace legacy airline-owned infrastructure at NEOM and Red Sea Project terminals. |
| Avionics Retrofit Compliance | UAE GCAA ADS-B mandates force narrow-body fleet standardization investments ahead of 2026 deadlines. |
| Sustainable Aviation Fuel Offtake | UAE National SAF Roadmap creates refinery investment certainty for biofuel supply chain development. |
| Urban Air Mobility Integration | NEOM vertiport infrastructure generates dedicated eVTOL certification demand for electric aircraft manufacturers. |
Study Parameters
Direct dialogue with airline network planners, MRO facility managers, GACA regulatory officials, airport privatization advisors, and cargo logistics operators grounded qualitative insights across the Middle-East aviation ecosystem. Secondary validation drew from IATA traffic databases, ICAO safety audit reports, OEM order backlogs disclosed in SEC filings, and customs records of aircraft component imports into Saudi Arabia and the UAE. Bottom-up fleet deployment models triangulated against top-down tourism flow projections from Vision 2030 documentation.
Bottom-up modeling tracked individual aircraft configurations by seat count, utilization rates, and route distance bands, while top-down analysis calibrated against GACA and UAE GCAA passenger traffic statistics. Segmentation dimensions spanned aircraft type, service delivery model, end-user procurement pattern, and technology adoption phase. CAGRs derived from regression analysis of historical capacity growth against forward infrastructure investment announcements. Forecast inputs incorporated extreme-heat performance degradation factors and Boeing-Airbus delivery slot allocation timelines.
Underlying measurement precision varies by segment; commercial passenger traffic carries tighter precision than nascent urban air mobility corridors. Forecasts reflect assumptions around Vision 2030 project completion schedules and open-skies negotiation progress that could shift hub economics. Regulatory velocity around SFDA harmonization and EASA bilateral recognition warrants ongoing watch as certification pathway changes alter fleet import timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Galley Systems Market
Aircraft
General Aviation Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Global Electronic Flight Bag Market
Aircraft
Aircraft Leasing and Rental Market
Aircraft
Aeronautic Propeller Market
Aircraft
Water Bomber Market
Aircraft
Tandem Rotor Helicopter Market
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
UK Aviation Market
Aircraft
Air Starter Market
Aircraft
Aircraft Hangar Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Helicopter Wheels Market
Aircraft
Airplane Brackets Market