
 Asia-Pacific Aviation Market | 2026-2036
Asia-Pacific Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aviation Market Analysis
Capital-intensity divergence between full-service network carriers and ultra-low-cost operators is bifurcating competitive dynamics across the Asia-Pacific Aviation Market. Singapore Airlines leverages premium cabin configurations and hub connectivity to sustain yield premiums on long-haul trunk routes. VietJet anchors rapid fleet expansion through sale-and-leaseback structures, dominating price-sensitive short-haul markets. AirAsia competes on operational simplicity and high aircraft utilization, controlling cost per available seat kilometer through standardized narrowbody fleets.
Asia-Pacific aviation encompasses fixed-wing aircraft, rotary-wing helicopters, unmanned aerial vehicles, and unpowered gliders engineered to altitudes exceeding 40,000 feet with turbofan thrust ratings above 20,000 pounds for commercial jet transport. The sector's primary purpose remains high-velocity passenger and cargo movement across archipelagic and continental geographies where surface infrastructure proves inadequate. Aircraft product type captures the dominant share of capital deployment, while drone technology segments expand fastest from precision agriculture surveys in Australia's outback to last-mile delivery trials in Singapore's urban air mobility corridors. Civil aviation end users generate the majority of revenue passenger kilometers, though military procurement across the region deepens indigenous aerospace manufacturing capabilities.
Civil Aviation Administration of China enforces airworthiness directives aligned with ICAO standards, while Australia's Civil Aviation Safety Authority mandates fatigue management systems for extended twin-engine operations across the Tasman Sea. India's Directorate General of Civil Aviation recently tightened unmanned aircraft system certification requirements, constraining drone service market entry. Japan's MLIT coordinates slot allocation at Haneda and Narita, directly shaping network planning for All Nippon Airways and Japan Airlines. Stakeholders must monitor evolving carbon offset mandates from ASEAN member states and assess sustainable aviation fuel blending obligations before committing to fleet renewal timelines.
Market Dynamics
Fleet modernization pressure from China's dual carbon goals and Indonesia's archipelagic connectivity mandates is restructuring capital allocation across Asia-Pacific aviation, forcing carriers to balance narrowbody density against sustainable aviation fuel compatibility.
Growth Catalysts
- UDAN Regional Connectivity:India's subsidy-linked route auctions activate dormant airfields, extending turboprop networks into secondary cities previously dependent on surface transport.
- Dual Carbon Goals:China's MEE enforcement accelerates sustainable aviation fuel procurement mandates, redirecting refinery investment toward hydrotreated esters.
- Archipelagic Geography:Indonesia's 17,000-island topology generates inherent demand for short-haul fixed-wing and rotary services where maritime alternatives impose time penalties.
Market Restraints
- Jet Fuel Price Volatility:Singapore jet kerosene benchmarks expose carriers to crude-linked cost swings that compress margins on price-sensitive leisure routes.
- Slot Concentration:Tokyo Haneda and Singapore Changi gate scarcity limits network expansion for secondary carriers, entrenching hub dominance by established flag carriers.
- Airframe Supply Bottlenecks:Narrowbody delivery backlogs at Airbus and Boeing stretch fleet renewal timelines, forcing operators to extend aging aircraft utilization.
Strategic Opportunities
- Vietnam Coastal Tourism Belts:Da Nang-Phu Quoc corridor expansion supports dedicated leisure carrier positioning beyond legacy business-traffic dependence.
- Urban Air Mobility Corridors:Singapore's Marina Bay drone delivery trials and Melbourne's aerial taxi testbeds open electric vertical-takeoff entry points before regulatory harmonization.
- ASEAN Carbon Offset Mandates:Emerging compliance frameworks create first-mover advantages for carriers with verified sustainable aviation fuel supply chains.
Industry Challenges
- Pilot Training Pipeline:Simulator-hour requirements and type-rating costs strain crew supply as fleet expansion outpaces cadet program throughput across Southeast Asia.
- Airworthiness Certification Lag:India's DGCA unmanned aircraft system rule revisions delay commercial drone service launches, compressing operational windows for agricultural survey operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aviation Market |
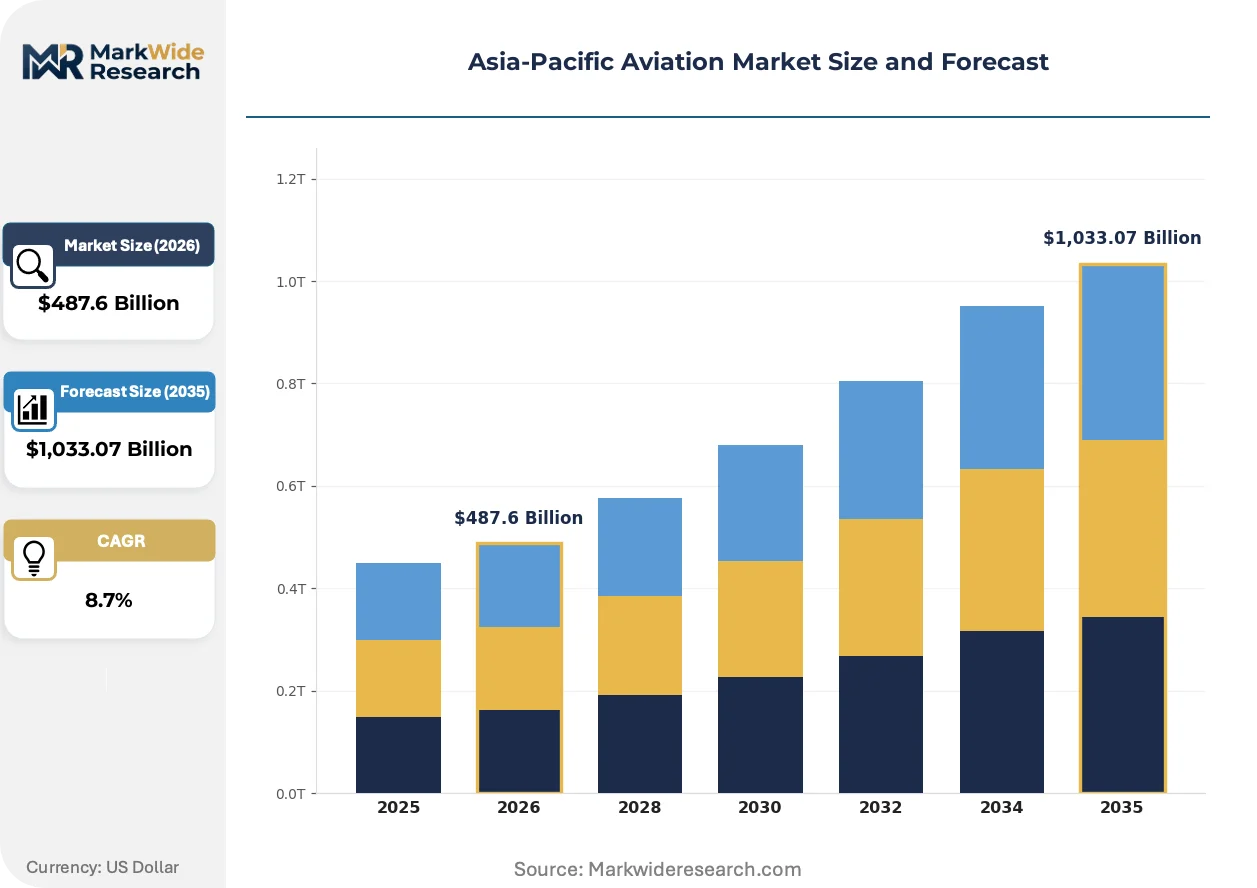
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,033.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aircraft, Helicopters, Drones, Gliders End User: Civil Aviation, Military, Cargo, Charter Service Type: Maintenance, Training, Repair, Inspection Technology: Fly-by-Wire, Avionics, Aerodynamics, Navigation |
| Companies Covered | AirAsia, VietJet, Singapore Airlines, Cebu Pacific Air, Lion Air, All Nippon Airways, Philippine Airlines, Air New Zealand, Japan Airlines, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aviation Market Emerging Trajectories
Sustainable propulsion architectures and digital airspace management systems are reconfiguring fleet economics and ground infrastructure investment priorities across the Asia-Pacific region.
Hybrid-electric propulsion development is bifurcating regional aircraft procurement strategies. MagniX and Collins Aerospace motor systems enable 30-50 seat turboprop replacements with battery-augmented thrust. Indonesian carriers evaluate these platforms for 200-nautical-mile inter-island hops where fuel logistics dominate operating costs. The technology is bifurcating fleet planning between hydrogen-ready narrowbodies and electric regional aircraft serving thin routes.
China's Civil Aviation Administration enforces airworthiness directives aligned with ICAO Annex 16 carbon standards, compelling domestic carriers to retrofit existing fleets with drag-reduction kits. The policy compresses residual values for pre-2020 airframes while accelerating lease returns. Southeast Asian lessors absorb these aircraft into secondary markets, extending operational lifecycles in jurisdictions with deferred compliance timelines.
Leisure travelers now book bundled ancillary products—seat selection, meal pre-order, and baggage—through mobile-native interfaces rather than traditional GDS channels. VietJet and AirAsia direct 60% of ancillary revenue through proprietary apps, disintermediating travel agents. This pattern concentrates in Vietnam and Thailand where smartphone penetration exceeds 85% and credit-card-linked wallets dominate payment flows.
Asia-Pacific Aviation Market Segmentation
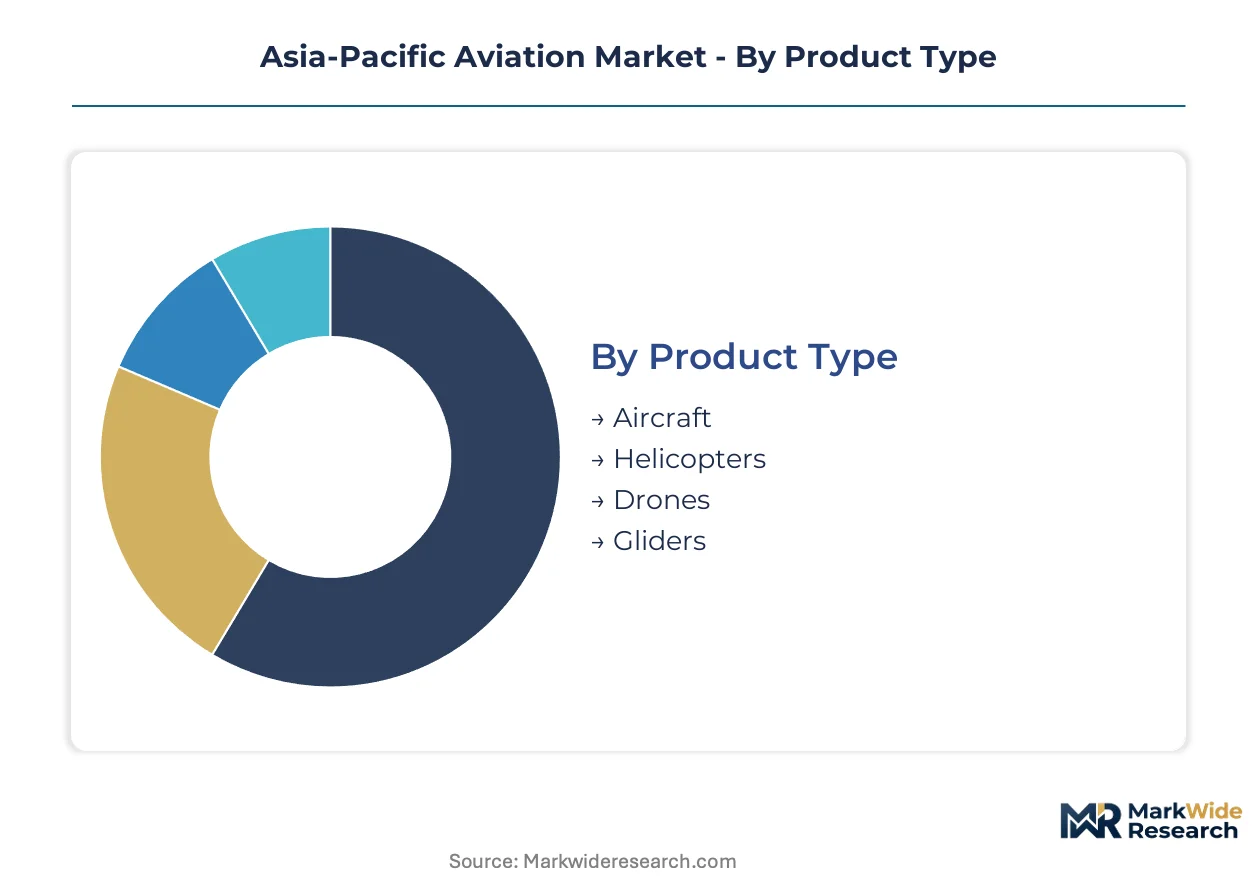
Segmentation across the Asia-Pacific Aviation Market reveals how capital allocation diverges between high-volume narrowbody deployment and emerging electric propulsion platforms. Procurement patterns in Indonesia's archipelagic corridors and Vietnam's coastal tourism belts reshape segment prioritization for fleet planners and lessors.
Product Type:
Fixed-wing platforms face substitution pressure from rotary and unmanned systems on routes below 300 nautical miles where surface infrastructure gaps persist.
- Aircraft:Turbofan-powered fixed-wing platforms dominate passenger and cargo movement across continental and archipelagic geographies, with narrowbody configurations capturing the majority of capital deployment from Indonesian and Vietnamese carriers expanding domestic networks.
- Helicopters:Rotary-wing systems serve offshore energy logistics and emergency medical evacuation across Australia's remote territories and Malaysia's Borneo oilfields, where runway construction proves economically unviable.
- Drones:Unmanned aerial vehicles expand fastest from Australia's agricultural surveys to Singapore's urban air mobility trials, constrained by India's DGCA certification revisions.
- Gliders:Unpowered recreational platforms occupy niche training and sport aviation segments with minimal commercial revenue contribution.
Aircraft anchors the volume base while drones gain share at the steepest rate.
End User:
Civil operators absorb the majority of new deliveries as military procurement deepens indigenous manufacturing capabilities across the region.
- Civil Aviation:Scheduled passenger carriers generate the dominant share of revenue passenger kilometers, with India's UDAN-subsidized regional routes and Indonesia's inter-island services driving turboprop demand.
- Military:Defense procurement from Australia's RAAF to Japan's Air Self-Defense Force accelerates local airframe assembly and avionics integration partnerships.
- Cargo:Dedicated freighter operations concentrate on China-ASEAN e-commerce corridors and perishable exports from Vietnam's Mekong Delta.
- Charter:On-demand services serve resource sector rotations and high-net-worth leisure travel across Papua New Guinea and the Philippines' resort archipelagos.
Civil aviation commands the largest fleet deployment while cargo expands most quickly on e-commerce lane growth.
Service Type:
Maintenance cost tiers separate flag carriers with captive MRO facilities from low-cost operators dependent on third-party providers.
- Maintenance:Line and base maintenance services concentrate at Singapore Changi and Kuala Lumpur's Subang aerospace clusters, capturing heavy check work from regional carriers.
- Training:Simulator-based type rating programs face capacity constraints as VietJet and AirAsia fleet expansion outpaces cadet throughput.
- Repair:Component overhaul services for landing gear and avionics cluster near OEM distribution hubs in Shanghai and Tokyo.
- Inspection:Regulatory-mandated airworthiness checks tighten for aging narrowbodies under China's MEE-aligned carbon enforcement.
Maintenance absorbs the greatest service expenditure while training faces the steepest capacity shortage.
Technology:
Avionics and navigation systems face rapid obsolescence pressure as China's Civil Aviation Administration aligns with ICAO Annex 16 standards.
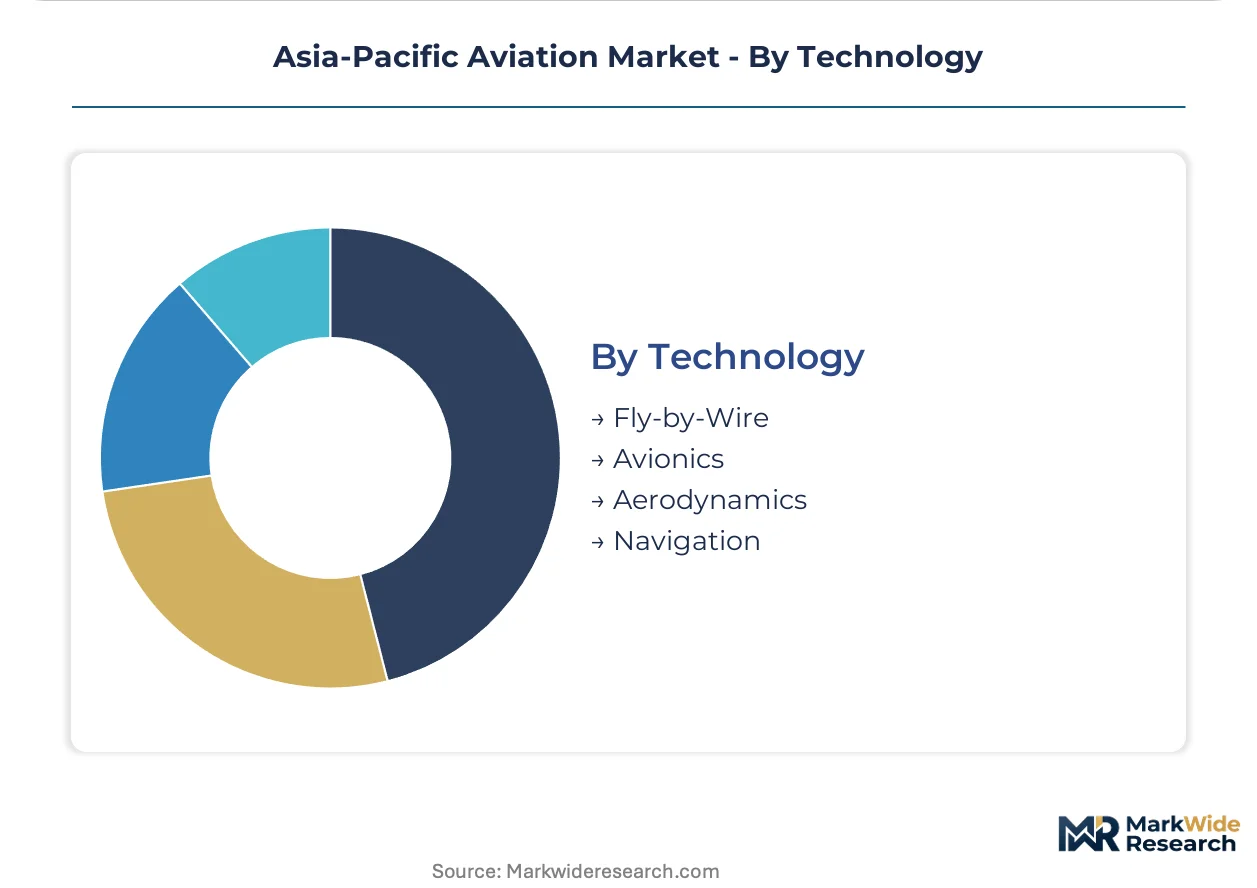
- Fly-by-Wire:Digital flight control architectures enable weight reduction and envelope protection, now standard on new narrowbody deliveries to AirAsia and Lion Air.
- Avionics:Integrated flight deck systems from Collins Aerospace and Honeywell dominate retrofit programs as Indonesia's carriers upgrade pre-2020 airframes.
- Aerodynamics:Drag-reduction kits and winglet retrofits compress residual values for non-compliant aircraft under China's dual carbon mandates.
- Navigation:GNSS augmentation and Required Navigation Performance approaches enable operations at secondary airports activated under India's UDAN scheme.
Avionics represents the largest technology investment category while aerodynamics retrofits climb fastest on regulatory compliance deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yield premiums at Singapore Changi diverge sharply from the price-sensitive corridors of Indonesia's domestic archipelago, creating a two-tier pricing architecture across the Asia-Pacific aviation market.
China
Beijing-Tianjin-Hebei and the Yangtze River Delta generate the majority of domestic revenue passenger kilometers as middle-class leisure travel accelerates. The Ministry of Ecology and Environment enforces dual carbon goals that redirect refinery investment toward sustainable aviation fuel production. Shanghai Pudong anchors international hub operations while Chengdu and Xi'an emerge as secondary long-haul departure points.
India
Maharashtra and Delhi-NCR concentrate premium business traffic, while Karnataka and Tamil Nadu feed IT corridor connectivity demand. The Directorate General of Civil Aviation administers UDAN regional route auctions that activate dormant airfields in secondary cities. Mumbai and Bangalore aerospace clusters host maintenance facilities serving narrowbody fleets expanding on trunk domestic routes.
Indonesia
Java-Bali and Sumatra corridors dominate archipelagic domestic volume as 17,000-island geography necessitates short-haul fixed-wing services. The national transportation ministry mandates fleet modernization timelines aligned with carbon reduction frameworks. Jakarta Soekarno-Hatta and Surabaya Juanda anchor hub-and-spoke networks feeding inter-island turboprop operations.
Vietnam
Da Nang-Phu Quoc coastal tourism belts drive dedicated leisure carrier positioning beyond legacy business-traffic dependence. The Civil Aviation Authority of Vietnam coordinates slot allocation at Tan Son Nhat and Noi Bai to accommodate low-cost carrier expansion. Ho Chi Minh City and Hanoi manufacturing zones supply component assemblies to regional aerospace supply chains.
Japan
Kanto and Kansai regions concentrate international premium cabin demand on long-haul trunk routes to North America and Europe. The Ministry of Land, Infrastructure, Transport and Tourism coordinates slot allocation at Haneda and Narita, directly shaping network planning for flag carriers. Nagoya Chubu and Osaka Kansai host maintenance, repair and overhaul clusters serving regional narrowbody fleets.
Asia-Pacific Aviation Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific aviation market. Full-service network carriers with captive premium cabin configurations consolidate yield on long-haul routes, while ultra-low-cost operators standardize narrowbody fleets to compress unit costs. Three strategic archetypes dominate: hub-dependent flag carriers leveraging slot scarcity, asset-light low-cost specialists exploiting sale-and-leaseback structures, and hybrid operators blending point-to-point density with selective long-haul deployment. Competitive moves center on fleet renewal acceleration and sustainable aviation fuel supply chain partnerships.
Within the ultra-low-cost tier, AirAsia and VietJet exemplify operational simplicity through standardized narrowbody utilization and high aircraft turnover. Singapore Airlines anchors the full-service archetype with premium cabin yield management on hub-dependent long-haul routes. Cebu Pacific Air occupies a hybrid position between these extremes, blending domestic density with selective international expansion from Philippine archipelagic corridors.
| Leading Market Players |
|---|
| AirAsia |
| VietJet |
| Singapore Airlines |
| Cebu Pacific Air |
| Lion Air |
| All Nippon Airways |
| Philippine Airlines |
| Air New Zealand |
| Japan Airlines |
| Others |
Supply Flow & Price Mechanics
Long-term sustainable aviation fuel offtake contracts lock in both supply access and price visibility for Asia-Pacific carriers navigating China's MEE enforcement and Indonesia's fleet modernization mandates. These structures transfer crude-linked volatility risk from jet fuel spot markets to fixed-price renewable feedstock agreements, reshaping procurement economics for narrowbody operators across the region.
Pricing Analysis
The customization-premium spread separates Singapore Airlines' configured premium cabin pricing from VietJet's standardized seat-only fares. Three-tier pricing structure across premium, standard, and economy levels dominates full-service yield management, while ultra-low-cost carriers compress differentiation to ancillary bundles alone. Pricing pressure stems from narrowbody delivery backlogs stretching fleet renewal timelines and forcing extended utilization of less fuel-efficient airframes. Price sensitivity concentrates in Indonesia's domestic leisure corridors, where AirAsia and Lion Air compete on base fare transparency; least sensitivity appears in Japan's Kanto-Kansai business routes where ANA and JAL sustain cabin premiums.
Supply Chain Analysis
Just-in-time inventory strategies dominate narrowbody component flows from Airbus and Boeing final assembly lines, while strategic stockpiling of sustainable aviation feedstocks emerges among Chinese refiners responding to dual carbon procurement mandates. Aerospace manufacturing concentrates in China, Japan, and South Korea for avionics and composite structures; engine final assembly centers on Singapore and Japan. Supply chains draw from titanium sponge processed in Japan, carbon fiber from South Korea, and avionics subsystems from China's eastern seaboard clusters. Single-source vulnerability runs through Pratt & Whitney and CFM International engine families powering the majority of regional narrowbody fleets. Distribution runs through Singapore Changi and Shanghai Pudong as consolidated logistics hubs serving Southeast Asian MRO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific aviation's competitive returns hinge on scarce type-rated flight crew supply and certified sustainable aviation fuel infrastructure, with fleet expansion timelines constrained by simulator capacity and hydrotreated ester refinery commissioning rather than capital availability alone.
For Market Incumbents: Compound hub dominance at slot-constrained airports through early renewal of widebody premium configurations before China's carbon enforcement compresses residual values for pre-2020 airframes. Deepen captive MRO capabilities at Singapore and Nagoya clusters to capture heavy check work from regional carriers facing pilot training pipeline bottlenecks. Defensive priority centers on sustainable aviation fuel supply chain partnerships that lock in offtake ahead of ASEAN carbon offset mandate harmonization. For New Entrants and Emerging Players: Lead with electric vertical-takeoff platform deployment in Singapore's Marina Bay and Melbourne's aerial taxi corridors before regulatory harmonization closes entry windows. Target Vietnam's Da Nang-Phu Quoc coastal tourism belt as the most penetrable leisure corridor, where dedicated carrier positioning can bypass legacy business-traffic dependence inherited by Vietnam Airlines. Go-to-market angle emphasizes mobile-native ancillary bundling that captures the 85% smartphone penetration in Thailand and Vietnam payment flows. For Investors and Strategic Acquirers: Capital is best deployed toward asset-light low-cost specialists with standardized narrowbody fleets and sale-and-leaseback expertise rather than hub-dependent flag carriers exposed to slot scarcity premiums. Long-term viability across the projection horizon favors operators with verified sustainable aviation fuel supply chains and digital distribution disintermediating traditional GDS channels. Acquisition target archetype: hybrid carriers blending domestic density with selective international expansion from archipelagic corridors. Signal to watch: Indonesia's DGCA unmanned aircraft system certification pace as inflection indicator for drone service market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Aviation Fuel Supply Agreement | Locks in hydrotreated ester procurement ahead of China's MEE enforcement deadlines. |
| Fleet Standardization Program | Reduces maintenance complexity for AirAsia and VietJet sale-and-leaseback structures. |
| Simulator Training Capacity Expansion | Addresses pilot pipeline constraints as Indonesia's archipelagic routes activate dormant airfields. |
| Mobile-Native Distribution Platform | Captures ancillary revenue flows disintermediating traditional GDS channels in Vietnam. |
| Urban Air Mobility Corridor Partnership | Positions electric vertical-takeoff entry before Singapore's regulatory harmonization solidifies. |
Methodological Framework
A standing panel of fleet planning executives, MRO operations directors, sustainable aviation fuel procurement leads, and Civil Aviation Administration regulators provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation from ICAO Annex 16 filings, IATA fuel price monitoring data, ASEAN member state carbon policy disclosures, and OEM delivery backlog reports. Bottom-up triangulation across narrowbody operator financial disclosures and top-down reconciliation against regional jet fuel consumption aggregates anchored volume estimates.
Consistency checks validated model outputs against external benchmarks including IATA passenger traffic forecasts and ICAO carbon standard implementation timelines. The analytical framework segmented across aircraft product type, civil-military-cargo end user classification, maintenance-training-repair service tiers, and fly-by-wire through navigation technology layers, with fleet age and sustainable fuel compatibility as aviation-specific dimensions. CAGRs derived from fitted trend lines across disclosed fleet expansion plans and refinery investment announcements, with carbon enforcement stringency and slot allocation policy as scenario-weighted inputs.
Underlying assumptions cover China's dual carbon goal enforcement trajectory, Indonesia's archipelagic connectivity mandate funding continuity, and narrowbody delivery schedule recovery, with deviation risk concentrated in jet fuel price volatility and pilot training pipeline throughput. Revision becomes warranted when sustainable aviation fuel blending obligation thresholds or unmanned aircraft system certification timelines cross material implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Europe Aircraft Engines Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
Aircraft Seals Market
Aircraft
Air Speed Indicator Market
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
Docking System Market
Aircraft
Electric VTOL (Evtol) Aircraft Market
Aircraft
Strategic Bomber Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
United States Aerospace and Defense Market
Aircraft
Anti Rolling Gyro (ARG) Market
Aircraft
General Aviation Market
Aircraft
Middle East and Africa Military Helicopters Market
Aircraft
Tanker Aircraft Market
Aircraft
Tandem Rotor Helicopter Market