
 Commercial Aircraft Aerostructures Market | 2026-2036
Commercial Aircraft Aerostructures Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Aerostructures Market Outlook
Composite-intensive wing fabrication is fragmenting traditional aluminum-dominant supply chains across the aerostructures value chain. Airbus SE leverages its European fabrication network to sustain composite wing leadership on the A350 program. Spirit AeroSystems anchors North American narrow-body fuselage production through its Wichita manufacturing complex. GKN Aerospace differentiates via thermoplastic composite expertise and specialized engine nacelle structures.
Commercial aircraft aerostructures encompass the primary load-bearing and aerodynamic assemblies—wings, fuselages, empennages, and control surfaces—typically manufactured from aluminum alloys, carbon fiber reinforced polymer, or titanium alloys through processes including automated fiber placement, resin transfer molding, and high-speed machining to achieve specified strength-to-weight ratios and fatigue life thresholds. These assemblies constitute the fundamental airframe architecture that generates lift, houses payloads, and maintains flight control across commercial aviation operations. Wings and fuselages capture the dominant share of OEM procurement value given their scale and systems integration complexity, while carbon fiber reinforced polymer segments outpace aluminum alloy growth due to fuel efficiency mandates driving lightweighting priorities. Empennages represent a concentrated margin pool where specialized thermoplastic expertise commands premium positioning among tier-1 suppliers.
FAA airworthiness standards, EASA CS-25 certification requirements, and China's CAAC type validation protocols collectively dictate material qualification timelines, structural test regimes, and supplier approval thresholds for aerostructure manufacturers seeking multi-jurisdiction market access. REACH chemical restrictions and evolving EU Green Deal industrial emissions frameworks compound compliance burdens for European-based fabrication facilities and their coating, bonding, and surface treatment processes. Stakeholders must monitor CAAC's accelerating indigenous certification autonomy and its implications for Western supplier participation in China's COMAC programs.
Market Dynamics
Composite wing fabrication is compressing qualification timelines and forcing aluminum-centric suppliers to rebuild process certifications around automated fiber placement and resin transfer molding capabilities. FAA and EASA material traceability mandates now require lot-level documentation across tier-2 and tier-3 suppliers, fundamentally restructuring subcontractor relationships.
Growth Catalysts
- CS-25 Amendment 25-146:EASA's updated damage tolerance requirements for composite primary structures accelerate thermoplastic adoption rates in empennage assemblies as manufacturers seek reduced inspection intervals.
- Narrow-body production surge:Boeing 737 MAX and Airbus A320 family output rates above 50 units monthly sustain demand for aluminum fuselage panels and subassemblies across Wichita and Toulouse supply clusters.
- Automated fiber placement:AFP robotics integration cuts layup labor hours by half while improving fiber alignment precision, enabling thicker monolithic wing skins without autoclave size constraints.
Market Restraints
- Titanium sponge volatility:Russian and Ukrainian feedstock disruptions since 2022 have compressed Western mill product availability, forcing long-term offtake commitments at inflated carrying costs.
- Prepreg freezer capacity:Cold storage infrastructure deficits in Southeast Asian fabrication clusters limit carbon fiber composite throughput despite labor cost advantages.
- Aluminum-lithium substitution ceiling:Third-generation Al-Li alloys hit fatigue performance limits at wing root joints, blocking further density reduction in high-load primary structures.
Strategic Opportunities
- India's PLI scheme for aerospace:The production-linked incentive framework for airframe components offers 15-year tax holidays for greenfield facilities in Gujarat and Karnataka manufacturing zones.
- Out-of-autoclave curing:Electron beam and microwave curing technologies eliminate autoclave bottlenecks, enabling distributed fabrication nodes closer to final assembly lines.
- Digital thread certification:Model-based definition workflows permit virtual structural testing, compressing FAA certification timelines from 18 months to under 8 months for derivative designs.
Industry Challenges
- Composite repair technician scarcity:BVID (barely visible impact damage) assessment and scarf repair skills require 2,000-hour certification programs with limited training infrastructure outside Wichita, Toulouse, and Hamburg.
- Dual qualification burden:Suppliers seeking COMAC C919 and ARJ21 participation must maintain parallel CAAC and FAA/EASA quality systems, doubling audit overhead without guaranteed volume.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Aerostructures Market |
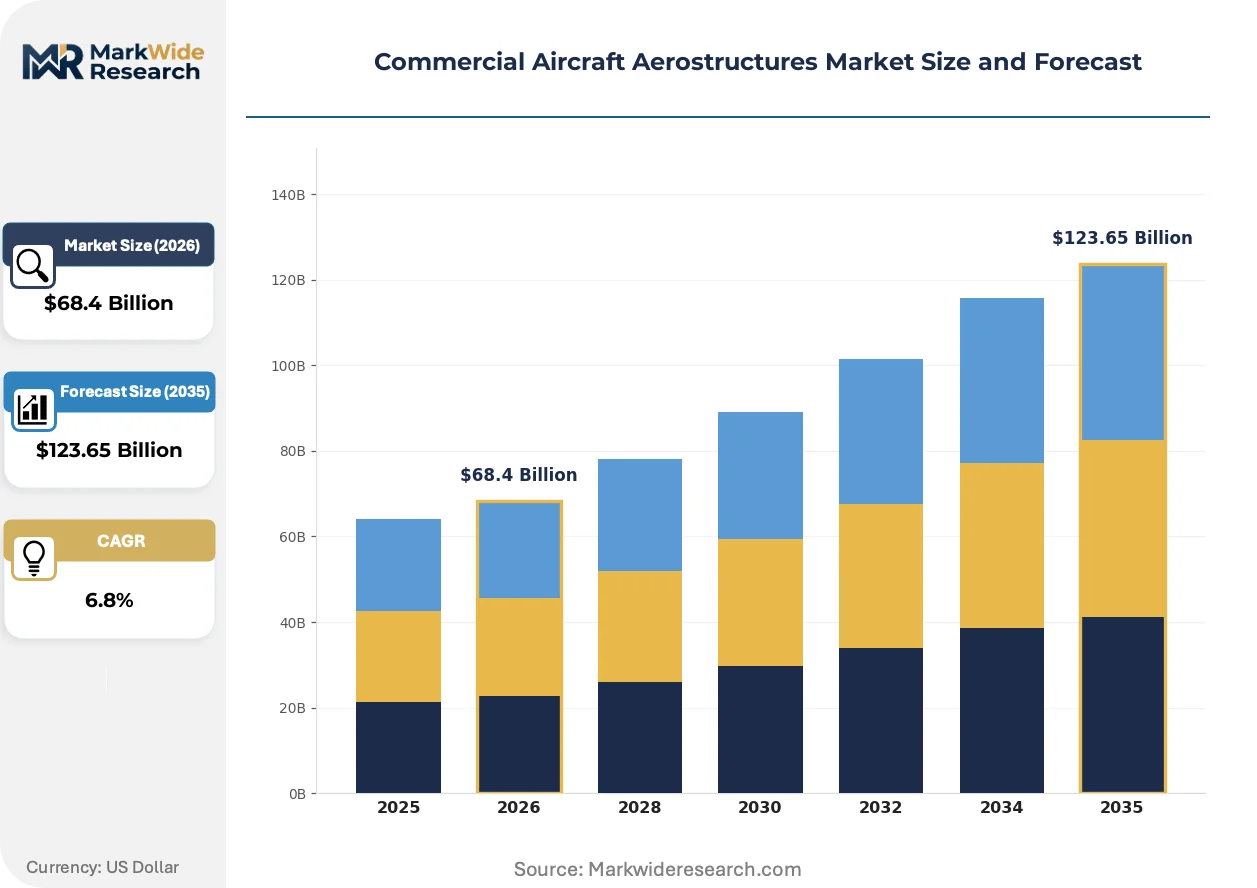
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wings, Fuselages, Empennages, Aerodynamic Surfaces Material: Aluminum Alloys, Carbon Fiber Reinforced Polymer, Titanium Alloys, Steel Alloys End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Maintenance Repair Overhaul Manufacturing Stage: Pre-production, Assembly, Fabrication, Testing |
| Companies Covered | Airbus SE, Magellan Aerospace, FACC AG, Collins Aerospace, Spirit AeroSystems, Elbit Systems Ltd., Singapore Technologies Engineering Ltd., GKN Aerospace, RUAG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Aerostructures Market Strategic Shifts
Digital engineering workflows are collapsing the traditional design-build-test cycle, compressing development timelines while multiplying the data infrastructure burden on tier-1 suppliers. Three convergent developments are restructuring competitive positioning across the aerostructures value chain.
Digital twin architectures are virtualizing physical structural test programs, allowing Airbus and Boeing to simulate fatigue life and damage progression across thousands of load cycles before first article fabrication. Tier-1 suppliers including Spirit AeroSystems and GKN Aerospace now embed sensor networks into production wings to feed operational data back into design models. This virtualization is compressing certification documentation from millions of physical test hours to validated simulation portfolios, though regulator acceptance remains uneven across jurisdictions.
REACH Annex XIV authorization requirements for chromium trioxide in surface treatment processes are forcing European suppliers to convert cadmium and hexavalent chromium plating lines to trivalent alternatives or plasma electrolytic oxidation. The 2024 sunset date for aerospace exemptions has triggered capital deployment into new coating infrastructure at Safran and Leonardo facilities. Suppliers without conversion capabilities face supply exclusion from EU-based OEM final assembly lines regardless of technical performance.
Airline procurement departments are consolidating aerostructure sourcing decisions at the platform level rather than component-by-component, favoring risk-sharing partners willing to assume design authority and aftermarket liability. This concentration is displacing traditional build-to-print subcontractors who lack integrated stress analysis capabilities. The shift is most visible in Southeast Asian markets where low-cost carriers now mandate 15-year total cost of ownership guarantees from wing and fuselage suppliers.
Commercial Aircraft Aerostructures Market Segmentation
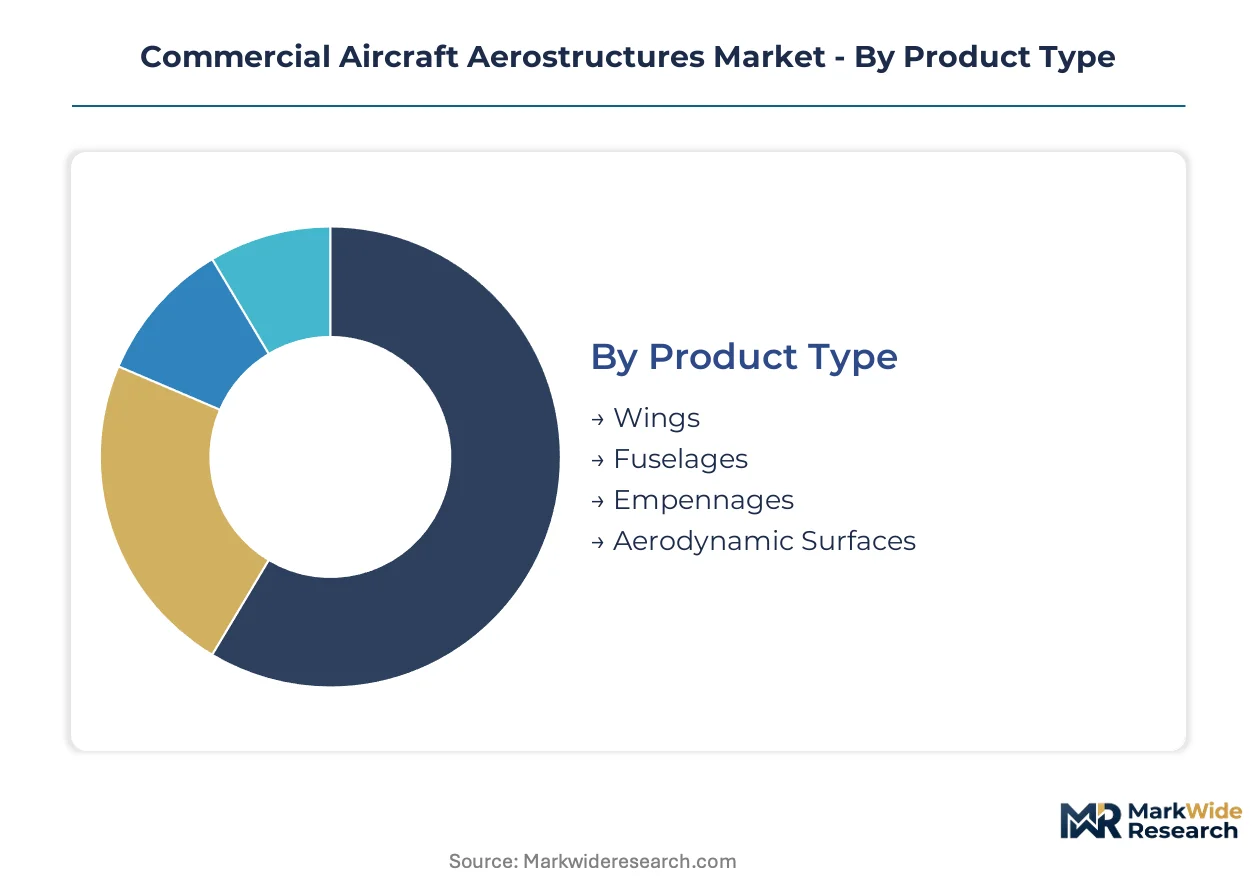
Aerostructure procurement patterns diverge sharply across product architectures and material classes. OEM sourcing strategies and regulatory qualification burdens reshape segment priorities across the value chain.
Product Type:
Mature fuselage and wing assemblies anchor procurement volumes, while empennage and aerodynamic surface segments emerge as margin concentration points.
- Wings:Composite-intensive primary structures integrating spars, ribs, and skins through automated fiber placement. Boeing 737 MAX and Airbus A320 programs in Wichita and Toulouse clusters drive aluminum wing box demand alongside carbon fiber outboard panels.
- Fuselages:Cylindrical pressure vessels and crown sections manufactured via high-speed machining and automated riveting. Spirit AeroSystems' Wichita complex processes aluminum fuselage barrels for narrow-body programs at sustained rates above 50 units monthly.
- Empennages:Thermoplastic composite tail assemblies commanding premium positioning through damage tolerance certification advantages under EASA CS-25 Amendment 25-146.
- Aerodynamic Surfaces:Flaps, slats, and spoilers requiring precise contour tolerances for laminar flow optimization.
Fuselages handle the majority of throughput; empennages are the fastest mover on share.
Material:
Cost tier stratification separates legacy aluminum systems from advanced polymer matrix alternatives, with titanium occupying a constrained premium niche.
- Aluminum Alloys:Third-generation Al-Li alloys deployed in wing root joints and fuselage frames where fatigue performance thresholds limit further density reduction. Narrow-body production surges sustain demand across North American and European fabrication networks.
- Carbon Fiber Reinforced Polymer:Toray T800H and Hexcel IM7 prepreg systems enabling monolithic wing skins without autoclave size constraints. Cold storage infrastructure deficits in Southeast Asian clusters constrain throughput despite labor cost advantages.
- Titanium Alloys:Mill products from Russian and Ukrainian feedstock sources face compressed Western availability, forcing long-term offtake commitments at elevated carrying costs.
- Steel Alloys:Landing gear attachment fittings and engine mount structures requiring ultra-high strength-to-weight ratios.
Aluminum alloys handle the majority of throughput; carbon fiber reinforced polymer is expanding most quickly on share.
End User:
Customer type determines design authority allocation and liability exposure across the procurement hierarchy.
- OEMs:Boeing and Airbus retain final assembly integration and type certification accountability, consolidating sourcing decisions at platform level rather than component-by-component.
- Tier-1 Suppliers:Risk-sharing partners assuming design authority and aftermarket liability, displacing traditional build-to-print subcontractors lacking integrated stress analysis capabilities.
- Aftermarket Providers:Barely visible impact damage assessment and scarf repair services requiring 2,000-hour technician certification programs with limited training infrastructure outside Wichita, Toulouse, and Hamburg.
- Maintenance Repair Overhaul:Line maintenance and heavy check facilities managing scheduled inspections and composite panel replacements.
Tier-1 suppliers handle the majority of throughput; aftermarket providers are climbing the fastest on share.
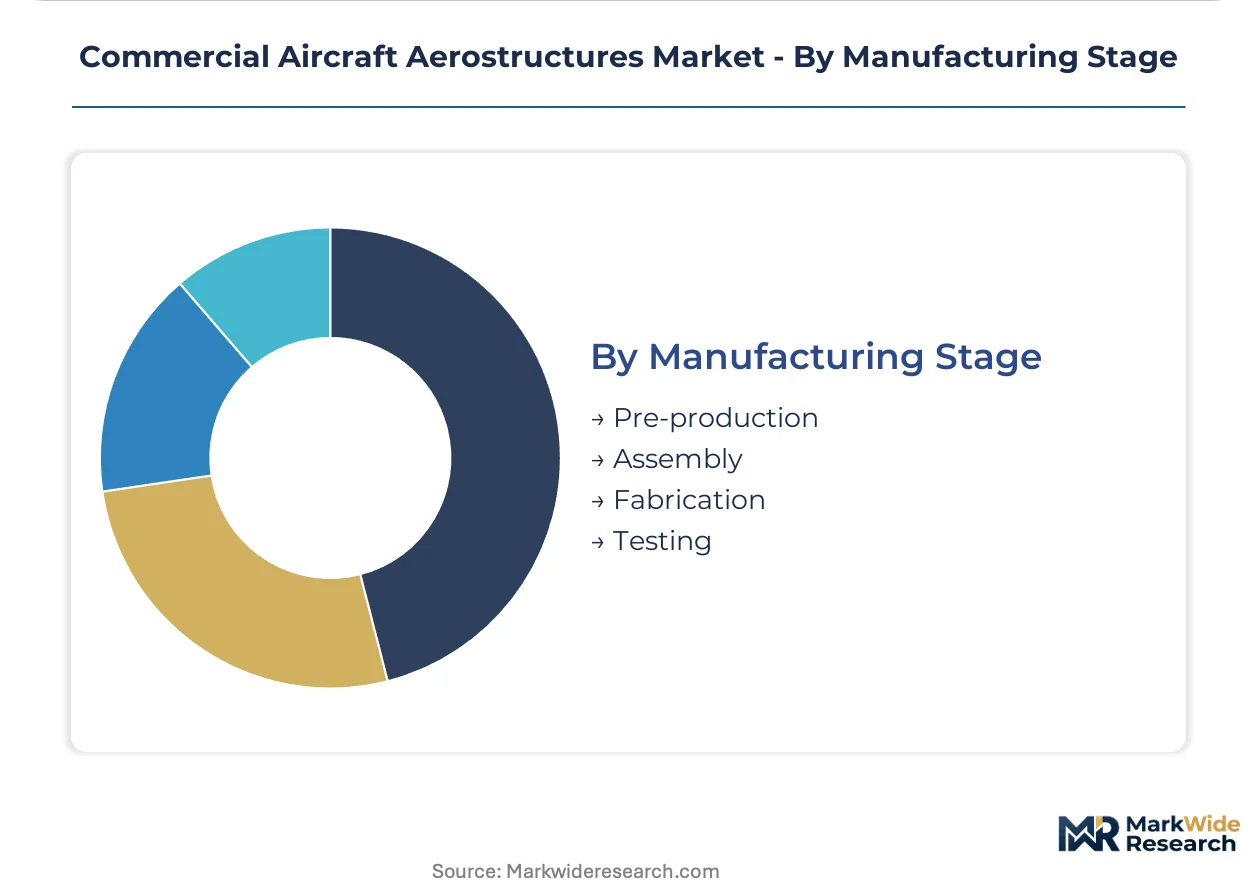
Manufacturing Stage:
Process maturity separates pre-qualified fabrication workflows from emerging out-of-autoclave curing technologies.
- Pre-production:Tooling design and first article qualification consuming 18-month FAA certification timelines for derivative designs, compressible to under 8 months through model-based definition workflows.
- Assembly:Fuselage join and wing-to-body attachment operations requiring precision alignment jigs and automated drilling systems.
- Fabrication:Automated fiber placement robotics cutting layup labor hours by half while improving fiber alignment precision for thicker monolithic structures.
- Testing:Digital twin architectures virtualizing fatigue life simulation across thousands of load cycles before physical first article fabrication.
Fabrication handles the majority of throughput; testing is gaining share fastest through virtualization adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France exports composite wing assemblies to Airbus final assembly lines in Germany and China, while the United States ships aluminum fuselage structures to Boeing's Renton and Charleston facilities.
United States
Boeing 737 MAX production rates above 50 units monthly sustain demand for aluminum fuselage panels and wing subassemblies. FAA airworthiness directives tighten material traceability requirements across tier-2 and tier-3 suppliers. Wichita, Kansas anchors North American narrow-body fuselage fabrication through Spirit AeroSystems' manufacturing complex.
France
Airbus A320 and A350 programs drive composite-intensive wing production for European and export markets. EASA CS-25 Amendment 25-146 accelerates thermoplastic adoption in empennage assemblies. Toulouse hosts the continent's dominant aerostructure design authority and final assembly integration hub.
Germany
Automated fiber placement robotics integration cuts layup labor hours while improving fiber alignment precision for monolithic wing skins. REACH Annex XIV chemical restrictions force conversion of cadmium and hexavalent chromium plating lines at supplier facilities. Hamburg concentrates A320 family fuselage join operations and composite repair certification programs.
China
COMAC C919 and ARJ21 programs expand indigenous supply chain capacity for wing boxes and empennage assemblies. CAAC type validation protocols require parallel quality system maintenance for Western supplier participation. Shanghai and Xi'an fabrication clusters scale carbon fiber composite throughput despite cold storage infrastructure deficits.
Singapore
Maintenance repair overhaul demand for barely visible impact damage assessment and scarf repair services climbs with regional fleet expansion. The country's national aviation regulator aligns certification standards with FAA and EASA frameworks. Seletar Aerospace Park concentrates composite panel replacement and heavy check facilities for Southeast Asian operators.
Commercial Aircraft Aerostructures Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply positions. Airbus SE and Boeing retain final assembly integration and type certification accountability, consolidating sourcing decisions at platform level. Three archetypes dominate: risk-sharing partners assuming design authority, build-to-print fabricators lacking integrated stress analysis, and aftermarket repair specialists with scarce technician certifications. M&A activity concentrates among tier-1 suppliers seeking expanded design authority, while strategic partnerships proliferate around out-of-autoclave curing technology licensing.
Among European-based risk-sharing partners, Airbus SE and GKN Aerospace occupy positions exemplifying composite wing leadership and thermoplastic empennage specialization respectively. Spirit AeroSystems anchors North American narrow-body fuselage production archetypes through its Wichita manufacturing concentration. These three entities represent the dominant competitive positioning vectors: European composite design authority, specialized thermoplastic expertise, and high-volume aluminum fabrication scale.
| Leading Market Players |
|---|
| Airbus SE |
| Magellan Aerospace |
| FACC AG |
| Collins Aerospace |
| Spirit AeroSystems |
| Elbit Systems Ltd. |
| Singapore Technologies Engineering Ltd. |
| GKN Aerospace |
| RUAG Group |
| Others |
Value Chain & Pricing Dynamics
Trans-Atlantic air freight corridors linking Wichita to Toulouse transmit titanium sponge and carbon fiber prepreg cost volatility directly into tier-1 supplier pricing power, compressing margins at build-to-print subcontractors while concentrating margin capture among risk-sharing partners with design authority.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange aluminum pricing and Toray prepreg spot rates dominate tier-1 procurement, with price differentiation driven by EASA CS-25 certification tier and automated fiber placement capability depth. Pricing pressure intensifies in aluminum fuselage segments as Boeing 737 MAX output rates strain Wichita capacity, while carbon fiber wing assemblies command stability through scarcity of qualified AFP robotics operators. Low-cost Southeast Asian fabrication clusters exhibit highest price sensitivity due to cold storage infrastructure deficits constraining throughput.
Supply Chain Analysis
Export control regimes restricting automated fiber placement machine tool exports to Chinese fabrication clusters fragment global composite wing supply, concentrating advanced thermoplastic capability in France, Germany, and the United States. Raw material flows draw from Russian and Ukrainian titanium sponge sources, Japanese carbon fiber precursors, and Australian bauxite alumina. Single-source vulnerability in qualified prepreg freezer capacity across Southeast Asian nodes threatens supply continuity. Distribution runs through OEM-managed platform-level contracts displacing component-by-component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
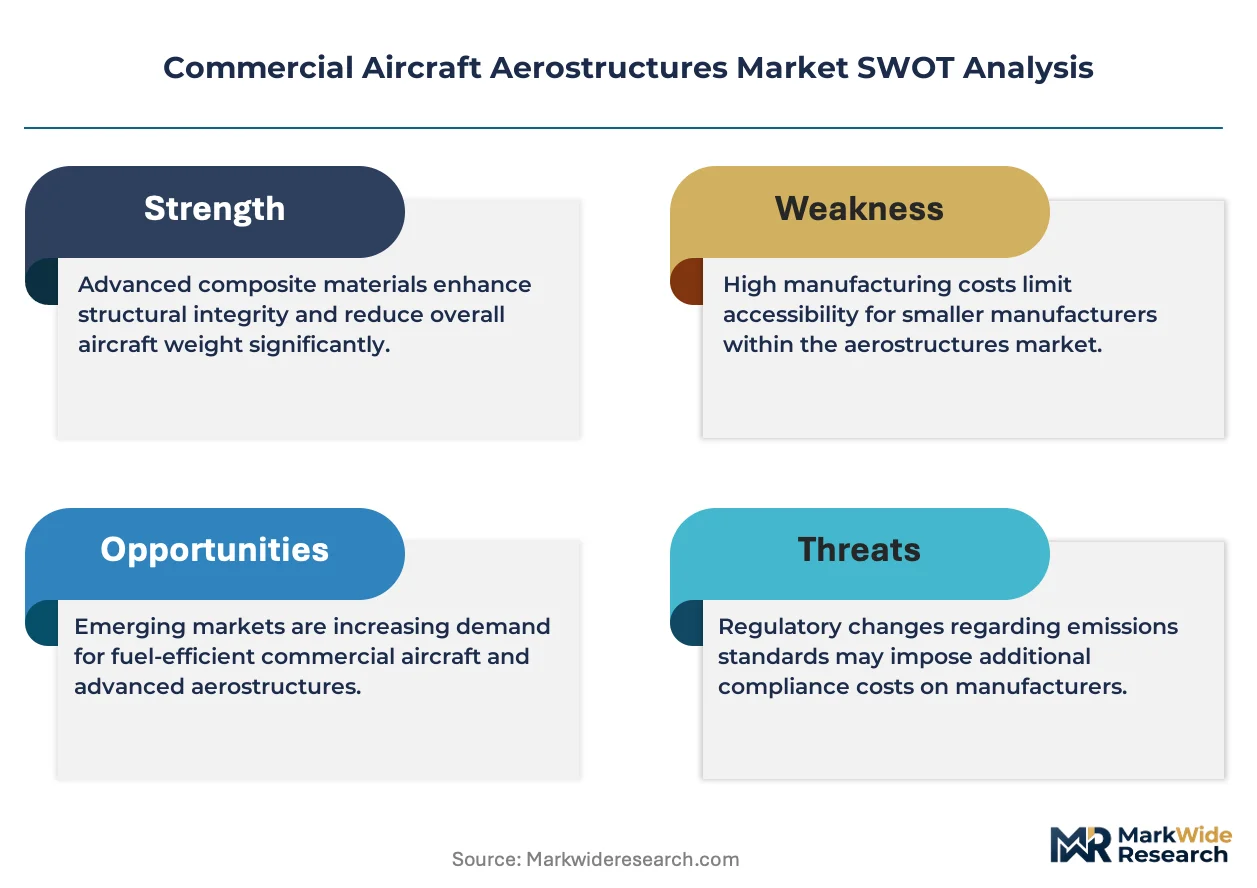
Scarcity of 2,000-hour certified composite repair technicians and qualified AFP robotics operators concentrates value capture among incumbents with captive training infrastructure, while locking new entrants out of margin-rich aftermarket and empennage segments.
For Market Incumbents: Pre-empt technician poaching by locking multi-year training pipeline commitments with Wichita, Toulouse, and Hamburg technical institutes before COMAC supply chain expansion drains qualified labor pools. Anchor aluminum fuselage pricing power through backward integration into Al-Li alloy mill product offtake agreements, insulating against London Metal Exchange volatility that threatens build-to-print competitors. For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat and Karnataka manufacturing zones under the PLI scheme's 15-year tax holiday framework, targeting aluminum subassembly fabrication for narrow-body programs before composite-intensive wing demand saturates qualified supplier capacity. Pursue electron beam curing technology licensing partnerships to bypass autoclave bottlenecks that constrain incumbent expansion timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors tier-1 suppliers with integrated stress analysis capabilities and CAAC-FAA dual qualification systems, as platform-level sourcing consolidation displaces build-to-print fabricators lacking design authority. Monitor CAAC indigenous certification autonomy acceleration as the inflection signal determining Western supplier participation viability in COMAC C919 and ARJ21 programs.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Robotics Deployment | Airbus and Boeing AFP integration cuts layup labor hours while enabling thicker monolithic wing skins. |
| Thermoplastic Composite Capability Buildout | GKN Aerospace thermoplastic empennage specialization commands premium positioning under EASA CS-25 Amendment 25-146. |
| Dual CAAC-FAA Quality System Certification | Parallel audit maintenance opens COMAC C919 participation though volume guarantees remain uncertain. |
| Out-of-Autoclave Curing Technology Licensing | Electron beam and microwave curing eliminates autoclave bottlenecks enabling distributed fabrication nodes. |
| Composite Repair Technician Pipeline Development | BVID assessment and scarf repair certification scarcity concentrates aftermarket margin in Wichita, Toulouse, and Hamburg. |
Study Parameters
Cross-validation between primary interviews with aerostructures procurement directors, composite manufacturing engineers, and FAA certification specialists and secondary validation through EASA CS-25 amendment filings, FAA airworthiness directive databases, and COMAC supplier qualification records anchors the qualitative findings. Bottom-up fabrication capacity assessments across Wichita, Toulouse, and Shanghai clusters triangulate against top-down OEM procurement spend analysis.
Calibration against historical narrow-body production rate elasticity and composite material adoption curves shapes the analytical framework across the projection horizon, with segmentation modeled by product type, material class, end-user tier, and manufacturing stage. CAGRs derive from elasticity-adjusted build rates and material substitution trajectories, incorporating titanium sponge supply disruption scenarios and REACH Annex XIV coating conversion capital deployment timelines.
Stress conditions across Boeing 737 MAX and Airbus A320 output rate bands, CAAC certification autonomy acceleration, and titanium feedstock availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Material shifts in FAA-EASA regulatory divergence or COMAC indigenous supply chain completion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
India Aviation Market
Aircraft
Heavy-Lift Helicopter Market
Aircraft
North America General Aviation Market
Aircraft
Commercial Aircraft Landing Gear Market
Aircraft
Flight Management Systems Market
Aircraft
Southeast Asia Aviation Market
Aircraft
Search and Rescue Aircraft Market
Aircraft
Aircraft Pushback Tugs Market
Aircraft
Aircraft Galley Systems Market
Aircraft
Latin America Commercial Aircraft Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Turboprop Aircraft Market
Aircraft
Asia-Pacific Fighter Aircraft Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Firefighting Aircraft Market
Aircraft
Docking System Market