
 US Automotive Composites Market | 2026-2036
US Automotive Composites Market Size, Share, and Industry Trends Forecast 2026-2036
US Automotive Composites Market Analytics
Aftermarket service revenue is reshaping margin capture across the US automotive composites value chain. Hexcel Corporation leverages its carbon fiber prepreg expertise to anchor defense and commercial aerospace-adjacent automotive programs. SGL Carbon specializes in automotive-specific carbon fiber solutions for electric vehicle battery enclosures. Owens Corning dominates glass fiber reinforcement supply for high-volume structural applications.
US automotive composites encompass fiber-reinforced materials combining polymer, metal, or ceramic matrices with carbon, glass, or aramid reinforcements, manufactured through resin transfer molding, sheet molding compound, or automated fiber placement to achieve strength-to-weight ratios exceeding conventional steel by fifty to seventy percent. Polymer matrix composites lead volume due to process maturity and cost scalability in exterior body panels and structural parts. Carbon fiber within the material dimension commands premium positioning in chassis components where stiffness and crash performance justify higher unit economics.
NHTSA enforces CAFE standards that penalize fleet-wide overweight vehicles, while EPA tailpipe emissions rules indirectly compel lightweighting through powertrain efficiency requirements. OSHA and state-level California Air Resources Board frameworks further constrain manufacturing processes and material chemistries. Stakeholders must monitor evolving federal Buy American content thresholds and state-level EV manufacturing incentives that will determine composite sourcing geography and qualification pathways.
Market Dynamics
CAFE compliance deadlines and EV platform rollouts are compressing automaker timelines for structural lightweighting, forcing simultaneous investment in high-pressure resin transfer molding capacity and automated fiber placement qualification pathways.
Growth Catalysts
- NHTSA CAFE Penalties:Fleet-wide overweight vehicle fines compel OEMs to substitute polymer matrix composites for steel in body-in-white structures, accelerating Michigan and South Carolina tooling investments.
- Electric Vehicle Battery Enclosures:Carbon fiber-reinforced thermoplastics deliver crash protection and thermal management for underfloor battery packs, with California manufacturers leading platform-specific qualification.
- Automated Fiber Placement:This process technology reduces layup labor hours by sixty percent versus hand layup, enabling cost-competitive high-volume structural part production for mid-size vehicle programs.
Market Restraints
- Acrylonitrile Price Volatility:Carbon fiber precursor costs swing with petroleum feedstock markets, compressing margin buffers for Tier 2 composite processors serving Detroit Three programs.
- Single-Source Carbon Fiber Supply:Domestic PAN-based precursor production concentrates in three facilities, creating geographic concentration risk for chassis component manufacturers.
- Repair Protocol Gaps:Collision shops lack standardized composite repair certification, limiting aftermarket revenue capture and depressing residual value calculations for insurers.
Strategic Opportunities
- Texas Gulf Coast Petrochemical Corridor:Proximity to propylene and epoxy resin feedstocks enables backward integration into SMC compound manufacturing for pickup truck bed applications.
- IRA Clean Vehicle Tax Credits:Domestic content thresholds for EV incentives reward US-sourced carbon fiber and resin systems, reshaping supplier qualification criteria.
- Thermoplastic Welding:Induction welding of carbon fiber/PA6 composites eliminates adhesive cure cycles, converging with automaker cycle time targets for closure panel assembly.
Industry Challenges
- Automated Fiber Placement Programming:Aerospace-trained technicians command wage premiums scarce in automotive manufacturing regions, constraining workforce scaling for EV platform launches.
- Crash Simulation Validation:Composite material cards require eighteen-month correlation cycles with physical barrier tests, delaying vehicle program timing gates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Automotive Composites Market |
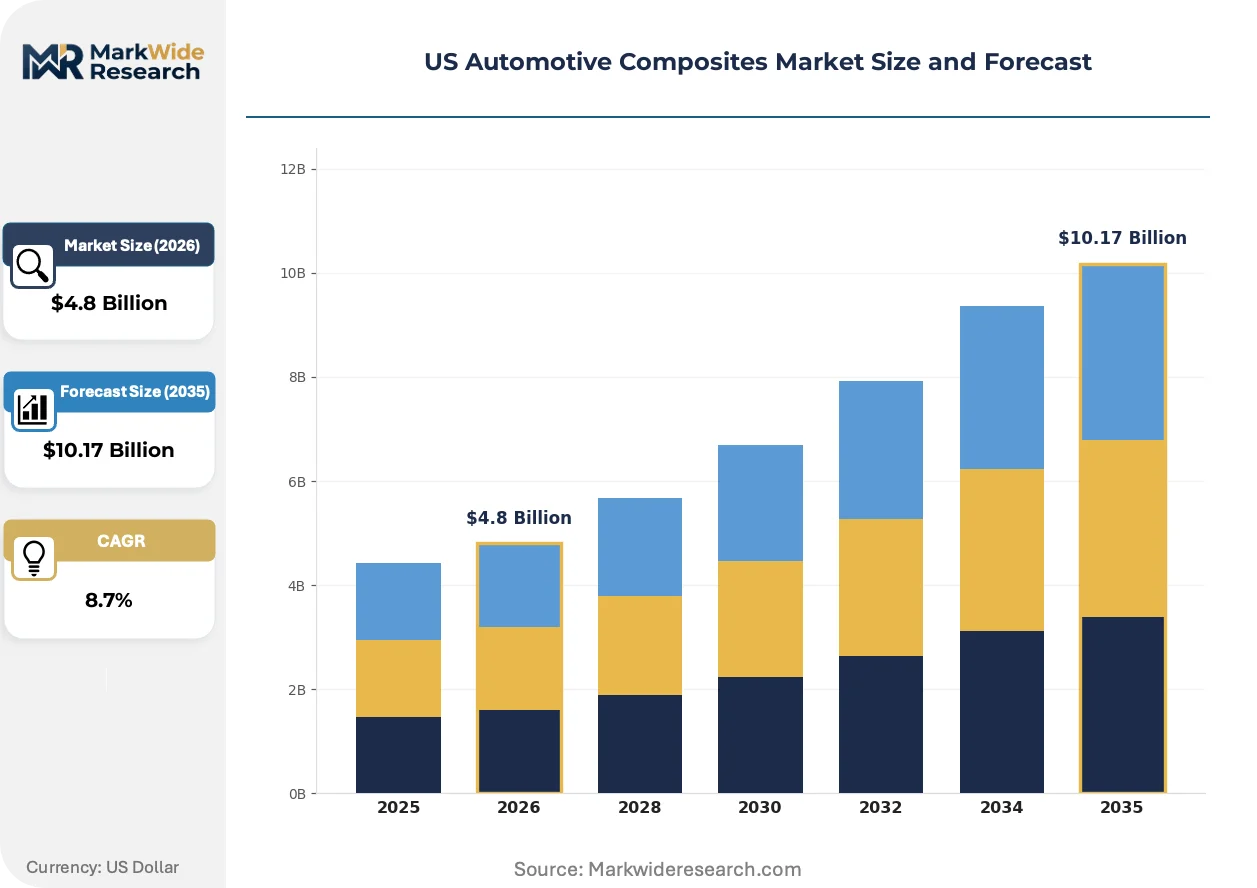
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Matrix Composites, Metal Matrix Composites, Ceramic Matrix Composites, Hybrid Composites Application: Structural Parts, Interior Components, Exterior Body Panels, Chassis Components End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Material: Carbon Fiber, Glass Fiber, Aramid Fiber, Others |
| Companies Covered | Toray Industries, SGL Carbon, Hexcel Corporation, Teijin Limited, Mitsubishi Chemical Group Corporation, Solvay S.A., Owens Corning, BASF SE, Huntsman Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Automotive Composites Market Evolving Landscape
Digital thread integration across design-to-manufacturing workflows is compressing composite part development cycles while regulatory pressure on embodied carbon intensifies material sourcing scrutiny.
High-speed automated fiber placement is digitizing preform manufacturing for structural automotive components. Tier 1 suppliers in South Carolina and Michigan are installing multi-tow systems capable of processing thermoplastic unidirectional tapes at rates exceeding one meter per second. This equipment is digitizing quality documentation and real-time defect detection, collapsing the feedback loop between production and engineering.
EPA tailpipe emissions rules are tightening indirect lightweighting mandates through powertrain efficiency multipliers. The regulatory pressure elevates mass reduction to parity with electrification in OEM technology roadmaps. Battery electric vehicle platforms in California and Michigan manufacturing corridors are responding with carbon fiber-intensive skateboard architectures.
Fleet procurement of composite-intensive vehicles is concentrating among rental and commercial operators seeking total cost of ownership advantages. These buyers are unbundling maintenance contracts and demanding component-level lifecycle data from suppliers. The behavioral shift is most visible in Michigan-based commercial fleet management programs specifying carbon fiber body panels for delivery vehicle durability targets.
US Automotive Composites Market Segmentation
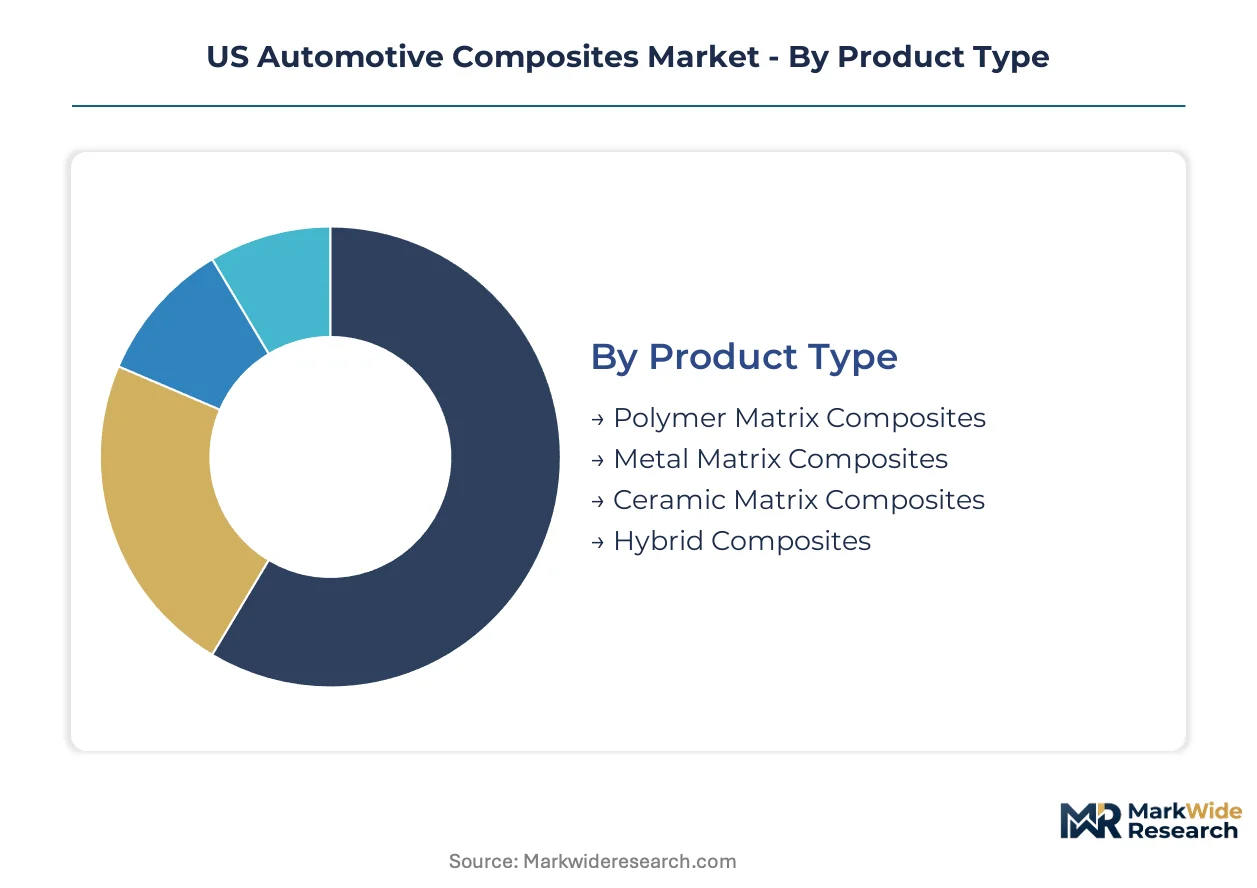
Segmentation reveals how material chemistry, manufacturing process, and supply chain position determine margin capture across the US automotive composites value chain. Each dimension exposes different competitive dynamics: product type separates process-mature from emerging technologies, application dictates qualification timelines, end user concentration shapes pricing power, and material selection drives feedstock risk exposure.
Product Type:
Cost tier separates established molding processes from capital-intensive emerging matrices with distinct qualification pathways and margin profiles.
- Polymer Matrix Composites:Thermoset and thermoplastic resins reinforced with carbon or glass fiber dominate exterior body panels and structural members through resin transfer molding and injection compression. Michigan-based OEM programs specify these materials for high-volume mid-size vehicle platforms where process maturity offsets raw material premiums.
- Metal Matrix Composites:Aluminum or magnesium matrices with silicon carbide reinforcement deliver thermal conductivity for brake rotors and powertrain housings. South Carolina manufacturing corridors concentrate demand from performance vehicle programs seeking stiffness-to-weight ratios exceeding polymer alternatives.
- Ceramic Matrix Composites:Silicon carbide fiber-reinforced ceramics withstand extreme temperatures in exhaust components and turbocharger housings.
- Hybrid Composites:Multi-material laminates combining polymer and metal layers optimize crash energy management in battery enclosures.
Polymer matrix composites command the established base. The steepest expansion runs through metal matrix composites.
Application:
Volume concentration varies dramatically by application, with structural members scaling to millions of units while chassis components remain program-specific.
- Structural Parts:Body-in-white components including A-pillars, roof rails, and floor pans substitute composites for high-strength steel to achieve CAFE-mandated mass reduction. South Carolina and Michigan tooling investments concentrate here for Detroit Three electric vehicle platforms.
- Exterior Body Panels:Hoods, fenders, and liftgates utilize sheet molding compound for dent resistance and styling flexibility. California manufacturers lead qualification of Class-A surface finishes for premium electric vehicle programs.
- Chassis Components:Carbon fiber-reinforced control arms and suspension links deliver unsprung mass reduction for performance variants.
- Interior Components:Seat backs, load floors, and trim panels prioritize acoustic damping and occupant safety over structural load-bearing.
Structural parts absorb the dominant share of composite tonnage. Exterior body panels are climbing the fastest as surface quality standards converge with steel.
End User:
Customer type determines contract structure, with OEM direct procurement favoring long-term qualification investments versus spot-market aftermarket dynamics.
- OEMs:Ford, General Motors, and Stellantis specify composite content through platform engineering decisions that lock in suppliers for seven-to-ten-year vehicle lifecycles. NHTSA CAFE compliance deadlines compress these qualification timelines, forcing simultaneous validation of multiple material grades.
- Tier-1 Suppliers:Magna, Lear, and Aptiv integrate composite manufacturing into modular assemblies delivered to vehicle assembly plants. These intermediaries concentrate procurement leverage for resin and fiber feedstocks.
- Vehicle Assemblers:Contract manufacturers and startup EV producers source composite-intensive skateboard platforms from integrated subsystem suppliers.
- Aftermarket Providers:Collision repair networks and performance upgrade specialists face certification gaps limiting composite part replacement revenue.
OEMs anchor procurement volume through platform specifications. Tier-1 suppliers are gaining share fastest as modular assembly outsourcing accelerates.
Material:
Supply concentration and feedstock chemistry create divergent risk profiles across reinforcement categories.
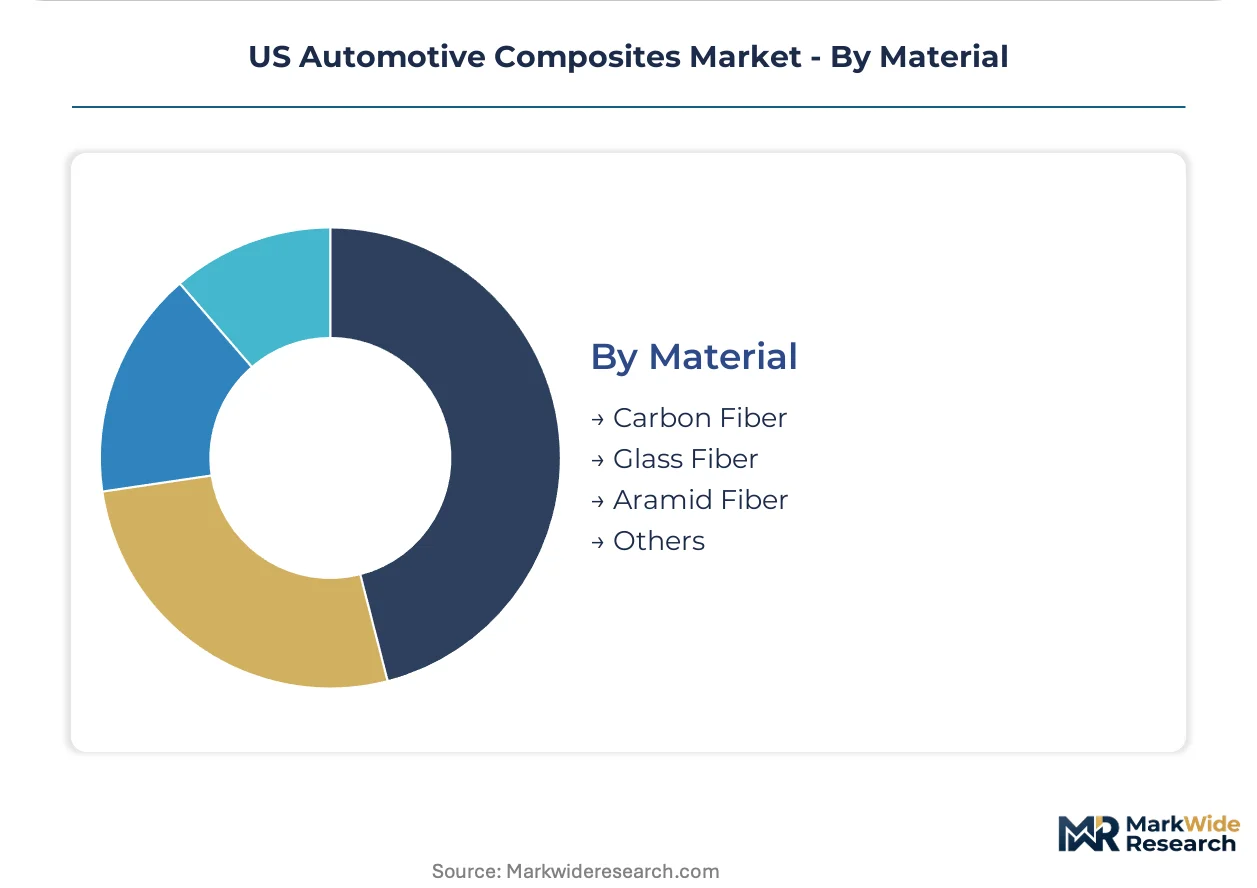
- Carbon Fiber:PAN-based precursors from domestic facilities supply chassis and battery enclosure applications where stiffness and crash performance justify unit economics. Acrylonitrile price volatility compresses margins for processors serving cost-sensitive programs.
- Glass Fiber:E-glass and S-glass reinforcements dominate high-volume structural applications through Owens Corning's integrated supply position. Texas Gulf Coast petrochemical proximity enables backward integration into SMC compound manufacturing.
- Aramid Fiber:Kevlar and Twaron reinforcements penetrate ballistic protection and tire reinforcement niches with limited automotive penetration.
- Others:Basalt and natural fiber reinforcements occupy sustainability-positioned segments with unproven scalability.
Glass fiber maintains volume leadership. Carbon fiber is expanding most quickly as electric vehicle battery protection requirements multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across US manufacturing corridors. Michigan OEMs absorb carbon fiber premiums for CAFE compliance, while Texas Gulf Coast processors prioritize propylene-adjacent SMC cost optimization.
Michigan
Detroit Three platform engineering locks in seven-to-ten-year composite supplier contracts for electric vehicle body-in-white structures. NHTSA CAFE penalty exposure drives simultaneous qualification of multiple polymer matrix grades. Tooling investments concentrate in Detroit-Warren-Dearborn corridor for high-pressure resin transfer molding capacity serving mid-size vehicle programs.
South Carolina
BMW and Volvo Car USA operations anchor demand for carbon fiber chassis components and battery enclosures. State-level manufacturing incentives stack with IRA Clean Vehicle Tax Credits to reward domestic fiber sourcing. Greenville-Spartanburg corridor hosts automated fiber placement installations processing thermoplastic unidirectional tapes for skateboard architectures.
California
Premium electric vehicle programs specify Class-A surface finish standards for exterior body panels, compressing qualification timelines. California Air Resources Board frameworks constrain manufacturing chemistries and embodied carbon thresholds. Bay Area-to-Los Angeles manufacturing axis leads battery enclosure platform-specific qualification for thermal management and crash protection.
Texas
Gulf Coast petrochemical proximity enables backward integration into sheet molding compound manufacturing for pickup truck bed applications. Propylene and epoxy resin feedstock access supports high-volume structural part cost competitiveness. Houston-Beaumont-Port Arthur corridor concentrates SMC compounders serving Detroit Three light truck programs.
US Automotive Composites Market Competitive Landscape
Integrated fiber producers and specialized compounders split the market along feedstock control lines. Concentration runs highest in PAN-based carbon fiber precursor supply, where three domestic facilities create geographic concentration risk. Two archetypes dominate: aerospace-adjacent carbon fiber specialists leveraging defense qualification pathways, and glass-integrated building materials giants with petrochemical backward integration. Competitive moves center on IRA domestic content threshold compliance and thermoplastic welding technology licensing.
Among Japanese- and German-based fiber producers, Toray Industries, SGL Carbon, and Teijin Limited occupy positions spanning PAN precursor through prepreg qualification. These entities exemplify the aerospace-to-automotive qualification bridge archetype, anchoring defense-adjacent supply relationships that accelerate automotive platform approval cycles. Owens Corning represents the scale-driven glass fiber integration model, with Texas Gulf Coast petrochemical proximity supporting captive SMC compound manufacturing.
| Leading Market Players |
|---|
| Toray Industries |
| SGL Carbon |
| Hexcel Corporation |
| Teijin Limited |
| Mitsubishi Chemical Group Corporation |
| Solvay S.A. |
| Owens Corning |
| BASF SE |
| Huntsman Corporation |
| Others |
Value Network & Pricing Analysis
The Houston-Beaumont-Port Arthur freight corridor's propylene logistics costs compress SMC compound margins while amplifying price differentiation between Gulf Coast-integrated suppliers and inland processors serving Michigan OEM programs.
Pricing Analysis
Aftermarket service revenue tiers drive lifetime value capture across collision repair networks and fleet maintenance contracts. Three-tier pricing structure across aerospace-qualified, automotive-grade, and industrial-standard carbon fiber separates Tier 1 suppliers from commodity processors. Pricing pressure stems from acrylonitrile feedstock volatility eroding margin buffers for PAN-based precursor converters. Commercial fleet operators exhibit highest price sensitivity, while defense-adjacent automotive programs absorb premium positioning.
Supply Chain Analysis
Tariff exposure between US and Asian carbon fiber precursor sources dominates supply chain risk calculations for chassis component manufacturers. Domestic production concentrates in South Carolina, Texas, and California manufacturing corridors, drawing from petroleum-based acrylonitrile and propylene feedstocks. Single-source vulnerability runs through three domestic PAN-based precursor facilities. Distribution runs through Tier 1 modular assembly suppliers with captive qualification pathways to Detroit Three OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US automotive composites constitute a high-growth disruption as NHTSA CAFE penalty structures and EV platform rollouts compress qualification timelines below historical aerospace baselines.
For Market Incumbents: Insulate core prepreg supply relationships by securing IRA domestic content threshold compliance through backward integration into Texas Gulf Coast resin manufacturing. Accelerate automated fiber placement workforce pipelines in South Carolina to counter aerospace-trained technician wage premiums. Threat substitution from thermoplastic welding adoption demands rapid process qualification.
For New Entrants and Emerging Players: Texas Gulf Coast SMC compound manufacturing for light truck bed applications represents the most penetrable entry point given propylene feedstock proximity and Detroit Three volume concentration. California battery enclosure platform-specific qualification offers secondary white-space access. Go-to-market leverage rests on induction welding cycle time advantages versus adhesive cure systems.
For Investors and Strategic Acquirers: Aerospace-to-automotive qualification bridge specialists with captive defense relationships anchor acquisition target profiles. Long-term viability frames around IRA incentive durability and NHTSA CAFE enforcement stringency across the analysis window. Signal to monitor: Michigan tooling investment announcements for high-pressure resin transfer molding capacity serving mid-size EV platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Capacity Expansion | South Carolina installations processing thermoplastic tapes at one meter per second compress labor hours sixty percent versus hand layup. |
| Backward Integration into SMC Compound Manufacturing | Texas Gulf Coast propylene proximity enables captive supply for pickup truck bed applications serving Detroit Three programs. |
| IRA Domestic Content Compliance Investment | US-sourced carbon fiber and resin systems unlock Clean Vehicle Tax Credit thresholds reshaping supplier qualification criteria. |
| Thermoplastic Welding Technology Licensing | Induction welding of carbon fiber/PA6 composites eliminates adhesive cure cycles converging with automaker cycle time targets. |
| Collision Repair Certification Program Development | Standardized composite repair protocols unlock aftermarket revenue capture currently depressed by insurer residual value calculations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and automated fiber placement technicians. Secondary validation drew from NHTSA CAFE filings, EPA tailpipe emissions rulemakings, SEC 10-K disclosures from fiber producers, and IHS Markit vehicle production databases. Bottom-up part-level content analysis and top-down OEM platform specification triangulation anchored volume estimates.
Calibration against historical qualification cycle data and announced tooling investments shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry, manufacturing process maturity, application structural intensity, end-user procurement structure, and regional manufacturing corridor concentration. CAGRs derived from correlation between CAFE compliance deadlines and EV platform rollout schedules, with battery enclosure content per vehicle and automated fiber placement adoption curves as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in petroleum feedstock pricing, interest rate environments affecting capital-intensive equipment investment, or IRA incentive policy durability would shift the trajectory. Forecasts reflect documented assumptions regarding NHTSA enforcement stringency and OEM lightweighting technology roadmaps. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Russia Automotive Electric Actuators Market
Automotive Components
Automotive Differential Market
Automotive Components
Italy Automotive Sunroof Market
Automotive Components
Automotive Distributor Market
Automotive Components
Automotive Gear Oil Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Off-Highway Actuators Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Australia Automotive Glass Fiber Composites Market
Automotive Components
Europe Torque Vectoring Market
Automotive Components
Automotive Mobile Accessories Market
Automotive Components
Automotive Transaxle Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Automotive Brake System and Components Market
Automotive Components
Automotive Brake Rotor Market