
 Automotive Buffers Market | 2026-2036
Automotive Buffers Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Buffers Market Analysis
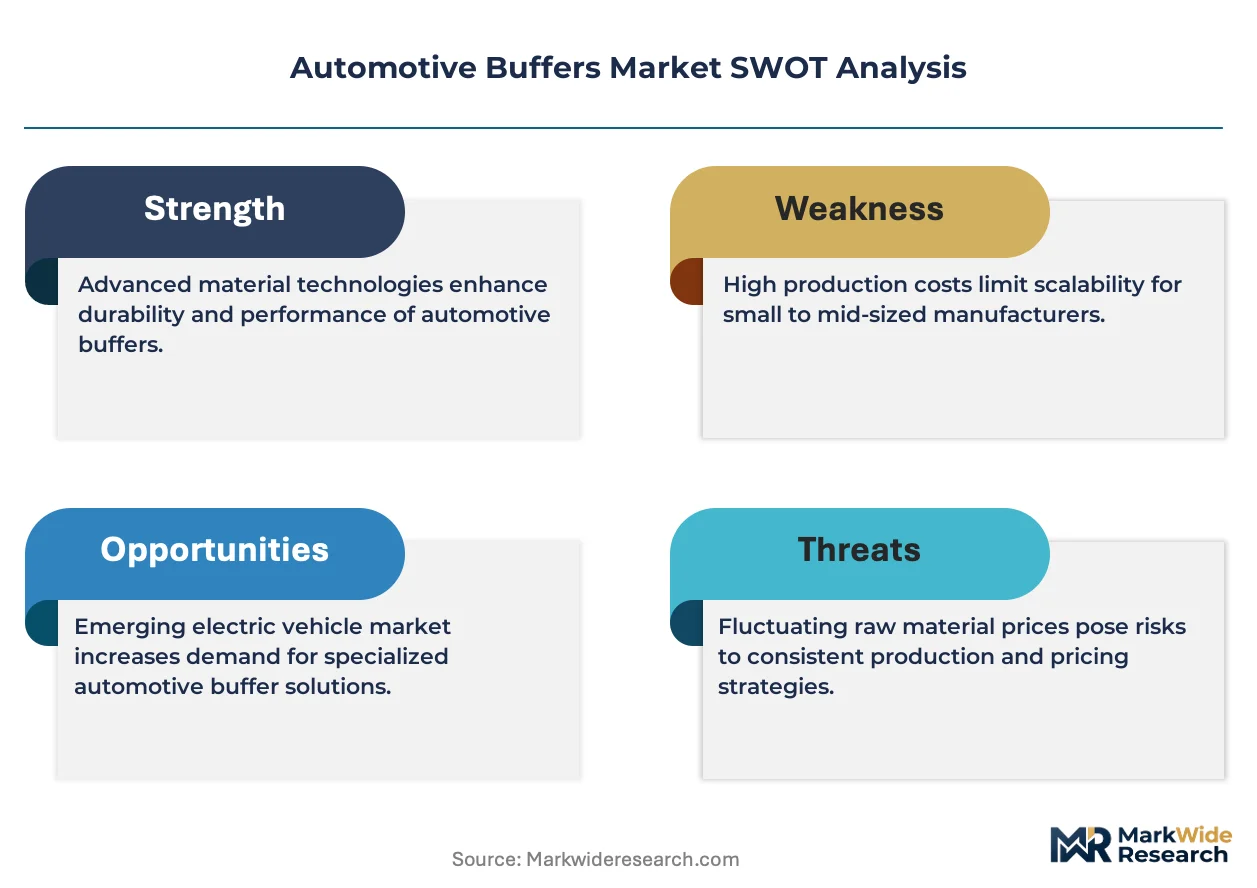
REACH compliance is shifting the cost-of-entry calculus for compound suppliers entering the European automotive buffer supply chain. 3M Company leverages its materials science portfolio to sustain certification across multiple buffer chemistries. Robert Bosch GmbH anchors its position through captive testing protocols that validate polyurethane formulations under OEM durability standards. Makita Corporation competes in the aftermarket channel with specialized tool-buffer systems for collision repair facilities.
Automotive buffers are vibration-dampening and impact-absorbing components manufactured from elastomeric compounds including natural rubber, synthetic polyurethane, silicone gel, and closed-cell foam, typically specified by Shore hardness ratings and compression set percentages to isolate mechanical noise and protect structural assemblies. Their primary industrial purpose is to reduce noise, vibration, and harshness while extending service life of connected vehicle systems. Polyurethane buffers command the largest volume share in suspension applications due to superior load-bearing capacity and oil resistance compared to natural rubber alternatives. Gel buffers represent the fastest-expanding category as electric vehicle platforms demand multi-axis vibration isolation for battery pack protection and motor mounting. Foam buffers occupy a mature niche in exhaust hanger applications where cost minimization outweighs performance optimization.
The EPA regulates volatile organic compound emissions from buffer manufacturing processes under Clean Air Act standards, while NHTSA crashworthiness protocols indirectly shape buffer deformation requirements in body mount applications. ISO 14001 environmental management certification has become a de facto qualification threshold for Tier-1 suppliers bidding on OEM contracts in North America and Europe. Stakeholders must monitor evolving battery electric vehicle platform architectures to anticipate where multi-material buffer assemblies displace single-compound legacy designs.
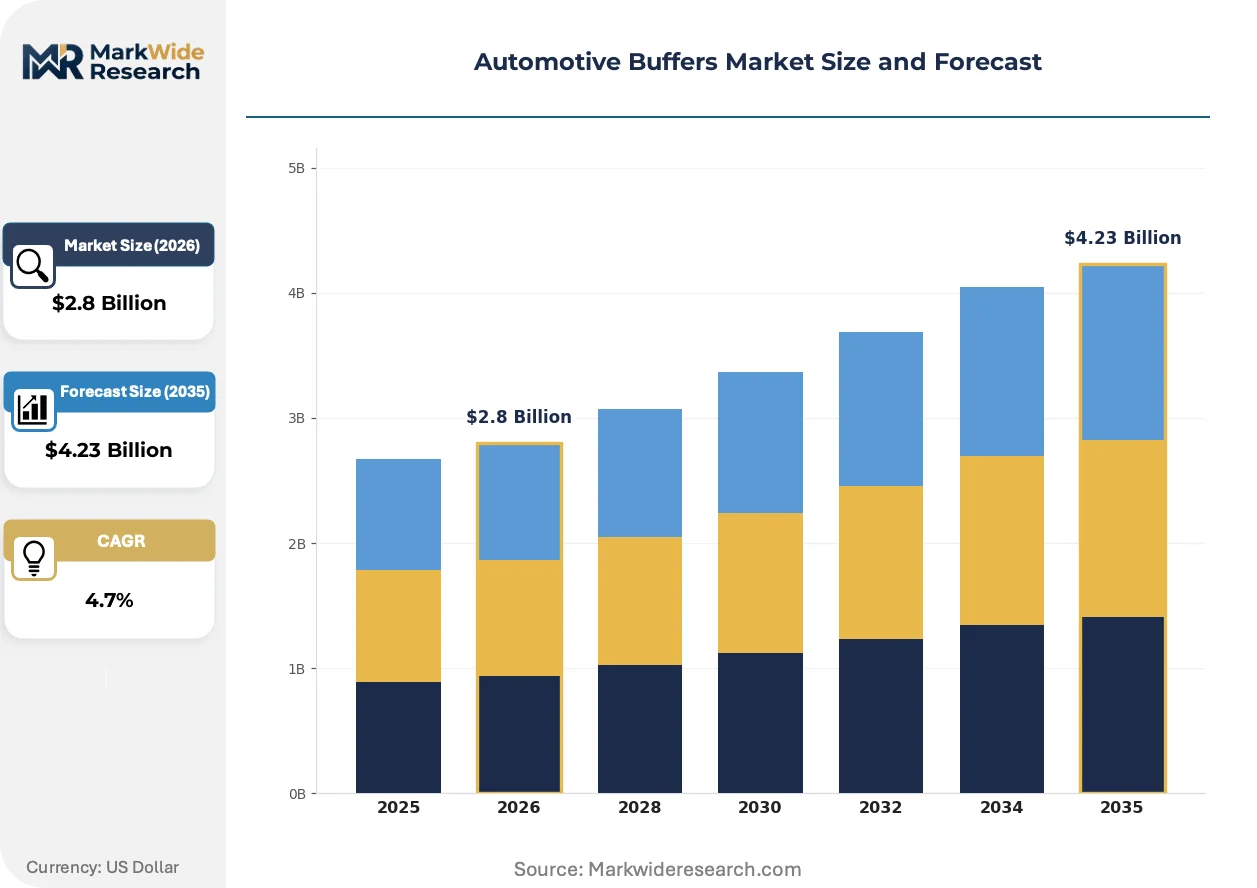
Market Dynamics
Electric vehicle platform architectures are forcing suspension redesigns that prioritize multi-axis vibration isolation over legacy single-plane damping, compressing compound qualification cycles and fragmenting supplier certification requirements across OEM programs.
Growth Catalysts
- REACH compliance mandates:ECHA chemical content rules for rubber compounds are accelerating reformulation investments among European suppliers, creating first-mover certification advantages for compliant compounders.
- Polyurethane suspension buffers:Load-bearing capacity and oil resistance specifications in heavy-duty EV platforms are displacing natural rubber in axle mounting applications.
- Germany luxury chassis demand:Premium automaker sourcing of specialized gel buffers for NVH reduction is concentrating high-margin procurement in Baden-Württemberg and Bavaria supplier clusters.
Market Restraints
- Petrochemical input volatility:Polyurethane precursor costs tied to propylene oxide and MDI spot markets create margin compression for non-integrated compounders.
- Testing protocol fragmentation:Captive OEM durability standards at Robert Bosch GmbH and similar Tier-1s lock out second-tier suppliers lacking capital for parallel validation infrastructure.
- Silicone gel substitution limits:Temperature performance ceilings above 150°C restrict gel buffer penetration into engine bay applications where fluorocarbon elastomers dominate.
Strategic Opportunities
- Battery pack protection assemblies:Multi-material buffer configurations combining polyurethane cores with silicone gel damping layers are opening specification slots in skateboard platform architectures.
- Collision repair channel digitization:Specialized tool-buffer systems for body shops are migrating from distributor networks to direct OEM-affiliated procurement portals.
- ISO 14001 certification arbitrage:Environmental management gaps among Asia-Pacific compounders create acquisition targets for Western suppliers seeking qualified manufacturing capacity.
Industry Challenges
- Compound formulation talent scarcity:Polyurethane chemistry expertise with EV-specific Shore hardness and compression set requirements concentrates among aging specialist workforces in Germany and Japan.
- Dual certification timelines:Simultaneous EPA Clean Air Act VOC compliance and REACH substance registration create 18-24 month qualification bottlenecks for new buffer introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Buffers Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Buffers, Polyurethane Buffers, Gel Buffers, Foam Buffers Application: Suspension Systems, Engine Mounts, Body Mounts, Exhaust Systems End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Commercial Vehicle Manufacturers Distribution Channel: Direct Sales, Online Retail, Specialty Stores, Wholesale Distribution |
| Companies Covered | 3M Company, Robert Bosch GmbH, Makita Corporation, DeWalt, Milwaukee Tool, Chemical Guys, Meguiar's, Inc, Porter-Cable, Rupes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Buffers Market Emerging Trajectories
Material science convergence and regulatory chemistry constraints are compressing traditional compound qualification pathways while opening specification slots for multi-layer buffer architectures.
Silicone gel buffer technology is expanding into electric vehicle battery pack isolation systems where multi-axis vibration damping protects cell-to-pack structural integrity. OEMs in Germany and California are specifying gel-to-metal bonding interfaces for motor mounting brackets at volumes outpacing legacy rubber-to-steel assemblies. This material transition is expanding into adjacent thermal management applications where gel compounds simultaneously damp vibration and conduct heat away from power electronics.
REACH substance restrictions under ECHA authorization lists are forcing reformulation of curative agents in polyurethane buffer manufacturing across European supply chains. Compounders must substitute dibutyltin catalysts with bismuth or zinc alternatives, extending R&D cycles by 8-14 months for equivalent mechanical performance. German Tier-1 suppliers are responding by consolidating formulation development in captive laboratories to protect proprietary curing protocols from disclosure requirements.
Aftermarket procurement for collision repair buffers is fragmenting from traditional distributor networks toward OEM-certified direct channels. Independent body shops in the US and Germany now purchase buffer-tool systems through manufacturer-affiliated portals that bundle technical documentation with physical supply. This channel migration is most visible in premium German marque repair facilities where warranty compliance requires traceable buffer origin documentation.
Automotive Buffers Market Segmentation
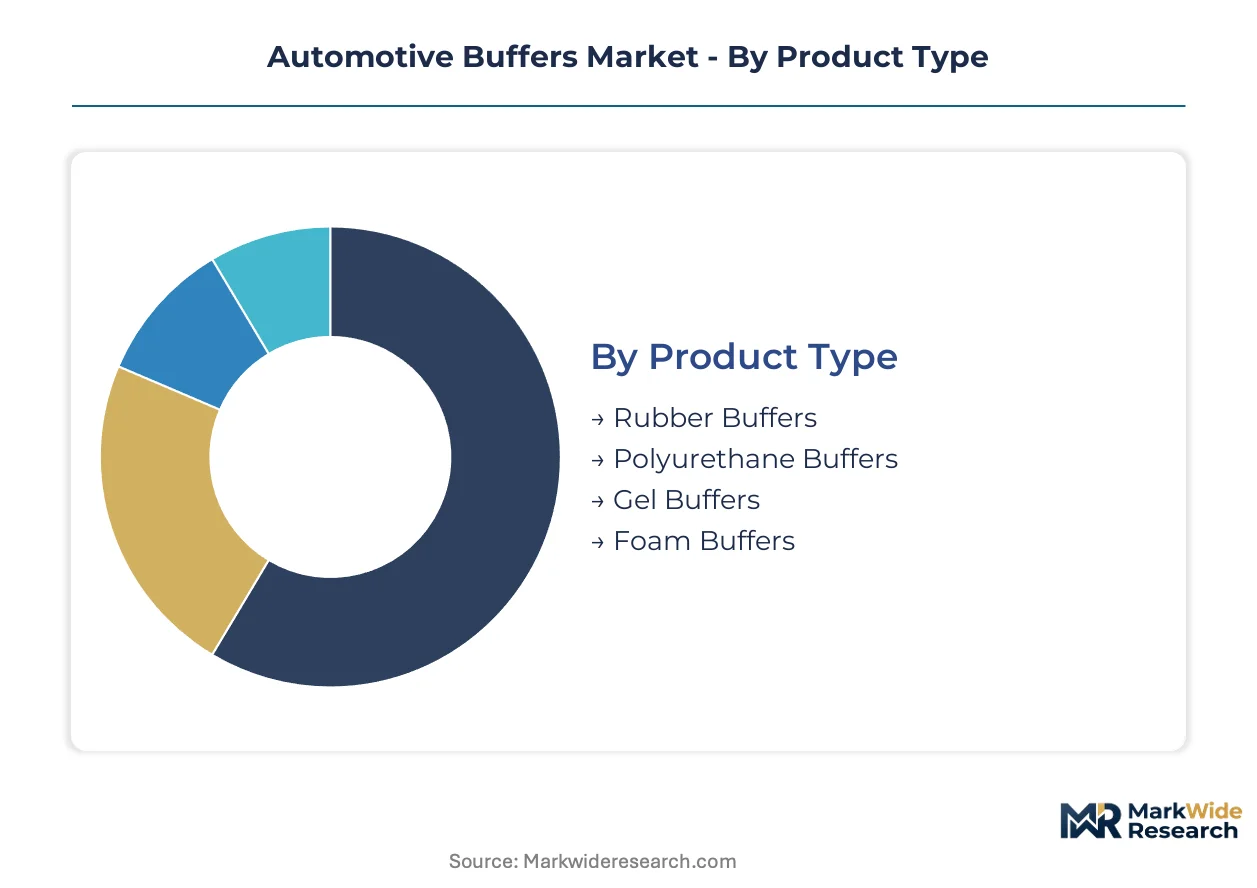
Segmentation in the automotive buffers market reveals how material chemistry and procurement channel choices directly determine margin capture. Suppliers must align compound portfolios against the specific durability and certification demands of each segment cluster.
Product Type:
Supply concentration for raw elastomer precursors shapes competitive positioning across buffer chemistries, with integrated compounders capturing margin from petrochemical volatility.
- Polyurethane Buffers:These load-bearing components combine MDI-cured polymer chains with Shore hardness ratings optimized for axle mounting stress. Demand concentrates in heavy-duty electric vehicle platforms where oil resistance and compression set performance exceed natural rubber capabilities. German OEM procurement for luxury chassis applications drives specification tightening.
- Gel Buffers:Silicone-based viscoelastic compounds deliver multi-axis vibration isolation through tuned damping coefficients. Battery pack protection assemblies in California and Baden-Württemberg represent the steepest expansion trajectory as skateboard architectures proliferate.
- Rubber Buffers:Natural and synthetic rubber compounds remain cost-competitive in legacy internal combustion exhaust hanger applications.
- Foam Buffers:Closed-cell polyurethane foam occupies mature niches where minimal unit cost outweighs performance optimization requirements.
Today's leader: Polyurethane Buffers. Tomorrow's challenger: Gel Buffers.
Application:
Application-driven specification divergence reflects the underlying mechanical stress profiles each buffer must absorb across vehicle architectures.
- Suspension Systems:Multi-axis isolation requirements in electric vehicle platforms demand reformulated polyurethane with enhanced compression set recovery. OEMs in Germany and Japan source these components through captive Tier-1 supply agreements.
- Engine Mounts:Temperature exposure above 150°C limits silicone gel penetration, preserving fluorocarbon elastomer dominance in powertrain isolation.
- Body Mounts:NHTSA crashworthiness protocols indirectly govern deformation characteristics for collision energy management.
- Exhaust Systems:Cost-minimized foam and natural rubber buffers satisfy hanger applications with moderate thermal and mechanical stress.
Suspension Systems command current procurement volume. Battery pack isolation within that category is climbing the fastest.
End User:
End user procurement authority determines certification burden and pricing leverage, with OEM direct contracts imposing the most stringent qualification requirements.
- OEMs:Direct automotive manufacturer procurement mandates ISO 14001 environmental management and REACH-compliant compound documentation. REACH substance registration creates 18-24 month qualification timelines for new buffer introductions.
- Vehicle Assemblers:Contract manufacturing arrangements for electric vehicle startups concentrate demand in California and Shanghai manufacturing corridors.
- Commercial Vehicle Manufacturers:Heavy-duty axle specifications prioritize polyurethane load-bearing capacity for fleet durability requirements.
- Aftermarket Providers:Collision repair channel digitization is migrating procurement from distributor networks to OEM-certified direct portals.
OEMs dominate qualified supply allocation. Aftermarket Providers are gaining share fastest through portal-based procurement transformation.
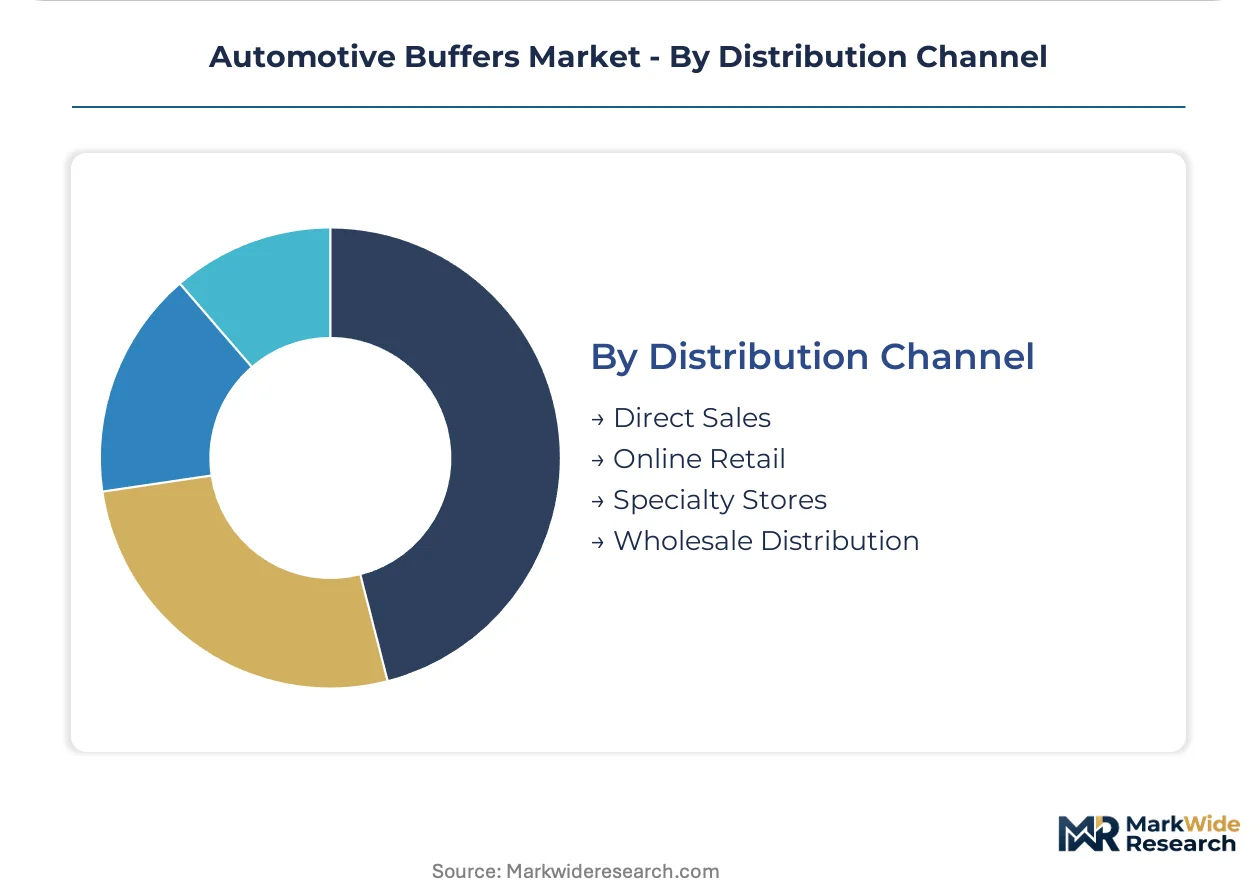
Distribution Channel:
Channel structure determines traceability documentation requirements and technical support bundling, with direct sales capturing high-complexity specification work.
- Direct Sales:OEM and Tier-1 procurement teams engage compounders through long-term supply agreements with embedded formulation development. German and Japanese suppliers consolidate these relationships through captive laboratory partnerships.
- Online Retail:Digital procurement platforms serve independent repair facilities with standardized buffer-tool system configurations.
- Specialty Stores:Regional distributors maintain inventory for collision repair facilities requiring immediate availability.
- Wholesale Distribution:Bulk logistics networks supply high-volume exhaust hanger and commodity buffer categories.
Direct Sales anchors premium specification capture. Online Retail is expanding most quickly as warranty compliance documentation digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyurethane chemistry expertise concentrates in aging specialist workforces across Germany and Japan, while gel buffer formulation talent clusters in California and Baden-Württemberg. These workforce concentrations anchor regional supply capabilities for electric vehicle platform redesigns.
Germany
Baden-Württemberg and Bavaria supplier clusters dominate premium automaker procurement of specialized gel buffers for NVH reduction in luxury chassis. ECHA REACH compliance mandates accelerate reformulation investments, creating first-mover certification advantages for compounders with captive laboratories. Stuttgart-based Tier-1 suppliers consolidate formulation development to protect proprietary curing protocols from disclosure requirements.
United States
California OEMs specify gel-to-metal bonding interfaces for motor mounting brackets at volumes outpacing legacy rubber-to-steel assemblies. EPA Clean Air Act VOC regulations govern manufacturing emissions, creating dual certification timelines with REACH for exporters. Detroit-area commercial vehicle manufacturers prioritize polyurethane load-bearing capacity for heavy-duty fleet durability specifications.
Japan
Kanto and Kansai industrial corridors house polyurethane chemistry specialists with EV-specific Shore hardness expertise. METI industrial standards shape domestic qualification protocols for buffer suppliers serving Toyota and Honda supply chains. Nagoya-based compounders face talent scarcity as aging workforces approach retirement without sufficient replacement pipelines.
China
Yangtze River Delta and Pearl River Delta manufacturing corridors concentrate vehicle assembler demand for electric vehicle startups. MIIT GB standards and dual carbon goals reshape domestic buffer specifications toward lower-emission compound formulations. Shanghai-based suppliers acquire ISO 14001 certification to qualify for Western OEM export contracts.
South Korea
Seoul Capital Area anchors domestic demand for battery pack protection assemblies in Hyundai-Kia electric platforms. MFDS chemical registration requirements parallel REACH substance restrictions for compound imports. Busan-Ulsan supplier clusters develop multi-material buffer configurations combining polyurethane cores with silicone gel damping layers.
Automotive Buffers Market Vendor Landscape
The competitive structure tilts toward integrated materials science conglomerates with captive certification infrastructure. Tier-1 automotive suppliers and diversified industrial tool manufacturers occupy distinct positioning tiers, with compound specialists and aftermarket distributors filling interstitial spaces. Strategic moves concentrate on backward integration into precursor manufacturing and geographic consolidation of formulation laboratories to compress qualification cycles.
Among diversified industrial conglomerates, 3M Company and Robert Bosch GmbH exemplify archetypes with materials science breadth and captive testing protocols respectively. Makita Corporation occupies a position within the power tool specialist tier, competing through aftermarket channel presence rather than OEM direct supply agreements. These three anchors demonstrate how certification infrastructure and channel configuration determine competitive positioning more than unit manufacturing scale.
| Leading Market Players |
|---|
| 3M Company |
| Robert Bosch GmbH |
| Makita Corporation |
| DeWalt |
| Milwaukee Tool |
| Chemical Guys |
| Meguiar's, Inc |
| Porter-Cable |
| Rupes |
| Others |
Supply Flow & Price Mechanics
REACH substance registration gates both qualified supply and premium-tier pricing access for European automotive buffer procurement, compressing margin capture for non-compliant compounders while rewarding integrated suppliers with captive certification infrastructure. German OEMs pay formulation premiums for ECHA-compliant polyurethane buffers that bypass 18-24 month qualification bottlenecks.
Pricing Analysis
Bundled technical documentation and warranty traceability packages command 15-25% premiums over unbuffered commodity buffer sales through distributor networks. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified gel buffers from uncertified rubber alternatives and bulk foam exhaust hangers. Price differentiation hinges on ISO 14001 environmental management tier and Shore hardness customization depth. Cost compression in natural rubber buffers is intensifying because of petrochemical input volatility and Asian compounder oversupply. Aftermarket collision repair facilities exhibit highest price sensitivity; OEM direct procurement teams demonstrate lowest sensitivity due to embedded durability validation requirements.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific precursor suppliers is reshaping regional sourcing strategies for Western compounders seeking supply security. Manufacturing concentrates in Germany, China, and Japan where polyurethane chemistry expertise and gel formulation talent anchor production capabilities. Raw material sourcing draws from MDI and propylene oxide petrochemical feedstocks, natural rubber plantations in Southeast Asia, and silicone precursor specialists. Single-source vulnerability in dibutyltin catalyst alternatives creates reformulation delays under REACH substance restrictions. Distribution runs through captive Tier-1 laboratory partnerships for OEM direct supply, with online retail portals capturing aftermarket channel growth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive buffer markets offer margin expansion through gel buffer premium-tier shifts and REACH compliance arbitrage, as reformulation investments create defendable certification moats against price-pressured commodity suppliers.
For Market Incumbents: Anticipate silicone gel substitution limits above 150°C by accelerating fluorocarbon elastomer R&D for engine bay penetration before regulatory windows close. Consolidate formulation development in captive Baden-Württemberg and Kanto laboratories to protect proprietary curing protocols from ECHA disclosure requirements. Defend margin position through backward integration into MDI precursor manufacturing, insulating against propylene oxide spot market volatility that compresses non-integrated compounder returns. For New Entrants and Emerging Players: Launch via OEM-certified direct procurement portals targeting collision repair digitization in US and German premium marque facilities, bypassing fragmented distributor networks. Target battery pack protection assemblies in California and Shanghai skateboard architectures where multi-material buffer configurations face limited qualified supply. Exploit ISO 14001 certification gaps among Asia-Pacific compounders through acquisition-led manufacturing capacity entry. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier rubber buffer suppliers lacking REACH reformulation capabilities and EV-specific Shore hardness expertise. Long-term viability favors compounders with gel-to-metal bonding IP and captive testing infrastructure aligned to OEM durability standards. Monitor ECHA authorization list expansions as inflection indicators for accelerated consolidation among non-compliant European suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Reformulation | Captive laboratory investments protect proprietary curing protocols from ECHA disclosure mandates. |
| Gel Buffer Capacity Expansion | Baden-Württemberg and California facilities capture battery pack isolation demand from skateboard architectures. |
| Backward Integration into MDI | In-house precursor production insulates margin from propylene oxide spot market volatility. |
| Collision Repair Portal Migration | Direct OEM-affiliated channels bundle warranty traceability with buffer-tool system procurement. |
| ISO 14001 Certification Arbitrage | Acquisition of Asia-Pacific compounders supplies Western OEM export qualification capacity. |
Methodological Framework
Bottom-up electric vehicle platform modeling reconciled against top-down elastomer precursor supply tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement teams, OEM platform engineers, aftermarket distributor operations heads, and compound R&D directors combined with secondary validation from ECHA substance registration databases, EPA Clean Air Act enforcement records, IHS Markit vehicle production data, and SEC filings from listed chemical suppliers. Triangulation across these sources calibrated segment-level volume and value estimates.
Input-output matrices mapped polyurethane, gel, rubber, and foam buffer chemistries against suspension, engine mount, body mount, and exhaust system applications across OEM, vehicle assembler, commercial vehicle, and aftermarket end-user channels. CAGRs derived from regression analysis of historical qualification timelines, petrochemical price elasticity coefficients, and electric vehicle platform adoption curves. Forecast inputs included REACH authorization list expansion schedules, battery electric vehicle architecture roadmaps, and collision repair channel digitization rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH substance restrictions or prolonged petrochemical input volatility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Filters Market
Automotive Components
Egypt Automotive Lubricants Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
Automotive Plastic Components Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Automotive Interconnecting Shaft Market
Automotive Components
India Automotive Sunroof Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Asia-Pacific Automotive Parts and Components Market
Automotive Components
Automotive Polycarbonate Glazing Market
Automotive Components
Torque Vectoring Market
Automotive Components
Drive System Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market
Automotive Components
Automotive Comfort Actuators Market
Automotive Components
Automotive Rear End Module Market