
 Automotive Brake Rotor Market | 2026-2036
Automotive Brake Rotor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake Rotor Market Analytics
Chinese foundry clusters is pivoting toward high-volume vented rotor production for electric vehicle platforms. Brembo S.p.A. leverages its motorsport heritage to dominate performance upgrade channels. Robert Bosch GmbH anchors aftermarket replacement networks through extensive service coverage. Aisin Corporation specializes in integrated brake modules for Japanese OEM transplants.
An automotive brake rotor is a cast or forged disc component, typically measuring 200-400 mm in diameter, that converts kinetic energy into thermal energy through friction against brake pads to decelerate a vehicle. Cast iron remains the dominant material due to thermal capacity and cost efficiency, though carbon composite rotors command premium positioning in racing and supercar applications. The vented rotor category leads volume shipments across SUV and truck segments where heat dissipation requirements are most severe. OEM application channels sustain higher margin pools than replacement markets due to long-term supply agreements and design-in complexity.
Federal Motor Vehicle Safety Standard 135 in the US, ECE R90 in Europe, and China's GB 5763 collectively govern friction material performance, dimensional tolerance, and thermal fade resistance for brake rotors. These frameworks elevate compliance costs for smaller foundries while favoring suppliers with in-house metallurgical testing and homologation expertise. Stakeholders must monitor evolving thermal load specifications from EV regenerative braking integration as conventional friction duty cycles compress.
Market Dynamics
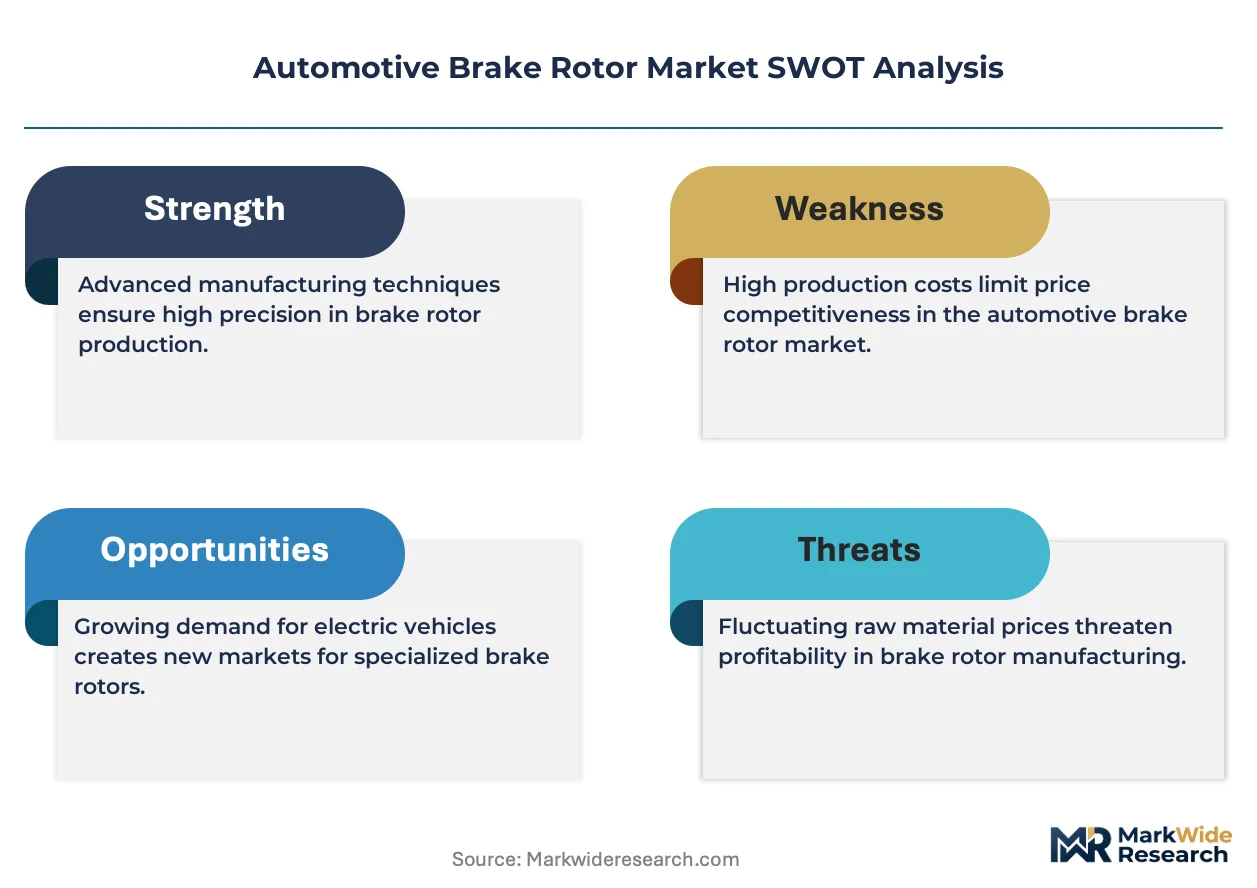
Regenerative braking integration in electric vehicles is compressing conventional friction duty cycles, forcing foundries to redesign thermal capacity specifications and metallurgical formulations for reduced wear intervals.
Growth Catalysts
- Lightweighting mandates:Passenger vehicle OEM procurement of aluminum-composite hybrid rotors intensifies as CAFE standards and EU CO₂ fleet targets tighten material efficiency requirements.
- GB 5763 alignment:China's national friction material standard is accelerating homologation investments by domestic foundries supplying BYD and NIO integrated brake platforms.
- Vented rotor architecture:Heat dissipation engineering advances are penetrating SUV and heavy truck segments where thermal load profiles exceed solid disc performance thresholds.
Market Restraints
- Scrap iron volatility:Foundry input costs fluctuate with steel scrap export restrictions from major supplier economies, squeezing margin pools for gray iron casting operations.
- Hebei-Tangshan concentration:Over half of global vented rotor casting capacity clusters in a single Chinese industrial corridor, creating geographic supply vulnerability.
- Carbon ceramic substitution ceiling:Supercar and motorsport applications capture premium positioning, but thermal shock limitations and machining complexity block mass-market penetration.
Strategic Opportunities
- EV platform integration:Brake-by-wire systems and integrated brake modules present white space for suppliers capturing design-in relationships with emerging EV-native OEMs.
- ECHA material compliance:Copper-free friction formulations mandated under REACH Annex XVII revisions create first-mover advantage for metallurgical laboratories with in-house testing protocols.
- Direct-to-fleet channels:Commercial vehicle operators are consolidating aftermarket procurement through telematics-linked predictive replacement programs, bypassing traditional distributor networks.
Industry Challenges
- Homologation timeline compression:ECE R90 certification cycles for new friction material grades now overlap with EV platform development sprints, straining testing laboratory capacity.
- Legacy foundry retooling:Conventional gray iron casting lines require capital-intensive CNC machining upgrades to meet OEM dimensional tolerance specifications for hybrid rotor assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake Rotor Market |
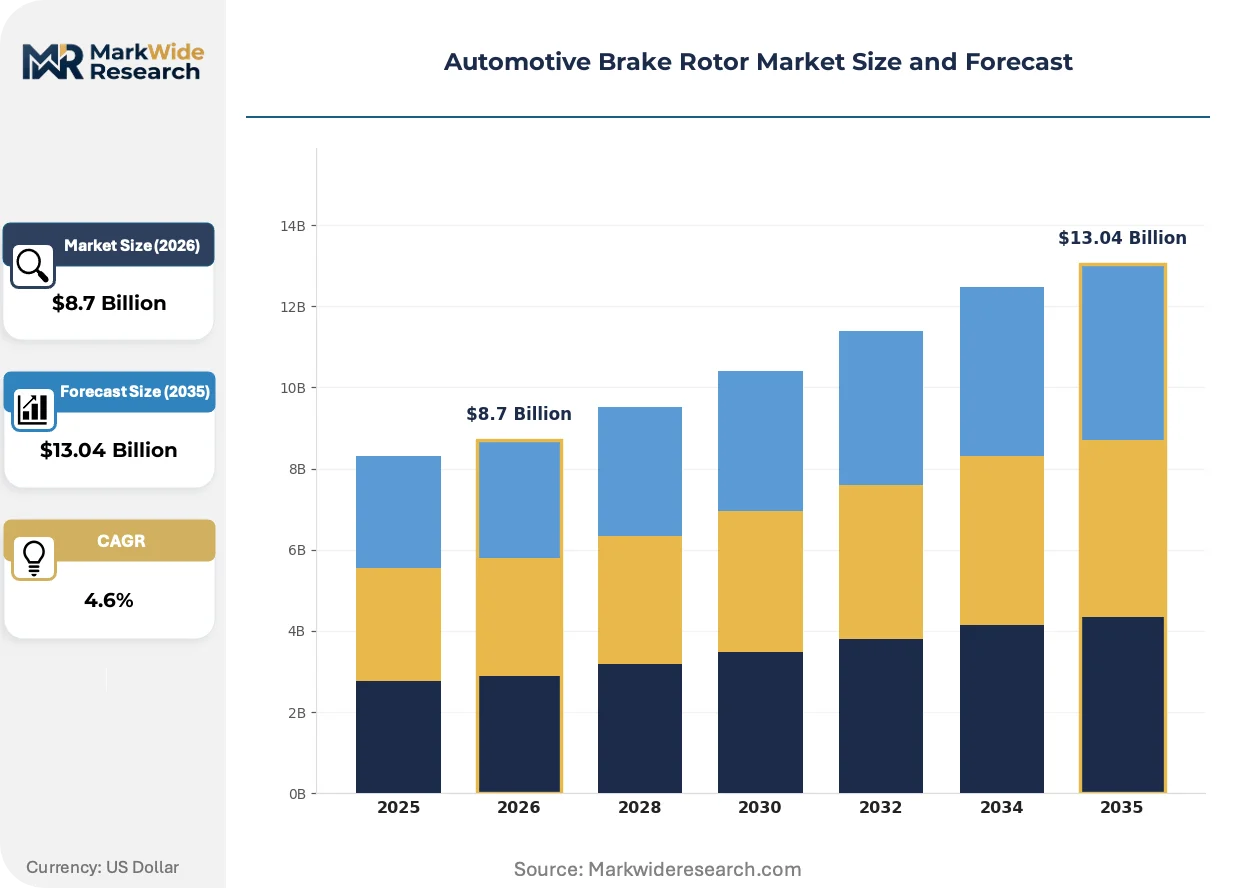
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Rotor, Vented Rotor, Slotted Rotor, Drilled Rotor Material: Cast Iron, Carbon Composite, Aluminum, Steel Vehicle Type: SUV, Sedan, Hatchback, Truck Application: Replacement, Performance Upgrade, Racing, OEM |
| Companies Covered | Brembo S.p.A., ZF Friedrichshafen AG, Aisin Corporation, Robert Bosch GmbH, Tenneco Inc., Nisshinbo Holdings Inc., Mando Corporation, Akebono Brake Industry Co., Ltd., Hitachi Astemo, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake Rotor Market Evolving Landscape
Active thermal management and material science advances are redefining brake rotor performance benchmarks as electrification shifts engineering priorities away from peak friction toward sustained thermal cycling durability.
Two-piece floating rotor designs are integrating aluminum hats with cast iron friction rings to reduce unsprung mass. Performance upgrade specialists and premium OEM fitments are adopting this architecture at accelerating rates. The technology is integrating modular repairability that separates wear components from structural elements, extending service intervals.
ECHA's REACH Annex XVII copper restrictions are forcing friction material reformulation across European supply chains. The regulation eliminates copper content exceeding specified thresholds in brake pads, compelling foundries to validate alternative thermal conductivity enhancers. Aftermarket suppliers serving Germany and France face the steepest compliance curves as national type-approval authorities enforce transitional deadlines.
Fleet operators are consolidating brake rotor procurement through outcome-based maintenance contracts tied to vehicle telematics. Commercial vehicle leasing companies in North America are displacing traditional parts distributor relationships with direct supplier partnerships. This pattern is most visible in long-haul trucking segments where predictive wear algorithms trigger just-in-time replacement scheduling.
Automotive Brake Rotor Market Segmentation
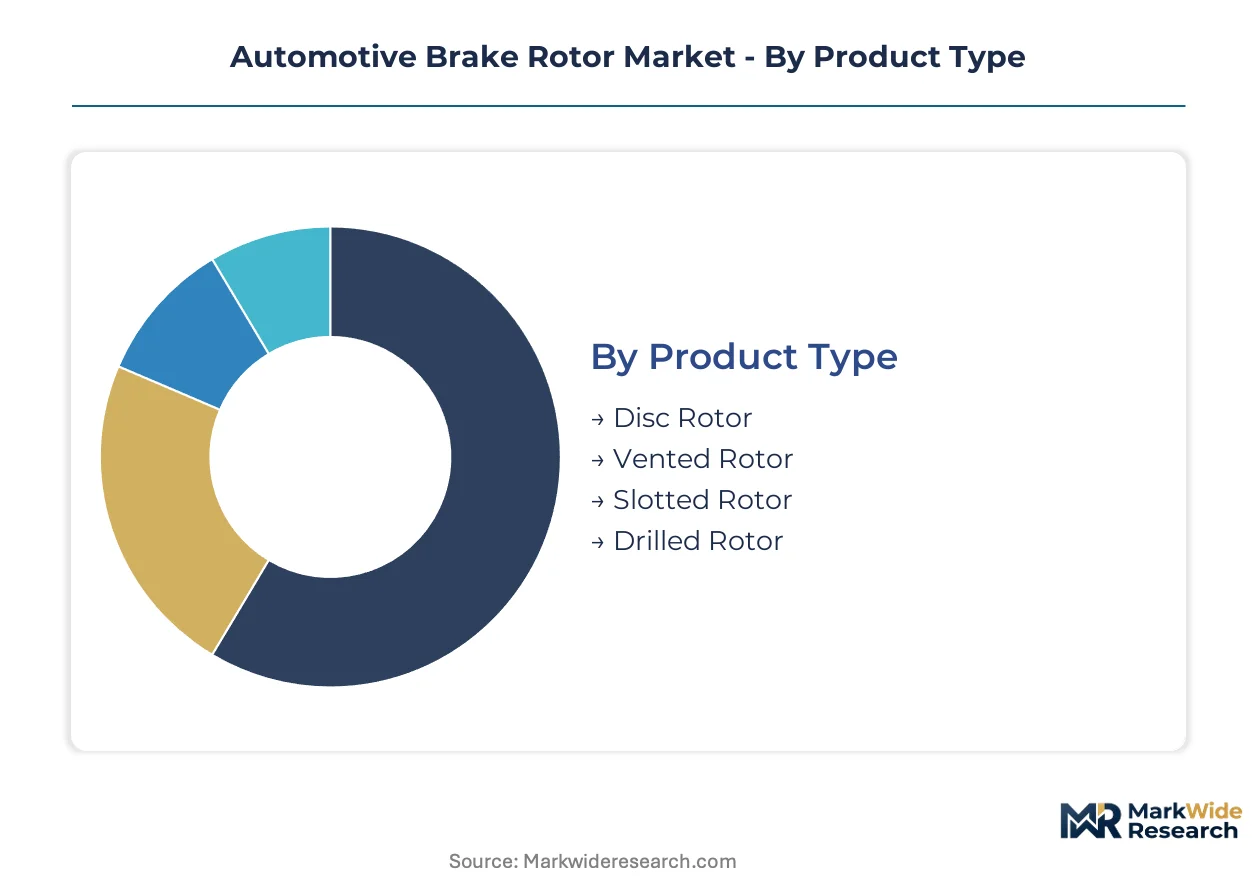
Brake rotor segmentation reveals divergent margin structures across thermal duty cycles and procurement channels. Material selection and architecture choices directly determine foundry capital intensity and OEM design-in success rates.
Product Type:
Volume shipments concentrate in vented architectures, while premium positioning attaches to specialized surface geometries serving performance segments.
- Vented Rotor:Internal channeling architecture accelerates convective heat dissipation through radial vanes. Demand concentrates in SUV and heavy truck applications across the US and China where thermal load profiles exceed solid disc thresholds. ECE R90 homologation requirements favor suppliers with in-house airflow simulation capabilities.
- Disc Rotor:Solid one-piece construction dominates economy passenger car fitments where thermal duty cycles remain moderate. Procurement concentrates with Chinese OEMs integrating cost-optimized brake modules into compact EV platforms. GB 5763 alignment pressures foundries to validate dimensional tolerance protocols.
- Slotted Rotor:Machined surface channels evacuate gas and debris during high-friction events.
- Drilled Rotor:Cross-drilled holes reduce unsprung mass and improve wet-weather bite consistency.
Mature deployment sits with Disc Rotor. Newer deployment is concentrated in Vented Rotor.
Material:
Cost tiers separate commodity foundry outputs from metallurgical specialties commanding design-in premiums.
- Cast Iron:Gray iron alloys deliver thermal capacity and cost efficiency through established high-volume casting processes. Demand concentrates in replacement channels across Germany and the US where service networks prioritize part availability over weight reduction. Scrap iron volatility squeezes margin pools for independent foundries.
- Carbon Composite:Carbon-ceramic matrix composites withstand extreme thermal shock without deformation. Adoption concentrates in motorsport and supercar applications where Brembo anchors premium positioning through F1-derived technology transfer. REACH Annex XVII copper restrictions complicate friction material pairing.
- Aluminum:Hybrid hat constructions reduce unsprung mass in two-piece floating designs.
- Steel:Alloy formulations serve commercial vehicle segments prioritizing durability over thermal performance.
Cast Iron captures replacement volume. Carbon Composite commands the steepest expansion trajectory in OEM performance fitments.
Vehicle Type:
Application scale varies with axle load ratings and regenerative braking integration depth across platform architectures.
- SUV:Higher curb weights and trailer tow ratings demand enhanced thermal mass in brake rotor specifications. Procurement concentrates with US and Chinese automakers scaling three-row electrified platforms where blended braking strategies compress friction duty cycles. Vented rotor penetration exceeds 80% in this segment.
- Truck:Commercial and heavy-duty applications prioritize service interval extension through thermal cycling durability. Fleet operators in North America consolidate procurement through telematics-linked predictive replacement programs. Outcome-based maintenance contracts displace traditional distributor relationships.
- Sedan:Compact and mid-size passenger cars balance cost efficiency with NVH performance.
- Hatchback:Urban-focused platforms favor lightweight solid disc configurations.
SUV anchors current volume. Truck represents the fastest-growing trajectory as commercial electrification accelerates.
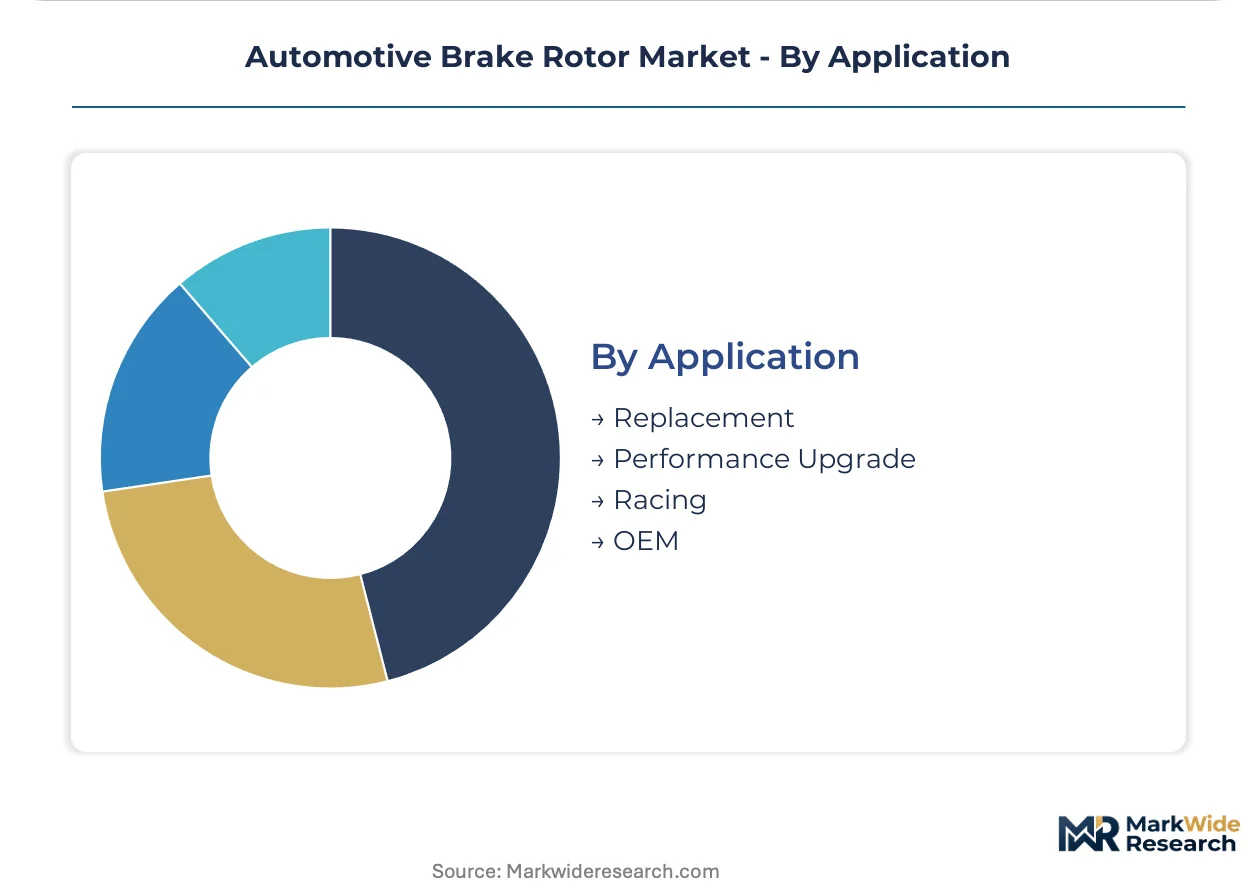
Application:
Channel economics diverge sharply between long-term supply agreements and transactional aftermarket procurement.
- OEM:Design-in relationships lock in multi-year supply agreements with embedded metallurgical development costs. Procurement concentrates with integrated brake module suppliers serving BYD, NIO, and legacy automaker EV platforms. Homologation timeline compression strains testing laboratory capacity.
- Replacement:Aftermarket channels sustain volume through vehicle parc expansion and wear-induced replacement cycles. Robert Bosch GmbH anchors distribution networks through service coverage density in Europe and North America. ECE R90 and GB 5763 compliance elevate barriers for non-certified suppliers.
- Performance Upgrade:Enthusiast segments prioritize thermal fade resistance and modulation precision.
- Racing:Motorsport applications validate technologies migrating to road car programs.
OEM captures margin concentration. Replacement sustains volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gray iron foundry feedstock from the Hebei-Tangshan corridor anchors Chinese production capacity. Scrap steel volatility across Turkish and Russian export markets shapes European foundry input costs. Casting-grade pig iron from Minas Gerais influences Brazilian supplier economics.
China
BYD and NIO are scaling integrated brake platforms for domestic EV production. MIIT enforces GB 5763 friction material standards that accelerate homologation investments. The Hebei-Tangshan industrial corridor concentrates over half of global vented rotor casting capacity.
United States
Fleet operators consolidate commercial vehicle procurement through telematics-linked predictive replacement programs. NHTSA administers FMVSS 135 thermal fade resistance requirements. Detroit-area Tier 1 suppliers anchor OEM supply relationships for electrified truck platforms.
Germany
Brembo leverages motorsport heritage to dominate performance upgrade channels serving enthusiast segments. ECHA REACH Annex XVII copper restrictions force friction material reformulation across supply chains. Stuttgart and Munich industrial zones concentrate brake module engineering for premium OEM fitments.
Japan
Aisin Corporation specializes in integrated brake modules for transplant manufacturing serving export markets. METI oversees JIS standards alignment with ECE R90 homologation protocols. Nagoya-area production clusters supply cast iron rotors for hybrid vehicle platforms.
India
Domestic automakers expand procurement of lightweight rotor designs for compact SUV production. BIS implements friction material testing protocols converging with European ECE standards. Pune and Chennai manufacturing corridors attract foundry investments from Japanese and Korean component suppliers.
Automotive Brake Rotor Market Competitive Landscape
Global majors compete with regional champions across homologation expertise and foundry scale. The vendor base organizes around three tiers: integrated brake module suppliers, standalone rotor foundries, and performance upgrade specialists. Strategic archetypes include metallurgical laboratories with in-house testing protocols, high-volume gray iron casters, and carbon-ceramic matrix composite developers. Competitive moves concentrate on backward integration into scrap iron sourcing and capacity expansion in Chinese industrial corridors.
Within the integrated systems tier, Brembo S.p.A. and Robert Bosch GmbH exemplify divergent positioning archetypes. Brembo S.p.A. occupies a motorsport-derived premium position. Robert Bosch GmbH anchors aftermarket replacement networks through service coverage density. Aisin Corporation represents the Japanese transplant supply model.
| Leading Market Players |
|---|
| Brembo S.p.A. |
| ZF Friedrichshafen AG |
| Aisin Corporation |
| Robert Bosch GmbH |
| Tenneco Inc. |
| Nisshinbo Holdings Inc. |
| Mando Corporation |
| Akebono Brake Industry Co., Ltd. |
| Hitachi Astemo, Ltd. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap foundries in Italy and Japan anchor specialized casting operations, linking generational metallurgical expertise to disciplined pricing power in premium rotor segments while resisting commodity margin erosion.
Pricing Analysis
Warranty bundling separates OEM supply agreements from aftermarket transactions, with long-term service contracts commanding 15-40% premiums over spot replacement purchases. Three-tier pricing structure across premium carbon-ceramic, standard vented gray iron, and economy solid disc configurations stratifies the market. Cost compression in economy tiers intensifies as Chinese foundries scale automated casting lines. Fleet operators exhibit lowest price sensitivity due to outcome-based maintenance contracts, while independent repair shops drive aggressive aftermarket discounting.
Supply Chain Analysis
Single-source vulnerability sits with the Hebei-Tangshan corridor, where over half of global vented rotor casting capacity concentrates in a 200-kilometer industrial zone. Gray iron feedstock draws from Chinese scrap steel recycling, Brazilian pig iron exports, and Turkish ferrous scrap flows. Tariff exposure on US-bound shipments threatens margin structures for Asian exporters. Distribution runs through Tier 1 brake module integrators serving OEM assembly plants, with aftermarket channels fragmenting across national distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive brake rotor market occupies a technology-transition phase as regenerative braking integration displaces conventional friction duty cycles and forces metallurgical reformulation for reduced wear intervals.
For Market Incumbents: Acquire metallurgical testing laboratories with ECE R90 and GB 5763 homologation credentials to compress certification timelines for EV-optimized rotor formulations. Cement design-in relationships with emerging EV-native OEMs before platform architectures freeze. Backward integration into scrap iron sourcing insulates margin pools from Turkish and Russian export volatility.
For New Entrants and Emerging Players: Commercial fleet operators consolidating procurement through telematics-linked predictive replacement programs represent the most penetrable buyer archetype. Target direct-to-fleet channels in North American long-haul trucking, bypassing entrenched distributor relationships. Lead with outcome-based maintenance contracts priced per brake-mile rather than per-unit part sales.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap foundries with stranded gray iron capacity in European industrial zones facing ECHA copper-restriction compliance costs. Five-to-ten year viability hinges on successful pivot toward aluminum-composite hybrid rotor production for electrified platforms. Monitor MIIT enforcement timelines for GB 5763 alignment as inflection indicator for Chinese domestic supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Homologation Laboratory Acquisition | ECE R90 and GB 5763 certification capabilities compress EV platform design-in timelines for Tier 1 suppliers. |
| Scrap Iron Sourcing Integration | Captive supply from Turkish and Russian ferrous scrap flows stabilizes gray iron casting margin pools against export restriction shocks. |
| Fleet Telematics Partnership | Predictive wear algorithms embedded in commercial vehicle leasing contracts displace traditional aftermarket distributor networks. |
| Aluminum-Composite Hybrid Capacity | Two-piece floating rotor production lines serve lightweighting mandates from CAFE standards and EU CO₂ fleet targets. |
| Copper-Free Friction Formulation R&D | REACH Annex XVII compliance creates first-mover advantage in European aftermarket channels facing 2025 enforcement deadlines. |
Research Methodology
Multi-period observation of foundry capacity utilization rates, scrap iron price indices, and EV platform launch schedules anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and metallurgical laboratory certification managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC 10-K filings of listed component suppliers, and MIIT GB standard enforcement notices. Bottom-up triangulation across regional production clusters converged with top-down market sizing from automotive parc expansion models.
Input-output matrices mapped brake rotor content per vehicle across SUV, truck, sedan, and hatchback propulsion architectures, with segmentation dimensions spanning product type, material grade, vehicle class, and application channel. CAGRs derived from regression analysis of historical OEM procurement volumes and replacement cycle compression factors. Forecast inputs incorporated regenerative braking duty cycle reduction coefficients and thermal load specification shifts from integrated brake module designs.
Revisions become necessary when Hebei-Tangshan corridor production disruptions, ECE R90 timeline accelerations, or EV platform architecture cancellations materialize. Deviation in scrap iron export restriction severity from Turkish or Russian supply markets would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Europe Torque Vectoring Market
Automotive Components
Automotive Refrigerant Market
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
Alloys for Automotive Market
Automotive Components
Drive System Market
Automotive Components
Brazil Automotive Composites Market
Automotive Components
Europe and North Africa Automotive Window Regulator Market
Automotive Components
Italy Automotive Sunroof Market
Automotive Components
Automotive Brake Pads Market
Automotive Components
Automotive Transaxle Market
Automotive Components
Automotive Glass Film Market
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
China Automotive Actuators Market
Automotive Components
Europe Automotive Electric Actuators Market