
 Automotive Alloy Wheels Market | 2026-2036
Automotive Alloy Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Alloy Wheels Market Analysis
Buyer concentration among vehicle assemblers is shifting toward long-term supply agreements with forged-wheel specialists. Ronal Group leverages its European casting network to serve premium OEM programs. CITIC Dicastal anchors high-volume aluminum wheel production for mass-market electric vehicle platforms. Superior Industries competes through vertical manufacturing control across North American assembly plant corridors.
Automotive alloy wheels are cast, forged, or flow-formed rims manufactured from aluminum, magnesium, or hybrid metal matrices, engineered to reduce unsprung weight while maintaining radial fatigue resistance and impact durability for vehicle dynamics and fuel efficiency. Lightweight wheels lead OEM fitment programs as manufacturers chase range extension on battery-electric architectures, while forged wheels capture margin pools in sports car and luxury SUV segments where performance specifications command price premiums. Decorative wheels remain mature in aftermarket channels, though smart features with embedded tire-pressure monitoring represent the fastest-growing connectivity dimension.
The US EPA and NHTSA jointly shape alloy wheel demand through corporate average fuel economy standards that reward mass reduction, while the EU's REACH regulation restricts certain alloying elements and surface treatments in European-sourced products. China's SAMR enforces GB standards on wheel fatigue testing that determine market access for domestic and imported suppliers. Stakeholders must monitor regulatory divergence between carbon-accounting frameworks and material certification requirements as procurement criteria harden.
Market Dynamics
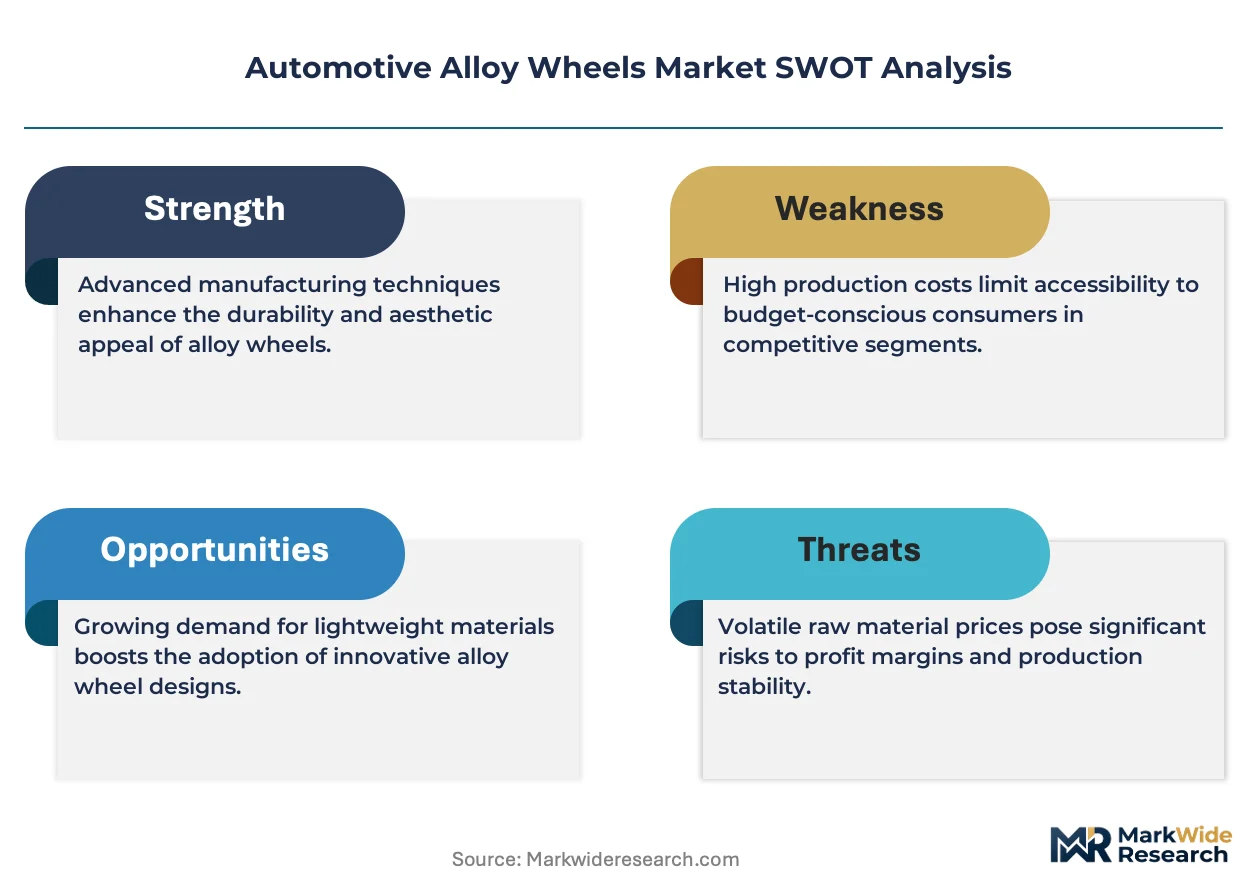
Electric vehicle platform architectures are compressing unsprung mass budgets, forcing wheel suppliers to requalify forged aluminum and magnesium matrix designs for load-bearing performance at reduced weight. This technical mandate is restructuring procurement relationships between vehicle assemblers and tier-one wheel manufacturers.
Growth Catalysts
- EU REACH substance restrictions:European chemical regulations are accelerating substitution of chrome-based surface treatments toward powder-coat and anodized finishes, creating premium positioning for compliant suppliers.
- Forged wheel adoption:Performance electric SUVs and sports car segments specify forged rims for strength-to-weight ratios that cast wheels cannot achieve, expanding addressable margin pools.
- China's Yangtze River Delta:Concentrated battery-electric vehicle assembly capacity in this manufacturing belt generates localized demand for lightweight wheel sourcing within 300-kilometer supply radii.
Market Restraints
- Primary aluminum price volatility:London Metal Exchange pricing swings compress margin visibility for cast wheel producers locked into annual OEM supply agreements.
- Magnesium supply concentration:Chinese smelters control 85 percent of global magnesium output, exposing forged wheel manufacturers to export quota disruptions.
- Fatigue testing certification timelines:China's SAMR GB standards require 18-month validation cycles that delay new wheel design commercialization.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives for advanced manufacturing equipment support greenfield forged wheel capacity serving domestic electric vehicle programs.
- Embedded sensor integration:Tire-pressure monitoring system housings cast directly into wheel spokes enable connectivity differentiation in premium aftermarket channels.
- Closed-loop aluminum recycling:European OEMs specify post-consumer scrap content thresholds that favor wheel suppliers with captive remelt capabilities.
Industry Challenges
- Flow-forming technician scarcity:Specialized machine operators who can program hybrid casting-forging processes command wage premiums that strain mid-volume producers.
- Multi-material bonding certification:Carbon fiber-reinforced aluminum hybrid wheels face fragmented homologation standards across German KBA, US NHTSA, and Chinese SAMR testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Alloy Wheels Market |
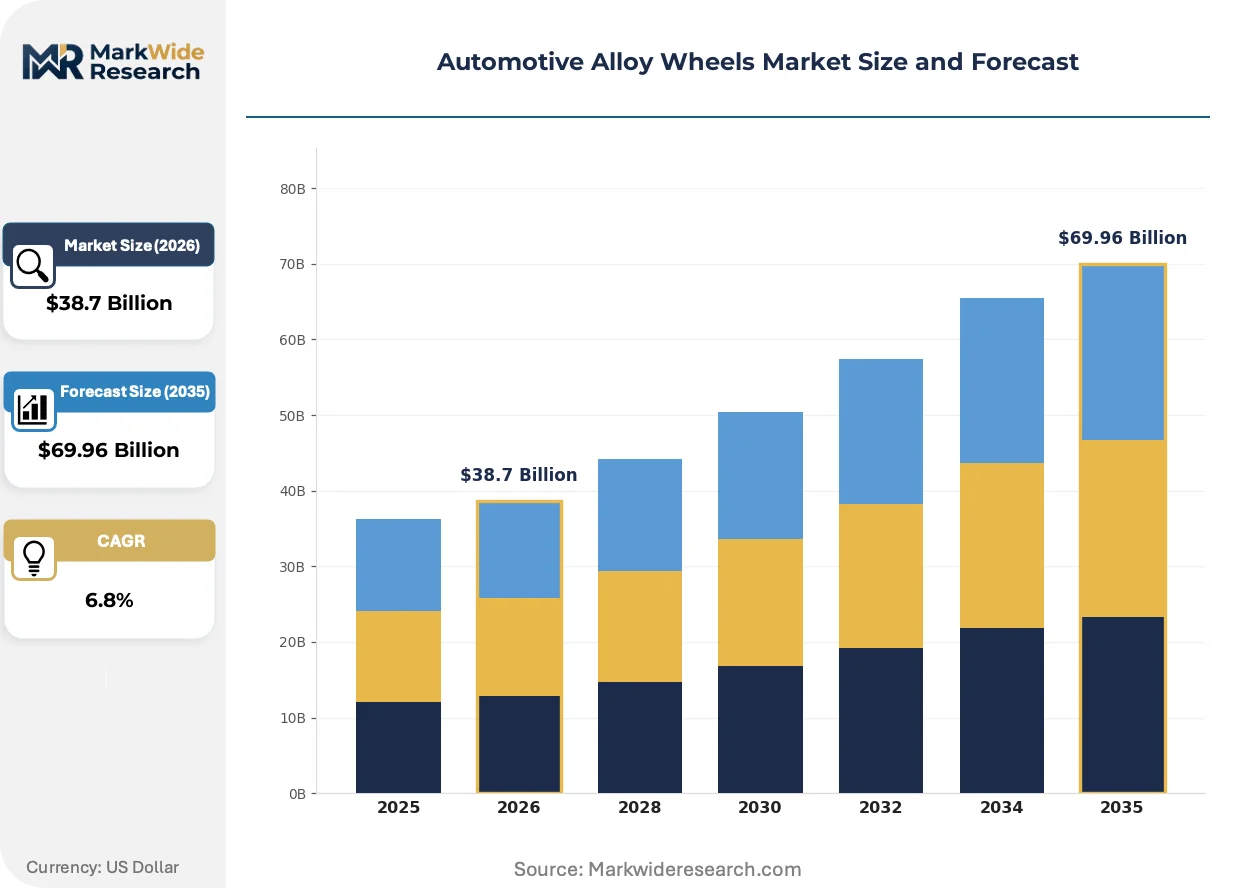
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lightweight Wheels, High-Performance Wheels, Decorative Wheels, Forged Wheels End User: OEMs, Aftermarket Retailers, Auto Parts Distributors, Vehicle Assemblers Application: Passenger Vehicles, Sports Cars, SUVs, Commercial Vehicles Connectivity: Wireless Sensors, Monitoring Systems, Integrated Navigation, Smart Features |
| Companies Covered | Ronal Group, BORBET, CITIC Dicastal, Alcoa Wheels, Superior Industries, Maxion Wheels, BBS, Wanfeng, Enkei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Alloy Wheels Market Emerging Trajectories
Wheel manufacturing is absorbing digital thread technologies that connect design simulation to production telemetry. This integration is compressing development cycles and enabling mass customization at forged-wheel quality levels.
Hybrid metal matrix composites combining aluminum with silicon carbide particles are absorbing impact loads previously requiring thicker cast sections. Performance electric vehicle programs at German and US luxury assemblers specify these materials for 20-inch and larger diameters. The technology is absorbing market share from conventional forged blanks by delivering comparable fatigue resistance at 12-15 percent lower mass.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon use in wheel coating cure ovens, forcing suppliers to convert thermal processes to infrared or induction heating. Industrial consequence includes capital retrofit requirements of 2-4 million euros per production line. Wheel finishers serving European OEM assembly plants are responding by consolidating coating operations into centralized facilities with carbon-capture thermal oxidizers.
Direct-to-fleet procurement models are bypassing traditional tier-one distribution for commercial vehicle wheel replacement. Logistics operators with 10,000-plus truck fleets negotiate wheel supply contracts directly with manufacturers, unbundling tire-and-wheel packages previously sold through dealer networks. This pattern is most visible in German long-haul freight corridors and US interstate trucking lanes where uptime guarantees drive specification authority toward fleet maintenance departments.
Automotive Alloy Wheels Market Segmentation
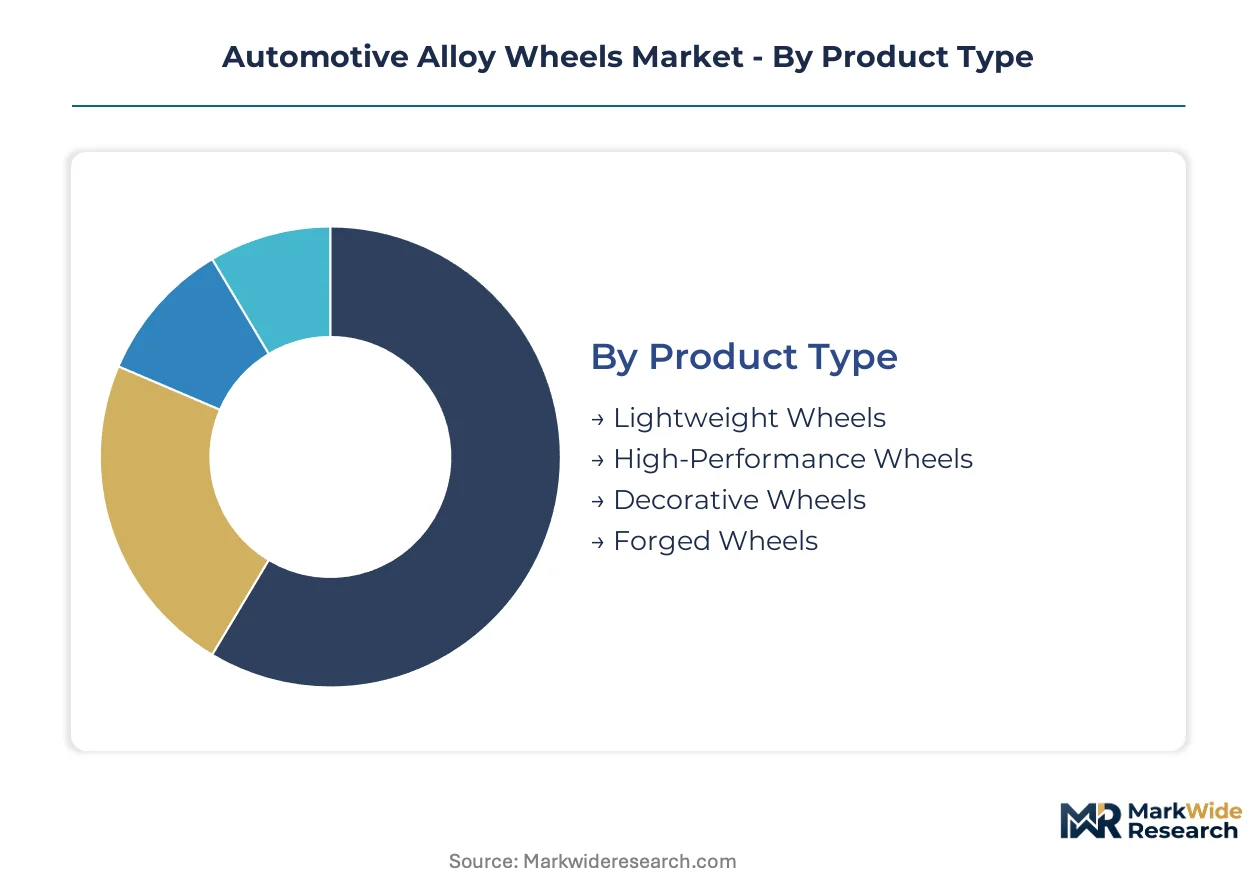
Wheel procurement patterns diverge sharply between vehicle assemblers chasing unsprung mass targets and aftermarket channels prioritizing aesthetic customization. Segment boundaries are blurring as forged designs penetrate mass-market electric platforms and connectivity features migrate from premium to mid-tier fitments.
Product Type:
Cost tier separates volume programs from margin capture opportunities.
- Lightweight Wheels:Cast aluminum and flow-formed designs dominate original equipment fitments where every kilogram of unsprung mass reduction extends electric vehicle range. German premium assemblers and China's Yangtze River Delta battery-electric platforms specify these for 18-inch and larger diameters under strict SAMR GB fatigue standards.
- Forged Wheels:High-pressure aluminum and magnesium matrix blanks deliver strength-to-weight ratios that cast processes cannot replicate. Sports car manufacturers and performance SUV programs in Germany's premium cluster absorb these at price premiums that justify longer machining cycles and specialized heat treatment.
- High-Performance Wheels:Hybrid metal matrix composites with silicon carbide reinforcement target 20-inch plus applications where impact resistance must not compromise rotational inertia.
- Decorative Wheels:Surface-finish-intensive designs prioritize aesthetic differentiation over mass reduction, serving aftermarket retailers with powder-coat and anodized alternatives to REACH-restricted chrome plating.
Lightweight wheels lead volumes today; forged wheels are gaining share fastest.
End User:
Volume scale and specification authority determine procurement relationship structures.
- OEMs:Vehicle assemblers negotiate multi-year supply agreements with forged-wheel specialists, embedding fatigue testing and carbon-accounting requirements directly into contract terms. China's SAMR validation timelines and Europe's REACH substance restrictions shape supplier qualification.
- Vehicle Assemblers:Electric vehicle platform architects compress unsprung mass budgets, forcing wheel suppliers to requalify designs for load-bearing performance at reduced weight. This technical mandate restructures tier-one relationships.
- Aftermarket Retailers:Channels serving enthusiast segments absorb decorative and upsized fitments where smart features with embedded tire-pressure monitoring enable connectivity differentiation.
- Auto Parts Distributors:Traditional wholesale networks face disintermediation as direct-to-fleet procurement models bypass tier-one distribution for commercial vehicle replacement cycles.
OEMs command the largest contract values; vehicle assemblers are consolidating specification authority most aggressively.
Application:
Performance requirements and duty cycles dictate material selection and manufacturing process.
- Passenger Vehicles:Mass-market electric platforms specify flow-formed aluminum wheels balancing cost and unsprung mass reduction. China's Yangtze River Delta manufacturing belt generates concentrated demand within localized supply radii.
- SUVs:Performance electric SUVs specify forged rims for strength-to-weight ratios supporting higher curb weights and towing capacities. German luxury assemblers lead specification intensity.
- Sports Cars:Low-volume programs absorb magnesium matrix and carbon fiber-reinforced aluminum hybrid wheels where fragmented homologation standards across German KBA, US NHTSA, and Chinese SAMR delay commercialization.
- Commercial Vehicles:Fleet operators with 10,000-plus truck fleets negotiate direct manufacturer contracts, unbundling tire-and-wheel packages previously sold through dealer networks in German long-haul corridors and US interstate lanes.
Passenger vehicles anchor volume; SUVs are climbing the fastest on electric platform proliferation.
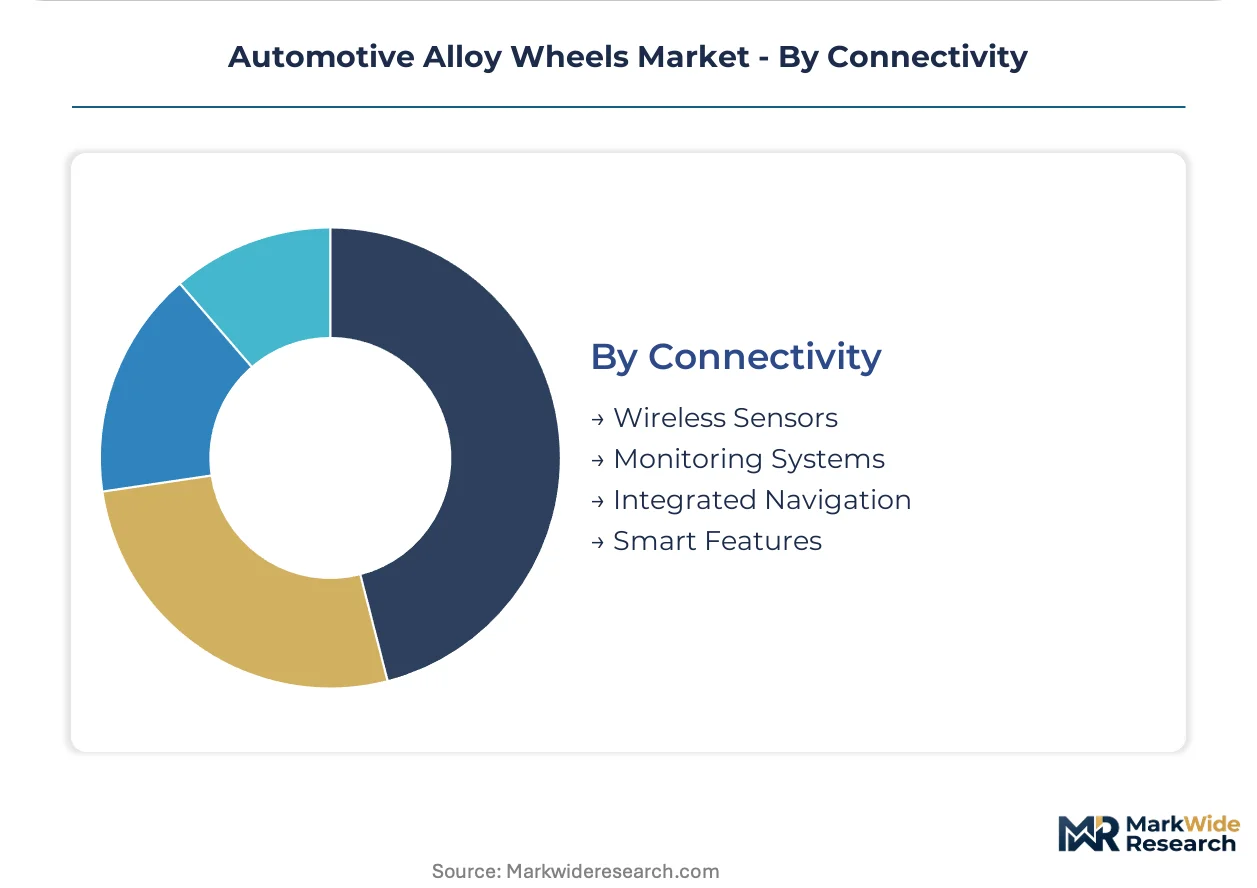
Connectivity:
Feature integration depth separates premium positioning from commodity substitution risk.
- Smart Features:Embedded tire-pressure monitoring system housings cast directly into wheel spokes represent the steepest expansion trajectory. Premium aftermarket channels absorb these for differentiation.
- Monitoring Systems:Real-time telemetry integration enables predictive maintenance contracts valued by logistics fleets prioritizing uptime guarantees over upfront hardware cost.
- Wireless Sensors:Bluetooth-enabled pressure and temperature transmitters retrofit existing wheel inventories, serving price-sensitive segments without spoke-integrated designs.
- Integrated Navigation:Wheel-mounted positioning sensors remain nascent, constrained by multi-material bonding certification complexity and fragmented regulatory testing protocols.
Monitoring systems dominate current fitment; smart features are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized forging technicians and flow-forming machine operators cluster in Germany's precision manufacturing belt and China's Yangtze River Delta industrial corridor, anchoring regional competitive advantages.
Germany
Premium electric SUV and sports car programs from Stuttgart and Munich assemblers drive forged wheel specification intensity. KBA homologation standards enforce rigorous fatigue testing protocols that filter supplier qualification. Bavaria's automotive cluster concentrates magnesium matrix development for performance applications.
China
Battery-electric vehicle assembly capacity in the Yangtze River Delta generates localized demand within 300-kilometer supply radii. SAMR GB standards mandate 18-month validation cycles for new wheel designs entering the market. CITIC Dicastal anchors high-volume aluminum wheel production serving mass-market electric platforms from Shanghai to Hangzhou.
United States
Corporate average fuel economy standards from EPA and NHTSA reward unsprung mass reduction in electric vehicle architectures. Long-haul freight fleet operators in interstate trucking corridors negotiate direct manufacturer contracts for commercial vehicle wheel replacement. Michigan and Ohio assembly plant corridors sustain North American procurement concentration.
India
Production-linked incentive schemes for advanced auto components support greenfield forged wheel capacity serving domestic electric vehicle programs. BIS certification requirements align with international fatigue testing norms for OEM supply qualification. Tamil Nadu and Maharashtra manufacturing belts attract wheel supplier investments targeting localized sourcing mandates.
Japan
Hybrid metal matrix composite development targets 20-inch plus applications for luxury electric vehicle programs. METI industrial policy prioritizes lightweight material innovation in automotive supply chains. Kansai region technical institutes collaborate with wheel manufacturers on silicon carbide reinforcement processing.
Automotive Alloy Wheels Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base organizes around three strategic archetypes: European casting network operators serving premium OEM programs, Chinese high-volume producers anchoring mass-market electric platforms, and North American vertically integrated manufacturers controlling assembly plant corridors. Dominant competitive moves include backward integration into aluminum remelt capabilities and geographic expansion through greenfield forging capacity.
Among European-based specialists, Ronal Group and BORBET exemplify the casting network archetype serving premium fitment programs. CITIC Dicastal represents the scale-driven Chinese producer position. Superior Industries occupies a position within North American corridor-focused manufacturing. These three anchors illustrate how procurement consolidation favors suppliers with captive technical capabilities and regional production proximity to vehicle assembly.
| Leading Market Players |
|---|
| Ronal Group |
| BORBET |
| CITIC Dicastal |
| Alcoa Wheels |
| Superior Industries |
| Maxion Wheels |
| BBS |
| Wanfeng |
| Enkei |
| Others |
Supply Flow & Price Mechanics
Specialized flow-forming machine operators in Germany's precision manufacturing belt and China's Yangtze River Delta command wage premiums that widen spreads between forged-wheel and cast-wheel pricing tiers, compressing mid-volume producers caught between labor-intensive quality demands and commodity aluminum cost floors.
Pricing Analysis
Bundled tire-and-wheel packages dominate dealer networks while direct-to-fleet procurement unbundles these services for commercial vehicle replacement. Three-tier pricing structure across premium forged, standard flow-formed, and economy cast levels separates OEM supply agreements from aftermarket retail channels. Pricing pressure stems from London Metal Exchange aluminum volatility locking cast producers into fixed annual contracts. Fleet operators with 10,000-plus truck fleets exhibit lowest price sensitivity due to uptime guarantee priorities, while mid-volume aftermarket retailers face highest substitution risk from imported alternatives.
Supply Chain Analysis
Single-source vulnerability sits with Chinese smelters controlling 85 percent of global magnesium output, exposing forged-wheel manufacturers to export quota disruptions. Primary aluminum draws from Australian bauxite and Chinese refining capacity, while silicon carbide reinforcement feeds from Japanese and US specialty ceramics producers. Tariff exposure runs through trans-Pacific raw material flows and finished wheel shipments to European OEM assembly plants. Distribution runs through tier-one supplier networks for OEM fitment and direct manufacturer contracts for fleet replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive alloy wheel manufacturing operates as a geographic-arbitrage play where India's production-linked incentive schemes offer 25-30 percent capital cost advantages against European REACH compliance burdens, redirecting greenfield forging investments toward Tamil Nadu and Maharashtra.
For Market Incumbents: Lock in long-term supply agreements with Yangtze River Delta battery-electric vehicle assemblers before localized sourcing mandates harden. Backward integration into captive aluminum remelt capabilities defends margin position against London Metal Exchange volatility. Certification investment in China's SAMR GB fatigue testing protocols preserves market access as validation timelines extend. For New Entrants and Emerging Players: Launch via direct-to-fleet distribution models targeting German long-haul freight corridors and US interstate trucking lanes where uptime guarantees override brand loyalty. India's electric vehicle component incentives represent the most penetrable geography for greenfield forged capacity. Embedded sensor integration for tire-pressure monitoring systems offers the clearest product differentiation angle against commodity cast competitors. For Investors and Strategic Acquirers: Tier 1 automotive suppliers with electric vehicle platform expertise are the most active acquirer in this space, seeking wheel manufacturers with SAMR-validated designs and regional production proximity. The acquisition target archetype combines flow-forming technical capabilities with captive remelt operations serving European post-consumer scrap thresholds. Watch magnesium export quota announcements from Chinese regulatory authorities as the critical inflection signal for forged-wheel input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Remelt | Captive scrap processing meets European OEM post-consumer content thresholds. |
| Embedded Sensor Platform Development | Tire-pressure monitoring housings cast into spokes enable premium aftermarket positioning. |
| Greenfield Forging Capacity in India | PLI scheme support reduces capital intensity for domestic electric vehicle supply. |
| SAMR Certification Pre-Investment | Early GB fatigue testing engagement compresses 18-month validation cycles. |
| Direct Fleet Distribution Partnerships | Logistics operators with 10,000-plus trucks unbundle traditional tier-one channels. |
Methodological Framework
Direct dialogue with OEM platform engineers, tier-one supplier procurement leads, aftermarket distributor operations heads, and flow-forming machine technicians grounded qualitative findings in production-floor realities. Secondary validation drew from vehicle production databases, IHS Markit registration data, London Metal Exchange pricing records, and SAMR regulatory filings. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Top-down macroeconomic drivers filtered through bottom-up segment elasticity models. Segmentation dimensions included vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from fitted growth curves applied to disclosed production volumes and average selling price trajectories. Forecast inputs incorporated battery-electric platform rollout schedules and REACH substance restriction phase-in timelines.
Several conditions sit outside the modeled scope, including unforeseen alloy substitution breakthroughs, abrupt magnesium export quota suspensions, and non-linear electric vehicle adoption curves. Forecasts reflect documented assumptions about regulatory stability and raw material supply continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Automotive Tire Analytics Market
Tires and Wheels
Automotive Wheel Spindle Market
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
Heavy Duty Tire Market
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Self-Sealing Tire Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
Tire Retreading Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Bike Wheels Market
Tires and Wheels
Specialty Tire Market