
 Global Automotive Tire Socks Market | 2026-2036
Global Automotive Tire Socks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Tire Socks Market Analysis
Automotive parts stores is narrowing its role as the dominant fulfillment channel for tire socks across European alpine regions. AutoSock Operations AS leverages its Nordic manufacturing base to sustain direct-to-fleet relationships with municipal transport departments. Michelin Group anchors its position through co-development programs with OEM winter-accessory catalogs. Continental AG competes via specialized textile engineering partnerships that reduce installation time for commercial drivers.
Automotive tire socks are high-friction textile sleeves engineered from woven aramid and polyamide blends, designed to stretch over standard tires and provide temporary traction on snow or ice without metallic chain damage to road surfaces. The product typically achieves operational effectiveness at temperatures below seven degrees Celsius and speeds under fifty kilometers per hour, serving both regulatory compliance and physical mobility needs in winter jurisdictions. Snow socks dominate current volume as the established product form, while textile chains capture expanding share through lighter weight and faster deployment protocols favored by rental companies. Fleet operators represent the fastest-growing end-user category as logistics providers standardize winter-preparedness protocols across multi-country routes.
Norwegian Public Roads Administration winter-equipment statutes, Austrian winter-tire mandate frameworks, and Japan Ministry of Land Infrastructure Transport and Tourism snow-region vehicle codes collectively shape product certification requirements and seasonal demand peaks. ECE Regulation 117 testing protocols further define traction-performance thresholds that manufacturers must satisfy for European market access. Stakeholders should monitor evolving national enforcement calendars and textile-durability standards to align inventory positioning with regulatory-driven replacement cycles.
Market Dynamics
EU winter-equipment mandates are compressing replacement cycles and forcing fleet operators toward standardized textile traction protocols across alpine logistics corridors.
Growth Catalysts
- ECE Regulation 117 traction thresholds:Certification requirements under this European framework compel commercial vehicle operators to maintain compliant winter equipment inventories, creating recurring procurement cycles.
- Aramid-polyamide blend engineering:Advanced textile weaving techniques deliver higher friction coefficients at reduced weight, accelerating adoption among rental fleets prioritizing rapid deployment.
- Norwegian Public Roads Administration statutes:Mandatory winter-equipment provisions on designated mountain passes generate concentrated seasonal demand spikes that sustain manufacturer order books.
Market Restraints
- Petrochemical feedstock volatility:Synthetic fiber production depends on polyamide precursor availability, exposing margins to naphtha and benzene price swings.
- Temperature-velocity operating envelope:Product effectiveness collapses above seven degrees Celsius and fifty kilometers per hour, limiting addressable use cases to strict climatic conditions.
- Metallic chain substitution in extreme terrain:Heavy commercial operators in severe ice conditions revert to traditional steel chains despite road-surface damage risks.
Strategic Opportunities
- Japan Ministry of Land Infrastructure Transport and Tourism snow-region codes:Expanding certification reciprocity with European standards opens direct export pathways for compliant manufacturers.
- Direct-to-fleet digital procurement platforms:Municipal transport departments are consolidating vendor relationships through integrated ordering systems that bypass traditional automotive parts stores.
- Textile-chain hybrid formats:Lighter-weight constructions with reinforced gripping elements address rental company preferences for faster installation without sacrificing traction performance.
Industry Challenges
- ECE 117 homologation timelines:Testing protocol completion for new textile formulations extends twelve to eighteen months, delaying product launches across multiple winter seasons.
- Installation training standardization:Commercial driver certification for proper tire sock deployment varies across national transport authorities, complicating cross-border fleet operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Tire Socks Market |
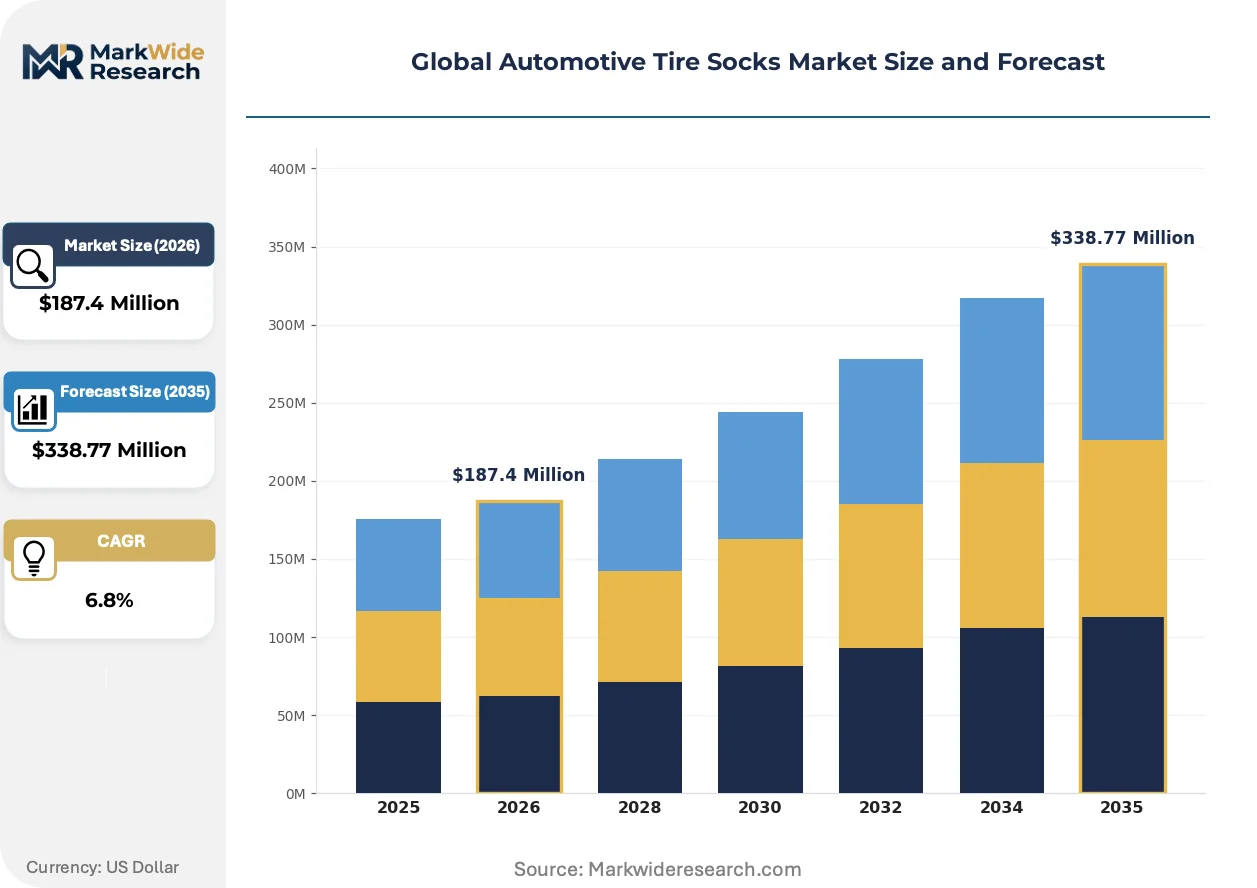
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snow Socks, Textile Chains, Rubber Chains, All-Weather Socks End User: Individual Consumers, Fleet Operators, Rental Companies, Government Agencies Vehicle Type: Passenger Vehicles, Light Trucks, Commercial Vehicles, SUVs Distribution Channel: Online Stores, Retail Outlets, Automotive Parts Stores, Wholesale Dealers |
| Companies Covered | AutoSock Operations AS, Michelin Group, Goodyear Tire & Rubber Company, ISSE Safety, Bridgestone Corporation, Continental AG, Thule Group, Weissenfels, Joubert Productions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Tire Socks Market Emerging Trajectories
Material science advances and procurement digitization are restructuring how winter traction equipment reaches end users. Three developments warrant particular attention.
Self-tensioning textile architectures incorporating elastic memory fibers are rendering obsolete manual adjustment protocols that previously required driver intervention during installation. Rental fleet operators in Austria and Switzerland have standardized on these formats, cutting roadside deployment time from four minutes to under ninety seconds. The compression of installation labor is shifting competitive advantage toward manufacturers with proprietary weaving equipment.
EU Green Deal circular-economy provisions are mandating recyclability disclosures for automotive accessories sold into member states. Textile manufacturers must now document fiber recovery pathways and restricted substance compliance under REACH annex restrictions. Nordic producers with established closed-loop material programs capture preferential placement in municipal procurement tenders.
Fleet operators are consolidating vendor relationships through multi-year framework agreements that bundle tire socks with telematics-based winter-readiness monitoring. Automotive parts stores lose volume to direct manufacturer contracts as logistics providers standardize equipment protocols across transalpine routes. German and Austrian freight consolidators have pioneered this model, with similar structures emerging in Japanese mountain-pass logistics corridors.
Global Automotive Tire Socks Market Segmentation
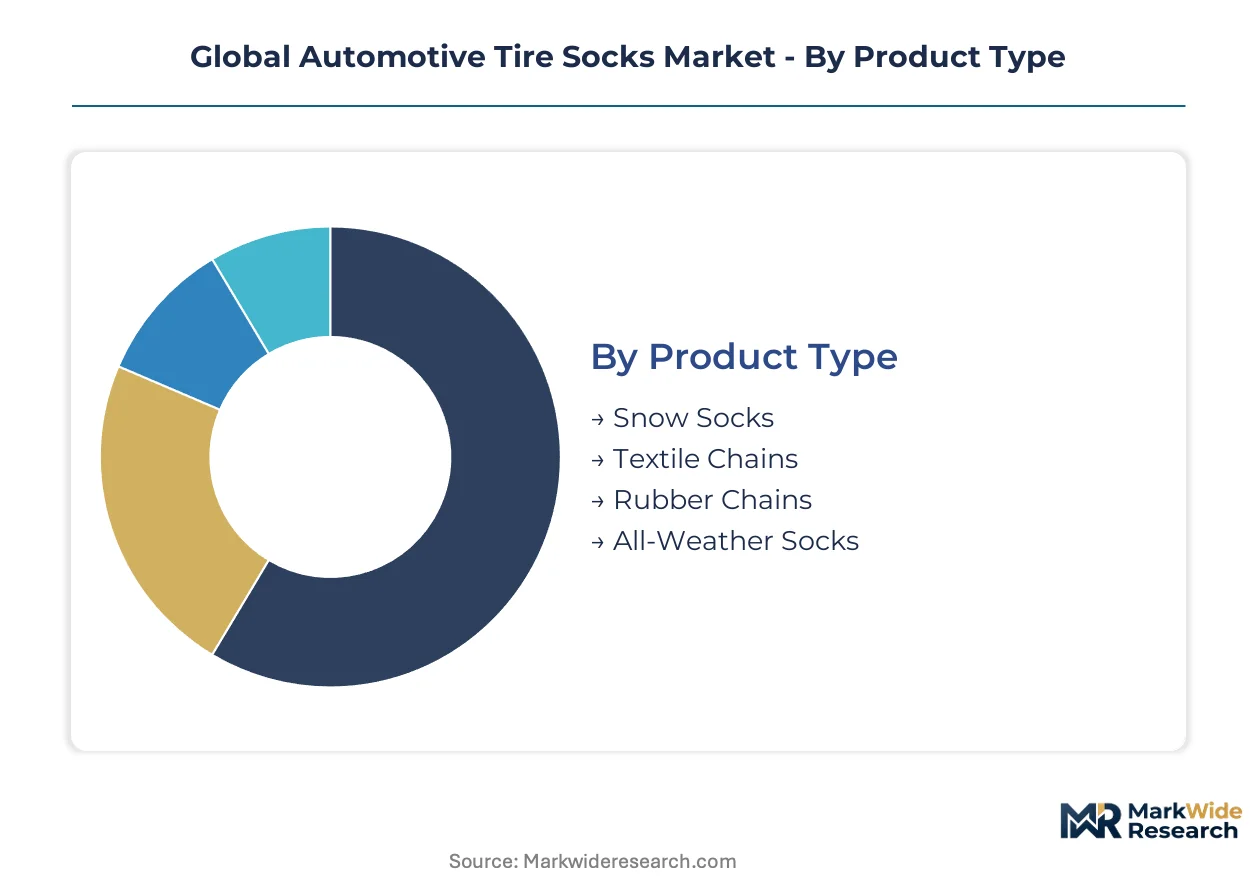
Segmentation in the automotive tire socks market reveals divergent procurement patterns between regulatory-driven fleet buyers and discretionary consumer purchases. Material composition and installation protocols vary sharply across product categories, creating distinct margin profiles and channel requirements.
Product Type:
Mature woven formats dominate current revenue, while emerging hybrid constructions reshape competitive positioning.
- Snow Socks:Traditional woven aramid-polyamide sleeves deliver proven traction below seven degrees Celsius. Norwegian mountain-pass mandates and Austrian winter-equipment statutes sustain replacement cycles among alpine fleet operators.
- Textile Chains:Reinforced gripping elements integrated into lighter textile substrates cut deployment time to under ninety seconds. Rental companies in Switzerland and Austria have standardized procurement on these formats for roadside efficiency.
- Rubber Chains:Elastomer-based traction aids serve heavy commercial applications where textile durability proves insufficient.
- All-Weather Socks:Multi-condition formulations extend operational range beyond strict winter parameters for temperate-zone consumers.
Snow Socks retain volume leadership; Textile Chains hold the steepest expansion curve.
End User:
Procurement concentration varies by buyer scale and regulatory exposure.
- Fleet Operators:Logistics providers standardizing winter-preparedness protocols across transalpine routes generate the steepest demand trajectory. Multi-year framework agreements with manufacturers displace automotive parts store volumes.
- Rental Companies:Rapid roadside deployment requirements drive preference for self-tensioning textile architectures. Austrian and Swiss rental fleets have cut installation labor through standardized procurement.
- Individual Consumers:Discretionary purchasers respond to seasonal enforcement calendars in Japan's snow-region prefectures and EU alpine jurisdictions.
- Government Agencies:Municipal transport departments in Norway consolidate vendor relationships through direct digital procurement platforms.
Fleet Operators capture the fastest volume gains; Individual Consumers provide seasonal demand stability.
Vehicle Type:
Weight-class specifications dictate textile engineering requirements and certification thresholds.
- Commercial Vehicles:Heavy-duty aramid weaves withstand axle loads on Norwegian Public Roads Administration designated corridors. ECE Regulation 117 homologation mandates compel maintained equipment inventories.
- Light Trucks:Mid-weight constructions balance traction performance with fuel economy considerations for regional logistics providers.
- Passenger Vehicles:Compact formats prioritize storage efficiency and single-driver installation for consumer markets.
- SUVs:Oversized tire dimensions require specialized sizing protocols that constrain manufacturer SKU economics.
Commercial Vehicles anchor regulatory compliance demand; Light Trucks expand most quickly through rental fleet standardization.
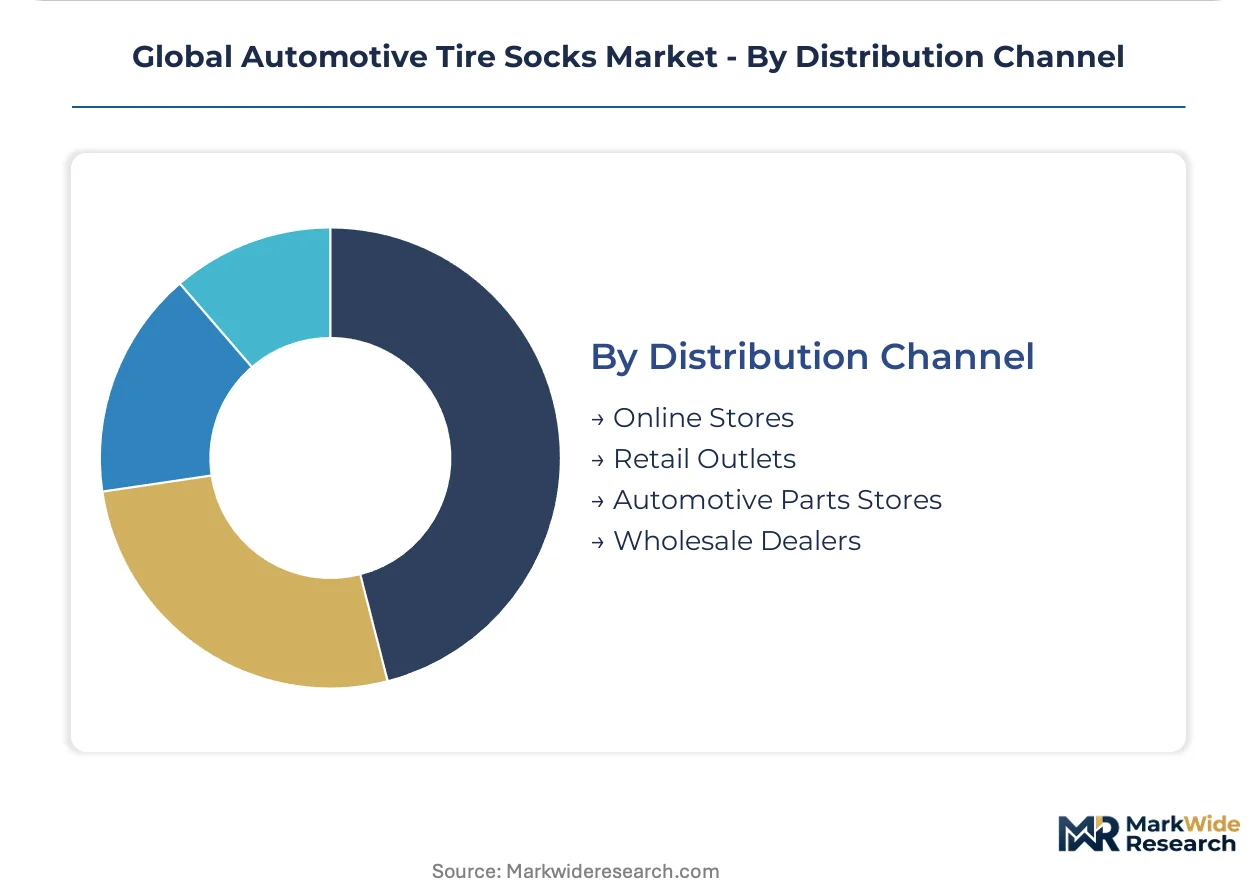
Distribution Channel:
Channel structure reflects buyer consolidation and procurement digitization trends.
- Automotive Parts Stores:Traditional fulfillment role narrows as fleet operators bypass intermediaries. Remaining volume concentrates in alpine region retail networks serving individual consumers.
- Online Stores:Direct-to-fleet digital platforms enable municipal transport departments to consolidate vendor relationships. German and Austrian freight consolidators pioneered integrated ordering systems.
- Retail Outlets:Seasonal pop-up installations persist in Japanese mountain-pass corridors and Norwegian tourist routes.
- Wholesale Dealers:Bulk procurement intermediaries serve rental company networks requiring standardized inventory across multiple locations.
Automotive Parts Stores retain consumer-facing volume; Online Stores gain share fastest through fleet procurement migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Norway exceeds that in Japan by a meaningful margin, reflecting stricter enforcement calendars and higher fleet-operator procurement concentration. Alpine corridor logistics in Austria and Switzerland generate comparable premiums, while German freight consolidators extract volume discounts through multi-year framework agreements.
Norway
Mountain-pass mandates on designated corridors drive concentrated seasonal demand spikes among municipal transport departments. The Norwegian Public Roads Administration enforces winter-equipment statutes that compress replacement cycles to 24-36 months. Tromsø and Bergen clusters anchor Nordic manufacturing relationships with direct-to-fleet digital procurement platforms.
Japan
Snow-region prefectures in Hokkaido and Tohoku generate regulatory-driven procurement from logistics providers standardizing winter protocols. The Ministry of Land Infrastructure Transport and Tourism maintains vehicle codes that shape product certification requirements and seasonal enforcement calendars. Nagano and Niigata mountain-pass corridors concentrate rental fleet standardization on rapid-deployment textile formats.
Austria
Alpine logistics corridors sustain replacement cycles among transalpine freight operators navigating winter-tire mandate frameworks. ECE Regulation 117 testing protocols define traction-performance thresholds for European market access. Tyrol and Salzburg transport clusters prioritize self-tensioning textile architectures that cut roadside deployment time below ninety seconds.
Germany
Freight consolidators pioneered multi-year framework agreements bundling tire socks with telematics-based winter-readiness monitoring. The KBA enforces type-approval standards that align with broader European homologation timelines. Bavarian and Baden-Württemberg logistics hubs drive procurement digitization that bypasses traditional automotive parts store intermediaries.
Switzerland
Rental fleet operators standardized procurement on lighter textile-chain formats for roadside efficiency across alpine tourist routes. Cantonal transport authorities coordinate with European standards for cross-border fleet operations. Zurich and Geneva logistics clusters concentrate demand for rapid-deployment protocols favored by multi-location rental networks.
Global Automotive Tire Socks Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying woven textile substrates and elastic memory fibers. The vendor base organizes around three strategic archetypes: Nordic direct-to-fleet manufacturers, diversified tire OEMs with winter-accessory catalogs, and specialized textile engineering houses. Consolidation pressures favor players with proprietary weaving equipment and established ECE 117 homologation track records. Dominant competitive moves include backward integration into aramid fiber supply and geographic expansion through certification reciprocity agreements.
Among Nordic manufacturers, AutoSock Operations AS exemplifies the direct-to-fleet archetype with its municipal transport department relationships. Michelin Group and Continental AG represent diversified tire OEMs leveraging co-development programs and textile engineering partnerships respectively. These three anchors illustrate how competitive positioning diverges between specialized regional players and global diversified suppliers.
| Leading Market Players |
|---|
| AutoSock Operations AS |
| Michelin Group |
| Goodyear Tire & Rubber Company |
| ISSE Safety |
| Bridgestone Corporation |
| Continental AG |
| Thule Group |
| Weissenfels |
| Joubert Productions |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock volatility in polyamide precursor markets determines both the premium spread for aramid-reinforced tire socks and the geographic clustering of Nordic weaving operations. Manufacturers with captive fiber supply or long-term benzene offtake agreements command pricing power over competitors exposed to spot naphtha markets.
Pricing Analysis
Configured-to-order pricing for fleet-specific sizing and ECE 117 certification tiers commands substantial premiums over standard retail SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by textile durability ratings and installation speed protocols. Cost compression in economy-grade snow socks is intensifying as automotive parts stores consolidate purchasing power. Rental companies exhibit the lowest price sensitivity due to roadside deployment efficiency requirements, while individual consumers in Japanese snow regions drive volume through seasonal discounting.
Supply Chain Analysis
Supplier-financing facilities from Nordic textile equipment vendors enable smaller manufacturers to access proprietary weaving technology without upfront capital outlay. Raw material sourcing concentrates in Germany, Belgium, and Norway for aramid fiber and polyamide precursors. Production draws from petrochemical feedstocks tethered to naphtha and benzene contract markets. Single-source vulnerability in specialized elastic memory fiber supply creates chokepoint risk for self-tensioning textile architectures. Distribution runs through direct-to-fleet digital platforms that bypass traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive tire socks market sits at an inflection driven by ECE Regulation 117 homologation timelines compressing product development cycles. EU Green Deal circular-economy provisions are accelerating material recovery pathway investments among Nordic producers.
For Market Incumbents: Harden supply chain resilience through backward integration into aramid fiber production or exclusive precursor offtake agreements with Belgian and German petrochemical suppliers. Invest in proprietary weaving equipment to defend margin position against textile-engineering houses entering through ECE 117 certification reciprocity. Prioritize closed-loop material recovery programs to secure preferential placement in municipal procurement tenders. For New Entrants and Emerging Players: Establish a beachhead in Japanese mountain-pass logistics corridors where rental fleet standardization on rapid-deployment formats creates vendor consolidation opportunities. Target textile-chain hybrid formats for Austrian and Swiss rental networks seeking sub-ninety-second installation protocols. Pursue direct digital procurement platform integration with German freight consolidators pioneering multi-year framework agreements. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors manufacturers with established ECE 117 homologation track records and proprietary weaving equipment. Long-term viability hinges on certification reciprocity agreements enabling geographic expansion without twelve-to-eighteen-month testing delays. Monitor Japan Ministry of Land Infrastructure Transport and Tourism code harmonization with European standards as the signal indicating accelerated export pathway opening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber Supply | Captive precursor sourcing insulates margins from naphtha volatility affecting Belgian and German suppliers. |
| ECE 117 Homologation Investment | Testing protocol completion secures European market access and compresses competitive launch timelines. |
| Direct-to-Fleet Digital Platform Launch | Bypassing automotive parts store intermediaries captures municipal transport department procurement consolidation. |
| Closed-Loop Material Recovery Program | EU Green Deal compliance documentation unlocks preferential Nordic municipal tender placement. |
| Textile-Chain Hybrid Format Development | Reinforced gripping elements address Austrian and Swiss rental fleet roadside efficiency requirements. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade customs data, ECE homologation registries, and EU regulatory filings. Interviews with fleet procurement directors, textile engineering specialists, municipal transport department contracting officers, and automotive aftermarket distributors informed demand-side segmentation. Secondary validation drew from Norwegian Public Roads Administration enforcement calendars, Japan Ministry of Land Infrastructure Transport and Tourism vehicle code amendments, and REACH annex restriction updates. Bottom-up unit economics triangulated against top-down market sizing across product type and end-user dimensions.
Forecast inputs incorporate vehicle registration data from alpine corridor jurisdictions, rental fleet standardization timelines, and petrochemical feedstock price indices. Modeled segmentation spans product format, end-user category, vehicle weight class, and regional regulatory cluster. CAGRs derive from regression analysis of historical procurement cycles against enforcement calendar shifts. Industry-specific inputs include ECE 117 testing queue lengths and municipal framework agreement renewal patterns across the projection horizon.
Sensitivities concentrate around ECE 117 protocol amendments, REACH substance restriction expansions, and petrochemical feedstock volatility. Forecasts embed assumptions regarding certification reciprocity progression and fleet procurement digitization adoption curves. Macroeconomic contraction in alpine logistics corridors, regulatory timeline delays, or breakthrough metallic chain alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Kuwait Tyres Market
Tires and Wheels
Tire Building Machinery Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Automotive Wheel Alignment Service Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Europe 2-Wheeler Replacement Tire Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Russia OTR Tire Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Southeast Asian Tire Market
Tires and Wheels
Automotive 3D Printed Tires Market