
 All-Terrain Vehicle Tire Market | 2026-2036
All-Terrain Vehicle Tire Market Size, Share, and Industry Trends Forecast 2026-2036
All-Terrain Vehicle Tire Market Outlook
DOT FMVSS 119 certification for pneumatic tires is redrawing competitive boundaries for highway-legal ATV tire variants. Bridgestone Corporation leverages its motorsport R&D pipeline to sustain premium positioning in knobby and trail categories. Titan International anchors its presence through captive rubber processing and vertical control over wheel-tire assemblies for agricultural OEM channels. Michelin S.E. differentiates via silica-infused compound technology that extends tread life across extreme temperature ranges.
All-terrain vehicle tires are pneumatic or solid structures engineered with reinforced sidewalls, multi-angle tread blocks, and bias or radial carcass constructions to deliver traction across loose rock, mud, sand, and packed soil surfaces. These tires typically operate at inflation pressures between 2.5 and 10 psi for soft-terrain flotation, with carcass plies of nylon, polyester, or aramid to resist puncture and deformation under uneven loads. Knobby tires occupy the largest revenue share due to universal fitment across utility and sport ATV platforms, while mud tires command premium pricing from specialized lug geometries and self-cleaning void ratios. Trail tires compete on durability metrics for high-mileage recreational users, whereas sand tires remain a niche segment with paddle-style tread patterns concentrated in coastal dune and desert racing applications.
EPA non-road emissions regulations under 40 CFR Part 1054 constrain tire-vehicle matching for engine compliance, while NHTSA FMVSS standards govern on-road ATV conversions sold in the United States. OSHA workplace safety directives affect commercial fleet tire maintenance protocols for agricultural and industrial ATV deployments. Stakeholders must monitor evolving state-level trail access legislation and federal tariff structures on imported rubber compounds to anticipate supply cost shifts and channel reconfiguration.
Market Dynamics
EPA non-road emissions standards under 40 CFR Part 1054 are compressing tire-vehicle matching windows and forcing compound reformulation investments across the supply base.
Growth Catalysts
- Desert racing tourism:Off-road recreational parks in Arizona, Nevada, and Utah draw rising visitor volumes seeking rugged trail experiences, concentrating replacement tire demand in the American Southwest.
- Low-rolling-resistance mandates:EPA emissions standards for non-road spark-ignition engines push manufacturers toward advanced tread compounds that reduce fuel consumption without sacrificing traction.
- Highway-legal conversions:DOT FMVSS 119 certification requirements for pneumatic tires expand the addressable market for street-capable ATV variants used in mixed-terrain commercial fleets.
Market Restraints
- Natural rubber price volatility:Input costs fluctuate with Southeast Asian supply disruptions and currency movements, compressing margin buffers for compound-dependent manufacturers.
- Thai and Indonesian supply concentration:Over 70 percent of natural rubber originates from two countries, exposing tire makers to geopolitical and climate-related supply interruptions.
- Aramid fiber technical limitations:High-performance carcass materials face puncture-resistance trade-offs in extreme cold, restricting deployment in northern latitude applications.
Strategic Opportunities
- Silica-infused compound convergence:Advanced filler technology combined with dual-cure processing extends tread life across temperature extremes, opening premium positioning in high-mileage recreational segments.
- Direct-to-consumer channel expansion:E-commerce platforms and manufacturer-owned digital storefronts bypass traditional distributor markups, capturing margin and customer data simultaneously.
- IRA clean energy incentives:United States domestic manufacturing credits support reshoring of rubber processing and tire assembly operations to serve North American demand clusters.
Industry Challenges
- Compound formulation talent scarcity:Specialized polymer chemists capable of balancing rolling resistance, wear rate, and wet traction metrics command premium compensation and extended recruitment timelines.
- FMVSS 119 certification complexity:Highway-legal tire variants require extensive testing protocols and documentation, extending product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | All-Terrain Vehicle Tire Market |
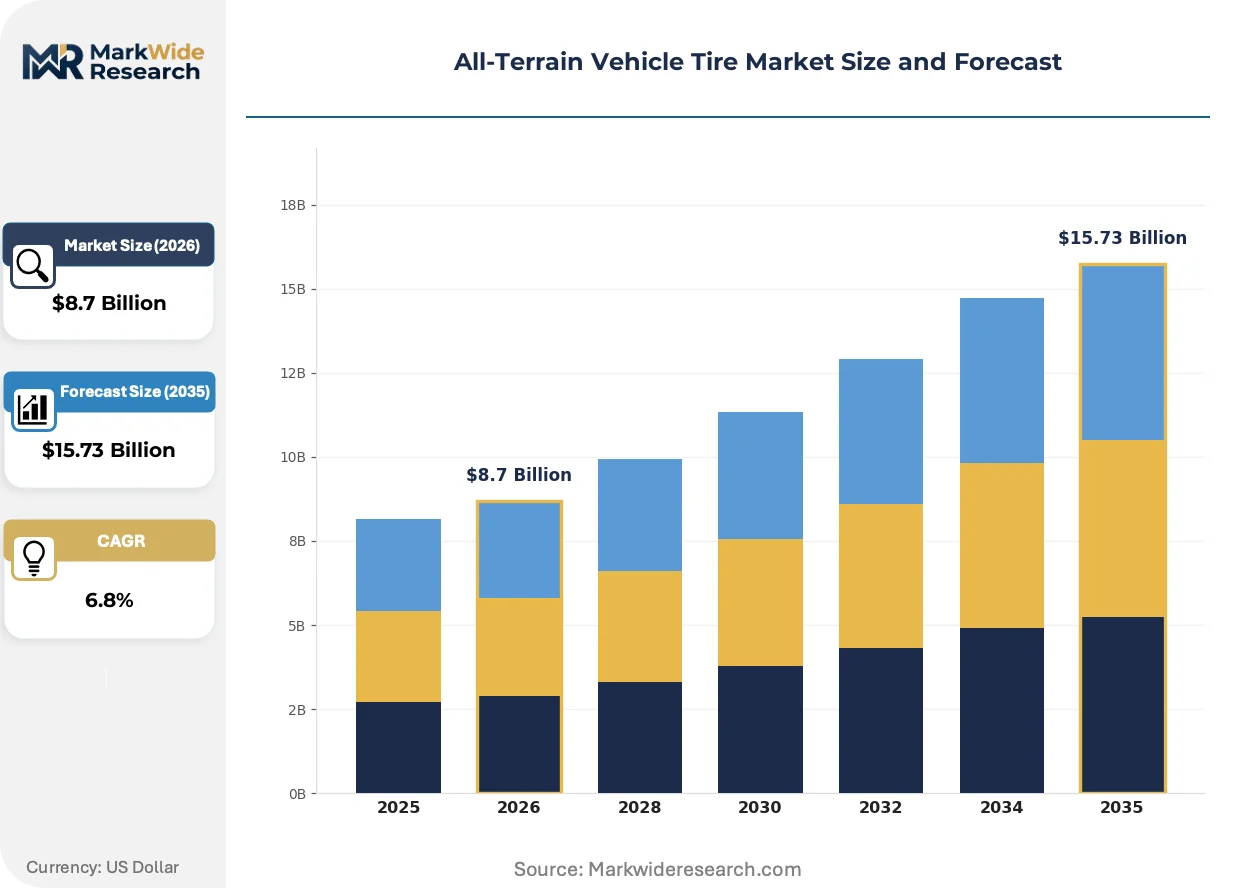
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knobby Tires, Mud Tires, Sand Tires, Trail Tires Material: Rubber, Polyurethane, Steel, Composite End User: Recreational Users, Commercial Fleets, Agricultural Operators, Sports Enthusiasts Size: Small, Medium, Large, Extra Large |
| Companies Covered | Carlisle Companies Incorporated, Bridgestone Corporation, Titan International, Inc., Yokohama Rubber Co., Ltd., Hangzhou Zhongce Rubber Co., Ltd., Michelin S.E., Kenda Rubber Industrial Co., Ltd., Goodyear Tire & Rubber Company, Cheng Shin Tire Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
All-Terrain Vehicle Tire Market Strategic Shifts
Material science advances and regulatory compression are reshaping how tire manufacturers balance performance, compliance, and cost across the ATV value chain.
Radial carcass construction is supplanting bias-ply designs in sport and utility platforms above 400cc displacement. OEMs in the United States and Australia specify radial architectures for their premium model lines, demanding higher ply ratings and reinforced bead bundles. This shift compresses the addressable market for traditional bias-ply suppliers while elevating technical barriers to tier-one supply status.
REACH substance restrictions in the European Union constrain the use of certain aromatic oils and plasticizers in tread compounds. Tire manufacturers serving EU export channels must reformulate recipes and requalify production lines to maintain market access. The regulatory friction disproportionately affects smaller compounders lacking dedicated regulatory affairs capabilities, consolidating formulation expertise among integrated multinationals.
Recreational buyers now prioritize DOT-certified variants even for dedicated off-road use, treating highway legality as a resale value and versatility signal. Specialty retailers report certified tires commanding 15-20 percent shelf price premiums over non-certified equivalents in the same size class. This preference shift is most visible in the American Southwest, where desert racing enthusiasts maintain dual-purpose fleets for trail and street use.
All-Terrain Vehicle Tire Market Segmentation
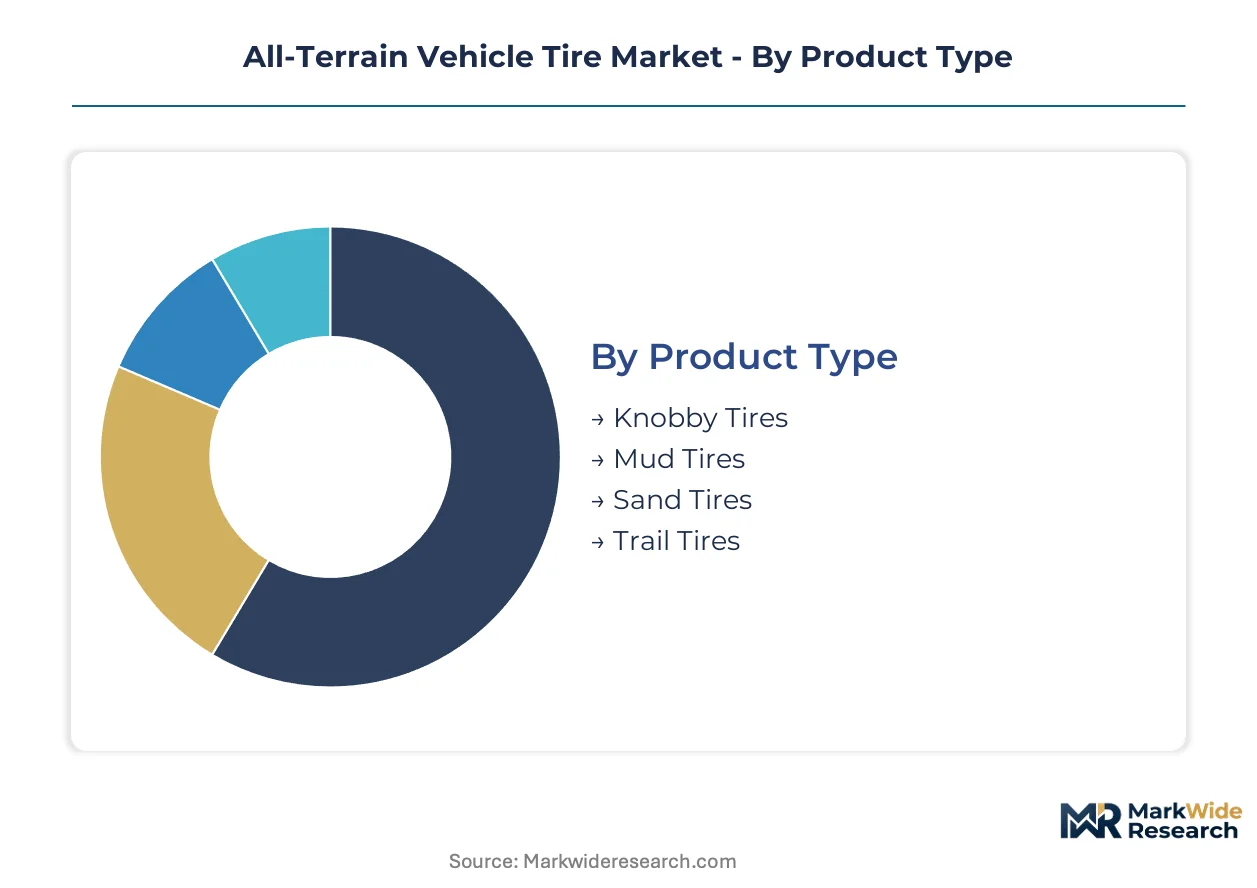
ATV tire segmentation reflects divergent technical requirements across terrain types, material science capabilities, and regulatory compliance tiers. Manufacturers configure product portfolios around DOT certification thresholds, compound durability metrics, and displacement-matched fitment specifications.
Product Type:
EPA non-road emissions standards under 40 CFR Part 1054 and NHTSA FMVSS 119 certification requirements create distinct compliance tiers that reshape product development priorities across knobby, mud, trail, and sand variants.
- Knobby Tires:Multi-angle tread blocks with reinforced nylon or polyester carcass plies deliver puncture resistance across loose rock and packed soil surfaces. Universal fitment across utility and sport ATV platforms concentrates replacement demand in Arizona, Nevada, and Utah desert racing corridors where trail abrasion accelerates wear cycles.
- Mud Tires:Specialized lug geometries with self-cleaning void ratios operate at inflation pressures between 2.5 and 10 psi for flotation through saturated terrain. Premium pricing reflects compound investments in silica-infused formulations that maintain grip across temperature extremes.
- Sand Tires:Paddle-style tread patterns with bias-ply construction dominate coastal dune tourism and desert racing niches.
- Trail Tires:Radial carcass designs above 400cc displacement emphasize high-mileage durability for recreational users prioritizing longevity over terrain specialization.
Established volume favors knobby configurations; emerging adoption favors trail variants as radial technology penetrates utility segments.
Material:
Cost tier differentiation separates compound-dependent natural rubber formulations from engineered alternatives with specialized performance profiles.
- Rubber:Natural rubber sourced from Thai and Indonesian supply chains combines with synthetic polymers in tread compounds subject to REACH aromatic oil restrictions. Over 70 percent of feedstock concentration in two countries exposes manufacturers to geopolitical disruption and currency volatility.
- Polyurethane:Solid tire structures eliminate puncture failure modes for industrial and agricultural deployments where downtime costs exceed material premiums.
- Steel:Bead bundle reinforcement and radial belt packages anchor high-displacement sport platform specifications.
- Composite:Aramid fiber carcass plies face puncture-resistance trade-offs in extreme cold, restricting northern latitude commercial fleet applications.
Volume concentration sits with rubber compounds; margin expansion sits with polyurethane and composite alternatives.
End User:
Application-specific duty cycles and maintenance protocols segment demand across recreational, commercial, agricultural, and sports user categories with distinct procurement patterns.
- Recreational Users:Southwest desert racing enthusiasts and dune tourism participants prioritize DOT-certified variants as resale value signals, accepting 15-20 percent shelf price premiums for highway-legal versatility.
- Commercial Fleets:OSHA workplace safety directives govern tire maintenance protocols for mixed-terrain utility deployments where uptime metrics dominate procurement criteria.
- Agricultural Operators:Captive wheel-tire assembly integration with OEM channels reduces field service complexity for seasonal equipment cycles.
- Sports Enthusiasts:Competitive racing specifications demand specialized compound formulations with accelerated replacement intervals.
Replacement frequency favors sports enthusiasts; contract stability favors commercial and agricultural accounts.
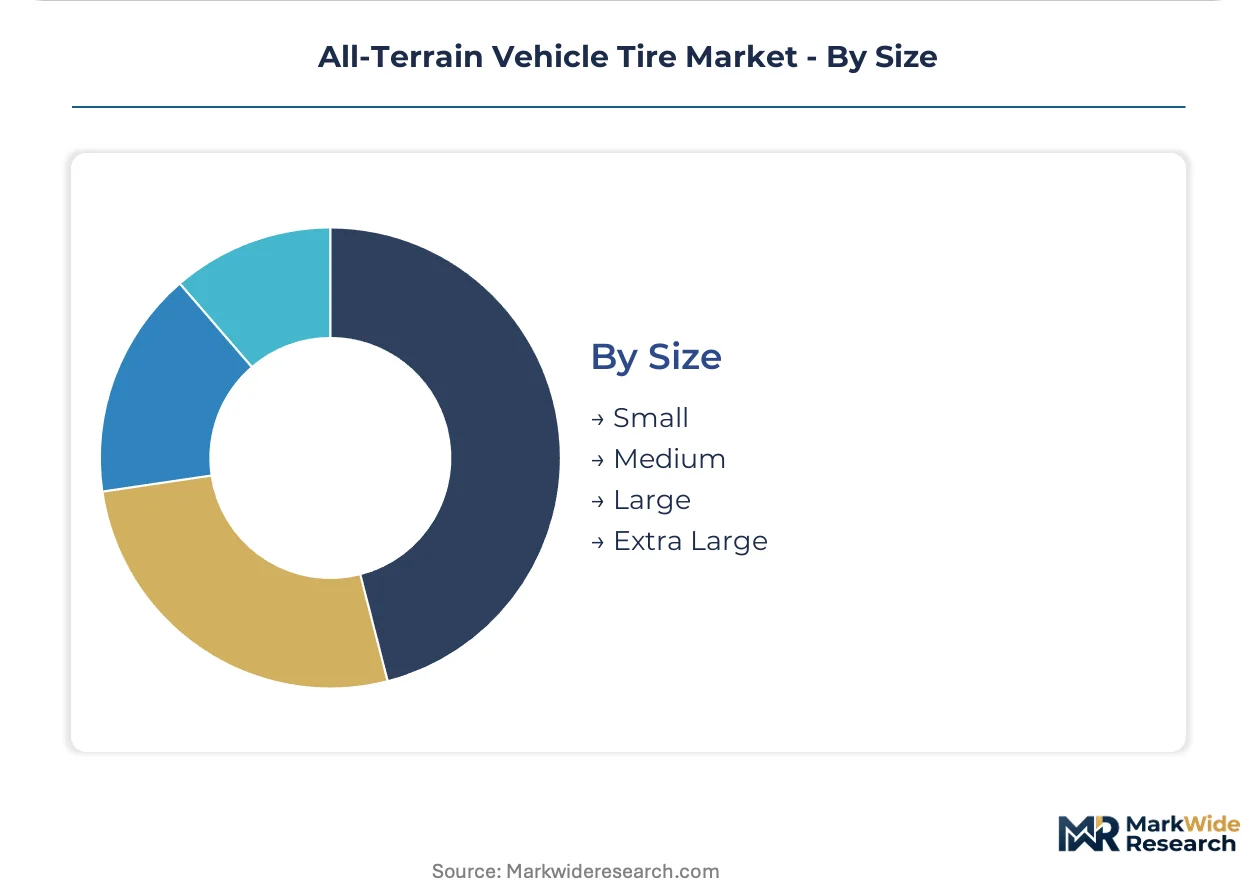
Size:
Displacement-matched fitment specifications create tiered demand clusters aligned with engine classification and terrain flotation requirements.
- Small:Youth platform and entry-level utility specifications below 250cc displacement.
- Medium:Mid-range sport and utility fitments between 250cc and 400cc dominate volume production for rental fleet and casual recreational channels.
- Large:Premium sport and utility platforms above 400cc specify radial architectures with higher ply ratings and reinforced bead bundles.
- Extra Large:Specialized UTV and side-by-side applications require extended load ratings for multi-passenger and cargo configurations.
Production volume clusters at medium sizes; specification complexity climbs fastest at extra large dimensions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Desert racing enthusiasts and commercial fleet operators concentrate replacement demand across distinct geographies shaped by terrain access, regulatory stringency, and OEM manufacturing footprints.
United States
Off-road recreational parks in Arizona, Nevada, and Utah draw rising visitor volumes seeking rugged trail experiences, concentrating knobby tire replacement cycles in the American Southwest. EPA non-road emissions standards under 40 CFR Part 1054 constrain tire-vehicle matching for engine compliance. The Phoenix-Mesa corridor anchors distribution infrastructure serving desert racing tourism and dune recreation clusters.
Canada
Arctic and subarctic commercial fleets deploy ATV platforms for resource extraction and remote infrastructure maintenance, prioritizing puncture-resistant carcass constructions. Health Canada and Transport Canada administer overlapping safety and environmental standards for on-road ATV conversions. Alberta's oil sands region generates concentrated demand for heavy-duty utility tire specifications.
Germany
REACH substance restrictions constrain aromatic oil and plasticizer use in tread compounds exported to EU channels, forcing reformulation investments. KBA type-approval requirements govern highway-legal ATV tire variants sold in domestic and export markets. Baden-Württemberg hosts specialized rubber compound R&D facilities serving premium OEM supply chains.
China
Domestic ATV manufacturing clusters in Shandong and Jiangsu provinces drive original equipment tire demand for export-oriented assembly plants. GB standards and MIIT regulations establish technical compliance baselines for domestic sales and overseas shipments. The Yangtze River Delta concentrates tire mold fabrication and rubber processing capacity.
Australia
Remote pastoral and mining operations sustain commercial fleet demand for puncture-resistant bias-ply and radial configurations across extreme temperature ranges. TGA-administered workplace safety directives affect maintenance protocols for agricultural and industrial deployments. Queensland's coastal dune tourism corridor sustains niche sand tire demand.
All-Terrain Vehicle Tire Market Competitive Environment
Player mix skews toward integrated multinational tire manufacturers with captive rubber processing and motorsport R&D pipelines. The supplier base stratifies across three tiers: premium compound innovators, scale-driven volume producers, and regional specialists serving captive OEM channels. Dominant competitive moves include silica-infused formulation investments and direct-to-consumer channel expansion bypassing traditional distributor markups.
Within the premium-tier vector, Bridgestone Corporation and Michelin S.E. exemplify compound-technology leadership, while Titan International, Inc. anchors presence through captive wheel-tire assembly integration. Hangzhou Zhongce Rubber Co., Ltd. represents scale-driven manufacturing concentration serving volume export markets.
| Leading Market Players |
|---|
| Carlisle Companies Incorporated |
| Bridgestone Corporation |
| Titan International, Inc. |
| Yokohama Rubber Co., Ltd. |
| Hangzhou Zhongce Rubber Co., Ltd. |
| Michelin S.E. |
| Kenda Rubber Industrial Co., Ltd. |
| Goodyear Tire & Rubber Company |
| Cheng Shin Tire Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day compound formulation lead times for silica-infused tread recipes concentrate pricing power among integrated manufacturers with captive rubber processing, while spot buyers face margin compression from Thai and Indonesian supply volatility.
Pricing Analysis
Cost-plus contracts indexed to Singapore natural rubber futures dominate procurement between tire manufacturers and agricultural OEM channels, with silica grade and DOT FMVSS 119 certification tier as primary price differentiation drivers. Pricing pressure intensifies in the knobby tire segment as desert racing tourism concentrates volume demand among Southwest fleet operators with consolidated purchasing leverage. Recreational buyers exhibit lowest price sensitivity, accepting premiums for highway-legal versatility, while commercial agricultural accounts negotiate hardest on per-unit costs.
Supply Chain Analysis
Thailand and Indonesia anchor natural rubber cultivation and initial processing, with China concentrating tire mold fabrication and radial belt package manufacturing. Compound formulation draws from Southeast Asian latex feedstocks, synthetic polymer additives, and aramid fiber carcass materials. Single-source vulnerability in Thai-Indonesian rubber supply exposes manufacturers to climate disruption and currency fluctuation. Distribution runs through Phoenix-Mesa corridor warehousing for Southwest desert racing clusters, with direct-to-consumer digital storefronts gaining share from traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect through DOT certification interoperability, where highway-legal tire variants create switching costs and data-rich direct channels capture lifetime customer value across replacement cycles.
For Market Incumbents: Shield premium positioning by deepening captive rubber processing in IRA-incentivized domestic facilities and accelerating silica-infused compound R&D to outpace formulation talent scarcity. Defend against direct-to-consumer disruptors by controlling distributor data access and locking Southwest fleet accounts through multi-year service bundling. For New Entrants and Emerging Players: Anchor in the sand tire niche serving Queensland coastal dune tourism and Arizona desert racing applications, where paddle-tread specialization limits incumbent scale advantages. Penetrate through manufacturer-owned digital storefronts targeting recreational buyers prioritizing DOT certification as resale value signals. For Investors and Strategic Acquirers: Long-term, this sits as a compound-technology consolidation play because silica-infused formulation expertise concentrates among integrated multinationals while REACH regulatory friction eliminates smaller compounders. Target mid-tier manufacturers with established OEM wheel-tire assembly relationships and underutilized radial production capacity. Monitor EPA 40 CFR Part 1054 enforcement intensity as inflection signal for low-rolling-resistance compound investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Silica-Infused Compound Scale-Up | Extends tread life across extreme temperature ranges for Southwest desert racing corridors. |
| DOT FMVSS 119 Certification Investment | Unlocks highway-legal market access and commands 15-20 percent shelf price premiums. |
| Direct-to-Consumer Channel Launch | Bypasses distributor markups while capturing customer data for replacement cycle targeting. |
| Domestic Rubber Processing Reshoring | Qualifies for IRA clean energy incentives serving North American demand clusters. |
| Radial Carcass Technology Licensing | Addresses OEM specification shifts above 400cc displacement in premium sport platforms. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including tire compound R&D directors, agricultural OEM procurement managers, desert racing fleet maintenance heads, and aftermarket distributor channel partners. Secondary validation drew from EPA 40 CFR Part 1054 regulatory filings, NHTSA FMVSS certification databases, natural rubber futures exchange data, and SEC 10-K disclosures from integrated tire manufacturers. Bottom-up volume modeling across terrain-specific product types triangulated with top-down value projections from displacement-matched fitment specifications.
Across the analysis window, forecasting segmented by product type, material composition, end-user category, and size tier captured replacement cycle dynamics and regulatory compliance thresholds. CAGRs derived from historical volume trajectories adjusted for radial architecture penetration rates and silica compound adoption curves. Model inputs incorporated desert racing tourism visitor flows, EPA emissions standard phase-in schedules, and IRA domestic manufacturing credit utilization patterns.
Decision-makers should treat outputs as directional under assumptions of sustained natural rubber supply from Thai-Indonesian origins and stable EPA regulatory enforcement intensity; material deviation in either would warrant model refresh. Recalibration cycles align with shifts in federal tariff structures on imported rubber compounds and state-level trail access legislation changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Global Commercial Vehicle Run Flat Tire Inserts Market
Tires and Wheels
Self-Sealing Tire Market
Tires and Wheels
Ground Support Equipment Tires Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
All Weather Tire Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Global Bead Wire (Tyre Bead Wire) Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Global OTR Tires Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Automotive Retread Tires Market
Tires and Wheels
United States Tire Market
Tires and Wheels
South Korea Automotive Carbon Wheels Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Tire Inflating Machine Market
Tires and Wheels
Global Tire Curing Press Market