
 Global OTR Tires Market | 2026-2036
Global OTR Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Global OTR Tires Market Outlook
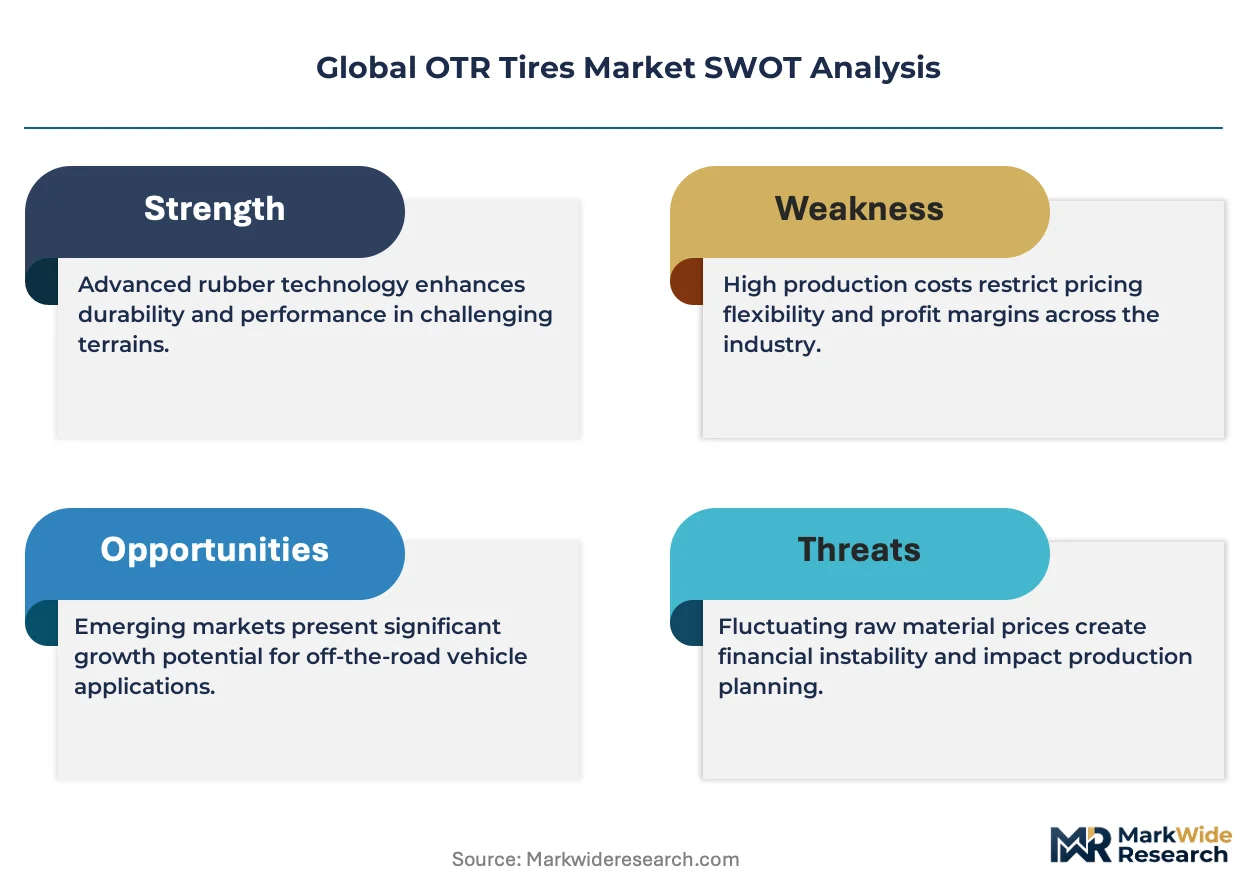
Radial-grade specification upgrades across heavy-duty mining and construction fleets is bifurcating the competitive landscape into premium engineered suppliers and volume-oriented producers. Michelin leverages its R&D intensity in heat-resistant tread compounds for deep-pit operations. Bridgestone Corporation anchors its position through backward integration into natural rubber sourcing across Southeast Asian plantation networks. Balkrishna Industries Limited specializes in cost-optimized bias-ply designs that dominate emerging-market agricultural tractor demand.
Off-the-road tires are pneumatic or solid rubber structures engineered with reinforced carcass constructions, multi-layer steel belts, and specialized tread patterns designed to operate under extreme load indices exceeding 150 PSI while resisting cuts, impacts, and thermal degradation in unpaved terrain. Their primary purpose is to sustain traction, stability, and service life for earthmovers, dump trucks, and agricultural machinery operating beyond conventional highway conditions. Radial construction commands the dominant share in mining applications due to superior heat dissipation and retreadability, while solid tires capture margin pools in port terminal operations where puncture elimination justifies premium pricing. The above-29-inch size category represents the fastest-growing dimension as ultra-class haul trucks proliferate in Australian and African iron ore corridors.
EPA emissions standards for non-road diesel equipment indirectly shape OTR tire demand by extending equipment replacement cycles and requiring matched tire durability. REACH and EU F-Gas Regulation constrain aromatic oil and synthetic rubber inputs, compelling reformulation investments that filter through to tire pricing structures. China's GB standards on tire labeling and energy efficiency create parallel compliance obligations for suppliers serving Belt and Road construction machinery exports. Stakeholders must monitor how carbon-border adjustment mechanisms and emerging national mining codes reshape total cost of ownership calculations for tire procurement across jurisdictional supply chains.
Market Dynamics
Radial construction specifications are displacing bias-ply designs across heavy mining fleets as payload weights and haul cycle distances extend beyond legacy tire thermal limits. This structural shift is fragmenting supplier capabilities between heat-engineered premium producers and cost-optimized volume manufacturers.
Growth Catalysts
- Australian Iron Ore Corridor Expansion:Ultra-class haul truck deployment in Pilbara operations demands above-29-inch radial tires with reinforced steel-belt carcasses rated for 24-hour continuous duty cycles.
- EU F-Gas Regulation:Restrictions on synthetic rubber processing emissions are accelerating reformulation investments toward bio-based tread compounds and solvent-free curing methods.
- Mechanized Palm Oil Harvesting:Indonesian plantation operators are replacing manual labor with heavy skidders and loaders, generating replacement tire demand for bias-ply agricultural specifications.
Market Restraints
- Natural Rubber Price Volatility:Latex supply concentration across Thai and Indonesian plantation networks exposes tire margins to weather-driven harvest disruptions and commodity speculation.
- REACH Compliance Costs:Aromatic oil bans and restricted chemical curatives in EU-bound production lines impose reformulation expenses that volume producers cannot absorb without pricing adjustments.
- Solid Tire Substitution:Port terminal operators in Rotterdam and Singapore are migrating to puncture-proof solid rubber designs, compressing pneumatic tire demand in container handling applications.
Strategic Opportunities
- Brazilian Agricultural Belt:Soybean and sugarcane mechanization in Mato Grosso and São Paulo states outpaces local tire retreading infrastructure, creating import channels for radial harvester specifications.
- China GB Standards Alignment:Belt and Road machinery exports must comply with domestic tire labeling and energy efficiency mandates, favoring suppliers with in-country testing certification.
- Sensor-Embedded Tire Systems:Integration of pressure and temperature monitoring hardware with telematics platforms enables predictive maintenance contracts for Chilean copper mining fleets.
Industry Challenges
- Compound Formulation Expertise Gap:Heat-resistant tread chemistry for deep-pit operations requires polymer scientists with mining-specific durability modeling experience that Southeast Asian technical institutes rarely produce.
- Retreading Certification Timelines:EU type-approval processes for remanufactured radial carcasses extend 14-18 months, delaying aftermarket revenue recognition for independent retreaders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global OTR Tires Market |
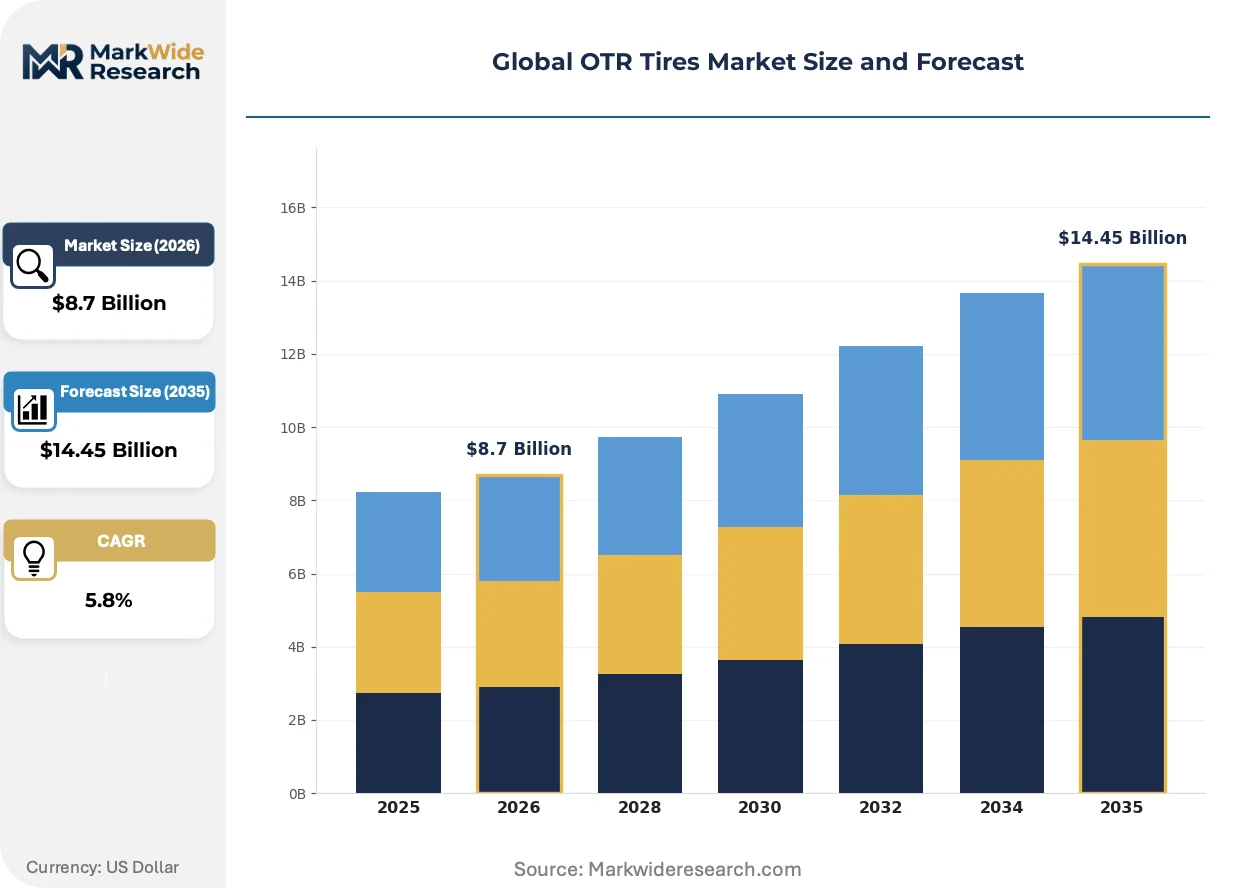
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial, Bias, Solid, Tubeless End User: Mining, Construction, Agriculture, Ports Size: Up to 22 inches, 23 to 25 inches, 26 to 29 inches, Above 29 inches Technology: All-Terrain, Non-Directional, High-Performance, Eco-Friendly |
| Companies Covered | The Yokohama Rubber Co Ltd, Triangle Tyre Co., Ltd, Michelin, Sumitomo Rubber Industries, Ltd, Apollo Tyres Ltd, Bridgestone Corporation, Continental AG, Balkrishna Industries Limited, The Goodyear Tire & Rubber Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global OTR Tires Market Strategic Shifts
Material science advances and embedded sensor architectures are redefining tire lifecycle economics. Suppliers now compete on total cost-per-kilometer metrics rather than upfront unit pricing, shifting buyer evaluation frameworks toward durability guarantees and predictive service intervals.
Silica-reinforced tread compounds with nanoscale dispersion technology are decomposing traditional carbon-black formulations in high-speed haul truck applications. Mining operators in Western Australia specify these compounds for 15% extended wear intervals on 400-ton payload routes. The technology is decomposing retread cycle economics by enabling third-life casing reuse rather than second-life scrap rates.
REACH and EU F-Gas Regulation constraints on aromatic extender oils are forcing compound reformulation across export-bound production lines. Manufacturers serving European construction equipment OEMs must eliminate polycyclic aromatic hydrocarbons from tread and sidewall formulations. Brazilian tire plants supplying EU machinery exporters are installing solvent recovery systems to maintain market access.
Fleet telematics integration is compressing traditional tire procurement cycles from annual volume contracts to continuous performance-based arrangements. Mining contractors in Chile's Atacama Desert now specify real-time pressure monitoring as a contract prerequisite, displacing spot-buy replacement practices. This pattern is most visible in copper extraction operations where unplanned downtime costs exceed tire unit values by orders of magnitude.
Global OTR Tires Market Segmentation
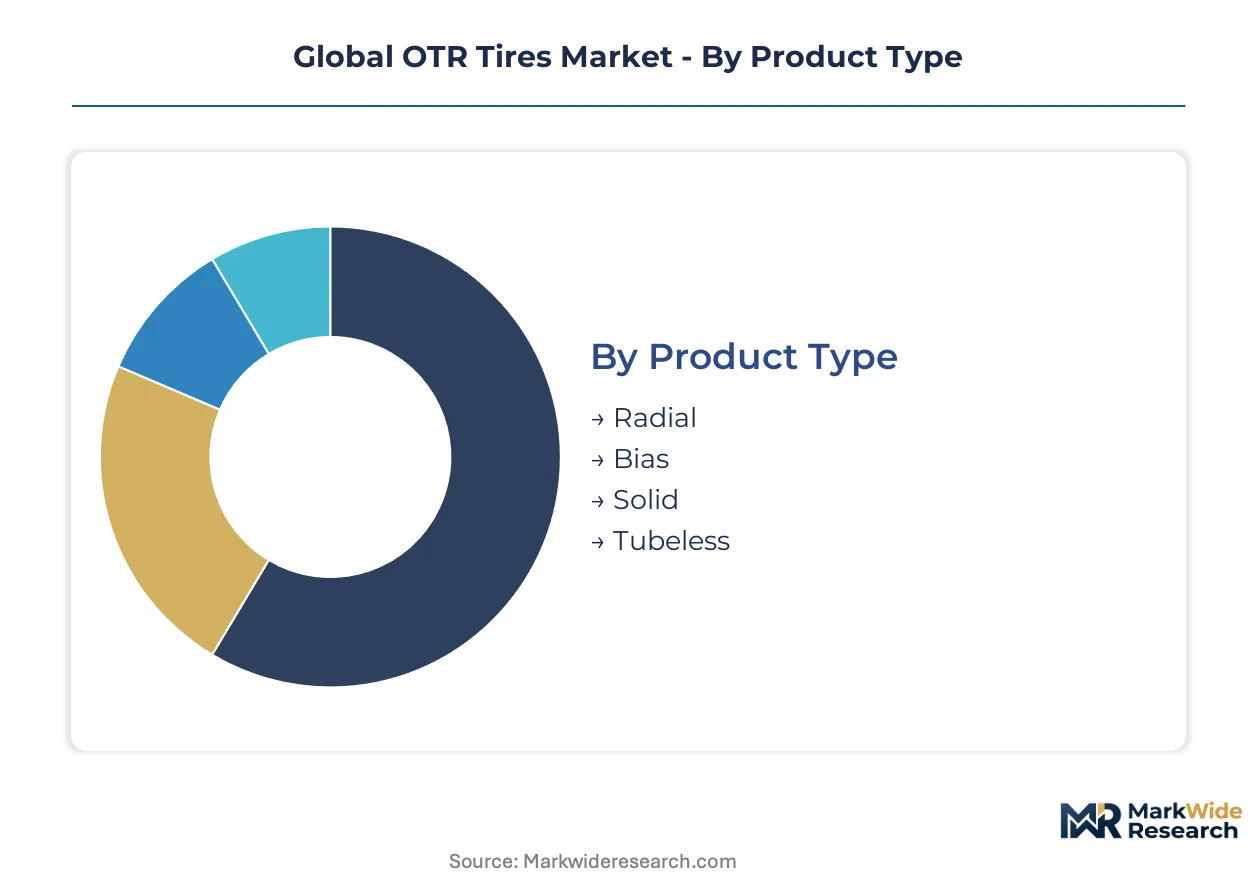
Segmentation in the OTR tires market reveals how construction method, end-use intensity, and dimensional requirements create distinct procurement channels. Each dimension carries different margin profiles, certification burdens, and geographic concentration patterns that shape supplier positioning.
Product Type:
Radial specifications dominate export-led demand from Australian and Chilean mining corridors, while bias-ply volumes concentrate in domestic agricultural markets across Brazil and India.
- Radial:Multi-layer steel-belt carcasses with reinforced sidewalls dissipate heat across 24-hour haul cycles. Australian iron ore operators in the Pilbara specify these for ultra-class trucks moving 400-ton payloads, with thermal performance requirements exceeding legacy bias-ply limits.
- Bias:Cross-ply nylon or polyester cord arrangements deliver lower unit costs for intermittent-duty equipment. Brazilian soybean harvesters in Mato Grosso and Indonesian palm oil skidders generate replacement demand where capital constraints favor durability-per-dollar over absolute lifespan.
- Solid:Puncture-proof rubber compounds eliminate downtime in container handling environments. Port terminal operators in Rotterdam and Singapore absorb premium pricing to avoid pneumatic failure risks in 24/7 cargo operations.
- Tubeless:Bead-seal designs reduce weight and simplify field repairs for construction fleets. Chinese excavator OEMs serving Belt and Road projects specify these for easier maintenance in remote Central Asian infrastructure corridors.
Radial construction holds the largest share; momentum sits with solid configurations in port automation applications.
End User:
Cost tiers separate capital-intensive mining procurement from price-sensitive agricultural replacement cycles, with construction and ports occupying intermediate positions.
- Mining:Heat-resistant tread compounds withstand continuous duty in deep-pit copper and iron ore extraction. Chilean Antofagasta operators and Western Australian corridor fleets specify above-29-inch radials with retreadable carcasses to amortize casing investments across multiple life cycles.
- Construction:Mixed-surface durability requirements span highway building, tunneling, and dam projects. Chinese state-owned contractors purchasing for Belt and Road deployment in Pakistan and Kazakhstan drive demand for 23-25 inch specifications with all-terrain tread patterns.
- Agriculture:Flotation designs minimize soil compaction in mechanized planting and harvesting. Brazilian sugarcane processors in São Paulo state and Indonesian plantation operators upgrading from manual labor generate volume demand for bias-ply harvester tires.
- Ports:Solid and pneumatic designs compete on total cost-per-container-moved metrics. Singapore terminal operators and Rotterdam cargo handlers specify sensor-embedded variants for predictive maintenance integration with fleet telematics platforms.
Mining commands premium pricing; agriculture generates the highest unit volumes through replacement frequency.
Size:
Dimensional scaling follows payload escalation in mining, with smaller categories serving diversified construction and agricultural equipment bases.
- Up to 22 inches:Compact loaders and skid-steers in urban construction environments. Japanese mini-excavator OEMs export these specifications to Southeast Asian infrastructure projects.
- 23 to 25 inches:Mid-size haul trucks and articulated dumpers. Indian road-building contractors deploy these across Himalayan tunneling projects.
- 26 to 29 inches:Heavy construction and smaller mining fleets. South African platinum extraction operations specify these for reef-access haulage.
- Above 29 inches:Ultra-class trucks in high-volume, low-grade ore operations. Australian Pilbara iron ore corridors and Brazilian Carajás iron ore systems drive specification upgrades here, with heat dissipation and retreadability determining supplier selection.
Above-29-inch specifications are climbing the fastest as fleet operators maximize payload-per-trip economics.
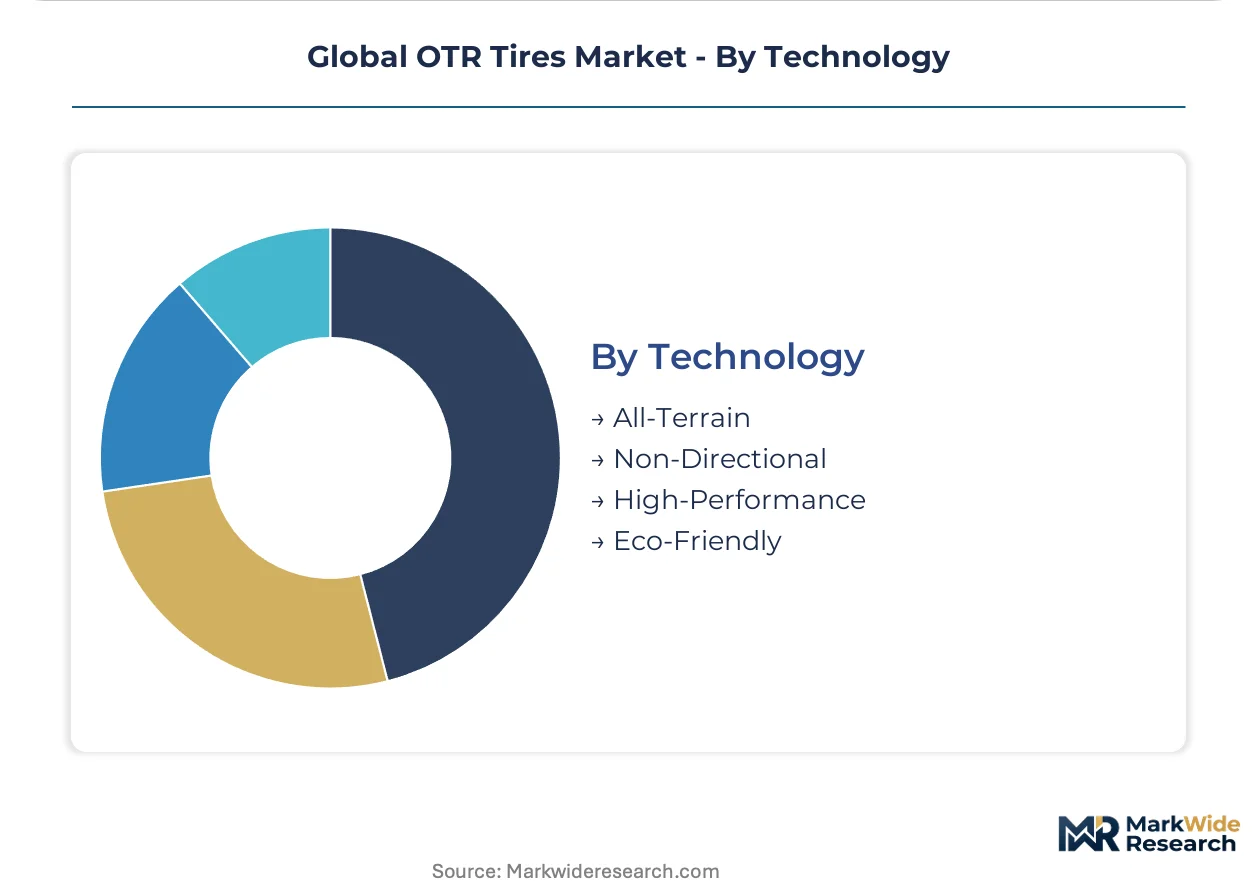
Technology:
Regulatory pressure on compound chemistry and fleet digitization are bifurcating technology adoption between compliance-driven European markets and performance-driven mining jurisdictions.
- All-Terrain:Interlocking tread blocks adapt to rock, mud, and loose aggregate surfaces. Canadian oil sands operators and Russian permafrost extraction fleets specify these for seasonal ground condition variability.
- Non-Directional:Symmetrical patterns allow rotation across all wheel positions to equalize wear. African copperbelt contractors in Zambia and DRC favor these for extended service intervals in remote maintenance environments.
- High-Performance:Silica-reinforced compounds with nanoscale carbon-black dispersion extend wear intervals. Western Australian 400-ton haul routes specify these for 15% lifecycle extensions.
- Eco-Friendly:Bio-based tread compounds and solvent-free curing methods satisfy REACH and EU F-Gas Regulation constraints. Brazilian plants supplying European machinery exporters invest in recovery systems to maintain market access.
High-performance compounds hold the largest mining share; eco-friendly formulations are gaining share fastest on regulatory compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai and Indonesian plantation networks concentrate natural rubber supply, while finished tire production clusters in China, India, Japan, and select European facilities serving mining and agricultural demand corridors.
Australia
Pilbara iron ore operators deploy ultra-class haul trucks demanding above-29-inch radial specifications rated for 24-hour thermal cycles. The country's national mining safety regulator enforces equipment certification standards that cascade into tire durability requirements. Perth-based procurement hubs coordinate replacement cycles for Western Australian corridor fleets moving 400-ton payloads.
China
Belt and Road machinery exports drive demand for 23-25 inch construction specifications with all-terrain tread patterns. MIIT-administered GB standards on tire labeling and energy efficiency create parallel compliance obligations for suppliers serving Central Asian infrastructure projects. Shandong Peninsula manufacturing clusters produce volume output for domestic excavator OEMs and export markets.
Brazil
Mato Grosso and São Paulo agricultural mechanization outpaces local retreading infrastructure, creating import channels for radial harvester tires. ANVISA chemical safety protocols and environmental licensing constrain aromatic oil use in tread formulations. São Paulo state sugarcane processors generate replacement demand as manual labor substitution accelerates.
Germany
Construction equipment OEMs source REACH-compliant tire specifications eliminating polycyclic aromatic hydrocarbons from export-bound production lines. ECHA enforcement of aromatic extender oil bans forces compound reformulation investments across supplier networks. Baden-Württemberg engineering clusters integrate tire telematics with fleet management platforms for predictive maintenance contracts.
Indonesia
Palm oil plantation operators replace manual labor with heavy skidders and loaders, generating bias-ply agricultural tire demand. The country's national environmental regulator monitors plantation expansion permits affecting equipment deployment timelines. Sumatra and Kalimantan processing hubs concentrate mechanization investment where terrain conditions favor puncture-resistant specifications.
Global OTR Tires Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with heat-engineered premium producers competing on durability guarantees while volume manufacturers optimize unit economics for price-sensitive replacement cycles. The market structure tiers into three supplier categories: integrated rubber processors with captive raw material access, specialized mining-grade compounders, and regional agricultural tire fabricators. Consolidation pressure concentrates among mid-scale retreaders facing EU type-approval timeline extensions. Dominant competitive moves include backward integration into plantation networks and sensor-embedded system partnerships with telematics platforms.
Within the premium engineered tier, Michelin and Bridgestone Corporation exemplify archetypes differentiated by R&D intensity versus upstream supply control. Michelin occupies a position emphasizing heat-resistant tread chemistry for deep-pit operations. Bridgestone anchors its competitive stance through captive natural rubber sourcing across Southeast Asian plantation networks. Among emerging-market specialists, Balkrishna Industries Limited sits within the cost-optimized volume manufacturer archetype, with its BKT-branded positioning targeting agricultural tractor replacement cycles where durability-per-dollar metrics dominate procurement decisions.
| Leading Market Players |
|---|
| The Yokohama Rubber Co Ltd |
| Triangle Tyre Co., Ltd |
| Michelin |
| Sumitomo Rubber Industries, Ltd |
| Apollo Tyres Ltd |
| Bridgestone Corporation |
| Continental AG |
| Balkrishna Industries Limited |
| The Goodyear Tire & Rubber Company |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Pilbara mining operators and premium radial suppliers lock in multi-year supply access while fixing price visibility against natural rubber volatility. These arrangements cascade through to retreading service agreements that amortize casing investments across three lifecycle stages, with EU F-Gas Regulation compliance costs embedded as pass-through clauses.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure by imposing reformulation costs that stratify suppliers across premium, standard, and economy certification levels. REACH aromatic oil bans force compound investments that premium producers absorb through durability guarantees while volume manufacturers face margin compression. Pricing pressure stems from Thai latex harvest disruptions that transmit volatility through spot-market buyers. Mining fleets in Western Australia exhibit lowest price sensitivity due to unplanned downtime costs, while Brazilian agricultural replacement cycles favor durability-per-dollar procurement.
Supply Chain Analysis
Strait of Malacca transit underwrites Southeast Asian natural rubber flows to Chinese and Indian manufacturing clusters. Thai and Indonesian plantation networks feed latex processing facilities in Shandong and Tamil Nadu that produce carcass compounds and tread formulations. Supply chain risk centers on monsoon-driven harvest disruptions that concentrate pricing power among integrated plantation operators. Distribution runs through OEM procurement hubs in Perth, São Paulo, and Rotterdam that coordinate fleet replacement cycles with regional mining and agricultural seasons.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mining fleet consolidation across Australian Pilbara operators has shifted procurement leverage toward volume-contracting buyers capable of dictating performance-based pricing terms. Three incumbent contractors now coordinate specification standards that fragment supplier pricing power across the premium tier.
For Market Incumbents: Shield margin structures by deepening backward integration into Sumatra plantation networks before latex supply tightens further. Prioritize sensor-embedded tire system partnerships with Chilean copper mining telematics platforms to lock in predictive maintenance contracts that resist price-only competition from Asian volume producers. For New Entrants and Emerging Players: Anchor in Brazilian Mato Grosso agricultural replacement cycles where local retreading infrastructure gaps force import dependence on cost-optimized bias-ply specifications. Target Indonesian palm oil plantation mechanization through skidder tire offerings that match terrain-specific puncture resistance requirements without premium radial investments. For Investors and Strategic Acquirers: Heat-resistant compound specialists with captive polymer science capabilities represent the most defensible acquisition profile as mining payload escalation accelerates specification divergence. Monitor EU type-approval timeline extensions for remanufactured radial carcasses as the signal indicating retreader consolidation pressure and aftermarket margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Networks | Captive latex supply from Thai and Indonesian estates insulates margins against commodity volatility. |
| Sensor-Embedded Tire System Deployment | Telematics integration with Chilean mining fleets enables predictive maintenance contract structures. |
| REACH-Compliant Compound Reformulation | ECHA aromatic oil bans force solvent-free curing investments for European machinery export access. |
| Retreading Certification Acceleration | EU type-approval compression delays aftermarket revenue recognition for independent operators. |
| Above-29-Inch Radial Capacity Expansion | Australian Pilbara ultra-class haul truck deployment demands heat-dissipating carcass investments. |
Study Parameters
Cross-validation between procurement director interviews at Australian mining contractors and customs trade data from Thai latex export records anchors the qualitative findings. Primary fieldwork encompassed maintenance directors at Chilean copper operations, OEM tire specification engineers in Baden-Württemberg, and plantation supply managers across Sumatra. Secondary sources integrated ECHA regulatory filings, MIIT GB standard documentation, and ANVISA chemical safety protocols. Bottom-up segment sizing triangulated against top-down mining fleet equipment deployment databases.
Sensitivity analysis across natural rubber price scenarios and haul cycle extension assumptions shaped the projection framework. Segmentation dimensions modeled encompass construction method, end-use intensity, dimensional category, and compound technology tier. CAGRs derived from equipment replacement cycle analysis and mechanization penetration curves in agricultural corridors. Key inputs included EPA non-road diesel equipment standards affecting tire durability matching and Belt and Road machinery export volumes driving construction specification demand.
Material uncertainties — carbon-border adjustment mechanism implementations, national mining code revisions, and plantation labor availability disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement continuity and commodity supply stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Brazil Automotive Tire Market
Tires and Wheels
United States Tire Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
GCC Tire Market
Tires and Wheels
Alloy Wheels Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
Russia OTR Tire Market
Tires and Wheels
Automotive Alloy Wheels Market
Tires and Wheels
Global Tire Curing Press Machine Market
Tires and Wheels
Europe 2-Wheeler Replacement Tire Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Global Automotive Tires Market
Tires and Wheels
North America OTR Tire Market