
 Automotive Carbon Wheels Market | 2026-2036
Automotive Carbon Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Carbon Wheels Market Analysis
Aluminum-to-carbon substitution in performance wheel architectures is shifting the cost-performance frontier for unsprung rotational mass. Carbon Revolution leverages proprietary one-piece carbon fiber manufacturing to anchor supply relationships with premium OEM programs. Rotobox specializes in braided carbon-composite motorcycle and automotive rim architectures that differentiate on impact tolerance. HRE controls the North American aftermarket for forged and carbon hybrid wheels through direct-to-enthusiast channel positioning.
Automotive carbon wheels are fiber-reinforced polymer structures, typically woven from continuous carbon filaments in epoxy matrices and cured under pressure at temperatures exceeding 150°C, engineered to reduce unsprung weight by 40-60% versus cast aluminum equivalents while maintaining radial fatigue thresholds above 300,000 cycles. Their primary purpose is to lower rotational inertia, improving vehicle acceleration, suspension response, and electric vehicle range. The application dimension shows electric vehicles as the fastest-expanding demand pool, where every kilogram of unsprung mass reduction translates directly to watt-hour-per-kilometer efficiency gains. The end-user dimension reveals OEMs capturing margin concentration through long-term supply agreements, while race teams sustain premium pricing tolerance for FIA-homologated wheel specifications.
The EPA governs fuel economy standards that indirectly incentivize lightweighting investments by domestic automakers, while NHTSA crashworthiness protocols shape carbon wheel impact-test validation requirements for US road certification. The EU's CE marking and MDR frameworks extend material conformity obligations to composite automotive components entering European type-approval channels. Stakeholders must monitor evolving battery-electric vehicle platform architectures, as skateboard chassis designs with in-wheel motor integration could either expand or constrain carbon wheel addressable space depending on brake-thermal management solutions.
Market Dynamics
Electric vehicle platform architectures are forcing unsprung mass reduction into core procurement specifications, binding carbon wheel adoption directly to battery efficiency targets and regenerative braking thermal management requirements.
Growth Catalysts
- EU F-Gas Regulation:Material traceability mandates for composite components are accelerating supplier qualification programs among German premium automakers seeking compliant carbon fiber sourcing.
- Battery-electric vehicle platforms:Watt-hour-per-kilometer efficiency targets are embedding carbon wheel specifications into OEM platform engineering sign-off criteria.
- German motorsport clusters:FIA-homologated wheel testing protocols are transferring validation expertise into road-car supply chains, compressing development cycles.
Market Restraints
- Carbon fiber precursor costs:Polyacrylonitrile supply concentration in Asian petrochemical complexes exposes wheel manufacturers to acrylonitrile price volatility.
- Single-source autoclave capacity:High-pressure curing equipment for one-piece rim construction concentrates in specialized German and Italian composite facilities.
- Aluminum forging substitution:Flow-formed aluminum wheels at 60% lower cost-per-kilogram retain specification share in mid-performance vehicle segments.
Strategic Opportunities
- US Inflation Reduction Act:Domestic content credits for EV component sourcing are incentivizing North American carbon wheel manufacturing localization.
- In-wheel motor integration:Convergence of hub-mounted electric motors with carbon rim architectures creates thermal management co-development partnerships.
- Direct-to-fleet channels:Subscription-based premium vehicle services are bypassing traditional dealer networks for wheel specification and replacement.
Industry Challenges
- Composite repair technician scarcity:Rim damage assessment and fiber layup restoration skills lag behind carbon wheel installation volumes.
- NHTSA impact-test certification timelines:Road-approval protocols for novel rim geometries extend product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Carbon Wheels Market |
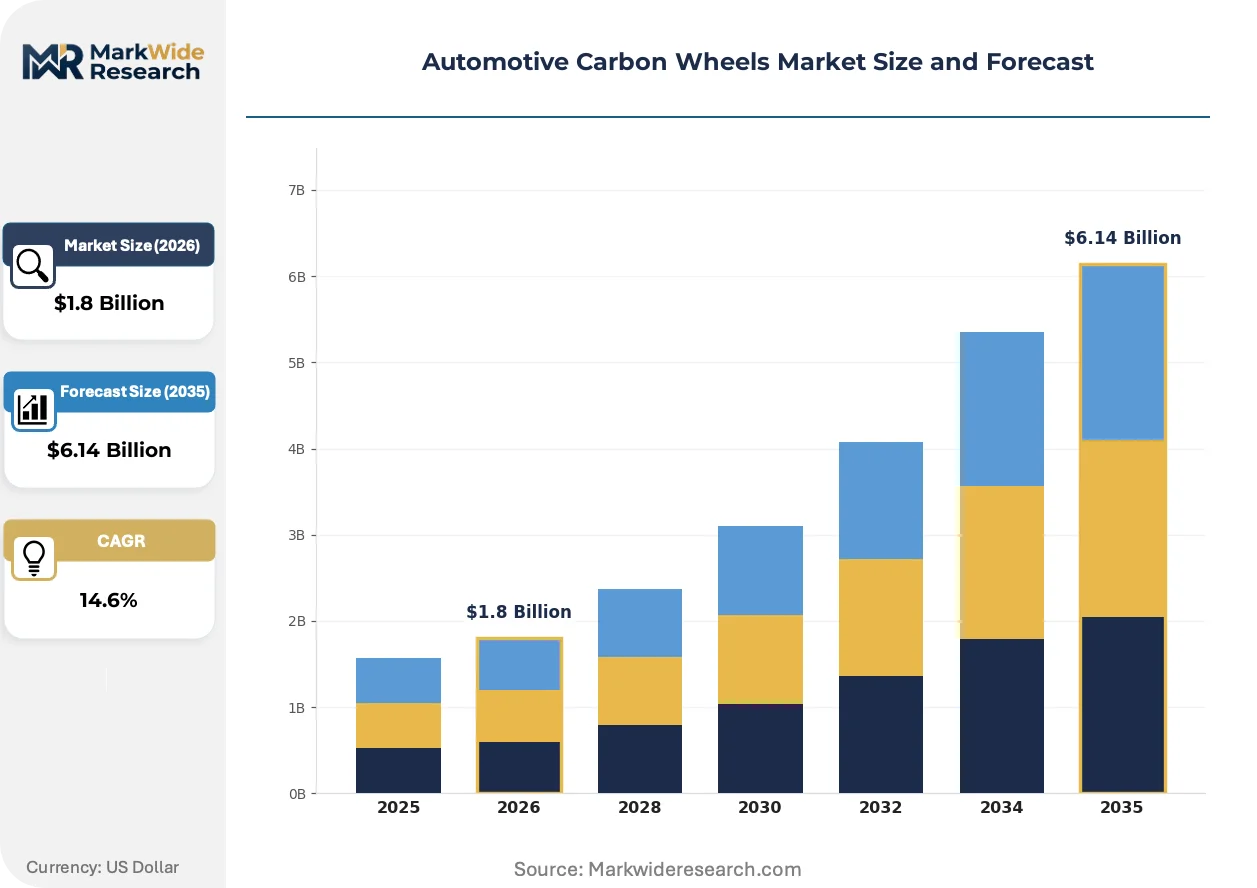
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rims, Discs, Spokes, Accessories Application: Sport Cars, Luxury Vehicles, Electric Vehicles, Aftermarket End User: OEMs, Tier-1 Suppliers, Automotive Enthusiasts, Race Teams Manufacturing Stage: Pre-Production, Production, Quality Control, Post-Production |
| Companies Covered | Vossen, Rotobox, Carbon Revolution, Weds, Vision Composite Products, DYMAG, BST, BUCCI Composites, HRE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Carbon Wheels Market Emerging Trajectories
Braided carbon-composite manufacturing is compressing the traditional autoclave-to-market pathway, while regulatory material disclosure requirements and fleet procurement centralization are redistributing specification authority across the value chain.
Thermoplastic resin transfer molding is unifying fiber placement precision with cycle-time compression. Tier-1 suppliers are adopting this process for high-volume electric vehicle platform contracts. The technology is unifying aerospace-derived automation with automotive cost structures, collapsing the historical price gap between forged aluminum and entry-level carbon wheels.
REACH substance-of-very-high-concern screening is extending compliance obligations to epoxy hardener chemistries in composite wheel supply chains. European importers must now document full material composition through tier-3 suppliers. German and Italian wheel manufacturers are responding by qualifying bio-based resin systems ahead of anticipated ECHA restriction expansions.
Fleet managers at premium mobility services are consolidating wheel procurement into platform-level lifecycle contracts. Direct sourcing agreements are displacing traditional aftermarket distributor markups for replacement and seasonal wheel sets. This concentration is most visible in California and Germany, where corporate electrification mandates bundle vehicle, charging, and maintenance spend under single vendor relationships.
Automotive Carbon Wheels Market Segmentation
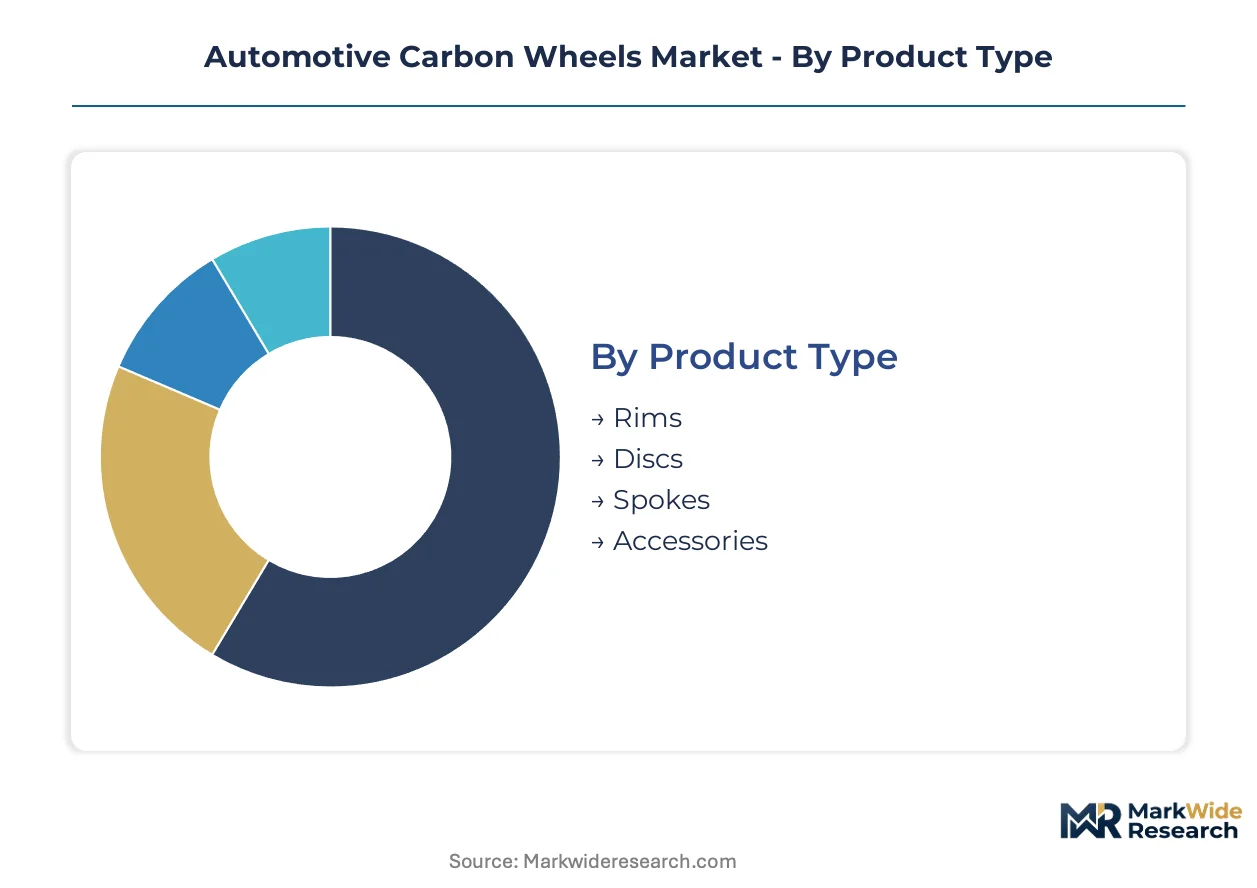
Carbon wheel procurement patterns diverge sharply across specification tiers, with OEM platform engineering driving standardization at volume while motorsport and aftermarket channels sustain bespoke geometries. Segmentation reveals how manufacturing complexity, thermal management requirements, and certification protocols fragment addressable markets across distinct value pools.
Product Type:
Customization intensity spans from fully engineered rim assemblies to commoditized hardware kits, with composite layup complexity determining supplier qualification barriers.
- Rims:One-piece carbon fiber hoop structures carry radial and lateral load paths through continuous filament wound preforms cured under autoclave pressure. OEM electric vehicle programs in Germany specify these for unsprung mass reduction targets tied to efficiency certification.
- Discs:Central hub-mounting interfaces machined from forged aluminum or titanium inserts bonded to carbon barrels. Demand concentrates in Italian and German premium sports car architectures where brake thermal management requires metallic heat sinks.
- Spokes:Multi-spoke or full-face carbon designs linking rim barrels to central discs. Japanese and US aftermarket distributors favor these for aesthetic differentiation in direct-to-enthusiast channels.
- Accessories:Valve stems, center caps, and lug nut covers in carbon or hybrid construction. These ride-along components capture margin through bundled OEM packaging rather than standalone specification.
Most installed capacity flows through Rims. Expansion is steepest in Discs as thermal interface engineering becomes critical for in-wheel motor integration.
Application:
Volume concentration tilts toward fleet procurement channels, while pricing power resides in homologated performance segments with FIA validation requirements.
- Sport Cars:Track-focused vehicles requiring FIA-homologated wheel specifications for competition eligibility. German and Italian manufacturers specify these through motorsport-derived supply chains with compressed development cycles.
- Luxury Vehicles:Premium grand touring and sedan platforms where carbon wheels signal specification hierarchy. UK and US ultra-luxury marques bundle these in option packages exceeding standard forged aluminum pricing by 400-600%.
- Electric Vehicles:Battery-electric platforms where watt-hour-per-kilometer targets embed unsprung mass reduction into engineering sign-off criteria. California and German OEM procurement teams are accelerating supplier qualification for next-generation skateboard architectures.
- Aftermarket:Direct-to-consumer replacement and upgrade channels bypassing OEM specification. US specialty distributors and German tuning houses dominate this fragmented segment with size-configured inventory models.
Electric Vehicles command the steepest expansion trajectory as platform engineering mandates carbon wheel adoption. Sport Cars retain the highest pricing tolerance per unit.
End User:
Specification authority concentrates differently across direct OEM integration, delegated Tier-1 supply, and enthusiast self-selection with divergent technical support requirements.
- OEMs:Vehicle manufacturers issuing long-term platform supply agreements with embedded volume commitments and design control. German premium automakers are consolidating carbon wheel sourcing into single-source contracts with dedicated capacity reservations.
- Tier-1 Suppliers:Wheel system integrators managing composite rim procurement, metallic hardware sourcing, and assembly validation. Italian and US Tier-1s are building captive carbon fiber layup capacity to secure margin capture from OEM customers.
- Automotive Enthusiasts:Individual purchasers through specialty retailers and direct channels. California and Texas markets show highest per-capita specification rates for track-day and show vehicle applications.
- Race Teams:Competition operators requiring FIA-compliant wheel specifications with rapid replacement logistics. German and UK motorsport clusters sustain premium pricing through homologated supply relationships.
Procurement volume concentrates with OEMs. Margin expansion is fastest among Tier-1 Suppliers building backward integration into composite manufacturing.
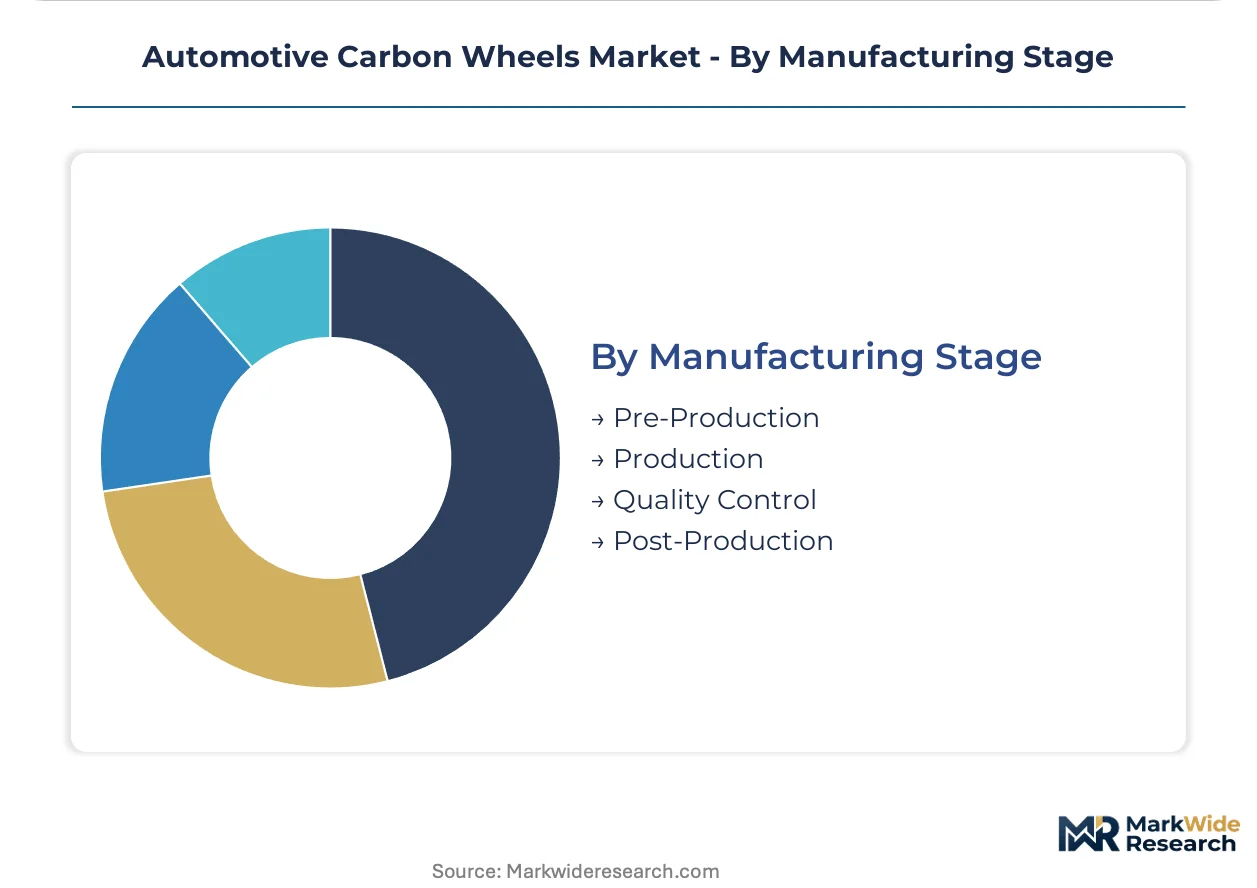
Manufacturing Stage:
Process control requirements intensify through production sequences, with quality validation representing the dominant cost center in road-certification pathways.
- Pre-Production:Fiber selection, resin formulation, and tool design for specific rim geometries. German and Italian composite specialists concentrate proprietary know-how in this stage, limiting technology transfer.
- Production:Filament winding, preform layup, autoclave curing, and machining operations. High-pressure curing equipment for one-piece rims concentrates in specialized German and Italian facilities.
- Quality Control:Non-destructive testing, dimensional verification, and fatigue cycle validation. NHTSA road-approval protocols extend this stage by 18-24 months for novel rim geometries entering US certification.
- Post-Production:Surface finishing, protective coating application, and logistics preparation. REACH compliance documentation for epoxy hardener chemistries has added tier-3 supplier traceability obligations to this stage.
Capital deployment concentrates in Production. Regulatory complexity is expanding fastest in Quality Control as multi-jurisdiction certification requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German premium automakers and motorsport clusters anchor carbon wheel demand through FIA-homologated supply chains and EV platform engineering mandates. Regulatory pressure on material traceability and unsprung mass reduction targets are redistributing procurement authority across four concentrated national markets.
Germany
FIA-homologated wheel testing protocols and skateboard EV architectures drive specification intensity. The EU F-Gas Regulation and REACH compliance tighten material traceability for composite suppliers. Stuttgart and Munich host dedicated carbon fiber curing facilities serving premium OEM platform programs.
United States
California fleet electrification mandates and Texas track-day culture split demand between OEM procurement and enthusiast aftermarket channels. The NHTSA crashworthiness protocols extend road-approval timelines for novel rim geometries. Southern California mobility services consolidate wheel procurement into lifecycle contracts bypassing dealer networks.
Italy
Premium sports car brake thermal management requirements concentrate demand for hybrid carbon-metallic disc architectures. CE marking and MDR frameworks extend material conformity obligations to composite components. Emilia-Romagna motorsport clusters transfer validation expertise into road-car supply chains.
Japan
Aftermarket aesthetic differentiation and lightweighting targets for kei-car electrification sustain dual demand channels. METI industrial policy supports domestic carbon fiber precursor supply security. Osaka-based tuning houses configure multi-spoke carbon designs for direct-to-enthusiast distribution.
United Kingdom
Ultra-luxury marques bundle carbon wheels in option packages with 400-600% pricing premiums over forged aluminum. FIA competition eligibility requirements sustain homologated supply relationships. Motorsport Valley clusters around Silverstone compress development cycles for road-car technology transfer.
Automotive Carbon Wheels Market Vendor Landscape
Capacity expansion dominates the current landscape as Tier-1 suppliers build captive carbon fiber layup facilities to secure margin capture from OEM customers. The vendor base stratifies across three tiers: integrated composite specialists with proprietary curing technology, wheel system integrators managing outsourced rim procurement and assembly validation, and aftermarket distributors configuring size-specific inventory for enthusiast channels. Strategic archetypes include aerospace-derived automation adopters, bio-based resin qualification leaders, and direct-to-fleet procurement disintermediators. M&A activity concentrates on autoclave capacity acquisition, while technology licensing agreements transfer filament winding expertise across automotive-aerospace boundaries.
Among Australian-registered composite specialists, Carbon Revolution occupies a position exemplifying proprietary one-piece manufacturing archetypes. Rotobox and HRE represent distinct specialization vectors within the premium tier—Rotobox anchoring braided carbon-composite architectures for impact tolerance, HRE sitting within North American aftermarket channel control for forged and carbon hybrid configurations. These three entities illustrate how geographic clustering around motorsport ecosystems and EV platform engineering centers shapes competitive positioning without requiring identical scale or integration depth.
| Leading Market Players |
|---|
| Vossen |
| Rotobox |
| Carbon Revolution |
| Weds |
| Vision Composite Products |
| DYMAG |
| BST |
| BUCCI Composites |
| HRE |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between FIA-homologated motorsport wheels and road-certified OEM specifications manifests in divergent pricing architectures and supply chain configurations. Premium homologated products command sustained margin pools through German and Italian curing facility access, while entry-level carbon wheels face cost compression from flow-formed aluminum substitution in mid-performance segments.
Pricing Analysis
Acrylonitrile precursor volatility passes through directly to carbon fiber wheel pricing, compressing margins for manufacturers without long-term PAN supply agreements. Three-tier pricing structure across premium homologated, standard OEM-fitment, and economy aftermarket levels differentiates on certification grade and thermal management specification. Pricing pressure stems from aluminum forging substitution at 60% lower cost-per-kilogram in volume vehicle segments. Fleet procurement teams at California mobility services exhibit highest price sensitivity, while German motorsport clusters sustain lowest sensitivity through FIA compliance requirements.
Supply Chain Analysis
Transatlantic freight costs for autoclave-cured rim preforms from German and Italian facilities to North American OEM plants concentrate working capital in transit inventory. Polyacrylonitrile precursor supply draws from Asian petrochemical complexes, carbon fiber tow production centers in Germany and Japan, and epoxy hardener formulation in Belgian and Dutch chemical hubs. Single-source autoclave capacity for one-piece rim construction creates vulnerability to equipment downtime or energy cost spikes. Distribution runs through Tier-1 wheel system integrators managing composite rim procurement, metallic hardware sourcing, and assembly validation for OEM platform programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon wheel procurement represents a geographic-arbitrage play between EU regulatory compliance costs and US Inflation Reduction Act domestic content credits, with North American manufacturing localization capturing margin differential against REACH-documentation-intensive European supply.
For Market Incumbents: Lock in captive carbon fiber layup capacity through German and Italian autoclave facility acquisitions or long-term dedicated reservations. Secure backward integration into PAN precursor supply through Asian petrochemical partnerships to defend against acrylonitrile price volatility. Qualify bio-based resin systems ahead of anticipated ECHA restriction expansions to preempt compliance-driven specification loss. For New Entrants and Emerging Players: Capture direct-to-fleet procurement channels in California and Germany where corporate electrification mandates consolidate vehicle, charging, and maintenance spend under single vendor relationships. Target aftermarket aesthetic differentiation segments in Texas and Japan where enthusiast self-selection bypasses OEM specification authority. Pursue thermoplastic resin transfer molding technology licensing to collapse cycle-time gaps with incumbent autoclave processes. For Investors and Strategic Acquirers: Asymmetric upside sits with Tier-1 suppliers building backward integration into composite manufacturing to secure margin capture from OEM customers. Five-to-ten year viability hinges on in-wheel motor integration adoption curves and brake-thermal management solution maturation. Watch for NHTSA road-approval timeline compression as signal of regulatory pathway normalization enabling faster product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Autoclave Capacity Acquisition | Secures dedicated curing infrastructure for OEM platform volume commitments in Germany and Italy. |
| Bio-Based Resin Qualification | Preempts REACH SVHC screening expansion for epoxy hardener chemistries in European supply chains. |
| North American Manufacturing Localization | Captures IRA domestic content credits for EV component sourcing in California and Texas markets. |
| In-Wheel Motor Thermal Partnership | Creates co-development relationships for brake-thermal management in skateboard EV architectures. |
| Direct-to-Fleet Procurement Channel | Bypasses traditional dealer markups through lifecycle contracts with California mobility services. |
Methodological Framework
Multiple input streams — OEM platform engineering interviews, Tier-1 supplier procurement assessments, aftermarket distributor configuration data, and motorsport team specification reviews — were reconciled against secondary validation from EPA fuel economy filings, NHTSA crashworthiness protocols, EU F-Gas Regulation documentation, and vehicle production databases. Bottom-up triangulation across carbon fiber wheel installation volumes and top-down cross-reference against electric vehicle platform engineering sign-off criteria anchored value estimates.
Historical adoption patterns for lightweight wheel technologies were cross-referenced against expert panel inputs from composite manufacturing specialists and regulatory affairs leads. Segmentation modeling spanned product type, application architecture, end-user procurement authority, and manufacturing stage process control. CAGRs were derived from slope analysis across the projection horizon, incorporating battery-electric vehicle platform ramp schedules and FIA homologation protocol evolution as industry-specific forecast inputs.
Acrylonitrile supply disruption, NHTSA certification timeline extension, and EU REACH restriction expansion are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
All-Terrain Vehicle Tire Market
Tires and Wheels
Rail Road Wheels Market
Tires and Wheels
GCC Tire Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
Alloy Wheels Market
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
Global High Performance Tires Market
Tires and Wheels
Automotive Summer Tire Market
Tires and Wheels
Bus Radial Tire Market