
 Intelligent Tire Market | 2026-2036
Intelligent Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Tire Market Intelligence
Leasing-based fleet procurement is rewriting competitive dynamics in the intelligent tire sector by lowering capital barriers for mid-size logistics operators. Continental AG leverages captive sensor manufacturing to sustain margin control across TPMS-integrated product lines. Michelin Group anchors its position through backward integration into IoT sensor supply chains. Bridgestone Corporation differentiates via R&D intensity in predictive maintenance algorithms.
Intelligent tires embed pressure, temperature, and acceleration sensors within the tire carcass or valve assembly, transmitting real-time data through RF or Bluetooth protocols to vehicle ECUs or cloud platforms for safety and operational optimization. The technology dimension shows TPMS as the mature baseline while IoT sensors capture expanding margin pools through subscription-based fleet analytics. Product type segmentation reveals truck tires as the fastest-growing category, driven by long-haul fleet operators seeking fuel efficiency gains from continuous pressure optimization. Application segmentation positions predictive maintenance as the emerging value center, displacing basic safety monitoring in OEM pricing structures.
NHTSA mandates TPMS integration on all US light vehicles, while the EU F-Gas Regulation pressures refrigerant-dependent tire inflation systems toward lower-GWP alternatives. Japan's METI promotes connected mobility standards that accelerate JIS certification requirements for sensor-embedded tires. Stakeholders must monitor how regulatory divergence between EPA emissions testing protocols and EU Green Deal material traceability rules reshapes cross-border product qualification costs.
Market Dynamics
Fleet operators now treat tire data as a fuel-cost control layer, forcing OEMs to integrate sensor architectures earlier in vehicle development cycles rather than as aftermarket add-ons.
Growth Catalysts
- NHTSA TPMS Mandates:US regulations require direct tire pressure monitoring on all light vehicles, compelling automakers to specify intelligent tire platforms from factory assembly lines.
- Long-Haul Logistics:Commercial trucking fleets deploy continuous pressure optimization systems to capture measurable fuel efficiency gains across interstate routes.
- EU F-Gas Regulation:Restrictions on high-GWP refrigerants in tire inflation systems accelerate migration toward sensor-based pressure management alternatives.
Market Restraints
- Sensor Cost Concentration:MEMS pressure and temperature sensing elements depend on concentrated semiconductor fabrication capacity in East Asian foundry networks.
- Tire Replacement Cycles:Extended commercial tire lifespans delay sensor hardware refresh rates, compressing recurring revenue windows for platform providers.
- RF Interference Limits:Dense electromagnetic environments in urban logistics hubs constrain reliable Bluetooth Low Energy transmission ranges for valve-integrated sensors.
Strategic Opportunities
- Subscription Fleet Analytics:Cloud-based tread wear prediction services create recurring revenue streams beyond hardware sales to logistics operators.
- Japan METI Connected Mobility Standards:Accelerated JIS certification pathways for sensor-embedded tires open procurement channels for Japanese domestic OEMs.
- Agricultural Tire Monitoring:Off-highway equipment operators in precision farming segments represent an underpenetrated vertical for soil-pressure sensing applications.
Industry Challenges
- Embedded Systems Engineering Talent:Shortages of RF antenna designers familiar with rubber-tire material properties delay product validation timelines.
- Cross-Platform ECU Integration:Proprietary vehicle bus protocols force redundant engineering cycles for each OEM qualification program.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Tire Market |
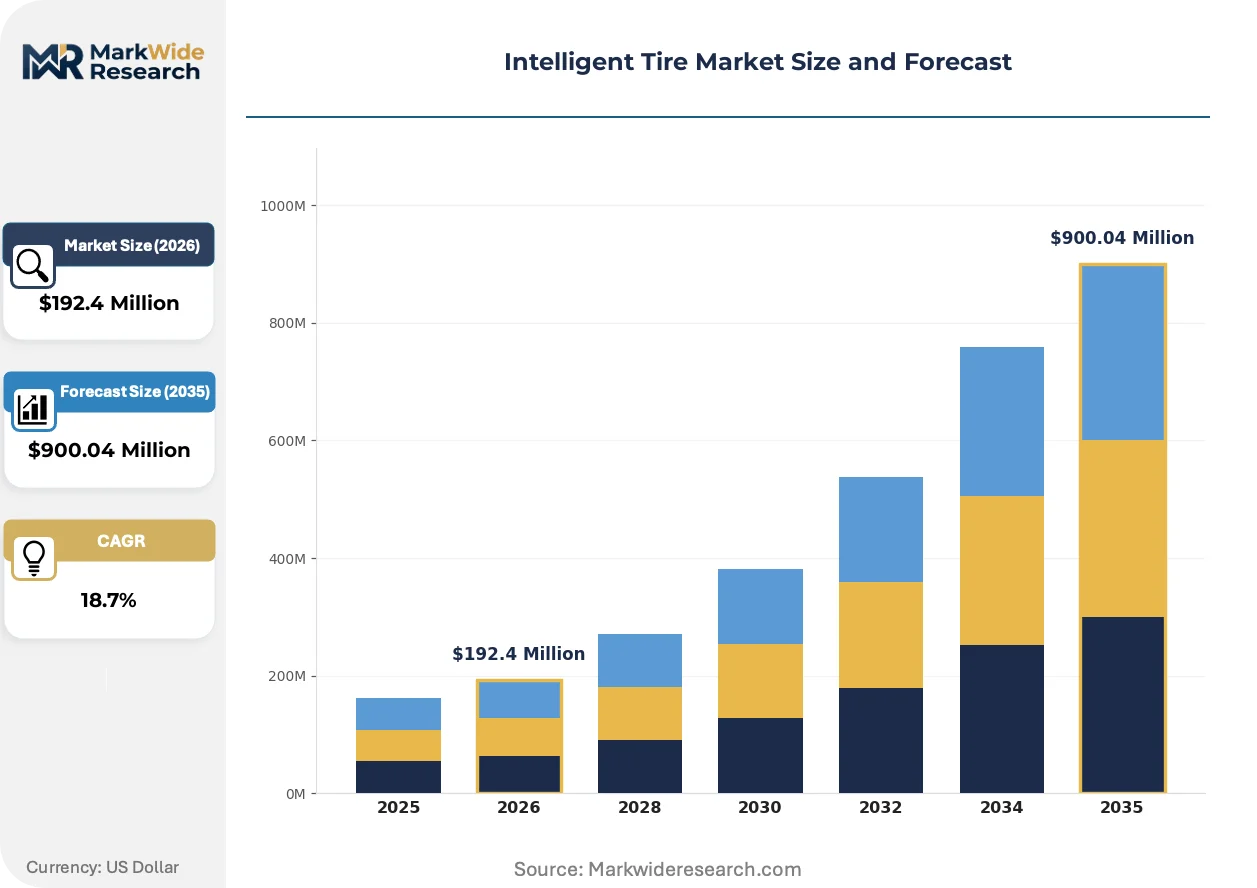
| Market Size in 2026 | $192.4 Million |
| Market Size in 2035 | $900.04 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: TPMS, RFID, Bluetooth, IoT Sensors Product Type: Passenger Tires, Truck Tires, Racing Tires, Off-Road Tires End User: OEMs, Fleets, Retailers, Aftermarket Providers Application: Safety Monitoring, Performance Tracking, Predictive Maintenance, Fleet Management |
| Companies Covered | The Goodyear Tire & Rubber Company, Sumitomo Rubber Industries, Ltd., Continental AG, Samsung Electronics, NEXEN TIRE Corporation, Bridgestone Corporation, Pirelli & C. S.p.A, LG Electronics, Michelin Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Tire Market Strategic Shifts & Innovations
Sensor fusion architectures are merging tire-derived data with vehicle dynamics models, creating unified predictive platforms that compress maintenance decision cycles from weeks to hours.
Multi-physics sensing modules is hybridizing pressure, temperature, and accelerometer inputs into single-package tire carcass assemblies. Tier-1 suppliers are qualifying these integrated units for 150,000-mile commercial lifecycles. The consolidation is hybridizing hardware procurement patterns, reducing supplier counts per vehicle platform from three discrete vendors to one system integrator.
EU Green Deal material traceability rules now require documented recycled content percentages in tire carcass compounds. This pressures compounders to requalify sensor adhesion chemistries for sustainable rubber formulations. German production clusters are responding fastest, with KBA-type approval processes already adapted for circular material certification pathways.
Leasing-based fleet procurement now dominates mid-size logistics operator tire acquisition, transferring capital risk to lessors who specify intelligent tire platforms as standard equipment. Equipment finance subsidiaries of major tire manufacturers capture this channel, displacing independent distributors in fleet account relationships. The shift concentrates most visible in Germany's Rhine-Ruhr logistics corridor, where full-service lease penetration exceeds traditional purchase models.
Intelligent Tire Market Segmentation
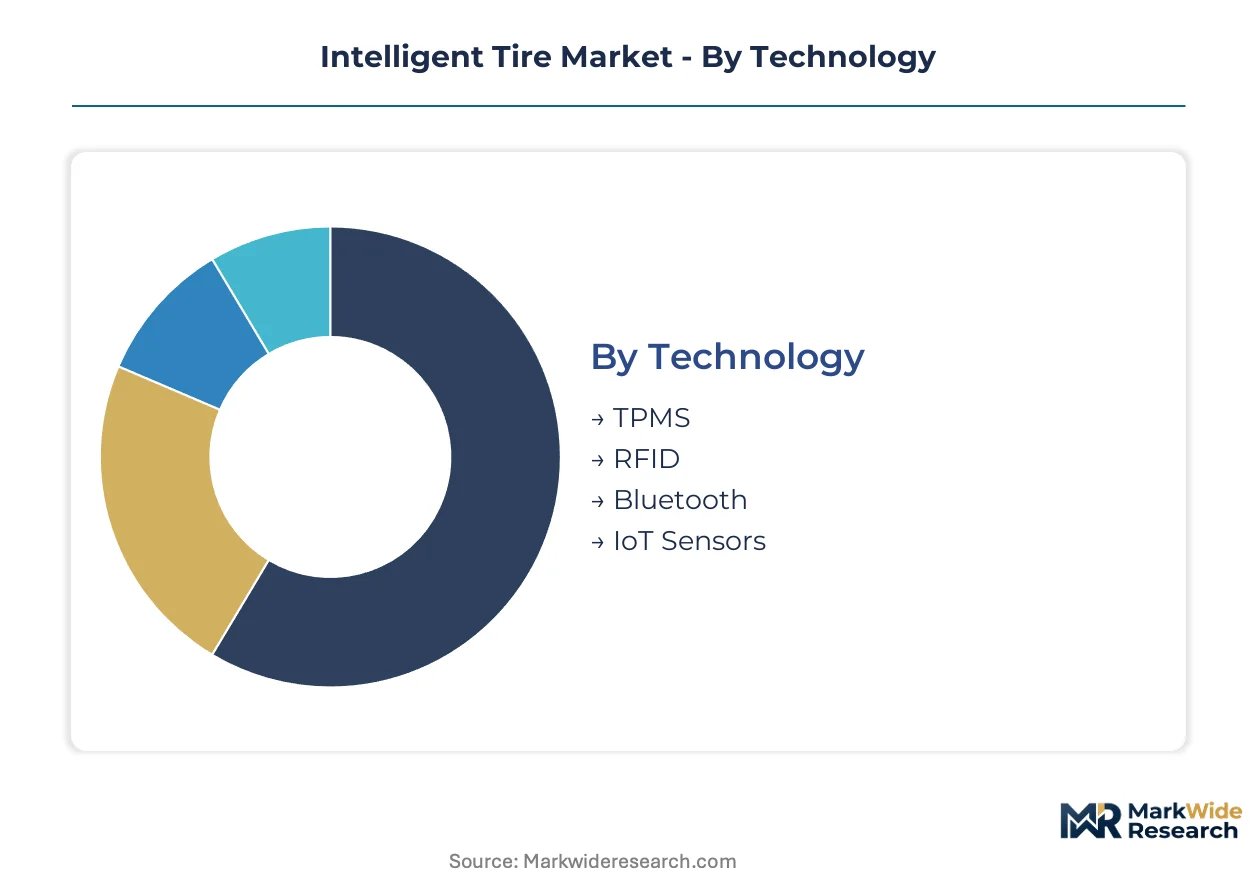
Intelligent tire architectures vary sharply by data transmission protocol, vehicle duty cycle, and procurement channel. Segment boundaries determine margin capture, sensor integration depth, and recurring revenue potential for platform providers.
Technology:
Cost tier stratification separates mature regulatory-mandated systems from emerging connected platforms commanding subscription premiums.
- TPMS:Direct pressure monitoring systems embed MEMS sensors within the tire valve or carcass, transmitting real-time pressure alerts to vehicle ECUs via RF protocols. US NHTSA mandates have saturated light-vehicle OEM specifications, compressing hardware margins while locking in baseline sensor volumes across Detroit Three and Japanese transplant assembly plants.
- IoT Sensors:Multi-parameter modules fuse pressure, temperature, and accelerometer inputs with edge computing capability for cloud-connected fleet analytics. Long-haul logistics operators in Germany's Rhine-Ruhr corridor specify these platforms to capture fuel efficiency gains from continuous pressure optimization algorithms.
- RFID:Passive identification tags enable tire lifecycle tracking from manufacturing through retreading operations without battery dependence. Tire retreaders in France deploy RFID for compound batch traceability under EU Green Deal material certification requirements.
- Bluetooth:Low-energy protocols support smartphone-direct diagnostics for consumer aftermarket applications. Urban logistics hubs face RF interference constraints that limit reliable transmission ranges for valve-integrated Bluetooth sensors.
TPMS holds installed capacity. IoT Sensors is rotating up the share rankings.
Product Type:
Application intensity and duty cycle severity determine sensor packaging robustness and data transmission frequency requirements.
- Truck Tires:Commercial long-haul specifications integrate reinforced sensor housings rated for 150,000-mile lifecycles and sustained highway vibration loads. Fleet operators across US interstate corridors treat continuous pressure data as a fuel-cost control layer, forcing earlier OEM integration of sensor architectures.
- Passenger Tires:Light-vehicle platforms prioritize cost-optimized TPMS compliance over multi-parameter sensing. Japanese OEMs accelerate JIS certification requirements for sensor-embedded tires under METI connected mobility standards.
- Off-Road Tires:Construction and mining applications demand shock-resistant sensor packages for uneven terrain operations. Precision farming segments in Germany represent underpenetrated demand for soil-pressure sensing variants.
- Racing Tires:Motorsport specifications require millisecond-latency temperature and pressure telemetry for pit strategy optimization. Track-side RF infrastructure constraints limit Bluetooth protocol adoption in professional racing series.
Passenger Tires dominates unit volumes. Truck Tires commands value concentration.
End User:
Procurement authority and capital structure shape platform specification power and pricing leverage.
- Fleets:Full-service leasing subsidiaries of major tire manufacturers specify intelligent platforms as standard equipment, transferring capital risk from mid-size logistics operators. Germany's equipment finance channel concentrates procurement authority with captive lessors.
- OEMs:Vehicle assemblers integrate sensor architectures during development cycles rather than accepting aftermarket add-ons. NHTSA TPMS mandates compel factory specification across all US light-vehicle production lines.
- Aftermarket Providers:Independent distributors face displacement as leasing-based procurement rewrites fleet account relationships. Sensor cost concentration in East Asian foundry networks constrains margin flexibility for aftermarket installers.
- Retailers:Consumer-facing channels emphasize smartphone-compatible Bluetooth diagnostics for DIY pressure monitoring. Urban RF interference limits constrain reliable product performance claims in dense metropolitan markets.
Fleets is expanding most quickly in specification influence. OEMs retains volume anchoring.
Application:
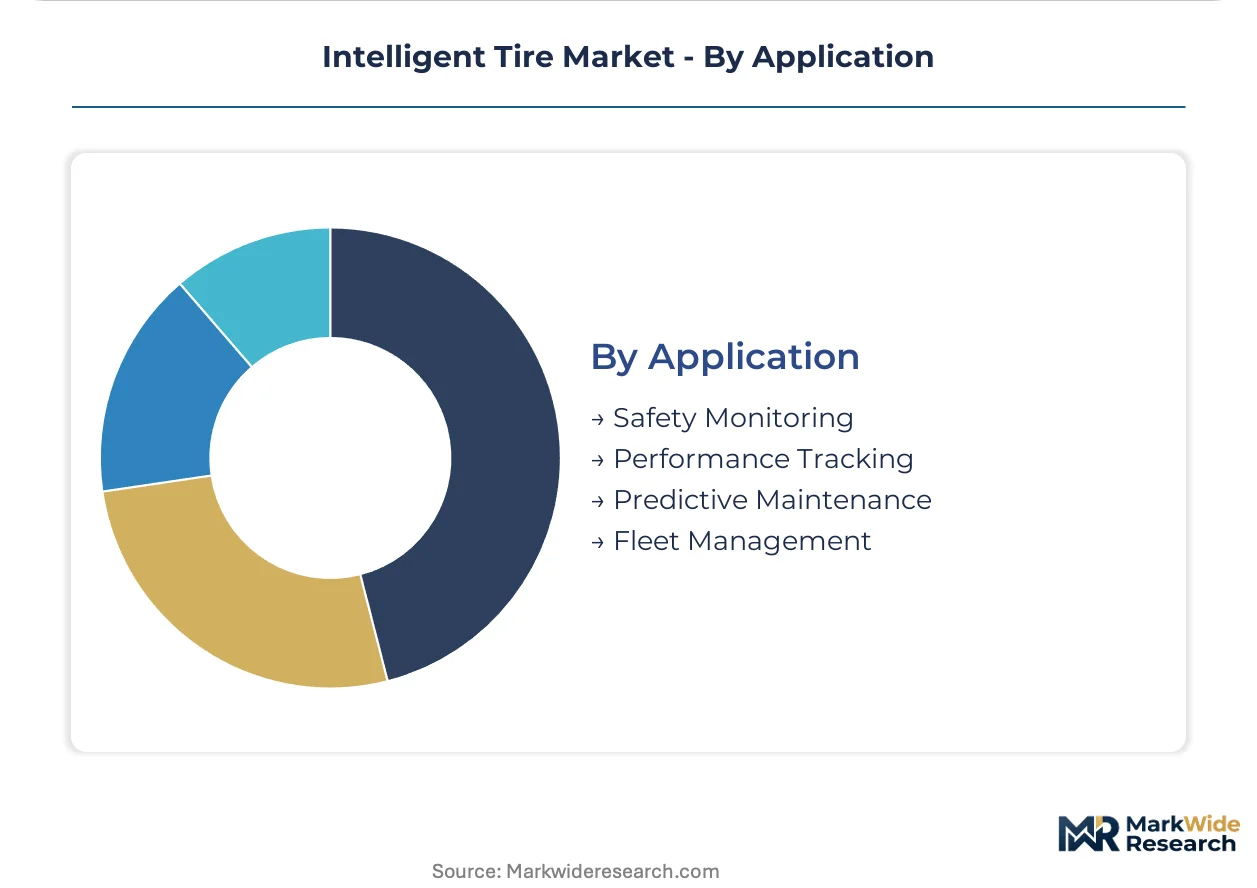
Value capture migrates from safety compliance toward operational optimization as fleet operators monetize tire-derived data.
- Predictive Maintenance:Cloud-based tread wear algorithms compress maintenance decision cycles from weeks to hours using sensor fusion with vehicle dynamics models. German production clusters adapt KBA-type approval processes for circular material certification pathways.
- Safety Monitoring:Pressure and temperature alerting functions satisfy baseline regulatory requirements without recurring revenue streams. EU F-Gas Regulation pressures refrigerant-dependent inflation systems toward sensor-based alternatives.
- Fleet Management:Unified platforms merge tire data with route optimization and fuel consumption analytics. Cross-platform ECU integration challenges force redundant engineering cycles for each OEM qualification program.
- Performance Tracking:Motorsport and premium consumer segments demand granular telemetry for driving behavior analysis. Embedded systems engineering talent shortages delay validation timelines for RF antenna designs compatible with rubber-tire material properties.
Safety Monitoring holds regulatory-mandated baseline. Predictive Maintenance is climbing the fastest toward value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA TPMS mandates in the United States, EU F-Gas Regulation compliance pressures, and Japan METI connected mobility standards are redirecting OEM procurement toward sensor-embedded tire platforms across major automotive production zones.
United States
Long-haul logistics operators across interstate corridors deploy continuous pressure optimization systems to capture fuel efficiency gains. NHTSA mandates direct tire pressure monitoring on all light vehicles, compelling Detroit Three assemblers to specify intelligent tire platforms from factory lines. The Midwest manufacturing belt anchors sensor integration engineering for commercial truck specifications.
Germany
Rhine-Ruhr logistics corridor fleets treat tire data as a fuel-cost control layer, accelerating full-service lease penetration over traditional purchase models. KBA-type approval processes adapt for circular material certification pathways under EU Green Deal rules. Continental AG and Michelin Group anchor production clusters for premium intelligent tire platforms in Lower Saxony and Baden-Württemberg.
Japan
Domestic OEMs accelerate JIS certification requirements for sensor-embedded tires under METI connected mobility standards. Precision farming segments in Hokkaido represent underpenetrated demand for soil-pressure sensing variants. Kansai and Chubu industrial zones concentrate MEMS sensor packaging expertise for 150,000-mile commercial lifecycles.
China
Commercial fleet operators in Yangtze River Delta logistics hubs specify IoT sensor modules for cloud-connected analytics. MIIT promotes connected vehicle standards that accelerate domestic qualification pathways for multi-parameter sensing architectures. Pearl River Delta electronics clusters supply MEMS fabrication capacity for pressure and temperature sensing elements.
France
Tire retreaders deploy RFID for compound batch traceability under EU Green Deal material certification requirements. ANSM and CNIL oversight shapes data governance frameworks for cloud-based fleet analytics platforms. Auvergne-Rhône-Alpes hosts compounder facilities requalifying sensor adhesion chemistries for sustainable rubber formulations.
Intelligent Tire Market Key Industry Players
Channel-controlling players compete with product-specialist players across a consolidated structure where captive equipment finance subsidiaries rewrite fleet procurement relationships. Three archetypes dominate: integrated tire-sensor manufacturers with backward integration into IoT supply chains, electronics conglomerates leveraging semiconductor fabrication scale, and pure-play tire makers defending position through predictive maintenance algorithm development. Competitive moves concentrate on strategic partnerships for ECU integration and geographic expansion through leasing-based fleet account capture.
Among integrated tire manufacturers, Continental AG exemplifies the captive sensor production archetype, while Michelin Group occupies a position defined by upstream control over IoT sensor supply chains. Bridgestone Corporation represents the R&D-intensive tier focused on predictive maintenance capabilities. Samsung Electronics and LG Electronics sit within the electronics conglomerate tier, leveraging semiconductor fabrication scale for MEMS sensing elements.
| Leading Market Players |
|---|
| The Goodyear Tire & Rubber Company |
| Sumitomo Rubber Industries, Ltd. |
| Continental AG |
| Samsung Electronics |
| NEXEN TIRE Corporation |
| Bridgestone Corporation |
| Pirelli & C. S.p.A |
| LG Electronics |
| Michelin Group |
| Others |
Cost & Logistics Intelligence
Single-source dependency on East Asian MEMS foundry capacity for pressure and temperature sensing elements determines both pricing tier spreads and supply chain shape, forcing tier-1 suppliers to absorb semiconductor volatility into long-term contract structures while fleet lessors capture margin through captive equipment finance channels.
Pricing Analysis
Certification level creates the primary spread between basic TPMS compliance modules and premium IoT sensor platforms with JIS or KBA-type approval pathways. Three-tier pricing structure across premium, standard, and economy levels reflects integration depth, with subscription-based fleet analytics commanding recurring revenue premiums over transactional hardware sales. Cost compression in the standard tier is intensifying because MEMS sensor cost concentration constrains margin flexibility for aftermarket providers. Independent distributors exhibit highest price sensitivity, while full-service leasing subsidiaries of major tire manufacturers demonstrate lowest sensitivity due to bundled service economics.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor manufacturing equipment limit MEMS fabrication capacity expansion outside established East Asian networks. Sensor element production draws from Taiwan, South Korea, and China, while tire carcass manufacturing rests on German and Japanese rubber compounding expertise. Raw material dependencies include semiconductor-grade silicon wafers, specialized rubber adhesion chemistries, and RF antenna substrates. Single-source vulnerability concentrates in 150,000-mile-rated sensor packaging qualification, where only two suppliers hold validated commercial lifecycle data. Distribution runs through equipment finance subsidiaries that specify intelligent platforms as standard lease equipment, displacing traditional aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator adoption of subscription analytics represents an early-cycle expansion story, with penetration rates in long-haul logistics corridors accelerating as fuel-cost control becomes a procurement priority.
For Market Incumbents: Insulate margin structures by deepening backward integration into IoT sensor supply chains and securing exclusive JIS certification pathways for Japanese OEM platforms. Threat substitution from electronics conglomerates leveraging semiconductor fabrication scale pressures hardware margin capture. Channel control through captive leasing subsidiaries remains the priority defensive lever. For New Entrants and Emerging Players: Build out precision farming applications in Hokkaido and Germany as the most penetrable vertical, where soil-pressure sensing variants face minimal incumbent saturation. Agricultural equipment operators represent white-space demand with limited qualified sensor packaging. A direct-to-fleet go-to-market angle bypasses OEM qualification bottlenecks. For Investors and Strategic Acquirers: Sensor-embedded tire platform specialists with validated 150,000-mile commercial lifecycle data command scarcity premiums in a consolidating vendor landscape. Long-term viability frames around recurring revenue capture from cloud-based tread wear prediction services displacing transactional hardware sales. Watch for inflection when KBA-type approval processes complete adaptation for circular material certification pathways under EU Green Deal rules.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Sensor Supply Chains | Captive semiconductor sourcing insulates margin from East Asian foundry volatility. |
| JIS Certification Pathway Investment | Accelerated METI-connected mobility compliance opens Japanese domestic OEM procurement. |
| Subscription Fleet Analytics Platform Launch | Cloud-based tread wear prediction creates recurring revenue beyond hardware sales. |
| Circular Material Certification Adaptation | KBA-type approval alignment with EU Green Deal rules secures premium platform positioning. |
| Precision Farming Sensor Development | Soil-pressure sensing variants address underpenetrated agricultural equipment demand. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with fleet operations directors, OEM platform engineers, tire manufacturer R&D heads, and aftermarket distribution managers; and secondary validation against NHTSA regulatory filings, EU F-Gas Regulation compliance databases, METI connected mobility standard publications, and vehicle production registration data. Bottom-up segment sizing triangulated with top-down market envelope checks.
Forecast inputs span technology adoption curves, regulatory mandate implementation timelines, and fleet procurement channel shifts across the projection horizon. Segmentation dimensions modeled include sensor protocol type, vehicle duty cycle severity, procurement authority structure, and application value capture migration. CAGRs derive from logistic diffusion curves fitted to observed fleet penetration patterns, with MEMS sensor cost trajectories and leasing channel growth rates as primary industry-specific inputs.
Stress conditions across semiconductor supply availability, regulatory divergence between EPA and EU Green Deal material traceability protocols, and RF interference constraints in dense urban logistics hubs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fleet operator data monetization readiness and OEM integration cycle timing. Material shifts in East Asian export-control enforcement or NHTSA mandate expansion scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
EV Tire Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Automotive Wheel Alignment Service Market
Tires and Wheels
Europe Tire Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Smart Tire Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Off-The-Road (OTR) Tire Market
Tires and Wheels
All-Terrain Vehicle Tire Market
Tires and Wheels
Automotive Steel Wheels Market
Tires and Wheels
Automotive Wheel Rims Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
Global Aircraft Tire Market
Tires and Wheels
Automotive 3D Printed Tires Market
Tires and Wheels
Rechargeable Tires Market