
 Bus Radial Tire Market | 2026-2036
Bus Radial Tire Market Size, Share, and Industry Trends Forecast 2026-2036
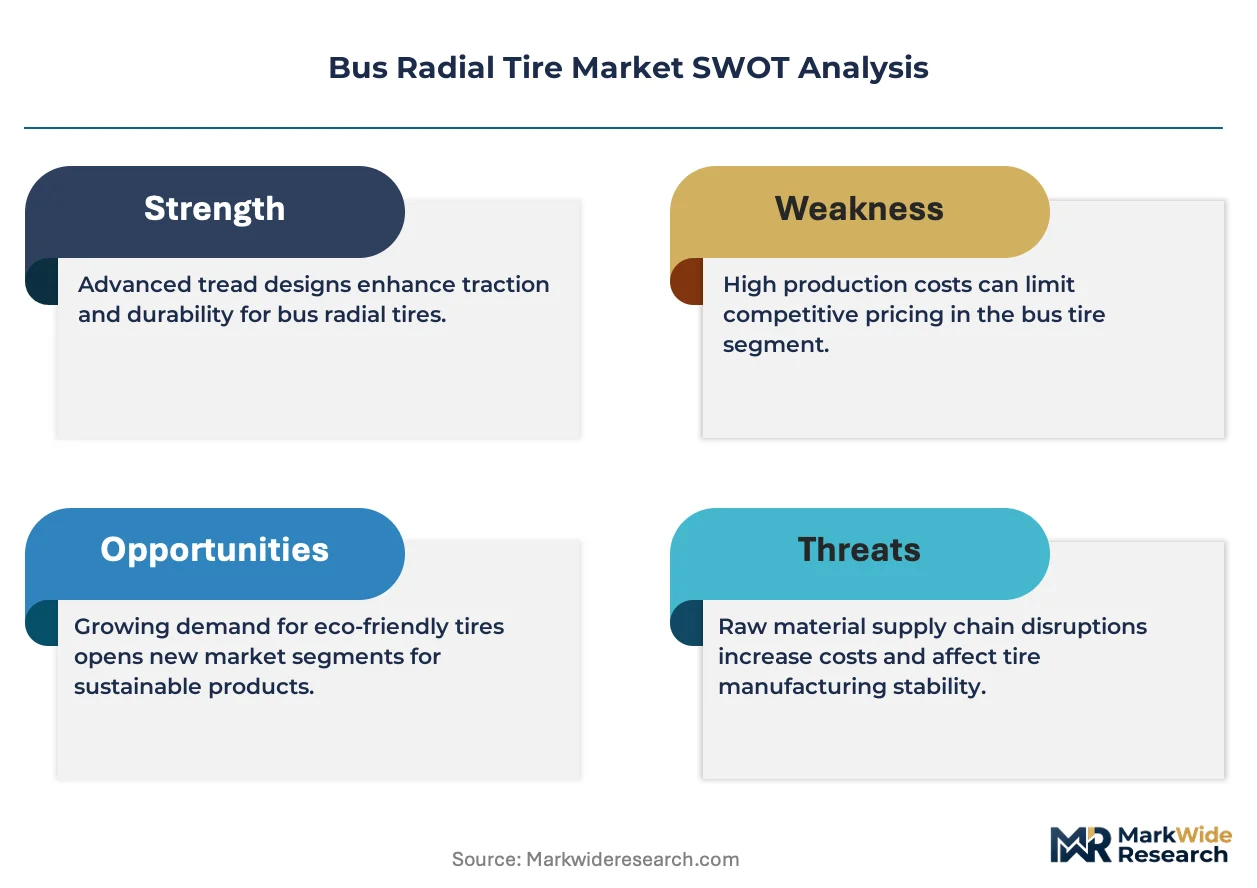
Bus Radial Tire Market Analysis
Asset-light leasing frameworks for commercial bus fleets is tilting procurement power toward fleet-management companies and away from direct tire purchasers. Michelin leverages its vertical integration into synthetic rubber compounding to sustain margin control across premium replacement cycles. Bridgestone anchors its position through captive supply of steel cord reinforcements, while Apollo Tyres dominates price-sensitive segments in South Asian markets through localized bead-wire production.
Bus radial tires employ steel-belted radial construction with multi-layer carcass designs rated for axle loads exceeding 13,000 kg, engineered to reduce rolling resistance and extend tread life under continuous urban duty cycles. The all-season product category leads volume shipments across temperate climate zones, though winter compounds command premium positioning in Nordic and alpine corridors. Public transport end users concentrate procurement through municipal tender frameworks, whereas tour bus operators prioritize 17-inch and 18-inch sizes for highway stability at sustained speeds.
Fleet operators in the European Union navigate CE marking and REACH compliance for tire labeling and chemical disclosure, while China's SAMR enforces GB standards on rolling resistance and wet-grip performance. India's BIS certification mandates puncture-resistance testing for radial bus tires deployed on national highway corridors. Stakeholders must monitor how evolving carbon-border mechanisms and extended producer responsibility frameworks reshape material sourcing decisions and regional manufacturing footprints.
Market Dynamics
Fuel-efficiency mandates across China, the European Union, and India are compressing replacement cycles and forcing compound reformulation toward low-hysteresis materials. Fleet operators now specify rolling-resistance grades in procurement tenders, transferring compliance burden upstream to tire manufacturers.
Growth Catalysts
- China's GB Standards:Mandatory rolling-resistance thresholds for commercial vehicle tires are accelerating R&D spending on silica-reinforced tread compounds. Domestic bus manufacturers must certify tire suppliers against these benchmarks.
- Intercity Coach Electrification:Battery-electric bus deployments in India and Europe impose heavier axle loads that radial construction handles more efficiently than bias-ply alternatives. State transport corporations specify radial fitments in fleet modernization tenders.
- Steel Cord Localization:Captive production of reinforcement materials in South Asia and Southeast Asia is shortening lead times for OEM supply agreements. Regional tire plants now source bead wire within 500-kilometer radii.
Market Restraints
- Natural Rubber Price Volatility:Thai and Indonesian supply disruptions transmit directly to compound costs, compressing margin buffers for tier-two manufacturers dependent on spot-market sourcing.
- Carbon Black Concentration:Five integrated producers control over seventy percent of furnace-grade supply for Asia-Pacific tire plants, creating input bottlenecks during energy-price spikes.
- Wet-Grip Trade-offs:Low-rolling-resistance formulations sacrifice traction coefficients below regulatory minimums in Nordic winter testing, limiting compound optimization headroom.
Strategic Opportunities
- India's PM-eBus Sewa Scheme:Central government subsidies for 10,000 electric buses create dedicated radial tire demand through state transport undertakings in Maharashtra, Karnataka, and Gujarat.
- Retreading Integration:Precured tread technology convergence with RFID-based casing tracking enables fleet-managed lifecycle programs that capture second-life revenue streams.
- EU Carbon Border Adjustment:Import tariffs on carbon-intensive tire components incentivize European production footprint expansion and green steel sourcing from Nordic electric-arc furnaces.
Industry Challenges
- Compound Formulation Talent:Shortage of polymer chemists with bus-tire-specific hysteresis modeling expertise delays new product validation timelines by eight to fourteen months.
- Multi-Homologation Burden:Simultaneous pursuit of India's BIS puncture-resistance certification, China's SAMR rolling-resistance labeling, and EU REACH chemical disclosure creates testing queue congestion.
- Legacy Fleet Compatibility:Mixed-age bus parches in Latin American and African markets require tread patterns and load ratings that diverge from standardized OEM specifications, fragmenting SKU portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bus Radial Tire Market |
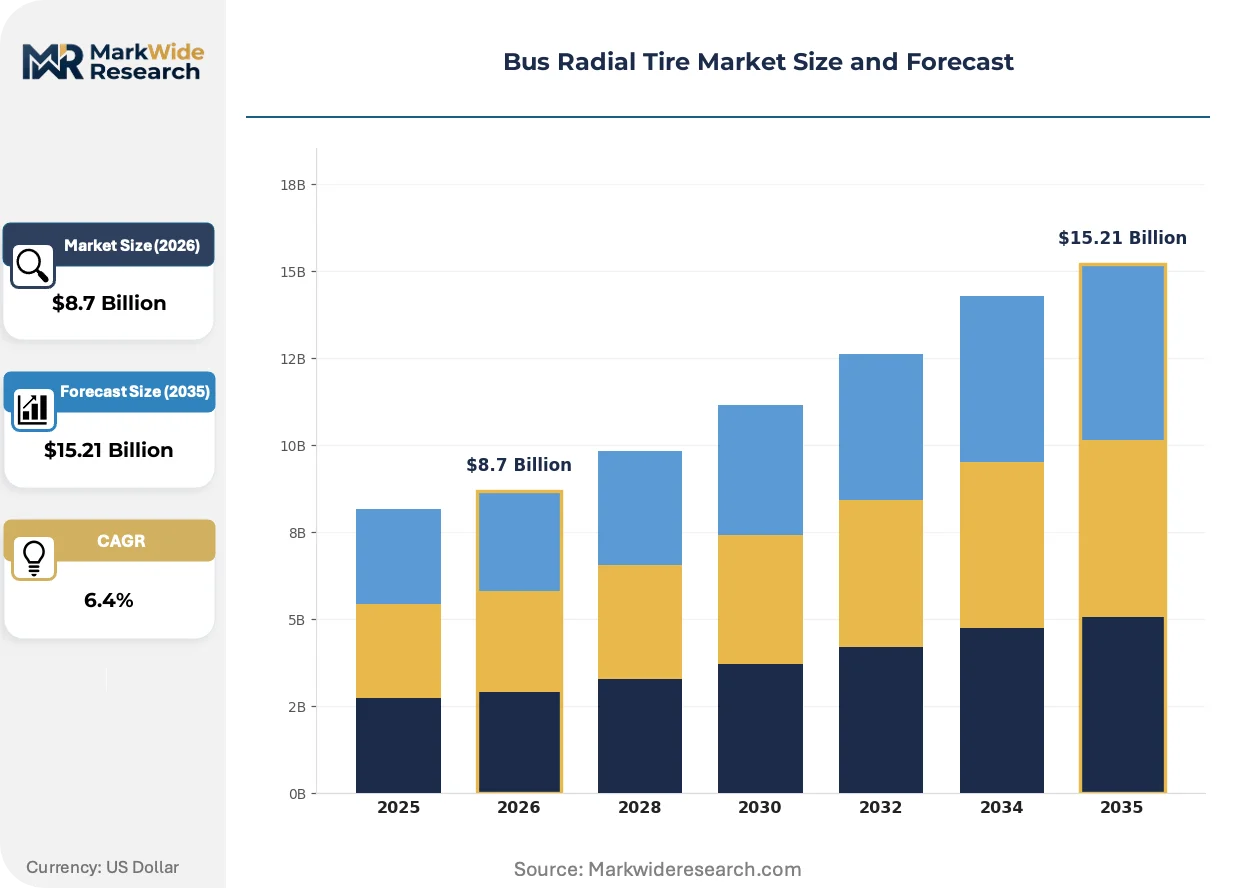
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Season, Winter, Summer, Specialty End User: Public Transport, Private Operators, Freight Services, Tour Bus Operators Size: 15 Inch, 16 Inch, 17 Inch, 18 Inch Material: Rubber, Steel, Polyester, Others |
| Companies Covered | Bridgestone, Michelin, Goodyear, Continental, Pirelli, Hankook, Yokohama Rubber, Apollo Tyres, China National Tire & Rubber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bus Radial Tire Market Emerging Trajectories
Material science advances and regulatory disclosure requirements are converging to redefine how bus radial tires are specified, manufactured, and managed through their service lives. Three developments dominate current strategic planning.
Silica-silane coupling systems are hybridizing traditional carbon-black reinforcement matrices to achieve simultaneous reductions in rolling resistance and heat buildup. European intercity operators specify these compounds in highway coach tenders, while Indian state transport corporations pilot them in high-frequency urban duty cycles. The technology is hybridizing competitive positioning between premium multinationals and regional compound specialists by raising the technical floor for new market entrants.
Europe's F-Gas Regulation on manufacturing emissions is forcing retooling of tire-curing press energy systems and solvent-based release-agent formulations. The industrial consequence extends beyond compliance costs to supplier qualification requirements for European OEM export contracts. Nordic and alpine corridor operators face compressed availability of winter-compound variants as manufacturers prioritize capacity for standard all-season SKUs with cleaner production footprints.
Fleet-management companies are consolidating procurement authority through tire-as-a-service contracts that unbundle acquisition from maintenance and replacement scheduling. Municipal tender frameworks in France and Germany now permit this model, displacing direct municipal purchasing departments. The shift is most visible in German Verkehrsverbund regional transport associations, where consolidated fleet pools exceed five thousand vehicles under single supplier agreements.
Bus Radial Tire Market Segmentation
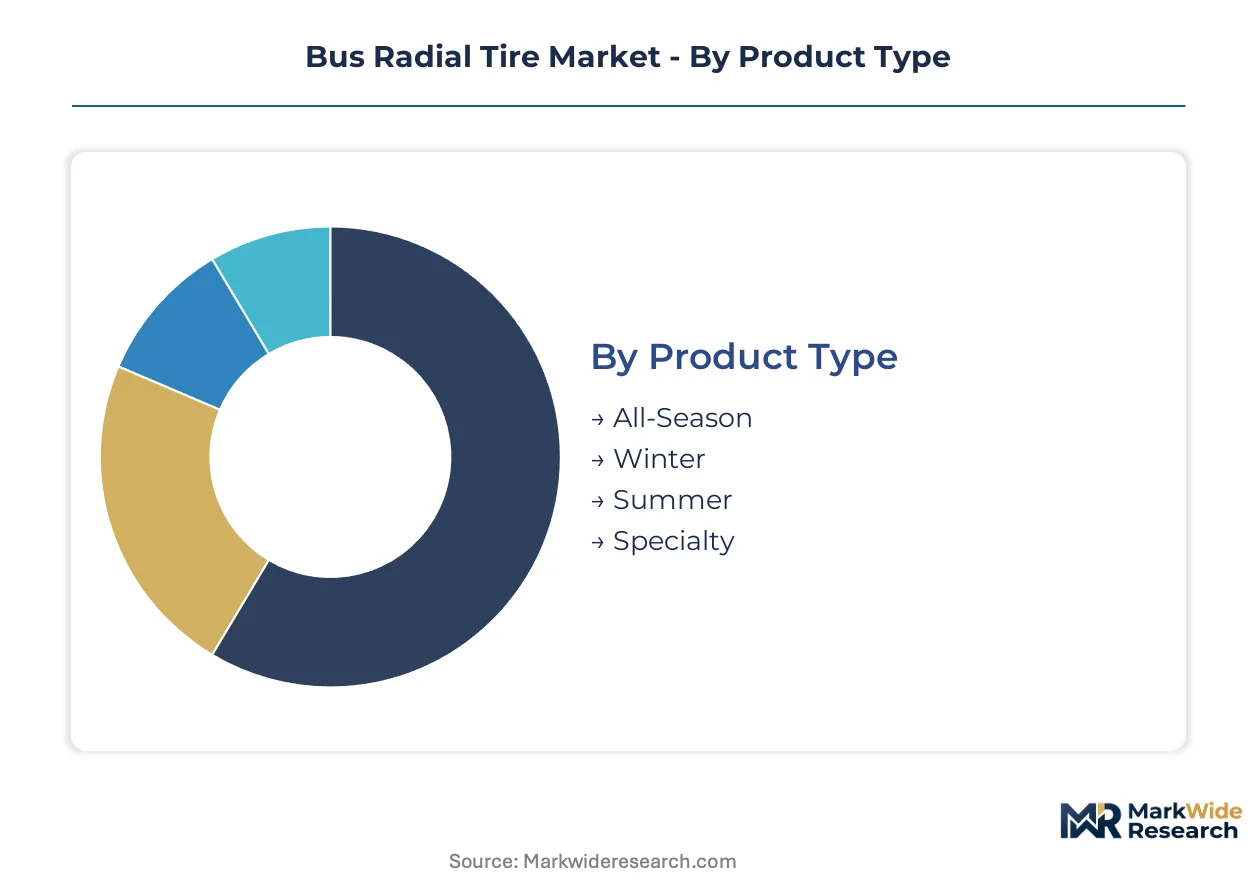
Segmentation in bus radial tires reveals how procurement specifications diverge across climate zones, duty cycles, and regulatory jurisdictions. Fleet operators segment demand through rolling-resistance grades and load ratings rather than brand preference alone.
Product Type:
Use-case spectrum spans Nordic winter corridors to tropical monsoon routes, with compound formulation driving specification divergence.
- All-Season:Multi-layer tread compounds balance wet-grip coefficients with rolling-resistance targets for temperate climate deployment. European intercity coach fleets concentrate procurement here under F-Gas Regulation compliance timelines, prioritizing silica-hybrid formulations that reduce hysteresis without sacrificing traction thresholds.
- Winter:Soft-tread polymers with siped block patterns maintain elasticity below minus 15 degrees Celsius for alpine and Nordic bus corridors. Norwegian and Swedish state transport undertakings mandate these fitments through municipal tender frameworks, though manufacturing capacity constraints from F-Gas retooling are compressing availability.
- Summer:High-silica compounds engineered for heat dissipation in sustained highway operation above 35 degrees Celsius ambient temperature.
- Specialty:Reinforced carcass designs for airport shuttle buses and mining-site personnel transport with puncture-resistant sidewall inserts.
The dominant share belongs to All-Season, while Winter is closing the gap fastest amid electrified fleet expansion into alpine corridors.
End User:
Procurement authority concentrates differently across municipal frameworks, commercial leasing structures, and captive fleet operations.
- Public Transport:State transport corporations in India, Germany, and Brazil consolidate purchasing through multi-year tender frameworks with total-cost-of-ownership clauses. India's PM-eBus Sewa Scheme directs specification toward 18-inch radial fitments for electric bus deployments in Maharashtra and Karnataka, with BIS puncture-resistance certification mandatory for national highway corridor service.
- Private Operators:Asset-light leasing companies in France and Germany are consolidating procurement authority through tire-as-a-service contracts that unbundle acquisition from lifecycle management. Verkehrsverbund regional transport associations now pool fleets exceeding five thousand vehicles under single supplier agreements.
- Freight Services:Mixed passenger-cargo configurations on intercity routes in Mexico and Turkey prioritize load ratings over rolling-resistance optimization.
- Tour Bus Operators:Highway stability at sustained speeds drives 17-inch and 18-inch size concentration for premium coach configurations.
Public Transport commands volume leadership, though Private Operators are expanding share fastest through fleet-management consolidation.
Size:
Axle load distribution and vehicle architecture determine diameter specification across urban duty cycles versus highway deployment.
- 17 Inch:Dominant specification for European intercity coaches requiring highway stability at sustained speeds above 100 kilometers per hour. Tour bus operators in Germany and France specify this diameter through OEM supply agreements, with bead-wire localization in South Asian plants shortening lead times.
- 18 Inch:Standard fitment for battery-electric bus platforms in India and Europe where heavier axle loads from battery packs demand reinforced carcass ratings. State transport undertakings in Gujarat and Karnataka specify 18-inch radials in PM-eBus Sewa tender documentation.
- 15 Inch:Legacy urban bus configurations in Latin American markets with mixed-age fleet parches.
- 16 Inch:Mid-size municipal transit buses in secondary Indian cities and Southeast Asian urban corridors.
17 Inch maintains installed base dominance, while 18 Inch is gaining share fastest through electrified fleet procurement.
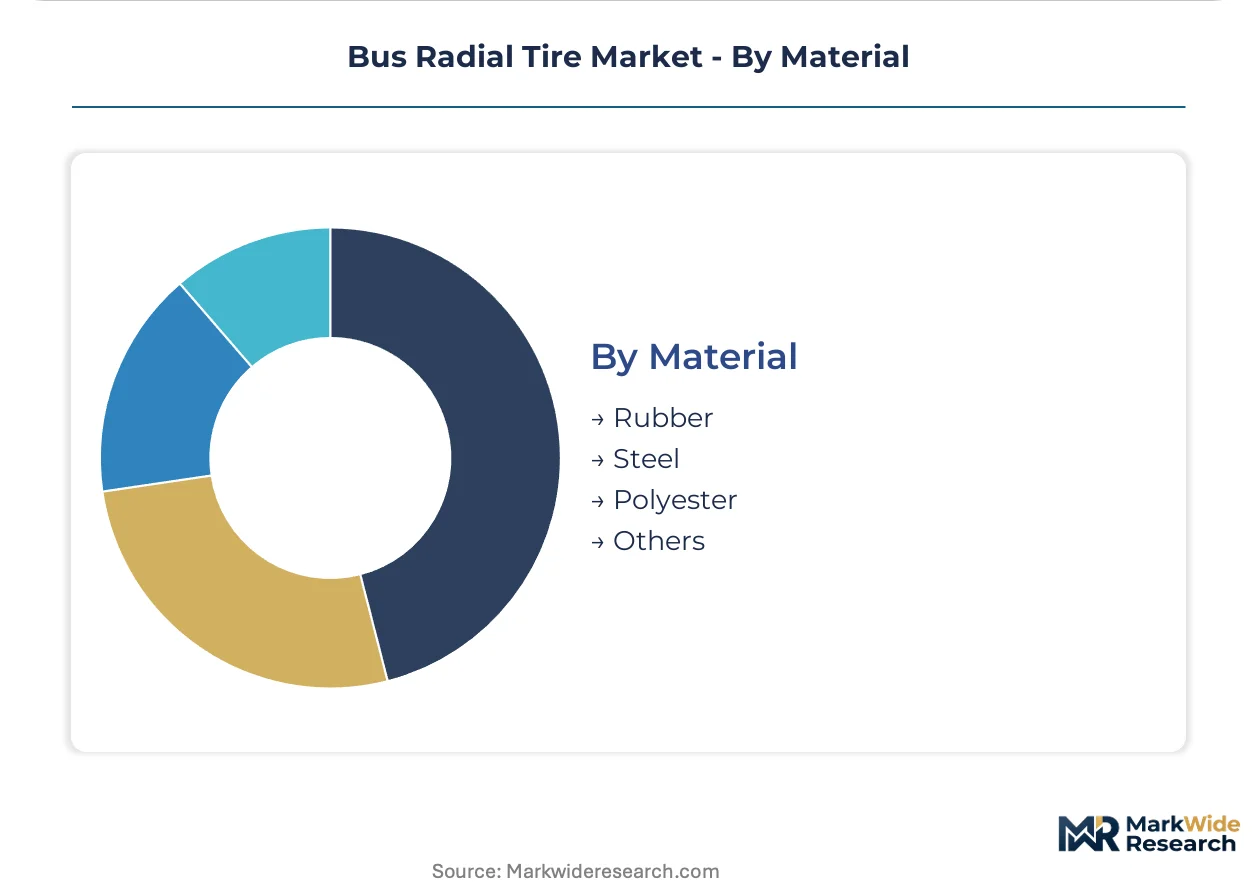
Material:
Supply chain configuration and carbon-border exposure are reshourcing reinforcement material sourcing decisions.
- Steel:High-tensile cord reinforcements in belt and bead packages handle axle loads exceeding 13,000 kilograms in multi-layer carcass designs. Bridgestone's captive supply of steel cord reinforcements anchors its position in premium replacement cycles, while regional plants in India and Thailand now source bead wire within 500-kilometer radii.
- Rubber:Natural rubber from Thai and Indonesian supply bases combines with synthetic polybutadiene in tread compounds, with price volatility transmitting directly to tier-two manufacturer margins.
- Polyester:Carcass ply material for lighter-duty urban bus configurations with reduced rolling-mass targets.
- Others:Aramid fiber reinforcements in specialty mining and airport applications with extreme puncture-resistance requirements.
Steel claims the dominant material share by weight, though Rubber compound reformulation is expanding fastest through low-hysteresis R&D mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet-management companies and state transport undertakings concentrate procurement authority across distinct regulatory jurisdictions, with electrification mandates and localization policies reshaping supply chain footprints in each major market.
China
Domestic bus manufacturers certify tire suppliers against mandatory GB rolling-resistance thresholds, compressing replacement cycles for intercity coach fleets. SAMR enforces wet-grip performance labeling that transfers compliance burdens upstream to compound formulators. Shandong and Jiangsu provinces host regional tire plants sourcing bead wire within 500-kilometer radii to shorten OEM lead times.
India
State transport corporations in Maharashtra, Karnataka, and Gujarat modernize fleets under the PM-eBus Sewa Scheme, specifying 18-inch radial fitments for battery-electric platforms. BIS mandates puncture-resistance testing for tires deployed on national highway corridors. Tamil Nadu and Gujarat industrial clusters localize steel cord production to serve regional manufacturing footprints.
Germany
Verkehrsverbund regional transport associations consolidate procurement through tire-as-a-service contracts exceeding five thousand vehicles under single supplier agreements. REACH chemical disclosure and CE marking requirements govern municipal tender frameworks. Bavaria and Baden-Württemberg anchor premium coach manufacturing corridors where 17-inch specifications dominate highway stability requirements.
United States
Intercity coach operators navigate EPA fuel-efficiency mandates that specify rolling-resistance grades in fleet procurement tenders. NHTSA safety standards intersect with state-level greenhouse gas regulations in California and the Northeast Corridor. Michigan and Ohio industrial basins concentrate retreading infrastructure serving mixed-age fleet parches across North American routes.
Brazil
Mixed-age bus parches in São Paulo and Rio de Janeiro require tread patterns and load ratings diverging from standardized OEM specifications, fragmenting SKU portfolios for regional suppliers. ANVISA oversees chemical disclosure frameworks affecting import qualification. Minas Gerais and São Paulo states host assembly plants serving price-sensitive procurement through localized compound sourcing.
Bus Radial Tire Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. The vendor base organizes around three archetypes: premium multinationals with captive reinforcement supply, regional compound specialists leveraging localized bead-wire production, and asset-light retreading integrators capturing second-life revenue. Consolidation pressures concentrate among mid-tier manufacturers facing natural rubber price volatility and carbon black supply bottlenecks. Strategic moves center on backward integration into synthetic rubber compounding and geographic expansion through state transport tender participation.
Within the premium multinational tier, Bridgestone and Michelin exemplify divergent supply chain architectures. Bridgestone anchors its position through captive supply of steel cord reinforcements, while Michelin sustains margin control through in-house production of synthetic rubber compounds. Apollo Tyres occupies a position among regional specialists dominating price-sensitive segments through localized manufacturing in South Asian markets. These three representations illustrate how competitive positioning stratifies across reinforcement material control, compound formulation depth, and geographic production footprint.
| Leading Market Players |
|---|
| Bridgestone |
| Michelin |
| Goodyear |
| Continental |
| Pirelli |
| Hankook |
| Yokohama Rubber |
| Apollo Tyres |
| China National Tire & Rubber |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Shandong province tire plants is compressing margin buffers for regional manufacturers while forcing premium multinationals to defend positioning through compound differentiation. This utilization dynamic simultaneously intensifies spot-market pricing pressure for natural rubber-dependent tiers and accelerates captive supply investments among vertically integrated leaders.
Pricing Analysis
Certification level creates the primary spread between replacement cycle tiers, with BIS puncture-resistance and SAMR rolling-resistance labeling commanding premium positioning over unmarked imports. Three-tier pricing structure across premium, standard, and economy levels reflects compound formulation depth and steel cord localization status. Cost compression in economy tiers is intensifying because Thai and Indonesian rubber supply disruptions transmit directly to spot-market compound costs. State transport corporations in India exhibit highest price sensitivity through total-cost-of-ownership tender clauses, while European intercity coach operators prioritize certified low-hysteresis formulations regardless of unit cost.
Supply Chain Analysis
Tariff exposure between Southeast Asian rubber plantations and Chinese tire manufacturing clusters dominates supply-side risk calculus for compound formulators. Production gravity centers on Thailand, Indonesia, and Vietnam for natural rubber feedstock, while steel cord reinforcements draw from integrated plants in China and India. Single-source vulnerability in furnace-grade carbon black concentrates input leverage among five Asia-Pacific producers. Distribution runs through OEM supply agreements for fleet modernization tenders and aftermarket replacement channels serving mixed-age bus parches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tire-as-a-service contracts represent the fastest-expanding recurring-revenue layer, outpacing hardware shipment growth as fleet-management companies consolidate procurement authority across European and Indian markets.
For Market Incumbents: Harden captive supply positions in synthetic rubber compounding and steel cord reinforcements against emerging regional compound specialists. Prioritize BIS and SAMR certification maintenance to defend access to Indian state transport tenders. Expand retreading integration capabilities to capture second-life revenue streams before asset-light leasing frameworks fully displace direct municipal purchasing. For New Entrants and Emerging Players: Pursue white-space positioning in electrified bus radial specifications for 18-inch platforms serving India's PM-eBus Sewa Scheme deployments. Target Maharashtra and Karnataka state transport undertakings with localized bead-wire production within 500-kilometer radii. Lead with silica-hybrid compound formulations that satisfy rolling-resistance mandates without premium multinational cost structures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-management companies operating tire-as-a-service contracts exceeding five thousand vehicles. Long-term viability favors manufacturers with backward integration into reinforcement materials and demonstrated state tender participation. Monitor F-Gas Regulation compliance timelines as inflection indicator for European production footprint expansion versus import displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rubber Compounding | Michelin sustains margin control through in-house polybutadiene production. |
| Steel Cord Localization within 500-Kilometer Radii | Regional plants in Tamil Nadu and Gujarat shorten OEM supply lead times. |
| Retreading Integration with RFID Casing Tracking | Fleet-managed lifecycle programs capture second-life revenue from state bus corporations. |
| BIS Puncture-Resistance Certification Investment | Qualification for PM-eBus Sewa tenders in Maharashtra and Karnataka. |
| F-Gas Regulation Compliance Retooling | European OEM export contracts require solvent-free release-agent formulations. |
Methodological Framework
A standing panel of fleet procurement directors, tire plant operations managers, state transport tender officials, and aftermarket distribution heads provided ongoing calibration against operating reality. Primary interviews with compound formulation chemists and steel cord procurement leads combined with secondary validation through customs trade data, BIS certification registries, SEC tire manufacturer filings, and state transport corporation tender documentation. Bottom-up volume builds across product type, end user, size, and material segments triangulated against top-down macroeconomic drivers.
Scenario-bracketing around regulatory acceleration timelines and electrification adoption curves anchored projection models across the analysis window. Segmentation dimensions encompassed climate-zone product categories, procurement authority structures, axle-load diameter specifications, and reinforcement material sourcing strategies. CAGRs derived from elasticity-adjusted replacement cycle frequencies and fleet modernization program commitments. Industry-specific inputs included GB standard threshold compliance costs and PM-eBus Sewa deployment schedules.
Sensitivities concentrate around natural rubber price volatility, carbon black supply bottlenecks, and multi-homologation testing queue congestion. Forecasts reflect documented assumptions on regulatory enforcement intensity and fleet electrification penetration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Rail Road Wheels Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
Automotive Wheel Alignment System Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Wheel Cover Market
Tires and Wheels
Truck and Bus Tires Market
Tires and Wheels
Automotive Wheel Alignment Service Market
Tires and Wheels
Airless Tires Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
Commercial Vehicles Tires Market
Tires and Wheels
Bias Tire Market
Tires and Wheels
Automotive Airless Tire Market
Tires and Wheels
Tire Carousel Market