
 Predictive Maintenance for Manufacturing Market | 2026-2036
Predictive Maintenance for Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Predictive Maintenance for Manufacturing Market Outlook
Aftermarket service revenue is rewriting profit structures across industrial automation. IBM leverages its Watson IoT platform to anchor predictive analytics contracts with heavy equipment operators. Siemens sustains technology leadership through its MindSphere industrial cloud, while ABB competes with integrated robotics and condition monitoring bundles.
Predictive maintenance for manufacturing deploys sensor networks, machine learning algorithms, and edge computing architectures to forecast equipment failures before operational disruption occurs. Systems typically process vibration spectra, oil particulate counts, and thermal signatures against baseline thresholds to trigger maintenance workflows. IoT Sensors and Machine Learning command the largest technology revenue pools, though Edge Computing segments are gaining traction where latency constraints exclude cloud-only architectures. Cloud-Based deployment retains dominance among multi-site manufacturers, while Hybrid configurations are expanding in pharmaceutical facilities governed by strict data sovereignty requirements.
ISO 17359 condition monitoring standards, IEC 61508 functional safety frameworks, and OSHA process safety management rules collectively shape system certification requirements and buyer procurement criteria in the United States. The EU Machinery Directive and CE marking obligations further constrain equipment integration protocols for vendors serving European automotive and electronics end users. Stakeholders must weigh capital intensity against subscription model flexibility as deployment preferences fragment across regulatory jurisdictions and operational technology maturity levels.
Market Dynamics
The predictive maintenance market pivots on the collision between tightening functional safety mandates and the operational imperative to compress unplanned downtime. Manufacturers face mounting pressure to retrofit legacy equipment with sensor networks while navigating fragmented certification requirements across industrial jurisdictions.
Growth Catalysts
- IEC 61508 Functional Safety Framework:European automotive suppliers accelerate sensor deployment to satisfy SIL-rated equipment monitoring mandates. German production lines now require continuous vibration surveillance for robotic welding stations.
- Oil Analysis Technologies:Petrochemical operators in Houston deploy real-time particulate monitoring to prevent turbine bearing failures. Thermal imaging integration with lubricant diagnostics extends maintenance intervals by 40% in refinery applications.
- Japan:METI's Smart Manufacturing initiative subsidizes edge computing infrastructure for small and mid-sized machinery producers. Osaka-based toolmakers retrofit CNC equipment with predictive algorithms to qualify for export certification.
Market Restraints
- Sensor Hardware Cost Volatility:MEMS accelerometer and infrared detector prices fluctuate with semiconductor foundry capacity constraints. Procurement teams face 18-month hedging horizons for vibration sensing components.
- Cloud Latency Limitations:Real-time thermal anomaly detection in steel rolling mills demands sub-10 millisecond response times. Public cloud architectures cannot satisfy these constraints without expensive edge node proliferation.
- EU Machinery Directive Compliance Friction:CE marking requirements for integrated monitoring systems extend vendor certification cycles by 8-14 months. Documentation burdens disproportionately burden mid-sized automation suppliers.
Strategic Opportunities
- India:BIS standards for industrial equipment safety remain underpenetrated by predictive maintenance vendors. PLI scheme incentives for smart manufacturing create subsidy-aligned entry paths for sensor-software bundles.
- Digital Twin Convergence:Physics-based simulation models fused with live sensor streams enable failure prediction 72 hours ahead of threshold breaches. Pharmaceutical facilities in Basel adopt these hybrid architectures for sterile processing lines.
- Outcome-Based Service Contracts:Equipment manufacturers in Detroit transition from hardware sales to uptime guarantees. Revenue models now tie payments to operational availability metrics rather than capital expenditure.
Industry Challenges
- Interoperability Skill Scarcity:OT-IT integration specialists command premium compensation in automotive clusters. Detroit manufacturers report 14-month average vacancies for engineers fluent in both PLC protocols and cloud architecture.
- ISO 17359 Certification Timelines:Third-party validation of condition monitoring systems requires 6-9 months of field data collection. Vendors cannot recognize revenue until certification documentation completes.
- Legacy Protocol Fragmentation:Proprietary fieldbus standards in installed industrial bases resist standardized sensor integration. Brownfield deployments demand costly protocol gateway hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Predictive Maintenance for Manufacturing Market |
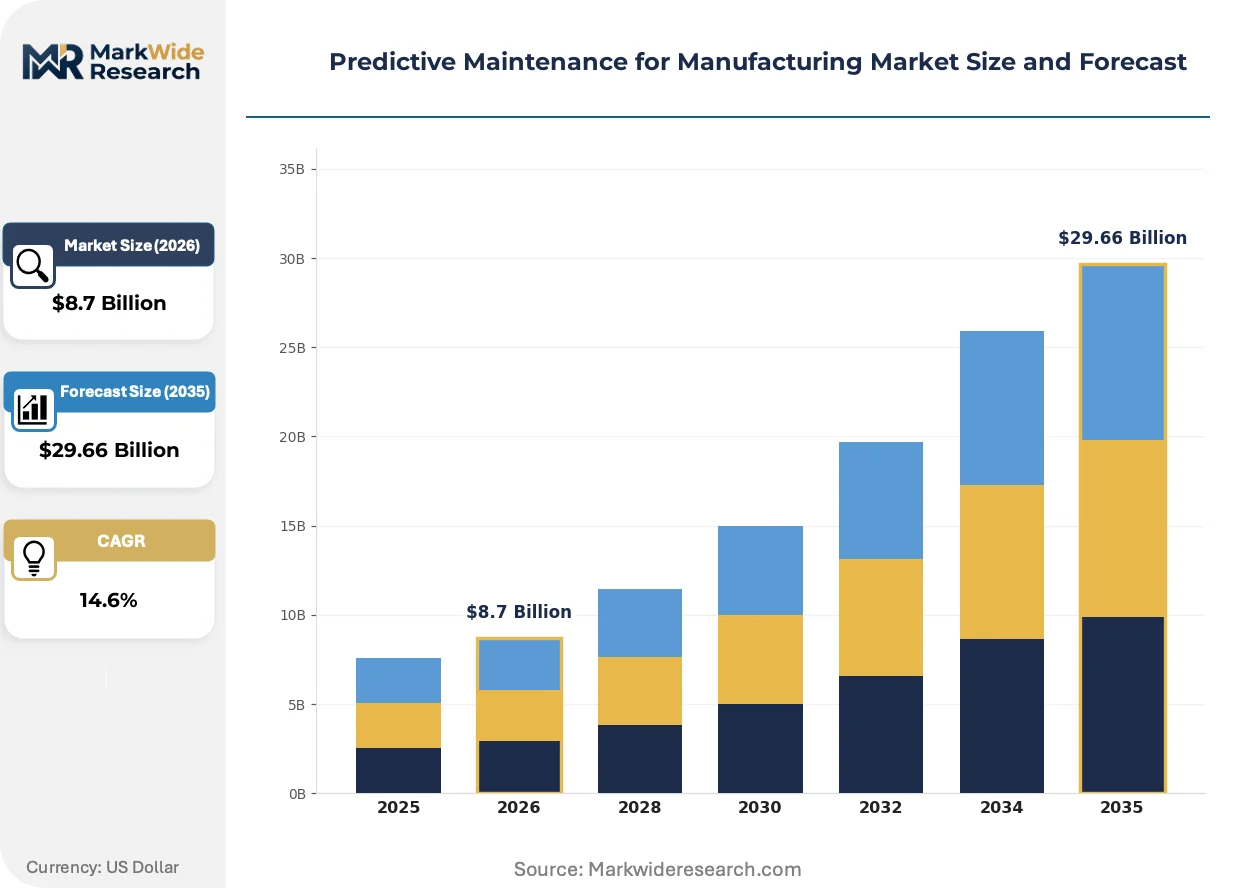
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, IoT Sensors, Cloud Computing, Big Data Analytics Service Type: Consulting Services, Integration Services, Support Services, Maintenance Services End User: Aerospace, Automotive, Electronics, Pharmaceuticals Deployment: On-Premise, Hybrid, Cloud-Based, Edge Computing |
| Companies Covered | IBM, General Electric, ABB, Siemens, Honeywell International, Schneider Electric, Microsoft, C3.ai, PTC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Predictive Maintenance for Manufacturing Market Strategic Shifts
Digital infrastructure is virtualizing physical maintenance workflows across industrial facilities. Sensor networks, machine learning inference, and cloud-native platforms now converge to displace scheduled inspection regimes with condition-triggered interventions.
Digital twin technology is virtualizing equipment behavior through real-time physics simulation. Automotive stamping plants in Stuttgart deploy these models to predict die wear before dimensional drift occurs. BMW and Mercedes-Benz suppliers compress tool changeover schedules by synchronizing virtual predictions with actual vibration signatures.
REACH chemical registration requirements are expanding sensor material disclosure obligations for EU-deployed equipment. Vendors must now document rare earth content in MEMS components and thermal detector substrates. Industrial automation suppliers serving German electronics manufacturers face supply chain requalification costs to maintain CE marking eligibility.
Asset-heavy manufacturers now unbundle after-sales service from original equipment procurement. Petrochemical operators in Houston negotiate standalone predictive maintenance subscriptions with third-party analytics providers. This disintermediation compresses incumbent vendor service margins while expanding addressable market for independent software specialists.
Predictive Maintenance for Manufacturing Market Segmentation
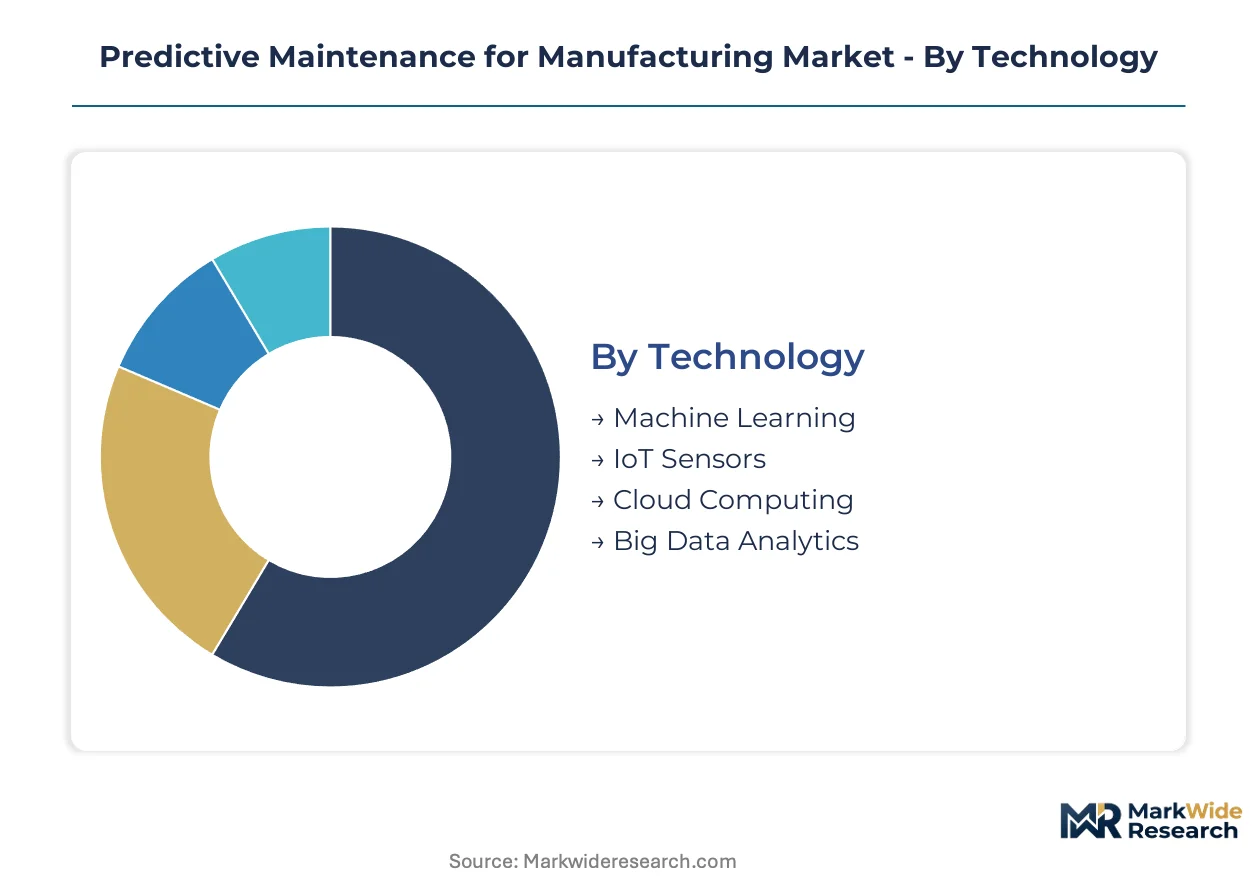
Predictive maintenance for manufacturing fragments across four distinct dimensions that shape procurement patterns and vendor positioning. Technology choices determine architectural complexity, while deployment models reflect data sovereignty constraints and latency requirements.
Technology:
Use-case spectrum spans from real-time anomaly detection in high-speed production lines to batch-mode degradation forecasting for intermittent-use assets.
- Machine Learning:Algorithms process multivariate sensor streams to identify failure precursors invisible to threshold-based monitoring. Automotive stamping plants in Stuttgart deploy these models to predict die wear before dimensional drift occurs.
- IoT Sensors:MEMS accelerometers, thermal imagers, and oil particulate counters generate the raw data feeding predictive algorithms. German production lines now require continuous vibration surveillance for robotic welding stations to satisfy IEC 61508 mandates.
- Cloud Computing:Centralized data lakes enable cross-facility pattern recognition and model retraining at scale.
- Big Data Analytics:Historical failure repositories and operational logs train classification models for rare-event prediction.
The dominant share belongs to IoT Sensors, while Machine Learning is closing the gap fastest as edge inference capabilities mature.
Service Type:
Cost tier segmentation separates capital-intensive integration projects from recurring subscription revenue streams.
- Integration Services:Sensor installation, protocol gateway deployment, and OT-IT network convergence command premium pricing due to scarce engineering talent. Detroit manufacturers report 14-month average vacancies for engineers fluent in both PLC protocols and cloud architecture.
- Consulting Services:Readiness assessments and ROI modeling guide brownfield retrofit decisions. Petrochemical operators in Houston engage these services to prioritize turbine-bearing monitoring investments across refinery assets.
- Support Services:Help desk operations and model performance monitoring ensure sustained algorithm accuracy.
- Maintenance Services:Field calibration, sensor replacement, and firmware updates preserve system reliability.
Integration Services captures the largest revenue pool, though Consulting Services is expanding most quickly as first-time buyers seek external validation.
End User:
Application intensity varies sharply across verticals governed by distinct safety and quality regimes.
- Automotive:High-volume production lines with minimal buffer inventory demand sub-minute failure prediction horizons. BMW and Mercedes-Benz suppliers compress tool changeover schedules by synchronizing virtual predictions with actual vibration signatures.
- Pharmaceuticals:Sterile processing lines require hybrid architectures that keep batch records on-premise while pushing anonymized sensor data to cloud analytics. Basel facilities adopt these configurations to satisfy data sovereignty requirements.
- Aerospace:MRO operations leverage digital twins to optimize engine overhaul intervals based on actual flight duty cycles.
- Electronics:Cleanroom environments deploy particle monitoring integrated with thermal imaging to prevent contamination events.
Automotive commands the dominant position, while Pharmaceuticals is climbing the fastest as regulatory pressure intensifies on continuous process verification.
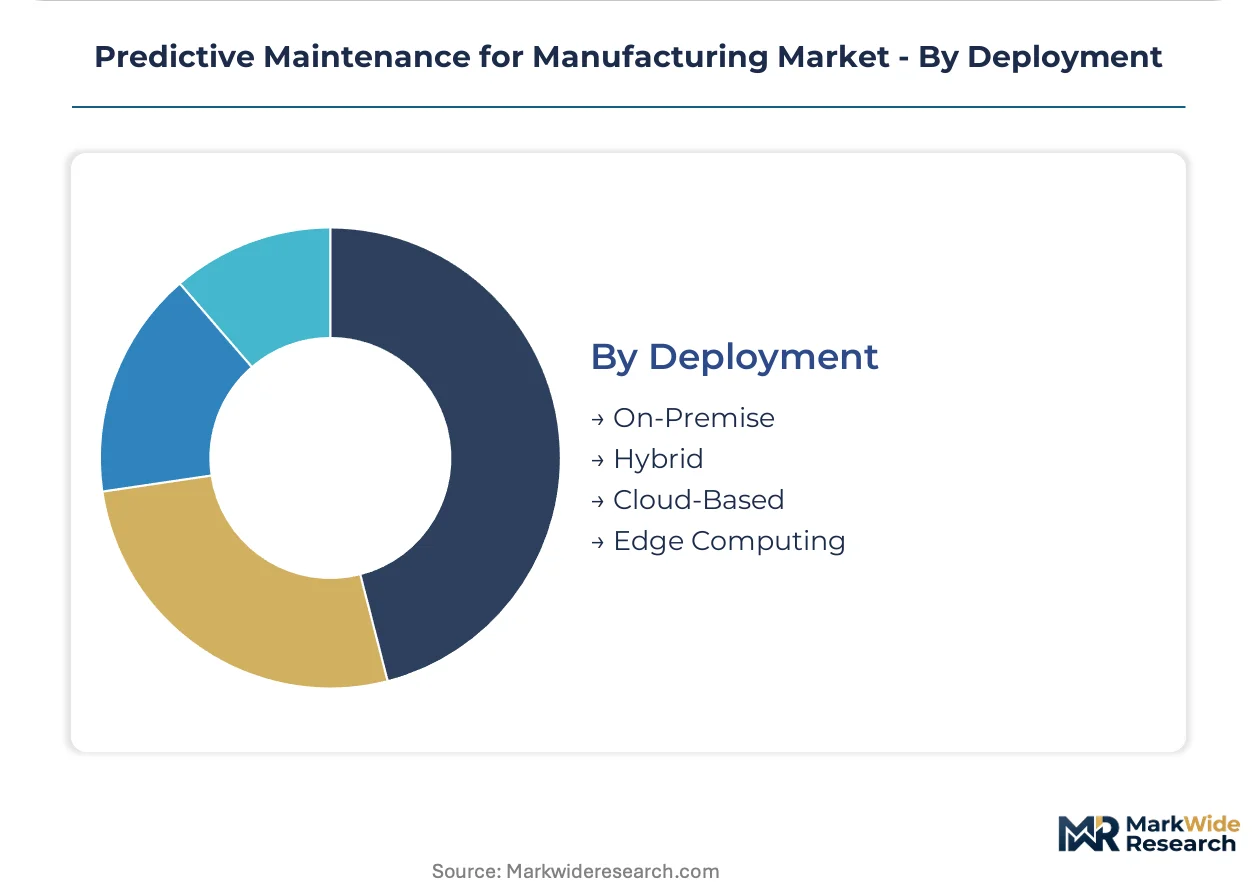
Deployment:
Customer maturity and infrastructure legacy dictate architecture selection more than feature requirements.
- Cloud-Based:Multi-site manufacturers standardize on SaaS platforms for centralized dashboarding and vendor-managed model updates. Public cloud architectures satisfy latency-tolerant applications like monthly degradation trending.
- Edge Computing:Sub-10 millisecond response requirements in steel rolling mills and robotic welding cells mandate local inference. Osaka-based toolmakers retrofit CNC equipment with predictive algorithms to qualify for METI-subsidized export certification.
- Hybrid:Pharmaceutical facilities and defense suppliers partition workloads between on-premise historians and cloud-based analytics.
- On-Premise:Air-gapped environments in critical infrastructure and classified manufacturing retain full stack control.
Cloud-Based deployment retains the largest installed base, while Edge Computing is gaining share fastest as semiconductor economics improve inference cost curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate low price elasticity as functional safety mandates override procurement discretion, while Indian and Brazilian purchasers remain acutely sensitive to upfront sensor hardware costs. The United States occupies a middle position where outcome-based contracts reshape total cost of ownership calculations.
United States
Petrochemical operators along Houston's refining corridor deploy real-time turbine monitoring to satisfy OSHA process safety management rules. The EPA's refinery sector enforcement priorities accelerate particulate sensor deployment. Detroit's automotive cluster compresses unplanned downtime through vibration surveillance on robotic welding lines.
Germany
Automotive stamping plants in Stuttgart synchronize digital twin predictions with actual vibration signatures to prevent die wear. The EU Machinery Directive's SIL-rated equipment mandates drive continuous monitoring adoption. Bavarian production lines now require thermal imaging integration for export certification under CE marking protocols.
Japan
Osaka-based toolmakers retrofit CNC equipment with edge computing algorithms to qualify for METI's Smart Manufacturing export subsidies. METI subsidizes predictive infrastructure for small and mid-sized machinery producers. Nagoya's automotive suppliers deploy sub-10 millisecond thermal anomaly detection on steel rolling mills.
India
Pharmaceutical facilities in Maharashtra adopt hybrid cloud architectures to satisfy data sovereignty requirements under emerging BIS industrial safety standards. The PLI scheme for smart manufacturing creates subsidy-aligned entry paths for sensor-software bundles. Gujarat's chemical corridors pilot lubricant diagnostics to extend maintenance intervals.
South Korea
Electronics manufacturers in the Seoul Capital Area integrate particle monitoring with thermal imaging to prevent cleanroom contamination events. KOSHA occupational safety guidelines tighten equipment surveillance requirements for semiconductor fabrication. Busan-Ulsan's shipbuilding cluster deploys vibration analysis on heavy crane systems.
Predictive Maintenance for Manufacturing Market Competitive Environment
Capability concentration sits with industrial automation specialists commanding deep OT-IT integration expertise; scale advantage sits with cloud-native platforms leveraging existing enterprise relationships. The market structure fragments across three tiers: legacy equipment manufacturers bundling monitoring with hardware sales, pure-play analytics vendors licensing algorithmic IP, and systems integrators bridging brownfield protocol gaps. Dominant competitive moves include vertical integration into sensor hardware production and geographic expansion through outcome-based service contract anchoring.
Within the industrial automation tier, Siemens and ABB exemplify integrated platform strategies spanning hardware through cloud analytics. IBM anchors the enterprise software vector with Watson IoT platform contracts. Honeywell International occupies a position bridging process control heritage with predictive algorithm deployment. These three represent divergent archetypes: European industrial conglomerates, American technology multinationals, and diversified automation specialists.
| Leading Market Players |
|---|
| IBM |
| General Electric |
| ABB |
| Siemens |
| Honeywell International |
| Schneider Electric |
| Microsoft |
| C3.ai |
| PTC |
| Others |
Value Chain & Pricing Dynamics
Semiconductor foundry concentration in Taiwan and South Korea feeds directly into sensor hardware margin pools, with MEMS accelerometer and thermal detector costs fluctuating against foundry capacity constraints. Procurement teams now face extended hedging horizons as component volatility reshapes system integrator pricing power.
Pricing Analysis
After-sales service contracts and extended warranty tiers now drive lifetime value in predictive maintenance, displacing upfront hardware margins. Three-tier pricing structure across premium certification-grade, standard compliance-level, and economy sensor-only bundles separates automotive OEMs from mid-tier machinery producers. Pricing pressure stems from cloud-native platform entrants undercutting integrated automation vendors on SaaS subscriptions. Petrochemical operators in Houston demonstrate lowest price sensitivity due to OSHA-mandated uptime requirements, while Indian pharmaceutical facilities remain acutely cost-conscious on initial sensor deployment.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for industrial sensor networks. Manufacturing concentration rests on Taiwan for MEMS fabrication, Japan for precision thermal detectors, and Germany for vibration analysis instrumentation. Rare earth dependencies in magnet-based sensors and infrared detector substrates create single-source vulnerability points. Distribution runs through authorized automation distributors and direct OEM channel partnerships serving discrete manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance for manufacturing represents high-growth disruption as IEC 61508 functional safety mandates and METI subsidy programs simultaneously accelerate retrofit demand across automotive and machinery verticals.
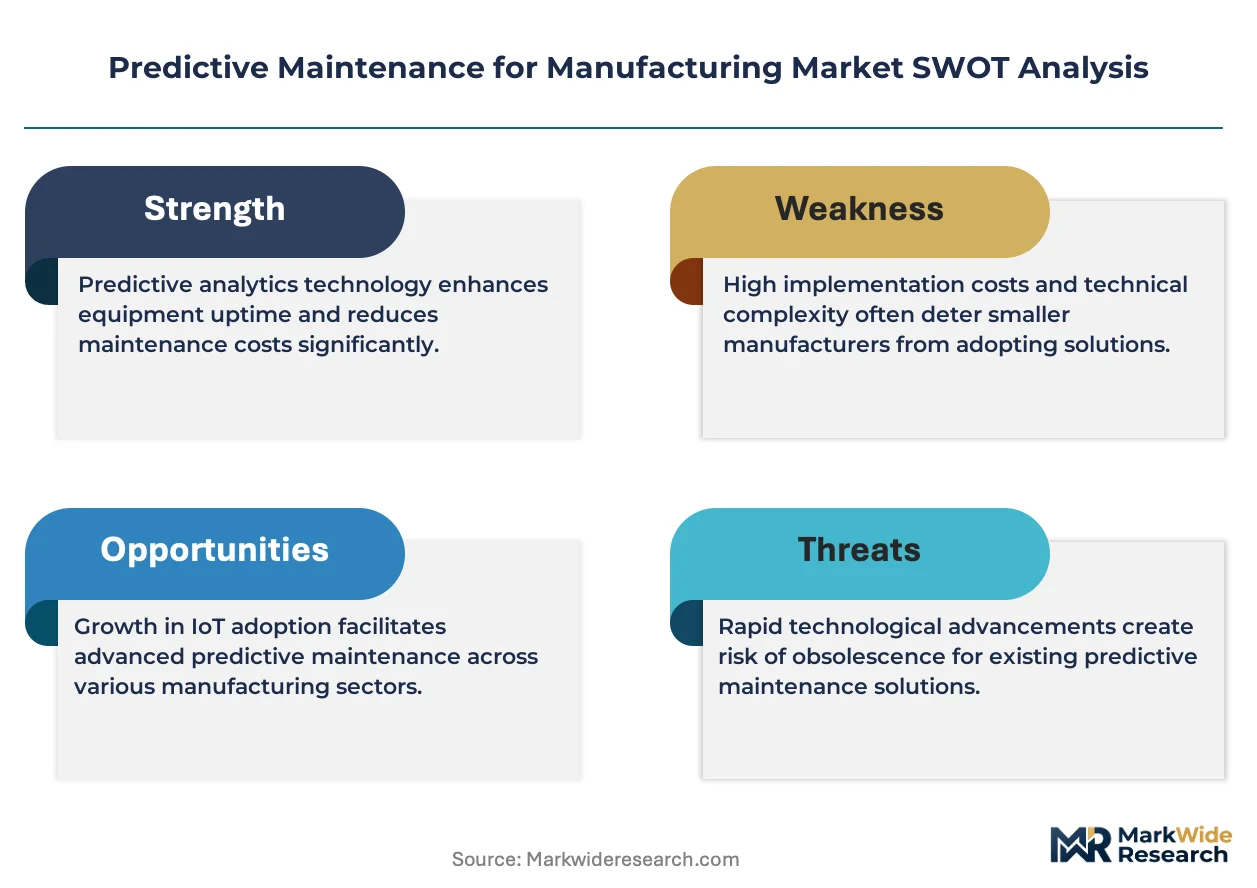
For Market Incumbents: Harden certification moats by accelerating ISO 17359 validation pipelines for edge computing architectures, compressing third-party field data collection timelines from 9 months toward 6. In-house production of MEMS sensor modules reduces exposure to foundry price volatility threatening system integrator margins. Channel control through exclusive distributor agreements in Detroit and Stuttgart automotive clusters limits pure-play analytics vendor encroachment.
For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical hybrid cloud segment where BIS standards remain underpenetrated and PLI scheme incentives align with sensor-software bundle subsidies. White-space concentration sits with small and mid-sized machinery producers in Osaka and Nagoya seeking METI-compliant export certification. Go-to-market leverage through outcome-based uptime guarantees rather than capital expenditure models differentiates against incumbent hardware bundling.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial software specialists possessing OT-IT integration talent pools scarce in automotive manufacturing clusters. Five-to-ten year viability hinges on algorithmic IP differentiation and recurring revenue share expansion. The signal to watch is consolidation velocity among mid-sized automation suppliers facing CE marking documentation burdens extending certification cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Infrastructure Deployment | Osaka toolmakers retrofit CNC equipment to qualify for METI Smart Manufacturing subsidies. |
| Digital Twin Platform Integration | Stuttgart automotive stamping plants synchronize virtual predictions with live vibration signatures. |
| Outcome-Based Service Contract Anchoring | Detroit equipment manufacturers tie payments to operational availability metrics rather than capex. |
| Backward Integration into Sensor Hardware | Automation vendors reduce MEMS accelerometer cost volatility through captive supply arrangements. |
| Regulatory Certification Fast-Tracking | Mid-sized suppliers compress ISO 17359 validation timelines to accelerate revenue recognition. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Secondary validation drew from IEC standards documentation, OSHA process safety filings, METI subsidy program disclosures, and customs records tracking sensor hardware trade flows. Bottom-up facility-level deployment estimates triangulated against top-down vendor revenue aggregation across the analysis window.
Calibration against historical adoption curves in automotive and petrochemical verticals anchored the analytical framework. Segmentation dimensions spanned technology tier, deployment architecture, service type intensity, and end-use regulatory cluster. CAGRs derived from fitted growth curves incorporating edge computing cost decline trajectories and functional safety mandate enforcement timelines. Model inputs included semiconductor foundry capacity projections and regional certification cycle duration estimates.
Sensitivities concentrate around foundry capacity constraints affecting sensor hardware costs, CE marking timeline extensions under EU Machinery Directive amendments, and cloud latency limitations in steel rolling mill applications. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Industrial Automation Motion Control System Software Market
Industrial Automation
South Korea Factory Automation and Industrial Controls Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Mini-Load Systems Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market
Industrial Automation
Linear Motion System Market
Industrial Automation
Linear Actuator Market
Industrial Automation
Smart Elevator Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
Europe SCADA Market
Industrial Automation
Europe Water Automation and Instrumentation Market