
 AI-driven Predictive Maintenance Market | 2026-2036
AI-driven Predictive Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
AI-driven Predictive Maintenance Market Insights
Germany is tilting toward edge-native predictive maintenance capacity as industrial OEMs localize AI inference for factory-floor latency requirements. Siemens sustains deep vertical integration from sensor hardware through cloud analytics platforms, spanning its own manufacturing footprint. IBM leverages hybrid cloud architectures to anchor enterprise deployments across regulated industries. C3 AI specializes in pre-trained machine learning models for energy and utility asset classes, differentiating through rapid time-to-value implementation.
AI-driven predictive maintenance deploys machine learning algorithms on vibration, thermal, and acoustic sensor streams to forecast equipment degradation before functional failure occurs, typically achieving prediction horizons of days to weeks depending on asset criticality and data granularity. The technology serves industrial and commercial operators seeking to shift from calendar-based servicing to condition-directed intervention, reducing spare parts inventory and labor dispatch costs. Machine learning dominates current deployment value due to mature toolchains and interpretable failure signatures, while computer vision is gaining fastest in applications where visual inspection drones and cameras supplement traditional sensor networks. Cloud-based deployment still captures the majority of new installations among mid-market adopters lacking on-site data science teams, though edge computing is carving out share where connectivity constraints or sub-second response requirements apply.
The EU AI Act imposes conformity assessment obligations on high-risk industrial AI systems, directly shaping product development roadmaps for vendors serving European manufacturing and energy clients. FDA oversight of AI-enabled diagnostic tools in the US is creating precedent documentation demands that predictive maintenance firms must anticipate as algorithmic health monitoring expands into regulated sectors. OSHA machinery safety standards are beginning to reference predictive analytics as a recognized hazard mitigation practice, reinforcing employer liability incentives for adoption. Stakeholders should monitor how divergent transatlantic regulatory timelines for AI system registration reshape vendor market access and customer procurement criteria.
Market Dynamics
Machine learning inference is migrating from cloud data centers toward edge-native architectures as manufacturing operators confront sub-100 millisecond latency requirements for critical asset protection.
Growth Catalysts
- EU AI Act compliance mandates:High-risk industrial AI systems face mandatory conformity assessments, accelerating vendor investment in algorithmic transparency documentation and audit-ready model governance frameworks.
- Automotive OEM sensor densification:German vehicle manufacturers embed multi-modal condition monitoring across stamping presses and robotic weld cells, generating continuous training data for failure prediction models.
- Edge computing hardware cost curves:NVIDIA Jetson and Intel Movidius module prices fell below deployment thresholds for mid-market factory operators, democratizing on-premise inference capability.
Market Restraints
- Specialized data science labor scarcity:Industrial ML engineering talent concentrates in Munich, Stuttgart, and Berlin, creating recruitment bottlenecks for facility operators in eastern German states.
- Legacy asset data interoperability gaps:Brownfield manufacturing equipment lacks standardized digital interfaces, forcing expensive sensor retrofit programs before predictive models achieve statistical validity.
- Cloud connectivity reliability variance:Rural industrial zones in Saxony and Thuringia experience intermittent fiber coverage, degrading hybrid edge-cloud model synchronization performance.
Strategic Opportunities
- Small and medium enterprise penetration:German Mittelstand metalworking and plastics processors remain underserved by predictive maintenance solutions, presenting white-space demand for packaged SaaS offerings.
- Digital twin convergence:Physics-based simulation engines from Siemens and Dassault Systems are merging with operational sensor streams, enabling prescriptive maintenance that recommends specific corrective actions.
- EU Green Deal equipment efficiency mandates:Industrial decarbonization targets create regulatory pull for predictive systems that optimize energy consumption alongside mechanical reliability.
Industry Challenges
- Model drift management complexity:Production environment changes degrade prediction accuracy over time, requiring continuous retraining pipelines that most plant engineering teams lack capability to maintain.
- Cross-functional integration friction:Maintenance, operations, and IT departments operate with misaligned KPIs, obstructing unified data governance for sensor infrastructure deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-driven Predictive Maintenance Market |
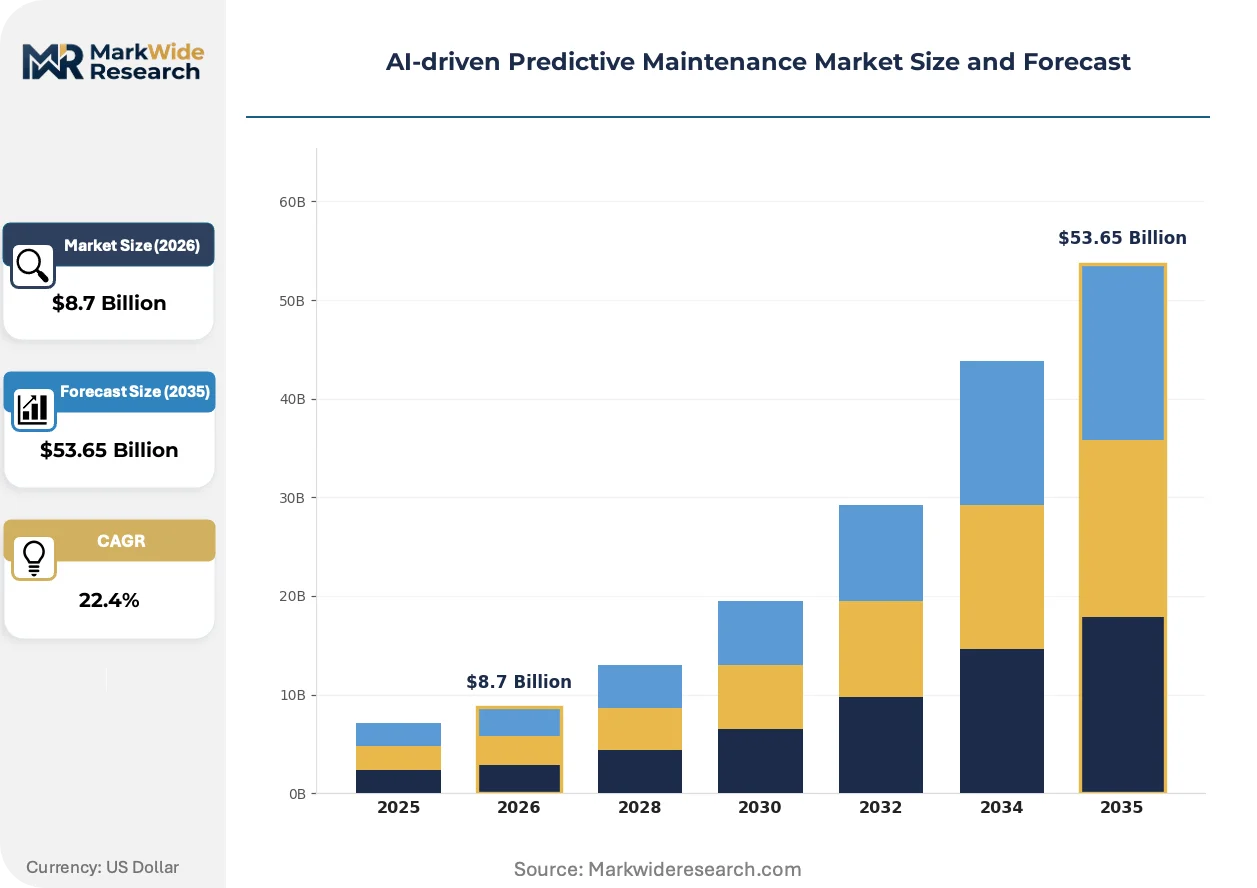
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision, Expert Systems Application: Manufacturing Equipment, Power Generation, Transportation Systems, Aerospace Assets, Smart Infrastructure Deployment: Cloud-based, On-premises, Hybrid, Edge Computing End User: OEMs, Facility Managers, Fleet Operators, Utility Providers, Data Centers |
| Companies Covered | IBM, Siemens, SAP, General Electric, C3 AI, ABB, Schneider Electric, Hitachi, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-driven Predictive Maintenance Market Trends and Innovations
Industrial AI deployment patterns are fragmenting across architectural approaches as latency requirements, data sovereignty concerns, and workforce capabilities diverge across operator segments.
Digital twin technology is migrating from design-phase simulation toward operational deployment, creating synchronized virtual replicas of physical assets that ingest real-time vibration and thermal data. German automotive stamping operations at BMW and Mercedes-Benz facilities now run parallel digital instances that forecast die wear progression. This migration from offline engineering tools to live operational systems is compressing maintenance planning cycles from monthly to daily horizons.
The EU AI Act's risk classification framework imposes documentation burdens on high-risk industrial AI systems, forcing vendors serving German manufacturing clients to maintain model cards, training data provenance records, and human oversight protocols. Equipment suppliers must now embed technical documentation capabilities into product roadmaps. German mechanical engineering associations are responding with sector-specific conformity guidance to streamline assessment procedures for predictive maintenance applications.
Condition-based service contracting is displacing traditional time-and-materials maintenance arrangements among German energy utilities and chemical processors. RWE and BASF procurement teams now specify uptime guarantees rather than spare parts schedules in vendor agreements. This shift concentrates financial risk with solution providers while rewarding predictive accuracy performance, most visibly in the Rhine-Ruhr industrial corridor where asset criticality justifies premium pricing for guaranteed availability.
AI-driven Predictive Maintenance Market Segmentation
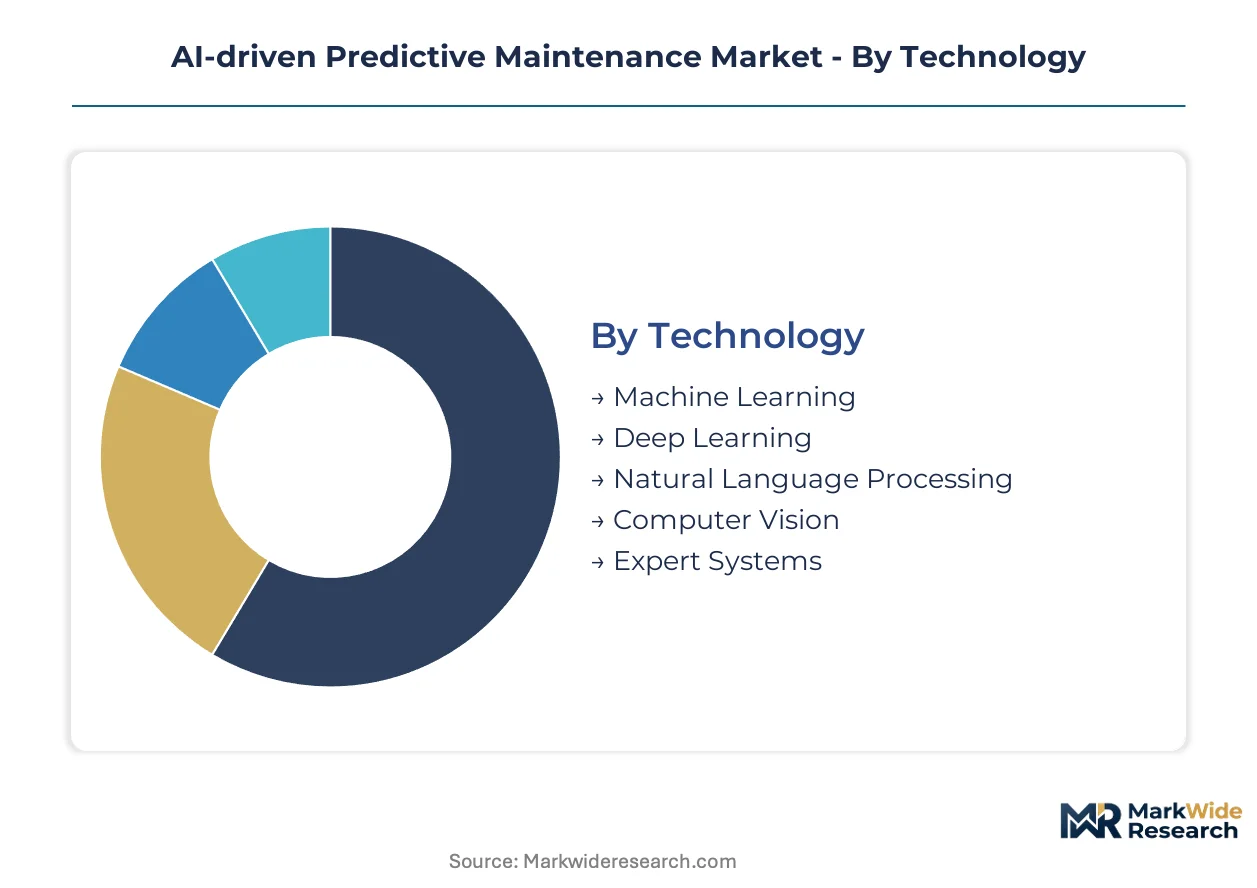
Segmentation in AI-driven predictive maintenance reveals how service intensity varies dramatically across technology architectures and operational contexts. Equipment operators select deployment configurations based on latency tolerance, data sovereignty requirements, and in-house technical capabilities rather than uniform vendor roadmaps.
Technology:
After-sales-service intensity climbs steeply with algorithmic sophistication, as deep learning implementations demand continuous model retraining and specialized ML engineering support that simpler rule-based systems avoid.
- Machine Learning:Supervised learning algorithms process structured sensor streams—vibration spectra, thermal profiles, acoustic signatures—to generate interpretable failure probability scores. German automotive stamping plants deploy gradient-boosted models for die wear forecasting, prioritizing explainability for maintenance technician acceptance. Demand concentrates in brownfield manufacturing environments where failure history datasets already exist.
- Deep Learning:Neural architectures—LSTM networks for temporal pattern recognition, autoencoders for anomaly detection—extract features from high-frequency, multi-variate sensor streams without manual engineering. Offshore wind operators in the North Sea apply these models to gearbox bearing degradation, accepting higher computational costs for extended prediction horizons. The segment attracts operators with clean, high-volume training data and tolerance for black-box predictions.
- Natural Language Processing:Text mining of maintenance logs and work order histories extracts unstructured failure context to enrich structured sensor data.
- Computer Vision:Convolutional neural networks analyze visual inspection imagery from drones and fixed cameras, supplementing traditional sensor networks in asset-dense environments.
- Expert Systems:Rule-based inference engines codify human maintenance expertise into deterministic diagnostic trees, persisting in safety-critical applications requiring auditable decision logic.
Machine Learning holds the largest share; momentum sits with Deep Learning as sensor densification generates training data volumes that reward neural architectures.
Application:
Cost tier segmentation separates capital-intensive continuous process industries from discrete manufacturing, with power generation commanding premium pricing for guaranteed uptime contracts.
- Manufacturing Equipment:Condition monitoring of CNC machining centers, robotic weld cells, and stamping presses dominates current deployment value. German automotive OEMs embed vibration and thermal sensors across legacy asset bases, generating the training data pipelines that sustain model accuracy. The segment rewards vendors with vertical domain expertise in specific machinery classes.
- Power Generation:Gas turbine blade creep monitoring, transformer thermal loading prediction, and wind turbine gearbox diagnostics command the highest service contract values. RWE and E.ON procurement teams specify availability guarantees rather than scheduled maintenance, concentrating financial risk with predictive analytics providers.
- Transportation Systems:Rail rolling stock bearing monitoring and fleet vehicle engine diagnostics apply similar algorithmic approaches to mobile assets with intermittent connectivity.
- Aerospace Assets:Engine health monitoring and airframe structural fatigue prediction operate under FAA and EASA regulatory documentation requirements that shape vendor product roadmaps.
- Smart Infrastructure:Bridge strain monitoring, water pipeline leak detection, and building HVAC optimization extend predictive maintenance into civil infrastructure with longer asset lifecycles.
Power Generation commands premium pricing; Manufacturing Equipment delivers volume scale.
Deployment:
Volume concentration favors cloud architectures among mid-market adopters lacking on-site data science teams, though edge-native deployments gain share where connectivity constraints apply.
- Cloud-based:Centralized model training and inference leverages scalable compute resources and simplifies multi-site deployment management. Saxon and Thuringian industrial zones with intermittent fiber coverage experience synchronization degradation, limiting addressable market.
- On-premises:Private data center deployment satisfies data sovereignty requirements in defense and critical infrastructure sectors, accepting higher capital expenditure for operational control.
- Hybrid:Edge preprocessing with cloud model refinement balances latency requirements against computational complexity, emerging as the dominant architecture for distributed manufacturing footprints.
- Edge Computing:NVIDIA Jetson and Intel Movidius modules enable sub-100 millisecond inference for critical asset protection without network dependency.
Cloud-based deployment retains volume leadership; Hybrid architectures are climbing the fastest as latency requirements harden.
End User:
Customer type segmentation distinguishes OEMs embedding predictive capability into equipment-as-a-service offerings from facility managers retrofitting brownfield assets.
- OEMs:Siemens, Bosch, and DMG Mori integrate predictive analytics into original equipment sales and service contracts, shifting revenue from capital sales to recurring availability guarantees. The segment demands white-label platform flexibility and multi-tenant architecture.
- Facility Managers:Industrial site operators procure predictive maintenance as standalone software or managed service, prioritizing rapid deployment over customization depth.
- Fleet Operators:Logistics and transportation companies apply unified condition monitoring across geographically distributed vehicle assets.
- Utility Providers:Energy and water infrastructure operators specify predictive maintenance within integrated asset management frameworks.
- Data Centers:Hyperscale computing facilities deploy thermal and power anomaly detection to prevent service interruption.
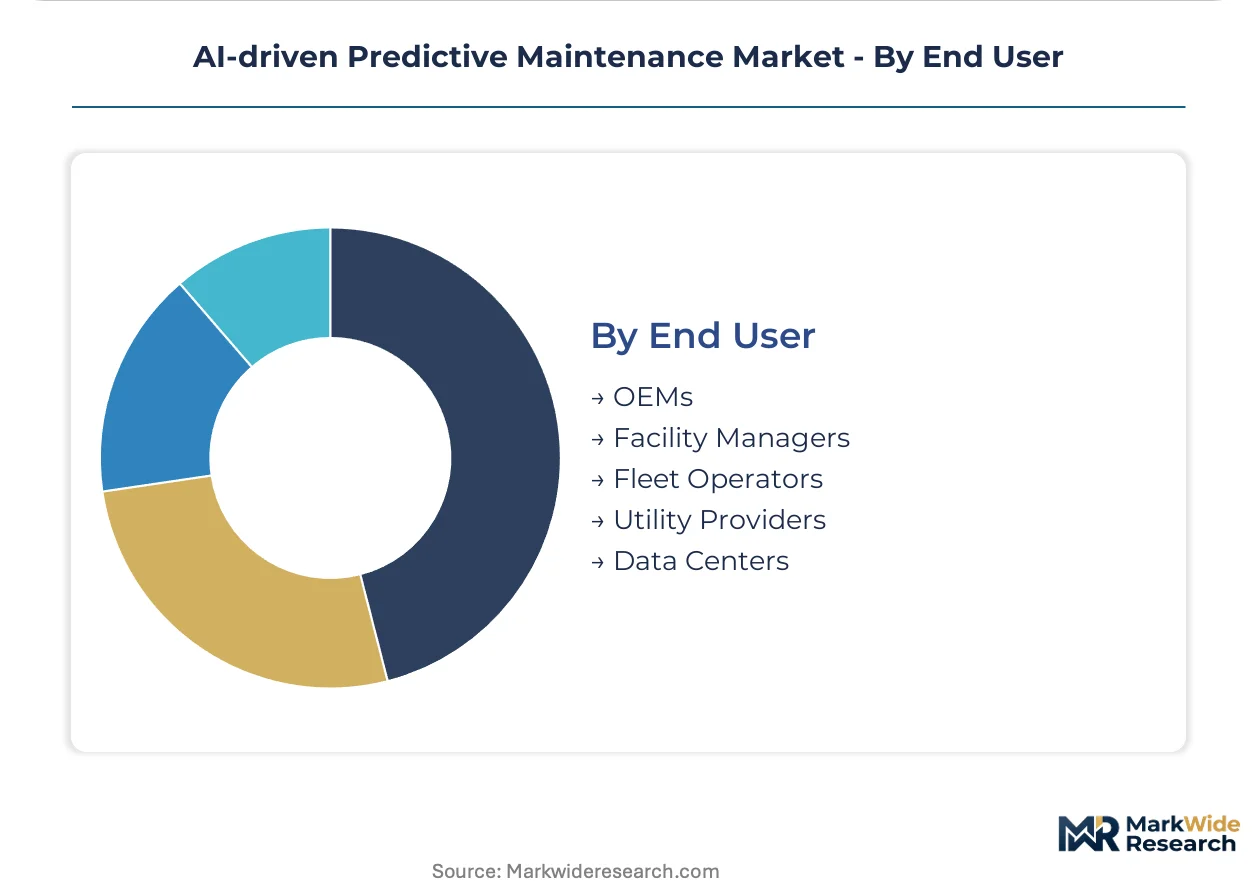
OEMs capture the highest contract values; Facility Managers represent the broadest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial AI vendors concentrate engineering resources near German automotive clusters and US manufacturing belts, creating asymmetric service capacity across geographies. European regulatory pressure from the EU AI Act accelerates compliance investment in algorithmic documentation. Asian markets scale through government-backed smart factory programs with standardized procurement frameworks.
United States
Automotive OEMs in Michigan and Ohio deploy vibration analytics across legacy stamping presses, generating training datasets for failure prediction models. FDA oversight of AI-enabled diagnostic tools creates precedent documentation demands as algorithmic monitoring expands into regulated sectors. The Rust Belt manufacturing corridor anchors demand concentration, with Detroit-area facilities pioneering edge-native inference architectures for sub-second latency requirements.
Germany
Industrial conglomerates embed predictive analytics into brownfield asset bases across Bavaria and Baden-Württemberg, prioritizing condition-directed intervention over calendar-based servicing. The EU AI Act imposes mandatory conformity assessments on high-risk industrial AI systems, forcing vendors to maintain model cards and audit-ready governance frameworks. The Rhine-Ruhr industrial corridor concentrates procurement activity, where RWE and BASF specify uptime guarantees rather than spare parts schedules in vendor agreements.
China
State-backed smart manufacturing initiatives accelerate sensor densification across Yangtze River Delta production facilities, with MIIT funding standardized condition monitoring deployments. National dual carbon goals create regulatory pull for predictive systems that optimize energy consumption alongside mechanical reliability. Shanghai and Suzhou industrial parks host the highest concentration of edge computing pilot programs for critical asset protection.
Japan
Precision equipment manufacturers in Nagoya and Osaka integrate predictive maintenance into original equipment sales contracts, shifting revenue from capital sales to recurring availability guarantees. METI industrial digitization programs subsidize SME adoption of packaged SaaS offerings for metalworking and plastics processing. The Chubu region anchors domestic demand, with Toyota supplier networks generating continuous training data for degradation models.
India
PLI scheme incentives attract industrial automation vendors to Gujarat and Maharashtra manufacturing corridors, though specialized ML engineering talent concentrates in Bengaluru and Hyderabad. The Central Electricity Authority mandates condition monitoring for critical thermal power infrastructure, creating procurement pull from NTPC and state gencos. Western India industrial zones lead deployment scale, with Mumbai-Pune automotive suppliers piloting hybrid edge-cloud architectures.
AI-driven Predictive Maintenance Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor hardware and inference modules. Market structure tilts toward consolidated platform providers with vertical integration from edge hardware through cloud analytics, while mid-market SaaS vendors fragment across application-specific niches. Two strategic archetypes dominate: industrial conglomerates embedding predictive capability into equipment-as-a-service offerings, and pure-play software vendors delivering rapid time-to-value through pre-trained models. Competitive moves concentrate on M&A for sensor technology access and strategic partnerships for edge computing hardware distribution.
Within the industrial conglomerate tier, Siemens and ABB exemplify backward integration into sensor hardware and captive supply of cloud analytics platforms. General Electric occupies a position bridging energy sector domain expertise with digital twin convergence capabilities. IBM represents the hybrid cloud architecture approach, anchoring enterprise deployments across regulated industries with compliance-ready model governance frameworks.
| Leading Market Players |
|---|
| IBM |
| Siemens |
| SAP |
| General Electric |
| C3 AI |
| ABB |
| Schneider Electric |
| Hitachi |
| Honeywell |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Rhine corridor freight cost dynamics compress margins for edge computing hardware shipments while amplifying price differentiation between EU AI Act-certified premium tiers and uncertified economy offerings. Supply concentration in German sensor manufacturing and Taiwanese semiconductor fabrication creates asymmetric pricing power that favors vertically integrated vendors with captive component supply.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for high-risk industrial AI systems, mandating conformity assessment documentation that separates premium-certified offerings from standard deployments. Three-tier pricing structure across premium, standard, and economy levels reflects algorithmic transparency depth, after-sales service intensity, and audit-ready model governance capabilities. Cost compression in the economy tier intensifies because mid-market factory operators lack procurement leverage for bundled ML engineering support. Facility managers in eastern German states exhibit highest price sensitivity due to intermittent cloud connectivity forcing hybrid architecture investments, while Rhine-Ruhr chemical processors accept premium pricing for guaranteed uptime contracts.
Supply Chain Analysis
Export controls on advanced GPU accelerators and AI training chips limit flows from US and Taiwanese fabrication facilities to Chinese system integrators, reshaping global hardware availability. Component supply concentrates in Germany for vibration sensors and edge inference modules, Taiwan for NVIDIA Jetson and Intel Movidius processors, and China for commodity sensor hardware. Raw material dependencies include rare earth elements for magnetic sensors, silicon carbide substrates for high-temperature applications, and lithium-ion cells for wireless sensor networks. Single-source vulnerability around NVIDIA edge modules creates procurement bottlenecks for mid-market operators. Distribution runs through OEM direct sales for enterprise accounts and industrial automation distributors for facility manager segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-driven predictive maintenance sits in early-cycle expansion as automotive OEM sensor densification generates continuous training data pipelines that sustain model accuracy improvement. The technology shift from calendar-based servicing to condition-directed intervention creates durable penetration tailwinds across brownfield manufacturing bases.
For Market Incumbents: Harden algorithmic transparency documentation capabilities to preempt EU AI Act conformity assessment delays that threaten German manufacturing contracts. Deepen captive supply of edge inference hardware through strategic partnerships with NVIDIA and Intel distribution channels to defend against pure-play SaaS vendors eroding mid-market share. Prioritize digital twin convergence investments that merge physics-based simulation with operational sensor streams, creating prescriptive maintenance differentiation that commands premium pricing. For New Entrants and Emerging Players: German Mittelstand metalworking and plastics processors represent the most penetrable entry point, as these SMEs remain underserved by predictive maintenance solutions lacking packaged SaaS offerings with rapid deployment timelines. Mid-market commercial buildings in Southeast Asia offer secondary white-space demand where government-backed smart factory programs subsidize adoption. Lead with outcome-based service contracting that concentrates financial risk with solution providers while rewarding predictive accuracy performance. For Investors and Strategic Acquirers: The EU AI Act's phased implementation timeline reshapes the acquisition landscape, favoring targets with pre-built model governance frameworks and audit-ready technical documentation. Long-term viability centers on vendors bridging edge-native inference capability with cloud analytics scalability across the projection horizon. Acquisition target archetype: mid-cap specialists with vertical domain expertise in automotive stamping or wind turbine gearbox diagnostics. Monitor FDA precedent documentation demands for AI-enabled diagnostic tools as the signal indicating expansion into regulated sectors.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Hardware Partnership | NVIDIA Jetson distribution agreements democratize on-premise inference for mid-market factory operators. |
| Digital Twin Platform Integration | Siemens and Dassault Systems physics engines merge with sensor streams for prescriptive maintenance recommendations. |
| EU AI Act Conformity Certification | Model cards and training data provenance records unlock high-risk industrial system procurement in Germany. |
| Condition-Based Service Contracting | RWE and BASF uptime guarantees concentrate financial risk with predictive analytics providers. |
| SME SaaS Packaging | Pre-configured offerings for Mittelstand metalworking reduce deployment barriers in underserved segments. |
Research Methodology
Desk research of regulatory filings, industrial automation trade publications, and OEM technical documentation preceded structured interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary fieldwork across Bavaria, Baden-Württemberg, and the Rhine-Ruhr corridor captured brownfield deployment patterns and conformity assessment preparation timelines. Secondary validation drew from EU AI Act implementation guidance, VDMA sector standards, and customs data on edge computing hardware imports. Bottom-up segment sizing triangulated against top-down market expenditure estimates from industrial engineering associations.
Forecast assumptions held fixed the EU AI Act's risk classification framework and phased enforcement timeline while varying edge computing hardware cost curves and cloud connectivity reliability improvements across the modeling period. Segmentation dimensions modeled include technology architecture, deployment configuration, application vertical, and end-user type. CAGR derivation incorporated sensor densification rates in automotive stamping operations, ML engineering labor availability constraints, and digital twin adoption curves in energy utilities. Industry-specific inputs encompassed vibration sensor installation costs and model retraining frequency requirements for production environment drift management.
Practitioners should monitor export control expansions on AI accelerators, EU AI Act enforcement variance across member states, and edge module price volatility for early signals of forecast deviation. Material shifts in transatlantic regulatory alignment or semiconductor supply chain restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Industrial Embedded Systems Market
Industrial Automation
Industrial Data Loggers Market
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
Global Programmable Logical Controllers Automation Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
Utility Automation Market
Industrial Automation
Asia Pacific Sortation Systems Market
Industrial Automation
Embedded Automation Computers Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
Forklift-Mounted Computers Market
Industrial Automation
Mining Automation Solutions Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
Smart Elevator Automation System Market