
 North America Industrial Automation Market | 2026-2036
North America Industrial Automation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Automation Market Insights
Aftermarket service revenue is tilting toward predictive maintenance platforms as hardware margins compress. Rockwell Automation sustains its position through embedded software architectures across factory floors. Siemens AG leverages its digital twin portfolio to anchor long-term client relationships. Emerson Electric Co competes on process control specialization in energy-intensive installations.
Industrial automation encompasses electromechanical systems, control software, and sensor networks that execute manufacturing processes with minimal human intervention, typically operating through programmable logic controllers managing inputs within millisecond cycle times to optimize throughput and safety. The primary purpose centers on reducing operational variability while scaling production consistency across continuous and discrete manufacturing environments. Control systems and programmable logic controllers capture the dominant share of product-type revenue due to their indispensability in every retrofit and greenfield deployment. Process automation applications lead factory automation in margin contribution because petrochemical and pharmaceutical buyers prioritize uptime guarantees over capital savings.
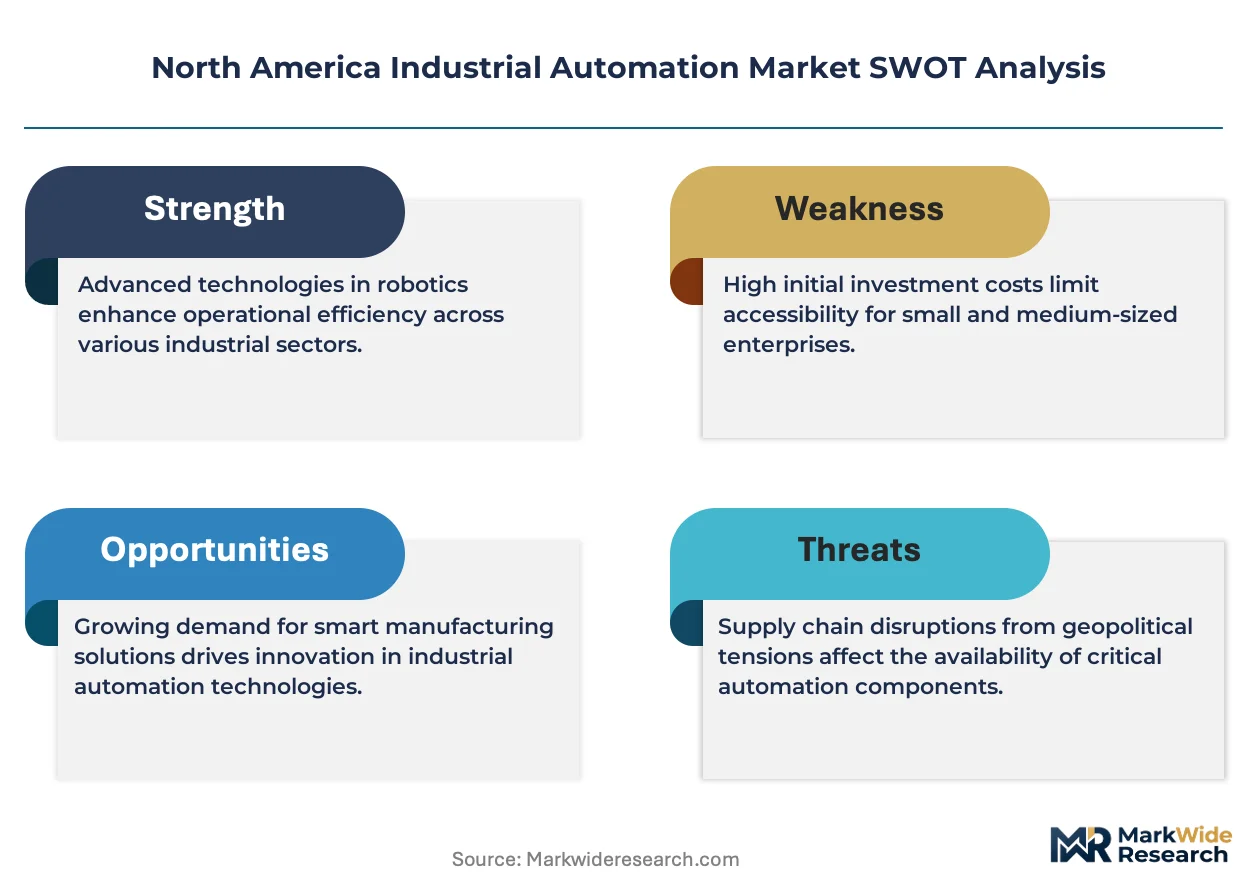
The US EPA enforces emissions monitoring standards that mandate automated reporting systems in heavy manufacturing, while OSHA's machine-guarding directives drive sensor integration on legacy equipment. Canada's CEPA framework and provincial regulators in Ontario and Alberta impose similar automation requirements for environmental compliance. Mexico's federal environmental enforcement through PROFEPA is tightening discharge monitoring, creating cross-border standardization pressure. Stakeholders must weigh the capital allocation trade-off between upgrading existing control layers and deploying greenfield AI-native architectures.
Market Dynamics
Capital allocation across the North America Industrial Automation Market tilts toward retrofitting brownfield facilities rather than greenfield construction, driven by EPA emissions mandates and Canada's carbon pricing framework that force continuous-process industries into compliance-driven automation upgrades.
Growth Catalysts
- US EPA Emissions Enforcement:Automated reporting systems are now mandatory in heavy manufacturing, compelling petrochemical and steel producers to deploy sensor networks and control systems that integrate real-time monitoring with regulatory submission protocols.
- Ontario Automotive Clusters:Electric vehicle retooling programs in Windsor and Oshawa are accelerating robotic assembly line deployments as Stellantis and domestic suppliers automate battery pack integration and quality inspection stations.
- Texas Gulf Coast Petrochemical Corridors:Process automation demand concentrates along the Houston Ship Channel where ethylene crackers and polyethylene plants prioritize uptime guarantees through distributed control system upgrades.
Market Restraints
- Semiconductor Component Volatility:PLC and servo drive production faces input cost pressure from specialized industrial chip shortages, with lead times for high-performance microcontrollers extending beyond 26 weeks.
- Single-Source Supply Concentration:Precision motion control hardware relies heavily on German and Japanese linear actuator suppliers, exposing North American system integrators to currency fluctuation and logistics disruption risks.
- Cybersecurity Compliance Friction:NERC CIP standards for energy sector automation create certification bottlenecks that delay project commissioning timelines by 4-8 months.
Strategic Opportunities
- Mexico Nearshoring Acceleration:Querétaro and Guanajuato automotive supplier parks present underpenetrated demand for collaborative robot deployments as OEMs relocate component manufacturing from Asia.
- AI-Native Predictive Maintenance:Convergence of edge computing platforms with vibration analysis algorithms creates white space for subscription-based asset health monitoring services displacing scheduled maintenance contracts.
- Canadian Clean Technology Investment Tax Credit:Ottawa's fiscal incentive for industrial decarbonization equipment lowers net capital cost for hydrogen production and carbon capture automation projects in Alberta's oil sands.
Industry Challenges
- Control Systems Integration Complexity:Brownfield facilities in Michigan and Ohio operate 1980s-era PLC architectures that resist seamless integration with modern IoT data layers, forcing costly middleware development.
- Functional Safety Certification Delays:TÜV Rheinland and exida SIL verification timelines for new safety instrumented systems stretch 14-18 months, compressing competitive windows for technology launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Automation Market |
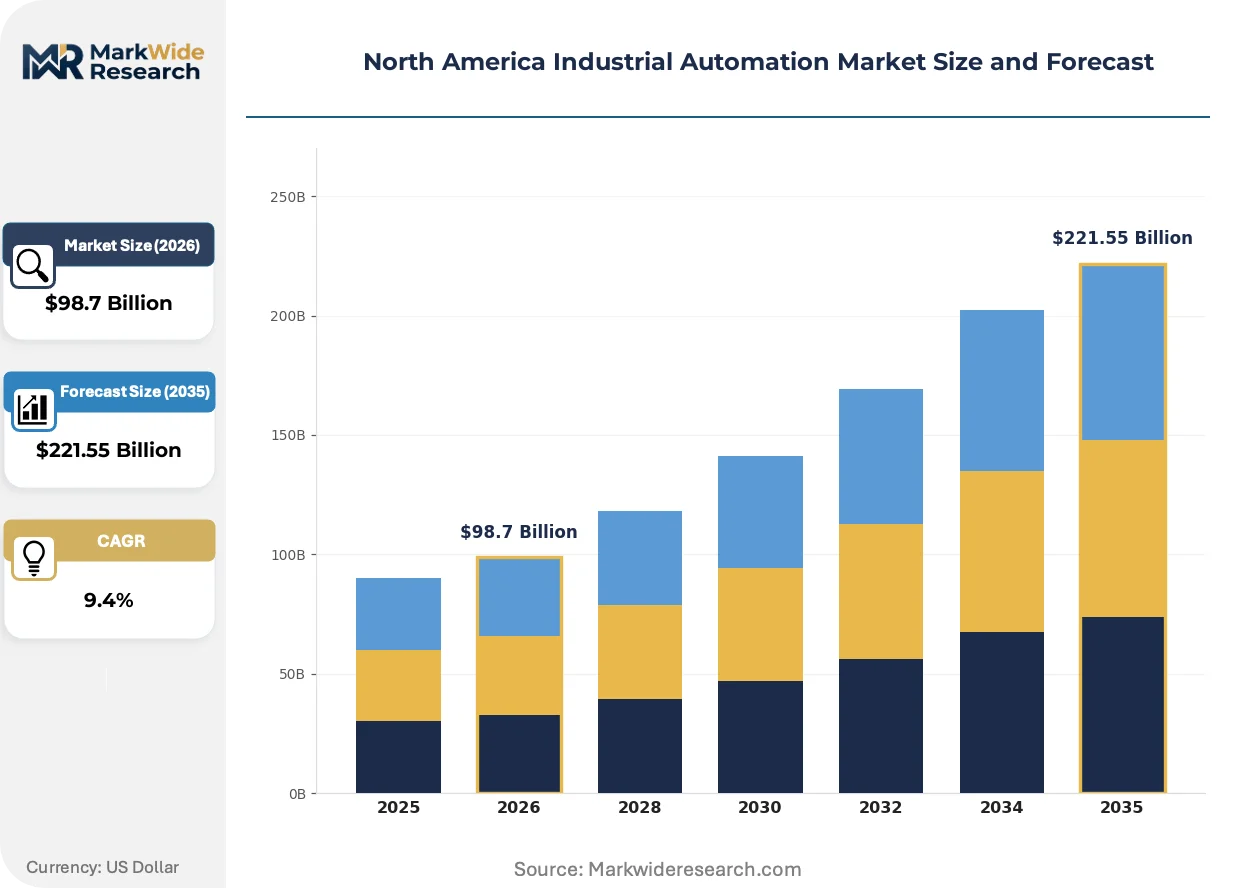
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $221.55 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotics, Sensors, Control Systems, Programmable Logic Controllers End User: Manufacturing, Oil & Gas, Food & Beverage, Pharmaceuticals Technology: IoT, AI, Machine Learning, Cloud Computing Application: Process Automation, Factory Automation, Building Automation, System Integration |
| Companies Covered | ABB Ltd, Rockwell Automation Inc, Emerson Electric Co, Honeywell International Inc, Schneider Electric SE, Siemens AG, Mitsubishi Electric Corp, OMRON Corp, FANUC Corp, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Automation Market Trends and Innovations
Software-defined automation architectures are compressing hardware replacement cycles while regulatory compliance mandates reshape procurement specifications across process industries.
Edge-native control platforms are collapsing the traditional separation between PLCs and SCADA systems by embedding real-time analytics directly at the device level. Food and beverage manufacturers in Wisconsin and California are piloting these architectures for traceability compliance. The structural consequence is collapsing profit pools for standalone HMI software vendors as functionality migrates to firmware.
OSHA's updated machine guarding directive forces metal fabricators and automotive stamping operations to retrofit legacy press lines with light curtain and laser scanner interlocks. The industrial consequence is accelerated demand for safety-rated motion controllers that combine standard and safety logic on unified hardware. Michigan and Tennessee stamping plants are responding by consolidating supplier relationships with vendors offering integrated safety certification.
Buyer preference is compressing toward outcome-based automation contracts where system integrators assume operational risk for throughput guarantees rather than delivering equipment on specification. This displaces traditional EPC contracting models in Texas and Louisiana petrochemical projects. The shift is most visible in ethylene and polyethylene expansions where operators now require vendors to tie payment milestones to sustained production rates.
North America Industrial Automation Market Segmentation
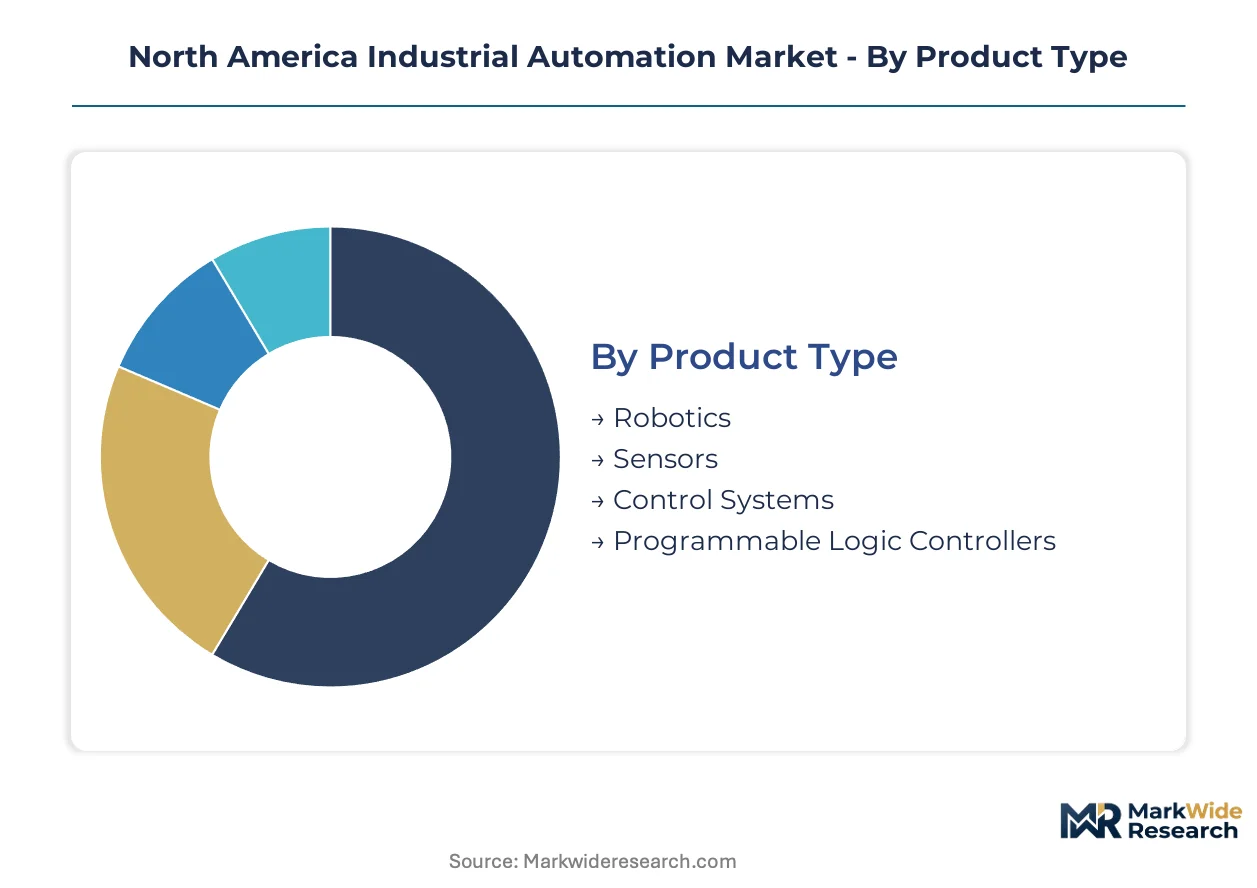
Segmentation reveals where capital concentrates across hardware, software, and service layers in North American industrial automation. Buyers in Texas petrochemical corridors and Ontario automotive clusters prioritize different performance specifications, forcing vendors to calibrate product architectures to end-use economics rather than universal platforms.
Product Type:
Mature electromechanical categories dominate installed base revenue while emerging software-embedded segments capture incremental margin expansion.
- Control Systems:Distributed control architectures manage continuous-process operations through redundant processor configurations and deterministic communication protocols. Demand concentrates along the Texas Gulf Coast where ethylene crackers require SIL-rated safety instrumented systems that integrate with EPA-mandated emissions monitoring infrastructure.
- Programmable Logic Controllers:Ruggedized industrial computers execute ladder logic and structured text with sub-millisecond scan times, forming the execution layer for discrete manufacturing. Michigan and Tennessee automotive plants are retrofitting legacy PLC-5 architectures with modern Ethernet/IP backbones to support battery pack assembly traceability requirements.
- Robotics:Articulated and collaborative manipulators perform material handling, welding, and quality inspection with force-torque sensing for human-robot collaboration.
- Sensors:Pressure, temperature, and proximity transducers convert physical variables to 4-20mA or digital signals for control system inputs.
Control Systems handles the majority of throughput; Robotics is expanding most quickly on share.
End User:
Capital intensity varies dramatically across process versus discrete manufacturing, with compliance-driven sectors commanding premium pricing for validated systems.
- Oil & Gas:Upstream, midstream, and downstream operations deploy explosion-proof instrumentation and safety shutdown systems for hazardous area classification. Alberta oil sands operators are automating steam-assisted gravity drainage wellheads under Canada's clean technology investment tax credit, prioritizing carbon intensity reduction over pure production optimization.
- Manufacturing:Discrete production lines integrate robotic material handling with machine vision for defect detection and predictive maintenance analytics. Windsor and Oshawa electric vehicle retooling programs are accelerating collaborative robot deployments for battery module assembly where precision tolerances exceed human repeatability limits.
- Pharmaceuticals:Batch process control with 21 CFR Part 11 electronic records compliance for FDA-regulated drug manufacturing.
- Food & Beverage:Washdown-rated automation with lot traceability for USDA-inspected processing facilities.
Manufacturing commands the largest installed base; Oil & Gas shows the steepest expansion trajectory from decarbonization capital allocation.
Technology:
Deployment architecture determines whether intelligence resides at the edge, in plant-level servers, or cloud-hosted platforms.
- IoT:Industrial internet-of-things platforms connect legacy equipment through protocol gateways, enabling data extraction from brownfield assets without control system replacement. Wisconsin food processors are piloting edge-native IoT architectures that collapse PLC-SCADA separation for real-time traceability compliance.
- AI:Machine learning models deployed on industrial edge devices enable predictive maintenance through vibration and thermal pattern recognition. Houston Ship Channel petrochemical operators are subscribing to AI-native asset health monitoring services that displace scheduled maintenance contracts with outcome-based uptime guarantees.
- Machine Learning:Supervised and unsupervised algorithms for process optimization and anomaly detection in continuous manufacturing.
- Cloud Computing:Scalable compute and storage infrastructure for enterprise-level manufacturing execution system hosting.
IoT carries the dominant deployment volume; AI is climbing the fastest on vendor margin contribution.
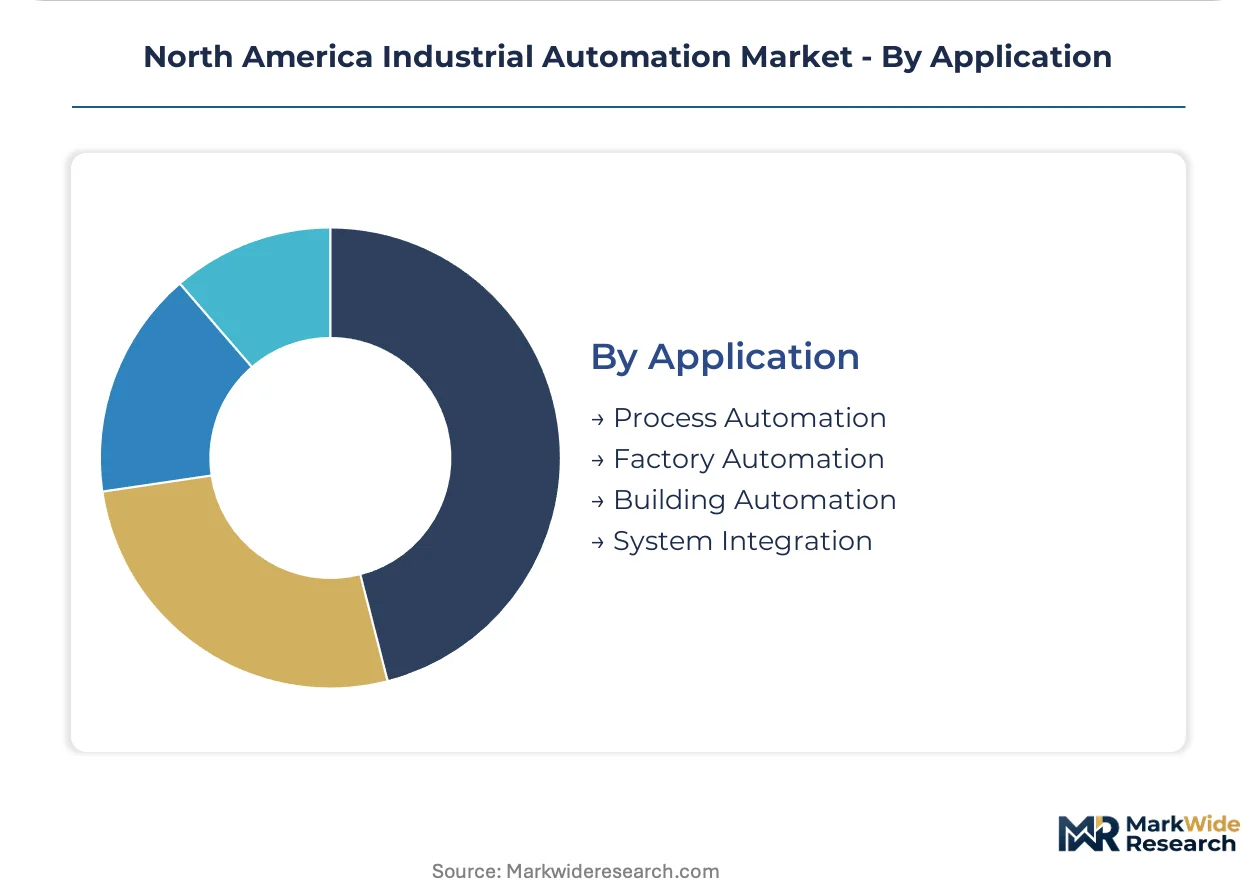
Application:
System scope ranges from single-loop control to enterprise-wide digital thread integration.
- Process Automation:Continuous-process control for petrochemical, pharmaceutical, and power generation with emphasis on uptime assurance and regulatory compliance. Louisiana ethylene expansions are requiring vendors to tie payment milestones to sustained production rate guarantees rather than equipment delivery specifications.
- Factory Automation:Discrete manufacturing coordination through programmable logic controllers, robotics, and machine vision for automotive and consumer goods production.
- Building Automation:HVAC, lighting, and security integration for industrial facilities and warehouses.
- System Integration:Engineering services combining hardware specification, software configuration, and commissioning for turnkey automation projects.
Process Automation captures the premium pricing tier; System Integration is gaining share fastest as buyers outsource complexity to specialized integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Ontario automotive clusters exhibit the highest price elasticity, prioritizing capital savings over uptime guarantees, while Texas Gulf Coast petrochemical operators accept premium pricing for validated process control systems. This demand-elasticity contrast shapes vendor pricing power across the region.
United States
Michigan and Tennessee automotive manufacturers are expanding robotic assembly lines for electric vehicle battery pack integration. OSHA's updated machine guarding directive forces metal fabricators to retrofit legacy press lines with light curtain interlocks. The Houston Ship Channel concentrates ethylene cracker automation demand where operators require vendors to tie payment milestones to sustained production rates.
Canada
Alberta oil sands operators are automating steam-assisted gravity drainage wellheads under Ottawa's clean technology investment tax credit. Canada's carbon pricing framework accelerates clean-process retrofits in continuous-process industries. Windsor and Oshawa electric vehicle retooling programs are accelerating collaborative robot deployments for battery module assembly precision.
Mexico
Querétaro and Guanajuato automotive supplier parks present underpenetrated demand for collaborative robot deployments as OEMs relocate component manufacturing from Asia. PROFEPA's tightening discharge monitoring creates cross-border standardization pressure with US EPA protocols. Mexico City Metro industrial corridors are seeing brownfield PLC architecture upgrades to support traceability compliance for export manufacturing.
North America Industrial Automation Market Competitive Landscape
Capability concentration sits with specialized process control vendors; scale advantage sits with diversified automation conglomerates with embedded software architectures. The vendor base organizes into three tiers: full-stack platform providers, process control specialists, and regional system integrators. Consolidation pressure runs through M&A activity targeting predictive maintenance software assets and strategic partnerships anchoring long-term client relationships.
Among diversified automation conglomerates, Rockwell Automation Inc and Siemens AG exemplify the full-stack platform archetype, anchoring factory floor presence through embedded software architectures and digital twin portfolios. Emerson Electric Co occupies a position within the process control specialist tier, competing on energy-intensive installation expertise. These three entities represent the competitive anchors shaping procurement specifications across Texas petrochemical corridors and Ontario automotive clusters.
| Leading Market Players |
|---|
| ABB Ltd |
| Rockwell Automation Inc |
| Emerson Electric Co |
| Honeywell International Inc |
| Schneider Electric SE |
| Siemens AG |
| Mitsubishi Electric Corp |
| OMRON Corp |
| FANUC Corp |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on German and Japanese linear actuator suppliers compresses hardware margins while expanding tier spreads between validated safety systems and commodity PLCs. EPA emissions mandates and OSHA machine-guarding directives force buyers toward premium-certified tiers regardless of base equipment economics.
Pricing Analysis
Aftermarket service revenue from predictive maintenance subscriptions now drives lifetime value, displacing transactional hardware margins as the primary profit pool. Three-tier pricing structure across premium SIL-rated safety systems, standard Ethernet/IP architectures, and economy legacy retrofits stratifies procurement specifications. Cost compression in economy-tier PLCs intensifies because semiconductor component volatility extends microcontroller lead times. Ontario automotive clusters exhibit highest price elasticity, prioritizing capital savings, while Texas Gulf Coast petrochemical operators accept premium pricing for uptime guarantees.
Supply Chain Analysis
Upstream feedstock for industrial semiconductors draws from Taiwan, South Korea, and the United States, with specialized industrial microcontrollers facing allocation constraints. Precision motion control hardware hinges on German linear actuator and Japanese servo drive inputs. Single-source vulnerability in safety instrumented system certification creates TÜV Rheinland and exida bottlenecks. Distribution runs through authorized system integrator networks that combine hardware specification with commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America Industrial Automation sits at a high-growth disruption inflection as EPA emissions enforcement and Canada's carbon pricing framework mandate compliance-driven capital deployment across brownfield facilities.
For Market Incumbents: Entrench factory floor presence through embedded software architectures that collapse PLC-SCADA separation, defending against edge-native platform disruption. Deepen backward integration into predictive maintenance software assets to capture recurring revenue streams. Prioritize TÜV Rheinland SIL certification investment to compress competitive windows for safety instrumented system launches.
For New Entrants and Emerging Players: Querétaro and Guanajuato automotive supplier parks present underpenetrated demand for collaborative robot deployments as nearshoring accelerates from Asia. Target Mexico City Metro industrial corridors for brownfield PLC architecture upgrades supporting export traceability compliance. Lead with subscription-based AI-native asset health monitoring services that displace incumbent scheduled maintenance contracts.
For Investors and Strategic Acquirers: The market sits at a compliance-acceleration phase that favors predictive maintenance software specialists and process control certification assets. Long-term viability centers on vendors anchoring client relationships through digital twin portfolios and outcome-based uptime guarantees. Watch for NERC CIP certification bottlenecks in energy sector automation as signal for vendor consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Edge Computing Platforms | Collapsing PLC-SCADA separation captures software-defined automation margin expansion in Wisconsin food processing. |
| AI-Native Predictive Maintenance Acquisition | Vibration analysis algorithm assets displace scheduled maintenance contracts with subscription revenue in Houston petrochemical corridors. |
| SIL Certification Fast-Track Investment | TÜV Rheinland and exida verification acceleration compresses competitive windows for safety instrumented system launches. |
| Mexico Nearshoring Joint Venture | Querétaro and Guanajuato supplier parks capture collaborative robot demand from OEMs relocating component manufacturing. |
| Clean Technology Tax Credit Structuring | Ottawa's fiscal incentive positioning lowers net capital cost for Alberta oil sands hydrogen production automation. |
Research Methodology
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and system integrator principals anchors the qualitative findings against secondary validation. SEC 10-K filings, customs and trade data, EPA enforcement disclosures, and OSHA directive records provide quantitative grounding. Bottom-up installation base modeling and top-down capital expenditure triangulation calibrate segment-level outputs.
Calibration against historical retrofit cycle timing and greenfield deployment patterns validates projection assumptions across the analysis window. Segmentation dimensions include product type hierarchy, end-use industry capital intensity, deployment architecture, and regional regulatory cluster. CAGRs derive from installed base replacement rates and compliance-driven upgrade mandates. Model inputs incorporate EPA emissions enforcement timelines and Canada's clean technology investment tax credit uptake curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-native predictive maintenance entrants or accelerated nearshoring into Mexico would shift outcomes. Cross-checking against EIA industrial electricity demand and vehicle production databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Smart Elevator Automation System Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Model Based Manufacturing Technologies Market
Industrial Automation
Linear Actuator Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
Warehousing Automation Equipment Market
Industrial Automation
Smart Industries Market
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
Intelligent Conveyor System Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Industrial Internet Connectivity Tracker Market