
 North America Automated Storage and Retrieval System Market | 2026-2036
North America Automated Storage and Retrieval System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automated Storage and Retrieval System Market Analytics
Steel-reinforced aluminum rack framing is recalibrating cost-per-pallet-position economics across high-bay installations. Daifuku Co., Ltd. leverages its North American manufacturing footprint to anchor regional supply chains for unit-load systems. Dematic Group competes through software-integrated controls that extend warehouse execution capabilities. SSI Schaefer differentiates via modular vertical lift modules that occupy compact urban distribution footprints.
An Automated Storage and Retrieval System comprises computer-controlled machines that automatically place and retrieve loads from defined storage locations, typically operating in rack structures exceeding 100 feet with throughput rates of 200-400 dual cycles hourly. These systems serve to maximize cubic space utilization while minimizing labor exposure in temperature-controlled and hazardous environments. Robotic AS/RS represents the fastest-expanding product category as autonomous mobile robots displace fixed-aisle cranes in flexible fulfillment layouts. Software Solutions within the technology dimension captures concentrated margin pools as warehouse control systems become the primary integration layer. Retail and E-commerce end users dominate installation volumes, though Pharmaceutical deployments sustain premium pricing through validated cleanroom configurations.
OSHA warehouse safety standards and the US Department of Labor ergonomic injury prevention mandates shape equipment design requirements, particularly for vertical lift modules reducing repetitive lifting exposures. Canada's CSA B335 industrial truck standards and Mexico's NOM workplace safety regulations create compliance thresholds for cross-border system deployments. Stakeholders must monitor how evolving FDA pharmaceutical traceability rules and EPA energy efficiency guidelines for material handling equipment reshape specification criteria for new installations and retrofit programs.
Market Dynamics
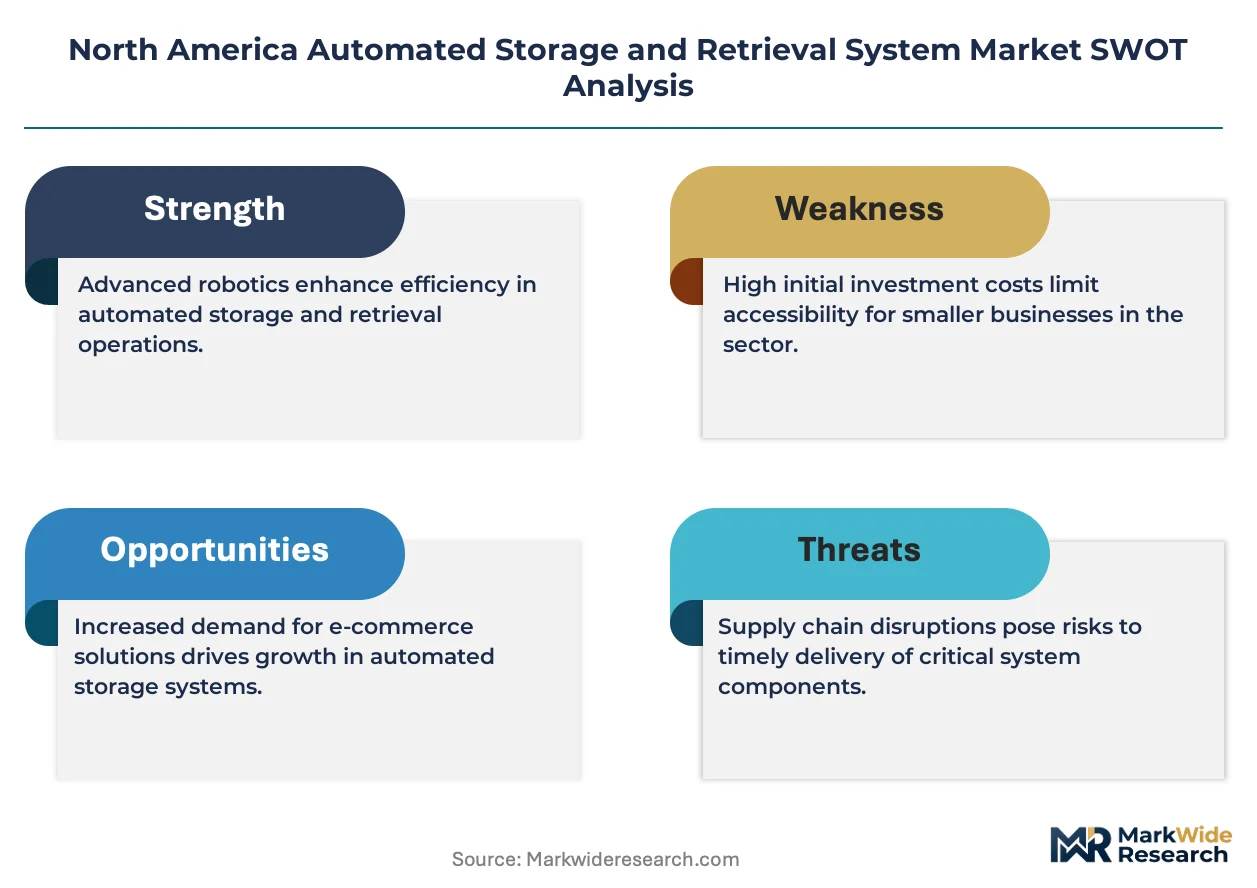
Robotic AS/RS architectures are compressing fixed-aisle crane economics as autonomous mobile robots enable flexible fulfillment layouts without permanent infrastructure commitments. This technology shift is restructuring capital deployment patterns across North American distribution networks.
Growth Catalysts
- OSHA Ergonomic Mandates:The US Department of Labor's warehouse safety standards accelerate mechanized storage deployment to reduce repetitive lifting injuries in high-volume fulfillment operations.
- E-commerce Fulfillment Density:California's Inland Empire distribution corridor concentrates demand for high-throughput AS/RS installations serving same-day delivery networks.
- Steel-reinforced Aluminum Framing:Advanced rack materials reduce cost-per-pallet-position economics in high-bay installations exceeding 100 feet.
Market Restraints
- Structural Steel Input Volatility:Fluctuating steel prices destabilize rack system quotations and project financing timelines for multi-million-dollar installations.
- Cross-border Regulatory Friction:Canada's CSA B335 industrial truck standards and Mexico's NOM workplace safety regulations create compliance complexity for unified North American system deployments.
- Fixed Infrastructure Lock-in:Traditional crane-based AS/RS requires permanent rack structures that limit facility reconfiguration options as fulfillment patterns shift.
Strategic Opportunities
- Texas Logistics Hub Expansion:Dallas-Fort Worth's distribution cluster presents underpenetrated demand for pharmaceutical-grade AS/RS with validated cleanroom configurations.
- FDA Traceability Tailwinds:Evolving pharmaceutical serialization rules create specification pull for software-integrated warehouse control systems with full lot tracking.
- Robotic-Conveyor Convergence:Integration of autonomous mobile robots with vertical lift modules enables compact urban distribution footprints in land-constrained Ontario markets.
Industry Challenges
- Controls Engineering Talent Scarcity:Warehouse execution software integration requires specialized skill sets that outpace North American technical education pipeline output.
- Legacy WMS Integration Complexity:Retrofitting AS/RS into existing warehouse management architectures demands custom middleware development that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automated Storage and Retrieval System Market |
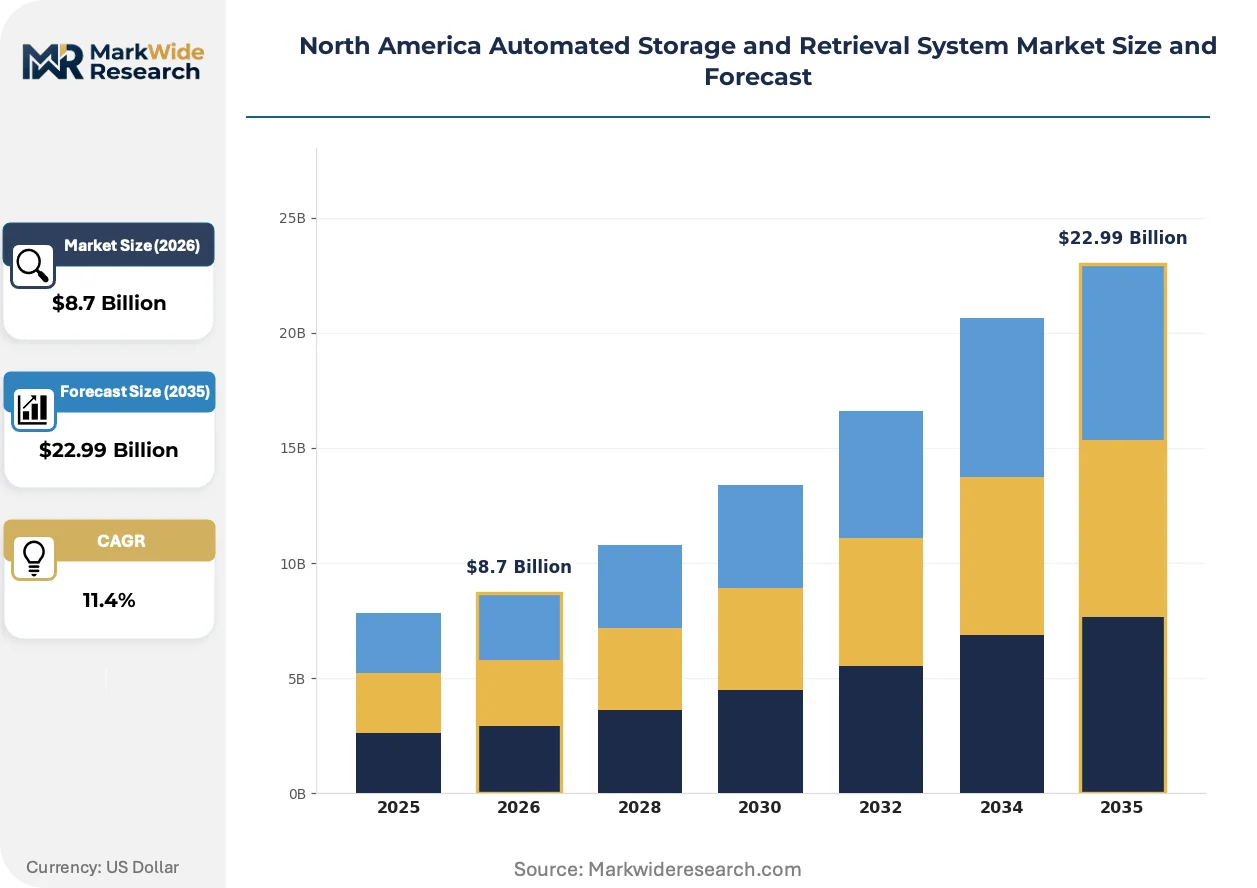
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unit Load AS/RS, Mini Load AS/RS, Vertical Lift Module, Robotic AS/RS Technology: Autonomous Robots, Barcode Scanners, RFID Systems, Software Solutions End User: Retail, E-commerce, Pharmaceuticals, Manufacturing Installation: New Installations, Retrofits, Upgrades, Customized Solutions |
| Companies Covered | Daifuku Co., Ltd., Dematic Group (KION Group AG), SSI Schaefer, Kardex Holding AG, Murata Machinery Ltd., TGW Logistics Group, Bastian Solutions LLC, Symbotic LLC, Swisslog Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automated Storage and Retrieval System Market Evolving Landscape
Software-defined warehouse control is displacing hardware-centric system architectures across North American fulfillment networks. This shift elevates margin capture toward integration layers and away from mechanical components.
Autonomous mobile robot fleets are electrifying fulfillment layout flexibility by eliminating fixed-aisle infrastructure requirements. Third-party logistics operators in Texas and California are deploying these systems at accelerated pace to support seasonal volume spikes. The technology is electrifying competitive positioning among mid-size fulfillment providers previously locked out of high-throughput automation.
EPA energy efficiency guidelines for material handling equipment are reshaping specification criteria for new installations and retrofit programs. Motor and drive system selections now face mandatory efficiency thresholds that favor regenerative crane technologies. Pharmaceutical and cold chain deployments across the US and Canada are responding with upgraded power management subsystems to maintain compliance.
Buyer preference is compressing toward outcome-based performance contracts that transfer throughput risk to system integrators. Retail and e-commerce end users in Ontario's Golden Horseshoe manufacturing zone are displacing traditional equipment purchase models with availability-guaranteed service agreements. This shift concentrates vendor balance sheet exposure while locking in multi-year maintenance revenue streams.
North America Automated Storage and Retrieval System Market Segmentation
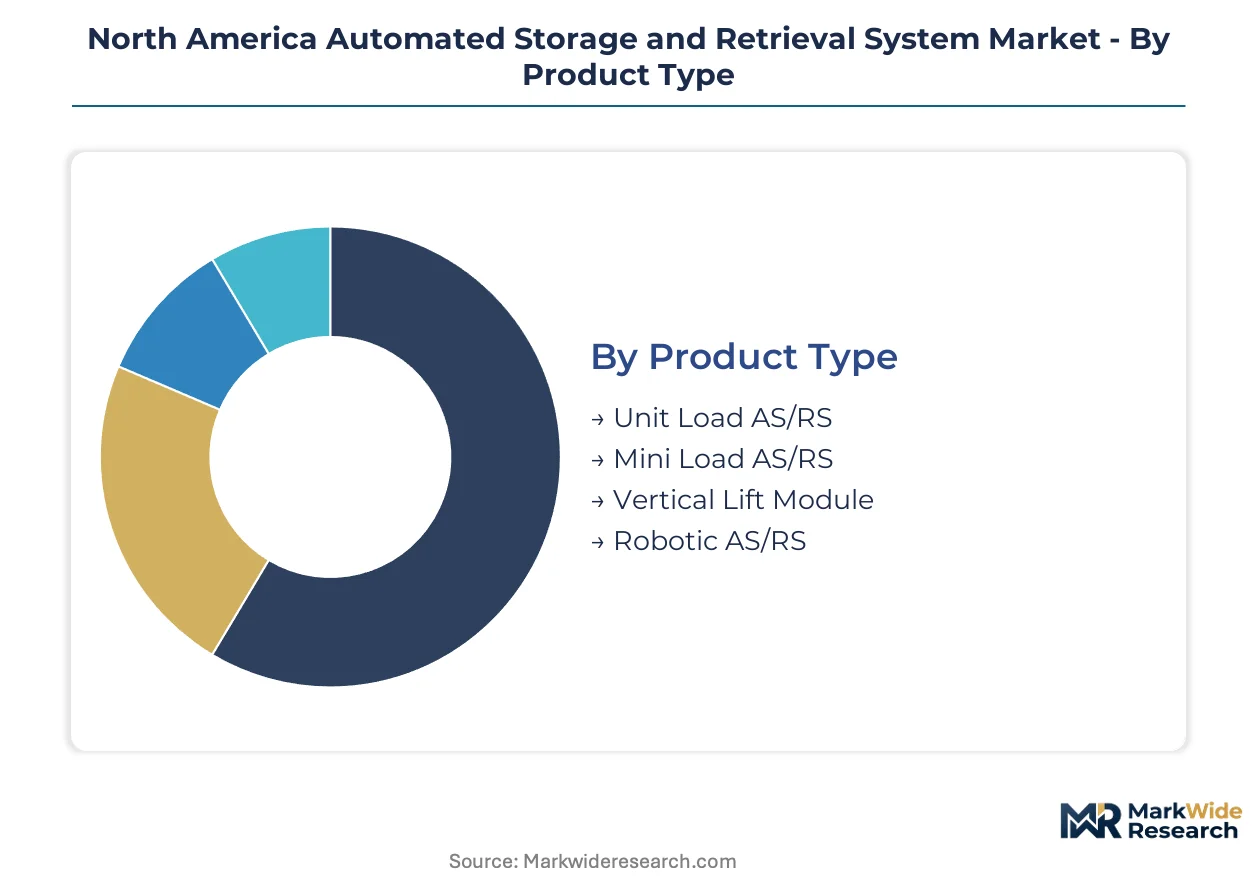
Segmentation in the North America Automated Storage and Retrieval System Market reveals distinct procurement patterns across fulfillment density, regulatory exposure, and infrastructure lifecycle stages. Buyers in California's Inland Empire corridor prioritize throughput velocity, while pharmaceutical operators in Texas and Ontario emphasize validated traceability systems.
Product Type:
System selection hinges on payload scale, vertical reach requirements, and reconfiguration flexibility across high-bay warehouse footprints.
- Robotic AS/RS:Autonomous mobile robots navigate without fixed aisle infrastructure, enabling seasonal layout reconfiguration. Third-party logistics operators in Dallas-Fort Worth deploy these systems to absorb e-commerce volume spikes without permanent capital commitments.
- Unit Load AS/RS:Crane-based systems handle palletized loads exceeding 3,000 pounds in rack structures surpassing 100 feet. Daifuku Co., Ltd. anchors regional supply chains for these installations across California's distribution corridor.
- Mini Load AS/RS:Tote-handling systems serve split-case picking in pharmaceutical and electronics fulfillment.
- Vertical Lift Module:Compact vertical storage towers occupy urban footprints in land-constrained Ontario markets.
Volume sits with Unit Load AS/RS; growth tilts toward Robotic AS/RS.
Technology:
Technology procurement stratifies between hardware sensing layers and software control architectures that command system-wide orchestration.
- Software Solutions:Warehouse control systems function as the primary integration layer between mechanical subsystems and enterprise WMS platforms. Dematic Group competes through these software-integrated controls that extend execution capabilities across heterogeneous equipment fleets.
- Autonomous Robots:AMR fleets displace fixed-aisle cranes by eliminating permanent infrastructure requirements. EPA energy efficiency guidelines for material handling equipment reshape motor and drive specifications for these electrified systems.
- RFID Systems:Radio-frequency identification enables lot-level traceability for FDA pharmaceutical serialization compliance.
- Barcode Scanners:Linear and 2D imaging systems provide cost-effective identification in retail fulfillment environments.
Margin capture concentrates in Software Solutions; Autonomous Robots are expanding most quickly.
End User:
End-user segmentation reflects divergent compliance burdens, throughput requirements, and facility investment horizons across North American distribution networks.
- Retail and E-commerce:These sectors dominate installation volumes through same-day delivery networks concentrated in California's Inland Empire and Texas logistics hubs. OSHA ergonomic mandates accelerate mechanized storage deployment to reduce repetitive lifting injuries in high-volume fulfillment operations.
- Pharmaceuticals:Validated cleanroom configurations sustain premium pricing through FDA traceability requirements. Texas's Dallas-Fort Worth cluster presents underpenetrated demand for pharmaceutical-grade AS/RS with full lot tracking capabilities.
- Manufacturing:Ontario's Golden Horseshoe zone integrates AS/RS into just-in-time production workflows for automotive and electronics assembly.
Installation volume concentrates in Retail and E-commerce; Pharmaceuticals command the steepest expansion trajectory.
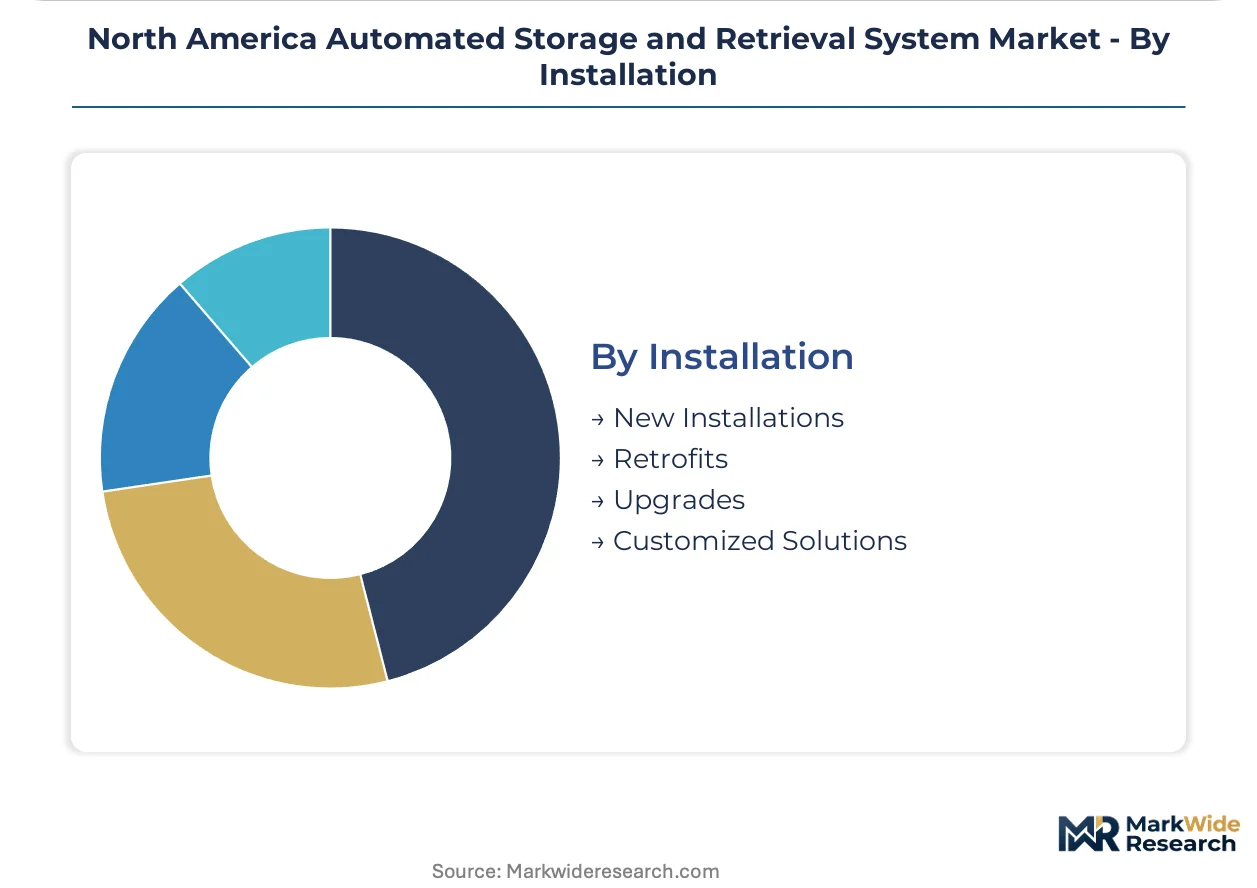
Installation:
Installation type reflects capital cycle positioning, with greenfield deployments competing against retrofit economics in existing warehouse stock.
- New Installations:Greenfield AS/RS deployments in Texas and California distribution corridors optimize rack geometry and material flow from foundation planning. Steel-reinforced aluminum framing reduces cost-per-pallet-position economics in these purpose-built facilities.
- Retrofits:Integration into existing warehouse management architectures demands custom middleware development that extends commissioning timelines. Legacy WMS integration complexity constrains retrofit velocity across North American fulfillment networks.
- Upgrades:Control system modernization and crane mechanism replacement extend operational life in maturing high-bay installations.
- Customized Solutions:Engineered-to-order configurations address non-standard payload geometries or hazardous environment requirements.
Capital deployment favors New Installations; Retrofits are gaining share fastest as existing warehouse stock pressures automation economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in three distinct logistics corridors where e-commerce fulfillment density and pharmaceutical distribution requirements intersect with regulatory pressure for mechanized storage.
United States
California's Inland Empire and Texas's Dallas-Fort Worth logistics hub drive installation volumes for same-day delivery networks. OSHA warehouse safety standards and ergonomic injury prevention mandates accelerate mechanized storage deployment to reduce repetitive lifting exposures in high-volume fulfillment operations. Steel-reinforced aluminum rack framing recalibrates cost-per-pallet-position economics in high-bay installations exceeding 100 feet across these distribution corridors.
Canada
Ontario's Golden Horseshoe manufacturing zone integrates AS/RS into just-in-time production workflows for automotive and electronics assembly. CSA B335 industrial truck standards create compliance thresholds for cross-border system deployments from US-based integrators. Vertical lift modules occupy compact urban distribution footprints in land-constrained Toronto and Hamilton markets where real estate premiums restrict horizontal expansion.
Mexico
Nuevo León and the Bajío Region attract nearshoring manufacturing investment that demands automated storage for automotive and electronics component flow. NOM workplace safety regulations establish equipment certification requirements that complicate unified North American system specifications. Mexico City Metro distribution clusters are deploying robotic AS/RS architectures to absorb e-commerce volume spikes without permanent infrastructure commitments.
North America Automated Storage and Retrieval System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system architects commanding premium positioning in pharmaceutical-validated installations while modular component suppliers capture retrofit opportunities. The vendor base concentrates around three strategic archetypes: full-stack integrators with captive software layers, regional rack fabricators with steel supply advantages, and robotic automation pure-plays attacking flexible fulfillment layouts. Consolidation pressure intensifies as warehouse control software becomes the primary customer lock-in mechanism. Geographic expansion and technology licensing dominate competitive moves as players seek to bridge regulatory fragmentation across the three-country trade bloc.
Within the full-stack integrator tier, Daifuku Co., Ltd. and Dematic Group exemplify contrasting geographic anchoring strategies—Osaka-based versus European-rooted—while both occupying positions defined by software-integrated control architectures. SSI Schaefer represents the modular vertical lift specialization that targets compact urban footprints. These three entities sit within distinct competitive vectors: captive manufacturing footprint, software-integrated execution capabilities, and space-efficient mechanical design.
| Leading Market Players |
|---|
| Daifuku Co., Ltd. |
| Dematic Group (KION Group AG) |
| SSI Schaefer |
| Kardex Holding AG |
| Murata Machinery Ltd. |
| TGW Logistics Group |
| Bastian Solutions LLC |
| Symbotic LLC |
| Swisslog Holding AG |
| Others |
Value Network & Pricing Analysis
Structural steel futures volatility cascades through AS/RS supply chains into three-tier pricing stratification across premium pharmaceutical-validated systems, standard unit-load configurations, and economy-grade vertical lift modules serving cost-constrained urban distributors.
Pricing Analysis
Volume concentrates in unit-load crane systems while margin capture tilts toward software-integrated warehouse control architectures. Pricing stratifies across premium FDA-validated installations, standard OSHA-compliant configurations, and economy-tier retrofit modules differentiated by certification depth and after-sales service bundling. Cost compression in steel-reinforced aluminum rack framing intensifies as mills pass through input volatility, squeezing fabricator margins. Third-party logistics operators in Texas exhibit highest price sensitivity due to seasonal volume unpredictability, while pharmaceutical operators in Ontario accept premium positioning for traceability assurance.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German precision drive component suppliers that anchor crane mechanism production for high-bay installations exceeding 100 feet. Rack fabrication draws from domestic US steel mills, Canadian aluminum smelters, and Mexican structural component workshops. Supply chain risk centers on tariff exposure for European-sourced warehouse control software and sensor arrays. Distribution runs through regional system integrators with captive installation crews in California, Texas, and Ontario logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controls engineering talent scarcity props pricing power for warehouse execution software layers, constraining supply expansion despite surging e-commerce fulfillment demand across North American distribution networks.
For Market Incumbents: Acquire specialized warehouse control software development teams to defend against robotic pure-plays attacking flexible fulfillment layouts. Pursue backward integration into steel-reinforced aluminum rack fabrication to capture margin pools currently leaking to regional metalworkers. Deepen captive manufacturing footprints in Texas to preempt tariff friction on cross-border pharmaceutical system deployments. For New Entrants and Emerging Players: Direct-to-integrator digital channels offer lowest-friction entry for autonomous mobile robot fleet vendors targeting mid-size third-party logistics operators in Dallas-Fort Worth. White-space opportunity concentrates in pharmaceutical-grade retrofits for legacy high-bay installations in Ontario's Golden Horseshoe, where validated traceability upgrades face limited incumbent attention. Lead with outcome-based performance contracts that transfer throughput risk and differentiate against capital-sale incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-defined warehouse control specialists with established FDA validation protocols in California distribution corridors. Long-term viability hinges on positioning upstream of mechanical commoditization as robotic hardware margins compress. Monitor EPA energy efficiency guideline enforcement as inflection signal for regenerative crane technology adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Control Architecture | Captures margin pools as warehouse execution systems become primary customer lock-in mechanism. |
| Regional Manufacturing Footprint Expansion | Daifuku's North American production base anchors supply chains against cross-border tariff exposure. |
| Regulatory Certification Investment | FDA pharmaceutical traceability compliance sustains premium pricing in validated cleanroom configurations. |
| Autonomous Robot Fleet Integration | Dematic's software-integrated AMR deployments displace fixed-aisle infrastructure in seasonal fulfillment layouts. |
| Outcome-Based Service Contracting | Availability-guaranteed agreements in Ontario concentrate vendor balance sheet exposure while locking maintenance revenue. |
Research Methodology
SEC 10-K filings, OSHA enforcement databases, and customs trade records formed the secondary backbone, supplemented by primary interviews with warehouse operations directors, system integrator project managers, and pharmaceutical supply chain executives. Bottom-up installation tracking across California, Texas, and Ontario logistics corridors was triangulated against top-down equipment vendor revenue segmentation.
Historical trendline analysis of AS/RS deployment velocity informed projection frameworks across product type, technology layer, end-user industry, installation mode, and regional regulatory cluster dimensions. CAGRs were derived from elasticity modeling of e-commerce fulfillment density and mechanization mandates over the projection horizon. Forecast inputs incorporated steel price index trajectories and FDA pharmaceutical serialization rule evolution timelines.
Inputs from primary stakeholder interviews and secondary regulatory filings were available through the study window; gaps in privately held system integrator financial disclosures introduce uncertainty bands around vendor market share estimates. Forecasts reflect documented assumptions regarding OSHA ergonomic mandate enforcement intensity and nearshoring manufacturing investment flows. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Predictive Maintenance for Manufacturing Market
Industrial Automation
Latin America HMI Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Asia-Pacific Programmable Logic Controller Market
Industrial Automation
Industrial Embedded Systems Market
Industrial Automation
Middle East and Africa Medical Automation Market
Industrial Automation
Industrial Data Loggers Market
Industrial Automation
Port Equipment Automation Market
Industrial Automation
Global Operational Technology Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
Rotary Actuators Market
Industrial Automation
Smart Factory Market
Industrial Automation
Computer-Aided Manufacturing (CAM) Market