
 Global Helium Gas Market | 2026-2036
Global Helium Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Global Helium Gas Market Foresight
The US Bureau of Land Management helium auction system is decoupling domestic supply from strategic reserve releases, forcing private operators to secure long-term offtake contracts. Air Products and Chemicals, Inc. leverages its Gulf Coast helium extraction infrastructure to sustain pipeline deliveries to semiconductor customers. Qatar Liquefied Gas Co. Ltd. anchors Middle Eastern supply through integrated LNG-helium co-production at Ras Laffan. Linde plc dominates merchant liquid helium distribution across North American and European cryogenic end users.
Helium gas is a colorless, odorless, inert noble gas with a boiling point of minus 268.9 degrees Celsius, extracted primarily through natural gas fractionation or cryogenic distillation of LNG off-gas streams. Its primary commercial purpose centers on supercooling applications, leak detection in high-vacuum systems, and shielding atmospheres for precision welding and additive manufacturing. Liquid helium leads product type revenue due to irreplaceable demand from MRI magnet cooling and particle accelerator research facilities, while compressed helium competes in lighter-volume industrial applications where portability outweighs thermal performance. Semiconductor fabrication represents the fastest-growing end user industry segment as extreme ultraviolet lithography tools require ultra-high purity helium for optical path purging and wafer temperature stabilization.
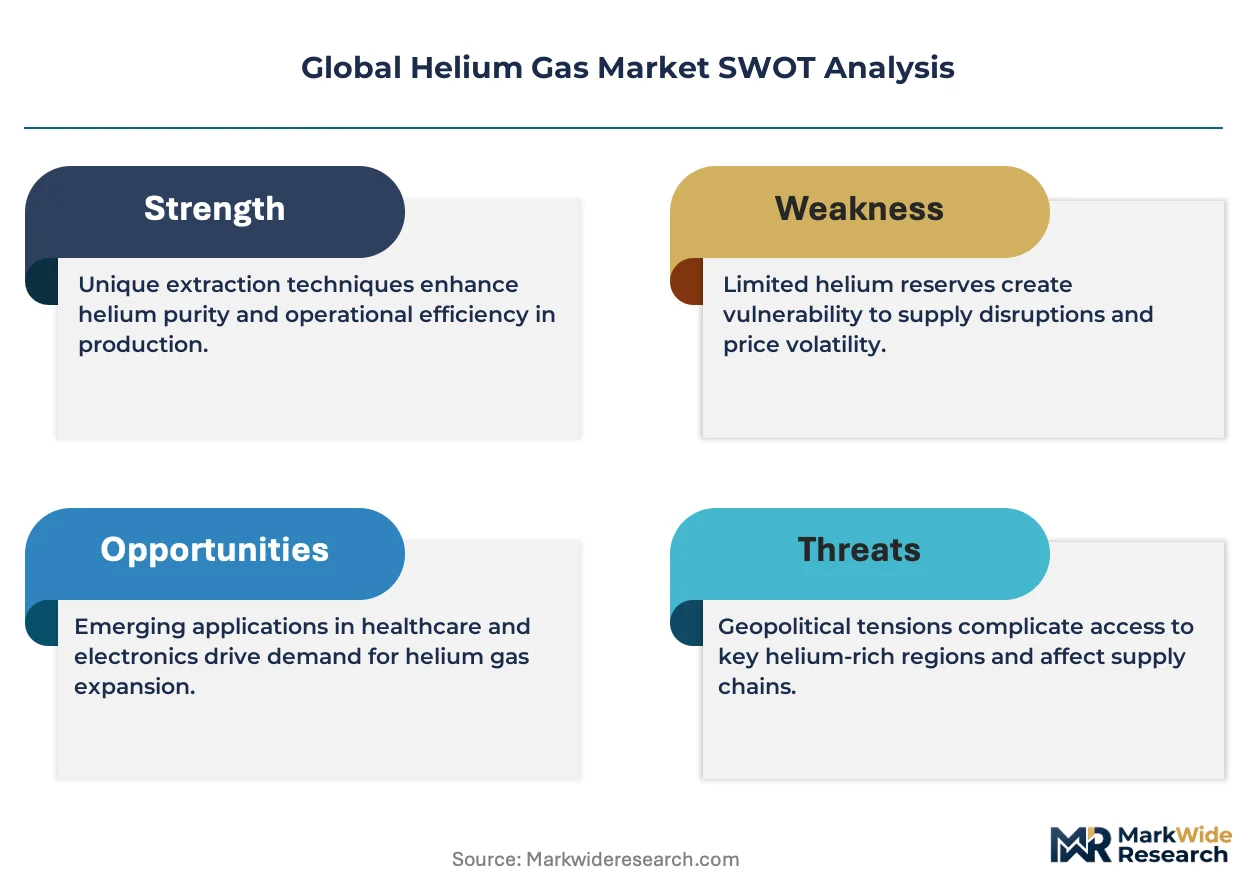
The US FDA regulates helium use in medical device applications, while the EU F-Gas Regulation governs fluorinated gas alternatives that indirectly preserve helium demand in sectors where substitution proves technically unviable. Japan's METI maintains strategic helium stockpiling mandates that buffer supply volatility for domestic electronics manufacturers. China's GB standards for industrial gas purity create non-tariff barriers that shape import specifications for foreign suppliers. Stakeholders must monitor auction calendar shifts, liquefaction capacity additions, and national stockpile policy revisions to time contract renegotiations and inventory positions effectively.
Market Dynamics
Extreme ultraviolet lithography deployment is compressing helium procurement cycles as chipmakers secure multi-year offtake agreements ahead of fab ramp schedules.
Growth Catalysts
- Semiconductor EUV Expansion:Wafer fabs in Taiwan and South Korea are locking helium volumes for optical path purging systems, creating demand pull that outpaces conventional industrial growth rates.
- MRI Magnet Installations:Hospital infrastructure programs across India and Brazil are driving liquid helium consumption for superconducting magnet cooling in diagnostic imaging suites.
- EU F-Gas Regulation:Restrictions on fluorinated refrigerants preserve helium demand in cryogenic applications where technical substitution remains unviable.
Market Restraints
- Qatar Supply Concentration:Over sixty percent of incremental liquefaction capacity originates from Ras Laffan, creating single-point vulnerability for global merchant helium.
- BLM Auction Decoupling:US federal reserve releases no longer buffer spot market volatility, forcing buyers to absorb price swings from private extraction.
- Helium-3 Scarcity:Radioisotope sourcing constraints limit neutron detection applications in homeland security and oil exploration logging tools.
Strategic Opportunities
- Tanzania Greenfield Development:Rukwa Basin non-associated gas fields offer untapped helium concentrations that could diversify African supply origins.
- Additive Manufacturing Shielding:Laser powder bed fusion systems require ultra-high purity helium for reactive metal processing in aerospace component production.
- Japan METI Stockpiling:Strategic reserve mandates create guaranteed offtake floors that de-risk long-term liquefaction investments for suppliers.
Industry Challenges
- Cryogenic Logistics Expertise:Liquid helium transport requires specialized dewar handling and boil-off management that exceeds conventional industrial gas capabilities.
- US FDA Device Certification:Medical-grade helium for MRI and respiratory therapy faces extended validation timelines that delay market entry for new purification facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Helium Gas Market |
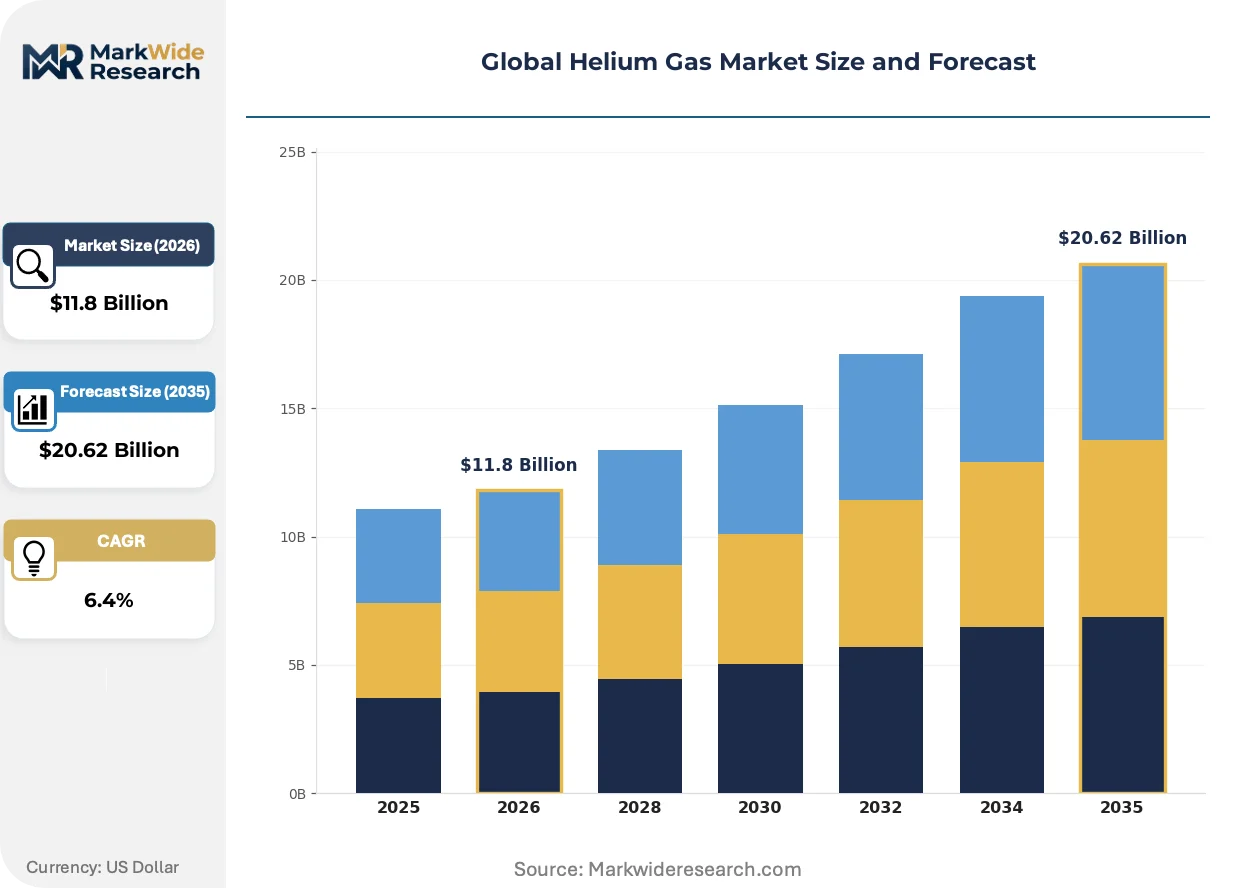
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grade-A Helium, Refined Helium, Liquid Helium, Compressed Helium Application: Cryogenics, Leak Detection, Controlled Atmospheres, Welding, Gas Chromatography End User Industry: Electronics Manufacturing, Scientific Research, Aerospace Engineering, Healthcare Diagnostics, Semiconductor Fabrication Distribution Channel: Direct Sales, Distributors, Online Platforms, Industrial Gas Suppliers |
| Companies Covered | Gazprom, Messer Group, Air Liquide, Iwatani Corporation, ExxonMobil Corporation, Air Products and Chemicals, Inc., Qatar Liquefied Gas Co. Ltd., Gulf Cryo, Linde plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Helium Gas Market Shifts & Advancements
Helium recovery and recycling systems are migrating from research laboratories into production environments, altering consumption economics for high-volume industrial users.
Membrane separation technology is expanding into primary helium extraction at lean-concentration natural gas wells, displacing energy-intensive cryogenic distillation for sub-one-percent helium streams. Operators in Wyoming and Colorado are piloting polymer membrane arrays that bypass conventional liquefaction steps. This diffusion-based approach is expanding into mid-scale production, compressing capital requirements for field development.
The EU F-Gas Regulation is tightening phase-down schedules for hydrofluorocarbons used in semiconductor etching and cleaning, indirectly preserving helium demand in wafer processing where fluorinated alternatives face elimination. German chemical regulators are accelerating compliance deadlines that force process requalification. Cryogenic equipment manufacturers in the Netherlands and France are responding with helium-compatible system redesigns.
Long-term contracting is displacing spot purchasing among semiconductor and aerospace buyers who previously relied on merchant market flexibility. Tier-one chipmakers now negotiate five-year minimum commitments directly with Qatari and Algerian producers. This preference shift concentrates procurement leverage with integrated energy majors and marginalizes regional distributors in Taiwan, South Korea, and Arizona.
Global Helium Gas Market Segmentation
Helium procurement cycles vary dramatically across purity grades and physical states, with semiconductor fabs and MRI networks driving divergent specification requirements. Upgrade schedules for EUV lithography tools and superconducting magnet cooling systems create asynchronous demand pulses that suppliers must reconcile through differentiated inventory positioning.
Product Type:
Replacement cycles for helium purification and liquefaction infrastructure determine upgrade timing across the value chain, with end-users trading off capital intensity against operational efficiency gains.
- Liquid Helium:Cryogenic liquid at minus 268.9 degrees Celsius requiring specialized dewar handling and boil-off management. MRI magnet cooling in hospital diagnostic suites across India and Brazil consumes the largest volumes, constrained by helium recovery system deployment timelines.
- Compressed Helium:High-pressure cylinder gas for portable industrial applications where thermal performance is secondary to mobility. Leak detection operations in aerospace manufacturing facilities favor this format for field deployment flexibility.
- Grade-A Helium:Ultra-high purity specification exceeding 99.9999 percent for semiconductor optical path purging. Taiwan and South Korea wafer fabs enforce stringent contamination thresholds.
- Refined Helium:Standard purity grades for welding shielding and controlled atmosphere applications. Industrial gas suppliers blend this stream for cost-sensitive manufacturing segments.
Liquid Helium sits at the top of the volume ranking, with Grade-A Helium climbing the fastest.
Application:
Cost tiers separate mission-critical applications from commodity industrial uses, with pricing spreads reflecting helium scarcity premiums and technical substitution barriers.
- Cryogenics:Supercooling applications for superconducting magnets in particle accelerators and fusion research facilities. Germany's DESY and CERN in Switzerland anchor European demand through continuous magnet operation requirements.
- Leak Detection:Mass spectrometry-based vacuum integrity testing for semiconductor process equipment and aerospace components. Taiwan chipmakers deploy this for chamber qualification protocols.
- Controlled Atmospheres:Inert shielding for additive manufacturing of reactive metal aerospace components. Laser powder bed fusion systems require ultra-high purity specifications.
- Welding:Arc shielding for precision joining in automotive and construction applications. Compressed helium competes with argon on portability metrics.
- Gas Chromatography:Carrier gas for analytical chemistry and petrochemical quality control. Laboratory instrumentation in Saudi Arabia and UAE research centers drives Middle Eastern consumption.
Cryogenics commands the highest purity premiums, with Leak Detection gaining share fastest as EUV tool counts multiply.
End User Industry:
Customer concentration varies sharply, with semiconductor fabs consolidating procurement through direct producer contracts while research institutions fragment across regional distributors.
- Semiconductor Fabrication:EUV lithography optical path purging and wafer temperature stabilization. South Korean and Taiwanese chipmakers negotiate five-year minimum commitments with Qatari producers.
- Healthcare Diagnostics:MRI superconducting magnet cooling and respiratory therapy applications. US FDA certification requirements extend validation timelines for new purification entrants.
- Electronics Manufacturing:Fiber optic production and display panel fabrication. Japan's METI stockpiling mandates buffer supply volatility for domestic manufacturers.
- Scientific Research:Particle physics, materials science, and low-temperature physics applications. CERN and Brookhaven National Laboratory anchor institutional demand.
- Aerospace Engineering:Rocket propulsion testing and satellite component leak detection. NASA and SpaceX operations in Florida and Texas drive North American consumption.
Semiconductor Fabrication leads procurement scale, with Healthcare Diagnostics expanding most quickly through emerging market hospital infrastructure programs.
Distribution Channel:
Supply chain configuration determines margin capture, with integrated energy majors extracting value through captive liquefaction while regional distributors face disintermediation pressure from direct contracting.
- Direct Sales:Long-term offtake agreements between producers and high-volume industrial consumers. Qatar Liquefied Gas Co. and Air Products bypass intermediaries for semiconductor and aerospace accounts.
- Industrial Gas Suppliers:Merchant liquid distribution through cryogenic logistics networks. Linde plc dominates North American and European last-mile delivery capabilities.
- Distributors:Regional inventory holders serving fragmented research and manufacturing segments. Taiwan and Arizona distributors face margin compression from producer direct outreach.
- Online Platforms:E-commerce procurement for small-volume laboratory and maintenance applications. Limited penetration due to cryogenic handling complexity.
Direct Sales captures the largest contract value, with Industrial Gas Suppliers deepening their logistics moats fastest through specialized dewar fleet expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium extraction scaled commercially in the United States during the early twentieth century through federal reserve accumulation. The industry subsequently dispersed across natural gas basins in Qatar, Algeria, and Russia as LNG co-production economics matured.
United States
Wyoming and Colorado host membrane separation pilots at lean-concentration natural gas wells that bypass cryogenic distillation. The BLM auction system no longer buffers spot volatility, forcing private operators toward long-term offtake structures. The Permian Basin anchors domestic extraction infrastructure serving semiconductor fabs in Arizona and Texas.
Qatar
Ras Laffan integrated LNG-helium co-production captures over sixty percent of incremental global liquefaction capacity. The North Field expansion concentrates merchant helium supply through single-point infrastructure. Doha-based producers negotiate five-year minimum commitments directly with Taiwanese and South Korean chipmakers.
Germany
DESY and CERN anchor European demand for superconducting magnet cooling in particle physics research. The EU F-Gas Regulation accelerates hydrofluorocarbon phase-downs that preserve helium demand in cryogenic applications. Chemical regulators in Frankfurt am Main compress compliance deadlines for semiconductor process requalification.
Japan
METI strategic stockpiling mandates buffer supply volatility for domestic electronics manufacturers. Fiber optic production and display panel fabrication drive consumption across the Kanto industrial corridor. Tokyo-based institutional buyers maintain inventory floors that de-risk long-term liquefaction investments.
China
GB standards for industrial gas purity create non-tariff barriers shaping import specifications for foreign suppliers. Yangtze River Delta wafer fabs expand EUV lithography capacity requiring ultra-high purity helium for optical path purging. Shanghai and Suzhou clusters concentrate procurement leverage among domestic semiconductor foundries.
Global Helium Gas Market Competitive Landscape
The competitive structure tilts toward integrated energy majors with captive liquefaction infrastructure. Market concentration reflects high capital barriers for cryogenic distillation and specialized logistics fleets. Three archetypes dominate: state-linked gas producers, diversified industrial gas conglomerates, and regional extraction specialists. Capacity expansion and strategic partnerships constitute the primary competitive vectors as spot purchasing gives way to direct contracting.
Within the state-linked producer tier, Qatar Liquefied Gas Co. Ltd. and Gazprom occupy positions reflecting sovereign resource control. Among diversified industrial gas conglomerates, Linde plc and Air Liquide S.A. exemplify merchant distribution archetypes spanning cryogenic logistics networks. Air Products and Chemicals, Inc. anchors the North American extraction-specialist segment through Gulf Coast infrastructure.
| Leading Market Players |
|---|
| Gazprom |
| Messer Group |
| Air Liquide |
| Iwatani Corporation |
| ExxonMobil Corporation |
| Air Products and Chemicals, Inc. |
| Qatar Liquefied Gas Co. Ltd. |
| Gulf Cryo |
| Linde plc |
| Others |
Supply & Pricing Matrix
Semiconductor fabs in Taiwan and South Korea command pricing leverage through multi-year offtake commitments that compress spot market premiums for ultra-high purity helium. Their consolidated procurement power forces suppliers toward contract-based structures that stabilize volume flows while exposing smaller research and industrial users to residual spot volatility.
Pricing Analysis
Contract-based long-term offtake dominates helium procurement as five-year minimum commitments displace spot purchasing among high-volume consumers. Price differentiation hinges on purity certification thresholds and volume scale tiers, with Grade-A specifications for EUV lithography commanding scarcity premiums over standard welding grades. Cost compression in industrial-grade segments is intensifying as membrane separation technology lowers extraction barriers in Wyoming and Colorado. Research institutions exhibit the highest price sensitivity due to fragmented purchasing and limited storage infrastructure, while semiconductor fabs absorb premium pricing to secure supply continuity.
Supply Chain Analysis
Regional distribution centers in Doha, Houston, and Rotterdam anchor hub-and-spoke patterns for liquid helium dewar logistics. Supply concentrates in Qatar, the United States, and Algeria as primary extraction origins, with Ras Laffan integrated LNG-helium co-production feeding over sixty percent of incremental liquefaction capacity. Raw material dependencies span natural gas feedstock with helium concentrations, cryogenic liquefaction equipment, and specialized transport dewars with boil-off management systems. Single-source vulnerability at Ras Laffan creates structural supply chain risk given concentrated infrastructure exposure. Distribution runs through industrial gas suppliers with captive cryogenic fleets rather than conventional freight networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where the EU F-Gas Regulation accelerates hydrofluorocarbon phase-downs that preserve helium demand in cryogenic applications lacking technical substitutes.
For Market Incumbents: Anchor Gulf Coast extraction infrastructure through capacity maintenance and liquefaction efficiency investments to defend against membrane separation technology entrants in lean-concentration fields. Secure backward integration into Qatari and Algerian long-term offtake contracts before direct producer outreach marginalizes regional distributor roles in Taiwan and Arizona. Certification investment in FDA medical-grade pathways extends validation moats against new purification facility entrants. For New Entrants and Emerging Players: The EU F-Gas Regulation in Europe opens a window for cryogenic equipment manufacturers to capture helium-compatible system redesign demand as German chemical regulators compress compliance deadlines. Tanzania Rukwa Basin greenfield development offers the most penetrable supply origin for portfolio diversification away from Qatar concentration. Target additive manufacturing shielding applications in aerospace component production where laser powder bed fusion systems require ultra-high purity specifications and established supplier relationships remain underdeveloped. For Investors and Strategic Acquirers: Integrated energy majors with captive liquefaction infrastructure are the most active acquirer in this space, consolidating extraction-specialist assets to secure helium streams for semiconductor and aerospace direct sales. Long-term viability across the projection horizon rests on national stockpiling policy durability and EUV lithography deployment trajectories. Watch Japan METI strategic reserve mandate revisions as the inflection indicator for guaranteed offtake floor stability.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Five-year minimum commitments with Qatari producers lock volume for Taiwan and South Korean chipmakers. |
| Backward Integration | Membrane separation pilots in Wyoming and Colorado bypass cryogenic distillation for sub-one-percent helium streams. |
| Capacity Expansion | Ras Laffan North Field expansion captures incremental liquefaction volumes for global merchant helium supply. |
| Green Manufacturing Transition | Helium recovery and recycling systems migrate from research laboratories into production environments for consumption economics. |
| Joint Venture | Tanzania Rukwa Basin partnerships diversify African supply origins away from Qatar concentration risk. |
Research Methodology
Bottom-up semiconductor and healthcare demand modeling reconciled against top-down LNG-helium co-production tracking forms the analytical core of this study. Primary interviews with cryogenic logistics managers, helium procurement leads at wafer fabs, MRI facility biomedical engineers, and industrial gas distribution channel partners inform volume assumptions. Secondary validation draws from SEC 10-K filings of listed industrial gas conglomerates, customs and trade data for helium import flows, FDA medical device certification records, and EU F-Gas Regulation compliance disclosures. Triangulation across these sources reconciles end-use consumption patterns against extraction and liquefaction capacity additions.
Input-output matrices map helium purity grades against application requirements and geographic demand clusters across the modeling period. Segmentation dimensions include physical state, purity specification, end-use industry, and distribution channel structure. CAGRs derive from weighted capacity expansion schedules, EUV lithography tool deployment trajectories, and hospital infrastructure program timelines in emerging markets. Forecast inputs incorporate BLM auction calendar shifts, Qatar North Field expansion phases, and Japan METI stockpile policy revisions.
Revisions become necessary when Qatar supply disruptions, BLM auction system modifications, or EU F-Gas Regulation acceleration materialize beyond baseline assumptions. Forecasts reflect documented assumptions about liquefaction capacity commissioning schedules and semiconductor fab ramp timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
US Specialty Gas Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
Xenon Gas Market
Industrial Gases
Helium Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Nitrogen Gas Springs Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Europe Specialty Gas Market
Industrial Gases
Global Rare Gases Market
Industrial Gases
United States Industrial Gases Market
Industrial Gases
Europe Industrial Gases Market