
 Middle East Ammonia Market | 2026-2036
Middle East Ammonia Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Ammonia Market Analysis
SFDA's tightening of industrial chemical handling protocols is repositioning the cost-of-entry calculus for ammonia producers across the Gulf. SABIC leverages its integrated petrochemical complexes to sustain feedstock advantages in bulk anhydrous production. Qatar Fertiliser Company anchors regional export capacity through its Qafco facilities, while Ma'aden dominates the Kingdom's west coast with phosphate-ammonia integration.
Middle East ammonia is a nitrogenous compound produced primarily via steam methane reforming of natural gas, typically containing 82% nitrogen by weight and serving as the foundational feedstock for synthetic fertilizers and industrial chemicals. Anhydrous ammonia leads product type volumes due to its direct application in urea synthesis and phosphate fertilizer complexes, while aqueous ammonia captures expanding demand from water treatment and pollution control installations. Fertilizers anchor end-user consumption through the region's phosphate-rich agricultural investments, and industrial chemicals represent the fastest-growing application segment as Gulf states diversify beyond hydrocarbon extraction.
SFDA, Saudi Arabia's national pharmaceutical and chemical regulator, enforces handling standards that shape product formulation and packaging requirements for ammonia destined for pharmaceutical and food processing end users. The UAE's MOHAP and Saudi Arabia's SFDA jointly influence import certification pathways, creating divergent compliance obligations for cross-Gulf suppliers. Stakeholders must monitor how green hydrogen subsidies and carbon border adjustments reshape the economics of conventional versus low-carbon ammonia production across the Arabian Peninsula.
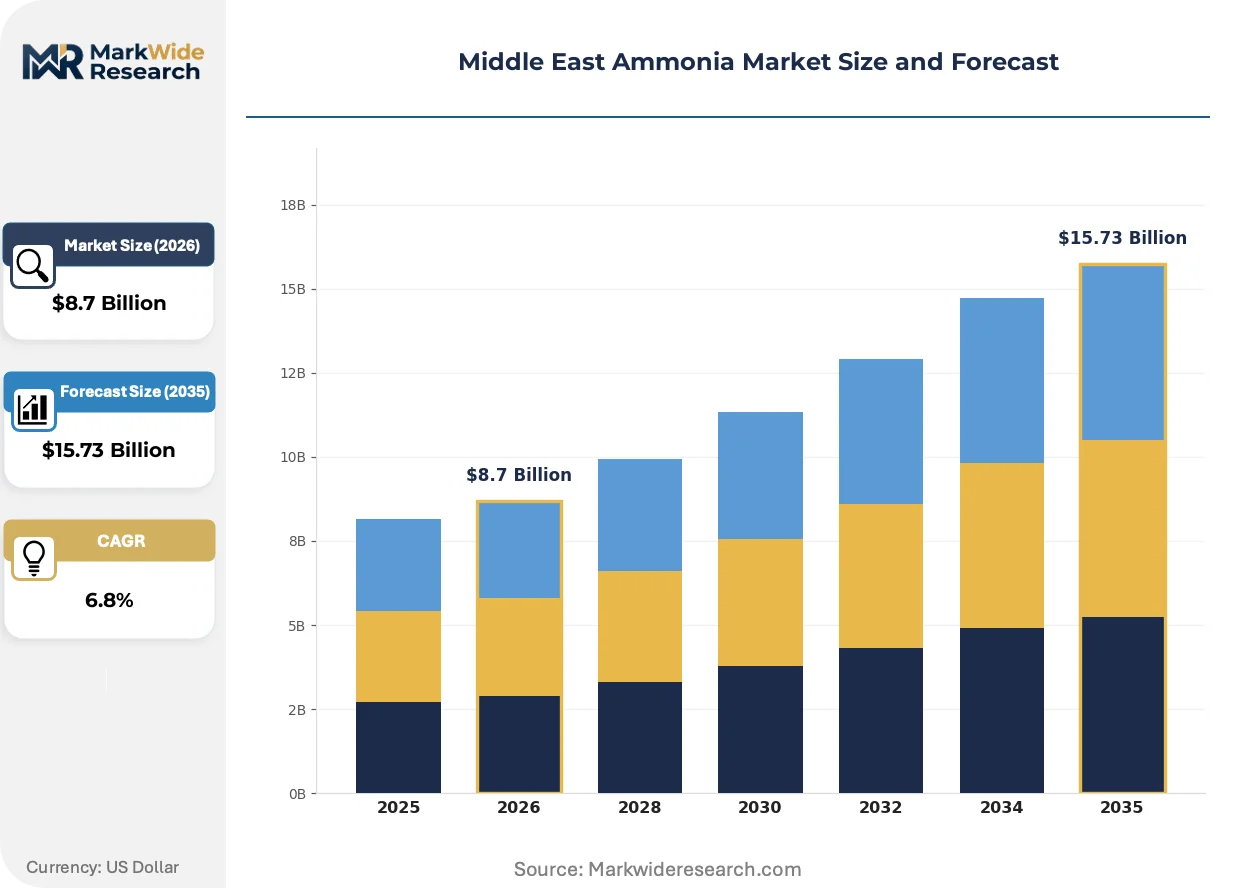
Market Dynamics
Saudi Arabia's SFDA chemical handling mandates and the UAE's green hydrogen subsidies are bifurcating capital flows between conventional steam methane reforming and electrolysis-based ammonia pathways across the Arabian Peninsula.
Growth Catalysts
- Agricultural Modernization:Saudi Arabia's phosphate-ammonia integration programs in the Eastern Province industrial cluster are expanding captive consumption loops for bulk anhydrous production.
- Green Hydrogen Policy:The UAE's national hydrogen strategy is redirecting state-backed capital toward low-carbon ammonia production technologies at Ruwais and Al Reyadah facilities.
- Water Treatment Demand:Aqueous ammonia offtake from pollution control installations in Qatar and Bahrain is accelerating as Gulf states tighten effluent discharge standards.
Market Restraints
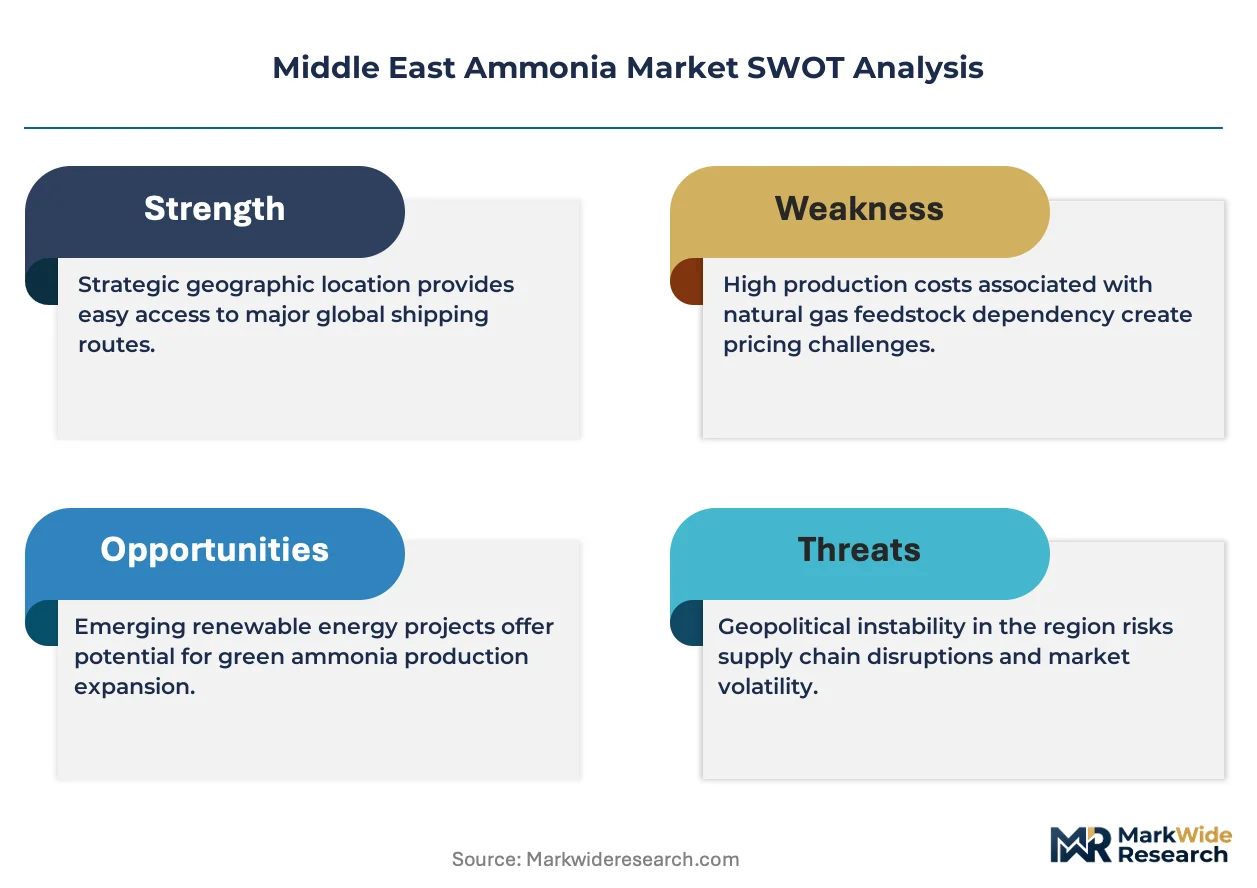
- Natural Gas Feedstock Volatility:Regional ammonia production remains tethered to Gulf Cooperation Council natural gas pricing, exposing margins to hydrocarbon market swings.
- Supply Concentration Risk:The Eastern Province industrial cluster hosts disproportionate production capacity, creating geographic vulnerability to single-point disruptions.
- Carbon Border Adjustment Pressure:European Union carbon border adjustment mechanisms threaten export competitiveness for conventional ammonia shipments to Mediterranean markets.
Strategic Opportunities
- Oman Greenfield Development:Duqm Special Economic Zone offers undeveloped coastal ammonia production sites with proximity to Asian shipping lanes.
- Blue Ammonia Certification:Carbon capture integration at existing Saudi facilities can access premium pricing in Japanese and South Korean offtake contracts.
- Industrial Chemical Diversification:Ammonia-to-hydrogen cracking for maritime fuel applications is opening new demand verticals beyond fertilizer synthesis.
Industry Challenges
- Electrolyzer Engineering Talent Scarcity:Green ammonia projects face acute shortages of proton exchange membrane specialists and grid integration engineers across the Gulf.
- SFDA Certification Timelines:Saudi pharmaceutical-grade ammonia approvals now require eighteen-month validation cycles, compressing working capital efficiency for specialty producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Ammonia Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous Ammonia, Aqueous Ammonia, Urea Ammonium Nitrate, Ammonium Sulfate End User: Agriculture, Chemical Industry, Pharmaceuticals, Food Processing Application: Fertilizers, Refrigerants, Industrial Chemicals, Cleaners Supply Chain Stage: Production, Distribution, Retail, Storage |
| Companies Covered | OCI N.V., Qatar Fertiliser Company, Yara International ASA, Pardis Petrochemical Company, Petrochemical Industries Company, SABIC, Gulf Petrochemical Industries Company, Istanbul Fertilizer Industry Inc. Co., Ma'aden, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Ammonia Market Emerging Trajectories
Electrolysis-based ammonia synthesis is rewriting project economics across the Middle East, with technology choices now determining access to premium export markets and state subsidy pools.
Proton exchange membrane electrolysis paired with Haber-Bosch synthesis loops is consolidating project development pipelines in the UAE and Saudi Arabia. State-owned utilities in Abu Dhabi are procuring modular electrolyzer units for 2027 commissioning at existing industrial ports. This technology convergence is compressing the capital cost gap between gray and green ammonia production pathways.
SFDA's tightening of industrial chemical handling protocols is mandating secondary containment and real-time leak detection at all ammonia storage facilities in Saudi Arabia. The regulation forces retrofit investments at legacy urea synthesis plants. Bulk anhydrous producers in Jubail Industrial City are responding by consolidating storage infrastructure into shared terminal facilities.
Long-term offtake contracting is displacing spot market transactions for Gulf ammonia exports. Japanese trading houses and South Korean fertilizer manufacturers are locking in fifteen-year supply agreements with carbon intensity clauses. This procurement pattern shift is most visible in Qatar's North Field expansion negotiations, where destination flexibility is being traded for price stability guarantees.
Middle East Ammonia Market Segmentation
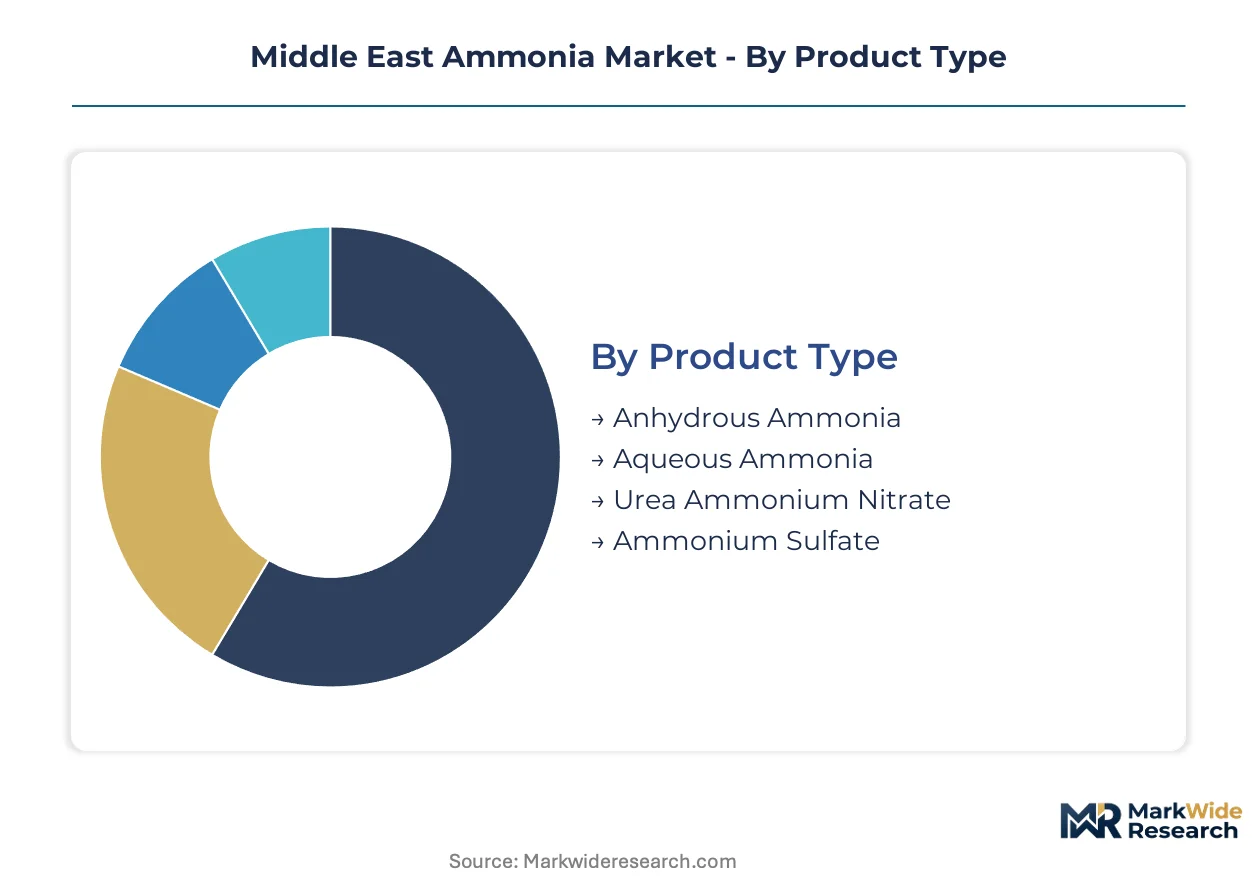
Ammonia segmentation in the Middle East reveals divergent margin profiles across product forms, with bulk commodity volumes competing against premium-grade specialties for capital allocation. Understanding these splits enables producers to optimize portfolio positioning against regulatory and end-use demands.
Product Type:
Anhydrous ammonia dominates absolute volumes while aqueous ammonia commands premium pricing through specialty applications.
- Anhydrous Ammonia:A nitrogenous compound containing 82% nitrogen by weight, stored and transported as a pressurized liquid without water content. Demand concentrates in Saudi Arabia's Eastern Province phosphate fertilizer complexes, where SABIC and Ma'aden operate integrated urea synthesis loops that consume bulk volumes at pipeline-connected sites.
- Aqueous Ammonia:A water-diluted solution typically ranging from 19% to 29% ammonia concentration, requiring less specialized handling infrastructure. Offtake is accelerating in Qatar and Bahrain water treatment facilities as Gulf states implement stricter effluent discharge standards under national environmental frameworks.
- Urea Ammonium Nitrate:A liquid fertilizer solution combining urea and ammonium nitrate in aqueous suspension, favored for precision agriculture applications.
- Ammonium Sulfate:A crystalline solid byproduct of caprolactam and steel industry operations, serving sulfur-deficient soils in the Levant and North Africa export markets.
Today's leader: Anhydrous Ammonia. Tomorrow's challenger: Aqueous Ammonia.
End User:
Customer concentration varies sharply, with agricultural offtake scaling through state-backed procurement while pharmaceutical buyers demand certification-intensive specialty grades.
- Agriculture:The dominant consumption channel, absorbing ammonia derivatives for phosphate and nitrogen fertilizer synthesis across Saudi Arabia's wheat and date palm modernization programs. SFDA's fertilizer quality mandates are forcing product reformulation at Qafco and Ma'aden blending facilities.
- Chemical Industry:Industrial chemical manufacturers in Jubail and Yanbu purchase ammonia for caprolactam, acrylonitrile, and nitric acid production. This segment is climbing the fastest as Gulf states execute downstream diversification strategies to reduce hydrocarbon export dependence.
- Pharmaceuticals:High-purity ammonia for drug synthesis and excipient applications, subject to eighteen-month SFDA validation cycles that compress working capital efficiency.
- Food Processing:Food-grade ammonia serving pH control and refrigeration applications in UAE and Saudi dairy and meat processing plants.
Agriculture locks in baseline volumes. Chemical Industry unlocks margin expansion.
Application:
Application mix determines capital intensity, with fertilizer synthesis requiring integrated petrochemical complexes while refrigerant and cleaner applications tolerate distributed production.
- Fertilizers:The foundational application, converting ammonia into urea, ammonium nitrate, and phosphate fertilizers at integrated complexes in Ras Al-Khair and Ruwais. Saudi Arabia's food security initiatives sustain offtake despite efficiency improvements in precision agriculture.
- Industrial Chemicals:Feedstock for explosives, synthetic fibers, and specialty chemicals manufacturing. Abu Dhabi's industrial ports are attracting modular ammonia-to-chemicals projects under green hydrogen subsidy frameworks.
- Refrigerants:Ammonia-based industrial cooling systems in cold chain logistics and food processing, with demand rising from UAE port expansion projects.
- Cleaners:Household and industrial cleaning formulations, a price-sensitive segment served by aqueous ammonia distributors in Dubai and Jeddah retail markets.
Fertilizers defend volume share. Industrial Chemicals capture value-added growth.
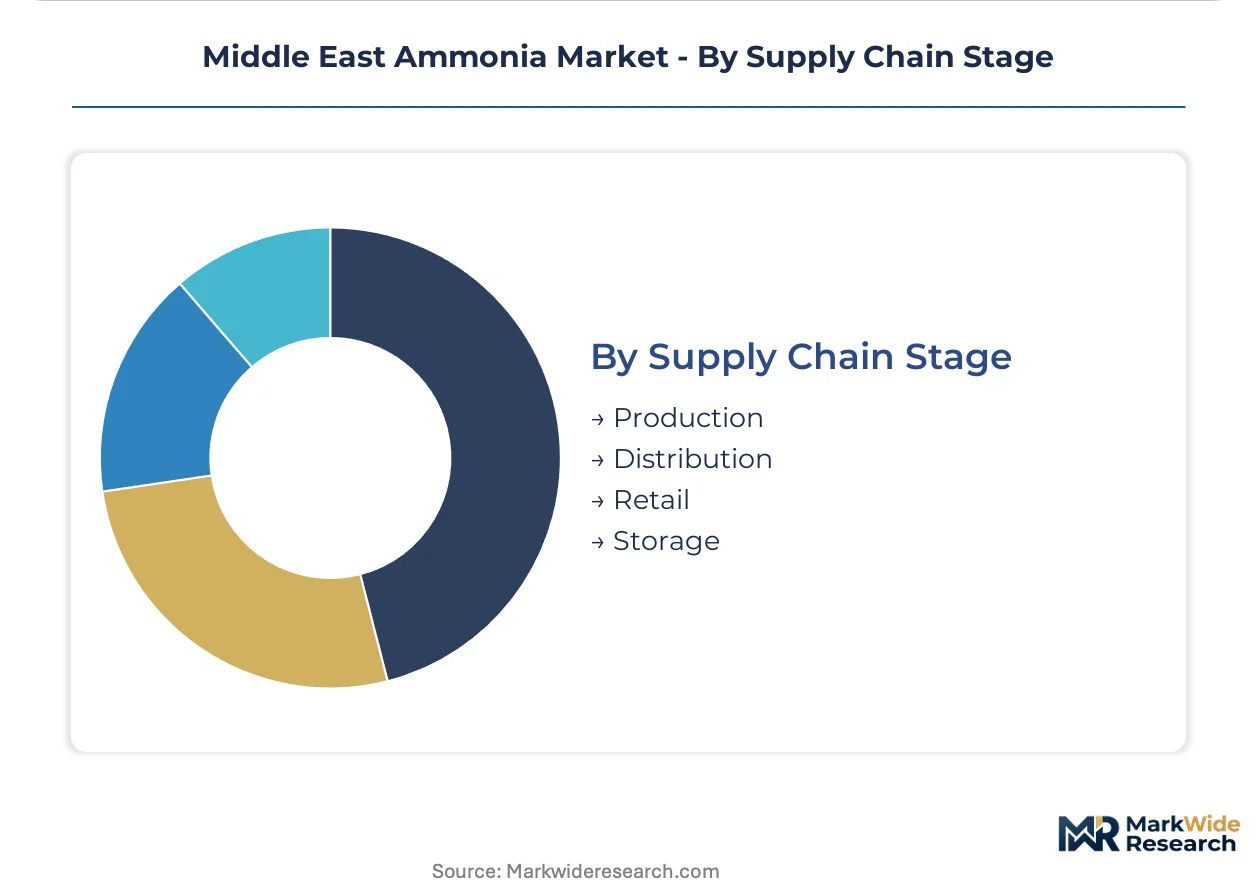
Supply Chain Stage:
Stage-specific economics favor backward-integrated producers who control production and storage while outsourcing distribution to regional traders.
- Production:Steam methane reforming and Haber-Bosch synthesis at integrated complexes, where natural gas feedstock access determines cost position. Qatar's North Field expansion and Saudi master gas system sustain regional production economics.
- Storage:Pressurized and refrigerated terminals at Jubail, Mesaieed, and Ruwais, with SFDA-mandated secondary containment retrofits forcing consolidation into shared terminal facilities.
- Distribution:Bulk vessel, rail, and truck logistics connecting production clusters to agricultural heartlands and export terminals.
- Retail:Packaged aqueous ammonia and blended fertilizers for smallholder farms and industrial consumers, fragmented across regional trading houses.
Production and Storage concentrate economic returns. Distribution and Retail commoditize rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled process engineers and Haber-Bosch specialists concentrate in the Eastern Province industrial corridor, anchoring the Gulf's ammonia production workforce density.
Saudi Arabia
Phosphate-ammonia integration at Ras Al-Khair and Jubail sustains captive consumption for bulk anhydrous production. SFDA chemical handling mandates force eighteen-month validation cycles for pharmaceutical-grade certification. The Eastern Province cluster hosts SABIC and Ma'aden facilities where pipeline-connected urea synthesis loops consume regional volumes.
United Arab Emirates
Green hydrogen subsidies redirect state-backed capital toward electrolysis-based ammonia at Ruwais and Al Reyadah. MOHAP import certification pathways diverge from Saudi SFDA requirements, creating cross-Gulf compliance friction. Abu Dhabi's industrial ports attract modular ammonia-to-chemicals projects under national hydrogen strategy frameworks.
Qatar
North Field natural gas expansion underpins Qafco's export capacity for long-term offtake contracts with Asian buyers. The national environmental regulator tightens effluent standards, accelerating aqueous ammonia demand from water treatment installations. Mesaieed industrial city concentrates storage and loading infrastructure for bulk vessel exports.
Oman
Duqm Special Economic Zone offers undeveloped coastal production sites with proximity to Asian shipping lanes. The sultanate's economic diversification agenda prioritizes downstream chemical investments over raw hydrocarbon exports. Port infrastructure investments at Duqm target transshipment advantages for Indian Ocean trade routes.
Bahrain
Water treatment and pollution control installations drive aqueous ammonia offtake as effluent discharge standards tighten. The island's limited domestic production capacity creates import dependence on Saudi and Qatari suppliers. Sitra industrial area hosts blending and distribution facilities serving local agricultural and chemical demand.
Middle East Ammonia Market Vendor Landscape
The competitive structure tilts toward state-anchored petrochemical conglomerates with privileged natural gas access. Gulf-based producers leverage integrated complexes and captive feedstock supply to sustain cost positions against global merchant ammonia traders. Two strategic archetypes dominate: vertically integrated national champions controlling full value chains, and export-focused fertilizer specialists securing long-term Asian offtake. Capacity expansion and carbon capture integration represent the dominant competitive moves as producers position for carbon border adjustment compliance.
Among state-anchored conglomerates, SABIC and Ma'aden exemplify the integrated archetype with phosphate-ammonia complexes and pipeline-connected consumption loops. Qatar Fertiliser Company occupies a position as the export-specialist anchor, leveraging North Field gas access for bulk anhydrous shipments to Asian markets. These three represent the competitive core around which regional supply dynamics organize.
| Leading Market Players |
|---|
| OCI N.V. |
| Qatar Fertiliser Company |
| Yara International ASA |
| Pardis Petrochemical Company |
| Petrochemical Industries Company |
| SABIC |
| Gulf Petrochemical Industries Company |
| Istanbul Fertilizer Industry Inc. Co. |
| Ma'aden |
| Others |
Supply Flow & Price Mechanics
Electrolysis-based ammonia synthesis is compressing the capital cost gap between gray and green production pathways while simultaneously concentrating supply authority among state-backed utilities with privileged grid access. This technology transition reshapes cost economics through modular electrolyzer deployments at Ruwais and Al Reyadah, tightening producer margins on conventional steam methane reforming while elevating pricing power for certified low-carbon output.
Pricing Analysis
Long-term offtake contracting dominates premium pricing while spot transactions commoditize bulk anhydrous volumes. Price differentiation hinges on carbon intensity certification and destination flexibility clauses in Japanese and South Korean procurement agreements. Pricing pressure stems from European Union carbon border adjustment mechanisms threatening export competitiveness for conventional shipments. Agricultural buyers in Saudi Arabia's Eastern Province exhibit lowest price sensitivity due to captive pipeline supply, while industrial chemical distributors in Dubai and Jeddah retail markets face acute margin compression.
Supply Chain Analysis
Direct-to-fertilizer-complex pipelines handle captive demand from SABIC and Ma'aden facilities, while bulk vessel exports serve Asian offtake markets. Geographic supply concentrates in Saudi Arabia, Qatar, and the UAE, with the Eastern Province industrial cluster hosting disproportionate capacity. Raw material dependencies center on natural gas feedstock from the North Field expansion and Saudi master gas system, plus water treatment chemicals for aqueous ammonia dilution. Supply chain risk manifests in single-point geographic vulnerability to disruption at Jubail and Mesaieed loading terminals. Distribution runs through shared terminal facilities consolidating SFDA-mandated secondary containment investments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where pharmaceutical-grade certification and blue ammonia carbon capture specifications command accelerating demand premiums over commodity bulk volumes.
For Market Incumbents: Cement feedstock advantages through backward integration into natural gas allocation rights under Saudi master gas system frameworks. Prioritize carbon capture retrofit investments at Ras Al-Khair and Jubail facilities to preempt European Union carbon border adjustment exclusions. Defensive positioning requires consolidating aqueous ammonia storage into shared terminals to distribute SFDA compliance costs across multiple producers. For New Entrants and Emerging Players: Launch via modular electrolyzer deployments at Duqm Special Economic Zone targeting Japanese hydrogen import tenders with fifteen-year offtake structures. White-space availability concentrates in Omani greenfield development and Bahrain import-dependent water treatment installations. The most penetrable segment is maritime ammonia-to-hydrogen cracking for shipping fuel applications, where first-mover certification unlocks premium contract structures absent incumbent legacy obligations. For Investors and Strategic Acquirers: Valuations sit cheapest among export-focused fertilizer specialists lacking carbon capture integration, while integrated petrochemical conglomerates trade at scarcity premiums for pipeline-connected consumption loops. Long-term viability over a decade horizon favors producers with secured North Field gas allocation and demonstrated electrolyzer engineering capabilities. The signal to watch is Japanese trading house procurement pattern shifts toward carbon intensity clauses in contract renegotiations.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Enables blue ammonia certification accessing premium Japanese and South Korean offtake contracts. |
| Electrolyzer Capacity Buildout | Positions UAE producers for state-backed green hydrogen subsidy pools under national strategy frameworks. |
| Shared Terminal Consolidation | Distributes SFDA-mandated secondary containment retrofit costs across multiple Jubail storage operators. |
| Long-term Supply Agreement | Locks in fifteen-year price stability with Asian buyers trading destination flexibility for volume guarantees. |
| Backward Integration into Feedstock | Secures privileged natural gas allocation from Qatar's North Field expansion sustaining cost position. |
Methodological Framework
Direct dialogue with plant managers at SABIC and Ma'aden facilities, procurement leads at Qafco downstream operations, distribution channel partners in Dubai and Jeddah, and technical R&D directors at electrolyzer engineering firms grounded qualitative assessment. Secondary validation drew from GCC customs and trade data, SEC filings of listed fertilizer producers, SABIC annual sustainability disclosures, and SFDA regulatory guidance documents. Bottom-up volume estimates from individual facility capacities triangulated against top-down demand projections from Saudi agricultural modernization program targets.
Bottom-up modeling of individual production facility economics across the projection horizon converged with top-down demand segmentation by product grade, end-use industry, and regional production hub. Segmentation dimensions included anhydrous versus aqueous ammonia grades, fertilizer synthesis versus industrial chemical applications, and captive pipeline-connected versus export-oriented supply configurations. CAGRs were derived from weighted average growth trajectories across these segments, incorporating natural gas price sensitivity bands and electrolyzer capital cost learning curves as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under European Union carbon border adjustment implementation timelines and Gulf Cooperation Council natural gas pricing reforms. Forecasts reflect documented assumptions regarding electrolyzer technology cost trajectories and SFDA certification timeline stability. Periodic stress-testing of base assumptions is recommended against regulatory shifts in pharmaceutical-grade handling protocols and green hydrogen subsidy allocation mechanisms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Sodium Percarbonate Market
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
Isatoic Acid Anhydride Market
Bulk Chemicals
North America Dimethyl Phosphate Market
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
Cesium Salts Market
Bulk Chemicals
United States Calcium Chloride Market
Bulk Chemicals
Global Concentrated Nitric Acid Market
Bulk Chemicals
Europe Quicklime Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Magnesium Citrate Market
Bulk Chemicals
Cyclohexane Market
Bulk Chemicals
Calcium Hypophosphite Market