
 Global Liquid Nitrogen Market | 2026-2036
Global Liquid Nitrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquid Nitrogen Market Foresight
Aftermarket service revenue for cryogenic infrastructure is tilting toward integrated lifecycle contracts. Linde plc leverages its global maintenance network to capture recurring revenue from pharmaceutical and electronics clients. Air Liquide S.A. anchors its position through on-site production agreements that lock in long-term offtake. Messer Group specializes in regional gas distribution, competing through localized delivery density rather than scale.
Liquid nitrogen is nitrogen gas cooled to approximately minus 196 degrees Celsius, existing as a colorless, odorless cryogenic fluid produced through fractional distillation of air or pressure-swing adsorption. It serves as an inert coolant for biological preservation, cryogenic grinding, shrink-fitting, and semiconductor manufacturing processes. Storage tanks dominate product-type revenue due to capital intensity and replacement cycles, while electronics manufacturing leads application growth driven by advanced node chip fabrication. Pharmaceutical manufacturers represent the fastest-expanding end-user segment as cell and gene therapy pipelines multiply.
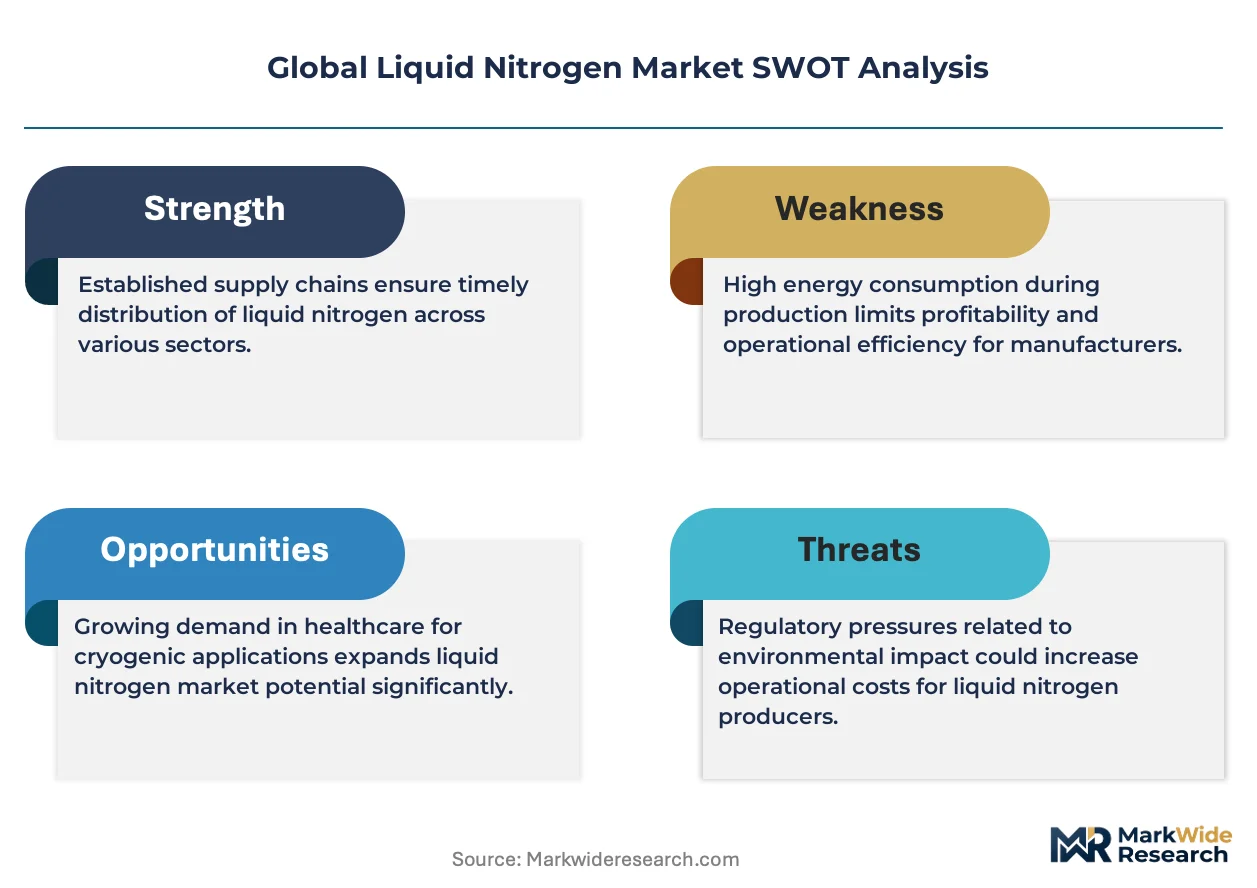
The U.S. FDA regulates cryogenic materials in pharmaceutical cold chains, while the EU F-Gas Regulation mandates leak detection and containment protocols for industrial gases. China's SAMR enforces GB standards for cryogenic vessel safety, shaping equipment certification requirements for market entry. Stakeholders must monitor how evolving biologics storage standards and carbon-intensity disclosure rules reshape procurement criteria for cryogenic supply chains.
Market Dynamics
The liquid nitrogen market is restructuring around cryogenic infrastructure lifecycle contracts, as pharmaceutical and electronics buyers trade capital ownership for operational certainty and guaranteed uptime.
Growth Catalysts
- EU F-Gas Regulation:Tightening containment standards for industrial gases are accelerating replacement of aging storage vessels and vapor recovery systems across European manufacturing facilities.
- Cell therapy manufacturing:Pharmaceutical producers are scaling cryogenic biobanking capacity to support multiplying gene therapy pipelines, creating sustained demand for ultra-low temperature logistics.
- Advanced node semiconductor fabrication:Chipmakers at 3nm and below are consuming record volumes of liquid nitrogen for wafer cooling and cleanroom inerting during EUV lithography.
Market Restraints
- Electricity cost volatility:Air separation units are electricity-intensive; regional power price spikes in Germany and Texas directly compress production margins.
- Geographic supply concentration:Merchant liquid nitrogen production clusters near coastal industrial zones, leaving inland biotech clusters in the US Midwest and Central China exposed to distribution constraints.
- Helium supply interdependence:Cryogenic cooling systems often require helium for pre-cooling; helium market tightness limits rapid capacity expansion for ultra-low temperature applications.
Strategic Opportunities
- India biopharma corridor:CDSCO regulatory harmonization with ICH standards is attracting contract manufacturing organizations that require cryogenic cold chains for biologics export.
- On-site generation adoption:Small-scale pressure-swing adsorption units are enabling food processors and electronics assemblers to bypass merchant delivery dependencies.
- Carbon intensity disclosure:EU CSRD reporting requirements are favoring suppliers with renewable-powered production, creating procurement preference for low-cryogenic carbon footprint nitrogen.
Industry Challenges
- Cryogenic systems engineering talent:The specialized skill set for vacuum-insulated vessel design and cryogenic fluid dynamics faces generational shortage as experienced engineers retire.
- GB standard vessel certification:China's SAMR approval timelines for imported cryogenic equipment extend 18-24 months, delaying market entry for non-domestic manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquid Nitrogen Market |
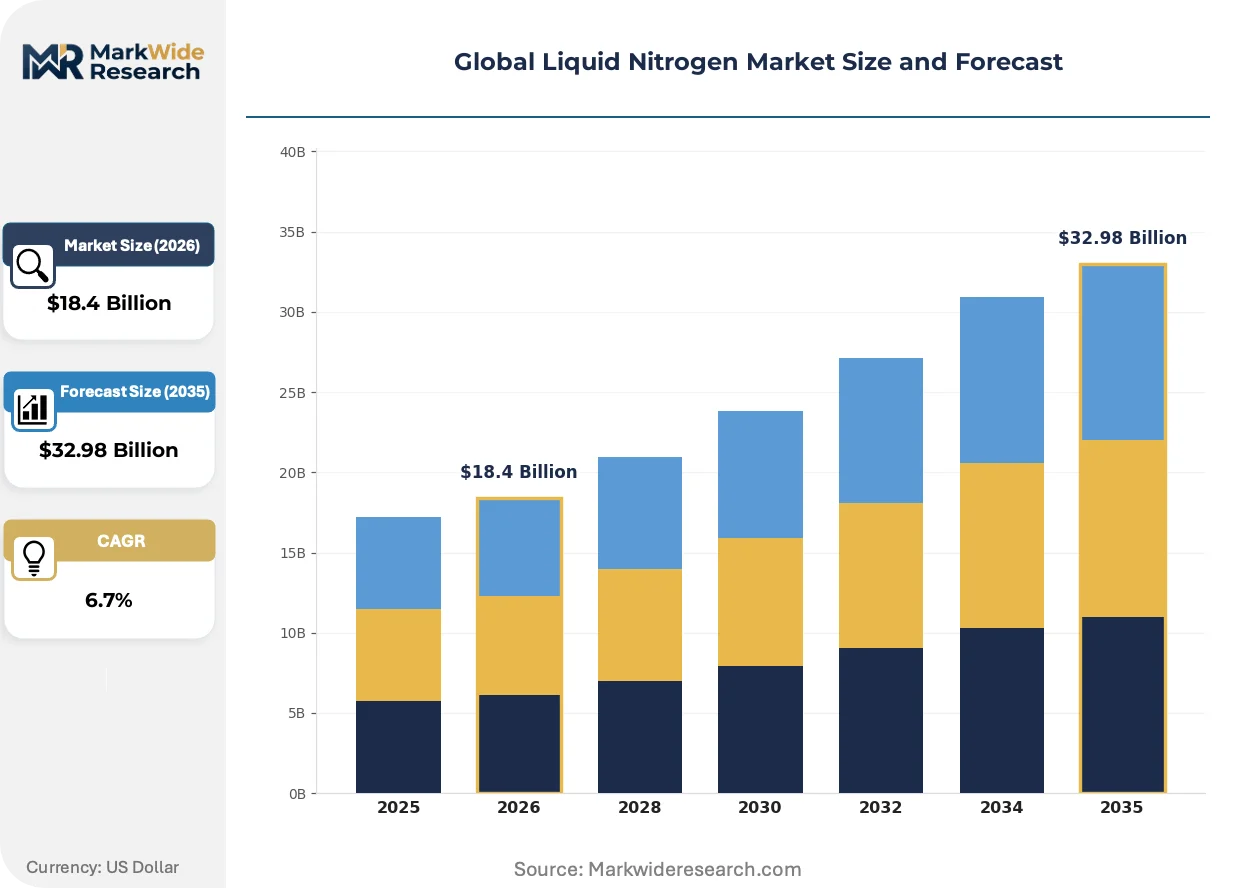
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $32.98 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vehicles, Storage Tanks, Delivery Systems, Filling Stations Application: Food Preservation, Cryosurgery, Metal Fabrication, Electronics Manufacturing End User: Pharmaceutical Manufacturers, Research Laboratories, Chemical Producers, Aerospace Companies Distribution Channel: Direct Sales, Distributors, Online Platforms, Third-Party Logistics |
| Companies Covered | Linde plc, Air Liquide S.A., Air Products and Chemicals, Inc., Taiyo Nippon Sanso Corporation, Messer Group, Gulf Cryo, SOL Group, Air Water Inc., Matheson Tri-Gas, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquid Nitrogen Market Shifts & Advancements
Digital monitoring systems and modular production architectures are compressing equipment replacement cycles while elevating service revenue as a structural component of supplier economics.
Magnetic levitation bearing technology in turboexpanders is rendering obsolete conventional oil-lubricated systems in air separation units. Industrial gas producers in Germany and Japan are retrofitting existing plants with frictionless compression to cut maintenance intervals from quarterly to annual. This upgrade path is rendering obsolete the aftermarket service contracts tied to mechanical bearing wear.
REACH authorization requirements for fluorinated greenhouse gases are forcing semiconductor fabs to audit cryogenic supply chains for indirect emissions. Equipment vendors must now certify vapor recovery rates above 99.5% to maintain qualification status. Korean and Taiwanese chipmakers are responding by specifying closed-loop nitrogen recycling in new fabrication facility designs.
Integrated service contracts that bundle equipment, maintenance, and cryogen supply are displacing transactional procurement in pharmaceutical manufacturing. Biologics producers in Massachusetts and Bavaria are signing ten-year agreements that transfer operational risk to gas suppliers. This consolidation of vendor relationships is most visible among cell therapy developers with limited in-house cryogenic engineering capabilities.
Global Liquid Nitrogen Market Segmentation
Liquid nitrogen procurement patterns diverge sharply across equipment types, industrial applications, and customer sophistication levels. Understanding these segment boundaries clarifies where capital intensity concentrates versus where operational flexibility commands premium pricing.
Product Type:
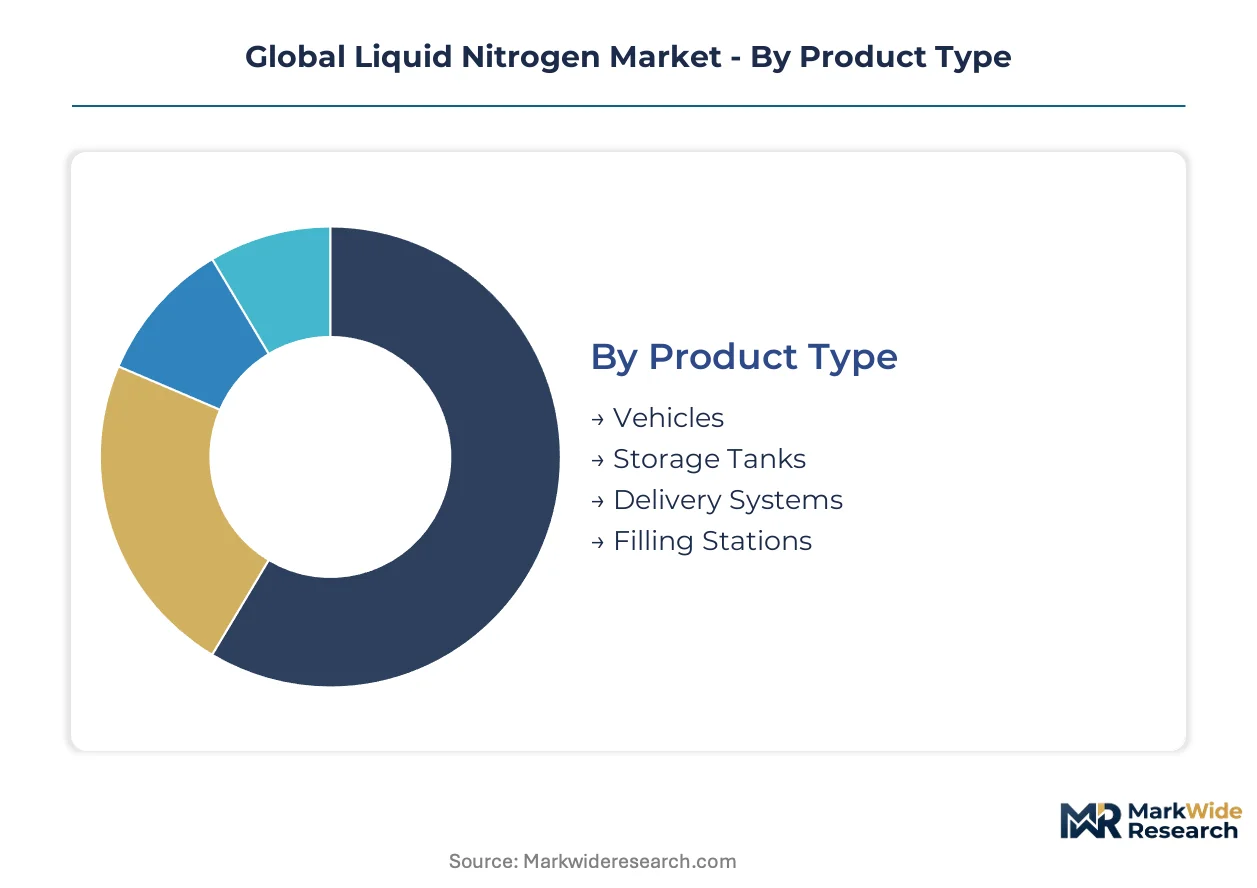
The use-case spectrum spans mobile delivery infrastructure through fixed-site generation assets, with capital deployment cycles ranging from three years for vehicle fleets to fifteen years for storage vessels.
- Storage Tanks:Vacuum-insulated double-wall vessels rated for minus 196 degrees Celsius duty, constructed from austenitic stainless steel with perlite powder insulation. Demand clusters at pharmaceutical manufacturing campuses in Massachusetts and Bavaria where biologics biobanking requires 10,000+ liter capacity vessels with 30-day hold times. Replacement cycles accelerate as EU F-Gas Regulation mandates leak detection retrofits on aging installations.
- Vehicles:Cryogenic road tankers and tube trailers engineered for minus 150 degrees Celsius transport with multi-layer insulation and pressure relief systems. Electronics manufacturing corridors in Taiwan and South Korea drive fleet expansion as advanced node chip fabs consume record delivery volumes. Fleet operators face margin compression from diesel price volatility and driver certification requirements for hazardous materials handling.
- Delivery Systems:Vacuum-jacketed piping networks and phase separators for point-of-use distribution.
- Filling Stations:Automated decant systems for cylinder and portable dewar replenishment.
The dominant share belongs to Storage Tanks, while Vehicles is closing the gap fastest.
Application:
Cost tier differentiation separates commodity cooling applications from precision processes where nitrogen purity specifications determine yield rates.
- Electronics Manufacturing:Ultra-high purity nitrogen for wafer cooling, chamber inerting, and EUV lithography purge gas in semiconductor fabrication. Taiwanese and Korean chipmakers at 3nm nodes specify 99.9999% purity with particle counts below 10 per cubic meter. Consumption intensity rises with each process shrink as thermal management becomes critical for yield optimization.
- Food Preservation:Cryogenic freezing and chilling for protein processing, bakery products, and prepared meals. Flash-freezing tunnels in Thailand and Vietnam shrimp processing plants replace mechanical freezing to preserve cellular structure. Demand concentrates where cold chain infrastructure gaps create spoilage risk in tropical climates.
- Cryosurgery:Dermatological and oncological tissue destruction using targeted liquid nitrogen spray or probe application.
- Metal Fabrication:Shrink-fitting of bearings and gears, cryogenic deburring, and thermal stress relief for welded assemblies.
Electronics Manufacturing commands the highest value per liter, while Food Preservation is expanding most quickly in Southeast Asian processing corridors.
End User:
Customer type determines contract structure, with pharmaceutical buyers favoring integrated service agreements and research laboratories maintaining transactional procurement.
- Pharmaceutical Manufacturers:Cell therapy developers and biologics producers requiring cryogenic cold chains from manufacturing through distribution. Massachusetts and North Carolina biotech clusters are scaling cryogenic biobanking capacity as gene therapy pipelines multiply. Ten-year lifecycle contracts with guaranteed uptime are displacing equipment ownership.
- Research Laboratories:Academic and government facilities using liquid nitrogen for sample preservation, NMR magnet cooling, and cryogenic research. Budget constraints favor small-volume cylinder delivery over on-site generation. Procurement remains transactional with limited vendor consolidation.
- Chemical Producers:Inert atmosphere requirements for oxygen-sensitive synthesis and cryogenic reaction control.
- Aerospace Companies:Rocket propulsion testing, wind tunnel cryogenics, and satellite component thermal cycling.
Pharmaceutical Manufacturers anchor revenue concentration, while Research Laboratories show steepest expansion trajectory in government-funded quantum computing initiatives.
Distribution Channel:
Supply concentration varies by geography, with direct sales dominant in industrial clusters and third-party logistics filling coverage gaps in fragmented markets.
- Direct Sales:Long-term contracts between industrial gas majors and high-volume consumers with predictable demand profiles. On-site air separation units and pipeline supply characterize relationships with semiconductor fabs and steel mills. Pricing ties to electricity indices with pass-through mechanisms for power cost volatility.
- Distributors:Regional gas specialists aggregating small and mid-volume demand across fragmented customer bases. Localized delivery density in Germany's Mittelstand manufacturing belt enables competitive positioning against integrated majors. Inventory pooling reduces working capital requirements for customers with intermittent consumption patterns.
- Third-Party Logistics:Cryogenic-capable transport and warehousing for biopharmaceutical cold chains.
- Online Platforms:E-procurement portals for standardized cylinder and dewar orders.
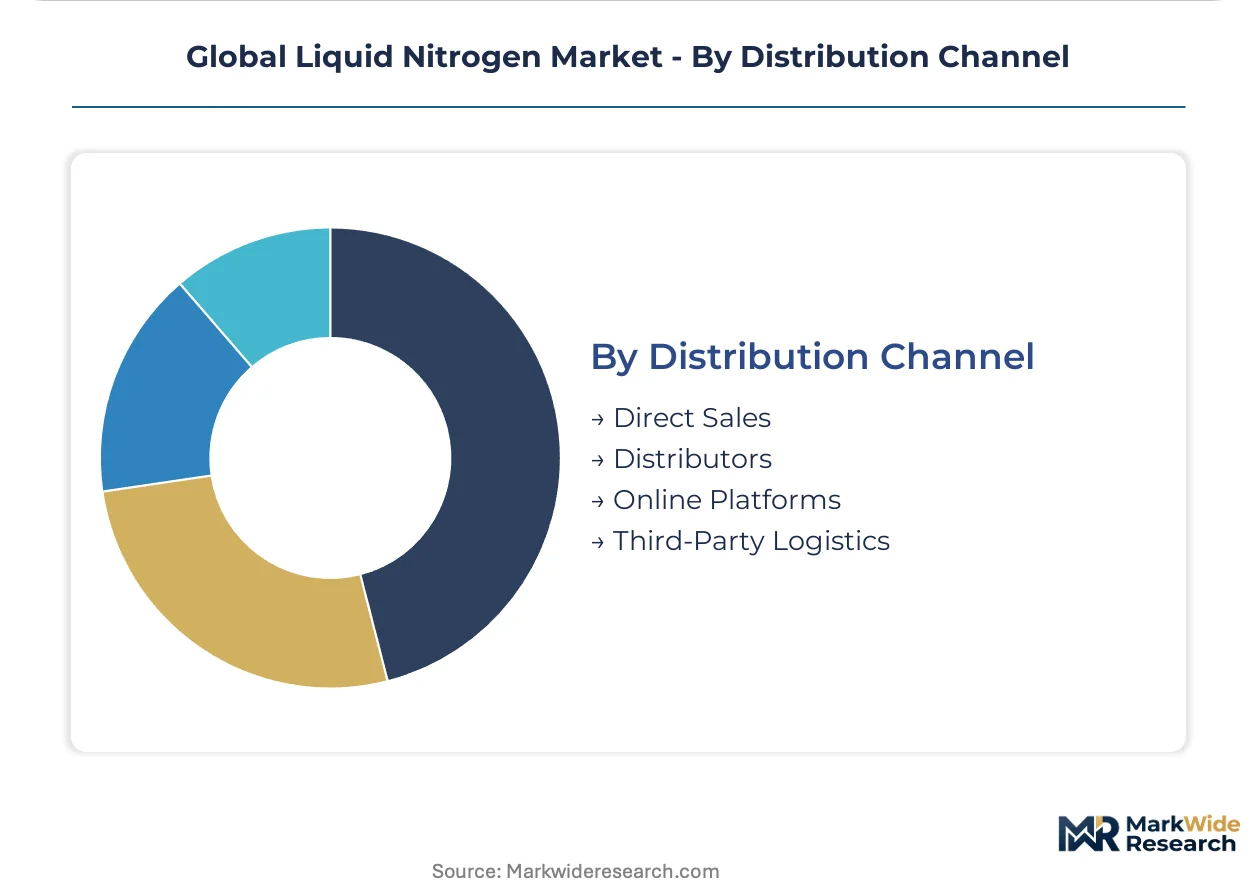
Direct Sales captures the majority of volume value, though Distributors are gaining share fastest in mid-market manufacturing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States and Germany prioritize pharmaceutical cold chains and biobanking infrastructure. China and South Korea concentrate demand in electronics manufacturing corridors. India represents an emerging biopharma frontier with nascent cryogenic logistics networks.
United States
Cell therapy developers in Massachusetts and North Carolina are scaling cryogenic biobanking capacity as gene therapy pipelines multiply. The FDA regulates cryogenic materials in pharmaceutical cold chains through stringent cold chain validation requirements. Greater Boston anchors demand concentration where ten-year lifecycle contracts with guaranteed uptime are displacing equipment ownership among biologics producers.
Germany
Advanced node semiconductor fabrication at 3nm and below consumes record volumes of liquid nitrogen for wafer cooling and cleanroom inerting. The EU F-Gas Regulation mandates leak detection and containment protocols for industrial gases, accelerating replacement of aging storage vessels. Bavaria's electronics manufacturing corridor drives fleet expansion as chip fabs consume record delivery volumes from regional merchant producers.
China
Electronics manufacturing leads application growth driven by advanced node chip fabrication in the Yangtze River Delta. SAMR enforces GB standards for cryogenic vessel safety, shaping equipment certification requirements for market entry with approval timelines extending 18-24 months for imported equipment. The Pearl River Delta concentrates demand where localized delivery density competes against integrated majors through inventory pooling.
South Korea
Semiconductor fabs at 3nm nodes specify 99.9999% purity nitrogen with particle counts below 10 per cubic meter for EUV lithography processes. Korean chipmakers are responding to REACH authorization requirements by specifying closed-loop nitrogen recycling in new fabrication facility designs. The Seoul Capital Area anchors production gravity where consumption intensity rises with each process shrink.
India
CDSCO regulatory harmonization with ICH standards is attracting contract manufacturing organizations that require cryogenic cold chains for biologics export. The country's national pharmaceutical regulator is aligning with international standards to facilitate export-oriented manufacturing. Maharashtra and Telangana are emerging as biopharma corridors where small-volume cylinder delivery dominates procurement among research laboratories with budget constraints.
Global Liquid Nitrogen Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around a consolidated top tier of integrated industrial gas majors and a fragmented mid-tier of regional specialists. Three archetypes dominate: global network operators with maintenance infrastructure, on-site production specialists with long-term offtake agreements, and localized distributors competing through delivery density. Competitive moves center on integrated lifecycle contracts and on-site generation adoption to bypass merchant delivery dependencies.
Within the integrated network tier, Linde plc and Air Liquide S.A. exemplify global operators with recurring revenue capture from pharmaceutical and electronics clients. Air Products and Chemicals, Inc. occupies a position among North American-based industrial gas suppliers. These three represent the scale-driven end of the market where backward integration into air separation units and pipeline supply characterizes relationships with high-volume consumers.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide S.A. |
| Air Products and Chemicals, Inc. |
| Taiyo Nippon Sanso Corporation |
| Messer Group |
| Gulf Cryo |
| SOL Group |
| Air Water Inc. |
| Matheson Tri-Gas, Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in European air separation units is compressing spot market premiums while tightening long-term offtake terms for pharmaceutical buyers. Utilization rates below 75% in Germany's industrial gas corridor have shifted bargaining power toward volume-commitment contracts with electricity pass-through clauses.
Pricing Analysis
Long-term offtake agreements dominate procurement for semiconductor fabs and biologics producers, locking in 5-10 year supply with electricity-indexed adjustments. Price differentiation rests on purity certification tiers and geographic delivery density, with 99.9999% EUV-grade nitrogen commanding substantial premiums over standard industrial grades. Cost compression in merchant delivery is intensifying because diesel volatility and driver certification requirements erode fleet operator margins. Research laboratories exhibit highest price sensitivity due to budget-constrained transactional procurement, while cell therapy developers accept premium pricing for guaranteed uptime.
Supply Chain Analysis
Contract manufacturing concentration among Taiwan Semiconductor Manufacturing, Samsung Foundry, and Intel's expanding Arizona footprint anchors cryogenic demand forecasting. Supply concentrates in the United States, China, and Germany, with merchant production clustering near coastal industrial zones. Raw material dependencies draw from electricity feedstock, austenitic stainless steel for vessel fabrication, and helium for pre-cooling systems. Single-source vulnerability in helium supply creates bottlenecks for ultra-low temperature capacity expansion. Distribution runs through direct pipeline supply for high-volume fabs, regional distributors for mid-market manufacturers, and third-party logistics for biopharmaceutical cold chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid nitrogen market is approaching a platform-economics inflection as integrated service contracts bundle equipment, maintenance, and cryogen supply into unified vendor relationships. Interoperability between digital monitoring systems and predictive maintenance platforms is consolidating buyer preference around full-stack suppliers.
For Market Incumbents: Build switching-cost moats through embedded IoT infrastructure that locks pharmaceutical clients into predictive maintenance ecosystems. Deepen backward integration into renewable-powered air separation to capture CSRD-driven procurement preference. Anchor capacity expansion in India's emerging biopharma corridors before CDSCO harmonization matures competitive intensity.
For New Entrants and Emerging Players: Establish a beachhead in small-scale pressure-swing adsorption systems for food processors seeking delivery independence. Target the US Midwest biotech cluster where inland distribution constraints create service gaps that localized generation can fill. Lead with modular on-site units that bypass merchant infrastructure entirely.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular cryogenic equipment manufacturing as standardized vessel designs reduce engineering overhead. Acquisition candidates with SAMR pre-certified GB standard equipment offer 18-24 month timeline advantages for China market entry. Monitor helium supply auction prices as the inflection signal for ultra-low temperature application viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Pharmaceutical manufacturers in Massachusetts are signing decade-long contracts transferring operational risk to gas suppliers. |
| Backward Integration | Electronics assemblers deploying pressure-swing adsorption units bypass merchant delivery dependencies entirely. |
| Green Manufacturing Transition | EU CSRD reporting requirements favor renewable-powered production with documented carbon intensity disclosure. |
| Joint Venture | Regional distributors in Germany's Mittelstand belt pool inventory to compete against integrated majors. |
| Capacity Expansion | Air separation unit upgrades with magnetic levitation bearings cut maintenance intervals from quarterly to annual. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cryogenic systems engineers, pharmaceutical procurement directors, semiconductor fab operations managers, and regional gas distribution executives; and secondary validation through customs trade data, SEC 10-K filings from industrial gas majors, EU F-Gas Regulation compliance filings, and SAMR equipment certification databases. Bottom-up triangulation across air separation unit capacity installations and top-down reconciliation against end-use consumption patterns anchored volume estimates.
Forecast inputs considered electricity price trajectories, biologics pipeline expansion rates, and semiconductor node migration timelines across the projection horizon. Segmentation modeling incorporated product type, application purity requirements, end-user contract sophistication, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of historical merchant delivery volumes against projected on-site generation adoption curves, with specific weighting for EU F-Gas vessel replacement cycles and India CDSCO regulatory harmonization pace.
Macroeconomic conditions sit as an overlay; deviation in industrial electricity tariffs, helium supply auction dynamics, or biotech venture funding levels would shift the trajectory. Quarterly review of SAMR certification approval timelines, EU vapor recovery compliance audit results, and advanced node semiconductor capex announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
North America Syngas Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
Xenon Gas Market
Industrial Gases
Industrial Hydrogen Peroxide Market
Industrial Gases
Transcritical CO2 Market
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
GCC Industrial Gases Market
Industrial Gases
Global Laboratory Gas Generators Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
Gas and Liquid Argon Market
Industrial Gases
Helium Market
Industrial Gases
Europe Specialty Gas Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Industrial Gas Regulator Market
Industrial Gases
Acetylene Gas Market