
 Marine Powerboat Battery Market | 2026-2036
Marine Powerboat Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Powerboat Battery Market Foresight
The EU Green Deal is expanding the addressable market for marine electrification by mandating emission reductions in inland and coastal waterways. Clarios leverages its automotive lithium-ion scale to supply modular battery packs for mid-size powerboat OEMs. Saft anchors its position through defense and commercial marine contracts requiring MIL-SPEC reliability standards. Trojan Battery specializes in deep-cycle lead-acid replacements for fishing boat operators transitioning gradually from conventional engines.
Marine powerboat batteries are electrochemical energy storage systems engineered for cyclic discharge tolerance, saltwater corrosion resistance, and vibration dampening in hull-mounted installations; they typically deliver 12V to 48V nominal outputs with cold cranking amp ratings exceeding 800A for dual-purpose starting and house-load applications. Lithium-ion chemistry dominates new-build yachts where energy density and weight reduction command premium positioning, while lead-acid retains volume share in fishing boats and rental fleets where capital constraints and simple retrofit paths sustain demand. Fully electric technology leads R&D investment among European builders, though hybrid systems occupy the practical middle ground for extended-range cruisers.
The EPA enforces marine engine emission standards under the Clean Air Act that indirectly accelerate battery-electric adoption in US navigable waters. ECHA's REACH restrictions on lead and cadmium content are reshaping cell chemistry decisions for OEMs serving European harbors. The EU F-Gas Regulation adds compliance layers to thermal management systems integrated with high-capacity battery banks. Stakeholders must monitor how IMO's evolving carbon intensity indicators for pleasure craft redirect fleet renewal schedules and retrofit investment cycles.
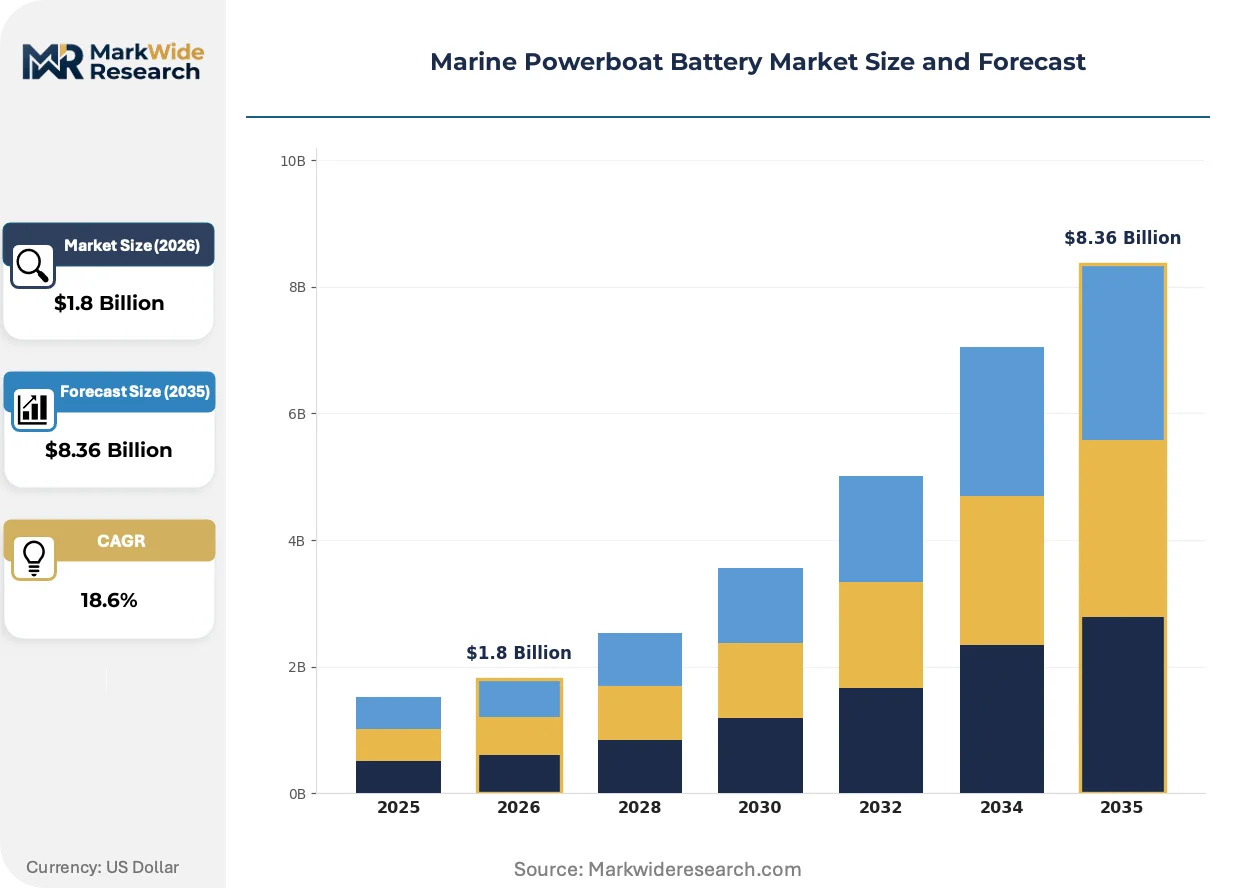
Market Dynamics
Recreational boating fleets are converting to electric propulsion systems at accelerating rates, forcing battery chemistry upgrades across European shipyards and compressing replacement cycles for legacy lead-acid installations.
Growth Catalysts
- EU Green Deal maritime decarbonization mandates:The framework forces emission reductions in inland and coastal waterways, expanding the addressable market for marine electrification and accelerating fleet renewal schedules among charter operators.
- Lithium-ion energy density improvements:New-build yacht builders are specifying high-density cells for weight reduction and range extension, pulling demand away from conventional deep-cycle alternatives in premium segments.
- Coastal manufacturing cluster concentration:Norway, Germany, and the Netherlands are anchoring battery pack assembly capacity, reducing logistics costs for OEMs serving Mediterranean and Baltic cruising grounds.
Market Restraints
- Lithium carbonate price volatility:Raw material input costs for cathode production create margin compression for pack assemblers unable to pass through increases to price-sensitive fishing boat operators.
- Lead-acid substitution lock-in:Rental fleet managers retain capital-constrained purchasing patterns, sustaining volume share for conventional chemistry despite total-cost-of-operating advantages from lithium alternatives.
- ECHA REACH heavy metal restrictions:Compliance layers for lead and cadmium content are reshaping cell chemistry decisions, adding certification timeline friction for OEMs serving European harbors.
Strategic Opportunities
- Hybrid system penetration in extended-range cruisers:Builders are specifying parallel electric architectures as a practical middle ground, creating demand for modular battery banks with rapid-swap capability during marina stops.
- IMO carbon intensity indicators for pleasure craft:Evolving maritime environmental standards are redirecting retrofit investment cycles toward electrification among aging fleet owners in Scandinavian waters.
- Direct-to-builder distribution channels:Pack manufacturers are bypassing traditional marine aftermarket distributors to secure long-term supply agreements with production boat builders in the Netherlands.
Industry Challenges
- Marine electrical engineering skill scarcity:Boatyards lack technicians trained in high-voltage DC system integration, slowing installation throughput and extending delivery timelines for electric repower projects.
- MIL-SPEC reliability certification complexity:Defense and commercial marine contracts require extended validation protocols, stretching R&D expenditure timelines before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Powerboat Battery Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Lead-Acid, Nickel-Cadmium, Gel Cell Application: Fishing Boats, Recreation Boats, Sailboats, Yachts End User: Private Owners, Commercial Operators, Rental Services, Government Agencies Technology: Hybrid Systems, Fully Electric, Fuel Cell, Conventional |
| Companies Covered | Clarios, Exide Technologies, Saft, Trojan Battery, GS Yuasa International Ltd, Victron Energy B.V., Power Sonic Corporation, Fullriver Battery, East Penn Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Powerboat Battery Market Shifts & Advancements
Active thermal management integration with high-capacity battery banks is reshaping system architecture decisions, as builders confront the EU F-Gas Regulation's compliance requirements alongside performance demands from electric drivetrains.
Solid-state lithium-metal chemistry is overtaking conventional liquid-electrolyte designs in next-generation marine applications. Premium yacht builders are specifying solid-state prototypes for prototype hulls entering sea trials this year. This transition is compressing the competitive window for incumbent pack assemblers dependent on cylindrical cell form factors.
The EPA's Clean Air Act marine engine emission standards are indirectly accelerating battery-electric adoption in US navigable waters. Inboard engine repower restrictions in sensitive water bodies are forcing charter operators toward zero-emission alternatives. Coastal states with submerged vegetation protection zones are seeing the fastest permit approvals for electric conversion projects.
Buyer preference is rotating toward integrated energy storage systems that combine propulsion, house load, and hotel power in unified architectures. Traditional separation of starting and deep-cycle banks is dissolving among mid-size cruiser buyers. This convergence is most visible in Pacific Northwest boating communities where extended anchoring demands unified power management.
Marine Powerboat Battery Market Segmentation
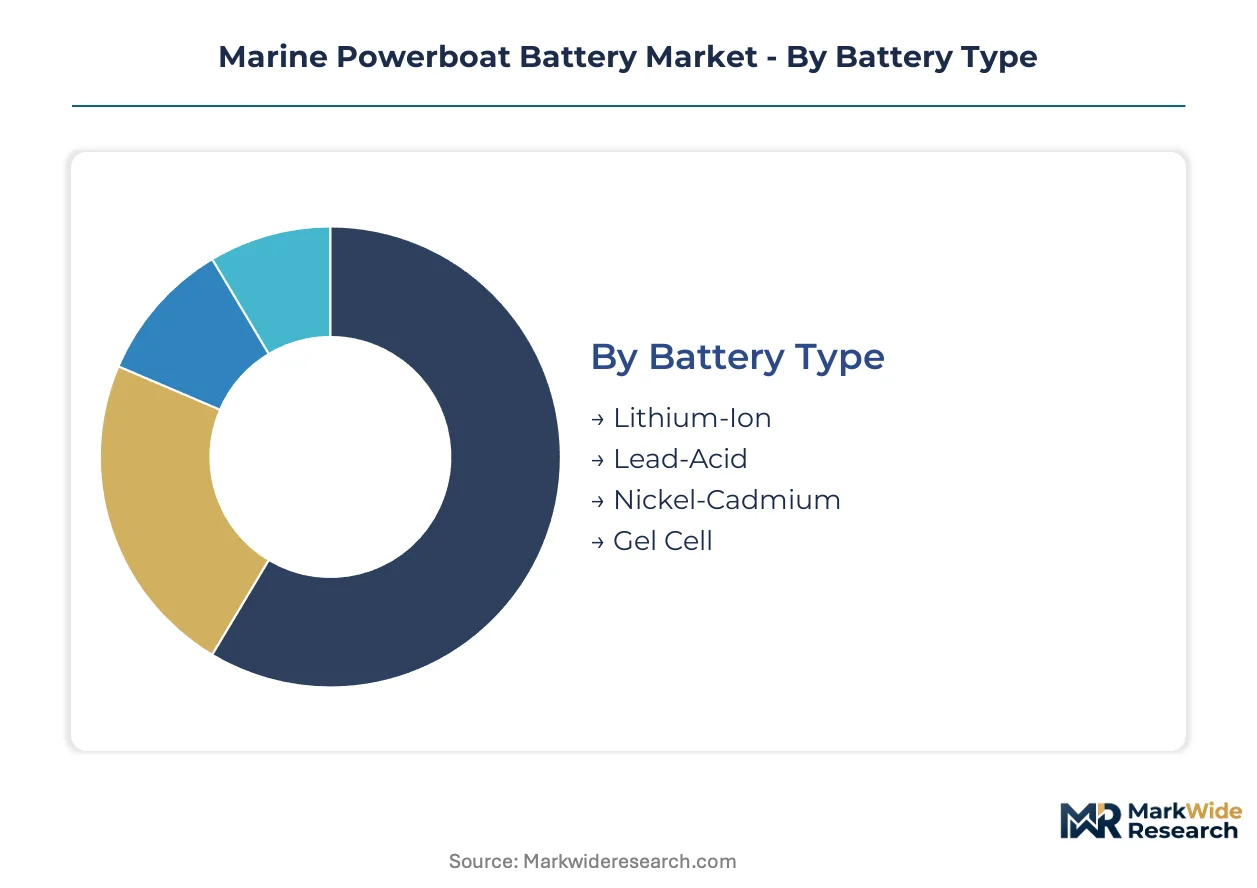
Marine powerboat battery segmentation reveals how chemistry choices, vessel duty cycles, and propulsion architectures create distinct demand clusters. Understanding these divisions exposes where pack assemblers must configure thermal management, cycle tolerance, and form factors to capture value.
Battery Type:
Electrochemical composition dictates energy density, cycle life, and saltwater corrosion resistance across hull-mounted installations.
- Lithium-Ion:NMC and LFP cathode architectures deliver 150-200 Wh/kg with 3,000+ deep discharge cycles. Demand concentrates in Norwegian yacht builders specifying weight reduction for extended Baltic cruising range under EU Green Deal emission mandates.
- Lead-Acid:Flooded and AGM variants retain 800-1,000 cold cranking amps at one-third the lithium cost. Mediterranean rental fleets in Barcelona and Marseille sustain volume share through capital-constrained replacement schedules.
- Nickel-Cadmium:Sintered plate construction tolerates extreme temperature swings in defense patrol craft. NATO member navies in German and Dutch shipyards specify these for MIL-SPEC reliability in North Sea conditions.
- Gel Cell:Thixotropic electrolyte eliminates spillage in heel angles exceeding 45 degrees. North Sea sailing charters in Hamburg and Copenhagen specify gel for house-load stability in rough conditions.
Lithium-Ion leads on scale; Lead-Acid leads on momentum through rental fleet lock-in.
Application:
Vessel operating profiles determine discharge depth, vibration exposure, and space constraints for battery integration.
- Fishing Boats:Trolling motor duty demands 12V-24V deep-cycle tolerance with 6-8 hour continuous draw. Baltic Sea commercial operators in Kiel and Rostock prioritize lead-acid retrofit compatibility for diesel-electric hybrid conversions.
- Recreation Boats:Dual-purpose starting and house-load requirements favor 800A+ cold cranking ratings with reserve capacity for overnight anchoring. Dutch inland waterway cruisers in Amsterdam and Utrecht drive lithium specification for weight-sensitive planing hulls.
- Sailboats:Heeling tolerance and low center-of-gravity placement constrain form factor selection. Scandinavian bluewater cruisers in Oslo and Gothenburg specify slim lithium banks for keel-adjacent mounting.
- Yachts:Integrated hotel power and propulsion architectures demand 48V-800V high-voltage systems with active liquid cooling. German superyacht builders in Bremen and Hamburg specify modular racks with rapid-swap marina capability.
Recreation Boats anchor volume; Yachts command premium positioning through integrated energy architecture.
End User:
Procurement authority and total-cost-of-ownership horizons segment purchasing behavior across installation channels.
- Private Owners:Individual buyers with 7-15 year vessel holding periods evaluate lifecycle cost against upfront capital. Norwegian leisure boaters in Bergen and Stavanger lead lithium adoption for second-home cruisers.
- Commercial Operators:Charter fleets with 2,000+ annual engine hours prioritize reliability and rapid turnaround. German Baltic Sea tour operators in Lübeck specify hybrid systems for emission-compliant harbor access.
- Rental Services:High-turnover, price-sensitive procurement sustains lead-acid volume despite operating cost penalties. Dutch canal boat rentals in Leiden and Delft defer electrification due to 3-year fleet rotation cycles.
- Government Agencies:Defense and coast guard contracts impose MIL-SPEC validation and domestic content requirements. Dutch and German naval procurement offices in Den Helder and Kiel anchor nickel-cadmium demand.
Commercial Operators expand most quickly on regulatory pressure; Private Owners retain decision autonomy.
Technology:
Propulsion architecture selection determines battery duty cycle, peak discharge rate, and thermal management complexity.
- Hybrid Systems:Parallel electric architectures combine diesel range extension with zero-emission harbor maneuvering. Extended-range cruisers in the Netherlands specify 20-50 kWh modular banks for 4-6 hour electric-only legs.
- Fully Electric:Pure battery-electric propulsion eliminates combustion entirely, demanding 100-400 kWh capacity with shore-fast charging infrastructure. Norwegian fjord tour operators in Flåm and Geiranger deploy these under zero-emission waterway mandates.
- Fuel Cell:Hydrogen proton-exchange membrane systems extend range beyond battery limits for ocean passages. German research vessels in Bremerhaven trial methanol-reformer fuel cells for Atlantic crossing capability.
- Conventional:Combustion-only propulsion with separate starting and house batteries retains share in price-sensitive segments. Polish and Baltic state fishing cooperatives defer electrification due to harbor infrastructure gaps.
Fully Electric climbs the fastest on EU Green Deal enforcement; Hybrid Systems bridge infrastructure timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine battery manufacturing traces its industrial lineage to Scandinavian shipbuilding traditions, where Norwegian and Swedish yards pioneered electric propulsion for fjord tourism vessels during the early 2000s. This heritage established technical standards and supply chain relationships that now propagate across European coastal clusters and into North American markets.
Norway
Zero-emission waterway mandates in the Sognefjord and Geirangerfjord UNESCO zones compel tour operators to deploy fully electric propulsion systems. The Norwegian Maritime Authority enforces strict harbor emission limits that accelerate fleet renewal timelines. Bergen and Stavanger anchor battery pack assembly capacity, with local suppliers integrating thermal management systems for high-latitude operating conditions.
Germany
Extended-range cruiser builders in Bremen and Hamburg specify hybrid architectures combining diesel range with electric harbor maneuvering. The EU Green Deal's maritime decarbonization framework forces emission reductions in Baltic and North Sea coastal zones. German shipyards concentrate MIL-SPEC validation expertise, serving defense patrol craft contracts requiring NATO-standard reliability protocols.
Netherlands
Inland waterway charter operators in Amsterdam and Utrecht drive lithium-ion specification for weight-sensitive planing hulls navigating shallow canal systems. Rotterdam's port authority mandates shore-power connectivity standards that accelerate onboard battery bank integration. The Randstad manufacturing cluster hosts modular pack assemblers supplying Mediterranean and Baltic cruising markets through direct-to-builder distribution channels.
United States
EPA Clean Air Act marine engine emission standards indirectly accelerate battery-electric adoption in Chesapeake Bay and Puget Sound sensitive water bodies. Coastal states with submerged vegetation protection zones expedite permit approvals for electric conversion projects. Pacific Northwest boating communities in Seattle and Portland anchor demand for unified energy storage architectures combining propulsion and house-load systems.
France
Mediterranean rental fleets in Marseille and Barcelona sustain lead-acid volume through capital-constrained replacement schedules despite operating cost penalties from lithium alternatives. The French environmental regulator enforces harbor air quality standards that redirect charter operator investment toward hybrid configurations. Provence-Alpes-Côte d'Azur marinas install shore-fast charging infrastructure supporting electric day-cruiser operations.
Marine Powerboat Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across chemistry specialization and certification tier. The vendor base stratifies between automotive-scale lithium suppliers, defense-contract battery specialists, and regional deep-cycle manufacturers serving price-sensitive fishing and rental segments. Three archetypes dominate: automotive crossover players leveraging passenger EV cell scale, MIL-SPEC validators capturing defense and commercial marine contracts, and legacy lead-acid specialists defending retrofit compatibility. Consolidation pressure concentrates in lithium-ion pack assembly, while lead-acid retains fragmentation through distributed aftermarket channels. Capacity expansion and direct-to-builder distribution partnerships represent the dominant competitive moves reshaping channel control.
Within the automotive-scale tier, Clarios exemplifies crossover players redirecting passenger EV lithium-ion production toward modular marine packs. Saft occupies a position among MIL-SPEC validators, anchoring defense and commercial marine contract flows through extended reliability certification protocols. Trojan Battery represents legacy deep-cycle specialists, sustaining volume share in fishing boat and rental fleet segments where gradual transition paths from conventional engines preserve demand for lead-acid chemistry.
| Leading Market Players |
|---|
| Clarios |
| Exide Technologies |
| Saft |
| Trojan Battery |
| GS Yuasa International Ltd |
| Victron Energy B.V. |
| Power Sonic Corporation |
| Fullriver Battery |
| East Penn Manufacturing Company |
| Others |
Supply & Pricing Matrix
Lithium carbonate feedstock flows from Chilean and Australian extraction through Chinese cathode processing before reaching Norwegian and German pack assemblers, with each transfer point layering margin capture that separates premium yacht-grade cells from economy fishing-boat alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs marine battery transactions, with differentiation anchored in MIL-SPEC certification grade and active thermal management inclusion. Premium yacht builders absorb 40-60% markups for solid-state prototypes and liquid-cooled architectures, while Baltic fishing cooperatives drive price compression in lead-acid replacement cycles. Price erosion runs through standard-tier lithium-ion packs as Chinese cell capacity floods European assembly channels.
Supply Chain Analysis
Marine electrical engineering skill scarcity in Bergen, Hamburg, and Rotterdam shipyards constrains pack installation throughput and extends delivery timelines for high-voltage system integration. Cell manufacturing draws from South Korean and Chinese cathode suppliers, with Norwegian and Dutch final assembly feeding Mediterranean and Baltic cruising markets. Single-source vulnerability concentrates in lithium carbonate offtake agreements, while distribution runs through direct-to-builder partnerships bypassing traditional marine aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine powerboat battery margins expand through solid-state chemistry adoption and thermal management bundling, with premium-tier shifts offsetting raw material volatility in cathode supply chains.
For Market Incumbents: To counter solid-state prototype disruption from automotive crossover players, defend position through MIL-SPEC certification depth and captive thermal management system production in Norwegian coastal clusters. Prioritize long-term supply agreements with Dutch and German production boat builders to lock channel control against modular pack assemblers. For New Entrants and Emerging Players: Launch via direct-to-builder distribution partnerships targeting Polish and Baltic state fishing cooperatives deferred on electrification by harbor infrastructure gaps. White-space concentrates in hybrid system retrofits for extended-range cruisers, where parallel electric architectures demand rapid-swap modular banks without incumbent lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where lithium-ion pack assemblers lack backward integration into cathode supply and thermal management subsystems. Acquisition targets center on mid-cap specialists with EU F-Gas Regulation compliance capabilities and German defense contract relationships. Watch for IMO carbon intensity indicator enforcement as fleet renewal inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Chemistry Transition | Premium yacht builders in Bremen specify lithium-metal prototypes compressing competitive windows for liquid-electrolyte incumbents. |
| Direct-to-Builder Distribution | Randstad cluster assemblers bypass marine aftermarket distributors to secure long-term supply agreements with Dutch production hull manufacturers. |
| Thermal Management Integration | Active liquid cooling bundling addresses EU F-Gas Regulation compliance while commanding 25-35% system-level price premiums. |
| MIL-SPEC Certification Investment | German and Dutch naval procurement offices anchor nickel-cadmium demand through NATO-standard reliability validation protocols. |
| Hybrid System Modularization | Netherlands extended-range cruiser builders specify 20-50 kWh rapid-swap banks bridging infrastructure timelines across Baltic harbors. |
Research Methodology
Coverage spans Norway, Germany, the Netherlands, and the United States, with primary inputs from each region's coastal manufacturing clusters and regulatory enforcement zones. Primary interviews engaged marine battery pack engineers, shipyard procurement directors, charter fleet operations managers, and naval procurement officers across 15 stakeholder conversations. Secondary validation drew from EPA marine engine emission filings, EU Green Deal implementation directives, ECHA REACH substance restriction databases, and IMO pleasure craft carbon intensity consultation documents. Bottom-up vessel fleet electrification modeling triangulated against top-down chemistry demand projections.
Rate-of-change decomposition separated volume expansion from value migration across the projection horizon, with segmentation modeling spanning battery chemistry tier, vessel application duty cycle, propulsion architecture technology, and end-user procurement authority. CAGRs derived from fitted adoption curves weighted by EU Green Deal enforcement timelines and harbor infrastructure buildout schedules. Industry-specific inputs included lithium carbonate spot price volatility bands and MIL-SPEC validation protocol duration estimates.
Several conditions sit outside the modeled scope, including unilateral tariff impositions on Chinese cell imports, breakthrough solid-state manufacturing cost reductions, and IMO regulatory scope expansion beyond current pleasure craft consultations. Forecasts reflect assumptions around EU member state enforcement uniformity and shore-fast charging infrastructure deployment cadence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Simulator Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
SLI Battery Market
Batteries
Aluminum Wire Battery Market
Batteries
Micro Mobility Battery PACK Market
Batteries
Power Tool Batteries Market
Batteries
Battery Voltage Recorder Market
Batteries
HIT Battery Market
Batteries
All-In-One Solar Storage Battery Market
Batteries
3D-Printed Battery Market
Batteries
Tubular Batteries Market
Batteries
48 Volt Battery System Market
Batteries
Low Temperature Battery Market
Batteries
Primary Lithium Battery for Industrial Market
Batteries
China Rechargeable Battery Market
Batteries
Global Lithium Titanate (LTO) Batteries Market