
 Battery-Powered Riveter Market | 2026-2036
Battery-Powered Riveter Market Size, Share, and Industry Trends Forecast 2026-2036
Battery-Powered Riveter Market Insights
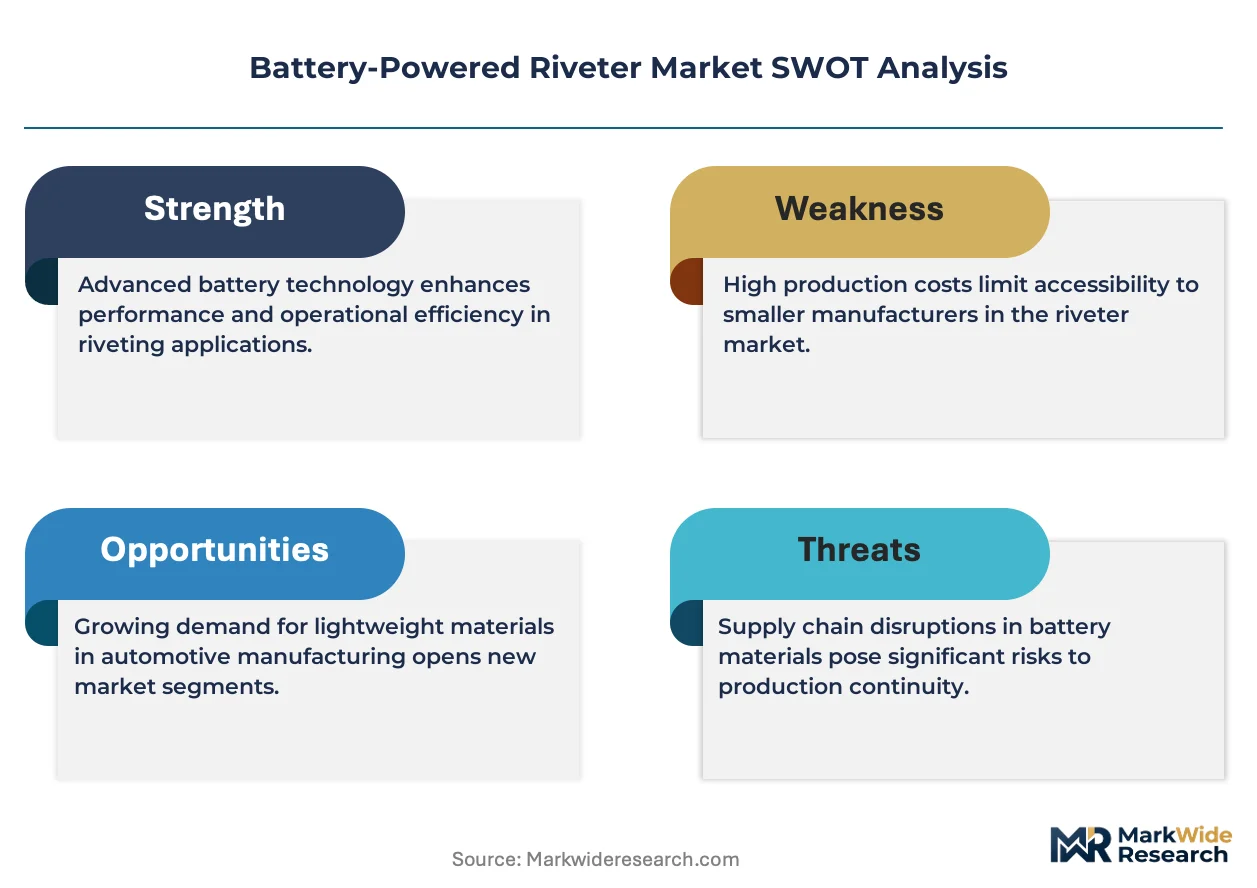
A capital-intensity divergence between full-line power tool conglomerates and specialized fastening equipment makers is redrawing competitive boundaries in battery-powered riveting. Stanley Black & Decker leverages its cordless platform ecosystem to cross-sell riveters through existing dealer networks. GESIPA anchors its position with application-specific blind rivet systems designed for mobility-constrained assembly environments. Böllhoff competes through regional service density, embedding technicians at customer plants for tool calibration and maintenance support.
A battery-powered riveter is a cordless fastening tool that uses rechargeable lithium-ion cells to drive mechanical or hydraulic force for installing blind, solid, or structural rivets without compressed air or electrical tethering. These tools typically deliver pull forces from 8 kN to 25 kN and incorporate brushless motors to extend duty cycles in high-volume manufacturing settings. Handheld riveters dominate volume sales across general assembly floors where operator mobility determines throughput. Automated riveting systems command premium positioning in aerospace fuselage programs where repeatability tolerances fall below 0.1 mm. Electromechanical technology is displacing legacy pneumatic alternatives in European automotive plants seeking to eliminate compressor infrastructure and leak-related energy losses.
The Occupational Safety and Health Administration sets workplace exposure limits that push manufacturers toward vibration-dampened battery tools, while the EPA's hazardous waste rules for spent lithium-ion packs shape end-of-life collection logistics. ISO 5393 torque-controlled fastening standards influence product design specifications for tools sold into regulated industrial channels. Stakeholders must monitor cell chemistry substitution timelines as solid-state prototypes approach commercial viability and threaten incumbent cylindrical cell supply agreements.
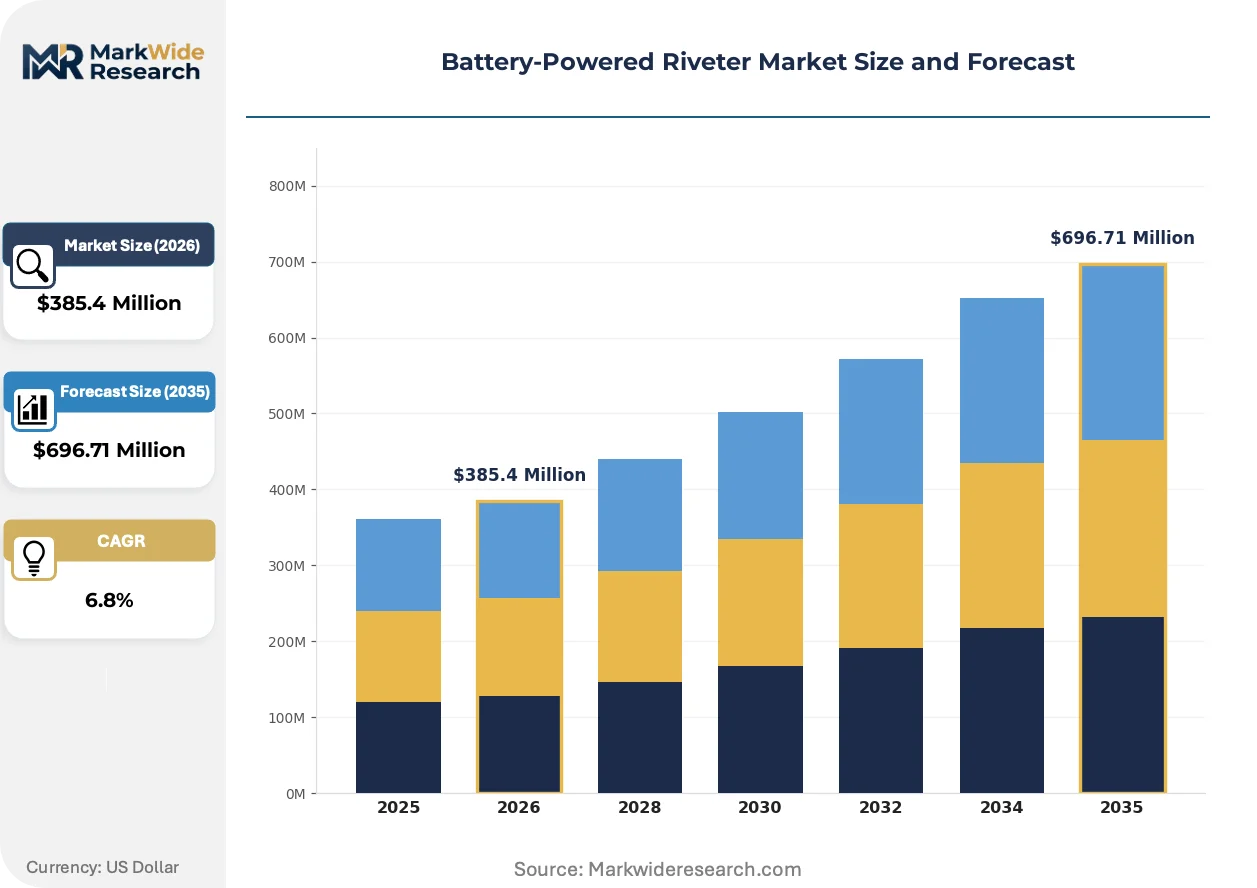
Market Dynamics
Brushless motor integration with high-density lithium-ion cells is compressing tool form factors while extending duty cycles, forcing incumbent suppliers to redesign thermal management architectures or cede share to electrification specialists.
Growth Catalysts
- OSHA vibration exposure limits:Manufacturers are retrofitting assembly stations with battery-powered alternatives to comply with workplace safety mandates and reduce operator injury claims.
- Aerospace fuselage automation:Cordless riveting systems eliminate tethering hazards in confined wing box assemblies where pneumatic hose routing proves impractical.
- Lithium-ion energy density gains:Cell chemistry improvements extend single-charge cycle counts, reducing downtime in high-volume automotive fastening operations.
Market Restraints
- Cylindrical cell supply concentration:Tool makers face dependency on East Asian battery suppliers, exposing production schedules to geopolitical trade friction and export licensing delays.
- Capital intensity of solid-state transition:Prototyping next-generation cell architectures requires R&D commitments that strain mid-tier fastening equipment specialists.
- Pneumatic infrastructure sunk costs:European automotive plants with depreciated compressor networks delay full electrification despite operating cost advantages.
Strategic Opportunities
- India PLI scheme for advanced manufacturing:Domestic content incentives attract battery tool assembly operations serving Southeast Asian aerospace subcontractors.
- Wind turbine blade assembly:Offshore nacelle construction demands portable fastening solutions where grid power remains unavailable.
- EU Green Deal industrial decarbonization:Compressed air elimination aligns with Scope 2 emissions reduction targets, creating preference for battery-operated alternatives in German automotive plants.
Industry Challenges
- Brushless motor calibration expertise:Field service technician shortages delay warranty repairs and erode customer uptime guarantees.
- ISO 5393 torque certification timelines:Third-party validation bottlenecks extend product launch cycles for tools targeting regulated industrial channels.
- Legacy MES integration:Shop floor data connectivity requirements force retrofitting of cordless tools with communication modules that pneumatic predecessors lacked.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery-Powered Riveter Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Riveters, Pneumatic Riveters, Automated Riveting Systems, Specialty Riveters End User: Automotive Manufacturers, Aerospace Industries, Construction Companies, General Contractors Technology: Electromechanical, Hydraulic, Pneumatic, Manual Application: Assembly, Repair, Manufacturing, Maintenance |
| Companies Covered | Stanley Black & Decker, Milwaukee, DEWALT, Makita, GESIPA, Bosch, Atlas Copco, Cherry Aerospace, Böllhoff, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery-Powered Riveter Market Trends and Innovations
Electrification architectures are converging with connectivity layers to transform standalone fastening tools into data-generating production assets, compressing the gap between operational technology and enterprise software.
Integrated force-feedback sensors embedded in riveter housings are miniaturizing to sub-millimeter precision without expanding tool weight. Aerospace tier-one suppliers in Toulouse and Hamburg are piloting these units for fuselage panel alignment. The technology is miniaturizing quality control steps previously requiring separate metrology stations, collapsing inspection timelines into the fastening operation itself.
REACH substance restrictions on cobalt compounds are compelling cell manufacturers to accelerate nickel-manganese-alternative cathode formulations. Tool OEMs must recertify thermal runaway protocols before these chemistries enter commercial riveter battery packs. European automotive final assembly lines face the tightest compliance windows, with KBA type-approval requirements governing tool deployment in German passenger vehicle plants.
Leasing structures are displacing capital purchase models among mid-volume contract manufacturers. Distributor networks in Stuttgart and Detroit now bundle tool maintenance, battery swap logistics, and firmware updates into per-rivet pricing. This shift is most pronounced among German Mittelstand metal fabricators seeking to preserve balance sheet flexibility amid order volatility.
Battery-Powered Riveter Market Segmentation
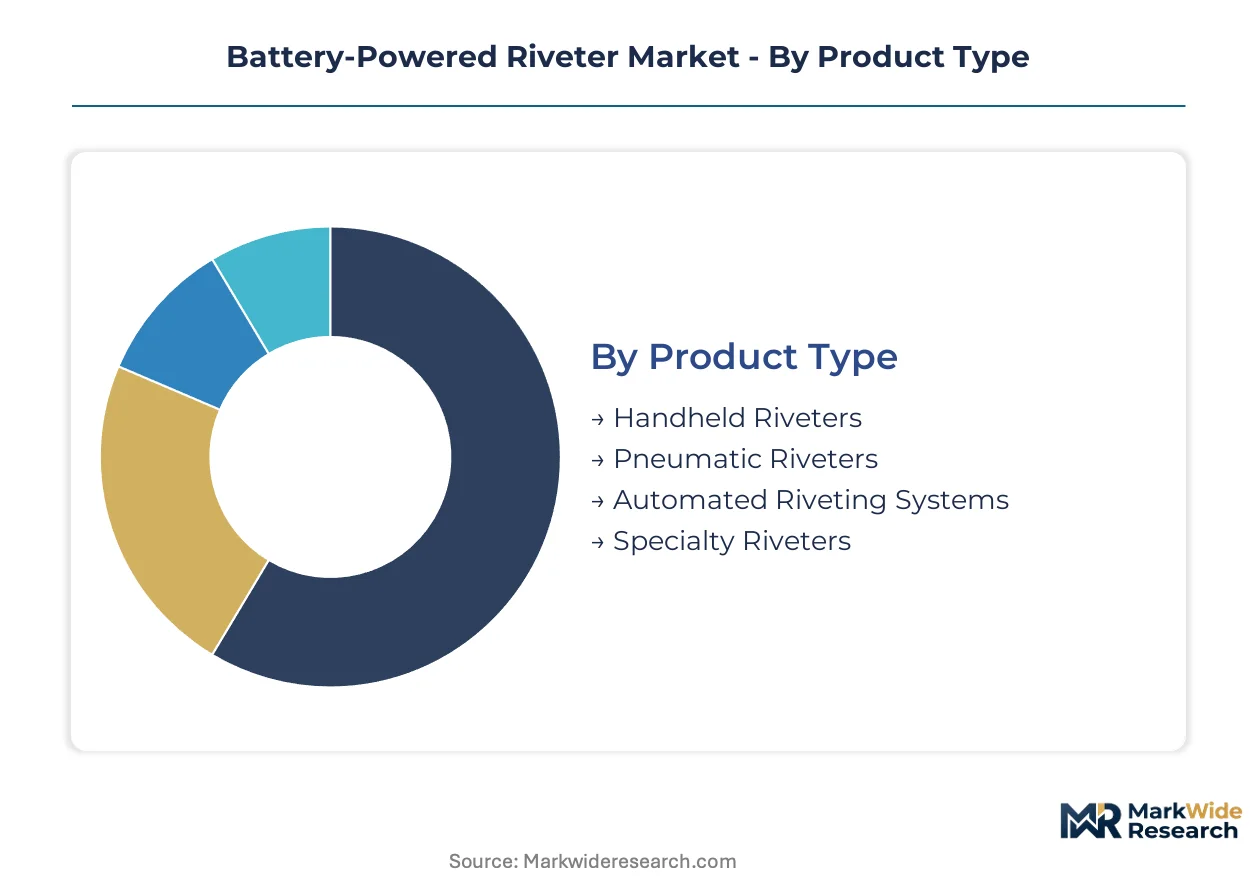
Battery-powered riveter segmentation reveals how cordless electrification is fragmenting traditional tool categories. Substitution pressure from brushless motor platforms is forcing suppliers to defend legacy pneumatic positions while capturing premium automation demand.
Product Type:
Pneumatic-to-battery substitution pressure concentrates most intensely in handheld formats, where mobility requirements clash hardest with compressor infrastructure dependency.
- Handheld Riveters:These cordless units integrate brushless motors with 18V-36V lithium-ion packs to deliver 8-25 kN pull force in sub-2 kg housings. Demand concentrates in German automotive final assembly stations retrofitting for OSHA vibration compliance and EU Green Deal decarbonization targets.
- Automated Riveting Systems:Gantry-mounted battery riveting cells serve aerospace fuselage programs in Toulouse and Hamburg where tethering hazards in confined wing box assemblies render pneumatic routing impractical. Repeatability tolerances below 0.1 mm justify premium positioning.
- Pneumatic Riveters:Legacy compressed-air tools retain installed base in European plants with depreciated compressor networks delaying full electrification despite energy losses.
- Specialty Riveters:Custom configurations address wind turbine blade assembly and offshore nacelle construction where grid power remains unavailable.
Handheld Riveters anchors the volume base while Automated Riveting Systems gains share at the steepest rate.
End User:
Cost tier stratification separates capital-rich aerospace programs from price-sensitive general fabrication, with automotive OEMs occupying the contested middle ground.
- Automotive Manufacturers:German OEMs at Wolfsburg and Stuttgart plants drive standardization of battery riveting platforms across final assembly, powertrain, and body-in-white operations.
- Aerospace Industries:Tier-one suppliers in Hamburg and Toulouse pilot force-feedback sensor integration for fuselage panel alignment, collapsing inspection timelines into fastening operations.
- Construction Companies:Infrastructure project contractors in India leverage PLI scheme incentives for domestic tool assembly serving Southeast Asian markets.
- General Contractors:Mid-volume metal fabricators in Stuttgart and Detroit increasingly prefer leasing bundles covering maintenance, battery swaps, and per-rivet pricing.
Automotive Manufacturers provides the revenue foundation while Aerospace Industries expands most quickly on automation premiums.
Technology:
Application maturity divides established electromechanical architectures from hydraulic force multiplication and residual pneumatic dependency.
- Electromechanical:Brushless motor drives with integrated force sensors dominate new platform development, compressing form factors while extending duty cycles through improved thermal management.
- Hydraulic:Force multiplication systems serve structural riveting above 25 kN where electromechanical torque density remains insufficient.
- Pneumatic:Compressed-air technology retains European automotive presence where sunk compressor costs delay replacement despite operating cost disadvantages.
- Manual:Unpowered tools persist in low-volume repair contexts and developing market entry segments.
Electromechanical technology commands the installed base expansion while hydraulic formats defend niche high-force applications.
Application:
Volume concentration in manufacturing contrasts with margin capture in maintenance and repair, where downtime costs justify premium tool deployment.
- Manufacturing:High-volume production lines in German passenger vehicle plants demand ISO 5393 torque certification and KBA type-approval for regulated industrial channel access.
- Assembly:General fabrication floors prioritize operator mobility and throughput metrics over absolute precision specifications.
- Repair:Field service operations for wind turbine and aerospace MRO accept per-rivet pricing models that preserve customer balance sheet flexibility.
- Maintenance:Scheduled tool calibration and firmware update requirements create recurring revenue attachment for distributor networks.
Manufacturing absorbs the greatest unit volume while Repair climbs fastest on outcome-based contracting adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes battery-powered riveters as fleet-standard equipment across automotive final assembly, while the United States deploys them selectively for OSHA compliance retrofitting. China integrates these tools through domestic manufacturing incentives rather than import substitution. Aerospace concentration in France and industrial upgrading in Japan round out the demand map.
Germany
Automotive OEMs at Wolfsburg and Stuttgart plants drive standardization across body-in-white and powertrain operations. KBA type-approval requirements govern tool deployment in passenger vehicle manufacturing, mandating ISO 5393 torque certification. The EU Green Deal's industrial decarbonization targets accelerate compressed-air elimination in Baden-Württemberg assembly halls.
United States
OSHA vibration exposure limits push manufacturers toward battery alternatives to reduce operator injury claims. The EPA's hazardous waste rules for spent lithium-ion packs shape end-of-life collection logistics for tool fleets. Aerospace tier-one suppliers in Seattle and Wichita pilot cordless systems for confined wing box assemblies.
China
Domestic content incentives through advanced manufacturing programs attract battery tool assembly operations serving aviation subcontractors. MIIT standards guide industrial equipment electrification timelines. Yangtze River Delta clusters concentrate production for export-oriented fastening equipment.
France
Aerospace fuselage programs in Toulouse demand automated riveting systems with repeatability tolerances below 0.1 mm. REACH substance restrictions on cobalt compounds compel cell chemistry recertification. The Occitanie region hosts tier-one supplier pilot programs for force-feedback sensor integration.
Japan
Precision manufacturing traditions favor electromechanical architectures with integrated force sensors. METI industrial efficiency programs subsidize compressor infrastructure retirement. Nagoya-area automotive suppliers retrofit final assembly stations with brushless motor platforms.
Battery-Powered Riveter Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-line power tool conglomerates leveraging cordless platform ecosystems against fastening equipment specialists defending application-specific positions. The structure rewards cross-selling through existing dealer networks on one vector and regional service density on another. Two dominant competitive moves are reshaping positions: strategic partnerships for cell chemistry access and portfolio diversification into automated fastening systems.
Within the integrated conglomerate tier, Stanley Black & Decker and Milwaukee exemplify platform-leveraged distribution models. Among European fastening specialists, GESIPA and Böllhoff occupy positions anchored in application-specific blind rivet systems and embedded technical service respectively. Japanese precision tool makers represented by Makita sit within a tier emphasizing electromechanical miniaturization for high-duty-cycle environments.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Milwaukee |
| DEWALT |
| Makita |
| GESIPA |
| Bosch |
| Atlas Copco |
| Cherry Aerospace |
| Böllhoff |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cylindrical cell lead times from East Asian suppliers compress pricing power for mid-tier fastening equipment makers while amplifying margin pressure across German automotive OEM tool procurement cycles. This inventory exposure forces tool OEMs into long-term offtake commitments with Samsung SDI and LG Energy Solution, locking in cell chemistry specifications before REACH cobalt restrictions trigger reformulation costs.
Pricing Analysis
Long-term offtake contracts dominate cell procurement for volume tool makers, while spot purchases persist for specialty chemistries and R&D prototyping batches. Price differentiation separates ISO 5393-certified industrial-grade units from general assembly tools lacking torque validation, with KBA type-approval adding further certification premiums for German passenger vehicle deployment. Cost compression in the handheld segment intensifies as Stanley Black & Decker and Milwaukee leverage cordless platform economies across riveter SKUs. General contractors and mid-volume metal fabricators exhibit highest price sensitivity, gravitating toward per-rivet leasing bundles that preserve working capital flexibility.
Supply Chain Analysis
Inventory concentration in cylindrical lithium-ion cells centers on South Korea, Japan, and China, with cathode active material processing clustering in the latter. Brushless motor stators and rare-earth magnet assemblies draw from Chinese and Japanese suppliers, while precision-machined aluminum housings source from German and Italian metalworking clusters. Single-source vulnerability in 21700 cell formats exposes production schedules to MIIT export licensing timelines and geopolitical trade friction. Distribution runs through authorized dealer networks embedding field technicians at customer plants for calibration and firmware maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-powered riveter incumbents face substitution defense against solid-state cell architectures that threaten incumbent cylindrical supply agreements and thermal management investments. Pneumatic-to-battery conversion momentum remains vulnerable to compressor infrastructure sunk costs in European automotive plants.
For Market Incumbents: Fortify cordless platform stickiness through embedded force-sensor integration and predictive maintenance firmware that pneumatic alternatives cannot replicate. Secure long-term offtake agreements with nickel-manganese cathode suppliers before REACH cobalt restrictions tighten, preserving margin structure against chemistry transition costs. Priority lever: regional service density in Stuttgart and Detroit distributor networks. For New Entrants and Emerging Players: Lead with application-specific configurations for wind turbine nacelle assembly and offshore construction where grid power unavailability creates forced adoption. India's PLI scheme for advanced manufacturing offers the most penetrable geography, with domestic content incentives lowering capital barriers for Southeast Asian aerospace subcontractor sales. Go-to-market angle: per-rivet outcome pricing that converts capital expenditure to operational expenditure for mid-volume fabricators. For Investors and Strategic Acquirers: Long-term, this sits as a industrial electrification infrastructure play because automotive and aerospace OEMs are eliminating compressed air systems on decade-long facility upgrade cycles. Acquisition target archetype: European fastening specialists with KBA type-approval relationships and embedded technician networks at German OEM plants. Signal to watch: solid-state cell prototype commercialization timelines threatening incumbent cylindrical supply agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Chemistry | Direct cathode material partnerships with Samsung SDI reduce REACH cobalt reformulation exposure. |
| Force-Feedback Sensor Integration | Sub-millimeter precision quality control collapses separate metrology stations at Toulouse aerospace suppliers. |
| Per-Rivet Outcome Contracting | Leasing bundles with battery swap logistics convert Mittelstand fabricators from capital to operational expenditure. |
| Regional Service Density Expansion | Embedded technician networks at Wolfsburg and Stuttgart plants defend against Milwaukee cross-selling. |
| Solid-State Cell Prototyping Partnership | Early thermal runaway protocol development with Japanese cell makers preserves certification lead time. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this analysis. Primary interviews across German automotive final assembly, Toulouse aerospace tier-one suppliers, and Detroit distributor networks combined with secondary validation from SEC filings of listed power tool conglomerates, KBA type-approval databases, and ECHA REACH substance restriction updates. Customs data on lithium-ion cell trade flows and ISO 5393 certification registries provided quantitative grounding. Bottom-up segment sizing triangulated against top-down OEM fleet deployment estimates.
Sensitivity analysis across cell chemistry substitution timelines, OSHA vibration limit enforcement intensity, and automotive production volatility shaped the analytical framework. Segmentation dimensions modeled include product format, end-user industry, technology architecture, and application context across the projection horizon. CAGRs derived from unit deployment trajectories at named OEM plants and distributor sell-through data. Industry-specific inputs encompassed brushless motor duty cycle improvements and force-sensor miniaturization cost curves.
Forecasts assume regulatory continuity in EPA hazardous waste rules, OSHA workplace exposure limits, and EU Green Deal industrial decarbonization targets; material policy shifts would require re-modeling. Solid-state cell commercialization acceleration, REACH substance restriction tightening, or automotive OEM production stoppages represent primary revision triggers. Revision becomes warranted when cylindrical cell supply concentration exceeds critical dependency thresholds or when force-feedback sensor adoption crosses inflection points in aerospace fuselage programs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Myanmar Battery Market
Batteries
Nickel-Metal Hydride (Ni-MH) Battery Market
Batteries
HIT Battery Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
Atomic Battery Market
Batteries
West Africa Battery Market
Batteries
Europe Consumer Battery Market
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Automotive Starting Battery Market
Batteries
North America Battery Market
Batteries
Sodium-Air Battery Market
Batteries
Iron Flow Battery Market
Batteries
Southeast Asia Battery Market
Batteries
Europe Battery Market
Batteries
Global Lithium Titanate (LTO) Batteries Market