
 India Rechargeable Battery Market | 2026-2036
India Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
India Rechargeable Battery Market Insights
Cell-grade energy density thresholds above 250 Wh/kg are reorganizing procurement criteria across the India Rechargeable Battery Market. Exide Industries leverages its established lead-acid infrastructure to anchor distribution networks in tier-two cities. Amara Raja Energy & Mobility Ltd competes through deep specialization in lithium-ion assembly for electric mobility. Samsung SDI Co., Ltd. extends its cathode chemistry expertise to supply premium automotive OEMs operating in Gujarat and Haryana.
India rechargeable batteries encompass electrochemical storage devices engineered for multiple charge-discharge cycles, typically employing lithium cobalt oxide or nickel manganese cobalt cathodes with graphite anodes in pouch or cylindrical formats, designed to convert and store electrical energy for cyclic reuse. The primary purpose spans propulsion power for electric vehicles, grid stabilization assets, and portable electronics requiring sustained energy delivery. Lithium-ion chemistry dominates installed capacity and captures the dominant margin pool across product types, while electric vehicle application outpaces consumer electronics in incremental volume growth. Fast charging technology leads R&D allocation as fleet operators demand sub-one-hour turnaround times for commercial deployment.
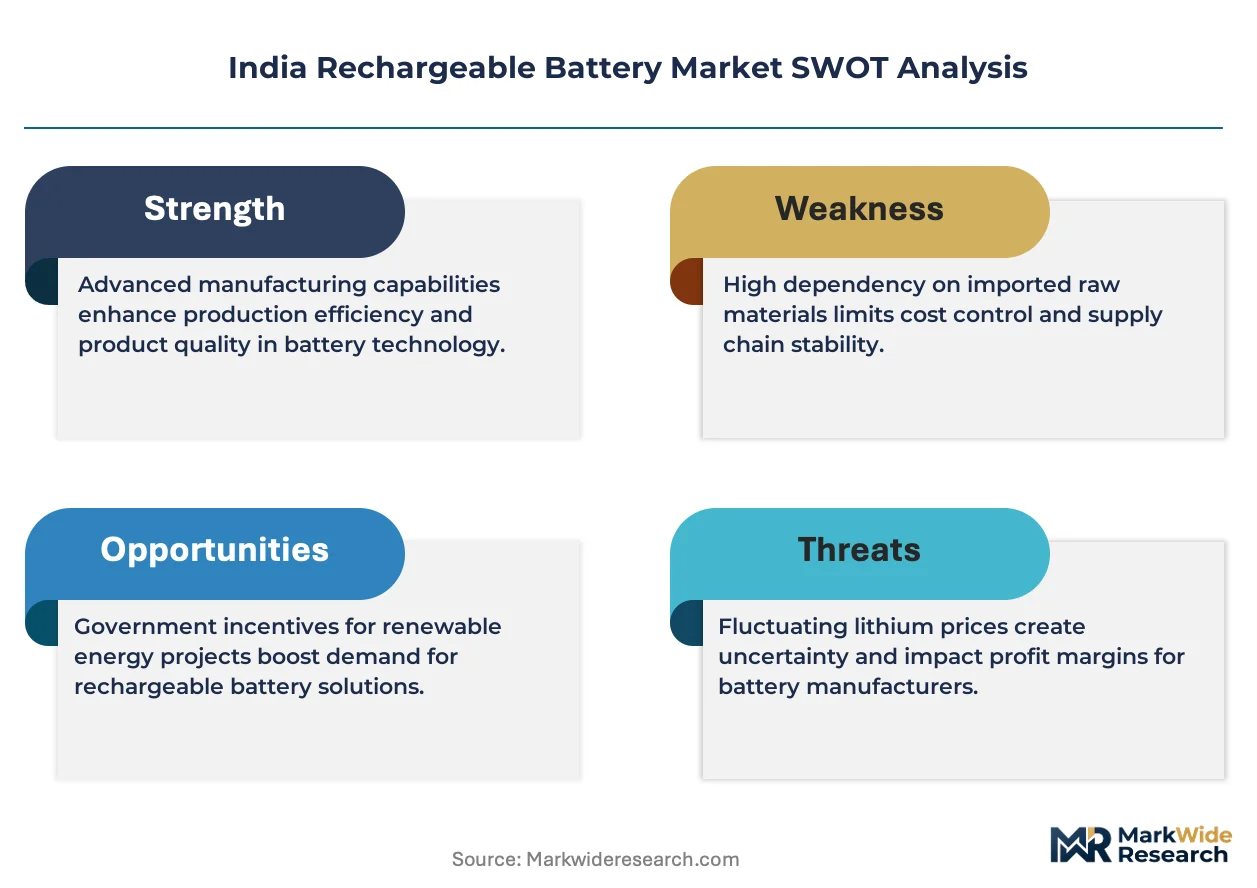
BIS certification mandates and the PLI scheme administered by the Ministry of Heavy Industries reshape domestic manufacturing obligations and import substitution timelines for cell producers. CDSCO guidelines govern battery safety in medical device applications, while CEA grid codes mandate storage compatibility standards for utility-scale installations. Stakeholders must track evolving BIS test protocols and state-level electric vehicle policies to align capacity expansion with certified demand channels.
Market Dynamics
The PLI scheme administered by India's Ministry of Heavy Industries is redirecting capital from imported cell assemblies toward domestic gigafactory capacity, compressing procurement lead times for automotive OEMs and utility developers.
Growth Catalysts
- Electric mobility mandates:State-level electric vehicle policies in Maharashtra and Tamil Nadu are accelerating fleet operator procurement of lithium-ion propulsion systems.
- Advanced Chemistry Cell PLI:The Ministry of Heavy Industries incentive structure is anchoring domestic cathode and cell manufacturing investments.
- Grid-scale storage integration:CEA grid code compatibility requirements are mandating battery energy storage systems for renewable stabilization assets.
Market Restraints
- Lithium carbonate volatility:Spodumene concentrate pricing swings from Australian and Chilean suppliers compress cell producer margins.
- Import dependency concentration:Over 80% of lithium-ion cell supply originates from Chinese cathode and separator manufacturers.
- BIS certification timelines:Extended test protocol durations for cell-grade energy density validation delay commercial deployment.
Strategic Opportunities
- Tier-two city electrification:Distribution networks in Indore, Coimbatore, and Lucknow remain underpenetrated for commercial vehicle battery swapping.
- Sodium-ion chemistry convergence:Hard carbon anode technology paired with Prussian blue cathodes offers cost displacement for stationary storage applications.
- Fleet operator direct contracting:Bypassing traditional automotive dealer channels enables volume-anchored pricing for logistics operators.
Industry Challenges
- Electrochemical engineering talent scarcity:Domestic universities produce insufficient cell design and thermal management specialists for gigafactory ramp rates.
- Legacy lead-acid integration friction:Exide Industries and Amara Raja service networks face retraining costs for lithium-ion diagnostics and warranty protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Rechargeable Battery Market |
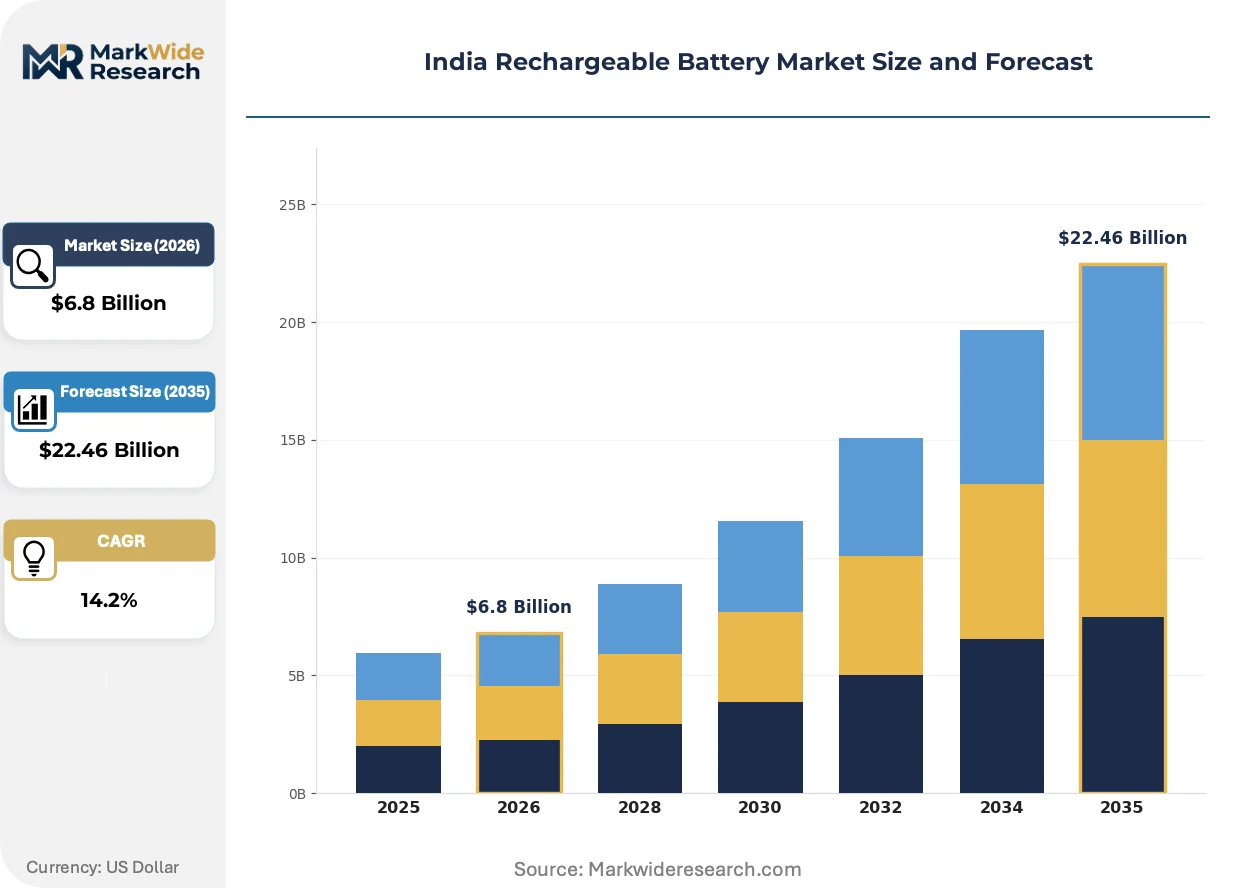
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Zinc-Carbon Application: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Industrial Equipment End User: Households, Commercial, Automotive, Utilities Technology: Fast Charging, Smart Batteries, Wireless Charging, Solar Hybrid |
| Companies Covered | Exide Industries, Amara Raja Energy & Mobility Ltd, Eveready Industries India Ltd, Panasonic Corporation, LG Chem Ltd, Samsung SDI Co., Ltd., Saft Groupe SA, Luminous Power Technologies, HBL Power Systems Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Rechargeable Battery Market Trends and Innovations
Cell chemistry evolution and procurement model compression are restructuring competitive advantage around energy density thresholds and direct fleet relationships rather than channel presence.
Sodium-ion battery technology is displacing lithium iron phosphate in stationary storage and low-speed electric vehicle applications. Hard carbon anodes paired with layered oxide cathodes achieve 160 Wh/kg at 30% lower bill-of-materials cost. Maharashtra-based utility developers are piloting sodium-ion systems for 4-hour grid stabilization, compressing payback periods for renewable-plus-storage projects.
BIS certification mandates for cell-grade energy density above 250 Wh/kg are forcing cathode chemistry transitions toward nickel manganese cobalt formulations. Domestic assemblers must retest existing pouch and cylindrical designs under revised thermal runaway protocols. Tamil Nadu automotive OEMs are accelerating supplier qualification timelines to meet 2025 model year production schedules.
Fleet operators are consolidating procurement through direct cell supplier contracts, bypassing traditional automotive tier-one integrators. Logistics operators in Gujarat and Haryana negotiate volume commitments with cathode material producers for sub-one-hour fast charging compatibility. This channel disintermediation compresses margin capture for established battery pack assemblers while rewarding chemistry specialists with certified BIS test reports.
India Rechargeable Battery Market Segmentation
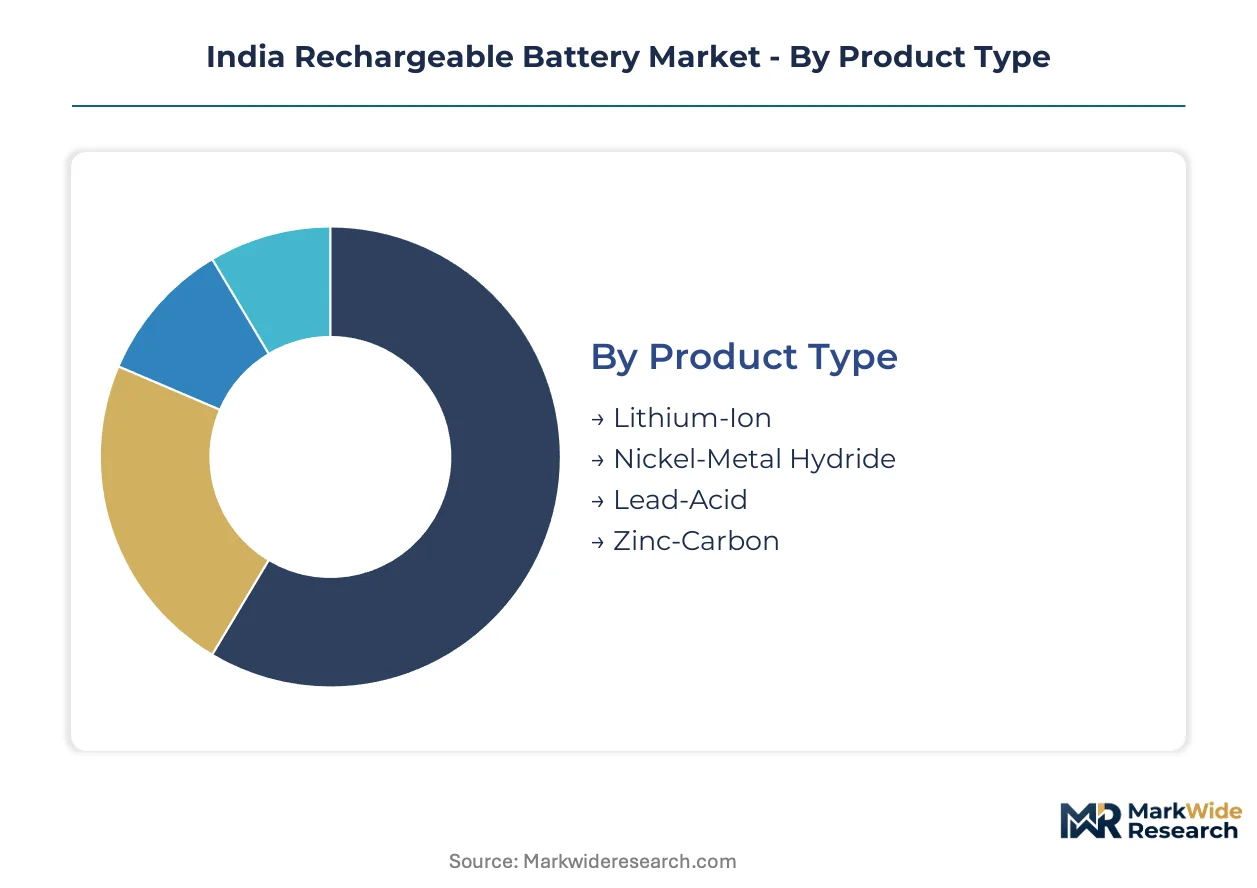
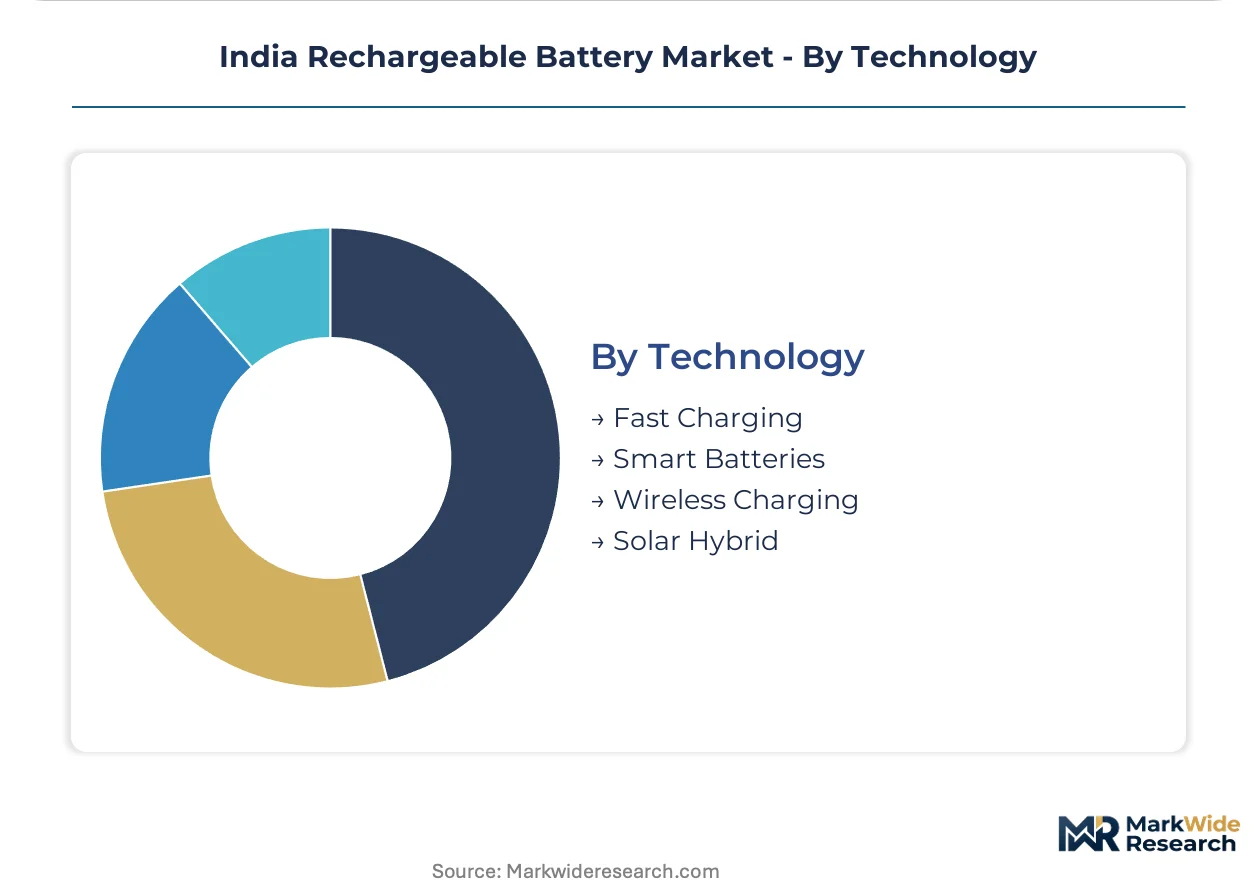
Segmentation reveals how procurement channels diverge across India's rechargeable battery landscape. Chemistry choices, application requirements, and end-user scale reshape distribution pathways from gigafactory direct sales to tier-two distributor networks.
Product Type:
Channel mix varies sharply by chemistry: lithium-ion flows predominantly through direct OEM contracts and fleet operator agreements, while lead-acid maintains entrenched distributor relationships in aftermarket automotive and UPS segments.
- Lithium-Ion:Nickel manganese cobalt and lithium iron phosphate cathodes dominate cell formulations, with energy density thresholds above 250 Wh/kg qualifying for BIS certification under revised protocols. Maharashtra and Tamil Nadu automotive OEMs concentrate procurement for electric vehicle propulsion systems, compressing supplier qualification timelines to align with production schedules.
- Lead-Acid:Flooded and valve-regulated designs persist in starter-lighting-ignition applications and stationary backup power. Exide Industries and Amara Raja leverage established service networks across tier-two cities for aftermarket replacement cycles, though retraining costs for lithium-ion diagnostics erode margin retention.
- Nickel-Metal Hydride:Rare earth hydride anodes paired with nickel oxyhydroxide cathodes retain niche positioning in hybrid electric vehicle battery packs and medical device power systems requiring stable discharge curves.
- Zinc-Carbon:Primary cell chemistry with limited rechargeability serves remote monitoring devices and low-drain consumer applications where cost minimization outweighs cycle life requirements.
By volume, lead-acid leads. By growth pace, lithium-ion is ahead.
Application:
Cost tier stratification separates premium automotive propulsion systems from commoditized consumer electronics cells, with utility-scale storage occupying an intermediate position on both capital intensity and margin structure.
- Electric Vehicles:Two-wheeler and three-wheeler fleet operators in Gujarat and Haryana drive demand for sub-one-hour fast charging compatibility. Direct contracting with cathode material producers bypasses traditional tier-one integrators, compressing margin capture for established pack assemblers.
- Consumer Electronics:Pouch and cylindrical formats power smartphones, laptops, and portable devices through established electronics retail channels. Energy density prioritization over cycle life shapes procurement criteria for this segment.
- Renewable Energy Storage:CEA grid code mandates compatibility standards for utility-scale installations, anchoring procurement around 4-hour duration systems for solar and wind stabilization assets in Maharashtra.
- Industrial Equipment:Forklift motive power and telecommunications backup applications favor lithium iron phosphate for thermal stability in high-temperature operating environments.
Electric vehicles command premium pricing. Consumer electronics delivers volume scale.
End User:
Customer type determines contract structure: automotive and utilities negotiate multi-year volume commitments, while households and commercial users transact through spot purchases and distributor inventories.
- Automotive:OEMs and fleet operators concentrate procurement decisions, with state-level electric vehicle policies in Maharashtra and Tamil Nadu accelerating lithium-ion pack adoption for commercial deployment.
- Utilities:State distribution companies and independent power producers procure battery energy storage systems under CEA regulatory frameworks for grid stabilization and renewable integration mandates.
- Commercial:Logistics operators, data centers, and manufacturing facilities source backup power and motive power systems through integrators and direct manufacturer relationships.
- Households:Replacement cycles for inverter batteries and emerging residential solar-plus-storage installations flow through electrical goods retailers and installer networks.
Automotive directs technology roadmaps. Utilities anchor long-duration demand.
Technology:
Maturity gradients separate commercialized fast charging from pilot-phase solar hybrid systems, with smart batteries occupying intermediate development status for telematics integration.
- Fast Charging:Silicon-graphite composite anodes and advanced thermal management enable sub-one-hour turnaround times for commercial electric vehicle fleets. Gujarat-based logistics operators negotiate volume-anchored pricing contingent on charging infrastructure compatibility.
- Smart Batteries:Integrated battery management systems with cellular connectivity enable remote diagnostics and predictive maintenance for fleet operators and utility-scale installations.
- Wireless Charging:Inductive power transfer systems pilot in automated guided vehicles and premium consumer electronics, with efficiency losses limiting adoption in high-power applications.
- Solar Hybrid:Integrated photovoltaic-cell-inverter systems target off-grid and weak-grid installations, with sodium-ion chemistry emerging as a cost-displacement option for stationary storage paired with hard carbon anodes.
Fast charging dominates R&D allocation. Solar hybrid is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive fleet operators in Gujarat and Haryana negotiate volume-anchored contracts, while Maharashtra and Tamil Nadu automotive OEMs absorb premium pricing for certified cell-grade energy density above 250 Wh/kg.
Maharashtra
Electric vehicle fleet operators in Mumbai and Pune drive lithium-ion pack procurement for commercial two-wheeler and three-wheeler deployment. The state's electric vehicle policy accelerates adoption through purchase incentives and charging infrastructure mandates. Automotive OEMs in the Pune-Chakan industrial corridor compress supplier qualification timelines to align with 2025 model year production schedules.
Tamil Nadu
Automotive manufacturers in Chennai and Sriperumbudur anchor demand for nickel manganese cobalt cathode formulations meeting BIS certification thresholds. State-level electric vehicle policies provide capital subsidies for battery manufacturing investments. The Sri City special economic zone hosts cathode material producers qualifying domestic cell assemblers for premium automotive contracts.
Gujarat
Logistics operators in Ahmedabad and Surat negotiate direct cathode material contracts bypassing traditional tier-one integrators. The state's industrial policy extends land and power subsidies for gigafactory investments. The Sanand-Vithalapur automotive cluster attracts cell producers seeking proximity to commercial vehicle OEMs demanding sub-one-hour fast charging compatibility.
Haryana
Fleet operators in Gurugram and Faridabad consolidate procurement through volume commitments with cell suppliers. The state's electric mobility policy mandates commercial vehicle electrification for last-mile delivery segments. The Manesar industrial area hosts battery pack assemblers serving premium automotive OEMs with certified thermal management systems.
Karnataka
Utility-scale developers in Bengaluru pilot sodium-ion systems for 4-hour grid stabilization under CEA grid code mandates. The state's renewable energy policy mandates storage compatibility for solar and wind integration. The Electronics City and Peenya industrial zones concentrate battery management system developers serving domestic gigafactory projects.
India Rechargeable Battery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where chemistry specialists capture premium margins while scale assemblers compete on volume throughput. Domestic lead-acid incumbents leverage established distribution networks for aftermarket replacement cycles, while Korean and Japanese cathode specialists anchor premium automotive supply chains. Three archetypes dominate: legacy battery manufacturers retooling for lithium-ion assembly, multinational chemistry specialists with certified BIS test protocols, and emerging domestic gigafactory developers securing PLI scheme allocations. Competitive moves concentrate on backward integration into cathode material production and direct fleet operator contracting to bypass traditional tier-one integrators.
Among domestic incumbents, Exide Industries and Amara Raja Energy & Mobility Ltd occupy positions bridging lead-acid aftermarket dominance and lithium-ion transition investments, while Samsung SDI Co., Ltd. exemplifies the multinational chemistry specialist archetype serving premium automotive OEMs in Gujarat and Haryana with certified high-energy-density cell formulations.
| Leading Market Players |
|---|
| Exide Industries |
| Amara Raja Energy & Mobility Ltd |
| Eveready Industries India Ltd |
| Panasonic Corporation |
| LG Chem Ltd |
| Samsung SDI Co., Ltd. |
| Saft Groupe SA |
| Luminous Power Technologies |
| HBL Power Systems Ltd |
| Others |
Pricing and Supply Chain Analysis
Sodium-ion chemistry substitution for lithium iron phosphate in stationary storage applications simultaneously redraws raw material sourcing maps toward India-domestic hard carbon suppliers and compresses cell-level pricing economics by thirty percent against incumbent lithium-ion benchmarks. This chemistry pivot redirects procurement negotiations from Australian spodumene and Chilean brine contracts toward local anode material partnerships, altering margin distribution across the value chain.
Pricing Analysis
After-sales service revenue from battery management system diagnostics and extended warranty contracts now drives lifetime value capture for pack assemblers. Three-tier pricing structure across premium automotive-grade cells, standard commercial vehicle packs, and economy stationary storage modules separates OEM-certified nickel manganese cobalt formulations from uncertified lithium iron phosphate alternatives. Cost compression in the economy tier intensifies because domestic sodium-ion pilots undercut lithium-ion bill-of-materials, though BIS certification premiums protect pricing power at the premium tier. Fleet operators in Gujarat and Haryana exhibit highest price sensitivity, negotiating volume-anchored direct contracts, while Tamil Nadu automotive OEMs absorb premium pricing for certified thermal management systems.
Supply Chain Analysis
Strategic stockpiling of lithium carbonate and cobalt sulfate dominates inventory strategy among domestic cell assemblers seeking insulation from Australian and Chilean concentrate volatility. Cathode active material supply concentrates in China, South Korea, and Japan, with over eighty percent of separator and electrolyte feedstock drawing from Chinese chemical processors. Single-source vulnerability in high-purity lithium hexafluorophosphate electrolyte salts creates structural risk for gigafactory ramp schedules. Distribution runs through direct OEM contracts for automotive applications and established electrical goods distributor networks for replacement cycles in tier-two cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as fleet operator procurement consolidates around direct cathode supplier relationships, creating niche openings for chemistry specialists outside traditional tier-one integrator channels. State-level electric vehicle policy divergence across Maharashtra, Tamil Nadu, Gujarat, and Haryana generates regional arbitrage possibilities for qualified entrants.
For Market Incumbents: Shield lead-acid aftermarket revenue streams in tier-two cities through accelerated lithium-ion service network retraining before Exide Industries and Amara Raja lose diagnostic capability differentiation. Backward integration into cathode material production anchors margin retention against Korean chemistry specialists capturing premium automotive contracts. BIS certification investment for cell-grade energy density above 250 Wh/kg remains the critical defensive lever. For New Entrants and Emerging Players: Anchor in sodium-ion chemistry for stationary storage applications where hard carbon anode supply chain localization offers cost displacement against lithium iron phosphate incumbents. Tier-two city battery swapping infrastructure for commercial two-wheeler fleets presents the most penetrable geography, with Indore, Coimbatore, and Lucknow showing underdeveloped distributor coverage. Direct contracting with Maharashtra utility developers for four-hour grid stabilization pilots provides the optimal go-to-market angle bypassing established pack assembler relationships. For Investors and Strategic Acquirers: The market sits at a chemistry-transition phase that favors cathode material specialists with certified BIS test protocols over scale assemblers dependent on imported cell supply. Long-term viability across the projection horizon rests on domestic gigafactory operators securing PLI scheme allocations with binding offtake commitments from automotive OEMs. Acquisition target archetype: mid-cap hard carbon anode developers with utility-scale pilot validation. The signal to watch is sodium-ion system cost parity achievement against lithium iron phosphate in stationary storage tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Backward Integration | Captures margin pool from Chinese suppliers while securing BIS certification timelines for domestic cell assemblers. |
| Fleet Operator Direct Contracting | Bypasses tier-one integrator channels to anchor volume commitments with Gujarat and Haryana logistics operators. |
| Sodium-Ion Chemistry Scale-Up | Displaces lithium iron phosphate cost structure for Maharashtra utility-scale storage under CEA grid code mandates. |
| Fast Charging Infrastructure Partnership | Aligns cell thermal management capabilities with sub-one-hour turnaround requirements from commercial vehicle OEMs. |
| BIS Certification Acceleration | Compresses test protocol durations to meet Tamil Nadu automotive OEM 2025 model year supplier qualification timelines. |
Research Methodology
Desk research of customs trade records, BIS certification filings, and CEA grid code documentation preceded structured interviews with gigafactory project developers, automotive OEM procurement officers, cathode material R&D directors, and utility-scale storage developers. Primary fieldwork with fleet operators in Maharashtra and Tamil Nadu validated demand assumptions for fast charging compatibility requirements. Secondary triangulation drew from Ministry of Heavy Industries PLI scheme disclosures, state electric vehicle policy circulars, and lithium carbonate import manifests. Bottom-up cell demand modeling and top-down energy storage deployment targets were reconciled through iterative stakeholder feedback.
Variance decomposition across chemistry type, application segment, and regional policy cluster shaped the analytical framework. Segmentation dimensions modeled include product chemistry, end-use application, customer scale tier, and state-level regulatory environment. CAGRs were derived from installed capacity buildout trajectories and replacement cycle intensities rather than extrapolated trend fitting. Industry-specific forecast inputs incorporated cathode material localization timelines and BIS test protocol revision schedules.
Decision-makers should treat outputs as directional under assumptions of sustained PLI scheme allocation continuity and stable lithium carbonate pricing bands; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Lithium-Fluorinated Graphite Batteries Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market
Batteries
Lithium Starters Market
Batteries
Aluminum-Air Battery Market
Batteries
Asia-Pacific Industrial Battery Market
Batteries
Micro Battery Market
Batteries
Battery-Powered Riveter Market
Batteries
Industrial Battery Charger Market
Batteries
Grid-Scale Lead-Acid Battery Market
Batteries
Norway Rechargeable Battery Market
Batteries
Potassium-Ion Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
Smart Diagnostic Battery Charger Market
Batteries
All-In-One Solar Storage Battery Market
Batteries
South Asia Battery Market
Batteries
Grid-Scale Battery Market