
 Asia-Pacific Industrial Battery Market | 2026-2036
Asia-Pacific Industrial Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Industrial Battery Market Outlook
Multi-source procurement for lithium raw materials is hardening across the Asia-Pacific industrial battery value chain. CATL leverages its captive mining partnerships in Indonesia to secure nickel supply. Samsung SDI competes through advanced NCM cathode formulations for high-cycle applications. BYD anchors its position with in-house LFP cell production serving grid storage and electric bus fleets.
Asia-Pacific industrial batteries are electrochemical storage systems engineered for continuous deep-cycle operation, typically rated between 500 and 5,000 ampere-hours with voltage architectures from 12V to 1,500V depending on application scale. These systems buffer intermittent renewable generation, stabilize manufacturing loads, and provide backup autonomy for critical telecommunications infrastructure. Lithium ion chemistry leads value creation due to superior energy density and declining cell costs, while lead acid retains substantial volume in cost-sensitive backup power installations across Southeast Asian manufacturing zones. Flow battery technology occupies a narrower but strategically significant niche in long-duration grid storage projects where cycle life economics override upfront capital sensitivity.
China's SAMR enforces GB standards for thermal runaway containment and recycling traceability, while India's BIS mandates compulsory registration for imported cells under its quality control order. Japan's METI directs subsidy frameworks toward solid-state battery R&D, redirecting domestic manufacturer investment priorities. Stakeholders must monitor how divergent national certification timelines reshape cross-border supply chain planning and capital allocation across the region.
Market Dynamics
China's GB standards for thermal runaway containment are forcing battery manufacturers to redesign cell architectures and thermal management systems across the Asia-Pacific supply base. This regulatory pressure cascades through procurement specifications for data center UPS and grid storage deployments.
Growth Catalysts
- India PLI scheme incentives:Production-linked incentives for advanced chemistry cell manufacturing are drawing cathode active material investments into Gujarat and Tamil Nadu manufacturing corridors.
- Data center UPS expansion:Hyperscale operators across Singapore, Indonesia, and Malaysia are doubling lithium-ion battery deployments for uninterruptible power supply redundancy.
- Renewable integration mandates:Grid codes in Australia and South Korea now require battery energy storage systems for utility-scale solar and wind interconnection.
Market Restraints
- Nickel supply concentration:Indonesian mining partnerships dominate feedstock access, creating single-source vulnerability for NCM cathode producers.
- Lithium carbonate price volatility:Spot market swings for lithium raw materials compress cell manufacturer margins and destabilize project financing.
- Lead acid substitution ceiling:Cost-sensitive Southeast Asian manufacturing zones retain flooded battery installations where capital constraints override lifecycle economics.
Strategic Opportunities
- Vietnam manufacturing emergence:Industrial zones near Hai Phong and Bac Ninh offer tariff-advantaged cell assembly capacity for export-oriented supply chains.
- Flow battery long-duration storage:Vanadium redox systems capture 8+ hour grid storage tenders where cycle life economics override lithium-ion capital cost advantages.
- Second-life battery repurposing:Retired electric bus and passenger vehicle packs create feedstock for stationary storage applications with reduced certification burden.
Industry Challenges
- Cell-to-pack engineering talent scarcity:Thermal simulation and battery management system firmware expertise concentrates in Shenzhen and Seoul, constraining regional expansion.
- Multi-jurisdiction certification timelines:Divergent GB, BIS, and JIS testing protocols delay product launches by 6-12 months for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Industrial Battery Market |
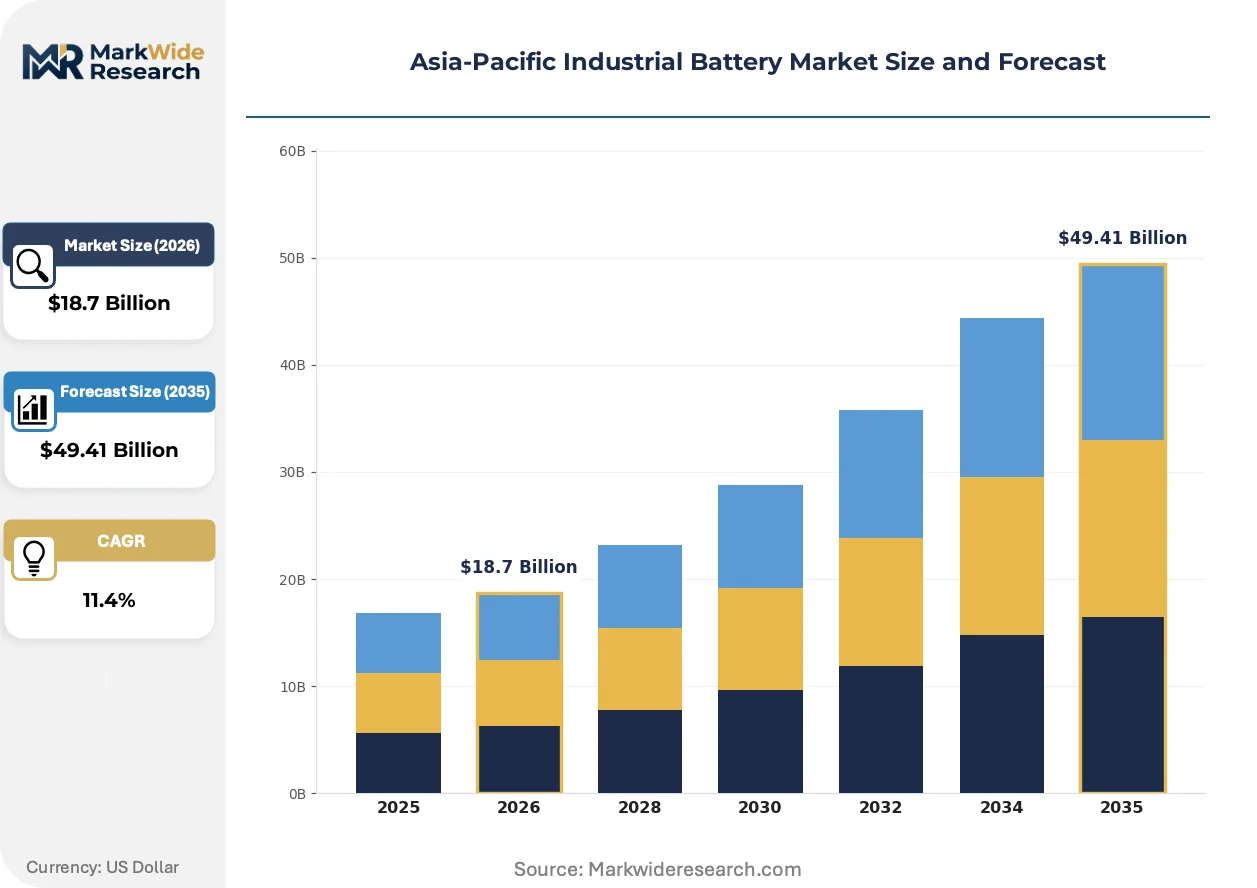
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium Ion, Nickel Cadmium, Flow Battery End User: Manufacturing, Construction, Transportation, Telecommunications Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity Application: Grid Storage, Backup Power, Electric Vehicles, Renewable Energy |
| Companies Covered | Exide Industries Ltd, GS Yuasa Corporation, Panasonic Corporation, Contemporary Amperex Technology Co. Limited (CATL), LG Energy Solution Ltd., Samsung SDI Co., Ltd., BYD Company Limited, EnerSys, East Penn Manufacturing Company Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Industrial Battery Market Strategic Shifts
Lithium iron phosphate chemistry is consolidating market position across Asia-Pacific industrial applications as energy density improvements narrow the performance gap with nickel-based alternatives. This chemistry shift reconfigures cathode supply chains and thermal management requirements.
LFP cell technology delivers superior cycle stability and thermal safety margins for grid storage and electric bus fleets. State-owned grid operators in China and independent power producers in India are specifying LFP-dominant battery energy storage system tenders. The technology is consolidating procurement specifications and compressing NCM market share in stationary applications.
China's SAMR enforcement of GB 38031 thermal propagation testing mandates cell-level containment barriers and venting protocols. Battery pack manufacturers must redesign module architectures and submit extended abuse test documentation. Data center and telecom backup power segments face the steepest compliance cost escalation.
Asset ownership models are displacing traditional equipment purchase contracts for large-scale industrial battery deployments. Independent power producers and data center operators prefer energy storage-as-a-service arrangements that transfer operational risk to system integrators. This shift concentrates in Australian grid storage and Singaporean colocation facility markets where balance sheet optimization drives procurement preferences.
Asia-Pacific Industrial Battery Market Segmentation
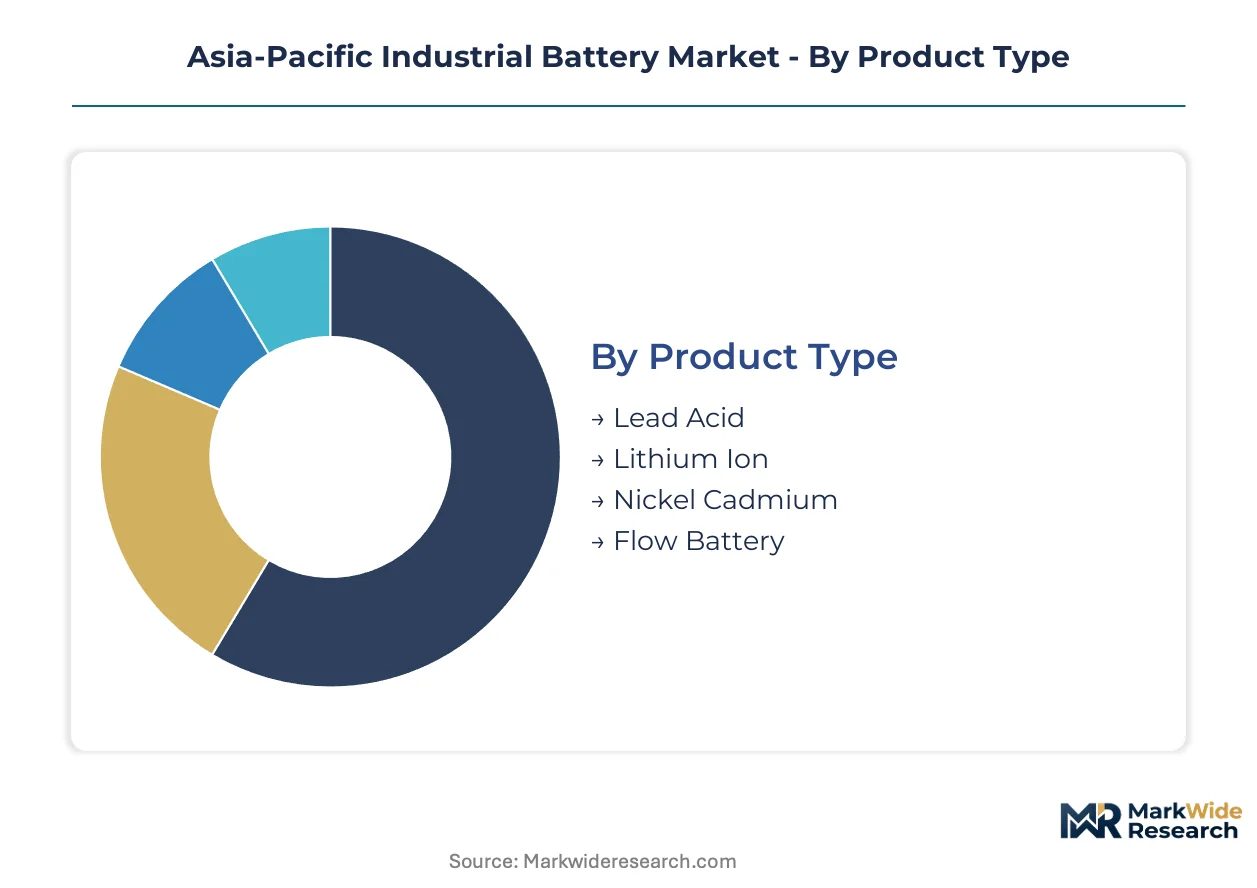
Industrial battery procurement in Asia-Pacific diverges sharply across chemistry types, end-use intensity, and scale requirements. Stakeholders configure supply strategies around cell thermal profiles, duty cycle specifications, and jurisdiction-specific certification burdens.
Product Type:
Lithium iron phosphate chemistry now dominates engineering specifications for new stationary deployments across the region.
- Lithium Ion:Energy density advantages and declining cell costs position this chemistry for grid storage and data center UPS applications. China's GB 38031 thermal propagation mandates are accelerating module redesign investments among pack integrators serving Southeast Asian markets.
- Lead Acid:Flooded and valve-regulated designs retain substantial installed base in cost-sensitive manufacturing corridors. India's small and medium enterprises specify lead acid for short-duration backup where capital constraints override lifecycle economics.
- Flow Battery:Vanadium redox systems capture long-duration grid tenders where cycle life economics override upfront capital sensitivity.
- Nickel Cadmium:Aviation and rail signaling applications sustain niche demand despite environmental handling restrictions.
Lithium Ion leads on scale; Flow Battery leads on momentum.
End User:
Procurement intensity varies with operational criticality and power quality requirements across industrial verticals.
- Telecommunications:Tower operators in Indonesia and India deploy lithium-ion systems for diesel displacement and grid backup autonomy. Battery swapping logistics and remote monitoring capabilities concentrate vendor selection criteria.
- Manufacturing:Semiconductor fabs and automotive assembly lines specify uninterruptible power supply configurations with sub-10 millisecond transfer times. Thailand's Eastern Economic Corridor investments are expanding medium-voltage battery energy storage system deployments.
- Transportation:Electric bus fleet operators in Shenzhen and Seoul specify LFP packs with 4,000+ cycle warranties.
- Construction:Mobile equipment and temporary power applications favor lead acid for equipment rental fleets.
Telecommunications leads on scale; Manufacturing leads on momentum.
Capacity:
System sizing follows application duty cycles and physical footprint constraints.
- High Capacity:Utility-scale grid storage and hyperscale data center deployments specify containerized systems above 10 MWh. Australian independent power producers tender for 100+ MWh configurations with four-hour duration requirements.
- Medium Capacity:Commercial and industrial peak shaving applications in South Korea's KEPCO service territory cluster in 1-10 MWh range.
- Low Capacity:Telecom tower backup and retail UPS units dominate unit volume.
- Ultra High Capacity:Pumped hydro hybridization and transmission deferral projects in China and India explore giga-scale configurations.
High Capacity leads on scale; Ultra High Capacity leads on momentum.
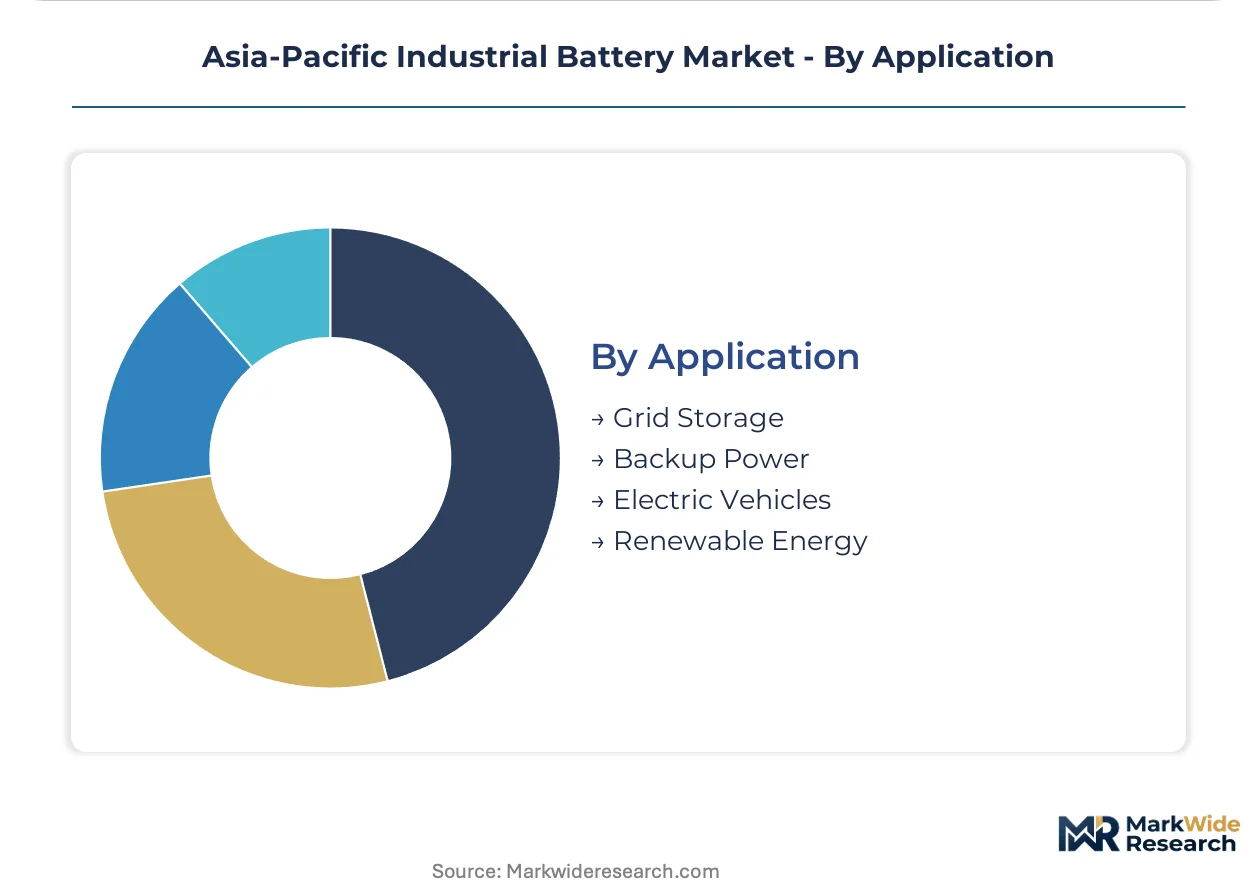
Application:
Revenue concentration follows grid modernization timelines and renewable penetration rates.
- Grid Storage:Frequency regulation and renewable firming tenders in Australia, South Korea, and China represent primary demand expansion. State-owned grid operators specify LFP-dominant procurements with 15-year service contracts.
- Backup Power:Data center colocation facilities in Singapore and Malaysia specify lithium-ion UPS with N+1 redundancy architectures.
- Renewable Energy:Solar-plus-storage and wind co-location projects in Vietnam and the Philippines drive DC-coupled system demand.
- Electric Vehicles:Bus fleet electrification and commercial vehicle depot charging sustain pack demand with distinct thermal management requirements.
Grid Storage leads on scale; Renewable Energy leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Pearl River Delta industrial corridor anchors regional battery demand through data center expansion and electric bus fleet electrification. Manufacturing clusters across Shenzhen and Dongguan specify high-cycle lithium-ion systems for grid storage integration.
China
State-owned grid operators tender for giga-scale battery energy storage systems under dual carbon policy mandates. SAMR enforces GB 38031 thermal propagation testing that forces module architecture redesigns. Shenzhen manufacturers concentrate cell-to-pack engineering capacity serving Southeast Asian export markets.
India
Production-linked incentive schemes draw cathode active material investments into Gujarat and Tamil Nadu manufacturing corridors. BIS mandates compulsory registration for imported cells under quality control orders. The Delhi-Mumbai Industrial Corridor expands medium-voltage battery deployments for semiconductor fabrication facilities.
Japan
Electric bus operators in Tokyo and Osaka specify solid-state battery pilot programs. METI directs subsidy frameworks toward next-generation R&D investments. Kansai region manufacturers concentrate thermal management system expertise for high-cycle industrial applications.
South Korea
KEPCO service territory mandates battery energy storage for renewable interconnection compliance. MFDS oversees safety certification protocols for grid-scale deployments. Busan-Ulsan industrial clusters anchor NCM cathode formulation capacity serving regional export demand.
Australia
Independent power producers tender for 100+ MWh configurations with four-hour duration requirements under national electricity market rules. The national regulator oversees grid code compliance for frequency regulation services. Queensland and New South Wales mining regions deploy containerized systems for remote power autonomy.
Asia-Pacific Industrial Battery Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue long-duration storage specializations and second-life repurposing services. The vendor base stratifies across integrated cell manufacturers, specialized pack integrators, and industrial equipment suppliers with captive battery divisions. Three archetypes dominate: chemistry-agnostic system integrators, captive producers with upstream mining control, and legacy lead acid suppliers defending installed base positions. Capacity expansion and strategic partnerships constitute the dominant competitive vectors as firms secure raw material offtake agreements.
Among Asia-Pacific-based producers, Contemporary Amperex Technology Co. Limited and BYD Company Limited exemplify integrated manufacturing archetypes with captive supply chain structures. GS Yuasa Corporation occupies a position within the established industrial equipment supplier tier. These firms represent contrasting strategic postures: integrated cell-to-system control versus specialized component supply relationships.
| Leading Market Players |
|---|
| Exide Industries Ltd |
| GS Yuasa Corporation |
| Panasonic Corporation |
| Contemporary Amperex Technology Co. Limited (CATL) |
| LG Energy Solution Ltd. |
| Samsung SDI Co., Ltd. |
| BYD Company Limited |
| EnerSys |
| East Penn Manufacturing Company Inc. |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers in China and South Korea anchor cell manufacturing capacity, translating upstream mining control into pricing discipline that filters through to Southeast Asian pack integrators and Australian independent power producers.
Pricing Analysis
Lithium carbonate and nickel sulfate spot volatility passes through to cell pricing on quarterly contract resets, compressing margins for non-integrated pack manufacturers. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels differentiates offerings, with GB 38031 thermal propagation certification commanding substantial premia. Cost compression in economy lead acid tiers is intensifying because Indonesian nickel supply concentration limits cathode material competition. Data center operators exhibit lowest price sensitivity due to balance sheet capacity, while Indian small and medium enterprises in manufacturing corridors remain most cost-constrained.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale data center and utility-scale grid storage demand, while distributor networks serve telecom tower operators and manufacturing facility procurement teams across Southeast Asia. Raw material extraction concentrates in Indonesia for nickel, Australia for lithium spodumene, and Chile for lithium brine, with China's Qinghai and Sichuan provinces hosting downstream refining and cathode active material production. Cell manufacturing draws from graphite anodes, electrolyte salts, and separator films with limited dual-sourcing options. Single-source vulnerability in Indonesian nickel laterite feedstock creates supply chain risk for NCM cathode producers serving South Korean and Japanese battery manufacturers. Distribution runs through specialized industrial equipment distributors and direct sales teams for large-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LFP chemistry standardization and captive mining integration are compressing production costs while GB 38031 certification requirements enable premium pricing tiers for compliant suppliers.
For Market Incumbents: Acquire vanadium redox flow battery technology specialists to capture long-duration grid storage tenders where cycle life economics override lithium-ion capital advantages. Defend position against emerging Chinese LFP specialists by securing Indonesian nickel offtake agreements and accelerating thermal management system R&D investments in Shenzhen engineering clusters. For New Entrants and Emerging Players: Launch via energy-storage-as-a-service financing models targeting Australian independent power producers and Singaporean data center operators seeking balance sheet risk transfer. Target Vietnam's Hai Phong and Bac Ninh industrial zones for tariff-advantaged cell assembly capacity serving export-oriented supply chains. Penetrate second-life battery repurposing for stationary storage applications where reduced certification burden lowers market entry costs. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap pack integrators lacking captive cathode supply but possessing established BIS and GB certification pathways. Long-term viability favors firms with backward integration into lithium refining or nickel processing assets. Watch LFP chemistry share in Indian PLI scheme tender awards as the inflection indicator for cathode supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Active Material Capacity Expansion | PLI scheme incentives in Gujarat and Tamil Nadu draw investment away from import-dependent supply chains. |
| Thermal Management System R&D Investment | GB 38031 compliance mandates from SAMR force module architecture redesigns across Southeast Asian exports. |
| Indonesian Nickel Mining Partnership | Captive laterite feedstock secures NCM cathode cost position against LFP substitution pressure. |
| Energy Storage-as-a-Service Launch | Asset ownership models displace equipment purchases in Australian and Singaporean procurement preferences. |
| Second-Life Battery Repurposing Program | Retired electric bus packs from Shenzhen and Seoul create feedstock for stationary storage with reduced certification burden. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cell manufacturing executives, data center procurement directors, utility planning officers at state-owned grid operators, and BIS certification specialists with secondary validation. Trade data from China's customs administration, SAMR GB standard enforcement notices, Indian PLI scheme disbursement records, and KEPCO battery energy storage interconnection filings anchored supply-side estimates. Bottom-up cell shipment tracking and top-down grid storage capacity announcements were triangulated against cathode active material production data.
Historical reference periods spanning pre-pandemic, disruption, and recovery phases anchored the forecast window across the analysis window. Segmentation modeling incorporated chemistry type, end-use vertical, system capacity tier, and jurisdiction-specific certification requirements. CAGRs were derived from regression analysis of cell cost curves and deployment pipelines. Key inputs included lithium carbonate spot price trajectories, GB 38031 compliance cost estimates, and PLI scheme incentive drawdown schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained lithium price volatility or accelerated solid-state battery commercialization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Nickel-Based Battery Charger Market
Batteries
Molten Salt Battery Market
Batteries
Custom Battery Pack Market
Batteries
Printed Batteries Market
Batteries
UAV Battery Pack Market
Batteries
Battery Swapping Market
Batteries
Battery Binders Market
Batteries
Micro Mobility Battery PACK Market
Batteries
Vanadium Redox Flow Batteries (VRFB) Market
Batteries
Europe Automotive Lead-Acid Battery Market
Batteries
Zinc-Manganese Oxide Batteries Market
Batteries
Drone Lithium Battery Charger Market
Batteries
Deep Cycle Battery Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
Global Industrial Battery Market
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market