
 Egypt Rice Market | 2026-2036
Egypt Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Rice Market Foresight
Multi-source sourcing from smallholder cooperatives is realigning how millers secure paddy volumes across Upper and Lower Egypt. Edfina Company for Rice Cultivation and Milling leverages backward integration into farming estates to lock in supply quality. GEFCO For Rice Mills S.A.E anchors its position through capital-intensive milling infrastructure in the Delta region. Lotus Food Industries competes on export-grade processing certifications that unlock Gulf and European buyers.
Egyptian rice comprises Oryza sativa cultivars adapted to Nile irrigation, with long-grain varieties typically measuring 6.6–7.5 mm pre-cooking length and exhibiting intermediate amylose content suited to parboiling and canning applications. The crop serves as a dietary staple for domestic households and as a processed input for regional food manufacturers. Extra Long Grain and Parboiled grades within the Quality Grade segment command premium positioning due to their suitability for institutional catering and re-export. The End User segment tilts toward Exporters and Food Manufacturers as these buyers absorb surplus production beyond subsistence consumption.
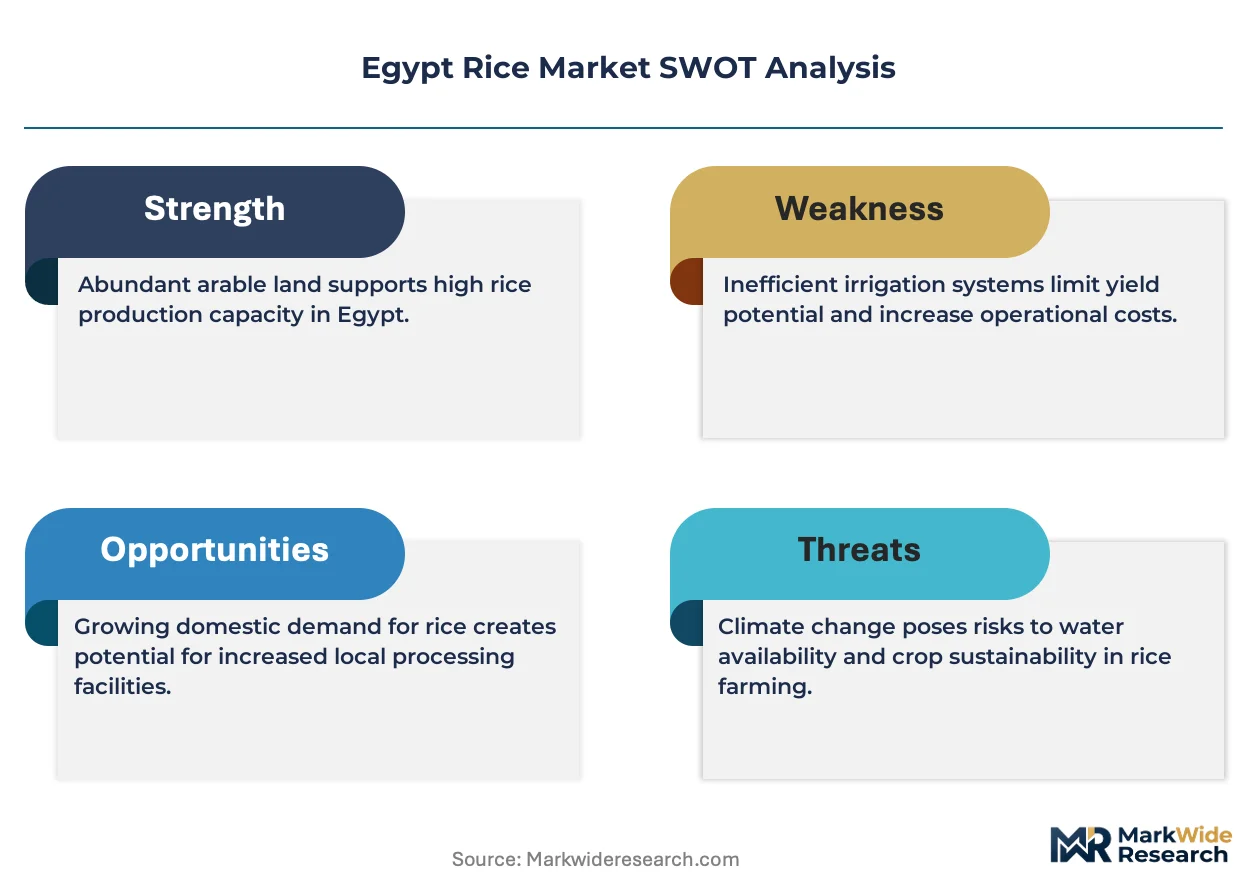
The Ministry of Agriculture and Land Reclamation sets planting quotas and seed certification rules that directly constrain acreage allocation between rice and strategic alternatives like wheat. BIS-equivalent national standards for milled rice moisture content and broken-grain thresholds determine market access for local millers and export eligibility. Stakeholders must monitor water allocation decisions under the Nile water framework and anticipate how climate-driven supply volatility will reshape procurement terms between cooperatives and commercial mills.
Market Dynamics
Water allocation decisions under the Nile water framework are compressing planting windows and forcing millers to renegotiate procurement terms with Upper Egypt cooperatives ahead of each growing season.
Growth Catalysts
- Hybrid seed mandates:The Ministry of Agriculture and Land Reclamation's crop rotation policies are redirecting acreage toward higher-yield certified varieties, expanding recoverable paddy volumes per hectare.
- Processed food demand:Food manufacturers across the Nile Delta are scaling parboiled rice procurement for canned and ready-meal applications, creating pull-through for long-grain cultivars.
- Export certification pathways:Gulf and European buyers are qualifying Egyptian mills against BIS-equivalent moisture and broken-grain standards, unlocking premium channel access.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings tied to import dependency are squeezing margins for smallholder cooperatives in Sharqia and Dakahlia governorates.
- Supply concentration risk:Milling capacity clusters heavily in the Delta region, creating geographic vulnerability to Nile flooding and infrastructure bottlenecks.
- Substitution pressure:Wheat and strategic alternatives compete for limited irrigated acreage under ministry planting quotas, capping rice expansion potential.
Strategic Opportunities
- Upper Egypt underpenetration:Sohag and Qena governorates hold untapped paddy volumes where cooperative formalization could integrate smallholders into commercial supply chains.
- Institutional catering channels:Extra Long Grain grades suited to food service and re-export are gaining traction in Saudi and UAE procurement tenders.
- Digital traceability integration:Blockchain-enabled origin verification is emerging as a compliance tool for European buyers demanding supply chain transparency.
Industry Challenges
- Skill gaps in quality control:Milling operations lack trained technicians for moisture management and broken-grain sorting to meet export-grade thresholds.
- Capex intensity for modernization:Parboiling and color-sorting equipment upgrades require capital that cooperative-owned mills struggle to access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Rice Market |
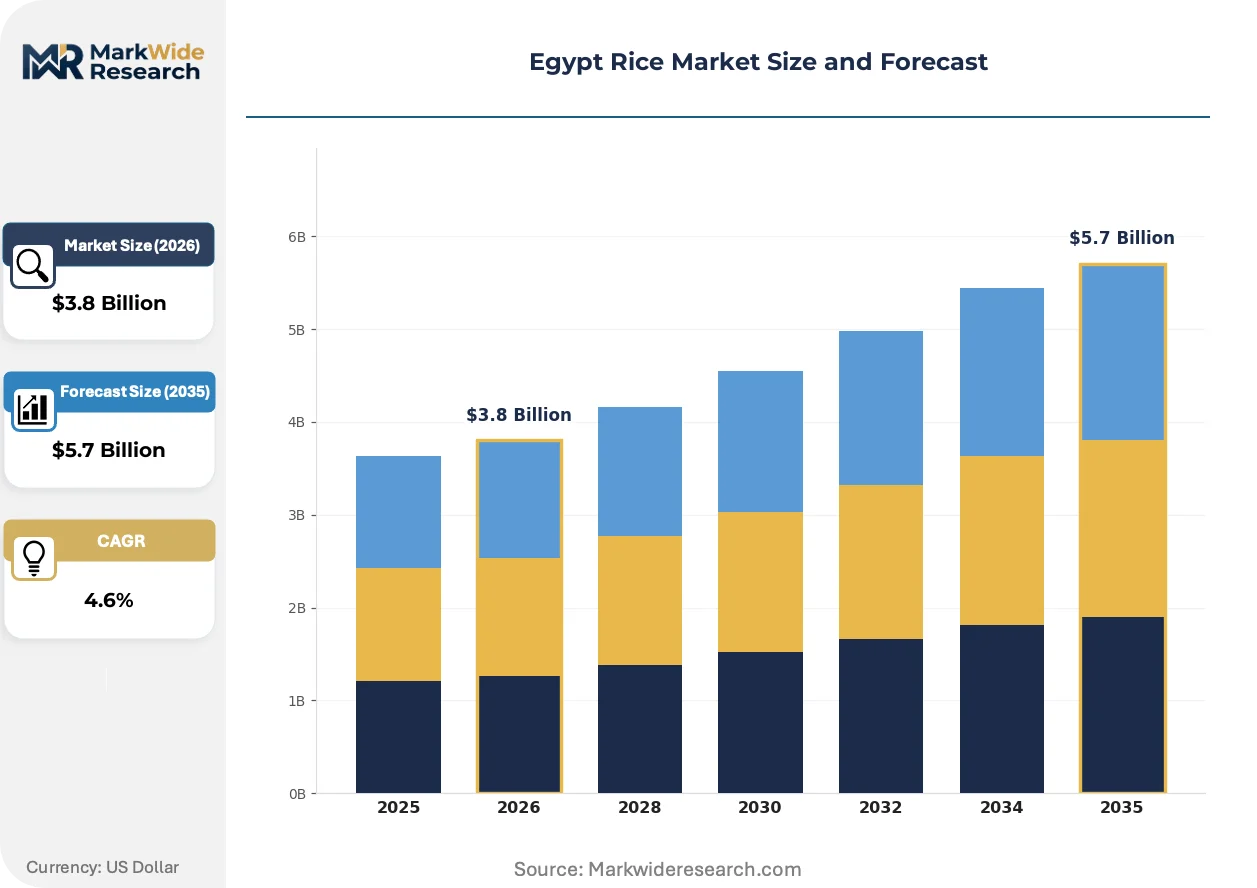
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long Grain, Short Grain, Jasmine, Basmati End User: Households, Restaurants, Food Manufacturers, Exporters Distribution Channel: Online Retail, Supermarkets, Wholesale Markets, Local Grocers Quality Grade: Extra Long Grain, Medium Grain, Parboiled, White Rice |
| Companies Covered | Lotus Food Industries, GEFCO For Rice Mills S.A.E, Egyptian Group Company for Agriculture and Food Industries, Tiamin Rice Company (Egypt), GAFCO Crops S.A.E, Edfina Company for Rice Cultivation and Milling, Modern Food Industries, Mira Exp, El Shams Rice Mills, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Rice Market Shifts & Advancements
Mechanization and digital traceability are converging to reshape how Egyptian rice moves from field to export terminal, with implications for quality consistency and buyer verification.
Optical sorting technology is automating defect detection and grade separation at Delta milling facilities. Large-scale processors in Sharqia Governorate are deploying these systems to reduce manual inspection labor and compress rejection rates for export batches. The capital barrier is automating competitive access to Gulf and European buyers who mandate consistent broken-grain thresholds.
The Ministry of Agriculture and Land Reclamation's seed certification framework is tightening genetic purity requirements for hybrid varieties. This regulatory compression is disqualifying uncertified planting material and consolidating supplier relationships around state-approved distributors. Smallholders in Kafr El Sheikh are responding by joining cooperatives that aggregate certification compliance costs.
Direct contracting between Delta millers and retail chains is displacing traditional wholesale auction channels in Cairo and Alexandria. Food manufacturers and supermarket buyers are negotiating multi-season supply agreements that specify moisture content and delivery schedules. This channel shift is most visible in domestic premium segments where traceability and consistent supply outweigh spot-market price flexibility.
Egypt Rice Market Segmentation
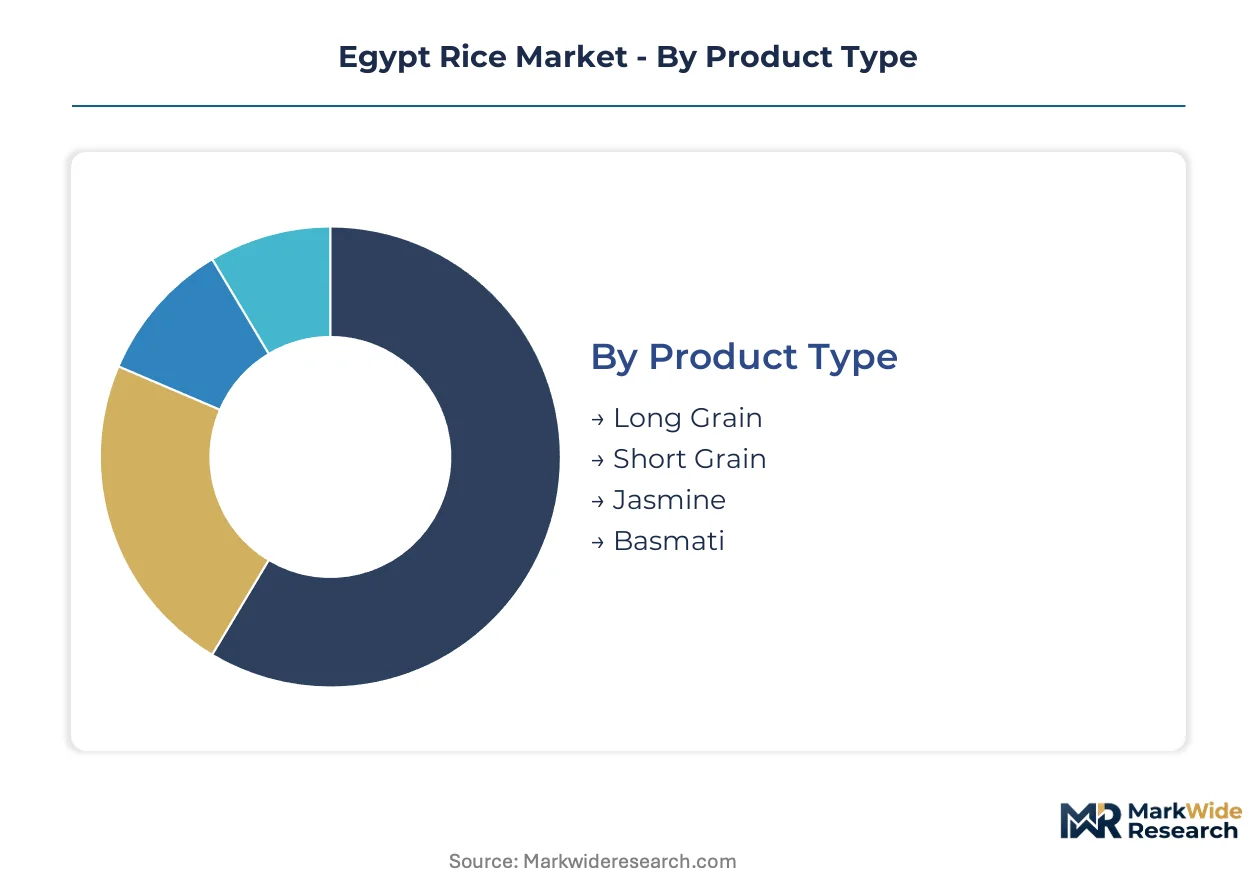
Egyptian rice procurement patterns diverge sharply between subsistence channels and industrial offtake, with quality grades and distribution pathways determining margin capture for millers. Segmentation clarity exposes where Delta milling clusters compete on volume versus where premium positioning unlocks export certification.
Product Type:
Long-grain cultivars dominate embedded food manufacturing applications, while specialty aromatic varieties serve standalone retail and foodservice positioning.
- Long Grain:Measuring 6.6–7.5 mm pre-cooking length with intermediate amylose content, this cultivar suits parboiling and canning lines across Nile Delta processing facilities. Food manufacturers in Sharqia Governorate anchor procurement here for institutional catering and re-export formulations.
- Short Grain:Higher moisture retention and softer cooked texture characterize this segment, concentrated in domestic household consumption and local restaurant channels where stickier mouthfeel commands preference.
- Jasmine:Aromatic profile drives premium retail placement in Cairo and Alexandria supermarket chains.
- Basmati:Limited cultivation under Egyptian conditions restricts volumes to niche import-substitution positioning.
Volume placements concentrate in Long Grain; the faster expansion belongs to Jasmine as urban retail premiumization accelerates.
End User:
Customer type determines contract structure, with food manufacturers and exporters demanding multi-season supply agreements while households transact through spot markets.
- Food Manufacturers:Delta-based processors of canned meals and ready-to-eat products specify moisture content and broken-grain thresholds in procurement contracts. Parboiled rice absorption by this segment is climbing the fastest as regional foodservice outsourcing expands.
- Exporters:Gulf and European buyers qualify Egyptian mills against BIS-equivalent standards, creating pull-through for certified Extra Long Grain volumes from Sharqia milling clusters.
- Households:Price-sensitive domestic consumers source through local grocers and wholesale markets with minimal quality premium.
- Restaurants:Foodservice operators in Cairo and Alexandria prioritize consistent cooking performance over origin certification.
Margin capture concentrates with Exporters; the steepest volume trajectory sits with Food Manufacturers as processed rice demand deepens.
Distribution Channel:
Channel selection maps directly to buyer sophistication, with digital and modern retail demanding traceability that traditional wholesale cannot supply.
- Supermarkets:Carrefour, Spinneys, and local chains in Cairo and Alexandria are displacing wholesale auctions through direct miller contracting that specifies delivery schedules and moisture guarantees.
- Online Retail:Jumia and local e-grocery platforms aggregate fragmented household demand, though cold-chain limitations constrain fresh milled rice penetration.
- Wholesale Markets:Traditional auction channels in Cairo and Alexandria retain price-sensitive bulk transactions.
- Local Grocers:Neighborhood stores in Upper Egypt governorates serve unbanked rural households with minimal packaging differentiation.
Supermarket volumes lead current placement; Online Retail is gaining share fastest as urban digital payment adoption spreads.
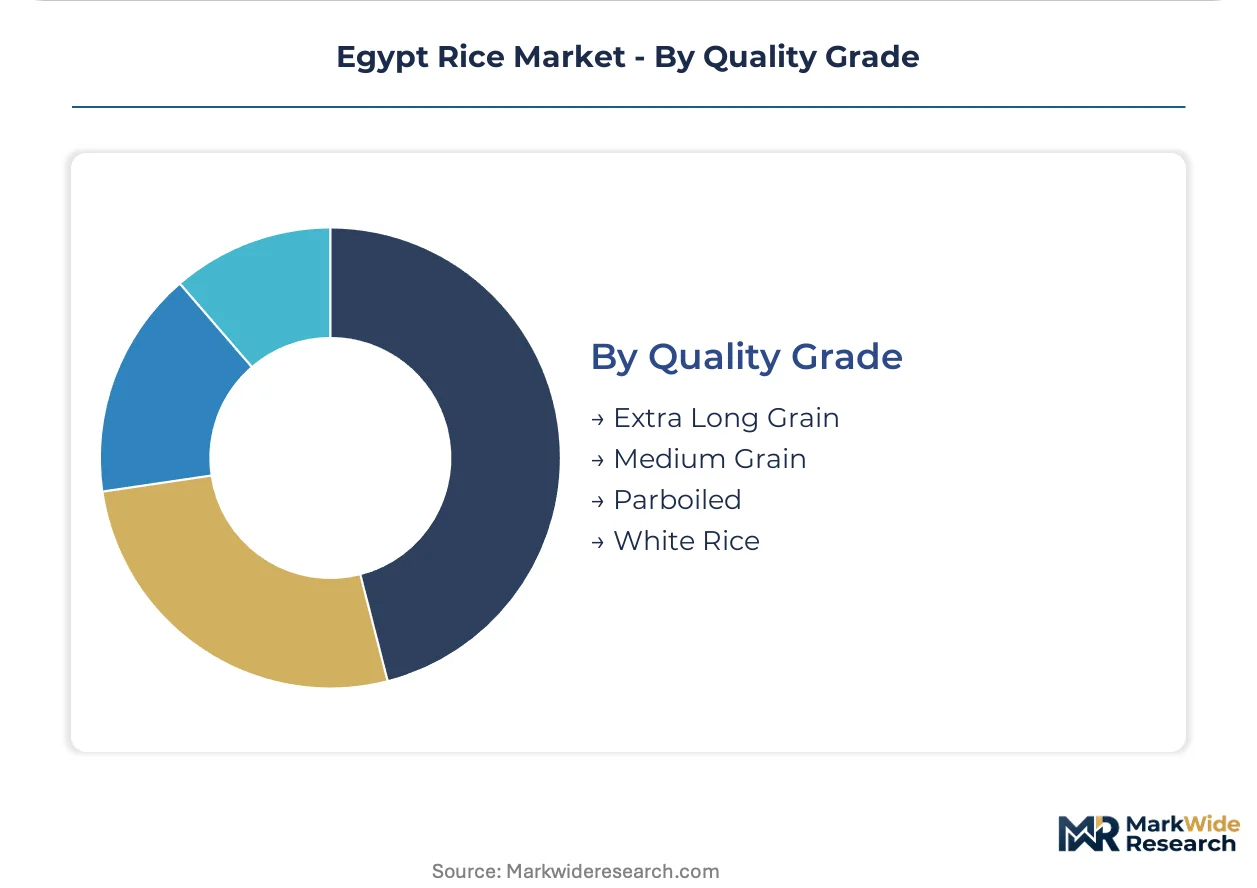
Quality Grade:
Grade stratification separates commodity rice from certified export streams, with processing intensity determining final channel eligibility.
- Extra Long Grain:Premium cultivars meeting 7.5 mm+ length specifications command institutional catering and Saudi procurement tender positioning. Color-sorting and optical grading investments by Delta millers concentrate here.
- Parboiled:Pre-cooking gelatinization delivers shelf stability and reduced breakage, aligning with food manufacturer requirements for canned and retort applications. The segment shows strongest expansion as regional processed food investment scales.
- Medium Grain:Intermediate positioning serves domestic retail price tiers without export certification overhead.
- White Rice:Standard milled product dominates commodity wholesale and local grocer channels.
White Rice holds volume concentration; Parboiled climbs fastest as industrial offtake deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic demand for processed rice concentrates in the Nile Delta governorates, where milling infrastructure and food manufacturing clusters align with population density and export logistics.
Sharqia Governorate
Food manufacturers in Sharqia absorb the largest share of long-grain paddy for parboiling and canning applications. The Ministry of Agriculture and Land Reclamation enforces crop rotation mandates that redirect acreage toward certified hybrid seeds. Milling clusters in Zagazig and Belbeis serve both domestic retail chains and Gulf export channels through BIS-equivalent quality certifications.
Dakahlia Governorate
Smallholder cooperatives in Dakahlia supply paddy to Delta-based processors under multi-season contracting arrangements. Input cost volatility for fertilizer and fuel squeezes margins for these cooperatives. Mansoura anchors a secondary milling hub where optical sorting investments are compressing broken-grain rates for export-grade batches.
Kafr El Sheikh Governorate
Kafr El Sheikh holds the densest concentration of rice cultivation acreage under Nile irrigation. Seed certification requirements under the Ministry of Agriculture and Land Reclamation are consolidating supplier relationships around state-approved distributors. Smallholders are responding by formalizing cooperative structures to aggregate compliance costs and secure miller offtake agreements.
Sohag Governorate
Sohag represents the most significant underpenetrated paddy source in Upper Egypt, with cooperative formalization lagging behind Delta benchmarks. Water allocation decisions under the Nile water framework compress planting windows and force advance procurement negotiations. Local aggregators are emerging to bridge smallholder supply gaps with commercial millers in Lower Egypt.
Alexandria Port Zone
Export qualification and re-export logistics concentrate at Alexandria, where European and Gulf buyers inspect containerized shipments against moisture and broken-grain thresholds. The port's cold storage and fumigation infrastructure determines seasonal export capacity. Millers in nearby Beheira Governorate prioritize Alexandria-bound logistics over Cairo wholesale channels for premium grades.
Egypt Rice Market Competitive Landscape
Backward integration into farming estates dominates the current landscape as millers seek supply security amid water allocation uncertainty. The vendor base spans state-linked agricultural enterprises, privately held milling groups, and cooperative-owned processors with varying capital access. Three archetypes define positioning: estate-integrated operators controlling cultivation through captive land, capital-intensive processors deploying optical sorting and parboiling infrastructure, and export-certification specialists qualifying for Gulf and European procurement tenders. Geographic expansion into Upper Egypt cooperatives and technology licensing for traceability systems represent the dominant competitive moves.
Within the estate-integrated tier, Edfina Company for Rice Cultivation and Milling exemplifies backward control over farming operations to lock in paddy quality. GEFCO For Rice Mills S.A.E occupies a capital-intensive position through Delta-based milling infrastructure investments. Lotus Food Industries anchors the export-certification specialist archetype, representing mills that prioritize European and Gulf buyer qualification pathways.
| Leading Market Players |
|---|
| Lotus Food Industries |
| GEFCO For Rice Mills S.A.E |
| Egyptian Group Company for Agriculture and Food Industries |
| Tiamin Rice Company (Egypt) |
| GAFCO Crops S.A.E |
| Edfina Company for Rice Cultivation and Milling |
| Modern Food Industries |
| Mira Exp |
| El Shams Rice Mills |
| Others |
Supply & Pricing Matrix
Food manufacturer procurement specifications for moisture content and broken-grain thresholds are compressing acceptable quality bands and forcing Delta millers to invest in optical sorting infrastructure that raises processing costs. This specification tightening propagates backward into paddy procurement premiums and cooperative certification requirements.
Pricing Analysis
Volume placements concentrate in White Rice commodity tiers where thin margins reflect spot-market competition among Sharqia milling clusters. Premium-mid-economy pricing differentiation separates Extra Long Grain and Parboiled certifications from standard grades, with export eligibility and BIS-equivalent compliance as the primary value drivers. Cost compression in commodity tiers is intensifying because fertilizer and fuel import dependency squeezes smallholder cooperatives. Households transacting through local grocers exhibit highest price sensitivity; Gulf and European exporters demonstrate lowest sensitivity due to certification-locked supply agreements.
Supply Chain Analysis
Workforce availability constraints in Kafr El Sheikh and Dakahlia governorates limit technician recruitment for moisture management and optical grading operations. Supply concentrates in the Nile Delta region where Zagazig and Belbeis milling clusters anchor processing capacity, while Sohag and Qena in Upper Egypt remain underdeveloped. Raw material flows draw from hybrid seed estates, smallholder cooperative aggregations, and state-certified distributors. Single-source vulnerability runs through Nile water allocation decisions that compress planting windows. Distribution runs through Alexandria Port Zone for export-grade batches and Cairo wholesale channels for domestic commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical sorting automation is displacing manual inspection labor across Delta milling facilities and redefining competitive access to premium buyer segments. This technology transition favors capital-intensive processors over cooperative-owned operations.
For Market Incumbents: To counter margin compression from input cost volatility, Edfina-style backward integration into farming estates locks in paddy quality and reduces procurement negotiation frequency. GEFCO-style capital deployment into parboiling and color-sorting equipment captures food manufacturer contract flows that specify technical thresholds. Certification investment represents the priority lever for maintaining export channel access. For New Entrants and Emerging Players: E-commerce platform partnerships with Jumia and local e-grocery aggregators offer lowest-friction customer acquisition for branded Jasmine and specialty aromatic rice. Sohag and Qena cooperative formalization presents the most penetrable geography where local aggregators bridge supply gaps with commercial millers. Direct-to-retail contracting with Carrefour and Spinneys bypasses wholesale auction margin erosion. For Investors and Strategic Acquirers: The window for entry favors estate-integrated operators with captive land and existing BIS-equivalent certifications over greenfield milling projects. Long-term viability rests on water security positioning under Nile framework negotiations and climate adaptation infrastructure. Watch for Ministry of Agriculture planting quota adjustments as the inflection signal for acreage reallocation between rice and strategic alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Estates | Captive paddy supply from Kafr El Sheikh estates reduces quality variance and procurement cost volatility. |
| Optical Sorting Infrastructure Deployment | Automated defect detection at Zagazig facilities compresses rejection rates for Gulf export batches. |
| Export Certification Pathway Investment | BIS-equivalent qualification unlocks European and Saudi procurement tender participation. |
| Cooperative Formalization Programs | Structured aggregation in Sohag integrates smallholders into commercial supply chains. |
| Digital Traceability Platform Integration | Blockchain-enabled origin verification satisfies European buyer compliance requirements. |
Research Methodology
Independent corroboration across milling operations executives, agricultural cooperative managers, and food manufacturer procurement leads underwrites the qualitative findings presented in this study. Primary fieldwork engaged Delta-based processors, Ministry of Agriculture officials, and Alexandria Port Zone logistics operators. Secondary validation drew from customs export records, BIS-equivalent standards documentation, and Nile water framework allocation announcements. Bottom-up paddy volume estimates from governorate-level cultivation data triangulate against top-down milling capacity assessments across Sharqia and Dakahlia clusters.
Rate-of-change decomposition separates volume growth from price realization effects across the projection horizon. Segmentation modeling incorporates product type, quality grade, end user, and distribution channel dimensions with regional governorates as the geographic stratifier. CAGRs derive from trend extrapolation of hybrid seed adoption curves, processed food demand coefficients, and export certification penetration rates. Water allocation scenarios and climate volatility inputs stress-test baseline projections.
The model holds under stable Nile water quota enforcement and continued hybrid seed mandate compliance; deviation in ministry planting quota reallocations or severe flood events would shift recoverable paddy estimates. Forecasts reflect assumptions regarding cooperative formalization velocity and optical sorting capital deployment timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Barley Grass Market
Grains
India Rice Market
Grains
Soya Flour Market
Grains
Grain Storage Systems Market
Grains
North America Rice Market
Grains
North America Wheat Market
Grains
Global Precooked Corn Flour Market
Grains
Tunisia Grain Market
Grains
Grain Augers Market
Grains
Rye Market
Grains
Africa Maize Market
Grains
Asia-Pacific Guar Market
Grains
Torrified Wheat Market
Grains
Masa Corn Products Market
Grains
Green Banana Flour Market
Grains
Organic Rice Market