
 IQF Rice Market | 2026-2036
IQF Rice Market Size, Share, and Industry Trends Forecast 2026-2036
IQF Rice Market Foresight
Specialized cryogenic engineering talent is redrawing competitive boundaries in IQF rice manufacturing as blast-freezing and fluidized-bed expertise becomes scarce. Riviana Foods leverages its North American milling infrastructure to sustain domestic supply security. Olam International Limited anchors global sourcing networks across multiple rice-growing basins. Ebrofrost Denmark A/S specializes in European cold-chain logistics and portion-controlled formats for food service clients.
Individually quick frozen rice consists of cooked grains flash-frozen at temperatures below minus forty degrees Celsius to preserve texture, prevent clumping, and enable direct reheating without thawing. The process employs tunnel freezers or spiral blast systems with core temperature monitoring to maintain amylopectin stability and mouthfeel parity with freshly prepared rice. Basmati and Jasmine varieties command premium positioning in retail pouches due to aromatic differentiation and ethnic cuisine proliferation. Bulk containers dominate food service procurement where restaurants and catering operations prioritize throughput over unit branding. Online distribution channels represent the fastest-expanding access point as direct-to-kitchen platforms displace traditional wholesaler relationships.
The US FDA enforces Hazard Analysis Critical Control Point protocols for frozen prepared foods while USDA grading standards influence rice quality specifications entering IQF processing. EU regulations under EFSA and national food safety authorities mandate strict cold-chain documentation and additive limitations that shape export formulations. Stakeholders must monitor evolving freezer technology costs and shifting food service labor economics to calibrate capacity investments against end-user migration patterns.
Market Dynamics
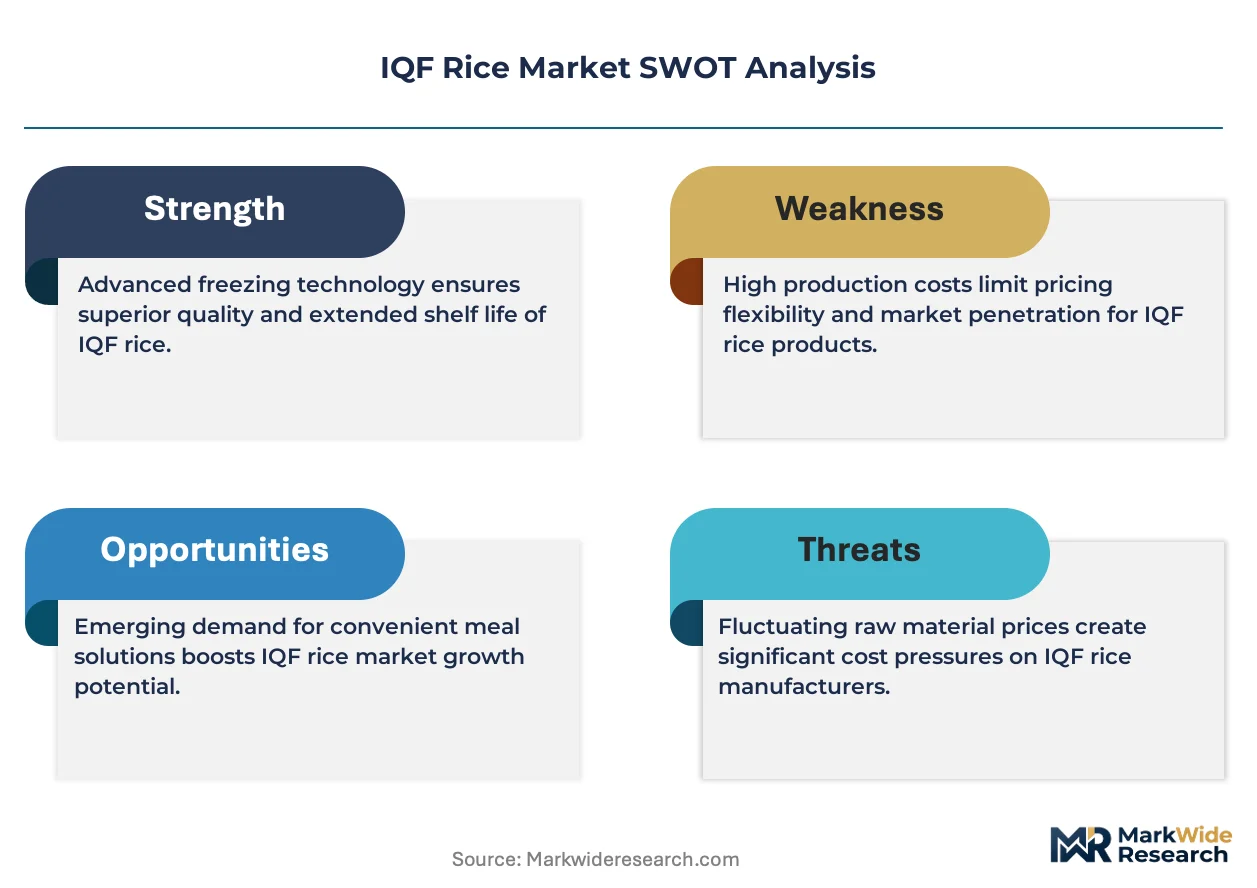
Food service labor economics and cryogenic freezing capital intensity are colliding to restructure capacity deployment across IQF rice manufacturing. Operators face pressure to automate while cold-chain infrastructure gaps limit geographic expansion.
Growth Catalysts
- USDA Grade Standards:Federal rice quality specifications create procurement transparency that accelerates institutional food service adoption of pre-cooked frozen formats.
- Blast-Freezing Automation:Tunnel freezer throughput gains reduce unit labor requirements below levels achievable with traditional batch cooling methods.
- Quick-Service Chains:Central kitchen consolidation across US restaurant networks generates demand for portion-controlled, retherm-stable rice components.
Market Restraints
- Natural Gas Price Volatility:Cryogenic nitrogen production and blast-freezing operations expose processors to energy cost swings that compress margin predictability.
- Specialized Equipment Concentration:Spiral freezer and fluidized-bed system manufacturing concentrates among German and Japanese engineering firms, creating supply bottlenecks.
- Fresh-Prepared Substitution:Regional rice cooker leasing programs in Southeast Asian food service markets offer lower capital barriers than frozen inventory buildouts.
Strategic Opportunities
- US Inflation Reduction Act Energy Credits:Cold-chain facility retrofits qualify for federal efficiency incentives that offset cryogenic system capital requirements.
- Direct-to-Kitchen Platforms:Restaurant procurement aggregators are supplanting traditional broadline distributors for mid-size independent operators.
- Jasmine Varietal Expansion:Aromatic rice segments remain underpenetrated in European food service relative to Basmati saturation in UK and Nordic markets.
Industry Challenges
- Cryogenic Engineering Talent Scarcity:Fluidized-bed thermal dynamics expertise and ammonia refrigeration certification pipelines lag equipment deployment timelines.
- HACCP Documentation Burden:FDA frozen food safety protocols demand continuous core-temperature logging that strains legacy quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IQF Rice Market |
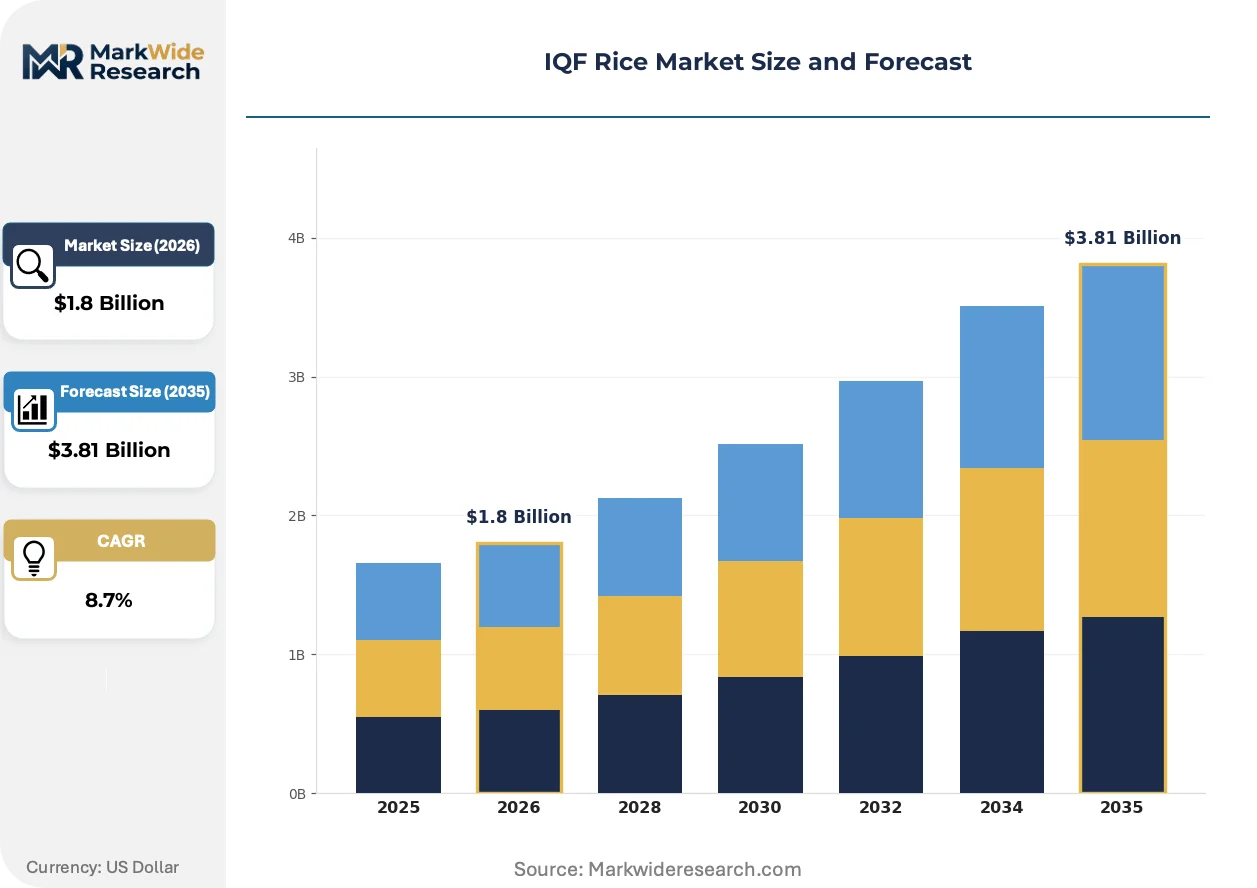
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Long Grain, Jasmine, Basmati, Arborio Packaging Type: Bags, Boxes, Pouches, Bulk Containers End User: Restaurants, Food Service, Retail, Catering Distribution Channel: Online, Supermarkets, Wholesalers, Distributors |
| Companies Covered | Riviana Foods, Turri’s Italian Foods, China National Cereals, Oils and Foodstuffs Corporation, Charoen Pokphand Foods Public Company Limited, Olam International Limited, KRBL Limited, Ebrofrost Denmark A/S, Simplot Company, Ardo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IQF Rice Market Shifts & Advancements
Processing technology convergence and procurement platform digitization are restructuring how IQF rice moves from mill to kitchen. Three developments dominate competitive positioning.
Spiral blast freezers with real-time amylopectin crystallization monitoring are supplanting conventional tunnel systems in new capacity installations. US contract manufacturers serving quick-service chains are adopting these systems fastest, compressing equipment replacement cycles from ten-year norms toward seven-year intervals as throughput efficiency becomes a bidding differentiator.
EU F-Gas Regulation phase-down schedules are forcing refrigerant transitions across European cold-chain infrastructure. Ammonia-CO2 cascade systems are emerging as the compliant pathway, affecting IQF rice export processing economics from non-EU origins. Danish and Dutch port facilities are responding with infrastructure retrofit programs that add handling cost premiums for non-compliant supply origins.
Food service buyers are consolidating purchase authority into procurement cooperatives that aggregate volume across independent restaurant groups. These platforms displace traditional broadline distributor relationships in the US Northeast and Pacific Northwest, compressing price discovery cycles and demanding SKU rationalization from processors.
IQF Rice Market Segmentation
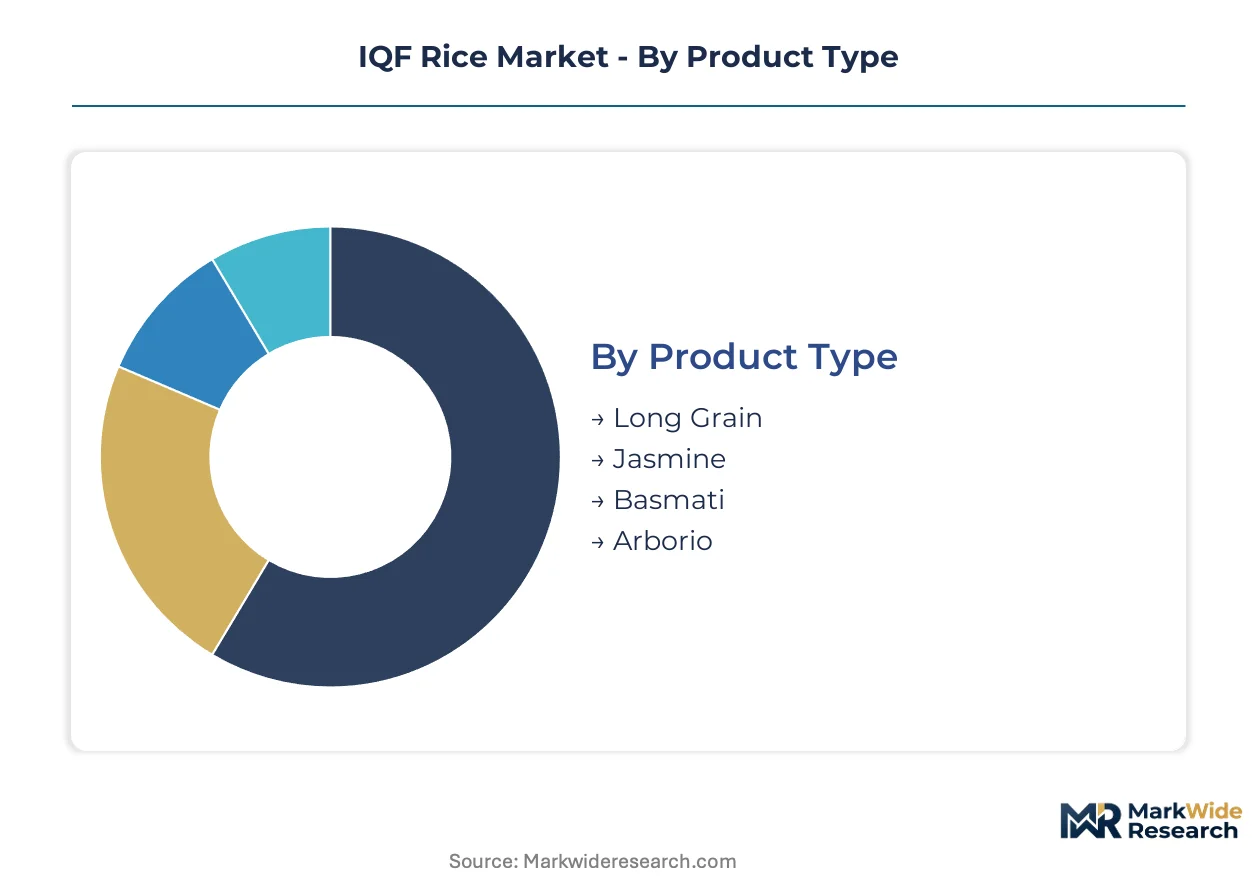
IQF rice processors configure product lines around thermal stability requirements and reheating protocols that vary sharply by end-use channel. Packaging and distribution investments follow divergent margin structures across food service and retail pathways.
Product Type:
Channel-mix patterns show Basmati and Jasmine commanding premium shelf placement in retail while Long Grain dominates institutional procurement for retherm consistency.
- Long Grain:Medium-amylose structure maintains individual grain separation after blast-freezing and microwave reheating. US quick-service chains and institutional kitchens concentrate procurement here due to neutral flavor profiles that accommodate sauce pairings.
- Basmati:Elongated grains with low amylopectin content resist retrogradation during freeze-thaw cycles. UK and Nordic retail markets drive premium positioning, though aromatic saturation limits expansion in continental European food service.
- Jasmine:Sticky texture profile suits Southeast Asian cuisine applications with direct-to-kitchen platform penetration accelerating.
- Arborio:High amylopectin ratio optimized for risotto reconstitution in Italian-focused restaurant chains.
By volume, Long Grain leads. By growth pace, Jasmine is ahead.
Packaging Type:
Cost tier stratification separates portion-controlled formats for labor-intensive kitchens from bulk configurations for high-throughput operations.
- Bulk Containers:10-20 kg polyethylene-lined totes minimize per-unit packaging cost for central kitchen consolidation. US contract manufacturers serving multi-unit restaurant groups prioritize this format where throughput economics override branding requirements.
- Pouches:Vacuum-sealed retail formats with steam-venting films enable direct microwave preparation. Online grocery platforms and meal-kit aggregators are expanding pouch SKU counts fastest.
- Bags:Standard retail polyethylene formats for conventional supermarket distribution.
- Boxes:Corrugated secondary packaging for food service distributor palletization efficiency.
By volume, Bulk Containers dominate. By margin expansion, Pouches are climbing the fastest.
End User:
Application requirements split between retherm-stable food service specifications and convenience-oriented retail preparation formats.
- Food Service:Central kitchen and commissary procurement demands core-temperature consistency across batch reheating equipment. HACCP documentation requirements from FDA frozen prepared food protocols shape supplier qualification processes.
- Restaurants:Independent operators and small chains prioritize portion control and waste reduction over unit cost minimization.
- Retail:Supermarket and online grocery channels emphasize preparation speed claims and ethnic cuisine positioning.
- Catering:Event-based volume with seasonal demand spikes and holding-time flexibility requirements.
By volume, Food Service leads. By channel migration, Restaurants are gaining share fastest.
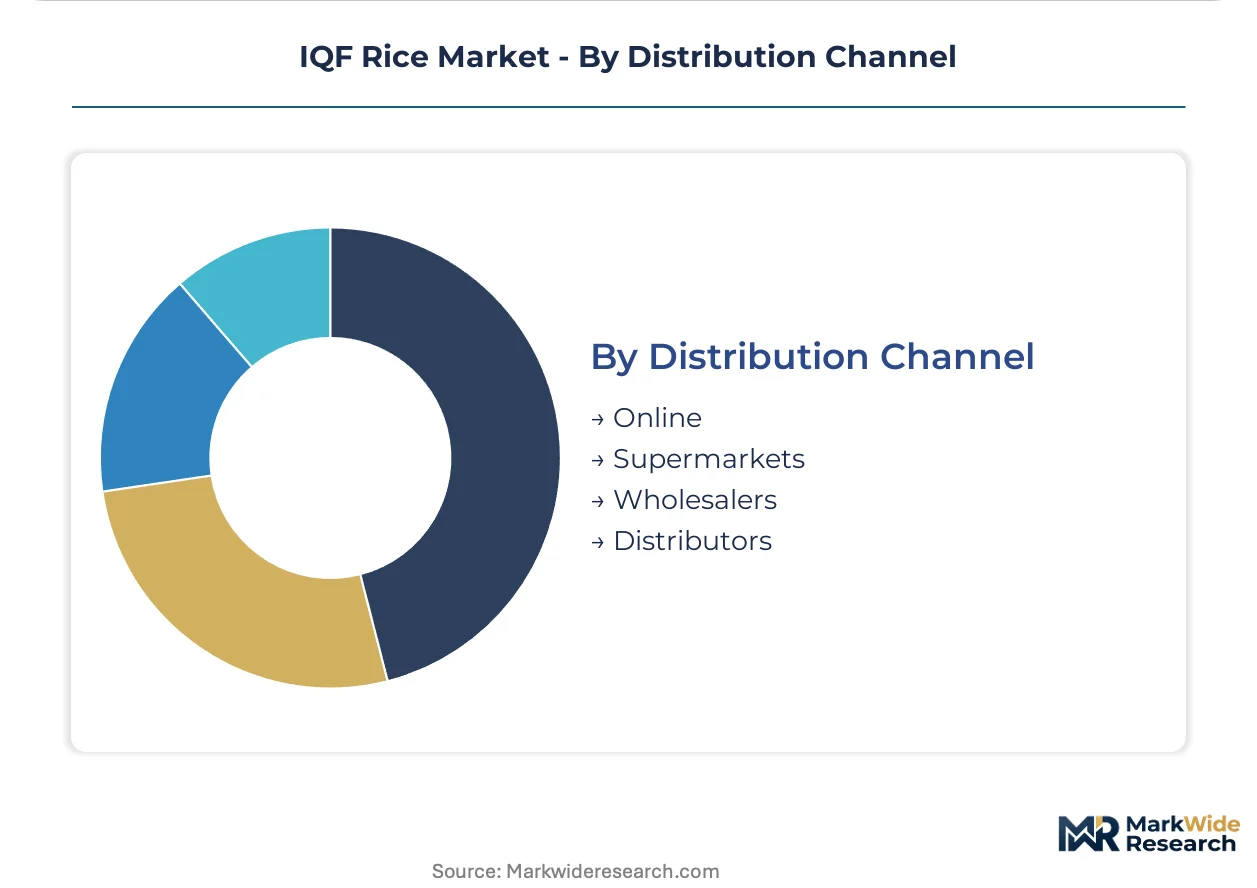
Distribution Channel:
Customer type concentration determines whether procurement flows through traditional broadline infrastructure or direct platform relationships.
- Wholesalers:Broadline distributors maintain inventory depth for multi-category food service procurement with established credit terms and delivery scheduling.
- Online:Direct-to-kitchen platforms and procurement cooperatives aggregate independent restaurant demand with compressed price discovery cycles.
- Supermarkets:Conventional retail grocery with slotting fee structures and promotional calendar dependencies.
- Distributors:Specialized frozen food distributors with cold-chain certification for institutional accounts.
By volume, Wholesalers lead. By expansion trajectory, Online is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature food service markets and emerging retail channels. The United States concentrates procurement in bulk formats for quick-service central kitchens, while European buyers emphasize cold-chain compliance and aromatic varietals. Asian markets split between institutional procurement in urban corridors and fresh-prepared substitution in Southeast Asian food service.
United States
Quick-service chains and institutional kitchens drive volume through portion-controlled procurement. FDA HACCP protocols for frozen prepared foods shape supplier qualification requirements. The Midwest and Southeast manufacturing corridors host blast-freezing capacity clusters serving national restaurant networks.
Germany
Food service distributors prioritize cold-chain documentation under EU F-Gas Regulation phase-down schedules. EFSA additive limitations and ammonia-CO2 cascade system mandates influence processing investments. The Port of Hamburg anchors refrigerated logistics infrastructure for continental distribution.
United Kingdom
Retail channels dominate Basmati procurement for ethnic cuisine positioning in supermarket formats. National food safety authority cold-chain standards exceed baseline EU requirements. Greater London distribution hubs concentrate pouch-format inventory for online grocery fulfillment.
Thailand
Jasmine rice IQF processing serves Southeast Asian restaurant chains and export-oriented direct-to-kitchen platforms. The country's national food safety regulator enforces frozen food standards aligned with Codex Alimentarius frameworks. Bangkok metropolitan area cold-storage capacity expansion supports regional food service consolidation.
Denmark
Portion-controlled formats for European food service clients concentrate procurement through specialized cold-chain logistics. Danish Veterinary and Food Administration frozen food protocols mandate continuous temperature monitoring. Copenhagen-Arhus corridor facilities specialize in retherm-stable rice components for Nordic institutional markets.
IQF Rice Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in IQF rice manufacturing. The upper tier combines milling infrastructure with captive freezing capacity, while specialists concentrate on single-origin sourcing or regional cold-chain logistics. Three archetypes dominate: diversified agribusiness conglomerates with upstream grain control, frozen food specialists with equipment expertise, and commodity traders with logistics networks. Competitive moves center on backward integration into milling assets and geographic expansion through distributor partnerships.
Among diversified agribusiness players, Olam International Limited exemplifies the upstream-control archetype through its multi-basin sourcing networks. Riviana Foods occupies a position representing North American milling-integrated supply security. Ebrofrost Denmark A/S sits within the specialist tier, anchoring European cold-chain expertise for food service portion-control formats.
| Leading Market Players |
|---|
| Riviana Foods |
| Turri's Italian Foods |
| China National Cereals, Oils and Foodstuffs Corporation |
| Charoen Pokphand Foods Public Company Limited |
| Olam International Limited |
| KRBL Limited |
| Ebrofrost Denmark A/S |
| Simplot Company |
| Ardo Group |
| Others |
Supply & Pricing Matrix
USDA Grade Standards and FDA HACCP certification simultaneously gate supplier qualification and enable price premiums for compliant processors serving institutional food service buyers. Contract structures stratify across long-term offtake agreements with quick-service chains, project-based spot procurement for catering events, and rolling annual contracts for retail distributors. Three-tier pricing separates aromatic varietal premiums from standard long-grain baselines and economy bulk formats, with differentiation anchored in thermal stability certification and cold-chain documentation. Cost compression in economy tiers intensifies because natural gas volatility feeds directly into cryogenic nitrogen production economics. Quick-service chains exhibit lowest price sensitivity due to labor-cost substitution value, while independent restaurants negotiate hardest on per-unit packaging costs.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships with multi-unit restaurant groups, locking volume commitments against price stability guarantees that spot markets cannot match. Price differentiation rests on amylopectin crystallization certification and retherm consistency metrics that institutional buyers mandate in supplier scorecards. Margins are tightening due to specialized equipment lead times stretching capacity deployment timelines. Food service procurement cooperatives demonstrate highest price sensitivity through aggregated bidding platforms, while premium retail pouch formats sustain markup tolerance from convenience-seeking household buyers.
Supply Chain Analysis
Inventory cycles compress toward just-in-time delivery windows as blast-freezing capacity constraints in the United States, Thailand, and Denmark force buyers to accept shorter lead-time commitments. Raw material flows draw from Arkansas long-grain basins, Thai Jasmine cultivation zones, and Indian Basmati export corridors. Single-source vulnerability concentrates in German and Japanese spiral freezer engineering firms that control equipment availability. Distribution runs through specialized frozen food distributors with cold-chain certification rather than conventional broadline infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across procurement platform architectures creates niche entry points as direct-to-kitchen aggregators displace traditional distributor relationships. Independent restaurant groups now source through cooperative structures that reward specialized portion-control capabilities over scale economies.
For Market Incumbents: Secure captive milling assets in North American rice basins to defend against Olam International's multi-origin sourcing flexibility. Lock in ammonia-CO2 cascade system retrofits ahead of EU F-Gas Regulation phase-down deadlines to maintain continental export eligibility. Reinforce equipment engineering partnerships with Japanese and German freezer manufacturers to preempt capacity bottlenecks.
For New Entrants and Emerging Players: Direct-to-kitchen platform under-service in the US Northeast and Pacific Northwest offers white-space entry with lower customer acquisition costs than national distributor penetration. Jasmine varietal processing for Southeast Asian restaurant chains represents the most penetrable segment given aromatic saturation limits in European Basmati markets. Lead with HACCP documentation automation as a qualification accelerator for institutional accounts.
For Investors and Strategic Acquirers: EU F-Gas Regulation enforcement reshapes the acquisition landscape toward processors with compliant cold-chain infrastructure already deployed. Five-to-ten-year viability favors milling-integrated operators with captive freezing capacity over pure-play logistics specialists. Watch ammonia refrigeration certification pipeline throughput as the signal indicating whether equipment deployment timelines will widen competitive moats or compress them.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Milling Assets | Captive grain supply secures USDA Grade Standard compliance for institutional procurement qualification. |
| Cold-Chain Infrastructure Retrofit | Ammonia-CO2 cascade systems satisfy EU F-Gas Regulation mandates for continental market access. |
| Direct-to-Kitchen Platform Partnership | Procurement cooperative relationships displace broadline distributor intermediation in US regional markets. |
| Aromatic Varietal Processing Expansion | Jasmine capacity addresses underpenetrated Southeast Asian cuisine segments in European food service. |
| Blast-Freezing Automation Investment | Tunnel freezer throughput gains compress labor requirements below batch cooling economics. |
Research Methodology
Desk research of customs trade databases, USDA crop production reports, and FDA frozen food guidance documents preceded structured interviews with quick-service chain procurement directors, cryogenic equipment engineering specialists, cold-chain logistics operators, and rice mill quality assurance managers. Primary fieldwork validated secondary findings through facility assessments of blast-freezing installations across US Midwest and Southeast manufacturing corridors. Bottom-up volume modeling triangulated against top-down expenditure analysis from institutional food service budget disclosures.
Variance decomposition across product type, packaging format, end-user channel, and distribution pathway segmentation dimensions anchored the analytical framework over the projection horizon. CAGRs derived from slope-consistent growth trajectory fitting against historical procurement volume patterns. Industry-specific forecast inputs incorporated natural gas price scenario modeling and quick-service chain central kitchen consolidation timelines.
Forecasts assume regulatory continuity in FDA HACCP enforcement and EU F-Gas Regulation phase-down schedules; material policy shifts would require re-modeling of compliance cost burdens and export eligibility thresholds. Cryogenic engineering talent scarcity and equipment manufacturing concentration represent specific risk factors that could revise capacity expansion assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Cornmeal Market
Grains
Africa Maize Market
Grains
Quinoa Flour Market
Grains
Paraguay Grains Market
Grains
Torrified Wheat Market
Grains
South America Rice Market
Grains
Uganda Grains Market
Grains
North America Oats Market
Grains
Argentina Maize Market
Grains
South Africa Maize Market
Grains
Soya Flour Market
Grains
Rice Flour Market
Grains
Durum Wheat Flour Market
Grains
Precooked Flour Market
Grains
Asia Pacific Wheat Protein Market
Grains
GMO Corn Market