
 Brazil Maize Market | 2026-2036
Brazil Maize Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Maize Market Outlook
Integrated grain-processor bundling of logistics, storage, and forward-contracting is consolidating buyer choice around full-service origination platforms. Bunge Global SA leverages its Santos port terminal network to anchor export flows. Cargill Inc. sustains inland crushing capacity through Mato Grosso processing complexes. Louis Dreyfus Company B.V. competes via river-barge integration along the Tapajós-Amazon corridor.
Maize comprises the dried kernel of Zea mays L., typically harvested at moisture content below 15.5 percent and classified by end-use protein profiles, oil content, and hardness indices for dry-milling or wet-milling suitability. Feed grade maize dominates volume throughput, with industrial grade gaining traction from fermentation-based ethanol and bioplastics offtake. Food grade channels command premium pricing through identity-preserved segregation, while seed represents a specialized margin pool tied to varietal licensing and phytosanitary certification.
ANVISA governs maximum mycotoxin thresholds for food-grade maize, while the national biosafety regulator, CTNBio, approves transgenic cultivar releases that shape seed sector composition. MAPA, the agriculture ministry, enforces grain quality standards and export phytosanitary protocols that determine market access timing. Stakeholders must track how CTNBio's stacked-trait approval velocity and MAPA's silo inspection digitization alter origination economics and contract structuring.
Market Dynamics
CTNBio's stacked-trait GMO approval velocity is compressing seed varietal substitution cycles while tightening origination compliance burdens across Mato Grosso and Goiás grain belts. This regulatory cadence is forcing processors to restructure forward-contracting terms and silo certification workflows.
Growth Catalysts
- Ethanol co-processing expansion:Fermentation-based ethanol offtake from industrial-grade maize is accelerating as biorefineries in São Paulo and Minas Gerais scale capacity. This pulls additional volume through Center-West origination channels.
- ANVISA mycotoxin enforcement:Stricter maximum thresholds for aflatoxin and fumonisin in food-grade channels are driving identity-preserved segregation investments. Premium pricing for certified lots expands processor margins.
- Tapajós-Amazon waterway integration:River-barge logistics corridors are reducing export cost differentials for northern Mato Grosso producers. This unlocks Santos port access for volumes previously trapped in high-cost truck hauls.
Market Restraints
- Input cost volatility:Fertilizer import dependence exposes Mato Grosso growers to urea and potash price swings tied to Black Sea supply disruptions. Margins compress when input spikes coincide with harvest price dips.
- Supply concentration risk:Silo infrastructure clusters around Sorriso and Lucas do Rio Verde create origination bottlenecks during peak harvest windows. Limited alternative storage forces price-taking behavior.
- Regulatory friction:CTNBio's case-by-case stacked-trait review timelines delay varietal commercialization by 18-24 months versus single-trait approvals. Seed developers face revenue recognition lags.
Strategic Opportunities
- Underpenetrated geography:Bahia's western expansion zone offers untapped acreage with growing water infrastructure. Early-mover processors can anchor origination before competitor silo networks arrive.
- Regulatory tailwind:MAPA's silo inspection digitization mandate creates first-mover advantage for operators with integrated traceability systems. Real-time certification data reduces contract settlement friction.
- Technology convergence:Satellite imagery fused with soil sensor networks enables variable-rate input application. Precision agriculture adoption lifts yields in degraded Cerrado patches.
Industry Challenges
- Certification timeline compression:CTNBio's evolving GMO documentation requirements force seed developers to maintain parallel regulatory dossiers. Compliance staff scarcity extends approval cycles.
- Capex intensity:Identity-preserved segregation infrastructure demands dedicated silo cells and cleaning systems. Food-grade channel entry requires capital outlays that strain mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Maize Market |
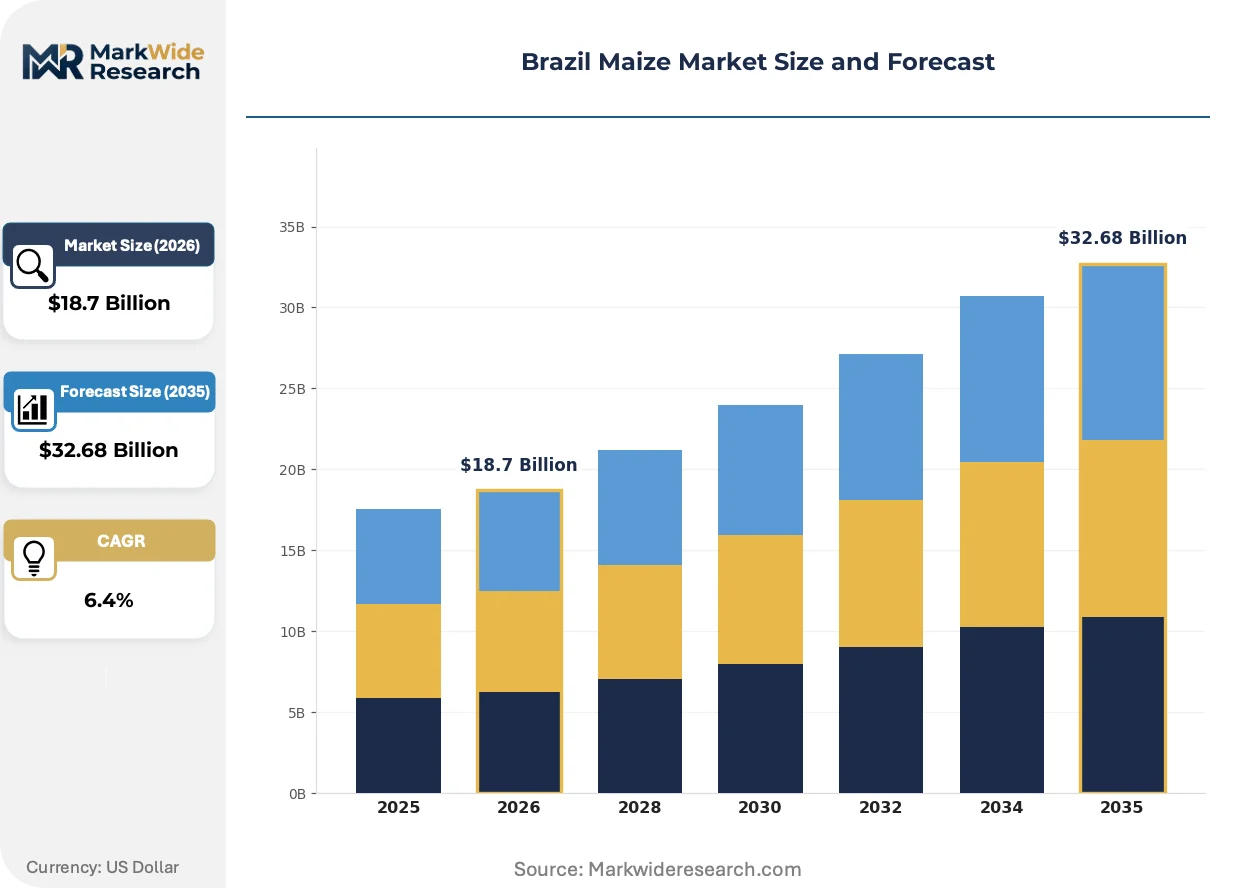
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feed Grade, Food Grade, Industrial Grade, Seed End Use Industry: Animal Feed, Food Processing, Bioplastics, Alcohol Production Distribution Channel: Wholesalers, Retailers, Online Sales, Direct Sales Application: Livestock Feed, Flour Production, Fermentation, Snack Manufacturing |
| Companies Covered | Bunge Global SA, Cargill Inc., Archer-Daniels-Midland (ADM), Louis Dreyfus Company B.V., COFCO Corporation, Amaggi Group, SLC Agricola S.A., Corteva Agriscience, Syngenta Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Maize Market Strategic Shifts
Digital traceability platforms are rewiring how origination quality is verified and priced. This shift is compressing information asymmetries between farmgate and export terminal while enabling new contract structures.
Gene-edited drought-tolerance traits are overtaking conventional transgenic approaches in breeder pipelines. These edits reduce water input requirements by 15-20 percent without triggering CTNBio's GMO classification thresholds. Large-scale growers in Goiás are piloting these varieties ahead of commercial release. The technology is overtaking stacked-trait hybrids in marginal rainfall zones where irrigation access remains limited.
MAPA's grain quality standard harmonization with Mercosur protocols is reducing cross-border friction for Brazilian exports. This alignment enables single-inspection clearance for shipments entering Argentina and Uruguay. Food-grade processors in Paraná are restructuring procurement to capture simplified phytosanitary documentation. The policy shift most affects seed exporters seeking regional varietal licensing.
Buyer concentration among integrated protein processors is consolidating origination negotiation leverage. Large feed compounders in Santa Catarina are unbundling logistics services from grain purchases. Independent truck cooperatives are displacing processor-captive fleets on key haul routes. This pattern is most visible in the southern corridor where pork and poultry integration density is highest.
Brazil Maize Market Segmentation
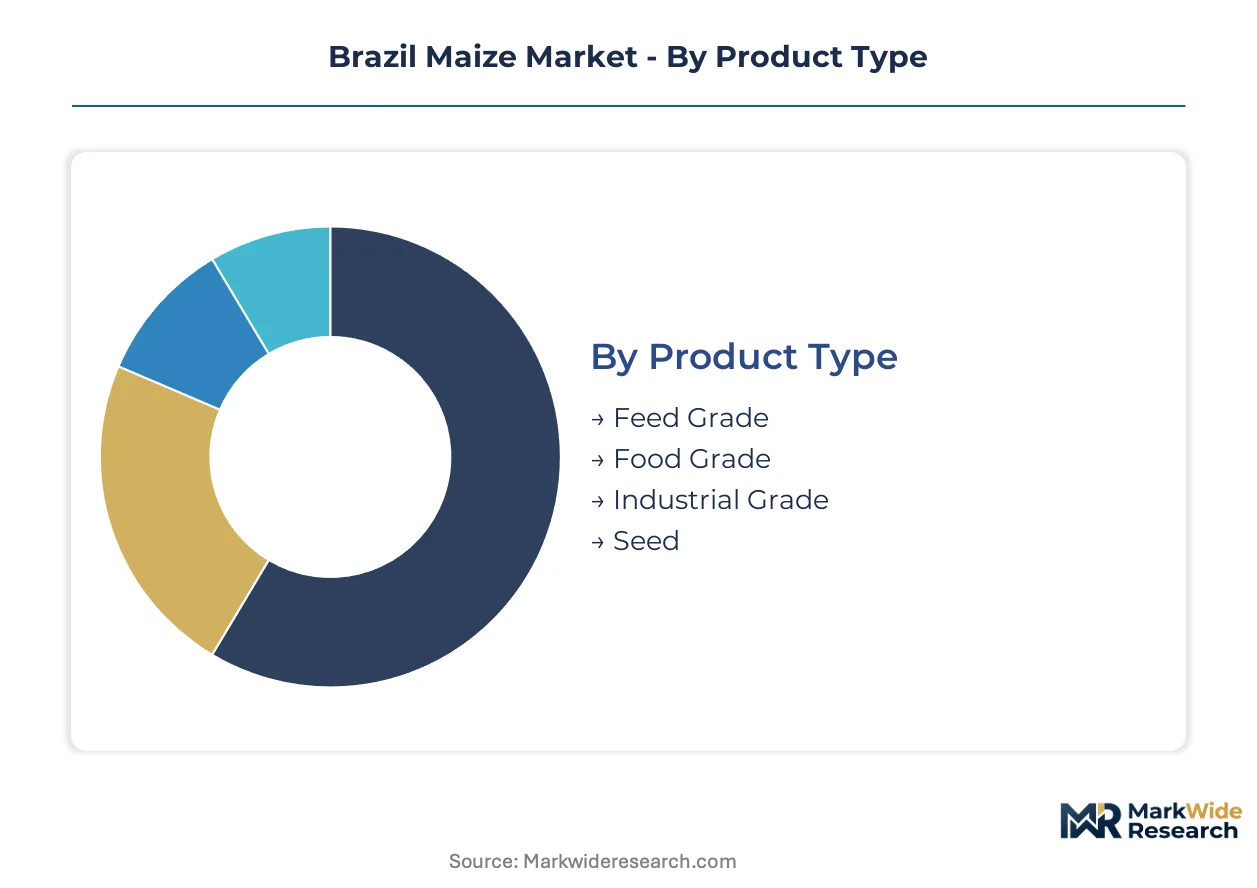
Maize segmentation in Brazil reflects divergent quality standards and channel economics that reshape processor procurement strategies. ANVISA mycotoxin thresholds and CTNBio certification requirements force distinct handling protocols across each product tier.
Product Type:
Upgrade cycles in seed genetics and industrial processing technology are fragmenting procurement specifications across Brazilian grain belts.
- Feed Grade:Standard protein profiles and hardness indices serve poultry, swine, and cattle operations in Santa Catarina and Paraná. Mato Grosso processors bundle feed-grade origination with logistics to capture integrated protein processor demand.
- Food Grade:Identity-preserved lots meet ANVISA aflatoxin and fumonisin thresholds below 20 ppb and 2000 ppb respectively. Segregated silo infrastructure in Paraná commands premium pricing from flour millers and snack manufacturers.
- Industrial Grade:Starch content and fermentation suitability specifications supply São Paulo ethanol biorefineries.
- Seed:Phytosanitary certification and varietal licensing terms govern CTNBio-approved trait stacks for commercial multiplication.
Feed grade sits at the top of the volume ranking, with industrial grade climbing the fastest.
End Use Industry:
Margin concentration varies sharply by downstream processing intensity and regulatory compliance burden.
- Animal Feed:Compounders in the southern corridor unbundle logistics from grain purchases to reduce procurement costs. Independent truck cooperatives displace processor-captive fleets on key haul routes.
- Food Processing:Identity-preserved channels demand dedicated cleaning systems and silo cells that strain mid-scale processor capital budgets.
- Bioplastics:Fermentation-derived polylactic acid offtake is expanding from industrial-grade feedstock.
- Alcohol Production:São Paulo and Minas Gerais biorefineries pull additional Center-West volume through co-processing capacity.
Animal feed dominates origination throughput, while bioplastics is gaining share fastest.
Distribution Channel:
Channel selection reflects buyer scale, certification requirements, and geographic access to silo infrastructure.
- Wholesalers:Aggregate farmgate production across Sorriso and Lucas do Rio Verde clusters for onward sale to processors.
- Retailers:Serve smallholder and specialty seed markets with bagged product and technical support.
- Online Sales:Digital platforms are compressing information asymmetries between farmgate and export terminal.
- Direct Sales:Large Mato Grosso growers contract forward with Bunge, Cargill, and Louis Dreyfus origination platforms.
Direct sales captures the largest volume flow, with online sales expanding most quickly.
Application:
Application-specific quality parameters determine suitability for dry-milling versus wet-milling process economics.
- Livestock Feed:Poultry integration density in Santa Catarina concentrates demand for consistent energy content and digestibility profiles.
- Flour Production:Food-grade hardness indices and moisture specifications below 15.5 percent determine dry-milling yields.
- Fermentation:Starch gelatinization temperatures and protein interference levels affect ethanol conversion efficiency.
- Snack Manufacturing:Expansion characteristics and oil absorption rates command premium lots from identity-preserved channels.
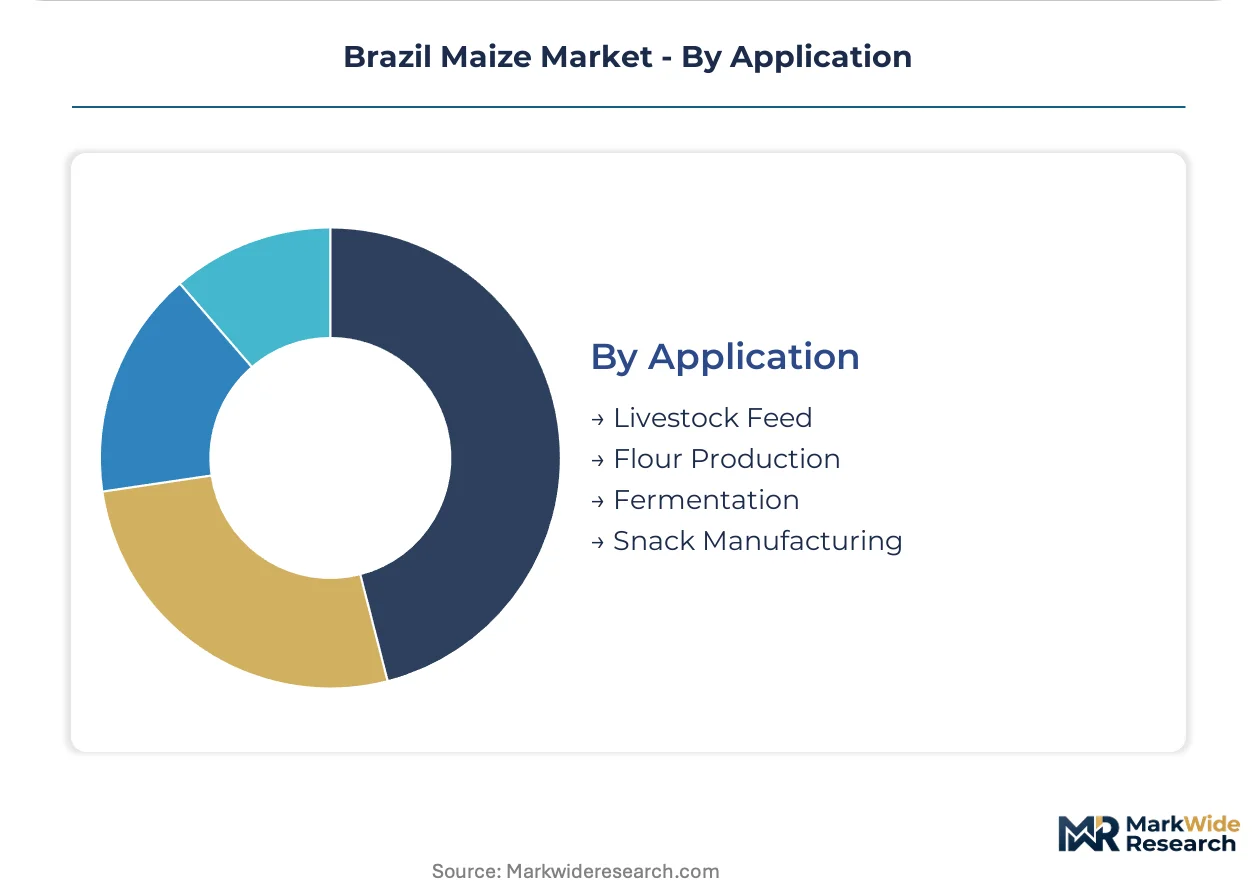
Livestock feed holds the volume lead, with fermentation showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian maize production traces its modern scale to the 1970s Cerrado colonization, when state-backed agricultural research converted acidic savanna into viable farmland. The Center-West grain belt now anchors national output.
Mato Grosso
Poultry integration and ethanol biorefinery offtake drive procurement volumes across Sorriso and Lucas do Rio Verde clusters. CTNBio's stacked-trait GMO certification requirements tighten origination compliance for seed developers and processors. Silo infrastructure concentration around these municipalities creates seasonal bottlenecks during peak harvest windows.
São Paulo
Fermentation-based ethanol demand from industrial-grade maize accelerates biorefinery capacity expansion in the state. ANVISA mycotoxin thresholds for food-grade channels remain less relevant here than in southern corridors. The state's processing complexes pull Center-West volumes through forward-contracting arrangements with Mato Grosso growers.
Paraná
Identity-preserved segregation for flour millers and snack manufacturers commands premium pricing in food-grade channels. MAPA's grain quality standards enforcement shapes export phytosanitary documentation workflows. Silo operators in western Paraná invest in dedicated cleaning systems to capture ANVISA-certified lot premiums.
Minas Gerais
Alcohol production facilities expand co-processing capacity alongside existing sugarcane ethanol infrastructure. The state's central location enables sourcing flexibility from both Center-West and southeastern production zones. Biorefinery operators negotiate directly with large-scale growers for industrial-grade feedstock supply.
Bahia
Western expansion zones offer untapped acreage with improving water infrastructure for irrigation development. Early-mover processors establish origination platforms before competitor silo networks arrive. The region's distance from established logistics corridors currently limits immediate volume throughput.
Brazil Maize Market Competitive Environment
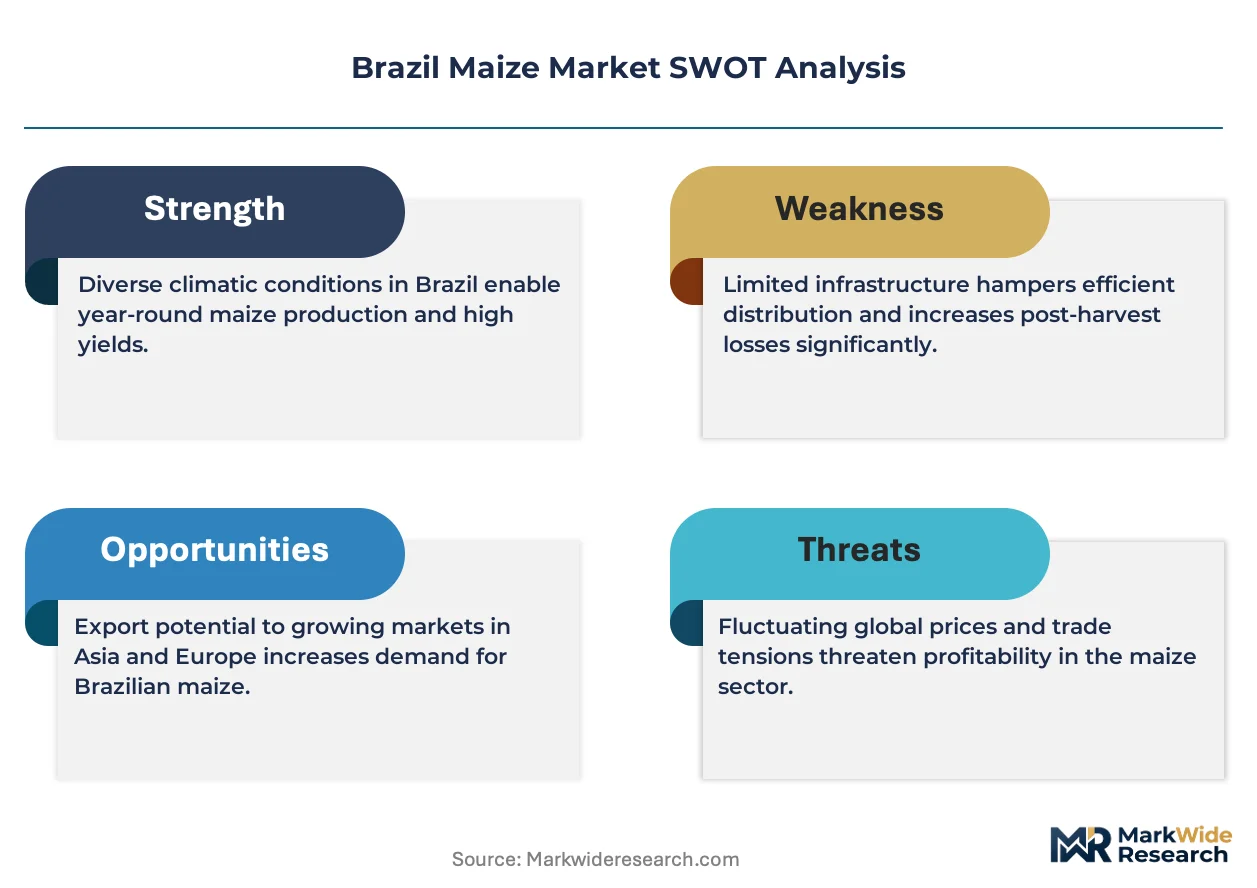
Premium-margin players sit above commodity-margin players across certification intensity and origination integration depth. The vendor base clusters around three strategic tiers: global traders with port terminal networks, domestic processors with crushing capacity, and seed developers with varietal licensing portfolios. Structural consolidation favors operators combining logistics, storage, and forward-contracting capabilities. Dominant competitive moves include geographic origination expansion and regulatory compliance system investments.
Among global trading houses with Brazilian operations, Bunge Global SA, Cargill Inc., and Louis Dreyfus Company B.V. occupy positions defined by infrastructure scale and corridor-specific logistics integration. These entities exemplify the full-service origination platform archetype, anchoring export flows through differentiated access to Santos port terminals, Mato Grosso processing complexes, or Tapajós-Amazon river-barge corridors respectively. Their market presence reflects the premium attached to integrated grain-processor bundling.
| Leading Market Players |
|---|
| Bunge Global SA |
| Cargill Inc. |
| Archer-Daniels-Midland (ADM) |
| Louis Dreyfus Company B.V. |
| COFCO Corporation |
| Amaggi Group |
| SLC Agricola S.A. |
| Corteva Agriscience |
| Syngenta Group |
| Others |
Value Chain & Pricing Dynamics
Grain origination specialists concentrated around Sorriso and Lucas do Rio Verde command wage premiums that compress labor-cost spreads between premium food-grade and standard feed-grade maize tiers. CTNBio certification complexity and MAPA inspection digitization requirements widen pricing differentials as skilled compliance personnel become scarcer across Mato Grosso.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies Brazilian maize markets by certification intensity and channel access. Food-grade lots meeting ANVISA mycotoxin thresholds capture premium spreads over feed-grade baselines, while identity-preserved segregation adds further markup for industrial-grade ethanol feedstock. Price compression runs through standard feed-grade channels as buyer concentration among Santa Catarina protein processors intensifies negotiation leverage. Smallholder cooperatives exhibit highest price sensitivity due to limited forward-contracting access and storage constraints.
Supply Chain Analysis
Direct-to-processor channels handle large-scale grower demand across Mato Grosso and Goiás grain belts, while wholesaler aggregators serve fragmented smallholder bases. Supply concentrates in Brazil's Center-West region, with secondary flows from Paraná and Minas Gerais biorefinery corridors. Raw material dependencies center on urea and potash imports subject to Black Sea supply volatility, plus diesel fuel for truck haul logistics. Single-source vulnerability at Santos port terminals creates chokepoint exposure for export-bound volumes. Distribution runs through integrated origination platforms combining silo storage, forward-contracting, and barge-rail intermodal capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Brazil maize market functions as a stable compounder anchored by fermentation-based ethanol demand from São Paulo and Minas Gerais biorefineries. Structural feed demand from integrated poultry and pork processors provides volume floor stability regardless of commodity price cycles.
For Market Incumbents: Anchor defensive positioning through MAPA silo inspection digitization compliance to capture first-mover certification advantages. Expand crushing capacity in Mato Grosso processing complexes to tighten backward integration into origination channels. Counter independent truck cooperative displacement by embedding logistics services within forward-contracting terms. For New Entrants and Emerging Players: The premium-to-economy price-point gap in food-grade channels offers entry space for mid-scale processors investing in dedicated silo cells and ANVISA-compliant cleaning systems. Target Bahia's western expansion zone before competitor silo networks arrive. Pursue satellite-enabled precision agriculture partnerships with large-scale growers to secure preferential origination access. For Investors and Strategic Acquirers: Valuations sit cheapest among regional processors lacking integrated traceability systems yet positioned to benefit from MAPA digitization mandates. Long-term viability across the analysis window hinges on ethanol co-processing capacity and CTNBio approval pipeline depth. Monitor CTNBio stacked-trait approval velocity as inflection signal for seed sector revenue recognition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origination | Captive supply from Mato Grosso silo networks secures volume throughput for Santos port terminals. |
| MAPA Digitization Compliance Investment | Real-time certification data reduces contract settlement friction for food-grade channel access. |
| Tapajós-Amazon Barge Capacity Expansion | River logistics unlock Santos port access for northern Mato Grosso volumes trapped in high-cost truck hauls. |
| Gene-Edited Trait Pipeline Development | Drought-tolerance varieties bypass CTNBio GMO classification while reducing water input requirements. |
| Identity-Preserved Segmentation Infrastructure | Dedicated silo cells capture ANVISA-certified premiums from flour millers and snack manufacturers. |
Study Parameters
Multiple input streams — grain processor procurement executives, CTNBio regulatory affairs specialists, MAPA inspection coordinators, and Santos port terminal operators — were reconciled against customs trade records, MAPA grain quality bulletins, CTNBio approval registries, and ANVISA mycotoxin enforcement data. Bottom-up volume estimates from Mato Grosso and Goiás origination clusters were cross-validated with top-down ethanol biorefinery demand projections and protein processor feed consumption surveys.
Data-stream reconciliation across the projection horizon employed segmentation modeling by product grade, end-use industry, distribution channel, and regional production cluster. CAGRs were derived from trend extrapolation of origination volumes, ethanol co-processing capacity additions, and export flow trajectories. Forecast inputs incorporated CTNBio approval pipeline velocity, MAPA silo inspection digitization rollout timing, and Black Sea fertilizer supply disruption scenarios.
Caveats apply where CTNBio regulatory timeline compression or MAPA enforcement intensity shifts could materially shift the outlook. Forecasts reflect assumptions regarding ethanol policy continuity and Mercosur phytosanitary harmonization progress. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Organic Oats Market
Grains
Tunisia Grain Market
Grains
Guar Complex Market
Grains
North America Oats Market
Grains
Oat Flour Market
Grains
Africa Wheat Protein Market
Grains
Grain Dryers Market
Grains
Wheat Fiber Market
Grains
Asia Pacific Maize Market
Grains
Brown Rice Market
Grains
Basmati Rice Market
Grains
Rye Market
Grains
Africa Maize Market
Grains
Red Rice Market
Grains
Gluten Feed Market
Grains
Green Pea Grits Market