
 Asia Pacific Maize Market | 2026-2036
Asia Pacific Maize Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Maize Market Outlook
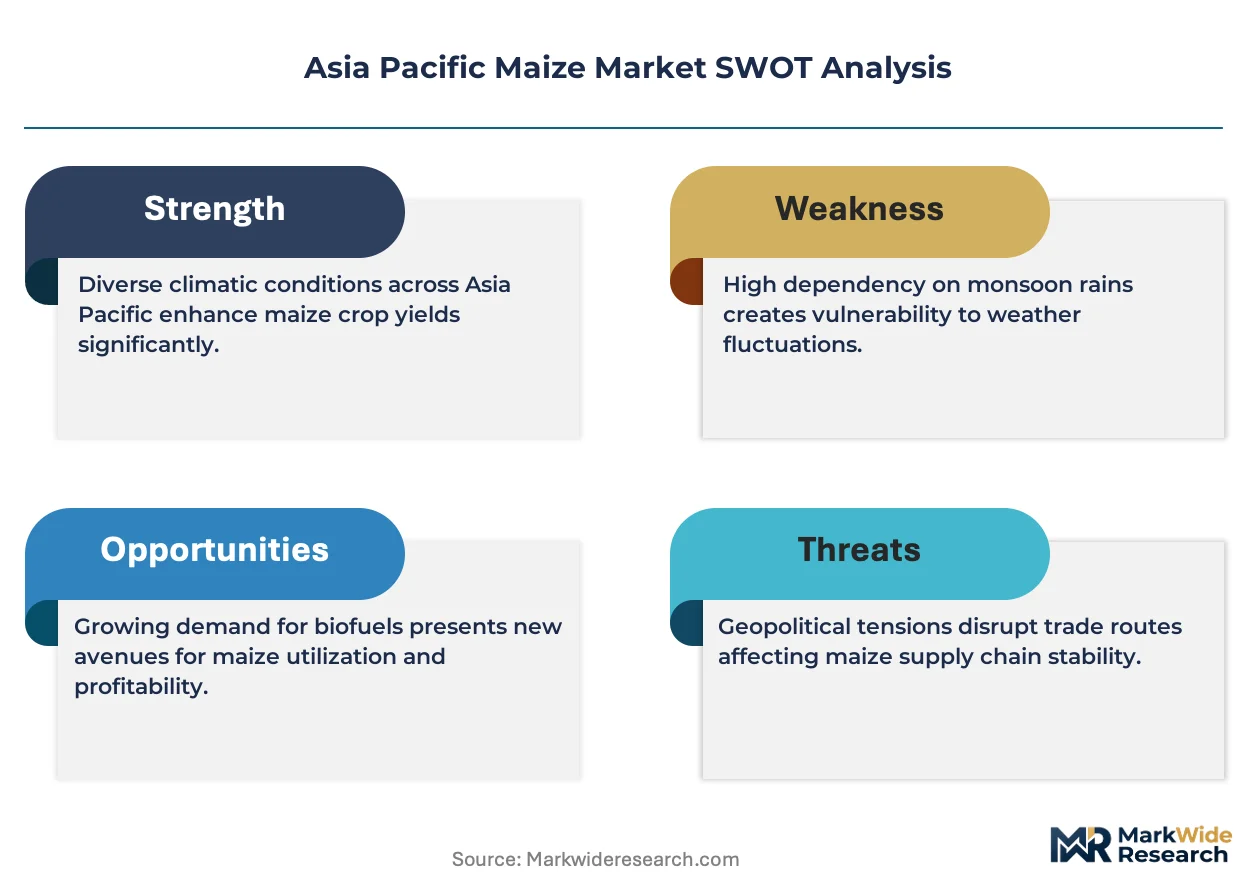
China's GB standards for maize quality and biosafety certification is reorganizing competitive access across the Asia Pacific seed and grain trade. Bayer leverages its molecular breeding platforms to sustain germplasm leadership in tropical hybrid development. Syngenta Group anchors its position through integrated seed-to-grain advisory services across Southeast Asian contract farming networks. Beidahuang Kenfeng Seed Co. Ltd dominates northern China's commercial maize belt with regionally adapted varieties and state-backed distribution infrastructure.
Asia Pacific maize comprises Zea mays cultivars distinguished by kernel texture, color, and endosperm composition, with moisture content, protein levels, and starch amylose ratios determining suitability for food processing, feed formulation, or industrial extraction. Yellow maize occupies the largest volume share due to its dominance in animal feed compounding across Indonesia, Vietnam, and Thailand, where metabolizable energy density drives formulation economics. Sweet maize differentiates through fresh and frozen food processing channels, while starch production commands premium margins in India's Gujarat and Maharashtra processing clusters where food-grade and pharmaceutical-grade specifications tighten procurement criteria.
China's SAMR enforces GB labeling and biosecurity protocols that filter import eligibility and domestic cultivation permits, while India's FSSAI and BIS standards govern food-grade maize derivative specifications for starch and sweetener applications. The EU Green Deal's due diligence requirements on deforestation-linked commodities are reshaping export-oriented sourcing protocols in Indonesia and Malaysia. Stakeholders must monitor how China's dual carbon goals redirect biofuel policy and whether India's PLI scheme for food processing expands maize-based industrial capacity.
Market Dynamics
China's GB standards for grain quality and GMO labeling are reorganizing competitive access across the Asia Pacific seed and grain trade, filtering import eligibility and domestic cultivation permits while industrializing livestock sectors in Vietnam and Indonesia pull procurement volumes upward.
Growth Catalysts
- Industrial Feed Demand:Livestock sector modernization in Vietnam and Indonesia is expanding compound feed production, with metabolizable energy density requirements favoring yellow maize procurement volumes.
- Starch Processing Premiums:India's FSSAI and BIS standards for food-grade and pharmaceutical-grade maize derivatives are tightening procurement criteria in Gujarat and Maharashtra processing clusters, attracting premium contract pricing.
- Biosecurity Certification:China's SAMR enforcement of GB labeling protocols is filtering import eligibility, creating compliant supply chain advantages for certified germplasm providers.
Market Restraints
- Input Cost Volatility:Fertilizer and fuel price fluctuations in Thailand and the Philippines are compressing margins for smallholder contract farming networks.
- Supply Concentration Risk:Northern China's commercial maize belt dominates regional germplasm distribution, creating geographic dependency for tropical hybrid varieties.
- Regulatory Friction:The EU Green Deal's due diligence requirements on deforestation-linked commodities are reshaping export-oriented sourcing protocols in Indonesia and Malaysia, extending compliance timelines.
Strategic Opportunities
- Underpenetrated Geographies:Myanmar and Cambodia present white space for integrated seed-to-grain advisory services as contract farming networks expand beyond Vietnam and Thailand.
- Regulatory Tailwind:India's PLI scheme for food processing may expand maize-based industrial capacity, particularly for modified starch and sweetener derivatives.
- Technology Convergence:Molecular breeding platforms combined with digital farm management tools are enabling precision variety matching to microclimatic zones in Southeast Asia.
Industry Challenges
- Certification Timeline Compression:Biosafety certification for new hybrid varieties under China's GB standards requires extended field trials, delaying commercialization windows.
- Skill Gap in Quality Assessment:Food-grade and pharmaceutical-grade maize derivative specifications demand trained laboratory personnel that remain scarce in emerging processing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Maize Market |
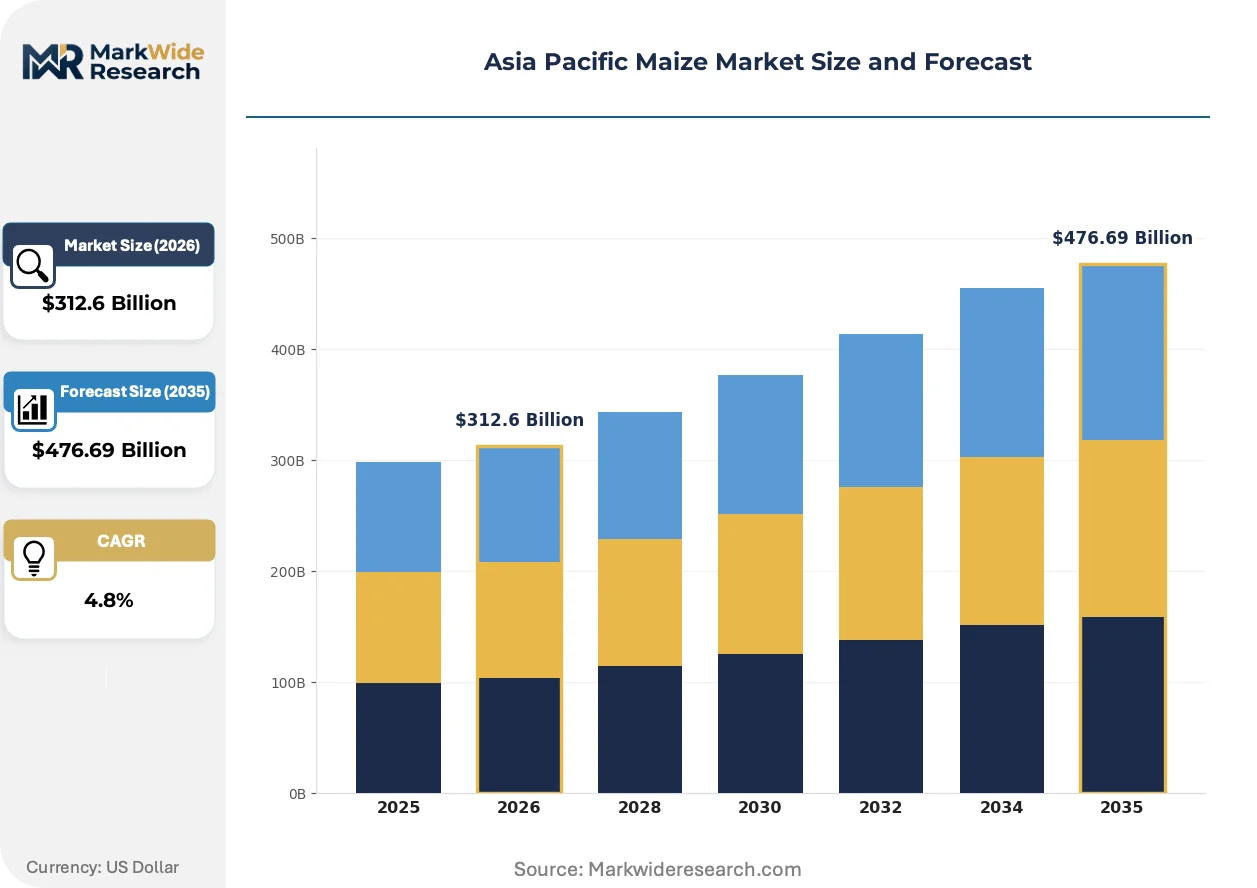
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $476.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yellow Maize, White Maize, Sweet Maize, Flint Maize End Use Industry: Food Processing, Animal Feed, Starch Production, Biofuels Distribution Channel: Direct Sales, Online Retail, Wholesalers, Supermarkets Packaging Type: Bags, Bulk, Boxes, Cans |
| Companies Covered | Corteva Agriscience, Bayer, Syngenta Group, Advanta Seeds - UPL, Beidahuang Kenfeng Seed Co. Ltd, Cargill, BASF, KWS SAAT SE & Co. KGaA, Charoen Pokphand Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Maize Market Strategic Shifts
Molecular breeding platforms and digital advisory systems are compressing variety development cycles while regulatory tightening around biosafety and sustainability credentials is reshaping procurement protocols across the value chain.
Gene editing-assisted molecular breeding is supplanting conventional backcrossing methods for tropical hybrid development. Seed companies in Thailand and Vietnam are adopting these platforms to compress trait introgression timelines from five years to eighteen months. The structural consequence is narrowing germplasm differentiation, as precision trait stacking becomes accessible beyond legacy breeding programs.
China's dual carbon goals are redirecting biofuel policy, with MEE and NDRC coordination tightening sustainability criteria for maize-to-ethanol pathways. Industrial processors are responding by sourcing certified low-carbon intensity feedstock, prioritizing supply chains with documented land-use change credentials. This shift most affects starch processors in Shandong and Jilin provinces, where facility upgrades to meet emission intensity benchmarks require capital deployment.
Contract farming consolidation is compressing procurement relationships toward fewer, larger aggregators with integrated quality assurance capabilities. Smallholder networks in Indonesia and the Philippines are being displaced by nucleus-plasma outgrower schemes that bundle input credit with guaranteed offtake. This pattern is most visible in Vietnam's Central Highlands, where feed millers now source directly from consolidated farming cooperatives rather than spot markets.
Asia Pacific Maize Market Segmentation
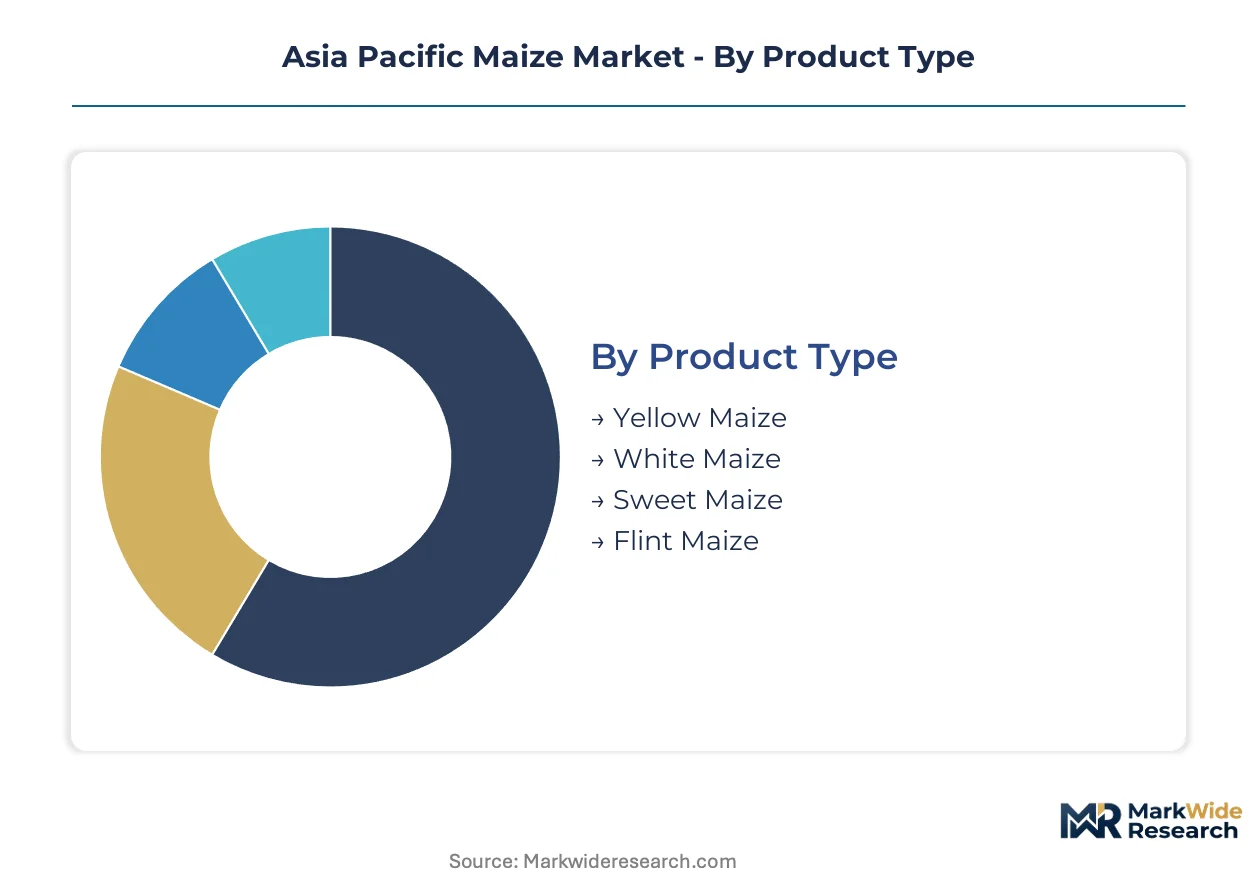
Kernel texture, endosperm composition, and moisture content specifications segment Asia Pacific maize into distinct procurement tiers. Regulatory differentiation across China's GB standards, India's FSSAI protocols, and Vietnam's feed safety requirements shapes how each segment commands price premiums and compliance investment.
Product Type:
Regulatory differentiation across food-grade, feed-grade, and industrial-grade specifications creates divergent certification burdens and margin structures for each cultivar category.
- Yellow Maize:High metabolizable energy density and carotenoid-rich kernel composition make this cultivar the baseline specification for compound feed formulation. Demand concentrates in Vietnam's Central Highlands and Indonesia's East Java feed mill clusters, where industrial livestock operations favor standardized energy content over varietal diversity.
- White Maize:Preferred for human consumption and specific food processing applications due to its neutral color profile and softer endosperm texture. Procurement in Myanmar and Cambodia favors this variety for traditional food products, though export eligibility to China's food processing corridor requires stricter aflatoxin compliance under SAMR protocols.
- Sweet Maize:High sugar content and tender pericarp distinguish this cultivar for fresh and frozen food channels. Thai processors dominate regional supply.
- Flint Maize:Hard endosperm structure delivers superior storage stability and grinding characteristics for industrial applications. Limited cultivation in the Philippines serves niche starch extraction.
Yellow maize handles the majority of throughput; sweet maize is expanding most quickly on share as Thailand's frozen food exports climb.
End Use Industry:
Customer type determines specification stringency, with pharmaceutical-grade and food-grade applications demanding laboratory-verified purity that feed-grade procurement can bypass.
- Animal Feed:Compound feed manufacturers in Indonesia and Vietnam constitute the dominant volume sink, with metabolizable energy density and amino acid profiles driving procurement decisions. Smallholder contract farming networks in the Philippines face margin compression from feed millers' consolidated direct sourcing.
- Starch Production:Gujarat and Maharashtra processing clusters attract premium contract pricing for food-grade and pharmaceutical-grade maize derivatives. FSSAI and BIS standards tighten amylose ratio and protein content specifications, filtering eligible suppliers toward certified farming cooperatives.
- Food Processing:Milling, snack production, and traditional food manufacturing span diverse kernel specifications across India and Southeast Asia.
- Biofuels:China's dual carbon goals redirect policy support toward certified low-carbon intensity feedstock pathways. Shandong and Jilin processors source documented land-use change credentials to meet MEE emission benchmarks.
Animal feed absorbs the largest procurement volumes; starch production delivers the steepest margin expansion trajectory.
Distribution Channel:
Geography shapes channel viability, with infrastructure quality and farm-gate consolidation determining whether direct sales or intermediary networks dominate procurement.
- Direct Sales:Feed millers and starch processors in Vietnam's Central Highlands and India's Gujarat corridor source directly from consolidated farming cooperatives, bypassing spot markets. Nucleus-plasma outgrower schemes bundle input credit with guaranteed offtake, displacing traditional smallholder aggregation.
- Wholesalers:Regional grain traders maintain procurement relationships across Myanmar and Cambodia's less consolidated farming networks. Quality assurance capabilities vary widely.
- Online Retail:Emerging platforms serve specialty sweet maize and packaged flour segments in urban Thailand and Malaysia.
- Supermarkets:Branded packaged maize products reach consumers through modern retail channels in Indonesia's Java corridor.
Direct sales channels capture the dominant procurement share; online retail is gaining traction fastest among urban consumer segments.
Packaging Type:
Supply concentration in northern China's commercial maize belt and India's processing corridors dictates packaging economics, with bulk handling dominating industrial flows and unitized packaging serving consumer channels.
- Bulk:Unpackaged grain movement dominates feed mill and starch processor procurement, minimizing handling costs across Vietnam's port infrastructure and India's rail-fed processing clusters. Beidahuang Kenfeng Seed Co. leverages state-backed distribution infrastructure for northern China's commercial belt.
- Bags:25-50kg woven polypropylene sacks serve small-to-midscale feed compounders and food processors lacking bulk handling capacity. Ubiquitous across Indonesia's archipelago logistics.
- Boxes:Corrugated containers protect specialty sweet maize and premium food-grade shipments for export channels.
- Cans:Aseptic and retort packaging preserves processed maize products for retail shelf stability in Thailand's export-oriented food manufacturing.
Bulk packaging handles the majority of regional throughput; bagged formats retain importance in Indonesia's fragmented island logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed millers and starch processors concentrate procurement across four demand centers, with regulatory filtering from China's SAMR and India's FSSAI reshaping supplier eligibility.
China
Shandong and Jilin processors source certified low-carbon intensity feedstock to meet MEE emission benchmarks under dual carbon goals. SAMR enforces GB labeling and biosecurity protocols that filter import eligibility and domestic cultivation permits. Beidahuang Kenfeng Seed Co. Ltd dominates the northern commercial maize belt with state-backed distribution infrastructure.
India
Gujarat and Maharashtra processing clusters attract premium contract pricing for food-grade and pharmaceutical-grade maize derivatives. FSSAI and BIS standards tighten amylose ratio and protein content specifications, filtering eligible suppliers toward certified farming cooperatives. The PLI scheme for food processing may expand maize-based industrial capacity for modified starch and sweetener derivatives.
Vietnam
Central Highlands feed millers source directly from consolidated farming cooperatives rather than spot markets. Industrial livestock operations favor standardized metabolizable energy content over varietal diversity. Nucleus-plasma outgrower schemes bundle input credit with guaranteed offtake, displacing traditional smallholder aggregation.
Indonesia
East Java feed mill clusters pull procurement volumes upward as livestock sectors industrialize. The EU Green Deal's due diligence requirements on deforestation-linked commodities are reshaping export-oriented sourcing protocols, extending compliance timelines. Contract farming consolidation is compressing procurement relationships toward fewer, larger aggregators with integrated quality assurance capabilities.
Thailand
Processors dominate regional sweet maize supply for fresh and frozen food channels. Gene editing-assisted molecular breeding platforms compress trait introgression timelines from five years to eighteen months. Smallholder networks face margin compression from feed millers' consolidated direct sourcing.
Asia Pacific Maize Market Competitive Environment
Player mix skews toward integrated seed-to-grain conglomerates with molecular breeding capabilities and state-backed distribution networks. Market structure concentrates around germplasm providers with regulatory certification advantages and tropical hybrid development expertise. Three archetypes dominate: multinational agrochemical conglomerates with breeding platforms, Chinese state-linked seed companies with regional distribution control, and Southeast Asian feed-to-farm integrators with contract farming networks. Competitive moves center on biosafety certification acceleration and nucleus-plasma outgrower scheme expansion.
Within the multinational tier, Bayer and Syngenta Group exemplify integrated seed advisory capabilities across Southeast Asian contract farming networks. Among state-linked germplasm providers, Beidahuang Kenfeng Seed Co. Ltd occupies a position anchored to northern China's commercial belt infrastructure. Corteva Agriscience and Advanta Seeds represent the molecular breeding platform specialists compressing variety development cycles for tropical hybrid deployment.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Bayer |
| Syngenta Group |
| Advanta Seeds - UPL |
| Beidahuang Kenfeng Seed Co. Ltd |
| Cargill |
| BASF |
| KWS SAAT SE & Co. KGaA |
| Charoen Pokphand Group |
| Others |
Value Chain & Pricing Dynamics
China's GB standards for grain quality and GMO labeling gate both supply qualification and price differentiation simultaneously, filtering import eligibility while creating certified-premium tiers that separate compliant germplasm providers from spot-market traders. SAMR enforcement compresses commercialization timelines for biosafety-certified varieties, concentrating pricing power among molecular breeding platforms with established regulatory navigation capabilities.
Pricing Analysis
Cost-plus contracts with Chicago Board of Trade indexation dominate procurement relationships between Vietnam's Central Highlands feed millers and consolidated farming cooperatives. Price differentiation rests on metabolizable energy density certification and FSSAI food-grade compliance, with pharmaceutical-grade starch derivatives commanding substantial premiums over feed-grade yellow maize. Margins are tightening due to fertilizer input volatility across Thai smallholder networks. Compound feed manufacturers exhibit highest price sensitivity, while Gujarat starch processors absorb premium differentials for amylose-ratio-specified supply.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Vietnam's industrial feed millers, while China's Shandong and Jilin processors maintain strategic stockpiles to buffer MEE emission benchmark compliance cycles. Geographic supply concentrates in northern China's commercial maize belt, India's Gujarat corridor, and Vietnam's Central Highlands. Raw material dependencies span certified germplasm, phosphate fertilizers, and fuel for mechanized harvesting. Single-source vulnerability runs through Beidahuang Kenfeng's state-backed distribution infrastructure. Distribution feeds from nucleus-plasma outgrower schemes directly into processor silos, bypassing traditional spot-market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific maize constitutes a high-growth disruption as gene editing-assisted molecular breeding compresses trait introgression timelines from five years to eighteen months, reorganizing competitive access around precision breeding capabilities rather than legacy germplasm libraries.
For Market Incumbents: Fortify biosafety certification pipelines under China's GB standards to preempt regulatory displacement by compliant rivals. Deepen backward integration into nucleus-plasma outgrower schemes across Vietnam and Indonesia, capturing direct procurement relationships that displace smallholder aggregation networks. Prioritize molecular breeding platform investment to sustain germplasm leadership as gene editing narrows differentiation windows.
For New Entrants and Emerging Players: Digital farm management advisory gaps in Myanmar and Cambodia present white-space entry points where incumbents under-serve contract farming networks with integrated quality assurance. Target nucleus-plasma scheme expansion in these geographies before consolidation hardens procurement relationships. Deploy precision variety-matching platforms as the primary go-to-market wedge, bundling input credit with guaranteed offtake to displace traditional wholesaler intermediation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across molecular breeding infrastructure as gene editing platforms require specialized laboratory capital deployment. Long-term viability centers on germplasm providers with regulatory certification advantages and tropical hybrid development expertise. Target acquisition archetypes include Southeast Asian feed-to-farm integrators with established contract farming networks and digital advisory capabilities. Watch for India's PLI scheme expansion signals as inflection indicators for maize-based industrial capacity deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Biosafety Certification Acceleration | GB compliance under SAMR protocols filters import eligibility and domestic cultivation permits. |
| Nucleus-Plasma Outgrower Expansion | Direct procurement from consolidated cooperatives displaces smallholder spot-market aggregation in Vietnam. |
| Molecular Breeding Platform Investment | Gene editing-assisted trait introgression compresses development cycles from five years to eighteen months. |
| Backward Integration into Input Supply | Captive germplasm and fertilizer provision secures margin control across Indonesian contract farming networks. |
| Digital Farm Management Deployment | Precision variety-matching tools enable microclimatic zone optimization in Southeast Asian advisory services. |
Study Parameters
Initial hypotheses were tested against primary input from seed company R&D directors, feed mill procurement managers, starch processor quality control leads, and contract farming cooperative coordinators, then refined through secondary validation. Primary fieldwork drew from customs and trade data, FSSAI regulatory filings, SEC disclosures from listed agribusiness conglomerates, and GB standards documentation. Bottom-up volume estimates from processor intake records were triangulated against top-down demand projections from livestock sector feed conversion ratios and starch industry capacity utilization.
Variance decomposition across kernel texture, end-use industry, and distribution channel dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from segmented growth rate aggregation calibrated to livestock industrialization trajectories in Vietnam and Indonesia, starch processing capacity expansion in Gujarat and Maharashtra, and biofuel policy redirection under China's dual carbon goals. Modeled outputs reflect price elasticity assumptions for compound feed formulation and pharmaceutical-grade derivative procurement.
Forecasts assume regulatory continuity in China's SAMR enforcement, India's FSSAI protocols, and Vietnam's feed safety requirements; material policy shifts would require re-modeling. Revision becomes warranted when EU Green Deal due diligence implementation crosses thresholds that reshape Indonesian and Malaysian export-oriented sourcing protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Canada Pulses Market
Grains
00 Flour Market
Grains
Colombia Grains Market
Grains
North America Oats Market
Grains
Masa Corn Products Market
Grains
Oat Flour Market
Grains
Basmati Rice Market
Grains
Organic Wheat Flour Market
Grains
Wheat Flour Market
Grains
White Rice Flour Market
Grains
Lentil Market
Grains
Brown Rice Market
Grains
Sorghum Market
Grains
North America Wheat Flour Market
Grains
Asia Pacific Wheat Protein Market
Grains
Green Banana Flour Market