
 Spain Adhesives Market | 2026-2036
Spain Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Adhesives Market Analytics
High-performance structural-grade bonding is unwinding across Spain's automotive and construction supply chains. Henkel AG & Co. KGaA leverages its R&D intensity in reactive adhesive platforms for electric vehicle battery assembly. Sika AG anchors the construction segment with specialized sealing and bonding systems for infrastructure projects. Arkema competes through advanced hot melt technologies tailored to flexible packaging converters in northeastern Spain.
Spain adhesives are formulated compositions—typically polymers, resins, and additives cured through moisture, heat, or chemical reaction—that create permanent or semi-permanent joints between substrates, with specifications ranging from peel strengths of 2–20 N/mm to temperature tolerances between -40°C and 150°C depending on end-use. Their primary industrial purpose is to replace mechanical fasteners, reduce assembly weight, and enable bonding of dissimilar materials in manufacturing processes. Water-based formulations lead volume sales due to regulatory pressure on volatile organic compound emissions, while reactive adhesives command the strongest margin pools given their specialized curing chemistry and performance guarantees. Hot melt segments sustain above-average growth in packaging applications driven by e-commerce fulfillment demands across Iberian distribution networks.
Spain's national implementation of EU REACH through the Ministry for Ecological Transition and the Demographic Challenge restricts hazardous substance use in adhesive formulations, while CE marking requirements under the Construction Products Regulation govern structural bonding applications in building projects. The country's national chemical regulator enforces compliance with F-Gas Regulation limits on fluorinated compounds used in certain specialty adhesive curing agents. Stakeholders must monitor pending revisions to EU-wide eco-design frameworks and assess how Spain's building energy renovation mandates will redirect specification priorities toward thermally efficient bonding systems.
Market Dynamics
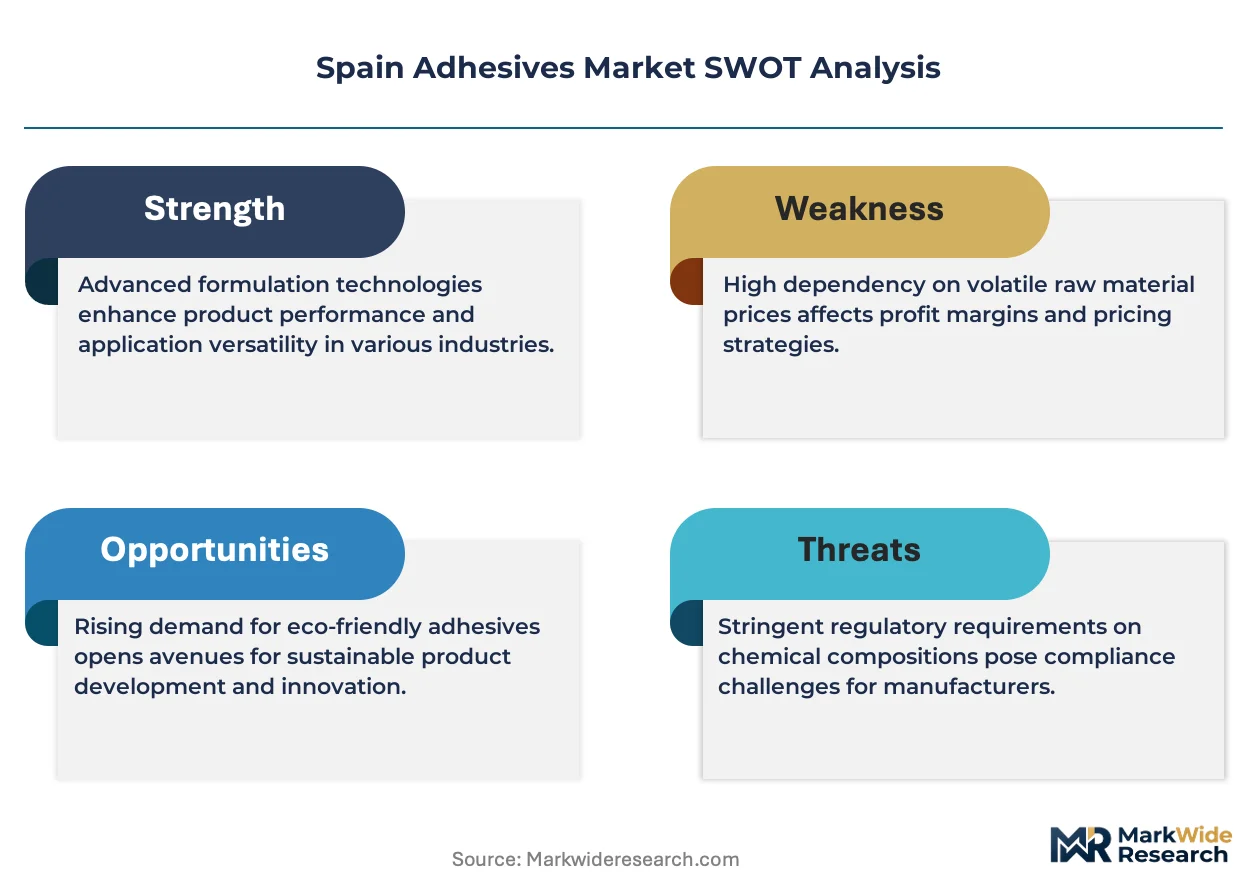
Spain's adhesives sector faces structural compression from REACH chemical restrictions and F-Gas Regulation compliance costs, forcing formulators to reformulate legacy solvent-based products while automotive OEMs in Zaragoza and Barcelona accelerate specification of lightweight bonding systems.
Growth Catalysts
- Automotive Lightweighting Mandates:Assembly plants in Catalonia and Aragon specify structural adhesives for multi-material vehicle bonding, replacing mechanical fasteners in battery enclosures and body-in-white construction.
- E-Commerce Packaging Volume:Iberian distribution hubs around Madrid drive hot melt consumption for corrugated case sealing and flexible pouch lamination across fulfillment networks.
- Building Energy Renovation Programs:Spain's national building retrofit mandates specify thermally efficient bonding systems for facade insulation and window installation, redirecting construction specification priorities.
Market Restraints
- Petrochemical Feedstock Volatility:Polyurethane and epoxy resin prices fluctuate with crude oil derivatives, compressing margin pools for Spanish formulators lacking backward integration into basic chemicals.
- Supply Concentration in German Chemicals:Specialty curing agents and isocyanates concentrate among Rhine-Ruhr producers, exposing Spanish compounders to single-source risk and extended lead times.
- REACH Registration Burden:ECHA substance data requirements impose fixed compliance costs that disproportionately burden mid-tier Spanish adhesive manufacturers with limited regulatory affairs capacity.
Strategic Opportunities
- Andalusian Solar Manufacturing:Photovoltaic module assembly plants in Seville and Malaga create specification demand for edge-seal adhesives and backsheet lamination systems with 25-year durability guarantees.
- Bio-Based Feedstock Transition:Castor oil-derived polyols and lignin-based tackifiers enable Spanish formulators to differentiate through renewable content claims aligned with EU Green Deal procurement criteria.
- Direct-to-Converter Digital Channels:Packaging converters in Catalonia's industrial corridor adopt platform-based adhesive procurement, bypassing traditional distributor markups for standardized hot melt grades.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Spanish technical universities produce limited polymer science graduates with adhesive-specific expertise, forcing manufacturers to recruit from German and French competitor pools.
- CE Marking Certification Timelines:Construction Products Regulation testing for structural bonding applications extends 12-18 months, delaying product launches for building sector specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Adhesives Market |
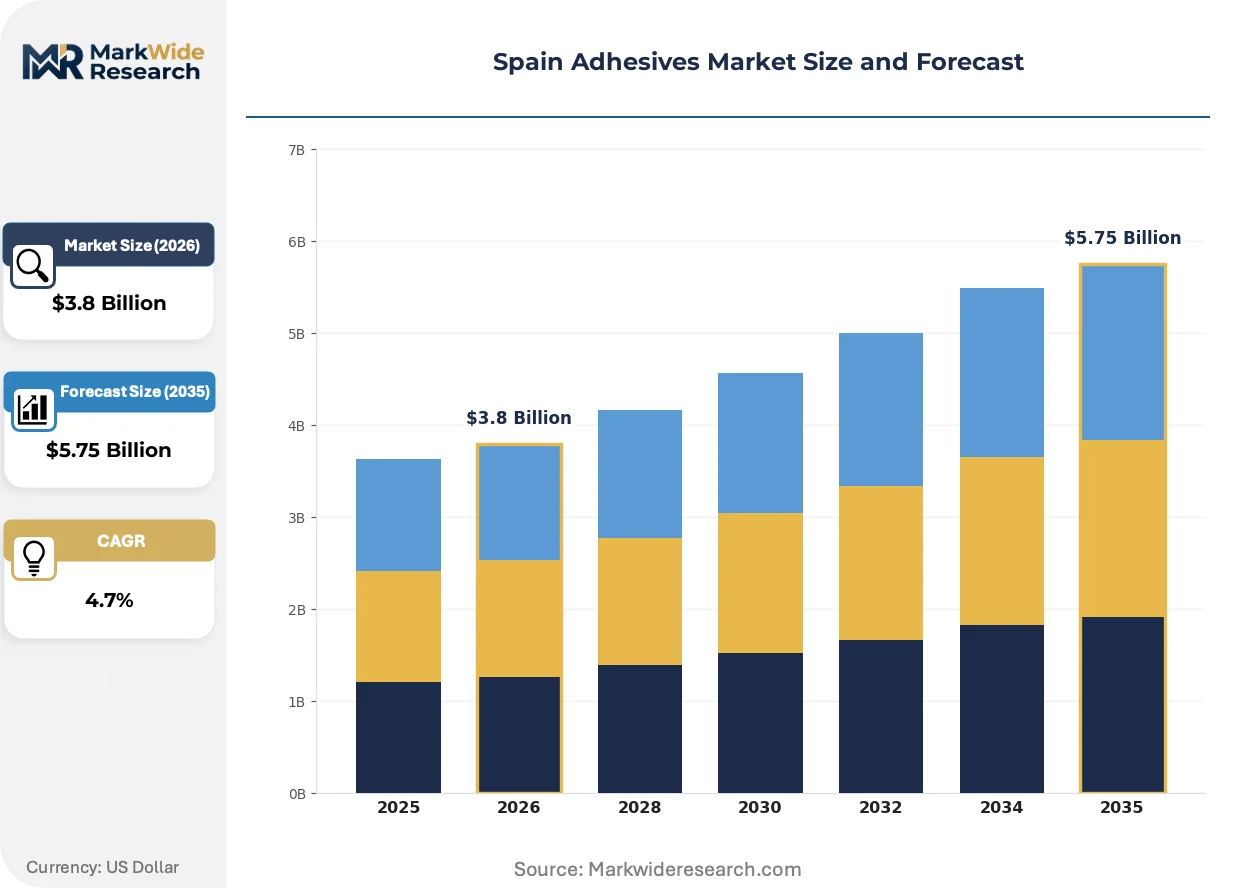
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Reactive End User: Automotive, Building & Construction, Packaging, Footwear Technology: Contact Adhesives, Pressure Sensitive, Structural, Anaerobic Application: Bonding, Coating, Sealing, Laminating |
| Companies Covered | Sika AG, Arkema, Henkel AG & Co. KGaA, Adhesivos Plásticos Reunidos S. L., COLAS ARTIACH, S.L., H.B. Fuller Company, Huntsman International LLC, INDUSTRIAS PROA, S. A., 3M, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Adhesives Market Evolving Landscape
Reactive adhesive platforms are compressing cure cycles and enabling automated dispensing in Spanish automotive plants, while regulatory pressure on VOC emissions accelerates water-based formulation investment across packaging and construction segments.
UV-curable acrylic adhesives are miniaturizing bond line thickness requirements in electronics assembly applications. Tier-one automotive suppliers in Barcelona specify these systems for display bonding and sensor mounting where gap control demands sub-50-micron precision. The technology is miniaturizing traditional mechanical fastening approaches in electric vehicle battery module assembly, reducing part count and assembly cycle time.
Spain's transposition of EU F-Gas Regulation through the Ministry for Ecological Transition restricts hydrofluorocarbon use in specialty adhesive curing agents and blowing agents. Formulators must qualify alternative chemistries for polyurethane foam bonding applications by 2030. Construction and appliance manufacturers in northern Spain face accelerated specification reviews to maintain compliance with phasedown schedules.
Converter procurement teams in Valencia and Barcelona increasingly specify adhesive performance through bonded-joint testing protocols rather than raw material certificates. This behavior displaces traditional volume-based supplier relationships with outcome-based partnerships where Spanish formulators guarantee peel strength and thermal cycling durability. The shift concentrates specification authority among technical buyers at large packaging groups with in-house testing laboratories.
Spain Adhesives Market Segmentation
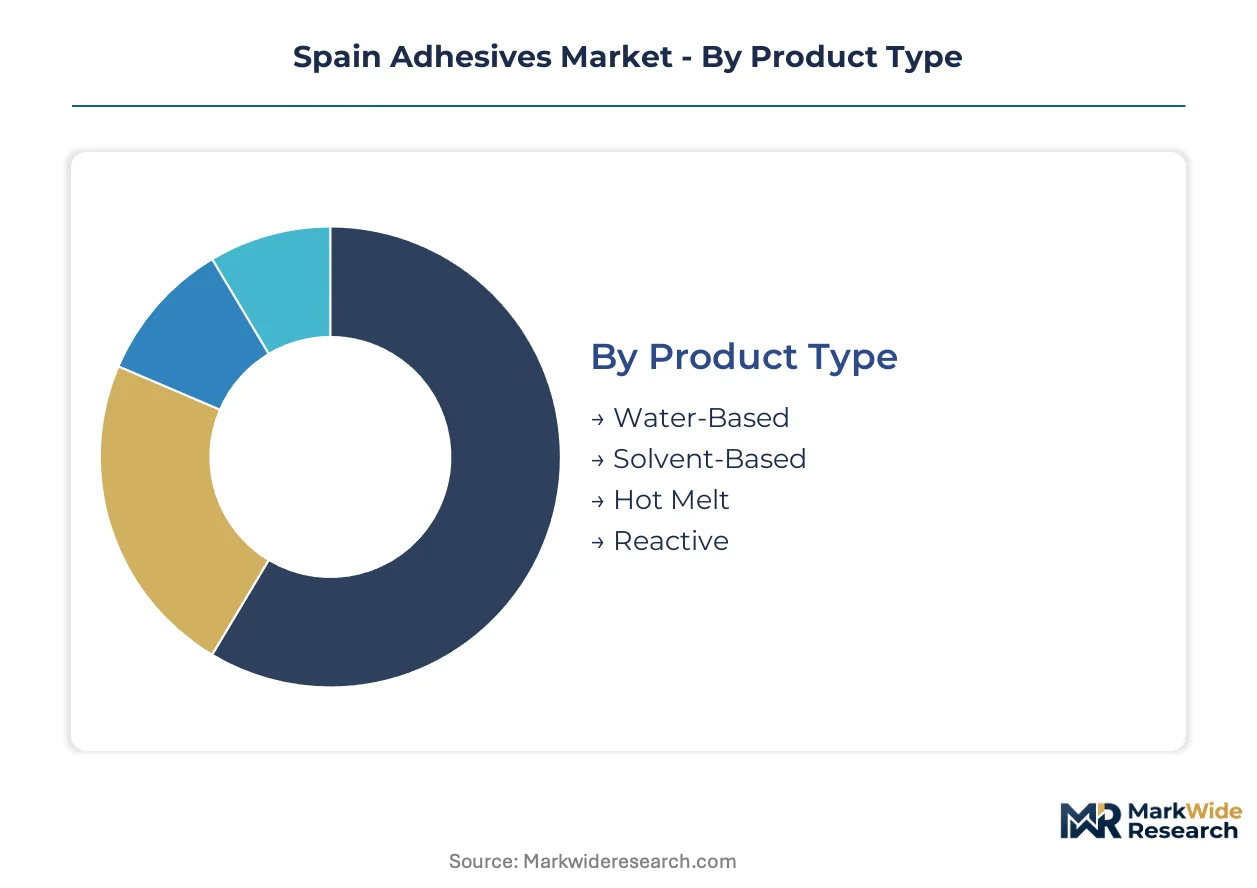
Adhesive specification in Spain fragments across regulatory thresholds, end-use performance requirements, and curing chemistry constraints. Each segmentation axis carries distinct compliance burdens and margin structures that reshape procurement patterns among Catalan automotive suppliers and Valencian packaging converters.
Product Type:
REACH substance restrictions and F-Gas Regulation limits create divergent compliance pathways across formulation chemistries, concentrating procurement among formulators with ECHA registration capacity.
- Water-Based:Acrylic and polyurethane dispersions cure through moisture evaporation, delivering bond strengths of 2–8 N/mm for porous substrates. Catalonia's corrugated packaging plants specify these systems to meet VOC emission limits under Spain's transposed EU solvent regulations.
- Reactive:Two-component epoxy and polyurethane systems polymerize through chemical reaction, achieving structural-grade bonds of 15–20 N/mm with temperature tolerance to 150°C. Zaragoza automotive assembly lines specify these for battery enclosure bonding where multi-material joints replace welded seams.
- Solvent-Based:Nitrile rubber and neoprene solutions in organic carriers deliver rapid tack for footwear assembly in Alicante's manufacturing cluster.
- Hot Melt:Ethylene-vinyl acetate and polyolefin formulations enable sub-second set times for Madrid distribution hub case sealing applications.
Established volume favors Water-Based; emerging adoption favors Reactive.
End User:
Customer procurement sophistication varies sharply — automotive and construction buyers mandate bonded-joint testing protocols while packaging converters prioritize throughput economics.
- Automotive:OEM assembly plants in Barcelona and Zaragoza specify structural adhesives for lightweight vehicle construction, with battery module bonding driving specification of thermally conductive formulations.
- Packaging:Iberian e-commerce fulfillment networks around Madrid consume hot melt systems for corrugated case sealing and flexible pouch lamination at volumes that dominate adhesive procurement tonnage.
- Building & Construction:Spain's national building energy renovation mandates redirect specification toward thermally efficient facade insulation bonding systems.
- Footwear:Alicante's leather goods manufacturers specify contact cements for upper-to-sole assembly where flexibility and peel resistance govern performance.
Procurement scale concentrates in Packaging; specification complexity concentrates in Automotive.
Technology:
Curing mechanism selection determines capital equipment requirements and labor skill thresholds across Spanish manufacturing plants.
- Pressure Sensitive:Permanent tack properties enable label and tape applications without activation, serving Valencia's label converting cluster with solvent-free formulations that align with REACH compliance timelines.
- Structural:Load-bearing capacity to 30 MPa shear strength supports automotive and construction applications where mechanical fasteners are eliminated.
- Contact Adhesives:Solvent-based neoprene and polyurethane solutions bond decorative laminates and footwear components.
- Anaerobic:Cure-in-place threadlocking compounds secure fasteners in machinery assembly across Basque Country industrial equipment manufacturers.
Volume application favors Pressure Sensitive; performance premium commands Structural.
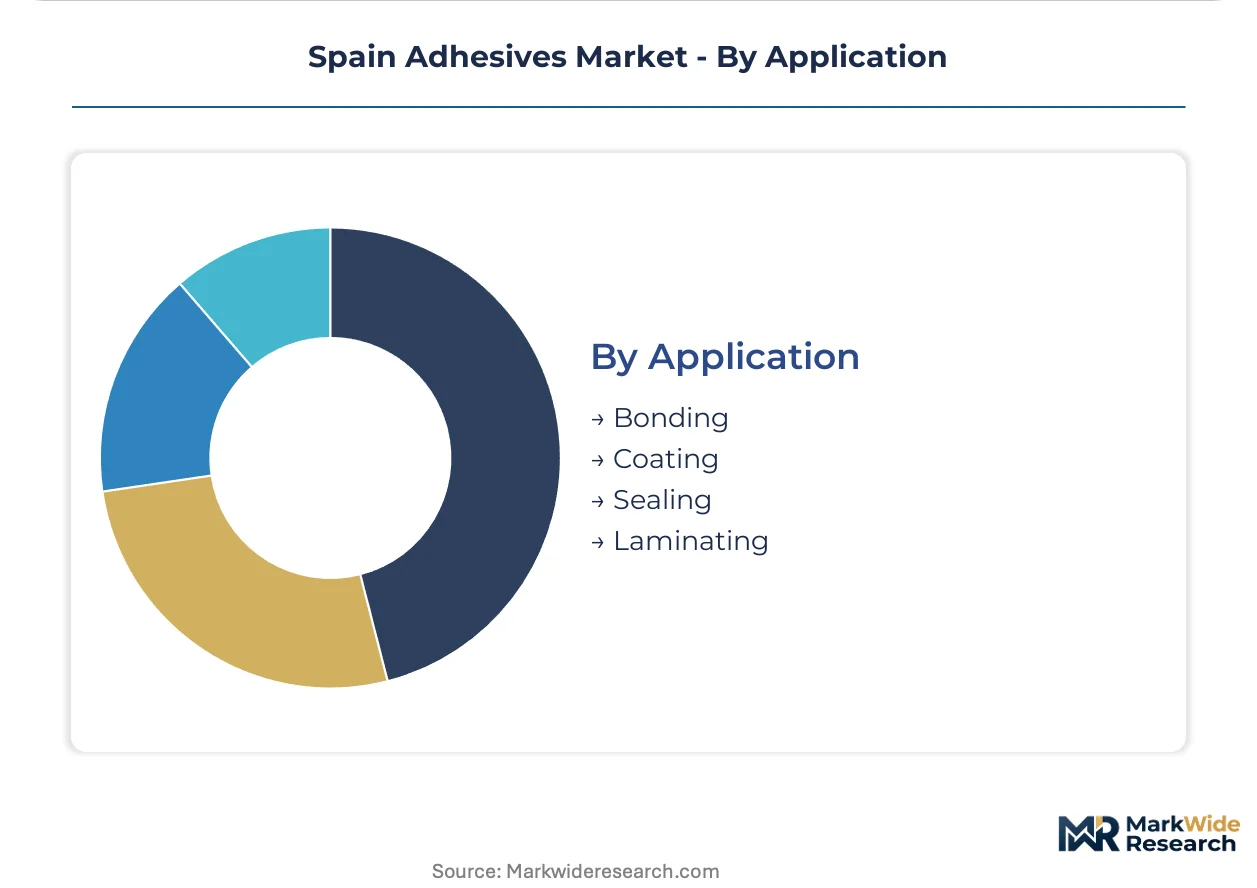
Application:
Functional purpose dictates specification testing protocols — bonding applications require destructive testing while sealing emphasizes durability guarantees.
- Bonding:Permanent substrate joining for automotive body-in-white and construction panel assembly, with Catalan plants specifying structural grades that carry CE marking under the Construction Products Regulation.
- Sealing:Gap-filling and environmental protection for photovoltaic module edge seals in Andalusian solar manufacturing, where 25-year durability guarantees are mandatory.
- Coating:Protective and functional layer deposition for industrial substrates.
- Laminating:Multi-layer film and foil assembly for flexible food packaging converters in Barcelona's industrial corridor.
Specification authority concentrates in Bonding; growth trajectory steepest in Sealing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's adhesive trade flows reflect a structural deficit in specialty curing agents, with formulators sourcing isocyanates and epoxy hardeners from Rhine-Ruhr producers while exporting finished water-based and hot-melt formulations to Portugal and North Africa. The national market's regional fragmentation concentrates specification authority in distinct industrial corridors.
Catalonia
Barcelona's automotive assembly plants and packaging converters drive structural adhesive consumption for multi-material vehicle bonding and corrugated case sealing. ECHA-registered formulators cluster along the industrial corridor to service OEMs with REACH-compliant reactive platforms. The region's technical buyers increasingly mandate bonded-joint testing protocols over raw material certificates.
Madrid
Iberian e-commerce fulfillment hubs surrounding the capital generate the nation's highest hot-melt tonnage for automated case sealing and flexible pouch lamination. Spain's Ministry for Ecological Transition enforces transposed EU solvent regulations that redirect procurement toward water-based formulations. Distribution center automation accelerates specification of sub-second set-time adhesives.
Basque Country
Industrial equipment manufacturers in Bilbao and San Sebastián specify anaerobic threadlocking compounds and structural bonding systems for machinery assembly. The region's machine tool sector demands adhesives with shear strength to 30 MPa for fastener elimination in precision equipment. Local formulators serve this demand with CE-marked construction products and specialty industrial grades.
Andalusia
Photovoltaic module assembly plants in Seville and Malaga create specification pull for edge-seal adhesives and backsheet lamination systems with 25-year durability guarantees. Spain's national renewable energy targets accelerate capacity expansion in solar manufacturing. Formulators must qualify products under Construction Products Regulation timelines for this emerging demand segment.
Valencia
Label converting clusters and footwear manufacturers in Alicante specify pressure-sensitive adhesives and solvent-based contact cements for decorative laminates and upper-to-sole assembly. The region's leather goods sector prioritizes flexibility and peel resistance in adhesive selection. REACH substance restrictions are forcing reformulation of legacy neoprene solutions toward compliant alternatives.
Spain Adhesives Market Competitive Landscape
Concentration sits with multinational chemical conglomerates possessing ECHA registration capacity and backward integration into resin production. Spanish mid-tier compounders occupy fragmented positions in packaging and construction segments, lacking scale to absorb REACH compliance costs. Three archetypes dominate: Rhine-Ruhr-based specialty chemical suppliers, diversified European industrial conglomerates, and regional Spanish formulators serving niche end-uses. Competitive moves center on bio-based feedstock differentiation and direct-to-converter digital procurement platforms that bypass traditional distribution markups.
Among diversified European industrial conglomerates, Henkel AG & Co. KGaA and Sika AG exemplify archetypes with the regulatory affairs infrastructure to navigate Spain's transposed REACH and F-Gas requirements. Arkema occupies a position within specialty materials, representing formulators with advanced polymer capabilities. These anchors demonstrate how multinational scale concentrates specification authority in automotive and construction segments where bonded-joint testing and CE marking create compliance barriers for smaller competitors.
| Leading Market Players |
|---|
| Sika AG |
| Arkema |
| Henkel AG & Co. KGaA |
| Adhesivos Plásticos Reunidos S. L. |
| COLAS ARTIACH, S.L. |
| H.B. Fuller Company |
| Huntsman International LLC |
| INDUSTRIAS PROA, S. A. |
| 3M |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Spanish automotive OEMs and Rhine-Ruhr chemical suppliers lock in isocyanate supply access while fixing raw material price visibility across multi-year procurement cycles. These arrangements insulate Zaragoza assembly plants from petrochemical volatility while exposing formulators to take-or-pay obligations when demand fluctuates.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in Spain's adhesives sector. Price differentiation rests on REACH registration status and CE marking certification, with ECHA-registered formulators commanding structural-grade premiums. Cost compression in economy-tier water-based formulations is intensifying because mid-tier Spanish compounders lack backward integration into resin production. Packaging converters in Madrid's fulfillment hubs exhibit highest price sensitivity, while Barcelona automotive plants prioritize bonded-joint performance guarantees over unit economics.
Supply Chain Analysis
Rhine-Ruhr corridor concentration in Germany underwrites Spanish adhesive formulators' access to specialty curing agents and epoxy hardeners. Raw material sourcing draws from German petrochemical complexes for isocyanates, Belgian resin producers for polyurethane precursors, and domestic Spanish facilities for water-based acrylic dispersions. Single-source vulnerability concentrates in aerospace-grade epoxy systems where qualified alternative suppliers require 18-month ECHA substance dossier reviews. Distribution runs through specialized chemical distributors serving Catalonia's industrial corridor with just-in-time delivery to converter plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise scarcity defines competitive boundaries in Spain's adhesives sector, with ECHA registration capacity and polymer science talent pools concentrating among multinational incumbents while mid-tier Spanish compounders struggle to absorb compliance fixed costs.
For Market Incumbents: Shield specification authority in automotive and construction segments by deepening captive supply of REACH-registered epoxy hardeners and accelerating CE marking certification timelines. Margin pressure from bio-based feedstock transitions demands R&D investment in castor oil-derived polyol platforms to preempt EU Green Deal procurement criteria shifts. For New Entrants and Emerging Players: Anchor in Andalusian solar manufacturing demand for photovoltaic edge-seal adhesies with 25-year durability guarantees, where Construction Products Regulation barriers remain lower than automotive qualification cycles. Direct-to-converter digital procurement platforms offer a go-to-market angle to bypass established distributor markups in Madrid's packaging hub. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier Spanish compounders possessing ECHA substance registrations but lacking scale to exploit bio-based formulation transitions. Long-term viability hinges on consolidation plays that aggregate regulatory affairs capacity across fragmented regional formulators. Watch Andalusian solar capacity expansion announcements as inflection indicators for specialty sealing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive supply of epoxy hardeners insulates Spanish formulators from Rhine-Ruhr price volatility. |
| Bio-Based Feedstock Transition | Castor oil-derived polyols enable renewable content claims aligned with EU Green Deal procurement. |
| CE Marking Certification Acceleration | Compressed 12-18 month testing timelines capture building energy renovation specification windows. |
| Direct-to-Converter Digital Platform | Platform-based procurement bypasses distributor markups for standardized hot melt grades in Catalonia. |
| Long-Term Supply Agreement with Solar OEMs | 25-year durability guarantees lock in Andalusian photovoltaic module assembly specification. |
Research Methodology
Operator-level perspectives from adhesive formulator plant managers, automotive OEM procurement leads, packaging converter technical buyers, and construction products distributors anchored the qualitative base for this analysis. Primary interview findings triangulated against secondary sources including Spanish customs trade data, ECHA substance registration databases, SEC filings from multinational chemical conglomerates, and Cefic sector reports. Bottom-up volume estimates from individual production facilities reconciled with top-down market sizing derived from end-use consumption patterns across Catalonia, Madrid, and Andalusia.
Sensitivity analysis tested forecast robustness across feedstock price scenarios and regulatory implementation timelines over the projection horizon. The analytical framework modeled segmentation across formulation chemistry, end-use industry, curing mechanism, and regional production hub. CAGRs derived from historical volume trajectories adjusted for automotive lightweighting mandates, e-commerce packaging growth, and building energy renovation program acceleration. Key inputs included petrochemical derivative pricing indices and EU F-Gas Regulation phasedown schedules.
Material uncertainties — REACH substance restriction revisions, F-Gas Regulation enforcement intensity, and photovoltaic manufacturing capacity deployment — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and feedstock supply continuity that practitioners should keep alternative scenarios live as EU eco-design framework negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
Construction Repair and Rehabilitation Chemicals Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
Europe Adhesives Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market
Adhesives & Sealants
Epoxy Glue Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Spray Fluxer Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
South America Sealants Market
Adhesives & Sealants
Global Hygiene Adhesives Market
Adhesives & Sealants
Glass Adhesive Market