
 Global Ceramic Adhesives Market | 2026-2036
Global Ceramic Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ceramic Adhesives Market Foresight
Industrial manufacturing buyers are reorganizing procurement priorities toward high-temperature bonding solutions that outperform conventional mechanical fasteners. Henkel AG & Co. KGaA leverages its R&D intensity in epoxy formulations for electronics assembly. Sika AG anchors its position through manufacturing scale in construction-grade ceramic adhesive systems. Dow Inc. competes on technology leadership in silicone-based thermal interface materials.
Ceramic adhesives are inorganic or hybrid bonding agents formulated with alumina, zirconia, or silica fillers that cure to withstand temperatures exceeding 1000°C while maintaining dielectric strength above 10 kV/mm. Their primary purpose is to join ceramic substrates, metalized surfaces, and composite materials in applications where thermal cycling resistance and chemical inertness are mandatory. Epoxy ceramic adhesives dominate volume in electronics assembly due to established supply chains and lower per-unit cost, while silicone formulations capture margin pools in aerospace bonding where outgassing specifications under ASTM E595 are non-negotiable. UV curable technology represents the fastest-growing segment as semiconductor fabrication lines accelerate throughput and reduce thermal budget exposure.
REACH registration requirements in Europe, GB standards enforcement by SAMR in China, and FDA device manufacturing regulations in the US collectively elevate barrier-to-entry for new adhesive suppliers while forcing incumbent formulators to document full material toxicity profiles. ECHA's persistent scrutiny of boron-containing compounds directly impacts borate-based ceramic adhesive chemistries, compelling substitution investments. Stakeholders must monitor evolving dual carbon goals in China and the EU Green Deal's embodied carbon tracking, as these frameworks will increasingly determine qualified supplier status rather than just product performance benchmarks.
Market Dynamics
Semiconductor fabrication facilities are accelerating throughput demands, forcing adhesive formulators to compress cure cycles while maintaining dielectric performance above 10 kV/mm under thermal cycling stress.
Growth Catalysts
- UV curable ceramic adhesives:Semiconductor fabrication lines in Germany and Japan are adopting UV cure technology to eliminate thermal budget exposure during die-attach processes.
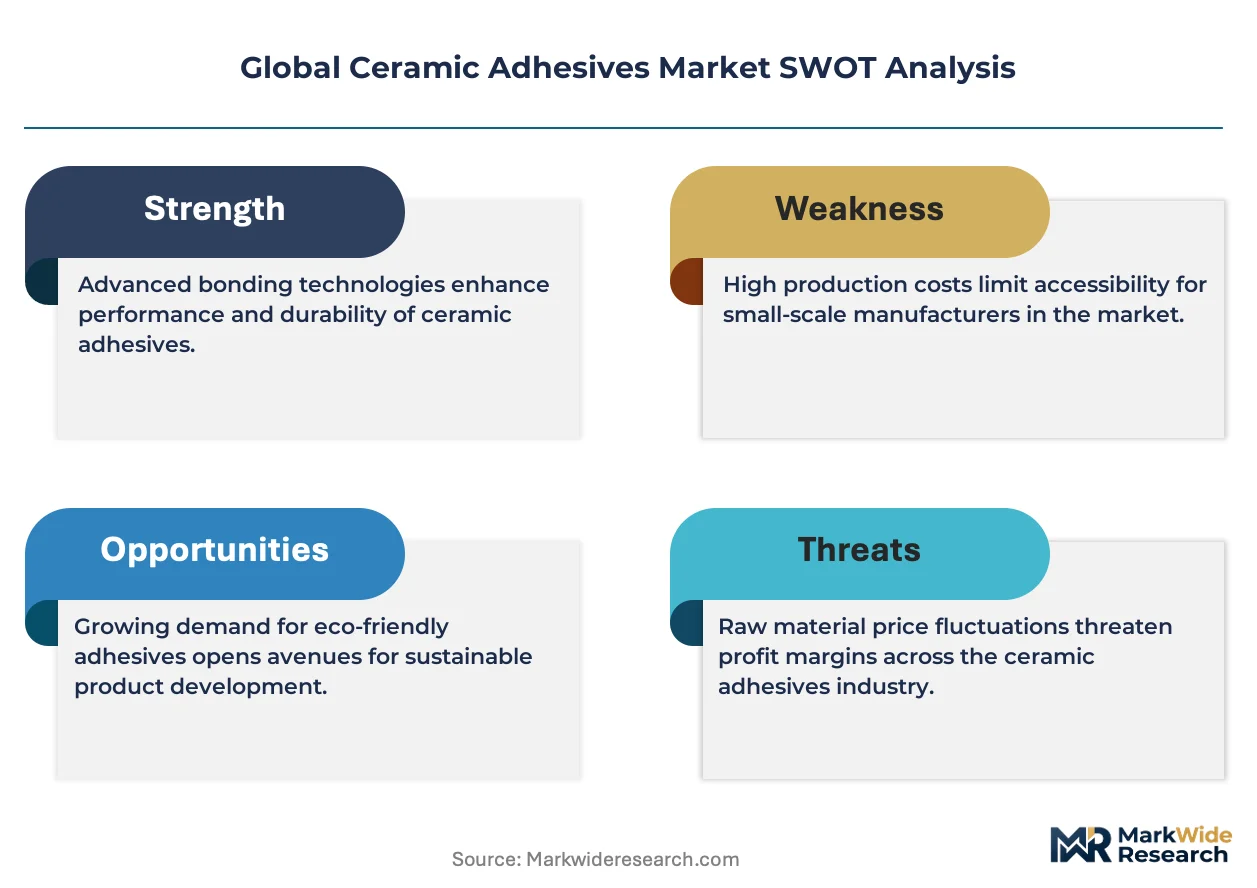
- REACH compliance substitution:ECHA scrutiny of boron-containing compounds is compelling formulators to invest in borate-free chemistries, opening procurement windows for compliant suppliers.
- India:PLI scheme incentives for electronics manufacturing are attracting substrate bonding adhesive volumes to Gujarat and Tamil Nadu clusters.
Market Restraints
- Alumina filler cost volatility:Mining concentration in Australia and Brazil creates input price instability for high-purity alumina grades used in thermal interface formulations.
- Technical limitation:Coefficient of thermal expansion mismatch between zirconia-filled adhesives and silicon carbide substrates limits adoption in wide-bandgap power electronics.
- Regulatory friction:GB standards enforcement by SAMR in China requires reformulation documentation that extends product registration timelines by 8-14 months.
Strategic Opportunities
- Solid-state battery assembly:Ceramic-to-metal bonding requirements for lithium-metal anode architectures represent uncontracted demand in South Korean pilot lines.
- EU Green Deal embodied carbon tracking:Adhesive suppliers with verified lifecycle data gain qualified supplier status in German automotive thermal management programs.
- Direct-to-fab distribution:Bypassing regional distributors to supply semiconductor fabs in Hsinchu and Dresden compresses lead times and captures margin.
Industry Challenges
- Formulation chemist scarcity:Expertise in hybrid inorganic-organic systems combining sol-gel chemistry with epoxy backbone modification commands premium compensation in Munich and Boston clusters.
- ASTM E595 outgassing certification:Aerospace adhesive qualification requires 12-18 month third-party testing cycles that delay revenue recognition.
- Legacy substrate integration:Bonding new UV-curable formulations to existing alumina nitride metallization layers requires process requalification that fabs resist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ceramic Adhesives Market |
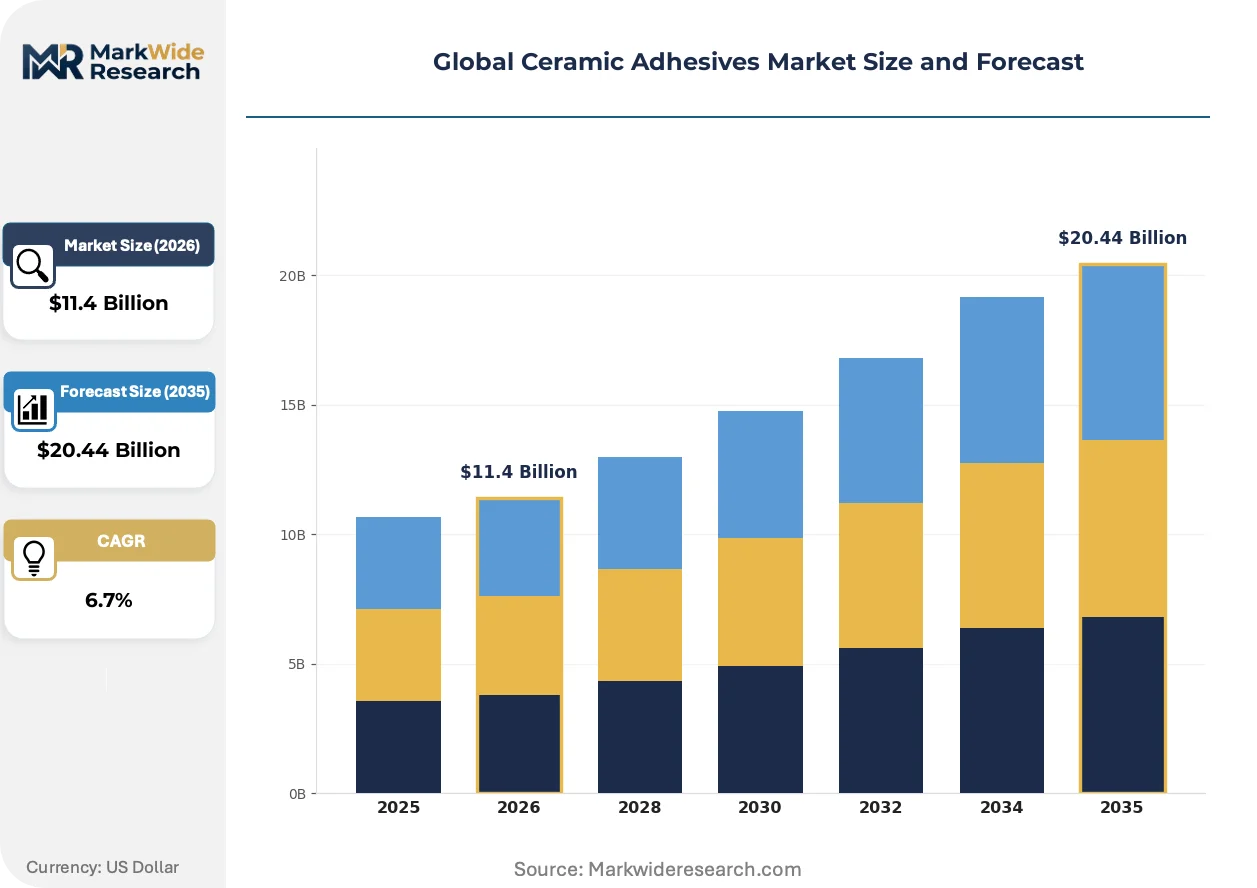
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.44 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Silicone, Acrylic, Polyurethane, Cyanoacrylate Technology: Heat Resistant, Electrical Insulating, High Strength, Flexible, UV Curable Application: Electronics Assembly, Aerospace Bonding, Construction Fixing, Industrial Manufacturing, Consumer Goods End User Industry: Semiconductor Fabrication, Aircraft Manufacturing, Heavy Machinery, Home Appliance Production, Packaging |
| Companies Covered | Sika AG, Henkel AG & Co. KGaA, 3M Company, Dow Inc., Mapei S.p.A., Arkema SA, Pidilite Industries Limited, H.B. Fuller Company, Laticrete International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ceramic Adhesives Market Shifts & Advancements
Formulation science is converging with semiconductor process engineering, creating adhesive systems that cure at ambient temperature while surviving reflow profiles above 260°C.
Nano-silica functionalized epoxy systems are displacing conventional micron-filled formulations in flip-chip underfill applications. TSMC and Intel packaging divisions are qualifying these materials for 2.5D interposer bonding. The structural consequence is compressing filler loading requirements by 40% while maintaining thermal conductivity targets, which is displacing legacy alumina-heavy compounds from high-density interconnect lines.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are forcing aerospace adhesive suppliers to eliminate perfluorinated cure catalysts from silicone ceramic formulations. Industrial consequence includes reformulation of thermal protection systems for re-entry vehicles and satellite structures. European Space Agency prime contractors in France and Germany are accelerating qualification of alkoxy-silane cure systems as replacement chemistries.
Consolidated procurement by semiconductor equipment OEMs is compressing adhesive supplier bases from twelve qualified vendors to three preferred partners per fab. Applied Materials and Lam Research are unbundling material specifications from equipment service contracts, forcing formulators to assume direct qualification liability. This pattern is most visible in South Korean memory fabrication clusters where Samsung and SK Hynix procurement teams have centralized ceramic adhesive sourcing decisions to Suwon headquarters.
Global Ceramic Adhesives Market Segmentation
Ceramic adhesive procurement decisions split across four independent dimensions: chemistry sets thermal limits, cure technology determines fab compatibility, application context governs certification requirements, and end-user industry drives volume scale. Formulators must optimize across all four simultaneously to capture qualified supplier status.
Product Type:
Margin pools concentrate in silicone and specialty epoxy formulations where aerospace and semiconductor qualifications command price premiums over construction-grade alternatives.
- Epoxy:Alumina-filled systems dominate electronics assembly with established supply chains and lower per-unit cost. Die-attach applications in German and Japanese semiconductor fabs absorb the highest purity grades where dielectric strength above 10 kV/mm is mandatory.
- Silicone:Thermal interface materials withstand temperatures exceeding 1000°C while maintaining flexibility. Aerospace bonding applications in France and Germany require ASTM E595 outgassing compliance that eliminates lower-grade competitors from qualification.
- Acrylic:Lower-temperature construction applications with faster ambient cure cycles. Building facade bonding in urban Chinese developments favors cost efficiency over thermal performance.
- Polyurethane:Flexible formulations for vibration-dampening industrial assemblies. Heavy machinery manufacturers in South Korea specify these for equipment mounting pads.
- Cyanoacrylate:Instant-bonding systems for consumer goods repair and small-component fixation. Limited thermal resistance restricts use to sub-100°C environments.
Epoxy holds installed capacity. Silicone is rotating up the share rankings.
Technology:
Volume leadership sits with heat-resistant formulations, though UV curable systems are climbing fastest as semiconductor lines eliminate thermal budget exposure.
- Heat Resistant:Conventional thermal cure systems anchor industrial manufacturing with proven reliability above 260°C reflow profiles. Automotive thermal management programs in Germany specify these for power module attachment.
- UV Curable:Semiconductor fabrication lines in Hsinchu and Dresden adopt these to compress cure cycles from hours to seconds. The elimination of oven infrastructure reduces capital intensity for new fab builds.
- Electrical Insulating:Dielectric formulations for substrate bonding in high-voltage power electronics. Wide-bandgap device manufacturers specify these for silicon carbide module assembly.
- High Strength:Structural ceramic-to-metal bonding for aerospace primary assemblies. European Space Agency prime contractors qualify these for satellite payload integration.
- Flexible:Vibration-tolerant formulations for industrial equipment subjected to thermal cycling stress. Heavy machinery OEMs in Japan favor these for turbine component repair.
Heat resistant maintains volume leadership. UV curable is expanding most quickly through semiconductor qualification pipelines.
Application:
Electronics assembly captures the highest absolute revenue, though aerospace bonding delivers superior per-kilogram margins through certification barriers.
- Electronics Assembly:Die-attach, substrate bonding, and underfill applications across memory and logic fabrication. TSMC and Intel packaging divisions drive qualification of nano-silica functionalized systems for 2.5D interposer bonding.
- Aerospace Bonding:Thermal protection systems and structural ceramic-to-metal joints. EU F-Gas Regulation restrictions are forcing reformulation of perfluorinated cure catalysts to alkoxy-silane alternatives.
- Construction Fixing:Facade cladding and tile bonding with ambient cure requirements. Chinese GB standards enforcement by SAMR extends product registration timelines for imported formulations.
- Industrial Manufacturing:Equipment repair and high-temperature fixture bonding. German automotive suppliers specify ceramic adhesives for electric motor thermal management.
- Consumer Goods:Appliance assembly and decorative ceramic repair. Price sensitivity limits formulation sophistication in this segment.
Electronics assembly commands absolute revenue. Aerospace bonding is climbing the fastest on qualification backlog.
End User Industry:
Semiconductor fabrication concentrates procurement decisions among three preferred partners per fab, while aircraft manufacturing sustains the longest qualification cycles.
- Semiconductor Fabrication:Die-attach and substrate bonding for advanced packaging. Samsung and SK Hynix centralized sourcing decisions to Suwon headquarters, compressing qualified vendor bases from twelve to three.
- Aircraft Manufacturing:Primary and secondary structural bonding with 12-18 month third-party testing requirements. Boeing and Airbus thermal protection system suppliers face EU F-Gas reformulation mandates.
- Heavy Machinery:Equipment repair and component fixation in high-vibration environments. Japanese and German OEMs specify ceramic adhesives for turbine blade restoration.
- Home Appliance Production:Heating element mounting and thermal interface applications. Cost pressure favors epoxy over silicone formulations in this segment.
- Packaging:Specialized sealing for high-temperature processing equipment. Limited volume but consistent specification requirements.
Semiconductor fabrication holds installed capacity. Aircraft manufacturing is rotating up the share rankings on new platform introductions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German adhesive exports supply semiconductor fabrication lines across Taiwan and South Korea, establishing a primary trade corridor that channels high-purity epoxy formulations into Hsinchu and Suwon industrial clusters.
Germany
Automotive thermal management programs and semiconductor equipment OEMs absorb specialty ceramic adhesives for power module attachment. REACH registration requirements enforced by ECHA compel formulators to document full material toxicity profiles. Bavaria's Munich cluster hosts formulation chemists commanding premium compensation for hybrid inorganic-organic systems expertise.
China
Construction-grade ceramic adhesive volumes concentrate in urban facade bonding applications across megacity developments. GB standards enforcement by SAMR extends product registration timelines by 8-14 months for imported formulations. Yangtze River Delta manufacturing hubs face dual carbon goals pressure that will increasingly determine qualified supplier status.
South Korea
Solid-state battery pilot lines generate uncontracted demand for ceramic-to-metal bonding in lithium-metal anode architectures. Centralized procurement decisions at Samsung and SK Hynix headquarters in Suwon compress qualified vendor bases from twelve to three preferred partners. Busan-Ulsan industrial corridors anchor heavy machinery specifications for vibration-dampening assemblies.
Japan
TSMC and Intel packaging divisions drive qualification of nano-silica functionalized systems for 2.5D interposer bonding in Kansai and Chubu regions. METI industrial standards govern chemical content disclosure for electronics assembly materials. Nagoya automotive suppliers specify ceramic adhesives for electric motor thermal management in hybrid vehicle platforms.
United States
FDA device manufacturing regulations elevate barrier-to-entry for medical-grade adhesive suppliers while forcing incumbent formulators to maintain compliance documentation. Boston clusters compete with Munich for scarce formulation chemists in hybrid sol-gel chemistry systems. Aerospace prime contractors face 12-18 month ASTM E595 outgassing certification cycles that delay revenue recognition.
Global Ceramic Adhesives Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with adhesive divisions rather than pure-play specialists. Market structure concentrates procurement influence among three preferred partners per semiconductor fab, compressing vendor bases from twelve qualified suppliers. Strategic archetypes include construction-scale volume players, electronics-qualified specialty formulators, and aerospace-certified premium suppliers. Competitive moves center on direct-to-fab distribution partnerships and borate-free chemistry substitution investments.
Among European chemical conglomerates, Sika AG and Henkel AG & Co. KGaA occupy positions exemplifying the construction-electronics dual-track archetype, while Dow Inc. anchors the silicone thermal interface specialization tier. These three represent the dominant competitive anchors around which procurement consolidation patterns organize in German and East Asian fabrication clusters.
| Leading Market Players |
|---|
| Sika AG |
| Henkel AG & Co. KGaA |
| 3M Company |
| Dow Inc. |
| Mapei S.p.A. |
| Arkema SA |
| Pidilite Industries Limited |
| H.B. Fuller Company |
| Laticrete International Inc. |
| Others |
Supply & Pricing Matrix
Capacity utilization at German epoxy formulators sits above 85 percent, compressing marginal production for spot buyers and elevating price floors for non-contracted volumes in semiconductor thermal interface materials.
Pricing Analysis
UV-curable next-generation formulations command 40-60 percent premiums over heat-cured prior-generation systems, while legacy alumina-filled epoxies face cost compression from nano-silica displacement. Pricing stratifies across aerospace-certified, semiconductor-qualified, and construction-grade tiers, with ASTM E595 certification and REACH compliance as primary differentiation drivers. Price erosion runs through construction-grade acrylics as Chinese domestic production scales. Semiconductor fabs show lowest price sensitivity; building facade contractors exhibit highest.
Supply Chain Analysis
Australia and Brazil anchor high-purity alumina mining, while Germany and Japan concentrate specialty epoxy formulation. Supply chains draw from zirconia feedstock locked into South African and Russian mining complexes, creating single-source vulnerability for wide-bandgap power electronics grades. Distribution runs through equipment OEM service contracts at Applied Materials and Lam Research, bypassing traditional chemical distributors for qualified fab supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists skilled in hybrid sol-gel epoxy systems command compensation premiums exceeding 40 percent above commodity adhesive R&D roles, constraining expansion capacity for mid-tier players.
For Market Incumbents: Consolidate qualified supplier status at Samsung and SK Hynix by securing direct-to-fab distribution agreements in Suwon, eliminating distributor margin leakage. Invest in borate-free chemistry substitution ahead of ECHA enforcement waves to capture procurement windows from non-compliant competitors. Vertical integration into nano-silica functionalization secures feedstock for 2.5D interposer bonding qualifications at TSMC and Intel. For New Entrants and Emerging Players: ASTM E595 fast-track certification through European Space Agency prime contractor partnerships opens aerospace thermal protection system supply. Target solid-state battery pilot lines in South Korea as the most penetrable segment, where lithium-metal anode ceramic-to-metal bonding specifications remain uncontracted. Lead with alkoxy-silane cure system expertise to exploit EU F-Gas Regulation substitution mandates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty formulators with existing semiconductor qualifications over construction-scale volume players facing margin compression. Long-term viability hinges on captive access to high-purity alumina supply or nano-silica functionalization capability. Watch for consolidation signals when fab procurement teams reduce qualified vendor bases below three partners per chemistry family.| Strategic Initiative | Industry Significance |
|---|---|
| Borate-Free Chemistry Substitution | ECHA scrutiny of boron compounds compels reformulation investment to maintain European market access. |
| Direct-to-Fab Distribution Partnership | Bypassing regional distributors to supply Hsinchu and Dresden fabs compresses lead times and captures margin. |
| Nano-Silica Functionalization Scale-Up | TSMC and Intel packaging divisions qualify these systems for 2.5D interposer bonding applications. |
| ASTM E595 Certification Investment | Aerospace adhesive qualification requires 12-18 month third-party testing cycles that eliminate fast-follower competition. |
| Alkoxy-Silane Cure System Development | EU F-Gas Regulation restrictions force elimination of perfluorinated catalysts from silicone ceramic formulations. |
Research Methodology
Desk research of customs trade data, ECHA substance registration databases, and semiconductor equipment OEM procurement disclosures preceded structured interviews with adhesive formulator R&D directors, fab materials engineers at TSMC and Intel, and aerospace prime contractor supply chain managers. Primary fieldwork validated secondary findings on cure technology adoption rates and qualification timeline compression. Bottom-up volume estimates triangulated against top-down spending analysis from German and Japanese industrial clusters.
Variance decomposition across chemistry type, cure technology, application context, and end-user industry anchored the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro manufacturing capex indicators. Forecast inputs incorporated UV-curable adoption curves in semiconductor fabrication and solid-state battery assembly line commissioning schedules.
Underlying assumptions cover stable alumina feedstock pricing and REACH registration continuity, with deviation risk concentrated in ECHA substance restriction timing and GB standards enforcement intensity. Recalibration cycles align with material shifts in semiconductor node transitions and EU Green Deal embodied carbon tracking implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
EMEA Epoxy Adhesives Market
Adhesives & Sealants
South America Electronics Adhesives Market
Adhesives & Sealants
Global Hygiene Adhesives Market
Adhesives & Sealants
Global Construction Silicone Sealants Market
Adhesives & Sealants
Anti-Corrosion Tape Market
Adhesives & Sealants
Spray Fluxer Market
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Mexico Sealants Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Indonesia Adhesives Market