
 Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market | 2026-2036
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market Outlook
Subscription-based adhesive monitoring and predictive maintenance software is recalibrating how PU hot-melt value gets captured in Asia-Pacific supply chains. Henkel AG & Co. KGaA leverages its regional technical service infrastructure to lock in multi-year automotive contracts. H.B. Fuller Company anchors its position through backward integration into polyol sourcing across Southeast Asian plants. BASF SE differentiates via specialty-grade formulations tailored to electronics miniaturization trends in South Korea and Taiwan.
Asia-Pacific polyurethane hot-melt adhesives are thermoplastic or reactive systems formulated from isocyanate-terminated prepolymers that cure via moisture reaction, typically achieving open times of 30–180 seconds and bond strengths exceeding 8 MPa on polar substrates. Their primary commercial purpose is to replace mechanical fasteners and solvent-based adhesives in automated assembly environments where rapid green strength and temperature resistance prove critical. Flexible adhesives command widening share as athletic footwear brands outsource production to Vietnam and Indonesia, while specialty adhesives capture the highest margin pools in medical electronics bonding. The automotive application segment sustains volume leadership through interior trim and headlamp assembly demand across Japanese and Chinese OEM supply chains.
China's MEE enforces VOC content limits under GB standards that directly restrict solvent-based adhesive use in Shanghai and Jiangsu manufacturing zones. Japan's METI promotes next-generation material adoption through JIS-compliant sustainability certifications that favor low-emission bonding systems. South Korea's MFDS and KOSHA jointly regulate workplace chemical exposure, creating compliance-driven upgrade cycles for woodworking and textile operations. Stakeholders must track how REACH-aligned substance restrictions propagate through ASEAN harmonization frameworks and whether India's BIS adopts comparable adhesive emission standards.
Market Dynamics
China's dual carbon goals and tightening VOC emission standards are compressing the window for solvent-based adhesive systems, forcing automotive and electronics manufacturers across the Asia-Pacific region to accelerate reactive hot-melt adoption timelines.
Growth Catalysts
- GB Standards Enforcement:China's MEE VOC content limits under GB standards restrict solvent-based adhesive use in Shanghai and Jiangsu manufacturing zones, redirecting procurement toward reactive hot-melt alternatives.
- Automotive Lightweighting:Japanese and Chinese OEM supply chains are expanding adhesive bonding for interior trim and headlamp assembly as structural weight reduction targets tighten.
- Electronics Miniaturization:South Korean and Taiwanese contract manufacturers are scaling specialty-grade PU hot-melt consumption for medical electronics bonding applications.
Market Restraints
- Isocyanate Feedstock Volatility:MDI and polyol input costs fluctuate with crude oil derivatives and regional petrochemical capacity constraints, compressing formulation margins.
- Technical Curing Limitations:Moisture-cure systems require controlled humidity environments that constrain deployment in high-altitude or arid manufacturing locations.
- Substitution Threat from UV-Curable Systems:Instant-cure UV acrylics are capturing share in electronics assembly where open time flexibility matters less than throughput speed.
Strategic Opportunities
- Vietnam and Indonesia Footwear Expansion:Athletic footwear brands are consolidating outsourced production in these markets, creating concentrated demand for flexible adhesive formulations.
- JIS-Compliant Sustainability Certifications:Japan's METI low-emission bonding system incentives favor suppliers with verified carbon footprint documentation.
- IoT-Enabled Predictive Maintenance:Subscription-based adhesive monitoring software is converging with equipment OEM service contracts to capture recurring revenue streams.
Industry Challenges
- Reactive Chemistry Expertise Gap:Formulation engineers with moisture-cure system experience command premium compensation in Southeast Asian labor markets.
- Multi-Jurisdiction Certification Timelines:Separate MFDS, KOSHA, and BIS compliance pathways delay product launches across Northeast and South Asian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market |
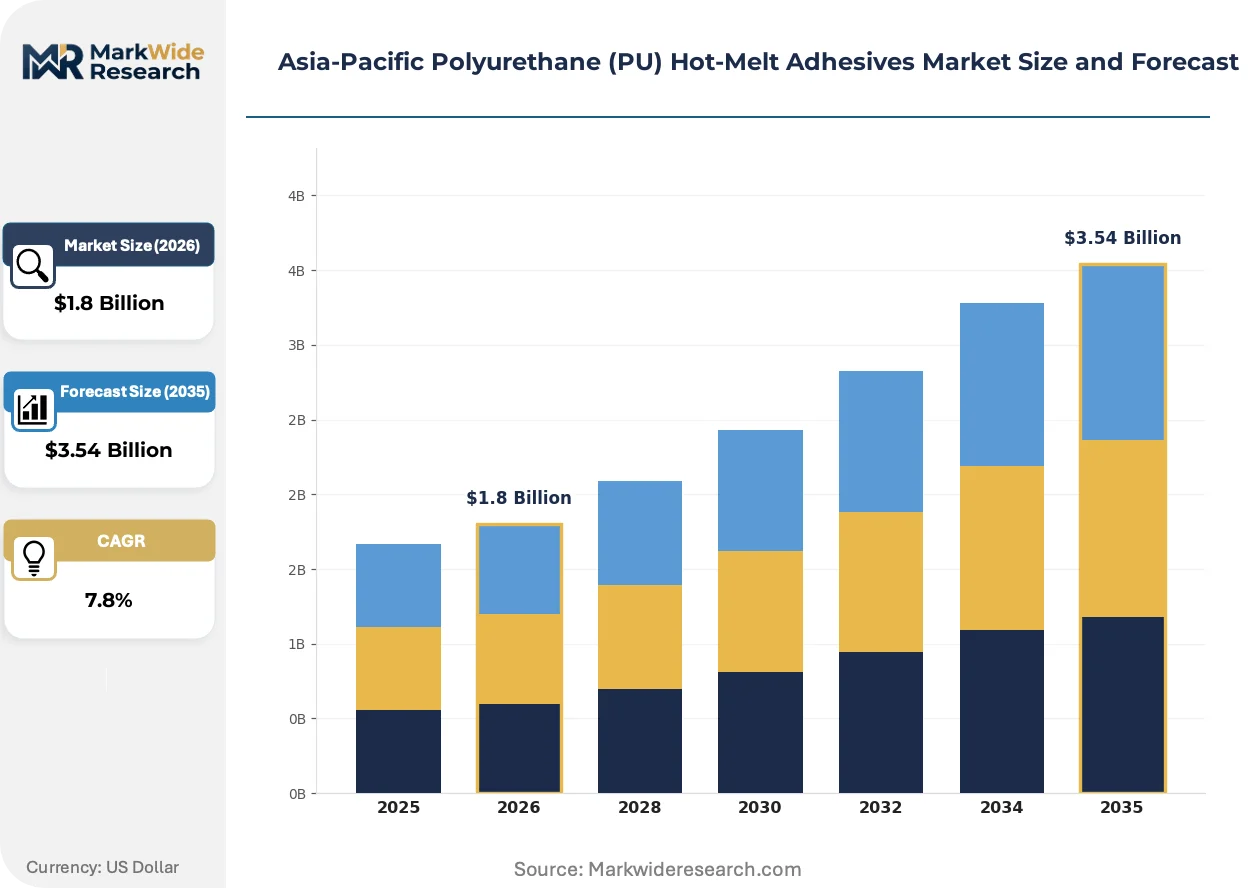
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Adhesives, Flexible Adhesives, Rigid Adhesives, Specialty Adhesives Application: Footwear, Furniture, Packaging, Automotive End User: Construction, Electronics, Textile, Woodworking Packaging Type: Bulk, Cartridge, Drum, Sachet |
| Companies Covered | 3M, H.B. Fuller Company, Henkel AG & Co. KGaA, Sika AG, Arkema Group, BASF SE, Bostik Inc, Huntsman Corporation, Nanpao Resins Chemical Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market Strategic Shifts
Reactive polyurethane chemistry is converging with digital manufacturing infrastructure, reshaping how adhesive value gets captured across Asia-Pacific assembly operations. Three distinct vectors are compressing traditional supply arrangements.
Moisture-reactive prepolymer systems with tunable open times are converging with automated dispensing robotics in Chinese automotive plants. Tier-1 suppliers in Guangdong and Zhejiang are retrofitting existing lines to accommodate 30–180 second working windows. This convergence is compressing the competitive advantage of mechanical fastening equipment vendors.
REACH-aligned substance restrictions are propagating through ASEAN harmonization frameworks, with Thailand and Vietnam adopting comparable adhesive emission screening protocols. Industrial consequence includes mandatory substance disclosure requirements for imported formulations. Electronics contract manufacturers in Malaysia and the Philippines are restructuring supplier qualification processes to preempt compliance failures.
Footwear OEMs are consolidating adhesive procurement under direct material partnerships rather than through tiered distributor networks. Vietnamese and Indonesian factory operators are negotiating volume commitments with formulation houses for multi-year supply security. This channel compression is most visible in Ho Chi Minh City and Jakarta manufacturing corridors where brand technical audits now precede contract awards.
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market Segmentation
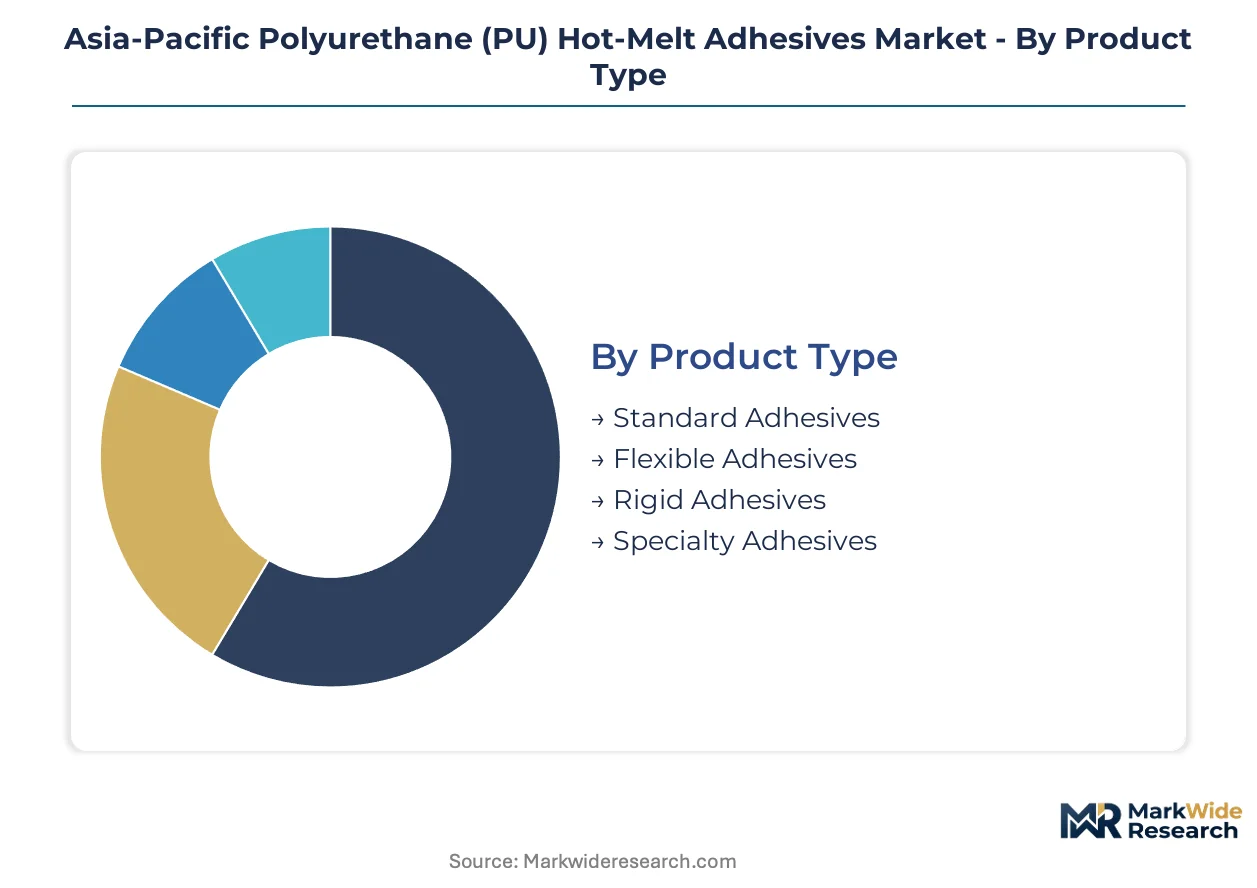
Segmentation in Asia-Pacific PU hot-melt adhesives reveals how formulation chemistry, application requirements, and supply logistics create distinct competitive battlegrounds. Each dimension carries different margin profiles and capital requirements that reshape supplier positioning across Chinese automotive corridors and Southeast Asian footwear clusters.
Product Type:
Capital intensity varies sharply across product categories, with specialty-grade reactors and moisture-cure control systems demanding the heaviest upfront investment.
- Specialty Adhesives:Medical-grade and electronics-focused formulations with ultra-low viscosity variance and sub-50 ppm ionic contamination specifications. South Korean contract manufacturers in Gyeonggi Province are scaling consumption for smartphone and wearable device bonding as device miniaturization tightens tolerance windows.
- Flexible Adhesives:Elastomeric systems formulated with polyester or polyether soft segments for dynamic flex resistance. Vietnamese and Indonesian footwear factories in Ho Chi Minh City and Tangerang are consolidating procurement under direct partnerships with formulation houses as athletic brands outsource production.
- Standard Adhesives:General-purpose reactive systems for commodity woodworking and packaging applications across China's central provinces.
- Rigid Adhesives:High-modulus formulations for structural bonding in furniture and construction panels with limited flexural recovery.
Most installed capacity flows through Standard Adhesives. Expansion is steepest in Specialty Adhesives.
Application:
Application segmentation tracks how end-use performance requirements fragment procurement patterns across divergent manufacturing ecosystems.
- Automotive:Interior trim, headlamp assembly, and structural bonding applications where temperature cycling resistance and VOC compliance prove critical. Japanese and Chinese OEM supply chains across Guangdong and Zhejiang are expanding adhesive bonding as structural weight reduction targets tighten.
- Footwear:Upper-to-sole bonding and decorative element attachment requiring dynamic flex fatigue resistance. Indonesian factory operators in Jakarta manufacturing corridors are negotiating multi-year volume commitments for supply security.
- Furniture:Panel lamination and edge-banding applications with moderate performance requirements and price-sensitive procurement.
- Packaging:High-speed case and carton sealing where open time and green strength balance against line speed constraints.
Automotive commands the highest formulation margins. Footwear is gaining share fastest as production consolidates in Vietnam and Indonesia.
End User:
End-user segmentation exposes how regulatory exposure and technical sophistication reshape customer-supplier relationships across divergent industrial verticals.
- Electronics:Medical device and consumer electronics bonding with cleanroom-compatible dispensing and ionic purity certification. Taiwanese contract manufacturers are restructuring supplier qualification processes to preempt REACH-aligned substance disclosure failures.
- Construction:Panel bonding, insulation attachment, and flooring applications where China's GB standards enforcement redirects procurement away from solvent-based alternatives.
- Textile:Lamination and seam-sealing applications for technical apparel and automotive interiors with wash durability requirements.
- Woodworking:Furniture and millwork assembly where South Korea's KOSHA workplace chemical exposure regulations drive compliance-driven upgrade cycles.
Electronics generates the highest margin pool. Construction delivers the steepest volume expansion as China's dual carbon goals compress solvent-based system timelines.
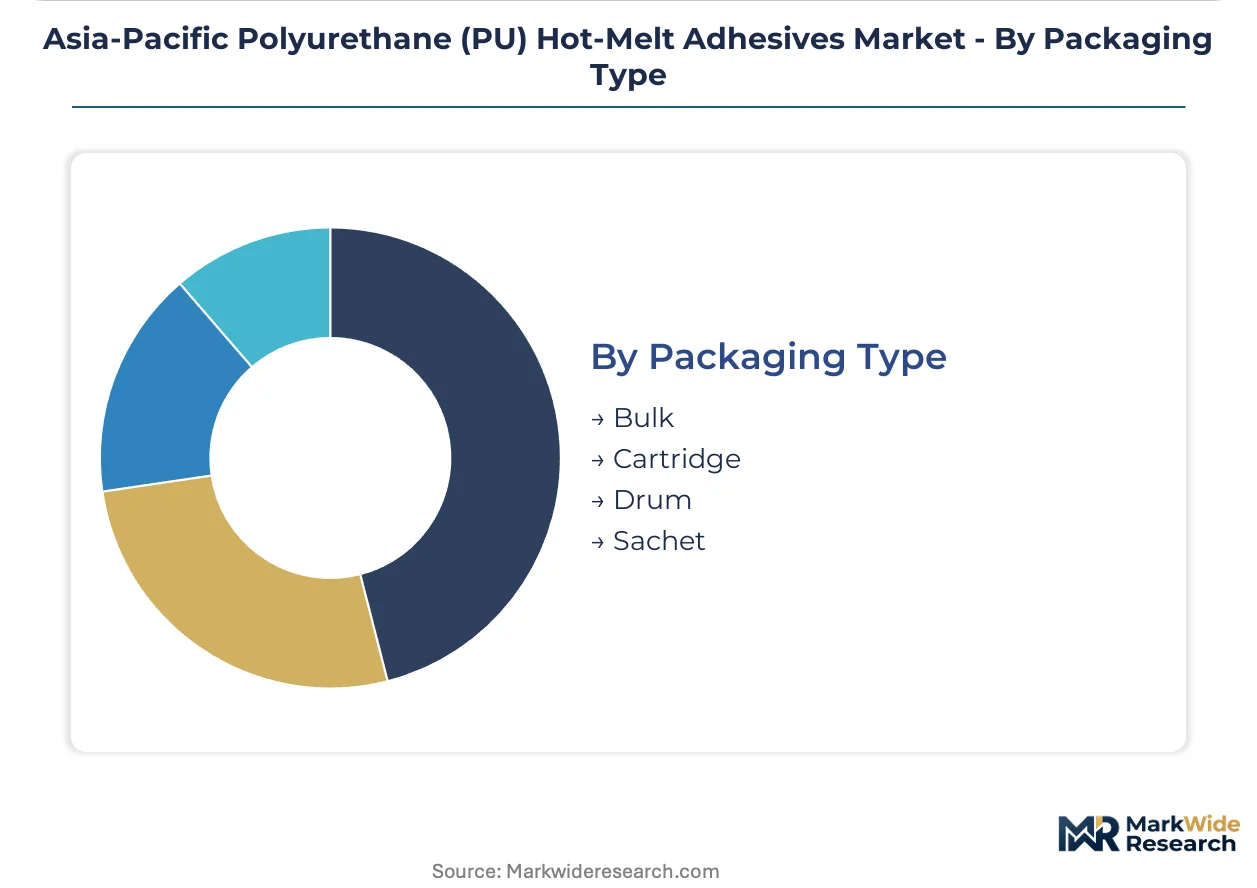
Packaging Type:
Packaging format segmentation reflects how logistics economics and application scale reshape distribution channel structure across fragmented customer bases.
- Bulk:Tanker and tote deliveries for high-volume automotive and footwear manufacturers with captive dispensing systems. Guangdong automotive tier-1 suppliers are retrofitting lines to accommodate 30–180 second open time windows for reactive systems.
- Drum:Intermediate-volume containers for mid-scale furniture and woodworking operations with periodic replenishment cycles.
- Cartridge:Manual and pneumatic dispensing formats for repair, maintenance, and small-batch manufacturing across distributed electronics workshops.
- Sachet:Single-use pouches for field applications and emerging market small-scale users with limited capital equipment.
Bulk shipments dominate volume throughput. Cartridge formats are expanding most quickly as electronics miniaturization spreads adhesive use to smaller-scale contract manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed base of reactive hot-melt capacity, yet Vietnam and Indonesia are capturing the fastest procurement growth as footwear brands consolidate outsourced manufacturing.
China
Automotive assembly lines across Guangdong and Zhejiang are retrofitting equipment to accommodate moisture-cure systems with 30–180 second open times. The MEE enforces GB standards VOC content limits that restrict solvent-based adhesive use in Shanghai and Jiangsu manufacturing zones. Eastern manufacturing corridors concentrate demand from footwear and electronics OEMs operating at industrial scale.
Japan
Japanese OEM supply chains are expanding adhesive bonding for interior trim and headlamp assembly as structural weight reduction targets tighten. METI promotes next-generation material adoption through JIS-compliant sustainability certifications that favor low-emission bonding systems. Tier-1 suppliers in Nagoya and Osaka manufacturing clusters are qualifying reactive systems for multi-year automotive contracts.
South Korea
Contract manufacturers in Gyeonggi Province are scaling specialty-grade PU hot-melt consumption for smartphone and wearable device bonding as device miniaturization tightens tolerance windows. The MFDS and KOSHA jointly regulate workplace chemical exposure, creating compliance-driven upgrade cycles for woodworking and textile operations. Seoul Capital Area electronics clusters are restructuring supplier qualification processes to preempt REACH-aligned substance disclosure failures.
Vietnam
Athletic footwear brands are consolidating outsourced production in Ho Chi Minh City manufacturing corridors, creating concentrated demand for flexible adhesive formulations. Factory operators are negotiating multi-year volume commitments with formulation houses for supply security. Direct material partnerships are replacing tiered distributor networks as brand technical audits precede contract awards.
Indonesia
Indonesian factory operators in Jakarta and Tangerang are securing long-term supply agreements for flexible adhesives used in upper-to-sole bonding applications. The country's national chemical regulator is adopting emission screening protocols aligned with ASEAN harmonization frameworks. Manufacturing corridors are experiencing channel compression as procurement consolidates under direct partnerships with international formulation houses.
Asia-Pacific Polyurethane (PU) Hot-Melt Adhesives Market Competitive Environment
Top-tier vendors anchor premium formulation supply, while regional specialists and local distributors occupy mid-market and commodity segments. The vendor base stratifies across three tiers: multinational chemical conglomerates with captive polyol sourcing, mid-scale regional formulators with technical service capabilities, and local distributors serving fragmented woodworking and packaging accounts. Two dominant competitive moves are reshaping positioning: backward integration into polyol production across Southeast Asian plants, and subscription-based adhesive monitoring software bundled with equipment service contracts.
Among European-headquartered chemical conglomerates, Henkel AG & Co. KGaA and BASF SE occupy positions exemplifying divergent strategic archetypes. Henkel leverages regional technical service infrastructure to secure multi-year automotive contracts, while BASF differentiates via specialty-grade formulations. H.B. Fuller Company represents the North American multinational tier, anchoring its position through upstream control over polyol sourcing. These three entities collectively illustrate how geographic origin and integration depth determine competitive positioning across Asia-Pacific supply chains.
| Leading Market Players |
|---|
| 3M |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| Sika AG |
| Arkema Group |
| BASF SE |
| Bostik Inc |
| Huntsman Corporation |
| Nanpao Resins Chemical Group |
| Others |
Value Chain & Pricing Dynamics
Moisture-cure reactive chemistry adoption across Guangdong and Zhejiang automotive plants is compressing equipment amortization timelines while concentrating procurement leverage among tier-1 suppliers with captive dispensing infrastructure. This production-method transition simultaneously elevates formulation premiums for specialty-grade systems and squeezes margins on standard adhesives as buyers consolidate volume under direct partnerships.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for flexible adhesive grades as footwear OEMs negotiate multi-year volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade specialty formulations with ionic purity certification from commodity woodworking adhesives. Pricing pressure stems from MDI and polyol feedstock volatility tied to regional petrochemical capacity constraints. Woodworking and packaging buyers exhibit highest price sensitivity, while electronics contract manufacturers prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Shanghai, Ho Chi Minh City, and Jakarta operate hub-and-spoke patterns to serve fragmented footwear and electronics manufacturing clusters. Supply concentrates in China, Vietnam, and Indonesia for formulated adhesives, with MDI and polyester polyol inputs drawn from Northeast Asian petrochemical complexes. Single-source vulnerability runs through isocyanate feedstock channels constrained by regional cracker maintenance cycles. Distribution runs through bulk tanker deliveries for automotive tier-1 suppliers and drum shipments for mid-scale furniture operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
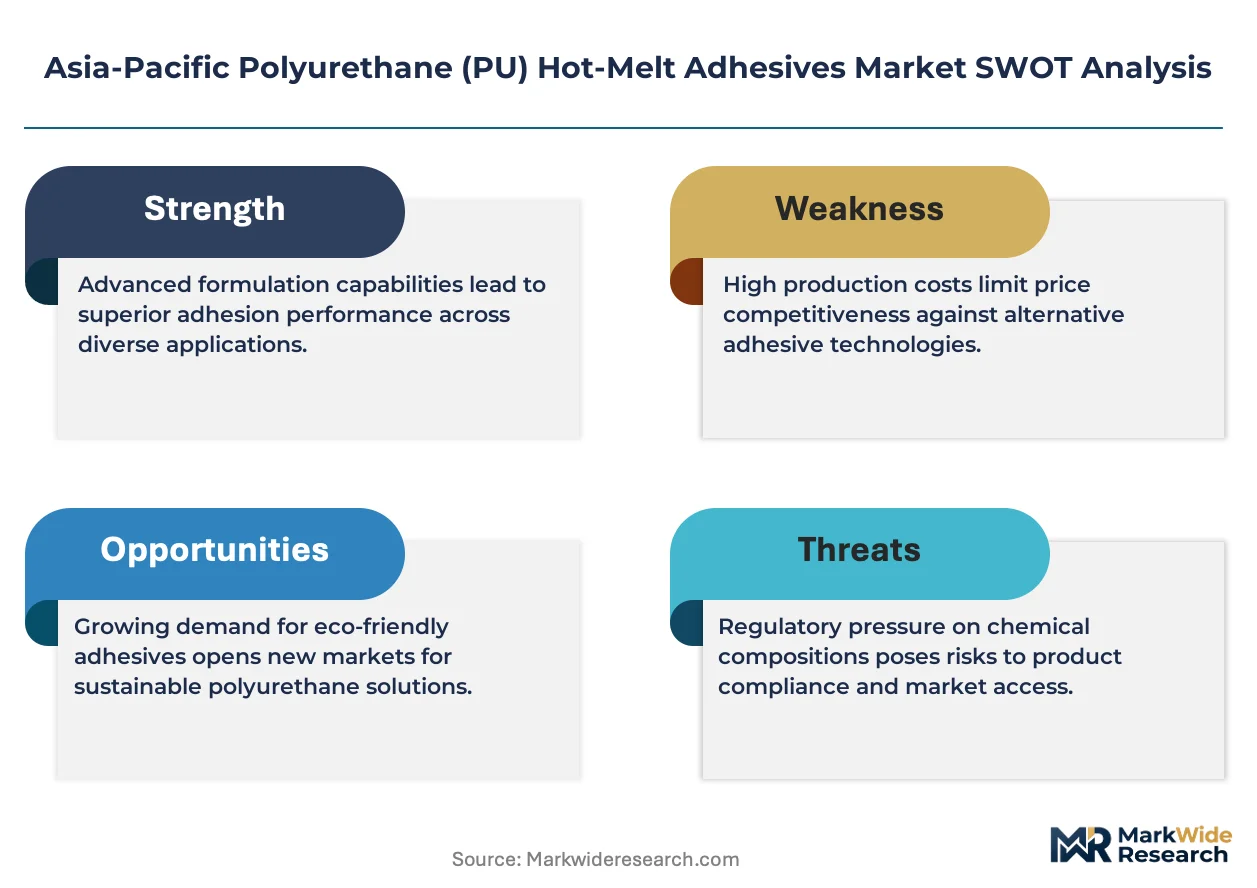
Margin expansion in this market rests on specialty-grade formulation premiums and backward integration into polyol sourcing that captures value from volatile feedstock markets.
For Market Incumbents: Deploy technical service bundling to lock in multi-year automotive contracts as UV-curable acrylics threaten electronics assembly share. Deepen backward integration into Southeast Asian polyol production to defend margin position against MDI price volatility. Secure JIS-compliant sustainability certifications ahead of METI incentive program expansions. For New Entrants and Emerging Players: Equipment OEMs represent the most accessible channel partner type for adhesive monitoring software subscriptions targeting mid-scale Vietnamese footwear factories. White-space exists in cartridge-format specialty adhesives for distributed electronics workshops across Malaysia and the Philippines. Pursue direct material partnerships with Indonesian factory operators bypassing tiered distributor networks. For Investors and Strategic Acquirers: Roll-up economics work for regional formulators with technical service capabilities because procurement consolidation under direct partnerships favors scaled suppliers with in-house R&D. Five-to-ten-year viability hinges on specialty-grade exposure and captive polyol sourcing. Watch ASEAN harmonization of REACH-aligned substance restrictions as the inflection signal for compliance-driven upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Sourcing | H.B. Fuller's Southeast Asian plant network secures margin protection against MDI volatility. |
| Long-term Supply Agreement | Vietnamese footwear OEMs negotiate multi-year volume commitments with formulation houses for supply security. |
| Green Manufacturing Transition | China's MEE GB standards enforcement redirects procurement from solvent-based to reactive hot-melt systems. |
| Joint Venture | Henkel leverages regional technical service infrastructure to capture recurring revenue from predictive maintenance software. |
| Capacity Expansion | BASF scales specialty-grade production for South Korean and Taiwanese electronics miniaturization demand. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with adhesive formulation chemists, automotive tier-1 procurement leads, footwear factory operations managers, and electronics contract manufacturer supply chain directors with secondary validation from customs trade data, ACC regional reports, SEC 10-K chemical segment disclosures, and ASEAN regulatory harmonization documents. Bottom-up volume estimates triangulated against top-down market sizing across product grade tiers and end-use industries.
Segment-weighting applied differential growth assumptions across specialty, flexible, standard, and rigid adhesive categories, with automotive lightweighting intensity, electronics miniaturization penetration, and footwear outsourcing velocity serving as demand drivers across the projection horizon. CAGRs derived from regression analysis of historical capacity utilization, feedstock cost trajectories, and regulatory compliance upgrade cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ASEAN regulatory harmonization pace and isocyanate feedstock supply disruptions. Forecasts reflect documented assumptions around automotive production schedules and electronics outsourcing trends. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
Asia-Pacific EVA Adhesives Market
Adhesives & Sealants
Middle East & Africa Automotive Adhesives & Sealants Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
Heat Resistant Sealant Market
Adhesives & Sealants
North America Glue-Laminated Timber Market
Adhesives & Sealants
South America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
Global Automotive Adhesive Market
Adhesives & Sealants
Acrylic Flooring Adhesives Market