
 Asia-Pacific Laminated Adhesives Market | 2026-2036
Asia-Pacific Laminated Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Laminated Adhesives Market Outlook
Skilled formulation chemists familiar with reactive hot-melt chemistry is bifurcating the competitive landscape across the Asia-Pacific laminated adhesives sector. Dow leverages its regional polymer science infrastructure to sustain leadership in water-based acrylic platforms for flexible packaging. Henkel AG & Co. KGaA anchors its position through specialized polyurethane systems serving automotive interior lamination in South Korea and Thailand. H.B. Fuller competes by extending its reactive adhesive portfolio to address high-temperature performance requirements in Japanese electronics packaging.
Asia-Pacific laminated adhesives are multi-layer bonding agents engineered from polyurethane, epoxy, acrylic, or silicone chemistries, typically applied at coat weights between two and six grams per square meter to create durable substrates for flexible packaging, furniture panels, and vehicle interiors. Their primary commercial purpose is to join dissimilar materials—polyester to aluminum foil, oriented polypropylene to polyethylene—while maintaining seal integrity under thermal and mechanical stress. Water-based technology occupies the largest volume share as environmental compliance tightens, though reactive systems represent the fastest-expanding margin pool due to their elimination of drying energy and solvent recovery costs. Polyurethane formulations dominate high-performance packaging applications requiring retort sterilization, while acrylic adhesives sustain growth in furniture lamination where ultraviolet resistance and cost efficiency matter most.
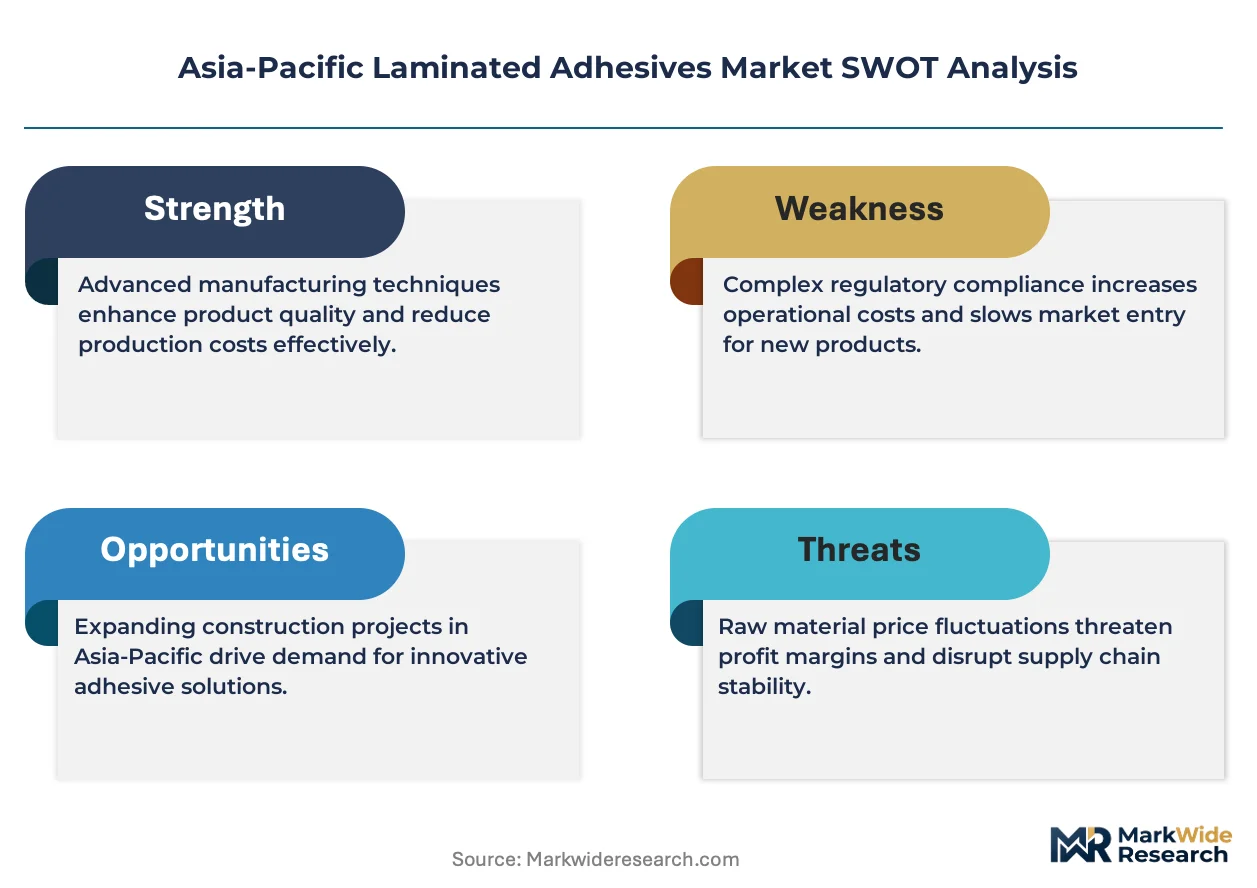
China's Ministry of Ecology and Environment enforces GB standards limiting volatile organic compound emissions from adhesive production, compelling manufacturers to reformulate solvent-based lines or absorb compliance penalties. Japan's METI promotes JIS-certified low-emission adhesives through procurement guidelines affecting construction and automotive supply chains. India's BIS mandates migration testing for food-contact laminates, creating barrier-to-entry conditions for uncertified imports. Stakeholders must monitor how these divergent national frameworks reshape regional supply chain configurations and determine whether centralized formulation hubs or country-specific blending assets offer superior compliance economics.
Market Dynamics
China's GB standards on volatile organic compound emissions are forcing wholesale reformulation of solvent-based adhesive lines across the Asia-Pacific laminated adhesives sector, compressing legacy capacity while accelerating investment in water-based and reactive systems.
Growth Catalysts
- Food-contact compliance mandates:India's BIS migration testing requirements for pharmaceutical blisters and retort pouches are pulling high-performance polyurethane systems into domestic production.
- Solvent-free lamination expansion:Flexible packaging converters across Southeast Asia are adding capacity to meet export market specifications and reduce drying energy costs.
- Dual carbon policy alignment:China's Ministry of Ecology and Environment enforcement of GB standards is redirecting R&D expenditure toward water-based acrylic platforms with lower carbon footprints.
Market Restraints
- Isocyanate input volatility:Polyurethane feedstock costs fluctuate with crude-linked MDI and TDI pricing, squeezing margin predictability for formulators serving automotive interior lamination.
- Specialized talent scarcity:Skilled chemists capable of reactive hot-melt formulation remain concentrated in Japan and South Korea, constraining technical service expansion elsewhere.
- Substitution pressure from thermal bonding:Heat-seal technologies in low-performance packaging segments bypass adhesive layers entirely, capping volume growth in commodity grades.
Strategic Opportunities
- Underpenetrated Indian western corridor:Mumbai-Pune packaging clusters lack sufficient local supply of retort-grade adhesives, creating white space for certified domestic production.
- Automotive lightweighting convergence:Multi-material bonding for electric vehicle battery enclosures and interior panels is opening specification windows for epoxy and silicone hybrid systems.
- Japan METI procurement guidelines:JIS-certified low-emission adhesive preferences in construction and automotive supply chains offer premium positioning for compliant formulators.
Industry Challenges
- Reactive chemistry skill gaps:Formulation expertise in moisture-cure and UV-acrylic systems remains scarce outside established Japanese and South Korean technical centers, limiting quality consistency.
- Certification timeline compression:BIS food-contact testing and GB VOC compliance documentation require 12-18 month validation cycles, delaying product launches for reformulated lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Laminated Adhesives Market |
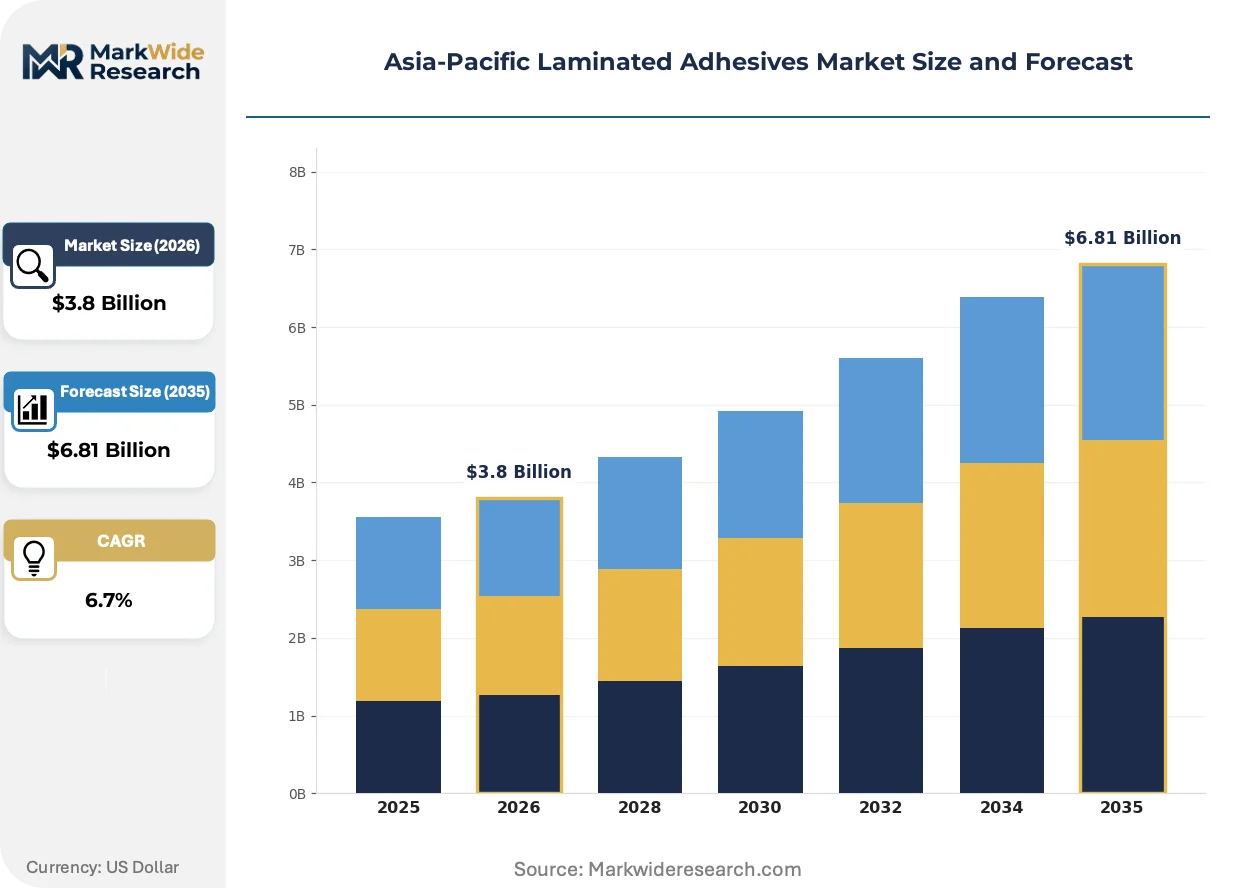
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Silicone Application: Packaging, Furniture, Automotive, Construction End User: Manufacturers, Contractors, Retailers, Distributors Technology: Solvent-Based, Water-Based, Hot Melts, Reactive |
| Companies Covered | Toyo INK Group, Ashland, Dow, Arkema, HuberGroup, Henkel AG & Co. KGaA, H.B. Fuller, LG Chem, 3M, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Laminated Adhesives Market Strategic Shifts
Reactive adhesive platforms are actively displacing conventional solvent-based systems across Asia-Pacific flexible packaging, driven by energy cost reduction and regulatory pressure. Three convergent developments are restructuring competitive positioning.
Two-component polyurethane chemistry with built-in moisture scavengers is bifurcating the high-performance packaging segment. Retort pouch manufacturers in Thailand and Vietnam are adopting these systems at accelerating rates to eliminate solvent recovery infrastructure. The technology is bifurcating market tiers between converters with capital for reactive equipment and those trapped in legacy solvent lines facing compliance penalties.
China's Ministry of Ecology and Environment is tightening GB 33372-2020 enforcement on adhesive VOC content limits, compelling domestic formulators to retire solvent-based production or absorb facility upgrade costs. Japanese electronics packaging suppliers are most affected, accelerating partnerships with water-based acrylic specialists to maintain China market access.
Specification-driven procurement is consolidating buyer power among Southeast Asian flexible packaging converters serving multinational food brands. Direct technical collaboration between adhesive formulators and brand quality teams is displacing distributor-mediated purchasing in Vietnam and Indonesia. This pattern is most visible in Ho Chi Minh City and Jakarta, where converter consolidation has created specification gatekeepers controlling annual contract volumes.
Asia-Pacific Laminated Adhesives Market Segmentation
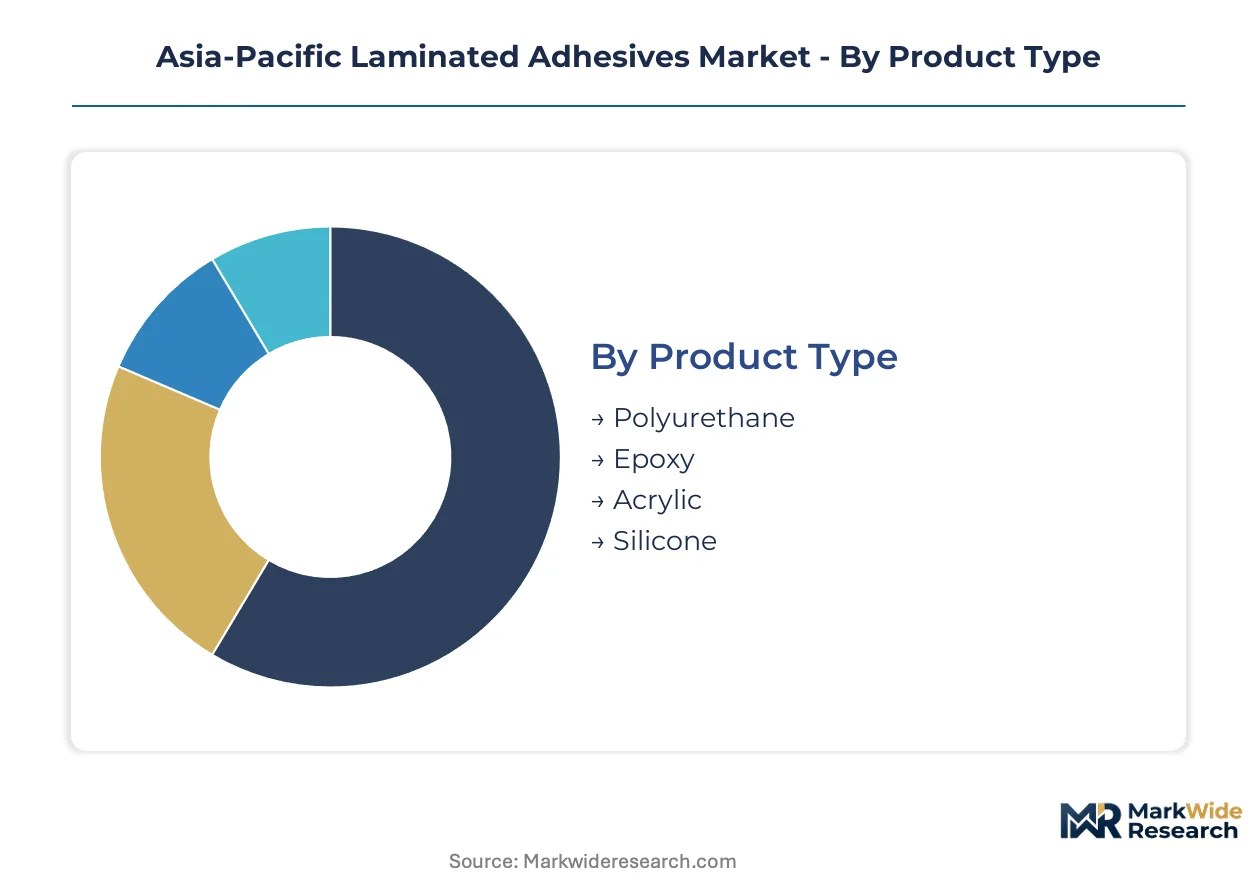
Segmentation in the Asia-Pacific laminated adhesives sector reveals how substitution pressures and compliance costs reshape competitive boundaries across chemistry platforms and bonding technologies. Understanding these divides enables formulators to prioritize R&D spending and capacity investments where margin protection remains strongest.
Product Type:
Polyurethane and acrylic systems face divergent substitution threats from thermal bonding and heat-seal alternatives in low-performance packaging tiers, forcing suppliers to defend specification positions through certification investments.
- Polyurethane:Two-component systems with moisture-scavenger chemistry dominate retort pouch and pharmaceutical blister applications requiring sterilization resistance. Mumbai-Pune packaging clusters in India's western corridor pull high-performance grades for food-contact compliance, though isocyanate feedstock volatility compresses margin predictability.
- Acrylic:Water-based emulsions sustain cost-efficient furniture lamination where ultraviolet resistance matters more than thermal performance. Japanese electronics packaging suppliers are accelerating partnerships with acrylic specialists to maintain China market access under tightening GB VOC standards.
- Epoxy:Hybrid formulations serve electric vehicle battery enclosure bonding where multi-material adhesion and thermal management converge.
- Silicone:High-temperature grades address automotive interior panels and construction membranes requiring flexibility across thermal cycling.
Polyurethane anchors the volume base while acrylic gains share at the steepest rate.
Application:
Cost tier differentiation separates premium specification-grade applications from commodity bonding where adhesive layers face elimination by alternative joining methods.
- Packaging:Flexible packaging converters across Southeast Asia are expanding solvent-free lamination capacity to meet export specifications and reduce drying energy expenditures. Retort pouch manufacturers in Thailand and Vietnam are adopting reactive polyurethane systems at accelerating rates to eliminate solvent recovery infrastructure.
- Automotive:Multi-material bonding for electric vehicle battery enclosures and interior panels opens specification windows for epoxy and silicone hybrid systems. Henkel AG & Co. KGaA anchors its regional position through specialized polyurethane systems serving automotive interior lamination in South Korea and Thailand.
- Furniture:Cost-driven lamination of decorative surfaces and panel substrates favors acrylic adhesives where ultraviolet resistance and price efficiency outweigh performance thresholds.
- Construction:JIS-certified low-emission adhesive preferences in Japanese building supply chains create premium positioning for compliant formulators serving membrane and insulation bonding.
Packaging commands the largest volume commitment while automotive climbs fastest on electrification-driven specification changes.
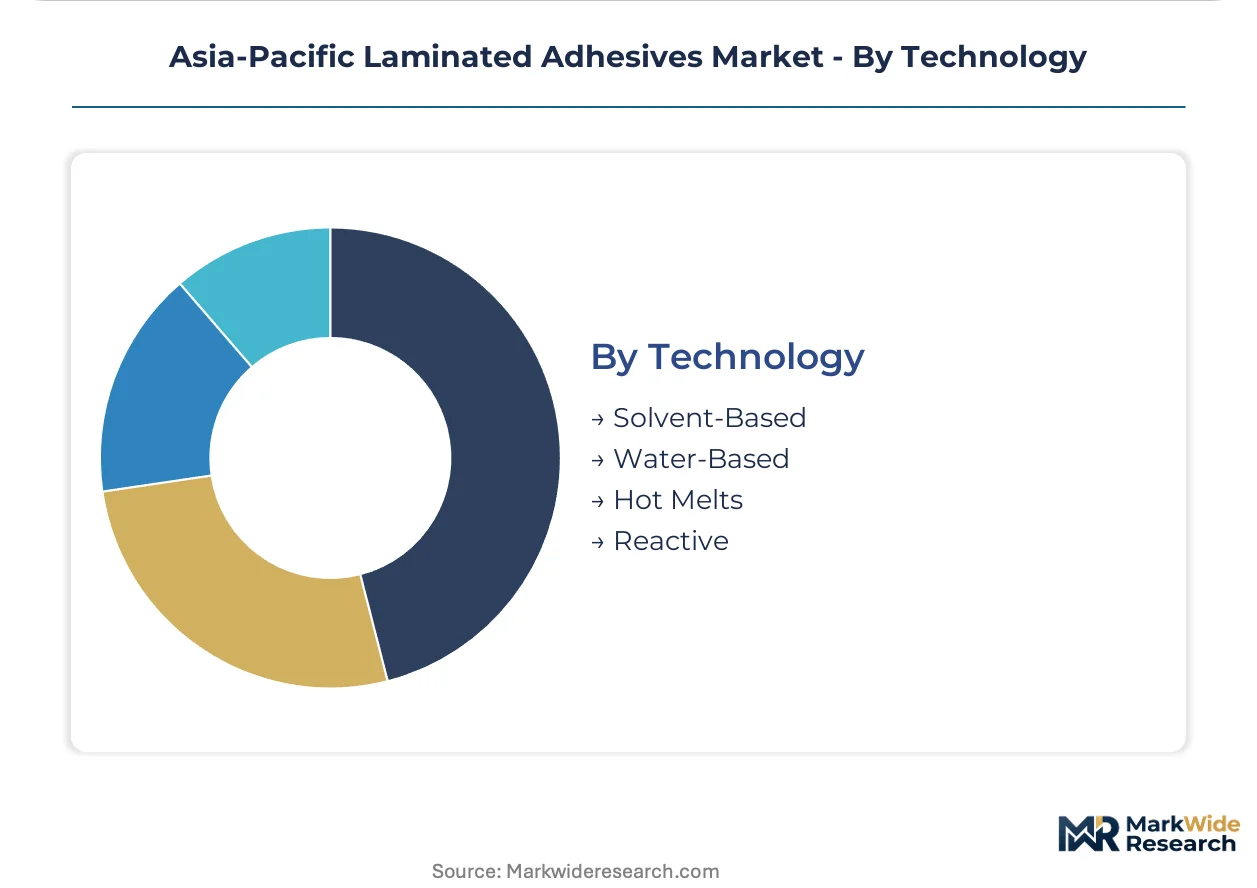
Technology:
Volume concentration favors mature bonding platforms, though margin expansion concentrates in systems eliminating energy-intensive drying and solvent recovery steps.
- Water-Based:Acrylic and polyurethane emulsions occupy the largest volume share as China's Ministry of Ecology and Environment enforcement tightens. Dow leverages regional polymer science infrastructure to sustain leadership in water-based acrylic platforms for flexible packaging.
- Reactive:Two-component polyurethane and UV-acrylic systems represent the fastest-expanding margin pool through elimination of drying energy and solvent recovery costs. H.B. Fuller competes by extending its reactive adhesive portfolio to address high-temperature performance requirements in Japanese electronics packaging.
- Solvent-Based:Legacy capacity faces wholesale reformulation pressure under China's GB standards on volatile organic compound emissions, compressing remaining production lines.
- Hot Melts:Reactive hot-melt chemistry requires skilled formulation chemists concentrated in Japan and South Korea, constraining technical service expansion elsewhere in the region.
Water-based technology retains volume dominance while reactive platforms capture the steepest margin expansion trajectory.
End User:
Customer type determines procurement leverage, with consolidated manufacturers extracting specification authority over fragmented distributor channels.
- Manufacturers:Flexible packaging converters serving multinational food brands are consolidating buyer power through direct technical collaboration with adhesive formulators, displacing distributor-mediated purchasing in Vietnam and Indonesia.
- Contractors:Construction and automotive assembly operations require JIS-certified or BIS-compliant adhesives with documented migration testing, creating barrier-to-entry conditions for uncertified supply.
- Distributors:Channel intermediaries face margin compression as specification-driven procurement concentrates volume among converter gatekeepers in Ho Chi Minh City and Jakarta.
- Retailers:Furniture and consumer goods outlets represent price-sensitive demand for standard-grade acrylic laminating adhesives with minimal technical service requirements.
Manufacturers control the largest contract volumes while contractors drive the fastest compliance-premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Asia-Pacific laminated adhesives sector diverge sharply between industrial corridors pursuing export-grade food-contact compliance and domestic markets prioritizing cost-efficient furniture lamination.
China
Flexible packaging converters in the Yangtze River Delta and Pearl River Delta are retiring solvent-based capacity under MEE enforcement of GB 33372-2020 VOC limits. Shanghai-based formulators are redirecting R&D expenditure toward water-based acrylic platforms. Zhejiang province hosts the largest concentration of reactive adhesive pilot lines serving electronics packaging exporters.
India
Retort pouch manufacturers in Maharashtra's Mumbai-Pune corridor are pulling high-performance polyurethane systems for pharmaceutical blister compliance. BIS migration testing mandates for food-contact laminates are compressing import timelines. Gujarat's chemical belt is adding domestic blending capacity to serve western industrial demand.
Japan
Automotive interior lamination in Toyota City and Nagoya maintains specification authority for reactive polyurethane systems. METI procurement guidelines favoring JIS-certified low-emission adhesives are reshaping construction supply chains. Kanto region electronics packagers are partnering with water-based specialists to preserve China market access.
South Korea
Battery enclosure bonding for Hyundai and Kia electric vehicle platforms is opening specification windows for epoxy-silicone hybrid systems. Ulsan automotive clusters require specialized polyurethane laminating adhesives with thermal cycling resistance. Seoul Capital Area technical centers concentrate formulation expertise in moisture-cure chemistry.
Vietnam
Ho Chi Minh City flexible packaging converters are consolidating buyer power through direct technical collaboration with adhesive formulators. Solvent-free lamination capacity expansion targets export specifications to European and North American food brands. Binh Duong province hosts accelerating reactive system adoption among retort pouch manufacturers.
Asia-Pacific Laminated Adhesives Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational chemical conglomerates commanding polymer science infrastructure while regional formulators defend niche certification positions. The competitive landscape organizes around three strategic archetypes: diversified materials science conglomerates with captive resin supply, adhesive specialists with deep formulation expertise in reactive chemistries, and packaging-focused suppliers with direct converter relationships. M&A activity concentrates on water-based technology assets in China and India, while strategic partnerships between Japanese electronics packagers and acrylic specialists accelerate under GB compliance pressure.
Among diversified chemical conglomerates, Dow and LG Chem occupy positions anchored by regional polymer science infrastructure. Henkel AG & Co. KGaA and H.B. Fuller exemplify the formulation specialist archetype with differentiated technology portfolios. Toyo INK Group represents the packaging-integrated vector with direct technical collaboration models across Southeast Asian converter networks.
| Leading Market Players |
|---|
| Toyo INK Group |
| Ashland |
| Dow |
| Arkema |
| HuberGroup |
| Henkel AG & Co. KGaA |
| H.B. Fuller |
| LG Chem |
| 3M |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between flexible packaging converters and polyurethane formulators lock in MDI supply access while insulating margin visibility against isocyanate feedstock swings across the Asia-Pacific laminated adhesives sector. China's GB 33372-2020 enforcement is compressing contract tenors as buyers demand shorter renegotiation windows to capture water-based technology cost curves.
Pricing Analysis
Contract-based long-term offtake structures dominate volume procurement between Southeast Asian converters and Japanese polyurethane suppliers, though spot purchasing is expanding for acrylic emulsions. Price differentiation hinges on BIS food-contact certification grade and volume scale, with retort-grade systems commanding substantial premia over furniture lamination grades. Pricing pressure stems from thermal bonding substitution in low-performance packaging tiers. Commodity furniture laminators exhibit highest price sensitivity, while pharmaceutical blister manufacturers prioritize compliance over cost.
Supply Chain Analysis
Strait of Malacca transit underwrites isocyanate feedstock flows from Northeast Asian petrochemical hubs to Mumbai-Pune packaging clusters, creating logistics vulnerability for Indian formulators. Supply concentrates in China, Japan, and South Korea for MDI and TDI precursors, with acrylic monomer production anchored in Zhejiang province and Ulsan. Raw material dependencies include crude-linked aromatic isocyanates, water-based acrylic emulsions, and epoxy resin hardeners. Single-source vulnerability runs through concentrated MDI reactor capacity. Distribution runs through technical service-direct models for certified grades and distributor channels for standard furniture adhesives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across China, India, and Japan is fragmenting the Asia-Pacific laminated adhesives market into certification-defined niches, creating entry points for specialized formulators alongside integrated incumbents.
For Market Incumbents: Consolidate formulation expertise in reactive hot-melt chemistry through targeted hiring from Seoul Capital Area technical centers, defending against emerging Chinese water-based specialists capturing share under MEE enforcement. Backward integration into acrylic emulsion production in Zhejiang province secures margin control as GB standards tighten. Channel control through direct technical collaboration with Ho Chi Minh City converter gatekeepers preserves specification authority.
For New Entrants and Emerging Players: Lead with BIS-certified domestic production targeting Maharashtra's Mumbai-Pune pharmaceutical blister corridor, where import timelines compress competitive response. The underpenetrated Indian western corridor offers the most penetrable geography for retort-grade polyurethane systems. A certification-first go-to-market angle, front-loading 12-18 month migration testing cycles, builds defensible positioning before volume scaling.
For Investors and Strategic Acquirers: Capital is best deployed toward water-based technology assets in China and India with established GB or BIS compliance documentation, offering 5-10 year viability as environmental enforcement hardens across the region. Acquisition target archetype: mid-cap formulators with captive certification pipelines and regional polymer science infrastructure. The signal to watch is MEE enforcement intensity in Zhejiang province, indicating acceleration of solvent-based capacity retirement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Emulsion Production | Zhejiang province concentration secures supply continuity under tightening GB 33372-2020 VOC limits. |
| Long-term Supply Agreement with MDI Producers | Ulsan and Yokkaichi petrochemical hubs anchor isocyanate cost predictability for automotive interior laminators. |
| Joint Venture with Japanese Electronics Packagers | Kanto region partnerships accelerate water-based acrylic adoption for China market access preservation. |
| Capacity Expansion in Maharashtra Chemical Belt | Gujarat blending assets reduce lead times to Mumbai-Pune pharmaceutical blister manufacturers. |
| Green Manufacturing Transition to Solvent-Free Systems | Binh Duong province reactive adhesive lines eliminate solvent recovery infrastructure for Vietnamese retort pouch exporters. |
Study Parameters
Cross-validation between primary interviews with flexible packaging procurement managers, adhesive formulation chemists, and automotive Tier 1 laminating engineers and secondary sources including customs/trade data, SEC 10-K filings from disclosed chemical conglomerates, and MEE enforcement bulletins anchors the qualitative findings. Bottom-up triangulation against top-down market sizing from regional production capacity assessments validates segment-level estimates across the analysis window.
Sensitivity analysis on isocyanate feedstock cost curves and GB compliance timeline assumptions shapes the forecast framework. Segmentation dimensions modeled include chemistry platform, bonding technology, end-use industry, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific inputs incorporate MEE enforcement intensity indices and BIS certification pipeline velocities.
The analysis sits within stated boundaries; outcomes outside sustained MEE enforcement or accelerated BIS migration testing standardization would require recalibration. Forecasts reflect documented assumptions on regulatory trajectory and feedstock cost normalization. Practitioners should keep alternative scenarios live as India's western corridor domestic capacity buildout and Japan METI procurement guideline revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Epoxy Active Diluent Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
France Sealants Market
Adhesives & Sealants
China Sealants Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
Waterproof Tapes Market
Adhesives & Sealants
Middle-East and Africa Contact Adhesives Market
Adhesives & Sealants
Contact Cement Market
Adhesives & Sealants
Global Construction Adhesives Market
Adhesives & Sealants
High Strength Laminated Adhesives Market
Adhesives & Sealants
Singapore Adhesives Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
France Adhesives Market
Adhesives & Sealants
Anaerobic Adhesives Market