
 High Fiber Feed Market | 2026-2036
High Fiber Feed Market Size, Share, and Industry Trends Forecast 2026-2036
High Fiber Feed Market Analytics
Dairy cattle nutrition is hardening as the dominant demand vertical for high fiber feed, displacing traditional equine and small ruminant applications in volume terms. Cargill, Incorporated leverages its North American grain handling infrastructure to anchor bulk silage distribution networks. ADM competes through oilseed processing co-products that extend fiber availability into commercial dairy formulations. Wilmar International Limited dominates Southeast Asian palm kernel expeller supply chains that feed regional cattle operations.
High fiber feed comprises forage-based rations and processed roughage products containing minimum crude fiber thresholds, typically manufactured through chopping, ensiling, pelleting, or dehydration to preserve digestible neutral detergent fiber for ruminant fermentation. Alfalfa and silage product types occupy mature margin pools in developed dairy regions where mechanized harvest systems sustain cost efficiency. Pellets represent the fastest-growing product type as transport logistics and storage constraints force commercial farms toward densified formats. Dairy cattle as an animal type leads volume absorption, while organic farming as an end use segment concentrates premium pricing power where certification requirements restrict conventional input substitution.
The USDA oversees feed safety through the Federal Food, Drug, and Cosmetic Act, while the EPA regulates manure management from fiber-fed concentrated animal feeding operations; the EU Green Deal and F-Gas Regulation shape European sourcing standards that restrict deforestation-linked imports. Stakeholders must monitor evolving carbon accounting rules for feed origin verification as border-adjusted sustainability tariffs penetrate agricultural trade channels.
Market Dynamics
Mechanized harvest-to-pellet systems are compressing supply chains as dairy operations consolidate feed procurement around densified formats that reduce transport costs per unit of digestible fiber.
Growth Catalysts
- EU Green Deal sourcing mandates:Deforestation-free import requirements are redirecting procurement toward certified European silage suppliers who can verify supply chain traceability.
- Brazilian dairy export expansion:Southeast Asian demand for milk solids is accelerating alfalfa imports through Santos port infrastructure upgrades.
- Pellet dehydration technology:Continuous-flow dryers are extending storage windows for commercial operations facing seasonal forage gaps.
Market Restraints
- Alfalfa acreage volatility:California Central Valley water allocation cuts are contracting reliable hay supply for West Coast dairy processors.
- Single-origin palm kernel dependence:Malaysian export licensing fluctuations concentrate risk for Southeast Asian cattle compounders.
- F-Gas refrigeration compliance:Cold-chain energy costs for silage preservation are rising under European fluorinated gas phase-down schedules.
Strategic Opportunities
- Organic certification premiums:USDA National Organic Program compliance is opening price-tier separation for pasture-based dairy systems.
- Co-product fiber recovery:Oilseed crush residues from biodiesel expansion are creating alternative roughage streams for formulation blending.
- Precision fermentation monitoring:In-silo sensor networks are enabling real-time neutral detergent fiber optimization for large-scale operations.
Industry Challenges
- Ensiling microbiology expertise:Commercial farms lack personnel trained in anaerobic fermentation management, causing spoilage losses in bunker silos.
- Carbon accounting verification:Scope 3 emissions documentation for feed origin is overwhelming procurement departments without standardized protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Fiber Feed Market |
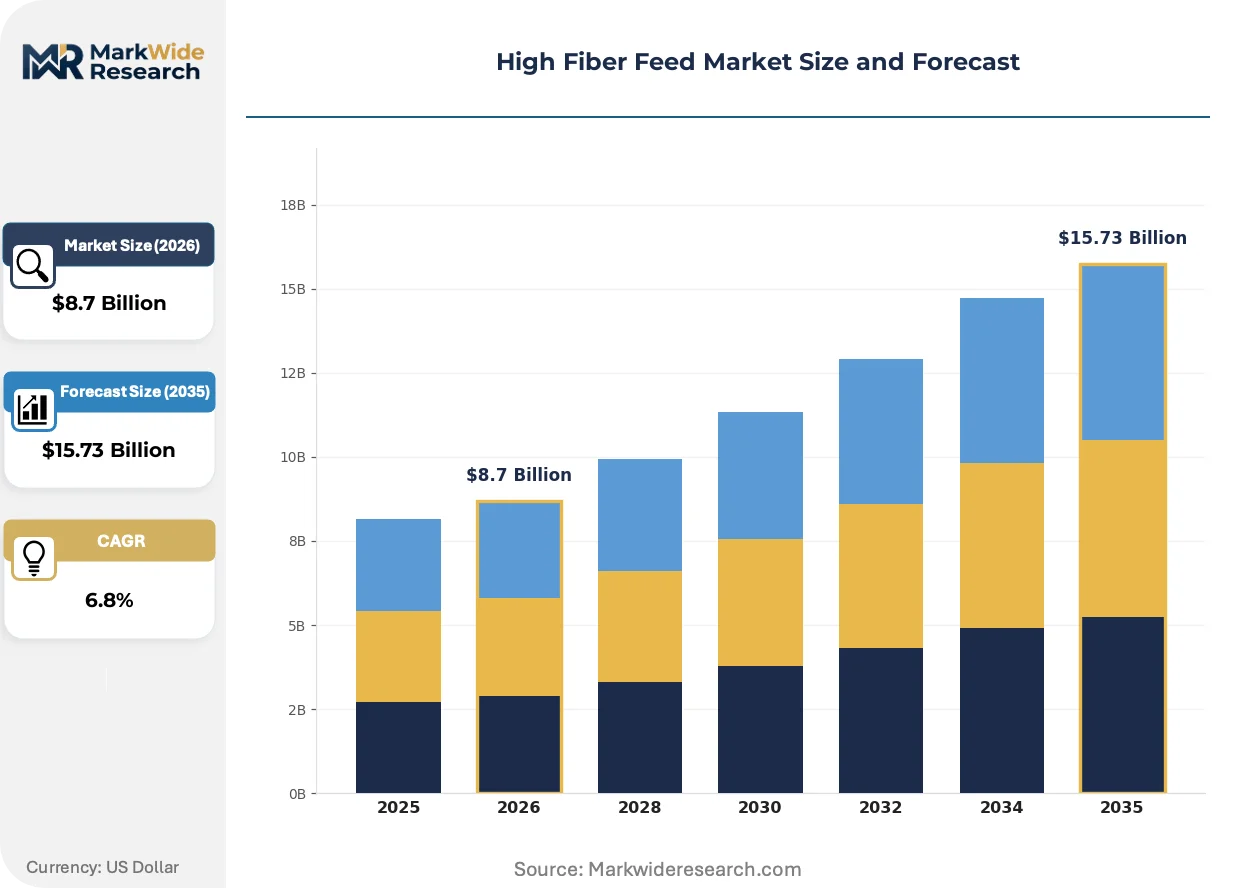
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grass, Alfalfa, Silage, Pellets Animal Type: Dairy Cattle, Sheep, Goats, Horses Distribution Channel: Online Retail, Specialty Stores, Agricultural Suppliers, Bulk Sales End Use: Commercial Farming, Livestock Breeding, Organic Farming, Research Institutions |
| Companies Covered | Wilmar International Limited, Charoen Pokphand Foods PCL, Cargill, Incorporated, MBRF, ForFarmers Group, ADM, Nutreco N.V., Alltech Inc., Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Fiber Feed Market Evolving Landscape
Digital feed formulation platforms are rewiring how nutritionists balance fiber fractions against energy density, compressing the cycle from forage testing to ration deployment.
Near-infrared spectroscopy is electrifying on-fiber quality assessment. Dairy nutritionists at large cooperatives are deploying handheld NIR units for instant neutral detergent fiber readings. Real-time data streams are compressing the gap between harvest timing and ration adjustment decisions.
The EU F-Gas Regulation is mandating refrigeration retrofits across European silage storage facilities. Cold-chain energy intensity is rising as hydrofluorocarbon systems phase out. Dutch dairy hubs are responding with ammonia-based cooling installations to preserve fermentation stability.
Consolidated procurement desks at multi-site operations are displacing decentralized feed buying. Volume aggregation through cooperative purchasing platforms is compressing price negotiation cycles. This pattern is most visible across Upper Midwest dairy clusters where three-farm mergers dominate supplier relationships.
High Fiber Feed Market Segmentation
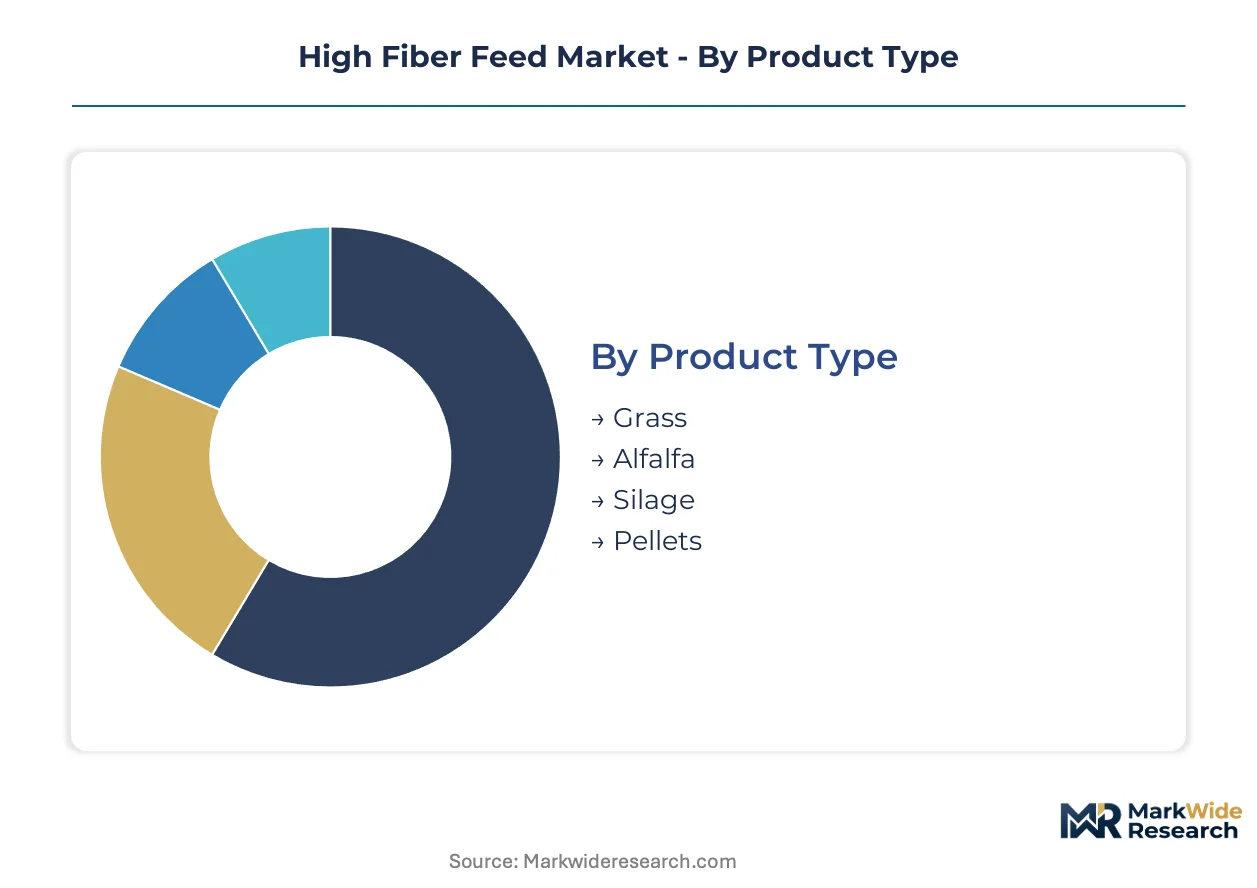
Segmentation in high fiber feed markets separates procurement behaviors across animal physiology, distribution economics, and certification requirements. Dairy operations demand precision-formulated fiber fractions that small ruminant and equine keepers rarely specify. Commercial farms and organic certifiers operate under divergent regulatory frameworks that reshape supplier qualification criteria.
Product Type:
USDA National Organic Program and EU organic certification impose distinct fiber-source traceability burdens on each product category, with dehydrated formats facing stricter moisture-content documentation than ensiled alternatives.
- Grass:Temperate pasture grasses deliver variable neutral detergent fiber depending on harvest maturity. Demand concentrates in New Zealand and Ireland where rotational grazing systems prioritize fresh fiber intake over purchased concentrates. Water allocation volatility in drought-prone regions constrains reliable supply.
- Alfalfa:Lucerne hay carries protein premiums that justify irrigation investment in arid dairy corridors. California Central Valley processors and Saudi Arabian alfalfa projects anchor global trade flows. Salinity tolerance breeding programs are expanding cultivation into marginal soils.
- Silage:Anaerobically fermented whole-crop cereals and legumes preserve digestible fiber across seasonal gaps. Bunker storage dominates on-farm systems while bagged silage serves smaller operations lacking infrastructure.
- Pellets:Densified formats reduce transport costs per unit fiber and extend storage stability. Commercial feed mills in the Netherlands and Wisconsin are expanding pelleting capacity to serve consolidating dairy cooperatives.
Alfalfa sits at the top of the volume ranking, with pellets climbing the fastest.
Animal Type:
Species-specific digestive physiology dictates fiber particle size, lignin tolerance, and fermentation rate requirements that suppliers must match through formulation precision.
- Dairy Cattle:Rumen function depends on adequate physically effective fiber to maintain butterfat production and prevent acidosis. Large Holstein operations in Wisconsin and the Netherlands specify minimum 30% NDF rations that anchor commodity demand.
- Sheep:Smaller rumen capacity requires finer particle processing than cattle formulations. Australian Merino breeding programs and British hill farming systems sustain regional hay merchant networks.
- Goats:Browsing behavior tolerates higher lignin content than grazing species. Mediterranean dairy goat cooperatives in Spain and Greece source brush and browse supplements alongside traditional hay.
- Horses:Hindgut fermentation demands low-sugar, high-fiber forage to prevent metabolic disorders. Equine competition stables and recreational riding centers in Kentucky and Virginia drive quality premiums for certified low-carbohydrate hay.
Dairy cattle dominate tonnage absorption, while horses command the steepest price premiums per unit fiber.
Distribution Channel:
Channel selection reflects farm scale, storage capacity, and the technical support intensity required for fiber management.
- Online Retail:E-commerce platforms serve hobby farmers and smallholders lacking established supplier relationships. Amazon and specialized agricultural marketplaces now carry packaged hay and supplement products with delivery logistics constraints.
- Specialty Stores:Equine-focused retailers stock premium hay brands and nutritional supplements with guaranteed analysis certificates. Kentucky and Virginia host dense networks serving thoroughbred breeding operations.
- Agricultural Suppliers:Cooperative-owned supply stores dominate rural dairy regions with credit terms and seasonal delivery scheduling. Upper Midwest networks in Wisconsin and Minnesota aggregate procurement for member farms.
- Bulk Sales:Direct mill-to-farm contracts eliminate intermediary margins for large operations with on-site storage. California Central Valley dairies and Dutch Friesland cooperatives negotiate annual tonnage commitments.
Bulk sales capture the largest volume share, with online retail expanding most quickly among non-commercial keepers.
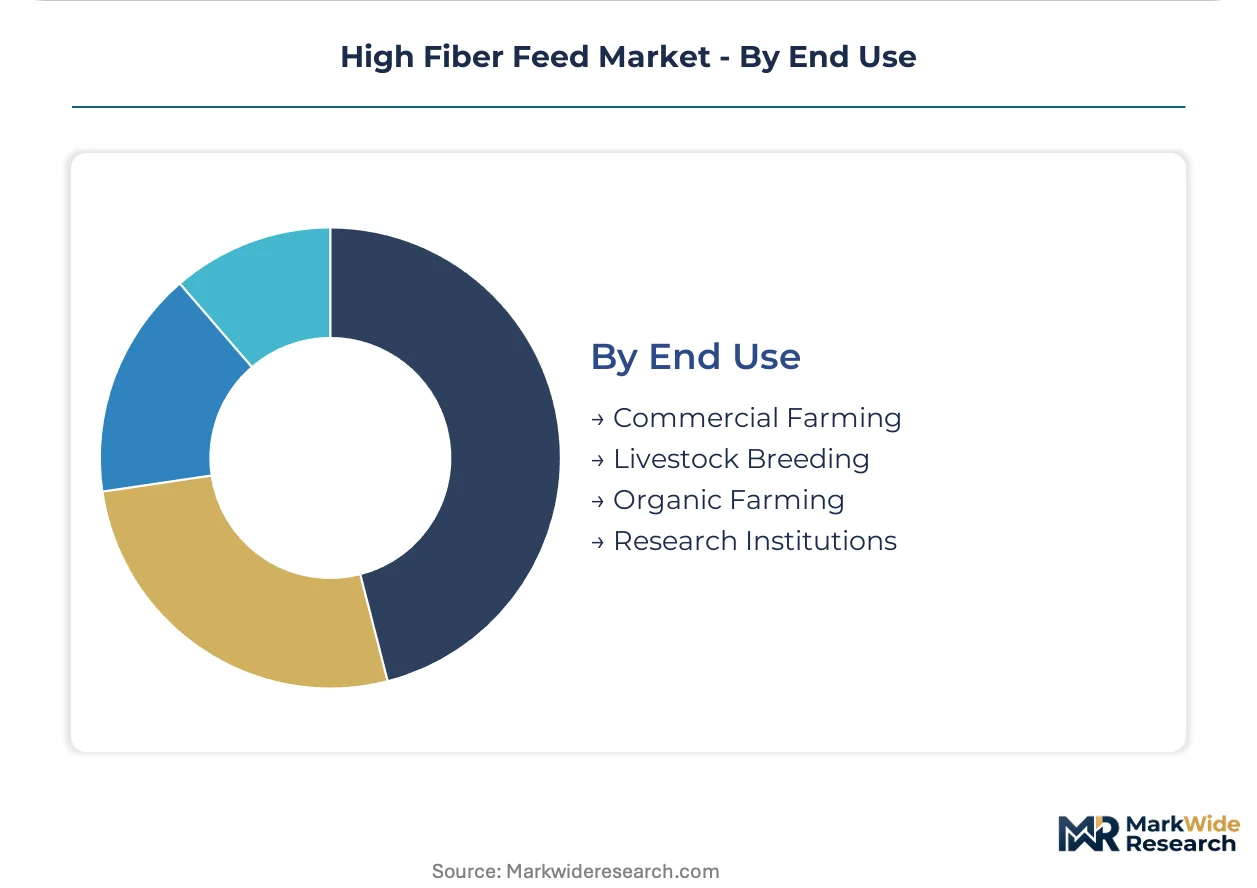
End Use:
End-use certification requirements range from voluntary quality standards to mandatory organic compliance that restricts input sourcing.
- Commercial Farming:Conventional operations prioritize cost-per-unit-energy metrics over certification premiums. Large Wisconsin and California dairies optimize rations through nutritionist-formulated blends.
- Livestock Breeding:Genetic improvement programs demand consistent nutritional inputs to isolate heritable traits. Semen export-oriented facilities in Brazil and Germany maintain strict feed documentation protocols.
- Organic Farming:USDA National Organic Program and EU organic regulations prohibit synthetic inputs and mandate pasture access. Premium price realization depends on certification maintenance through audited supply chains.
- Research Institutions:Universities and government stations require standardized, analyzed feed for controlled trials. Cornell and Wageningen maintain dedicated forage analysis laboratories supporting experimental protocols.
Commercial farming absorbs the greatest tonnage, with organic farming gaining share fastest on premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting high fiber feed production toward jurisdictions with lower compliance burdens for carbon verification and deforestation-free certification. Producers in Brazil and the United States capture margin advantages against European competitors facing stricter EU Green Deal traceability mandates. This cost-of-compliance gap accelerates investment in mechanized harvest infrastructure across the Americas.
United States
Wisconsin and California dairy cooperatives anchor North American demand for precision-formulated fiber rations. The USDA enforces Federal Food, Drug, and Cosmetic Act standards for feed safety documentation. California Central Valley processors negotiate annual tonnage commitments despite chronic water allocation volatility constraining reliable alfalfa supply.
Brazil
Southeast Asian demand for milk solids accelerates alfalfa imports through Santos port infrastructure upgrades. ANVISA oversees veterinary drug residue limits in exported dairy products. São Paulo state feed compounders expand pellet dehydration capacity to serve consolidating commercial farm operations.
Netherlands
Friesland dairy hubs respond to F-Gas Regulation mandates with ammonia-based cooling installations for silage preservation. The EU Green Deal deforestation-free import requirements redirect procurement toward certified European suppliers. Wageningen maintains dedicated forage analysis laboratories supporting experimental protocols for precision fermentation monitoring.
China
Domestic dairy herd expansion drives demand for imported alfalfa and domestic silage processing. SAMR enforces feed safety standards under national food security frameworks. Shandong Peninsula feed mills densify roughage into pellet formats to reduce transport costs for Inner Mongolian cattle operations.
Australia
Temperate pasture grass systems in Victoria and New South Wales prioritize fresh fiber intake over purchased concentrates. The country's national agricultural regulator maintains export certification protocols for dairy genetics programs. Merino breeding operations in regional New South Wales sustain specialized hay merchant networks serving smaller ruminant keepers.
High Fiber Feed Market Competitive Landscape
Capacity expansion dominates the current landscape as commercial feed mills invest in continuous-flow dryers and pelleting infrastructure. The vendor base clusters around three strategic archetypes: integrated agribusiness conglomerates with oilseed crush co-product streams, regional cooperative networks with member-procurement aggregation platforms, and specialized forage processors with certified organic supply chains. Competitive positioning hinges on backward integration into grain handling infrastructure and geographic proximity to consolidating dairy cooperatives.
Among Asia-Pacific-based agribusiness groups, Wilmar International Limited anchors Southeast Asian palm kernel expeller supply chains. Cargill, Incorporated and ADM represent North American integrated conglomerates leveraging grain handling infrastructure and oilseed processing co-products respectively. These three exemplify the scale-driven archetype where captive supply of raw fiber inputs compresses procurement costs for commercial dairy formulations.
| Leading Market Players |
|---|
| Wilmar International Limited |
| Charoen Pokphand Foods PCL |
| Cargill, Incorporated |
| MBRF |
| ForFarmers Group |
| ADM |
| Nutreco N.V. |
| Alltech Inc. |
| Bunge Limited |
| Others |
Value Network & Pricing Analysis
EU Green Deal deforestation-free import requirements gate qualified supply for premium-tier pricing access, restricting procurement to certified European silage suppliers and traceable Brazilian alfalfa exporters who can document supply chain integrity. Buyers lacking verification documentation face exclusion from premium organic and export-oriented dairy channels, compressing margin capture to commodity-grade spot markets.
Pricing Analysis
Distributor margins compress as bulk sales channels displace intermediary layers across Upper Midwest dairy clusters and Dutch Friesland cooperatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment scale, with USDA National Organic Program compliance commanding substantial premiums over conventional rations. Pricing pressure stems from California Central Valley water allocation volatility contracting reliable hay supply. Smallholder equine keepers exhibit highest price sensitivity, while consolidated commercial dairies prioritize cost-per-unit-energy optimization over per-ton procurement.
Supply Chain Analysis
Certification gating under EU F-Gas Regulation and USDA Federal Food, Drug, and Cosmetic Act redirects procurement toward ammonia-based cooling installations and documented fermentation protocols. Supply concentrates in Brazil, the United States, and the Netherlands as export-oriented dairy hubs expand fiber-intensive ration programs. Raw material dependencies rest on alfalfa cultivation, oilseed crush co-products, and palm kernel expeller streams from Southeast Asian processing. Single-origin palm kernel dependence from Malaysian export licensing fluctuations concentrates risk for regional compounders. Distribution runs through cooperative-owned agricultural suppliers dominating rural dairy regions with credit terms and seasonal delivery scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pellet dehydration technology adoption and precision fermentation monitoring represent margin-expansion vectors as mechanized harvest-to-pellet systems compress supply chain costs and real-time NDF optimization reduces spoilage losses.
For Market Incumbents: Lock in backward integration into grain handling infrastructure and oilseed crush co-product streams to anchor captive fiber supply against ADM and Cargill procurement advantages. Expand pelleting capacity in Wisconsin and Netherlands dairy corridors to serve consolidating cooperatives. Invest in ammonia-based cooling retrofits ahead of F-Gas Regulation phase-down deadlines to preserve fermentation stability premiums. For New Entrants and Emerging Players: Agricultural suppliers lacking digital feed formulation platforms present white-space opportunity for precision nutrition software integration. Target organic certification compliance gaps among pasture-based dairy systems in Upper Midwest clusters where USDA National Organic Program documentation overwhelms existing procurement desks. Pursue cooperative purchasing platform partnerships to aggregate volume and compress price negotiation cycles. For Investors and Strategic Acquirers: Roll-up economics work for regional forage processors with certified organic supply chains because EU Green Deal traceability mandates fragment procurement toward verified suppliers. Five-to-ten-year viability favors backward-integrated specialists with captive alfalfa cultivation and dehydration infrastructure. Monitor Brazilian Santos port infrastructure upgrade completion as inflection indicator for Southeast Asian export demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alfalfa Cultivation | Cargill leverages North American grain handling infrastructure to anchor bulk silage distribution networks against water volatility. |
| Pellet Dehydration Capacity Expansion | Continuous-flow dryers extend storage windows for commercial operations facing seasonal forage gaps in California and Netherlands. |
| Ammonia-Based Cooling Retrofit | Dutch Friesland dairy hubs respond to F-Gas Regulation mandates with fermentation-stable preservation systems. |
| Precision Fermentation Monitoring Deployment | In-silo sensor networks enable real-time NDF optimization for large-scale Wisconsin and California operations. |
| Organic Certification Supply Chain Investment | USDA National Organic Program compliance opens price-tier separation for pasture-based dairy systems in premium channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy nutritionists, cooperative procurement managers, feed mill operations directors, and agricultural supplier network heads with secondary validation from USDA Federal Food, Drug, and Cosmetic Act filings, EPA manure management regulations, EU Green Deal documentation, ANVISA veterinary residue protocols, and customs trade flow records. Bottom-up volume aggregation across product type, animal physiology, and distribution channel segments triangulated against top-down macroeconomic drivers.
Comparable-period anchoring linked projection horizons to historical reference intervals across mechanized harvest system deployment cycles and dairy cooperative consolidation waves. Segmentation modeling spanned product format, ruminant digestive physiology, procurement channel economics, and certification requirement intensity. CAGRs derived from fitted growth curves incorporating alfalfa acreage volatility, F-Gas refrigeration compliance cost trajectories, and pellet dehydration technology adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to California water allocation policy shifts, Malaysian palm kernel export licensing fluctuations, and EU carbon accounting protocol standardization. Forecasts reflect documented assumptions on dairy herd expansion rates and mechanization investment cycles. A model refresh is warranted upon material change in EU Green Deal enforcement timelines or Brazilian port infrastructure completion schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Angola Agriculture Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Bamboos Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
Organic Hemp Market
Agriculture and Agri Products
Cage Free Eggs Market
Agriculture and Agri Products
Elaeis Guineensis (Palm) Fruit Extract Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
South America Cashew Market
Agriculture and Agri Products
Coir Market