
 Saudi Arabia Alfalfa Market | 2026-2036
Saudi Arabia Alfalfa Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Alfalfa Market Analytics
Agricultural labor shortages among skilled irrigation technicians is unwinding expansion timelines for domestic alfalfa growers. Almarai Company leverages its captive dairy herd network to anchor demand for high-grade pelleted feed across its vertically coordinated supply chain. NADEC sustains its position through government-backed land concessions in the Al-Jawf region. Al Dahra ACX, Inc. competes by importing premium dehydrated product from its overseas farming operations to supplement local harvest gaps.
Alfalfa is a perennial legume forage crop typically harvested at pre-bloom stage to maximize crude protein content near 18-22% and digestible fiber for ruminant nutrition, primarily serving as the foundational feedstock for dairy cow total mixed rations. Pelleted alfalfa dominates value capture due to reduced transport spoilage and standardized nutrient density preferred by industrial feed manufacturers. Dehydrated alfalfa commands premium positioning among export-oriented dairy farms seeking extended shelf stability. Fresh alfalfa retains cost-sensitive share in poultry and aquaculture applications where moisture content tolerance runs higher.
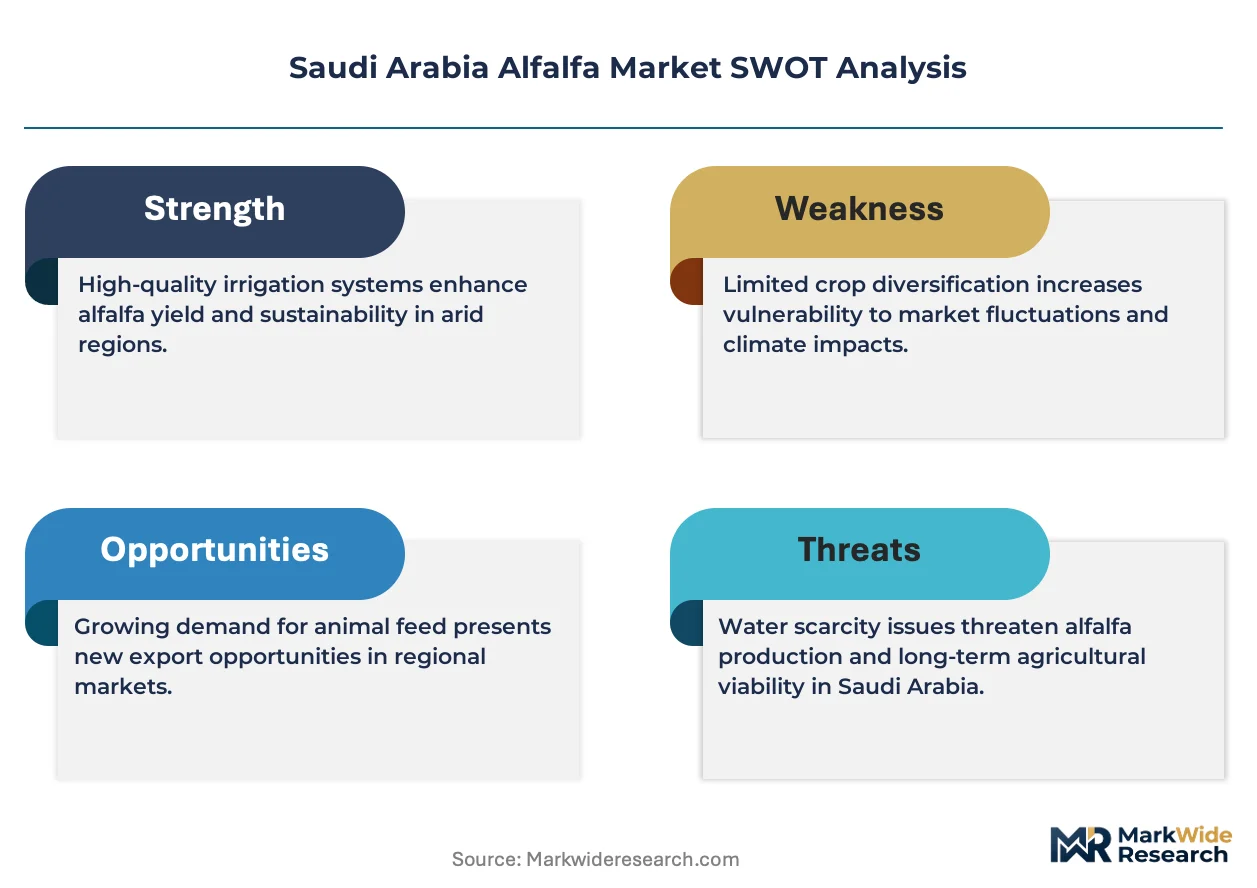
SFDA feed registration requirements and MOEWA water quota allocations shape which producers qualify for commercial licensing and irrigation access. The Saudi Standards, Metrology and Quality Organization sets moisture and contaminant thresholds that imported and domestic product must clear. Stakeholders must track groundwater withdrawal enforcement intensity and alternative forage substitution programs as signals for domestic production viability versus import dependency.
Market Dynamics
Water quota enforcement by MOEWA is compressing domestic alfalfa acreage while dairy herd expansion in the Central Region intensifies demand for imported feedstock, reshaping supply sourcing patterns across the Kingdom.
Growth Catalysts
- Dairy herd expansion:Commercial farms around Riyadh and Qassim are scaling cow populations to meet liquid milk targets, anchoring offtake for high-protein forage.
- SFDA feed registration protocols:Mandatory safety documentation is professionalizing the supplier base and locking out informal traders, consolidating volume with licensed operators.
- Pelletization infrastructure:Investments in densification equipment at Al-Kharj and Buraydah processing hubs are reducing transport costs and spoilage losses for long-haul distribution.
Market Restraints
- Groundwater depletion:MOEWA irrigation allocations for alfalfa have tightened in the Eastern Province and Najd, forcing acreage abandonment or crop switching.
- Import dependency concentration:Dehydrated product flows predominantly from the United States and Spain, exposing buyers to shipping rate volatility and port congestion at Jeddah.
- Technical storage limitations:Domestic silage bunkers lack climate control for extended fresh forage preservation, restricting harvest-to-feed windows.
Strategic Opportunities
- Al-Jawf expansion zone:Government land concessions in the northern region offer untapped groundwater reserves for new irrigated alfalfa development.
- Aquaculture feed formulation:Tilapia and shrimp producers in the Eastern Province are testing alfalfa meal as a partial soybean replacement in grow-out diets.
- Organic certification pathway:SASO standards for pesticide residue thresholds create premium positioning for certified hay exports to Gulf Cooperation Council neighbors.
Industry Challenges
- Irrigation technician scarcity:Precision agriculture specialists capable of managing drip system maintenance and soil moisture monitoring are in short supply across Najd farms.
- SFDA registration timelines:Feed safety dossier reviews currently stretch across multiple quarters, delaying new product commercialization for importers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Alfalfa Market |
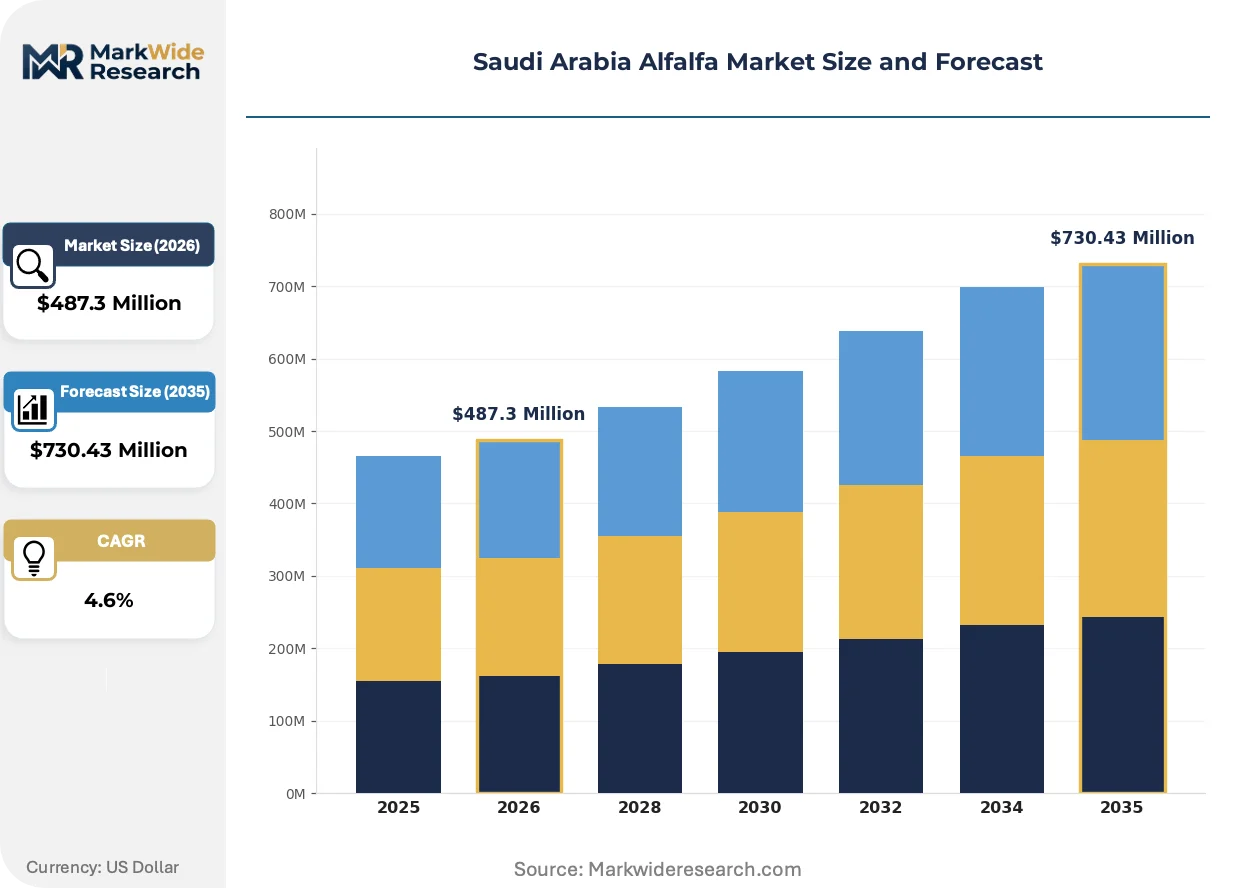
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dehydrated Alfalfa, Pelleted Alfalfa, Chopped Alfalfa, Fresh Alfalfa End User: Animal Feed Manufacturers, Dairy Farms, Poultry Farms, Aquaculture Distribution Channel: Direct Sales, Wholesalers, Retailers, E-commerce Packaging Type: Bags, Bales, Bulk, Containers |
| Companies Covered | Alfeed, Nafosa (Grupo Osés), Al Dahra ACX, Inc., Al-Safi Danone, National Agricultural Development Company (NADEC), Almarai Company, Alfalfa Monegros S.L., Al-Faisaliah Group, Tabuk Agricultural Development Company (TADCO), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Alfalfa Market Evolving Landscape
Digital irrigation management and alternative forage substitution programs are disrupting traditional production economics, while regulatory tightening on water withdrawals accelerates technology adoption timelines.
Variable rate irrigation systems equipped with soil moisture sensors and satellite-derived evapotranspiration data are fragmenting the domestic grower base into technology-adopters and water-constrained laggards. Large-scale operators in Qassim have deployed these platforms to squeeze additional cuts per season from limited quotas. The capability gap is compressing margins for farms unable to justify precision hardware capex.
MOEWA's alternative forage promotion schemes are redirecting subsidy eligibility toward Rhodes grass and sorghum-sudangrass hybrids with lower water coefficients. Dairy compounders must now reformulate rations around reduced alfalfa inclusion rates without compromising milk solids output. Feed mills in Riyadh are responding with expanded analytical laboratories to validate nutritional equivalence of substitute roughages.
Consolidated procurement by vertically integrated dairy processors is displacing spot-market hay purchases across the Central Region. Almarai and NADEC now contract directly with overseas dehydration facilities for multi-year supply commitments. Smaller independent farms in Asir and Baha provinces face squeezed access to premium imported product as allocation priority shifts to volume buyers.
Saudi Arabia Alfalfa Market Segmentation
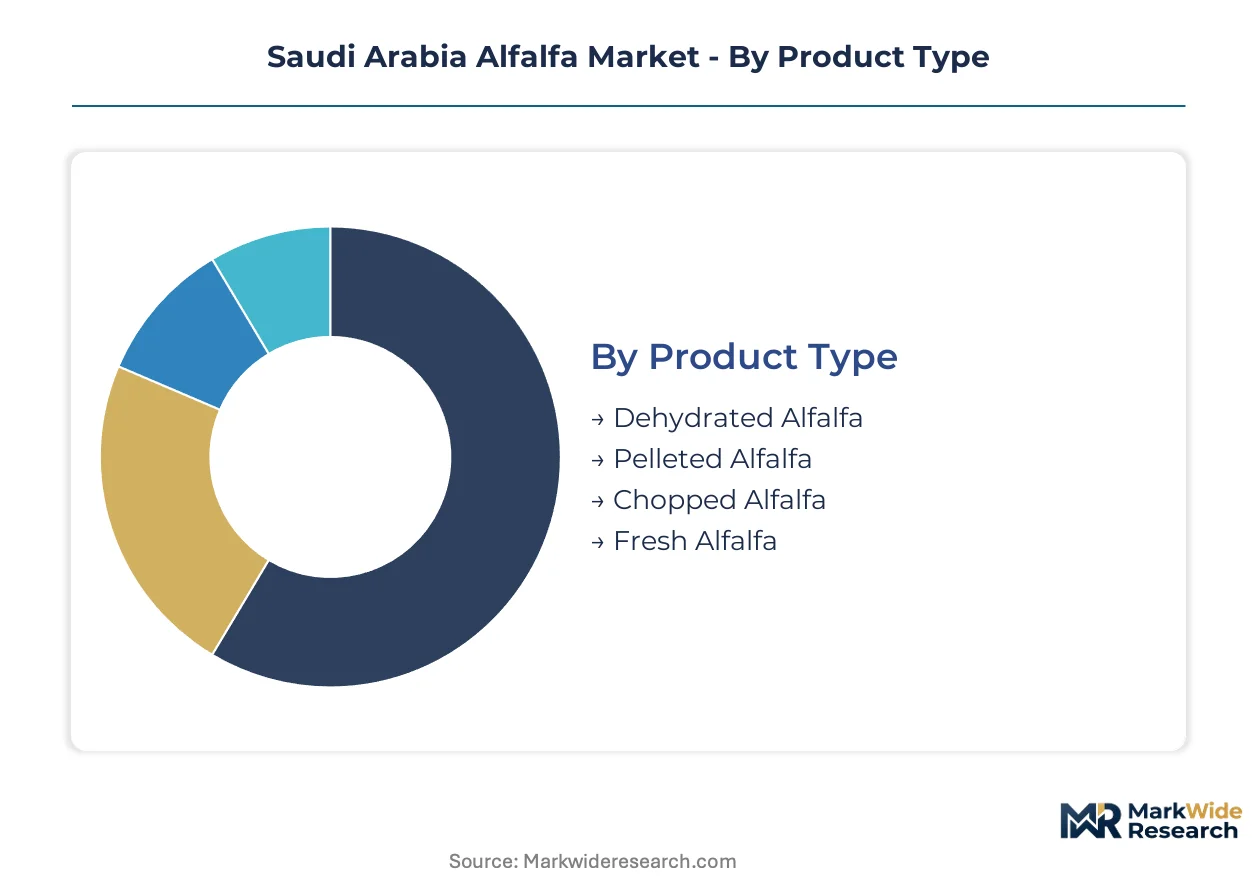
Segmentation in the Saudi alfalfa market reveals how water constraints and dairy herd expansion are reallocating value across processing formats and delivery channels. Distinct buyer requirements across ruminant nutrition, poultry operations, and aquaculture create specialized demand pockets with diverging price elasticities and sourcing patterns.
Product Type:
Pelleted and dehydrated formats capture the deepest margin pools due to transport efficiency advantages and premium positioning among industrial compounders.
- Pelleted Alfalfa:Densified feed produced through mechanical compression reduces bulk volume by 60-70% versus loose hay, enabling cost-effective long-haul distribution from processing hubs at Al-Kharj and Buraydah to dairy clusters around Riyadh. SFDA registration requirements favor licensed pellet manufacturers with standardized nutrient documentation, consolidating procurement with Almarai and NADEC compounders.
- Dehydrated Alfalfa:Thermally dried product achieving sub-12% moisture content delivers extended shelf stability for export-oriented dairy farms and strategic reserve stocking. Import flows from the United States and Spain dominate supply, exposing buyers to Red Sea shipping rate volatility and Jeddah port congestion.
- Chopped Alfalfa:Field-cut forage with minimal processing serves cost-sensitive beef operations and smallholder dairy units in Asir and Baha provinces.
- Fresh Alfalfa:High-moisture harvest retains poultry and aquaculture share where climate-controlled storage infrastructure remains limited across Najd farms.
Pelleted alfalfa holds installed capacity. Dehydrated alfalfa is rotating up the share rankings.
End User:
Volume concentration tracks dairy herd expansion in the Central Region, while aquaculture emerges as the most price-elastic demand segment testing alternative protein sources.
- Dairy Farms:Commercial operations around Riyadh and Qassim scale cow populations to meet liquid milk targets, anchoring offtake for 18-22% crude protein forage as foundational total mixed ration ingredient. MOEWA water quota enforcement compresses domestic acreage, intensifying reliance on imported dehydrated and pelleted product.
- Animal Feed Manufacturers:Industrial compounders in Riyadh operate expanded analytical laboratories to validate nutritional equivalence of substitute roughages as MOEWA redirects subsidy eligibility toward Rhodes grass and sorghum-sudangrass hybrids.
- Poultry Farms:Broiler and layer operations tolerate higher moisture content, retaining fresh alfalfa share despite limited climate-controlled silage bunkers.
- Aquaculture:Tilapia and shrimp producers in the Eastern Province test alfalfa meal as partial soybean replacement, expanding most quickly among end-use segments though from a low base.
Dairy farms command procurement priority. Aquaculture is climbing the fastest among emerging demand verticals.
Distribution Channel:
Direct contracting displaces spot-market intermediation as vertically integrated processors secure multi-year supply commitments with overseas dehydration facilities.
- Direct Sales:Volume buyers contract directly with domestic pellet mills and international dehydration facilities, bypassing intermediaries to lock nutrient specifications and delivery schedules.
- Wholesalers:Regional distributors serve independent farms in peripheral provinces with consolidated shipments from Jeddah and Dammam port zones.
- Retailers:Agricultural supply stores in Qassim and Asir cater to smallholder operations with bagged product.
- E-commerce:Digital procurement platforms gain traction among tech-adopting mid-scale operators seeking transparent pricing and documented SFDA compliance.
Direct sales channels hold volume concentration. E-commerce is gaining transaction share fastest among distribution modalities.
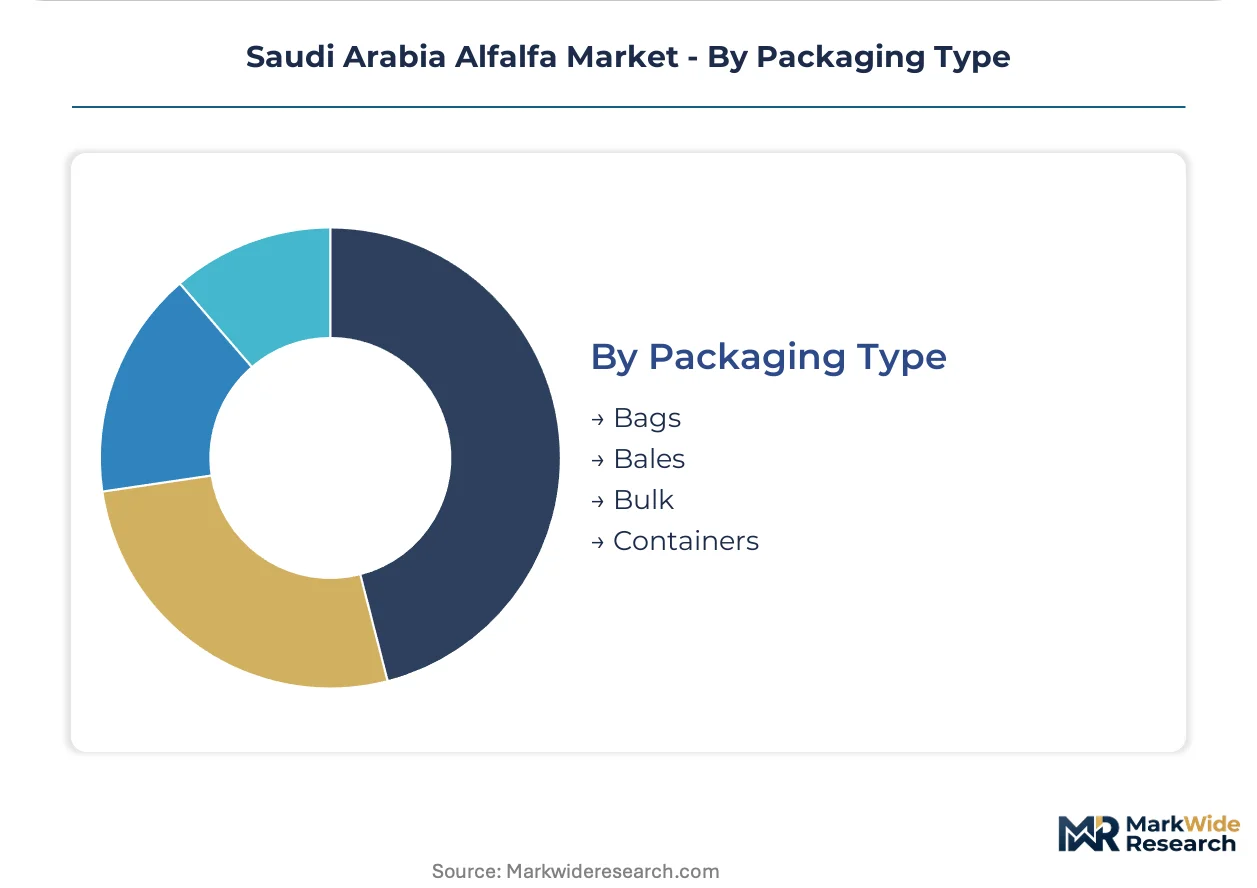
Packaging Type:
Unitization choices reflect transport distance and buyer scale, with bulk formats dominating industrial procurement and bales retaining smallholder accessibility.
- Bulk:Unpackaged loose product flows through pneumatic handling systems at major feed mills, minimizing labor cost for volume compounders.
- Bales:Compressed rectangular or round units enable mechanical handling at intermediate-scale dairy operations lacking pneumatic infrastructure.
- Bags:25-50kg woven polypropylene sacks serve retailers and small poultry farms requiring manageable manual handling.
- Containers:Intermodal shipping units facilitate import logistics from dehydration facilities in the United States and Spain.
Containerized shipping holds import infrastructure capacity. Bulk handling is rotating up the share rankings among domestic distribution formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Saudi Arabia diverge sharply between the Central Region's dairy-intensive feed rations and the Eastern Province's emerging aquaculture trials, with water availability dictating which alfalfa format dominates local procurement.
Riyadh
Commercial dairy clusters around Al-Kharj and Al-Muzahmiyah anchor the Kingdom's highest alfalfa consumption intensity per hectare of irrigated land. SFDA feed registration protocols concentrate procurement with licensed pellet manufacturers operating densification equipment. Almarai and NADEC compounders dominate offtake through multi-year direct contracts with dehydration facilities.
Qassim
Buraydah feed mills process pelleted product for distribution to expanding herds across the agricultural belt. MOEWA water quota enforcement has compressed domestic acreage, intensifying reliance on imported dehydrated shipments arriving through Dammam port. Variable rate irrigation adopters squeeze additional cuts per season from limited allocations.
Eastern Province
Tilapia and shrimp producers in Al-Jubail test alfalfa meal as partial soybean replacement in grow-out diets, creating price-elastic demand distinct from ruminant nutrition standards. Technical storage limitations restrict fresh forage preservation, favoring dehydrated imports with extended shelf stability. Port congestion at Dammam periodically disrupts shipment schedules.
Al-Jawf
Government land concessions offer untapped groundwater reserves for new irrigated development, positioning the northern region as a domestic production expansion zone. NADEC sustains operations through state-backed concessions with preferential irrigation access. Precision agriculture deployment lags behind Central Region adoption curves due to technician scarcity.
Asir and Baha
Smallholder dairy units and poultry operations in southwestern highlands retain cost-sensitive share for fresh and chopped alfalfa formats. Limited climate-controlled silage infrastructure restricts harvest-to-feed windows during peak summer months. Independent farms face squeezed access to premium imported product as allocation priority shifts to volume buyers in Riyadh and Qassim.
Saudi Arabia Alfalfa Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertical coordination separating captive supply networks from merchant market participants. Dairy processors with in-house feed compounding capabilities lock in multi-year dehydration contracts, while independent growers compete for residual spot-market volume. Three archetypes dominate: integrated dairy-feed conglomerates, government-concession landholders, and import-dependent trading specialists. Competitive intensity centers on procurement priority allocation and SFDA registration compliance rather than price undercutting.
Among integrated dairy processors, Almarai Company and Al-Safi Danone exemplify the captive demand archetype through vertically coordinated supply chains. National Agricultural Development Company (NADEC) occupies a distinctive position as a government-concession landholder with preferential water access in Al-Jawf. Import specialists such as Al Dahra ACX, Inc. represent the trading tier, sourcing dehydrated product from overseas farming operations to bridge domestic harvest gaps.
| Leading Market Players |
|---|
| Alfeed |
| Nafosa (Grupo Osés) |
| Al Dahra ACX, Inc. |
| Al-Safi Danone |
| National Agricultural Development Company (NADEC) |
| Almarai Company |
| Alfalfa Monegros S.L. |
| Al-Faisaliah Group |
| Tabuk Agricultural Development Company (TADCO) |
| Others |
Value Network & Pricing Analysis
Ninety-day dehydrated alfalfa inventories at Jeddah port anchor procurement flexibility for Saudi compounders, concentrating pricing power with volume buyers who lock multi-year offtake agreements while spot-dependent independents absorb Red Sea shipping volatility.
Pricing Analysis
Long-term offtake contracts dominate Saudi alfalfa procurement, with Almarai and NADEC securing multi-year dehydration commitments that insulate against spot-market swings. Pricing stratifies across certified-SFDA, standard-grade, and unregistered tiers, with registration status and volume scale as the primary differentiation drivers. Cost compression in the standard tier intensifies because MOEWA water quotas force domestic acreage abandonment. Independent farms in Asir and Baha provinces exhibit highest price sensitivity, while integrated dairy processors with captive supply networks show lowest elasticity.
Supply Chain Analysis
Domestic silage bunkers lack climate control, compressing harvest-to-feed windows and forcing reliance on thermally dried imports with extended stability. Supply draws from the United States, Spain, and domestic Al-Jawf concessions, with dehydration capacity concentrated overseas. Raw material dependencies include groundwater access, diesel-powered irrigation equipment, and phosphate-based fertilizers. Single-source vulnerability runs through Red Sea shipping lanes exposed to port congestion at Jeddah. Distribution feeds from direct contracts with overseas dehydration facilities to Riyadh and Qassim feed mills, bypassing traditional wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi alfalfa market rewards operators who control scarce precision irrigation talent and secure preferential water allocations, with capability gaps in drip system maintenance and soil moisture analytics fragmenting competitive outcomes.
For Market Incumbents: Shield margin pools by deepening backward integration into Al-Jawf groundwater concessions before MOEWA reallocates remaining quotas to alternative forage programs. Accelerate SFDA registration coverage across all product SKUs to lock out informal traders. Prioritize technician retention through equity participation in precision agriculture platforms, defending against poaching by NADEC's state-backed operations. For New Entrants and Emerging Players: Anchor in aquaculture feed formulation, where tilapia and shrimp producers in the Eastern Province test alfalfa meal as a soybean replacement with minimal incumbent saturation. Target independent poultry farms in Asir and Baha provinces with fresh alfalfa logistics solutions that bypass climate-controlled storage requirements. Pursue e-commerce procurement platforms with transparent SFDA compliance documentation to capture tech-adopting mid-scale operators. For Investors and Strategic Acquirers: Long-term, this sits as a water-rights arbitrage play because MOEWA quota enforcement irreversibly compresses domestic production while dairy herd expansion sustains import demand growth. Acquisition candidates include government-concession landholders with untapped Al-Jawf reserves and import specialists with established dehydration facility relationships. Monitor groundwater withdrawal enforcement intensity as the critical inflection signal for domestic versus import dependency shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Irrigation Technology Deployment | Variable rate systems with satellite-derived evapotranspiration data squeeze additional cuts from MOEWA-limited quotas. |
| SFDA Registration Acceleration | Feed safety dossier completion locks out informal traders and consolidates volume with licensed operators. |
| Alternative Forage Substitution R&D | Analytical laboratories validate nutritional equivalence of Rhodes grass and sorghum-sudangrass hybrids for ration reformulation. |
| Direct Contracting with Overseas Dehydration Facilities | Multi-year supply commitments bypass Jeddah port congestion and secure nutrient specification consistency. |
| Aquaculture Feed Formulation Partnerships | Alfalfa meal trials with Eastern Province tilapia producers open price-elastic demand verticals beyond ruminant nutrition. |
Research Methodology
Desk research of customs trade records, MOEWA water allocation disclosures, and SFDA feed registration databases preceded structured interviews with dairy farm operations managers, feed mill procurement directors, precision agriculture technicians, and dehydration facility export coordinators. Primary fieldwork across Riyadh, Qassim, and Al-Jawf production zones validated secondary data on irrigation quota enforcement and pelletization capacity utilization. Bottom-up acreage and herd-size estimates triangulated against top-down import volume flows through Jeddah and Dammam ports.
Variance decomposition across product format, end-use segment, and regional demand clusters informed the analytical framework throughout the projection horizon. Modeled dimensions include processing format, ruminant versus non-ruminant application, and distribution channel structure. CAGRs derived from historical import trajectories, dairy herd expansion curves, and water constraint elasticity assumptions. Industry-specific inputs incorporated MOEWA alternative forage subsidy redirection timelines and SFDA registration backlog clearance rates.
Decision-makers should treat outputs as directional under assumptions of continued MOEWA quota tightening and stable Red Sea shipping access; material deviation in groundwater policy enforcement or port logistics disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Sudan Alfalfa Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
Africa Poultry Feed Market
Agriculture and Agri Products
Australia Animal Protein Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
Australia Compound Feed Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Singapore Floriculture Market
Agriculture and Agri Products
Oman Agriculture Market
Agriculture and Agri Products
Potting Soil Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Corn Gluten Feed Concentrates Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Algeria Agriculture Market