
 Cut Flower Market | 2026-2036
Cut Flower Market Size, Share, and Industry Trends Forecast 2026-2036
Cut Flower Market Analysis
Direct-to-consumer subscription revenue is reconfiguring margin pools away from wholesale auction channels. Flamingo leverages its East African farm network to sustain year-round rose supply. Dümmen Orange anchors global breeding programs through proprietary cultivar development. Farmgirl Flowers differentiates via domestic sourcing and transparent farm partnerships.
Cut flowers comprise harvested ornamental blooms sold fresh for decorative, ceremonial, and gift purposes, requiring temperature-controlled logistics to maintain vase life of seven to fourteen days. Roses dominate product-type value pools due to universal occasion-based demand and premium pricing. Online retailers represent the fastest-expanding end-user channel as digital subscription models capture recurring household spend. Event delivery mode commands elevated margins through bespoke arrangement services and time-sensitive fulfillment requirements.
The USDA enforces phytosanitary import protocols that determine market access for Latin American and African origin farms. REACH and EU F-Gas Regulation govern chemical inputs and refrigerated transport emissions across European supply chains. Stakeholders must monitor evolving cold-chain compliance costs and digital platform commission structures as determinants of net farmgate returns.
Market Dynamics
Cold-chain compliance costs and direct-to-consumer platform economics are restructuring margin distribution between farmgate producers and retail intermediaries, compressing wholesale auction viability while elevating vertically integrated farm networks.
Growth Catalysts
- EU F-Gas Regulation:Mandated refrigerant phase-downs accelerate investment in next-generation controlled-atmosphere transport, creating technology upgrade cycles across European import corridors.
- Subscription commerce:Recurring household bouquet purchases via digital platforms generate predictable demand patterns that stabilize farm production scheduling and reduce post-harvest loss.
- Kenya-Ethiopia corridor:Concentrated rose and summer flower cultivation leverages equatorial growing conditions to supply year-round Northern Hemisphere demand with minimal supplemental lighting.
Market Restraints
- Phytosanitary protocol fragmentation:USDA import requirements for Latin American and African origins impose inspection bottlenecks at Miami and Los Angeles entry points, extending transit times.
- Input cost volatility:Fertilizer and fuel price swings directly compress net returns for open-field growers dependent on diesel-powered irrigation and freight.
- Substitute competition:Dried and preserved floral arrangements capture gift-segment spend with extended shelf life and lower logistics intensity.
Strategic Opportunities
- Domestic sourcing revival:California and Florida greenhouse operations capture premium local-origin positioning through transparent farm partnerships and reduced transport miles.
- Event delivery specialization:Bespoke arrangement services for weddings and corporate functions command elevated margins through time-sensitive fulfillment and design consultation.
- Blockchain provenance tracking:Farm-to-vase transparency systems align with emerging retailer ESG requirements and consumer traceability preferences.
Industry Challenges
- Post-harvest physiology expertise:Specialized cold-chain management talent remains concentrated among Dutch auction veterans and Colombian export operations, constraining quality consistency at newer origin farms.
- Legacy auction system integration:Digital platform order flows require API connectivity with Aalsmeer and Naaldwijk trading systems, creating technical friction for direct-ship challengers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cut Flower Market |
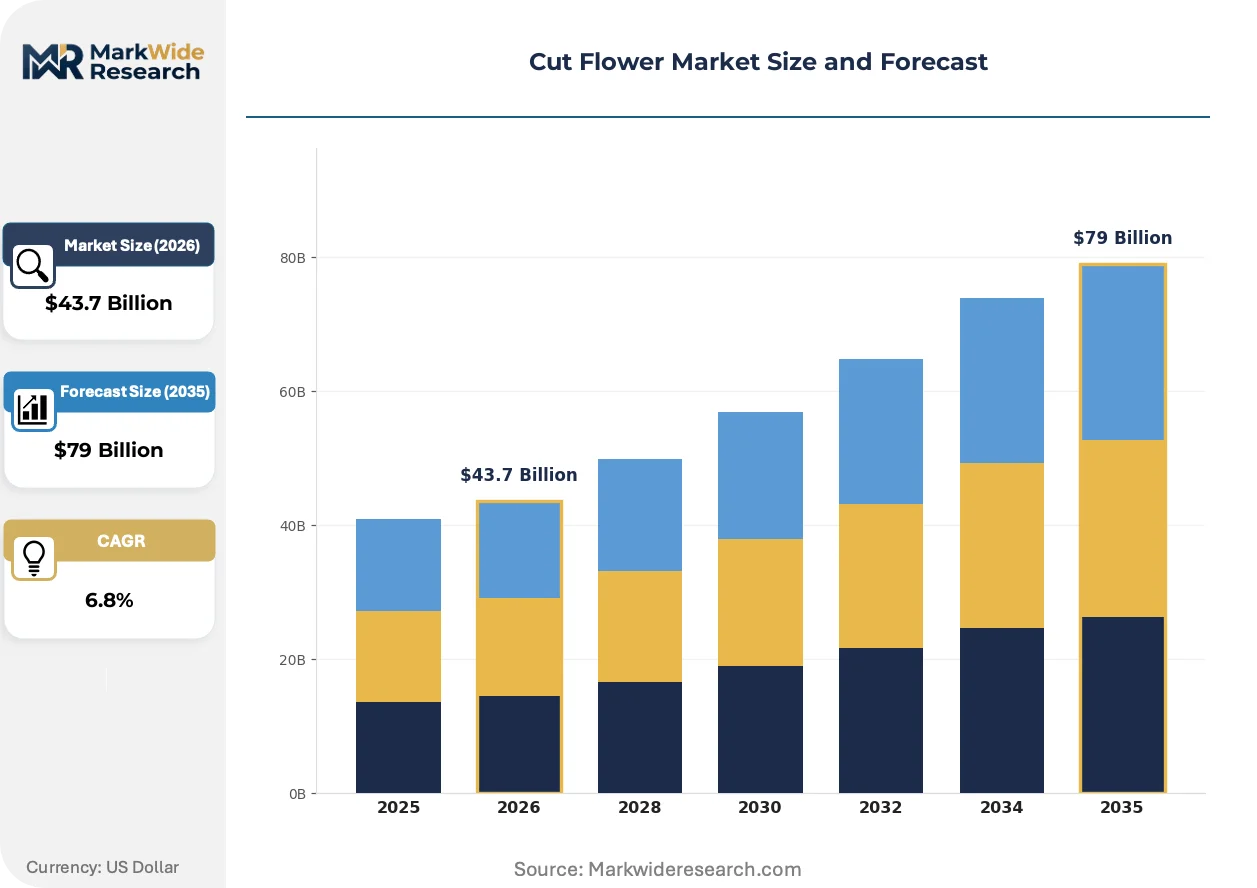
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roses, Tulips, Lilies, Carnations End User: Retail Florists, Event Planners, Wholesale Distributors, Online Retailers Delivery Mode: Direct Delivery, Local Pickup, Event Delivery, Subscription Service Seasonal Variation: Spring, Summer, Autumn, Winter |
| Companies Covered | Flamingo, FTD, Danziger, UrbanStems, 1-800-Flowers.com, Dümmen Orange, The Bouqs Company, Farmgirl Flowers, Marginpar BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cut Flower Market Emerging Trajectories
Digital subscription models, regulatory-driven cold-chain modernization, and shifting procurement patterns are compressing traditional wholesale layers while elevating farm-direct relationships.
Controlled-atmosphere shipping technology is hybridizing sea and air freight modalities. Major importers now trial ocean containers with modified atmosphere systems for non-rose varieties, extending transit tolerance from days to weeks. This compression of transport cost structures enables East African farms to bypass traditional air-cargo dependency for selected product lines.
REACH chemical registration requirements and EU F-Gas refrigerant mandates are restructuring European supply chain compliance. Input suppliers must reformulate crop protection chemistries and cold-chain operators face accelerated equipment replacement cycles. Dutch and German import handlers absorb disproportionate compliance burden while building certified-cold-chain credibility as competitive differentiation.
Household purchasing through digital subscription platforms displaces impulse supermarket and florist transactions. Recurring delivery commitments generate demand visibility that farms convert into production planning advantages. This pattern concentrates most visibly in US coastal metropolitan markets where same-day and next-day fulfillment networks achieve critical density.
Cut Flower Market Segmentation
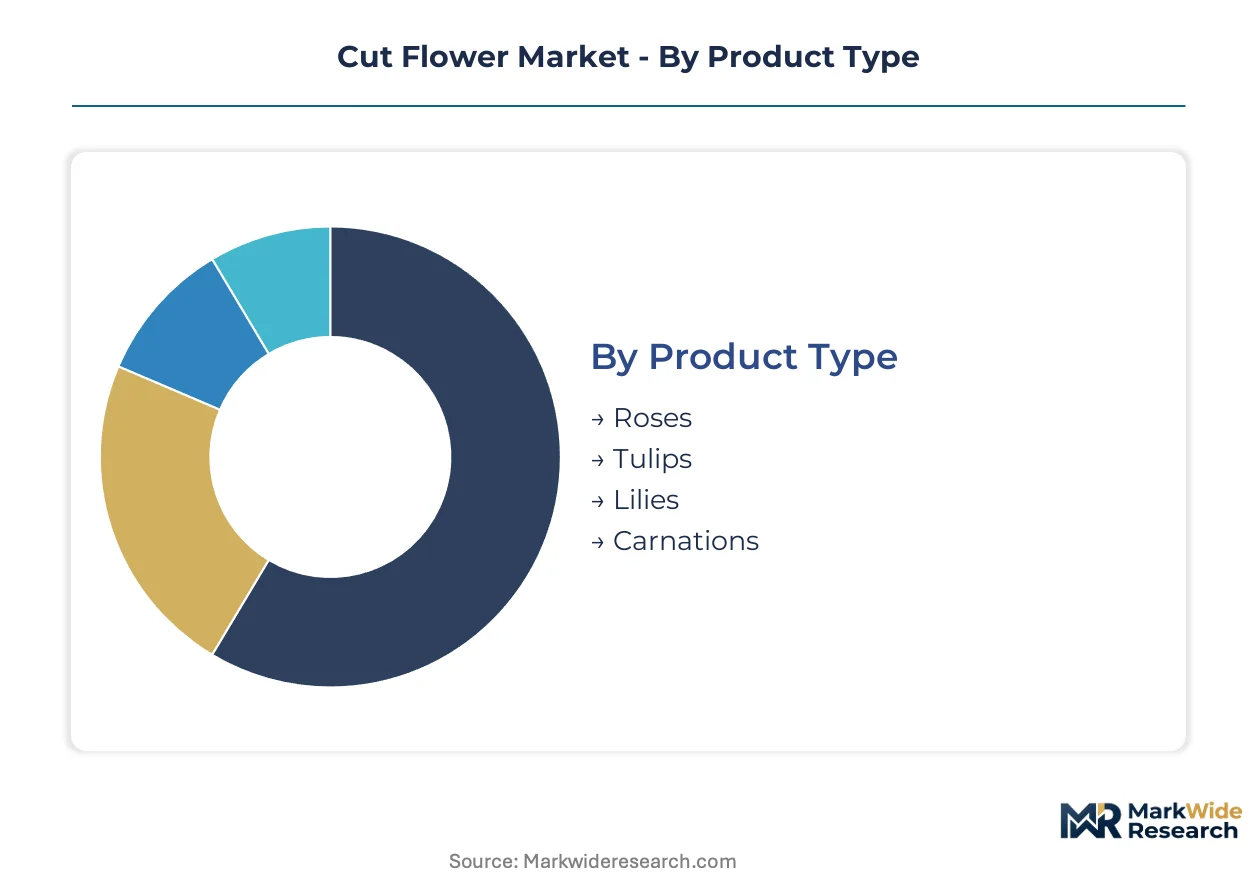
Segmentation in cut flowers exposes how product physiology, fulfillment urgency, and procurement channel economics allocate margin pools differently. Each dimension reveals distinct operational requirements for cold-chain investment and customer acquisition costs.
Product Type:
Mature rose and lily categories dominate revenue concentration while tulips and carnations occupy specialized volume niches with distinct sourcing geographies.
- Roses:Woody-stemmed blooms with extended vase life of 10-14 days under controlled atmosphere. Premium Valentine's and Mother's Day demand concentrates in US metropolitan markets, where subscription platforms capture recurring household spend. Kenya and Ethiopia supply year-round availability through equatorial production.
- Lilies:Bulb-derived flowers requiring ethylene-sensitive handling and specialized post-harvest treatment. Event planner procurement drives demand concentration, with fragrance intensity and bloom stage timing determining suitability for wedding and corporate installations.
- Tulips:Geophytes with limited vase life of 5-7 days and strict temperature requirements to prevent stem elongation. Netherlands field production and greenhouse operations supply concentrated spring-season Northern Hemisphere demand.
- Carnations:Dianthus caryophyllus varieties with exceptional durability and low per-stem cost structure. Bulk funeral and hospitality procurement in price-sensitive segments favors Colombian and Ecuadorian field production.
Roses handle the majority of throughput; lilies are the fastest mover on share through event-specialist channel expansion.
End User:
Channel cost structures separate transaction-frequency models from project-based procurement with divergent logistics requirements.
- Retail Florists:Brick-and-mortar operations combining walk-in impulse purchases with telephone order fulfillment. Dutch auction connectivity and local wholesaler relationships determine product availability and margin capture.
- Event Planners:Wedding and corporate function specialists requiring guaranteed bloom-stage timing and bespoke color matching. Miami and Los Angeles import corridors supply time-sensitive procurement with elevated quality specifications.
- Wholesale Distributors:Volume aggregators serving downstream retail and event channels through Aalsmeer auction participation or direct farm contracting. Cold-chain asset intensity and phytosanitary compliance expertise create entry barriers.
- Online Retailers:Digital-native platforms leveraging subscription mechanics and direct-to-consumer logistics. Same-day fulfillment networks in coastal US metros and European capitals enable customer acquisition at scale.
Wholesale distributors maintain volume leadership; online retailers are expanding most quickly through recurring revenue mechanics.
Delivery Mode:
Fulfillment timing precision and handling intensity separate premium-positioned services from cost-optimized alternatives.
- Direct Delivery:Farm-to-door shipment bypassing intermediary handling stages. Kenya and Ecuador export operations leverage this channel for US and EU customer acquisition, absorbing logistics complexity to capture retail-equivalent pricing.
- Local Pickup:Consumer collection from retail florist or warehouse location. Reduced last-mile cost structure supports price-competitive positioning in suburban and secondary metropolitan markets.
- Event Delivery:Time-guaranteed installation with on-site arrangement construction. Wedding and corporate segments absorb premium pricing for reliability assurance and design consultation integration.
- Subscription Service:Recurring weekly or biweekly bouquet delivery with prepaid commitment. Digital platforms convert demand visibility into production planning advantages and reduced post-harvest loss.
Direct delivery channels process the highest stem volume; subscription services are climbing the fastest as household purchasing patterns shift.
Seasonal Variation:
Production geography and controlled-environment investment determine supply continuity across demand peaks and troughs.
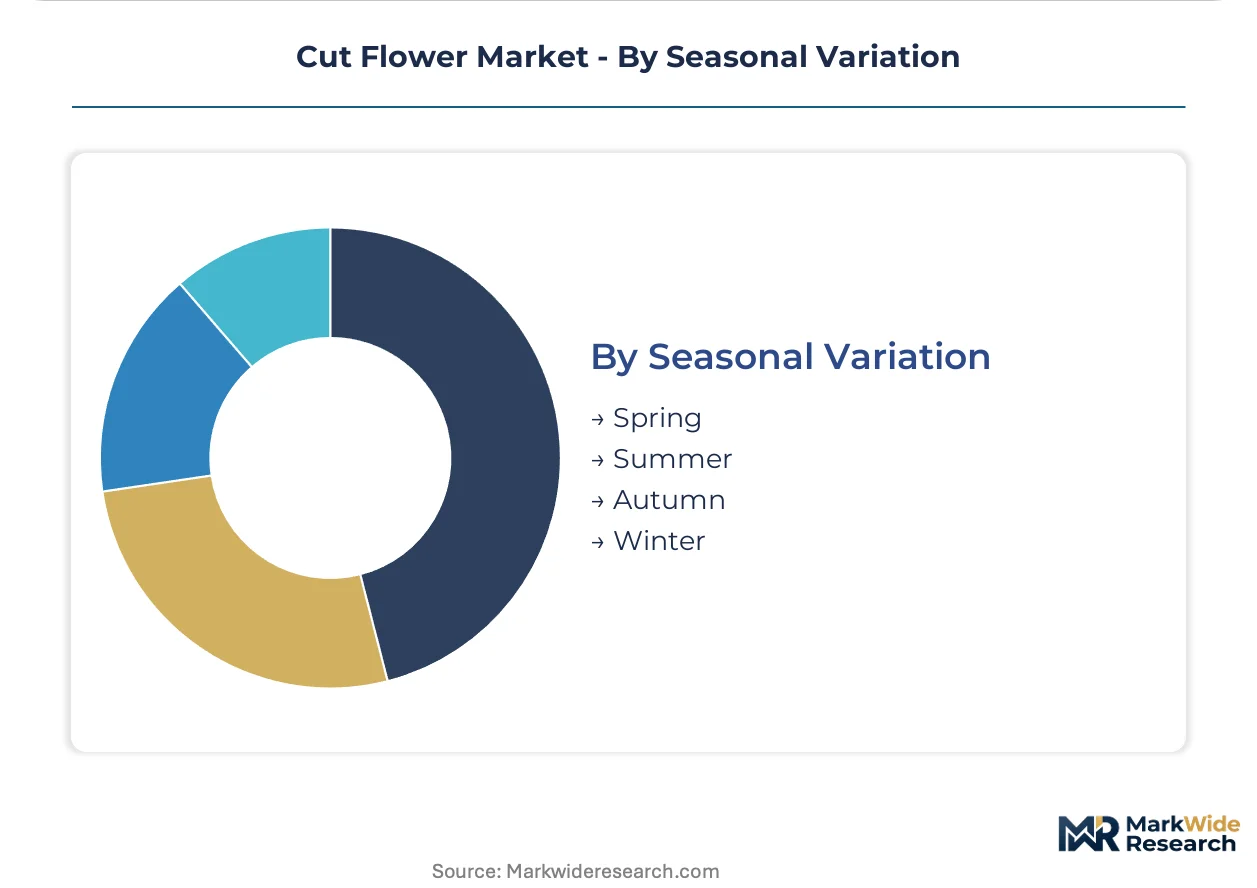
- Spring:Peak demand concentration around Easter and Mother's Day in Northern Hemisphere markets. Netherlands tulip field production and Colombian rose greenhouse output face compressed fulfillment windows.
- Summer:Wedding season procurement elevation combines with reduced domestic field availability in temperate climates. East African equatorial production supplies quality consistency without supplemental lighting cost.
- Autumn:Transitional period with school reopening and corporate event resumption. Mixed-origin sourcing strategies balance Southern Hemisphere spring production against Northern Hemisphere greenhouse supply.
- Winter:Valentine's Day and holiday season demand spikes requiring inventory pre-positioning. Cold-chain capacity constraints at Miami and Amsterdam entry points create fulfillment bottlenecks.
Spring and winter quarters absorb peak demand intensity; summer sourcing is gaining operational sophistication through East African supply integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cut flower consumption patterns diverge sharply by geography. European households favor weekly bouquet subscriptions through digital platforms. US procurement concentrates around Valentine's Day and Mother's Day peaks with premium event-driven purchasing. East African equatorial farms supply year-round rose availability to both markets.
United States
Event-driven demand from weddings and corporate functions absorbs premium stem volumes. USDA phytosanitary import protocols govern entry through Miami and Los Angeles corridors. California greenhouse operations in Ventura County and Santa Barbara County capture local-origin positioning through transparent farm partnerships.
Netherlands
Aalsmeer auction infrastructure handles global price discovery for tulip and lily varieties. REACH chemical registration and EU F-Gas Regulation impose compliance costs on cold-chain operators. Westland greenhouse clusters around Naaldwijk maintain breeding expertise and post-harvest physiology specialization.
Kenya
Equatorial rose production supplies Northern Hemisphere demand without supplemental lighting cost. EU F-Gas Regulation drives investment in controlled-atmosphere sea freight trials. Naivasha and Thika growing regions concentrate export-grade cultivation with direct-to-retailer bypass capabilities.
Germany
Subscription commerce penetration exceeds other European markets through digital-native platform adoption. ECHA chemical governance and EU F-Gas refrigerant mandates reshape import logistics standards. Berlin and Hamburg metropolitan areas anchor same-day fulfillment network density.
Ecuador
Field-grown rose and summer flower exports leverage altitude and equatorial conditions for stem length and vase life. USDA phytosanitary inspections at Miami entry points create transit bottlenecks. Quito and Cayambe production zones supply direct-delivery channels to US and EU retailers.
Cut Flower Market Vendor Landscape
Capability concentration sits with breeding specialists and cold-chain operators; scale advantage sits with vertically integrated farm networks and digital platforms. The market structures around three tiers: proprietary cultivar developers, equatorial production aggregators, and direct-to-consumer subscription platforms. Competitive moves center on backward integration into captive farm supply and API connectivity with legacy auction trading systems.
Within the vertically integrated tier, Flamingo anchors East African production networks while Dümmen Orange represents proprietary breeding program concentration. Farmgirl Flowers occupies a position emphasizing domestic sourcing transparency. These three exemplify how geographic specialization and channel strategy differentiate competitive positioning without overlapping core capabilities.
| Leading Market Players |
|---|
| Flamingo |
| FTD |
| Danziger |
| UrbanStems |
| 1-800-Flowers.com |
| Dümmen Orange |
| The Bouqs Company |
| Farmgirl Flowers |
| Marginpar BV |
| Others |
Supply Flow & Price Mechanics
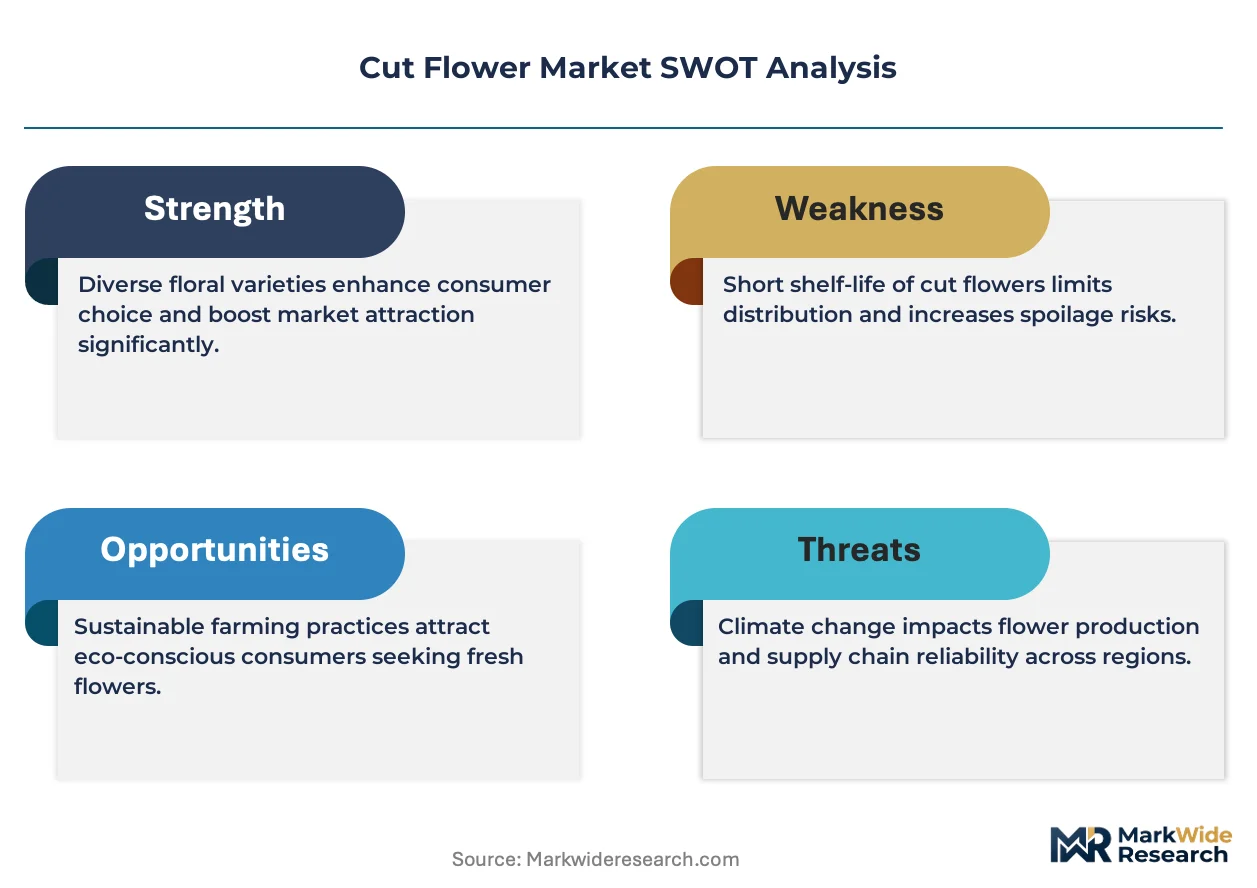
Kenya and Ethiopia's equatorial rose production concentration anchors margin capture at the farmgate, while downstream subscription platforms extract value through recurring revenue mechanics that bypass traditional auction intermediaries. This upstream-downstream tension reshapes how pricing power distributes across temperature-controlled logistics corridors.
Pricing Analysis
Long-term offtake contracts between East African farms and European retailers anchor volume pricing, while spot procurement through Aalsmeer auctions sets reference levels for event-specialist demand. Three-tier pricing structure across premium event-grade, standard retail, and economy funeral-hospitality segments reflects stem length and vase life certification. Pricing pressure stems from dried floral substitutes capturing gift-segment spend. Event planners demonstrate lowest price sensitivity; bulk hospitality procurement shows highest.
Supply Chain Analysis
Tariff exposure between Ecuador and the United States through Miami entry-point inspections dominates supply chain risk planning for Latin American exporters. Production concentrates in Kenya, Ethiopia, and Ecuador for equatorial rose supply, with Netherlands greenhouse operations for tulip and lily specialization. Input dependencies span fertilizer formulations, diesel fuel for irrigation, and refrigerant gases for controlled-atmosphere transport. Distribution runs through direct-delivery farm networks, wholesale auction houses, and digital subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across procurement channels creates specialist opportunities as household demand shifts from impulse supermarket purchases toward recurring subscription commitments. This demand-side reconfiguration rewards differentiated positioning over scale dominance.
For Market Incumbents: Insulate core farmgate margins through captive cold-chain infrastructure investments in Kenya and Ethiopia, countering direct-delivery challengers. Deepen API connectivity with Aalsmeer and Naaldwijk trading systems to capture digital platform order flows. Certification investment in EU F-Gas compliant transport equipment builds defensible credibility with European retailers. For New Entrants and Emerging Players: Domestic greenhouse operations in California and Florida represent the most penetrable entry point for local-origin premium positioning. Event delivery specialization for wedding and corporate segments offers margin capture through time-guaranteed fulfillment. Blockchain provenance tracking as a go-to-market angle aligns with emerging retailer ESG requirements. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated farm networks with direct-retailer relationships and controlled-atmosphere shipping capabilities. Long-term viability over a multi-year horizon rests on climate-resilient equatorial production geography and subscription commerce integration. Watch for inflection in sea freight trial adoption rates as a signal of transport cost structure compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Farm Supply | Kenya and Ethiopia land acquisitions secure year-round rose availability without auction dependency. |
| Controlled-Atmosphere Sea Freight Trials | Ocean container conversion reduces air-cargo costs for East African non-rose variety exports. |
| Subscription Platform API Development | Direct connectivity with Aalsmeer trading systems captures wholesale auction liquidity. |
| Blockchain Provenance Implementation | Farm-to-vase transparency satisfies retailer ESG sourcing requirements and consumer traceability demand. |
| Event Delivery Specialization Buildout | Time-guaranteed wedding and corporate installation commands premium pricing through reliability assurance. |
Methodological Framework
Desk research of customs trade data, USDA phytosanitary filing records, and EU regulatory disclosure databases preceded structured interviews with cold-chain logistics operators, East African farm export managers, Dutch auction house trading specialists, and digital platform procurement leads. Primary fieldwork combined with secondary validation through SEC filings of listed floral retailers and industry association production statistics. Bottom-up volume triangulation against top-down value estimates calibrated segment-level outputs.
Assumptions held fixed across the projection horizon include prevailing EU F-Gas refrigerant phase-down schedules and USDA import protocol inspection intensity at Miami and Los Angeles corridors. Variables tested across sensitivity scenarios span fertilizer and diesel price volatility, subscription commerce penetration rates, and sea freight trial adoption timing. Segmentation modeling incorporated product type, end-user channel, delivery mode, and seasonal demand pattern dimensions. CAGRs derived from historical volume trajectories adjusted for structural channel-shift effects.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices and freight fuel cost trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance cost evolution and cold-chain technology upgrade cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Okara Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
Africa Orange Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
Non GMO Soybean Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
Guarana Market
Agriculture and Agri Products
Specialty Egg Market
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
Palm Kernel Expeller Market
Agriculture and Agri Products
Organic Cassava Flour Market