
 Global Warm Water Aquaculture Feed Market | 2026-2036
Global Warm Water Aquaculture Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Warm Water Aquaculture Feed Market Outlook
Smallholder cooperatives is collapsing as the dominant buyer archetype while industrial shrimp and tilapia operations gain procurement share. Cargill Incorporated leverages its integrated soy processing network to secure cost advantages in plant-protein formulations. BioMar Group anchors Nordic extrusion expertise across Mediterranean and Southeast Asian production sites. Charoen Pokphand Foods PCL dominates integrated feed-to-table operations across Thailand and neighboring markets.
Warm water aquaculture feed denotes nutritionally complete or supplementary diets formulated for species cultured above 20°C, typically containing 25-45% crude protein with lipid profiles adjusted for tropical metabolism and digestible energy targets of 4.0-4.5 kcal per gram. These feeds sustain intensive production of shrimp, tilapia, catfish, and sea bass in pond, cage, and recirculating systems where natural productivity cannot match stocking densities. Pellet formulations command the largest volume share due to their stability in high-biomass ponds and compatibility with automated feeding systems. Medicated and organic formulation types are gaining fastest as residue monitoring tightens and export certification requirements multiply across buyer markets. Plant protein ingredient types are displacing fishmeal in cost-sensitive applications, though premium shrimp broodstock diets retain marine-derived protein minimums.
EU REACH and EFSA frameworks govern maximum residue limits and feed additive approvals for aquaculture products entering European supply chains. The FDA and USDA co-regulate imported aquaculture feed and finished seafood in the United States, with specific pathogen and contaminant thresholds. China's SAMR and GB standards enforce domestic feed safety protocols that increasingly align with export destination requirements. Stakeholders must monitor divergence between evolving mycotoxin standards in major importing jurisdictions and the ingredient traceability systems their suppliers can actually document.
Market Dynamics
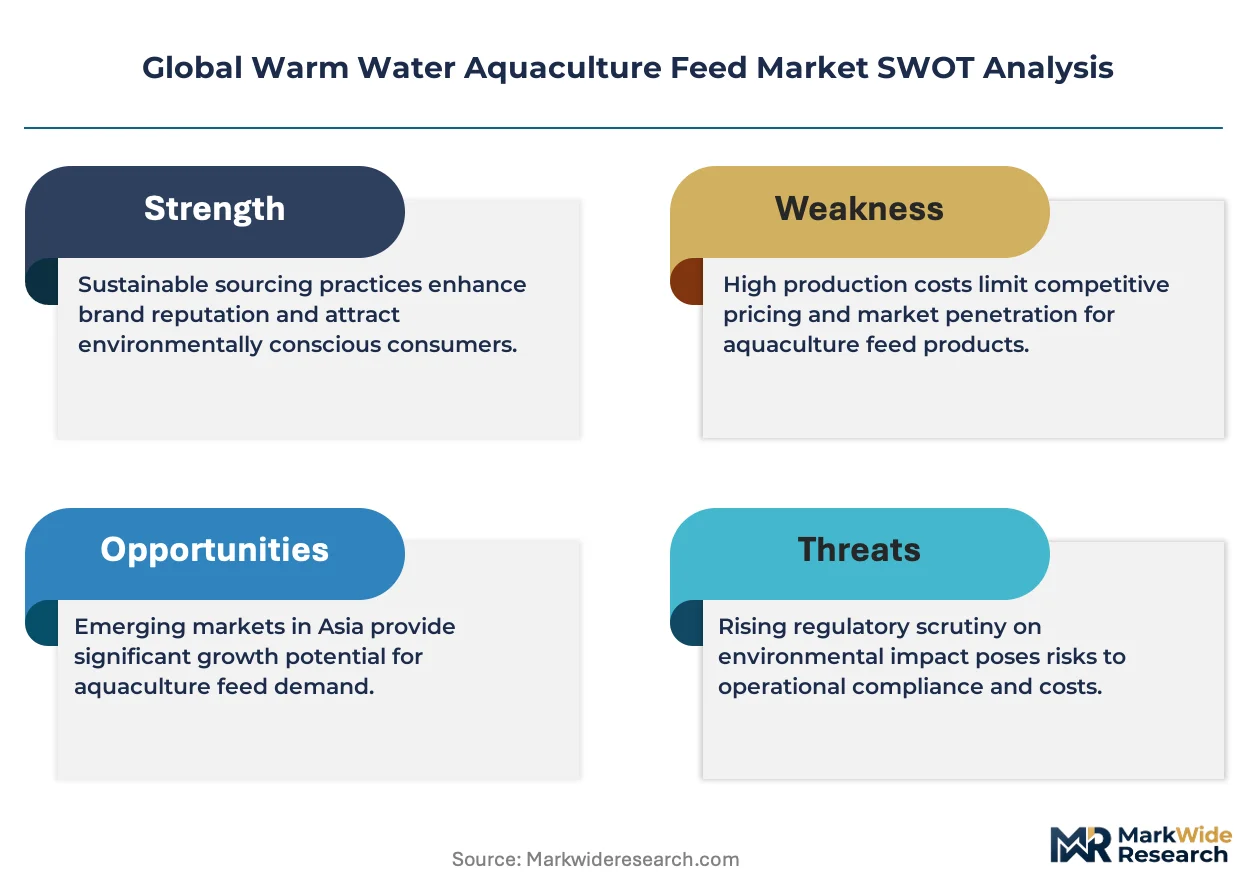
Ingredient substitution economics are compressing traditional fishmeal formulations across Southeast Asian shrimp operations, with plant-protein concentrates capturing formulation share as marine protein costs diverge from soy processing economics.
Growth Catalysts
- EU Green Deal sustainable aquaculture provisions:Certified plant protein sourcing mandates redirect procurement toward deforestation-free supply chains, accelerating feed mill certification investments across Mediterranean and Southeast Asian production sites.
- Indonesia's feed-to-farm integration:Industrial shrimp operations consolidate procurement volumes through captive hatchery networks, concentrating demand for high-performance broodstock diets with traceable ingredient documentation.
- Extrusion technology advances:Twin-screw processing systems enable higher inclusion rates of alternative proteins without pellet durability loss, supporting density-intensified pond systems across Vietnam and India.
Market Restraints
- Soy protein concentrate cost volatility:Crush margin compression at major oilseed processors transmits directly to feed formulation economics, squeezing mid-scale compounders without backward integration into oilseed processing.
- Single-origin marine ingredient concentration:Premium shrimp maturation diets remain dependent on Antarctic krill and Peruvian anchovy meal, creating supply vulnerability to El Niño-driven catch fluctuations.
- REACH mycotoxin divergence:EFSA tightening of aflatoxin B1 and deoxynivalenol limits for aquaculture feeds exceeds documentation capabilities of many Southeast Asian ingredient suppliers, blocking EU market access.
Strategic Opportunities
- India's eastern seaboard expansion:Andhra Pradesh and Tamil Nadu pond infrastructure investments outpace domestic feed mill capacity, creating import substitution potential for integrated Thai and Vietnamese producers.
- Organic certification premiums:EU Regulation 2018/848 aquaculture standards create price differentiation for certified organic feeds, rewarding early compliance investments in traceability systems.
- Recirculating aquaculture system feed specialization:Closed-loop shrimp and tilapia operations in Saudi Arabia and UAE demand low-fouling formulations with enhanced digestibility, opening premium formulation segments.
Industry Challenges
- Formulation chemist scarcity:Rapid protein substitution outpaces technical training pipelines, leaving compounders dependent on external technical service agreements for novel ingredient matrix optimization.
- Export certification timeline compression:BRC and GMP+ accreditation requirements for EU and US-bound feeds extend qualification cycles, freezing formulation changes during audit windows.
- Ingredient provenance documentation:Mass balance verification for deforestation-free soy and fishery improvement project marine meals demands IT infrastructure investments beyond smallholder cooperative capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Warm Water Aquaculture Feed Market |
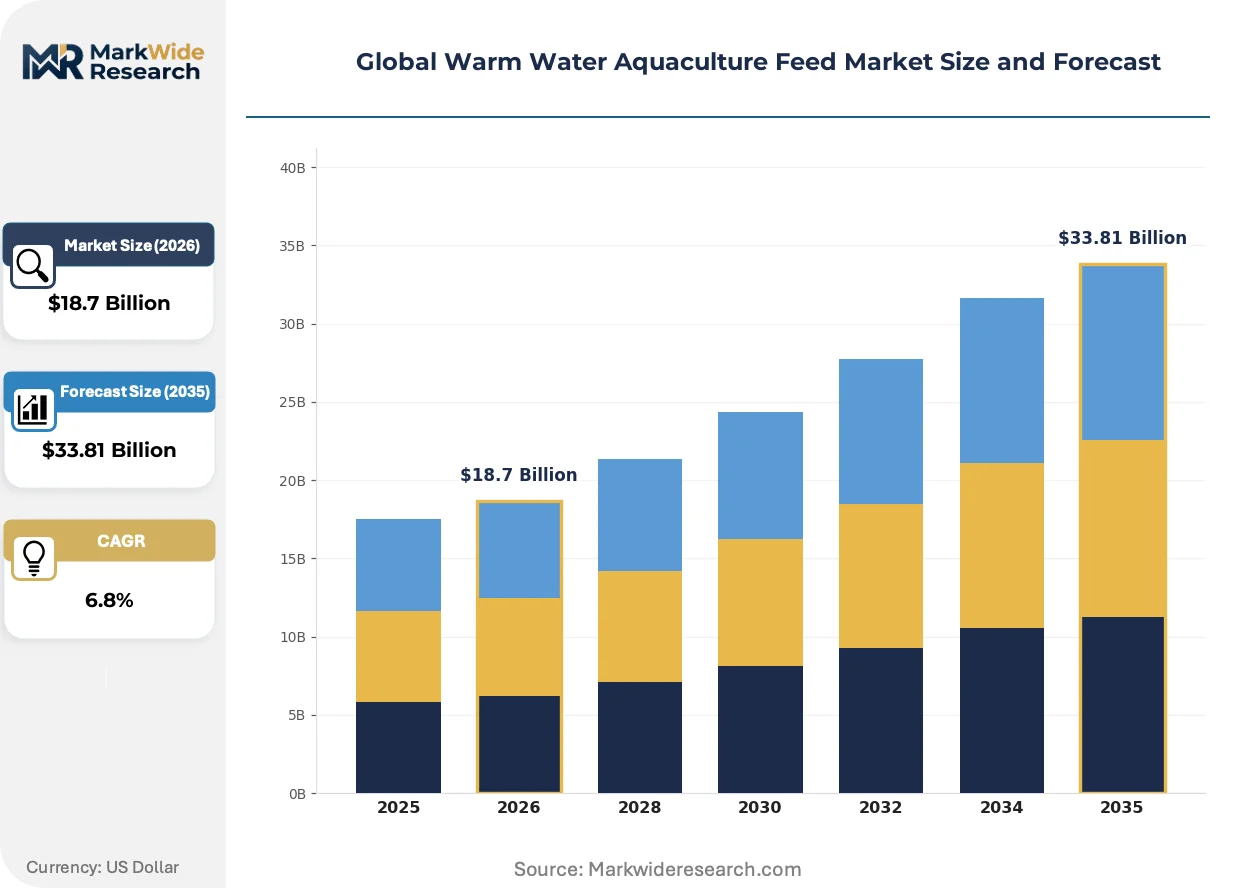
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feed Type: Pellets, Crumbles, Meals, Granules Ingredient Type: Fishmeal, Plant Protein, Oils, Vitamins Formulation Type: Complete, Supplementary, Medicated, Organic End User: Fish Farms, Aquaponics, Research Institutions, Commercial Fisheries |
| Companies Covered | Cargill Incorporated, Nutreco N.V., BioMar Group, Charoen Pokphand Foods PCL, Aller Aqua Group, Alltech Inc., Avanti Feeds Limited, BENEO, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Warm Water Aquaculture Feed Market Strategic Shifts
Single-cell protein fermentation and insect meal processing are converging with precision extrusion to reshape ingredient portfolios, while regulatory residue monitoring tightens formulation transparency requirements across export-oriented supply chains.
Microbial biomass cultivation from methanotrophic bacteria is supplanting fishmeal in grow-out diets for tilapia and catfish. Vietnamese and Indonesian integrators now specify 15-20% single-cell protein inclusion in standard grower formulations. This substitution is compressing marine protein demand in cost-sensitive segments while preserving premium shrimp broodstock diets for marine-derived minimums.
EFSA's 2023 updated guidance on feed additive safety assessments now requires extended environmental fate studies for novel proteins entering European supply chains. Compounders serving EU export markets must front-load toxicology and ecotoxicology data packages before formulation registration. Mediterranean sea bass and seabream producers face the tightest compliance timelines as their buyer concentration in Italian and Spanish retail chains intensifies certification scrutiny.
Long-term offtake contracting is displacing spot market purchasing among industrial shrimp operations in Thailand and Vietnam. Feed mills now offer 12-18 month volume commitments with indexed pricing to secure utilization rates. This shift is most visible across Charoen Pokphand Foods' integrated operations and independent processors supplying Costco and Tesco certification programs, where supply security outweighs short-term price optimization.
Global Warm Water Aquaculture Feed Market Segmentation
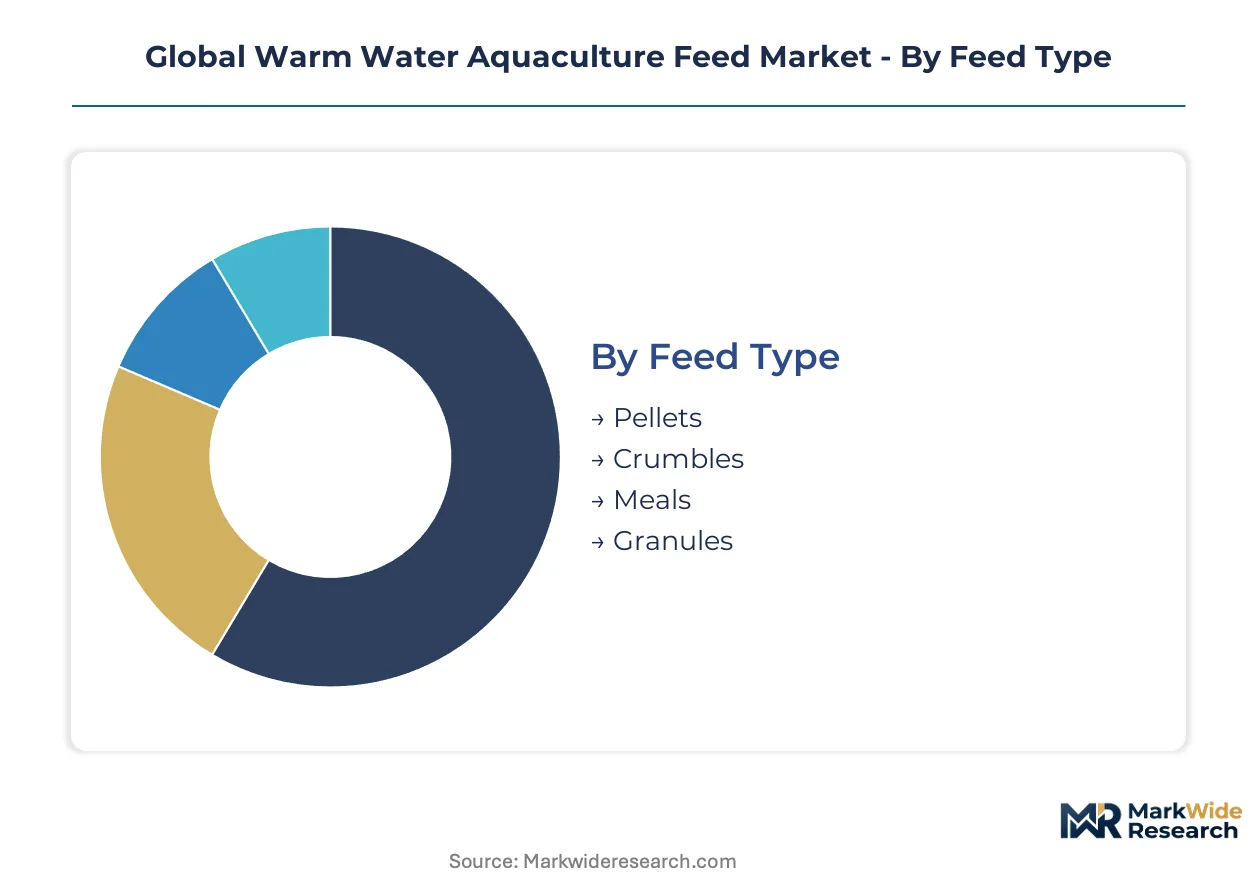
Physical form and nutritional composition determine feed handling economics, pond stability, and species-specific intake efficiency across tropical aquaculture systems. Procurement managers in Southeast Asian shrimp operations and Mediterranean sea bass farms prioritize format selection based on biomass density, automated feeding compatibility, and residue certification requirements.
Feed Type:
Alternative protein concentrates and extrusion advances are reshaping which physical formats can deliver performance without fishmeal dependence.
- Pellets:Compressed extruded cylinders with 2-8mm diameter ranges engineered for high-biomass pond stability and automated feeder compatibility. Vietnamese and Indonesian industrial shrimp operations concentrate procurement here due to sinking rate control and reduced nutrient leaching in density-intensified systems.
- Crumbles:Fragmented pellet products sized for juvenile fish and early-stage shrimp post-larvae with softer texture profiles. Andhra Pradesh tilapia hatcheries and Thai nursery operations specify crumbled formulations for fry transition diets where particle acceptance governs survival rates.
- Meals:Powdered or finely ground feed forms for larval stages and species with filter-feeding adaptations.
- Granules:Irregular-shaped extrudates bridging pellet density with crumble palatability for mid-size grower stages.
Pellets retain volume leadership; granules hold the steepest expansion curve as extrusion technology enables higher alternative protein inclusion without durability loss.
Ingredient Type:
Cost tier stratification separates premium marine-dependent formulations from commodity plant-protein alternatives.
- Fishmeal:Marine protein concentrate derived from reduction fisheries supplying 60-72% crude protein with complete amino acid spectra. Peruvian anchovy and Antarctic krill sourcing constraints concentrate remaining demand in premium shrimp broodstock diets where export certification mandates traceable marine minimums.
- Plant Protein:Soy protein concentrate, pea protein isolate, and rapeseed meal formulations displacing fishmeal in grow-out applications. Indonesian and Vietnamese integrators now specify 35-45% plant protein inclusion in standard tilapia and catfish diets as EU Green Deal deforestation-free sourcing requirements redirect procurement toward certified crush facilities.
- Oils:Marine and vegetable lipid sources adjusting digestible energy density and essential fatty acid profiles.
- Vitamins:Premix additives ensuring micronutrient adequacy across intensive production systems.
Plant protein retains volume leadership; organic-certified ingredient sourcing represents the fastest-growing trajectory as Regulation 2018/848 compliance investments accelerate.
Formulation Type:
Application maturity separates established complete feeds from emerging certified segments facing qualification timeline compression.
- Complete:Nutritionally balanced diets containing all required macro and micronutrients for target species at specific life stages. Thai and Vietnamese industrial operations concentrate procurement here through captive feed mill networks supplying integrated hatchery-to-harvest operations.
- Supplementary:Partial diets designed for extensive pond systems with residual natural productivity.
- Medicated:Therapeutic formulations incorporating approved additives for disease prevention under strict residue monitoring protocols.
- Organic:Certified feeds meeting EU Regulation 2018/848 and equivalent standards with full ingredient traceability and synthetic additive prohibitions.
Complete feeds retain volume leadership; organic formulations are gaining share fastest as Mediterranean retail chain certification requirements multiply.
End User:
Customer scale and integration depth determine specification complexity and contract structure preferences.
- Fish Farms:Intensive pond, cage, and recirculating system operators requiring bulk volume procurement with 12-18 month offtake commitments. Charoen Pokphand Foods and BioMar Group concentrate service here through technical support teams embedded across Thailand, Vietnam, and Indonesia.
- Aquaponics:Integrated plant-fish production systems demanding low-fouling formulations with enhanced digestibility.
- Research Institutions:Experimental facilities requiring small-batch custom formulations for nutrition trials and breeding programs.
- Commercial Fisheries:Capture-based operations using aquaculture feeds for live bait or holding pen conditioning.
Fish farms retain volume leadership; aquaponics operations are expanding most quickly as Saudi Arabia and UAE closed-loop investments create premium formulation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Laem Chabang Deep Sea Port anchors Thailand's position as Southeast Asia's aquafeed distribution hub, handling bulk soy protein concentrate and fishmeal shipments for re-export across the Mekong basin. Integrated feed mill clusters along the Eastern Economic Corridor process formulated diets for industrial shrimp operations.
Thailand
Charoen Pokphand Foods' captive hatchery networks concentrate demand for high-performance broodstock diets with full ingredient traceability. The Thai FDA enforces feed safety protocols aligned with EU export requirements. Samut Sakhon and Chachoengsao provinces host the densest feed mill infrastructure, supplying integrated operations across the Gulf of Thailand.
Vietnam
Mekong Delta shrimp farms are scaling 12-18 month offtake contracts to secure utilization rates at extrusion facilities. Vietnam's Ministry of Agriculture and Rural Development implements circulars on antibiotic residue monitoring that exceed domestic enforcement capacity. Bac Lieu and Ca Mau provinces concentrate industrial pond systems demanding pellet stability in density-intensified operations.
Indonesia
East Java and Sulawesi feed mills are redirecting procurement toward RSPO-certified palm kernel meal under EU Green Deal deforestation-free mandates. Indonesia's National Agency of Drug and Food Control (BPOM) enforces halal certification requirements that complicate marine protein sourcing. Lampung and South Sulawesi clusters supply integrated operations with captive broodstock networks.
India
Andhra Pradesh pond infrastructure investments outpace domestic feed mill capacity, creating import substitution openings. India's FSSAI enforces mycotoxin limits that diverge from EFSA thresholds, blocking some EU-bound supply chains. Visakhapatnam and Krishnapatnam ports handle growing soy protein concentrate volumes for Tamil Nadu and Andhra Pradesh operations.
Saudi Arabia
NEOM and Jazan Economic City recirculating aquaculture systems demand low-fouling formulations with enhanced digestibility for closed-loop shrimp production. The Saudi Food and Drug Authority (SFDA) adopts EU-equivalent residue standards for export-oriented operations. Red Sea coastal zones concentrate premium formulation demand from technology-intensive farms serving Gulf retail chains.
Global Warm Water Aquaculture Feed Market Competitive Environment
Listed leaders compete with private specialists across certification depth and backward integration reach. The market structures around three tiers: multinational compounders with oilseed processing networks, regional integrators with captive hatchery supply, and specialized extrusion contractors serving independent farms. Strategic archetypes include soy-processing conglomerates leveraging crush economics, Mediterranean-Nordic technology licensors, and Southeast Asian feed-to-table operators. Dominant competitive moves involve long-term offtake contracting with indexed pricing and certification co-investments for EU Green Deal compliance.
Within the integrated conglomerate tier, Cargill Incorporated and Charoen Pokphand Foods PCL exemplify divergent approaches to supply chain control. Cargill's position reflects oilseed processing economics applied to plant-protein formulation cost structures. Charoen Pokphand Foods occupies a distinct space through hatchery-to-harvest integration across Thailand and neighboring markets. BioMar Group represents the technology-licensing archetype, anchoring Nordic extrusion expertise across Mediterranean and Southeast Asian production sites.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Nutreco N.V. |
| BioMar Group |
| Charoen Pokphand Foods PCL |
| Aller Aqua Group |
| Alltech Inc. |
| Avanti Feeds Limited |
| BENEO |
| DSM-Firmenich |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracting with indexed pricing locks in both supply access and price visibility for industrial shrimp operations across Thailand and Vietnam, compressing spot market liquidity while binding feed mills to 12-18 month utilization commitments under EU Green Deal traceability requirements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates organic-certified broodstock formulations from commodity grow-out diets and uncertified regional blends. Price differentiation rests on certification grade and volume scale, with EU Regulation 2018/848 compliance commanding substantial premia over standard formulations. Cost compression in economy tiers is intensifying because soy protein concentrate crush margins transmit directly to formulation economics. Smallholder cooperatives exhibit highest price sensitivity, while integrated industrial operations prioritize supply security over short-term optimization.
Supply Chain Analysis
Laem Chabang Deep Sea Port transit underwrites Southeast Asian feed ingredient distribution, anchoring bulk soy protein concentrate flows from crushing facilities across Indonesia and Vietnam. Raw material dependencies center on Peruvian anchovy meal, Antarctic krill, and RSPO-certified palm kernel meal. Single-source vulnerability concentrates in marine protein streams subject to El Niño-driven catch fluctuations. Distribution runs through integrated feed mill clusters along Thailand's Eastern Economic Corridor and captive hatchery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where technical support teams and formulation consulting expand faster than commodity feed volumes, with embedded nutritionists and residue documentation services capturing recurring revenue from certification-dependent export operations.
For Market Incumbents: Fortify backward integration into oilseed processing to secure crush margin capture as soy protein concentrate cost volatility squeezes mid-scale compounders. Deepen certification co-investments for EU Green Deal compliance to defend against Nordic technology licensors expanding extrusion service contracts across Mediterranean sea bass operations. For New Entrants and Emerging Players: Anchor in India's eastern seaboard import substitution gap, where Andhra Pradesh pond infrastructure investments outpace domestic feed mill capacity. Target aquaponics low-fouling formulation segments across Saudi Arabia and UAE as the most penetrable premium niche, deploying technical service partnerships with recirculating system engineering firms as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward regional integrators with captive hatchery networks and established EU export certification pathways, given their structural insulation from spot market volatility and residue documentation bottlenecks. Watch single-cell protein fermentation scale-up rates as the signal indicating when marine protein substitution economics will compress premium tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Cargill's captive soy crush network secures cost advantages in plant-protein formulations against non-integrated compounders. |
| EU Green Deal Certification Co-Investment | Deforestation-free supply chain documentation opens access to premium Mediterranean retail chain procurement programs. |
| Long-term Offtake Contracting with Indexed Pricing | Charoen Pokphand Foods' 12-18 month volume commitments lock utilization rates across integrated Thai operations. |
| Single-Cell Protein Fermentation Scale-Up | Vietnamese integrators' 15-20% microbial biomass inclusion compresses fishmeal demand in cost-sensitive tilapia segments. |
| Recirculating Aquaculture System Feed Specialization | Low-fouling formulations for Saudi NEOM operations capture premium pricing from technology-intensive closed-loop farms. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with feed mill procurement managers, hatchery network directors, EU export certification auditors, and extrusion technology specialists. Secondary validation drew from FAO aquaculture production databases, EFSA feed additive guidance documents, customs trade flow records, and GB standards filings. Bottom-up volume modeling and top-down value triangulation were cross-referenced against regional production capacity estimates.
Across the analysis window, the forecasting framework modeled physical form segmentation, ingredient type substitution dynamics, formulation certification tiers, and end-user integration depth as primary demand dimensions. CAGRs were derived from production capacity expansion rates, protein inclusion trend trajectories, and certification penetration curves. Industry-specific inputs included El Niño cycle impacts on marine protein availability and EU Green Deal implementation timelines for deforestation-free sourcing mandates.
Material uncertainties — regulatory divergence in mycotoxin standards, single-cell protein toxicology data package approvals, and crush margin volatility at major oilseed processors — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EFSA residue limit tightening and Indonesian halal certification complexity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Aloe Vera Market
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
Sudan Alfalfa Market
Agriculture and Agri Products
Africa Poultry Feed Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
Africa Orange Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
Uruguay Agricultural Products Market
Agriculture and Agri Products
Argentina Agriculture Market
Agriculture and Agri Products
Japan Floriculture Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Sugar Beet Market
Agriculture and Agri Products
Brazil Cashew Market