
 Cattle Feed Concentrate Market | 2026-2036
Cattle Feed Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Feed Concentrate Market Outlook
Aftermarket nutritional consulting and precision feeding advisory is tilting margin pools away from commodity volume sales toward value-added services. Cargill leverages its global grain procurement network to secure cost-advantaged ingredient positions across multiple continents. Nutreco anchors its portfolio through advanced premix and additive formulations that command premium positioning in dairy nutrition. De Heus Animal Nutrition specializes in region-specific concentrate recipes tailored to local forage deficiencies and breed requirements.
Cattle feed concentrate denotes nutritionally dense, industrially formulated feed products typically containing 15-25% crude protein, energy-rich grains, and supplemented vitamins and minerals, manufactured through pelleting or extrusion processes to deliver precise nutrient delivery for ruminant performance optimization. Protein Supplements capture concentrated margin pools as soybean meal and distillers grains prices drive formulation economics for high-performance dairy herds. Pellet form dominates commercial channels due to reduced waste, improved intake consistency, and compatibility with automated feeding systems in large-scale operations. Dairy Farms represent the most structurally demanding end-use segment, with concentrate ratios often exceeding 50% of dry matter intake in intensive production systems.
The EPA regulates feed manufacturing emissions under Clean Air Act provisions, while the FDA oversees medicated feed additives and veterinary feed directives that constrain antibiotic inclusion in concentrates. USDA Organic certification standards dictate ingredient provenance and processing restrictions for concentrate products sold into certified dairy and beef operations. Stakeholders must monitor evolving state-level nutrient management regulations and carbon accounting frameworks that will reshape concentrate formulation priorities and sourcing geography.
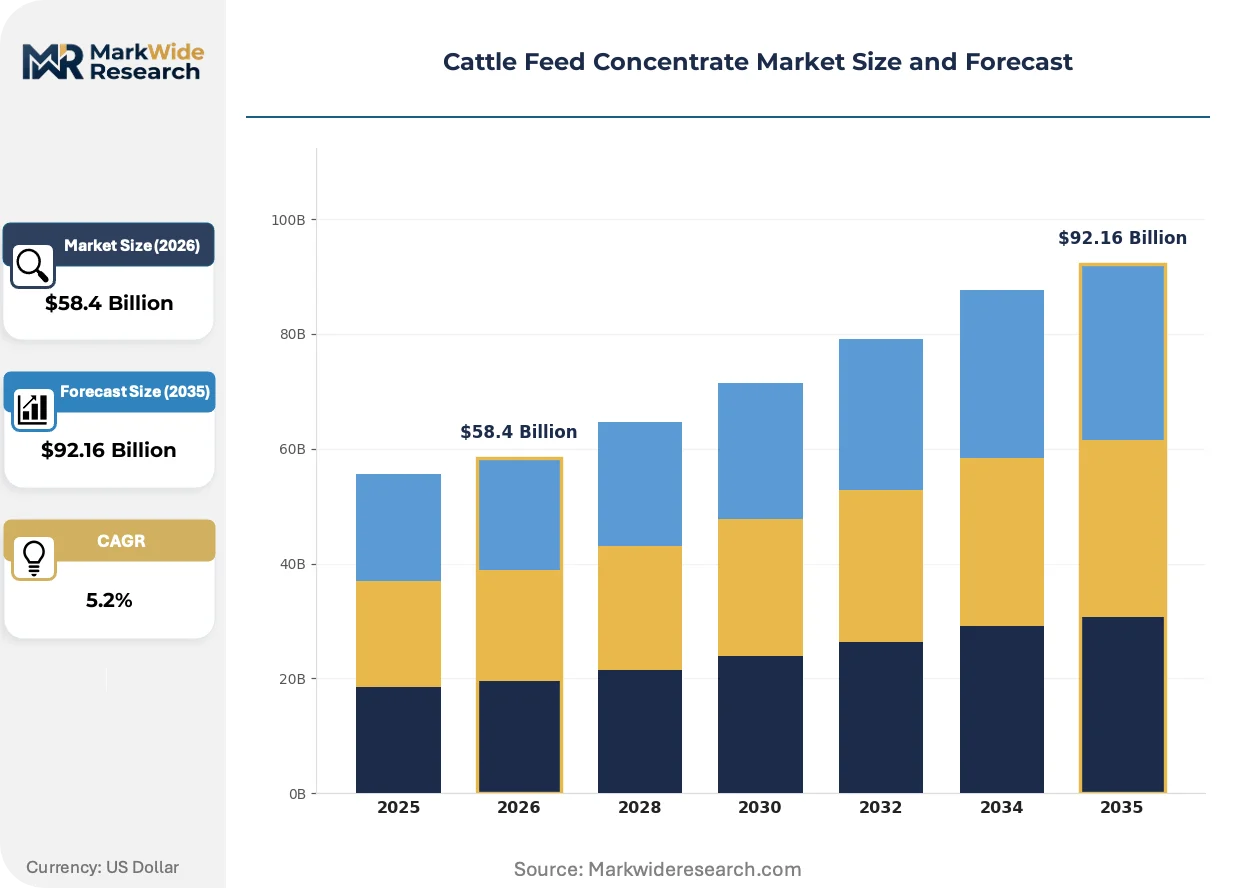
Market Dynamics
The EU Green Deal's Farm to Fork strategy is forcing concentrate manufacturers to reformulate around deforestation-free soy and reduced-carbon grain sourcing, compressing legacy supply chains while opening premium positioning for verified-sustainable producers.
Growth Catalysts
- Precision Livestock Farming:Sensor-based intake monitoring and automated ration adjustment in large-scale dairy operations is accelerating concentrate optimization and reducing feed waste.
- USDA Organic Certification:Expanding certified dairy herds across the United States is creating dedicated demand channels for ingredient-traceable concentrate products.
- Distillers Grains Integration:Ethanol co-product streams from Midwestern biofuel plants are anchoring cost-competitive protein sourcing for regional feed formulators.
Market Restraints
- Soybean Meal Price Volatility:Weather-driven South American harvest variability and export competition from Chinese crushing demand is destabilizing formulation cost structures.
- Antibiotic Restriction Compliance:FDA veterinary feed directives and state-level medicated feed regulations are constraining growth-promoter inclusion and requiring reformulation investments.
- Single-Source Grain Dependency:Concentrated procurement from Black Sea and North American breadbaskets exposes formulators to geopolitical disruption and export restriction risk.
Strategic Opportunities
- Regenerative Agriculture Partnerships:Carbon credit stacking and soil health verification under emerging state-level carbon accounting frameworks is enabling premium pricing for climate-smart concentrates.
- Insect Protein Integration:Black soldier fly and mealworm meal converging with traditional oilseed proteins is opening novel amino acid sourcing for antibiotic-free dairy systems.
- Direct-to-Farm Digital Channels:Bypassing traditional cooperative distributors through proprietary nutrition advisory platforms is capturing margin from precision feeding services in the Upper Midwest.
Industry Challenges
- Ruminant Nutritionist Scarcity:Specialized PhD-level formulation expertise required for precision ration balancing is concentrating in incumbent firms and agricultural universities, constraining independent mill expansion.
- Organic Transition Timelines:Three-year land conversion and ingredient segregation requirements for USDA certification are delaying market entry and tying up working capital for conventional suppliers pivoting to certified channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Feed Concentrate Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $92.16 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Feed, Grain-Based, Protein Supplements, Mineral Mixes End Use: Dairy Farms, Beef Cattle Operations, Organic Farms, Commercial Feedlots Form: Pellets, Powders, Liquids, Blocks Ingredient: Fruits, Legumes, Grasses, By-Products |
| Companies Covered | Alltech, Purina Animal Nutrition, Cargill, Charoen Pokphand Foods, ForFarmers, Archer Daniels Midland Company, Nutreco, De Heus Animal Nutrition, Land O’Lakes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Feed Concentrate Market Strategic Shifts
Real-time rumen monitoring and algorithmic ration adjustment are collapsing the information lag between feed delivery and metabolic response, compressing the optimization cycle from weeks to hours.
Near-infrared spectroscopy embedded in mixer wagons is collapsing the delay between ingredient variation detection and formulation correction. Large integrators in the Netherlands and Denmark are deploying these systems across multi-site dairy operations. The technology is collapsing the traditional role of periodic laboratory analysis and enabling continuous ration refinement without manual sampling delays.
REACH chemical authorization requirements and emerging EFSA feed additive safety assessments are tightening novel ingredient approval pathways. European compounders face extended registration timelines for alternative proteins and fermentation-derived nutrients. Dairy nutrition specialists are responding by anchoring R&D partnerships within established regulatory frameworks rather than pursuing unapproved novel materials.
Consolidation among US dairy cooperatives is compressing the buyer base and elevating procurement sophistication. Direct supply agreements with ethanol producers and oilseed crushers are displacing spot-market purchasing for volume concentrate buyers. This concentration is most visible in Wisconsin and California, where thousand-plus cow operations now negotiate ingredient positions twelve to eighteen months forward.
Cattle Feed Concentrate Market Segmentation
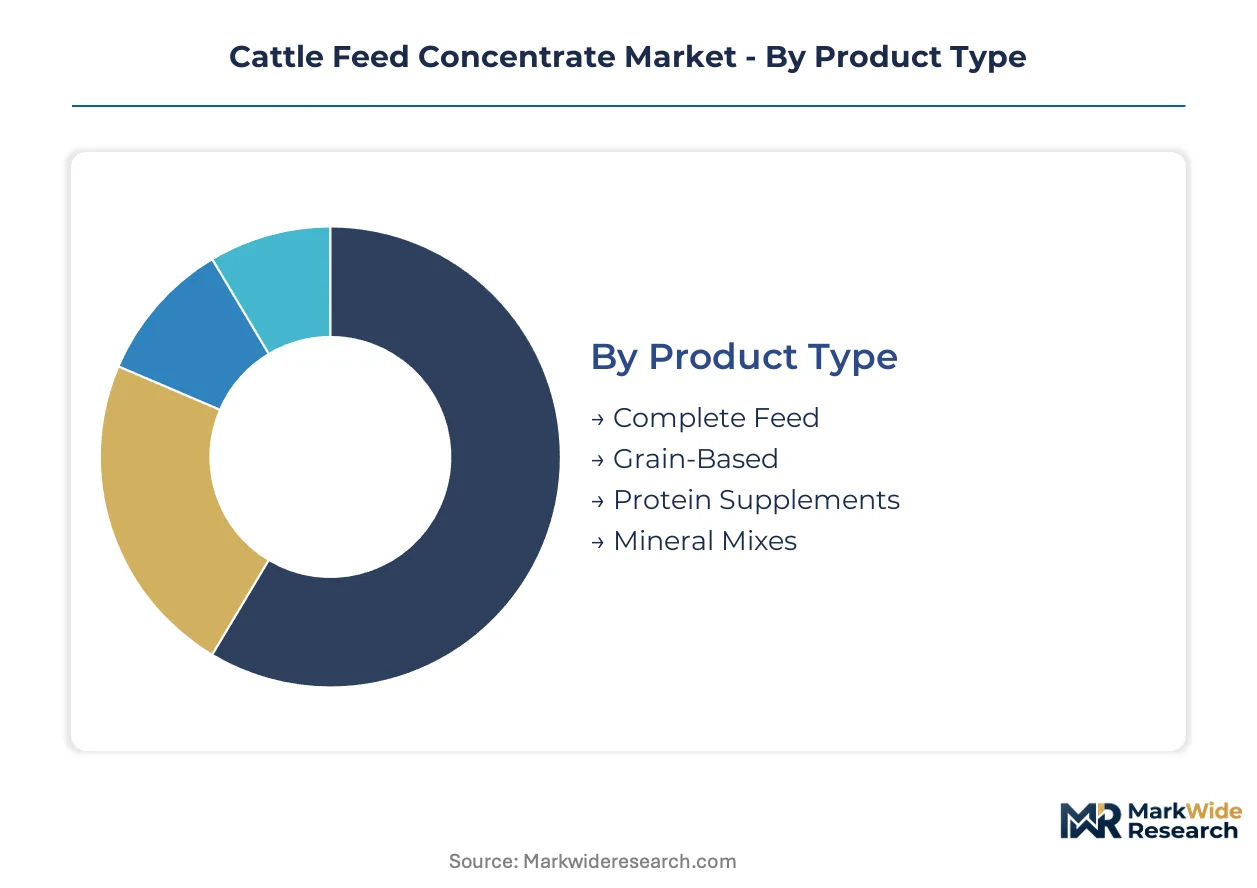
Cattle feed concentrate segmentation reveals distinct margin architectures across product tiers. Formulation complexity and regulatory compliance requirements create divergent competitive dynamics within each category.
Product Type:
Complete Feed turns inventory fastest with standardized formulations, while Mineral Mixes sit longest due to custom blending lead times.
- Complete Feed:Fully balanced rations containing 15-25% crude protein with pre-mixed vitamins and minerals for total diet replacement. Demand concentrates in large-scale commercial feedlots across Texas and Kansas where labor minimization drives procurement. Automated delivery systems favor uniform pellet specifications that reduce mixing errors.
- Protein Supplements:Concentrated amino acid sources derived from soybean meal, distillers grains, and oilseed cakes for forage-based ration balancing. Dairy farms in Wisconsin and California command the majority of volume, with formulation economics tightly coupled to commodity crush spreads and ethanol co-product availability.
- Grain-Based:Energy-dense formulations anchored by corn, barley, and sorghum for weight gain optimization.
- Mineral Mixes:Custom-trace-element blends addressing regional forage deficiencies and breed-specific metabolic requirements.
Complete Feed anchors the volume base while Protein Supplements gain share at the steepest rate.
End Use:
Commercial Feedlots represent the highest volume tier with price-sensitive procurement, while Organic Farms command premium positioning through certification requirements.
- Dairy Farms:Intensive production systems where concentrate ratios exceed 50% of dry matter intake, demanding precise energy-protein synchronization for milk yield optimization. Operations in the Upper Midwest and California Central Valley drive formulation innovation around rumen-protected amino acids and mycotoxin binders.
- Commercial Feedlots:Large-scale finishing operations with thousand-plus head capacities negotiating direct ingredient positions twelve to eighteen months forward. Texas Panhandle and Nebraska clusters dominate procurement volume, with ration design optimized for average daily gain and feed conversion efficiency.
- Beef Cattle Operations:Cow-calf and backgrounding segments with seasonal feeding patterns and lower concentrate inclusion rates.
- Organic Farms:USDA-certified operations requiring three-year land conversion and ingredient segregation with full traceability documentation.
Commercial Feedlots anchor the volume base while Organic Farms expand most quickly amid certified dairy herd growth.
Form:
Pellets dominate capital-intensive operations with automated handling, while Blocks serve extensive grazing systems with infrequent supplementation intervals.
- Pellets:Extruded or compressed cylinders reducing waste, improving intake consistency, and enabling precision delivery through automated feeding systems. Large integrators in the Netherlands and Denmark deploy these across multi-site dairy operations with real-time ration adjustment capabilities.
- Liquids:Molasses-based suspensions and emulsified fat supplements for high-energy density applications in transition cow nutrition and heat stress mitigation.
- Powders:Loose-mix formulations for on-farm blending flexibility and lower per-unit transport costs.
- Blocks:Compressed mineral and protein supplements for pasture-based systems with limited labor availability.
Pellets anchor the volume base while Liquids climb the fastest amid precision feeding technology adoption.
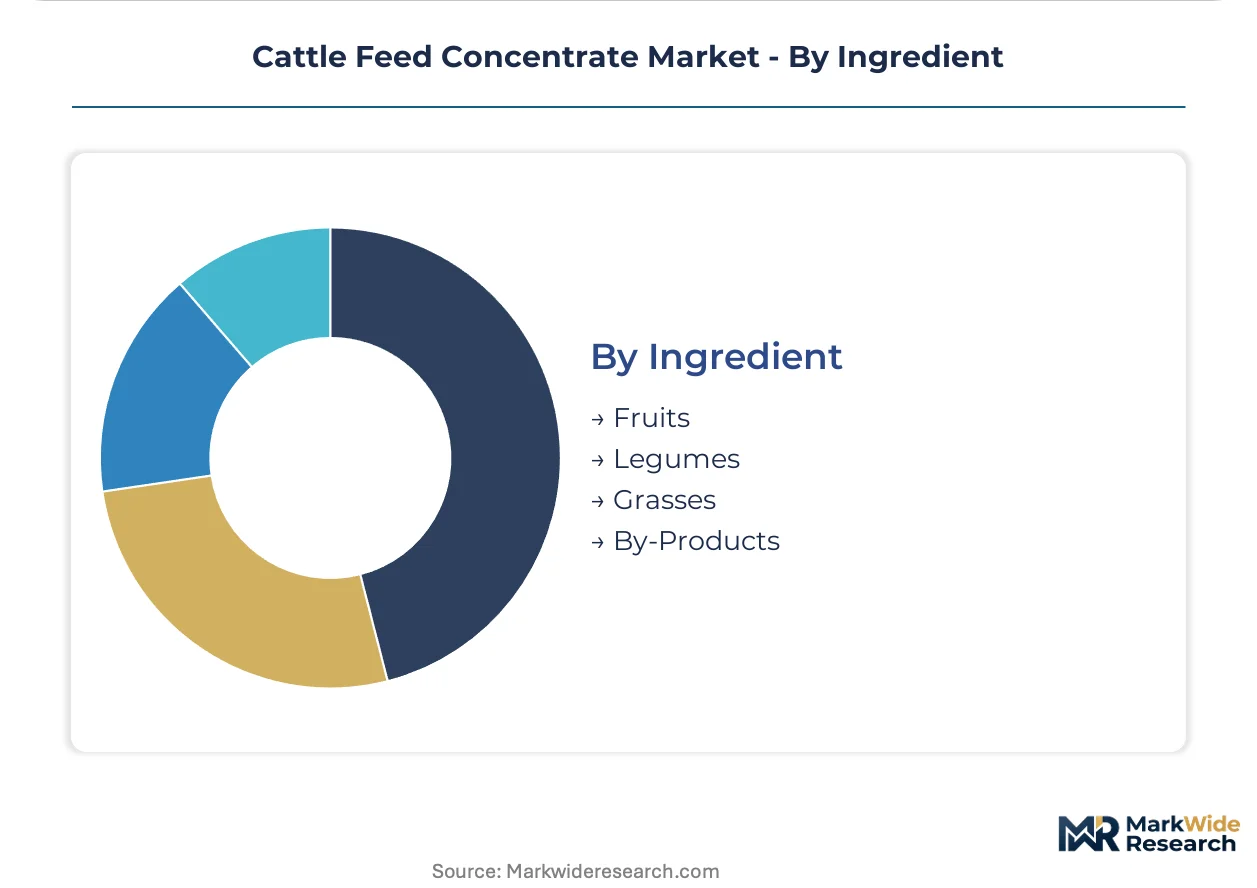
Ingredient:
By-Products turn fastest through ethanol plant and oilseed crusher offtake agreements, while Fruits face seasonal supply windows and preservation challenges.
- By-Products:Distillers grains from Midwestern biofuel plants, oilseed meals, and food processing residues anchoring cost-competitive protein sourcing. Regional feed formulators in Iowa and Illinois leverage geographic proximity to ethanol facilities for margin-advantaged procurement positions.
- Legumes:Soybean meal, lupins, and field peas providing rumen-degradable protein with amino acid profiles complementary to cereal grains.
- Grasses:Alfalfa and grass meals contributing fiber and protein to high-forage ration designs.
- Fruits:Citrus pulp, apple pomace, and other fruit residues offering fermentable fiber and palatability enhancement in niche applications.
By-Products anchor the volume base while Legumes gain share fastest amid deforestation-free sourcing mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial feedlot operators in the United States negotiate ingredient positions with minimal price elasticity, while smaller dairy cooperatives in Europe and pasture-based systems in Brazil exhibit greater sensitivity to commodity swings. This demand-elasticity contrast shapes regional formulation strategies and margin architectures.
United States
Thousand-plus cow dairy operations in Wisconsin and California drive concentrate procurement through direct supply agreements with ethanol producers. The FDA's veterinary feed directives constrain antibiotic inclusion, forcing reformulation investments. Texas Panhandle feedlots anchor volume demand with twelve-to-eighteen-month forward ingredient positions.
Brazil
Pasture-based beef operations in Mato Grosso and Goiás rely on mineral blocks and seasonal protein supplementation rather than intensive concentrate feeding. The country's national agricultural regulator enforces deforestation-free sourcing certifications under revised supply chain traceability mandates. São Paulo-state dairy clusters increasingly adopt total mixed ration systems.
Germany
Precision livestock farming adoption concentrates in Lower Saxony dairy cooperatives with automated ration adjustment capabilities. The EU Green Deal's Farm to Fork strategy mandates deforestation-free soy sourcing, compressing legacy supply chains. Bavarian compounders reformulate around reduced-carbon grain verification.
Netherlands
Multi-site dairy integrators deploy real-time rumen monitoring across Friesland and Gelderland operations. EFSA feed additive safety assessments extend novel ingredient approval timelines. Rotterdam-port proximity enables diversified oilseed meal sourcing from multiple continents.
China
Industrial dairy complexes in Heilongjiang and Inner Mongolia expand concentrate ratios as domestic milk demand intensifies. The Ministry of Agriculture and Rural Affairs tightens feed safety standards under revised national food security frameworks. Shandong Province feed mills scale premix production for regional distribution.
Cattle Feed Concentrate Market Competitive Environment
Capability concentration sits with nutrition formulation specialists; scale advantage sits with grain-trading conglomerates with captive ingredient positions. The vendor base stratifies across three tiers: global grain processors with backward integration into oilseed crushing, regional compounders with localized formulation expertise, and specialty additive suppliers with patented rumen-modification technologies. Dominant competitive moves include strategic partnerships with ethanol producers for distillers grains offtake and geographic expansion through cooperative distributor acquisitions.
Among North American agribusiness conglomerates, Cargill and Archer Daniels Midland Company occupy positions anchored by global grain procurement networks. Nutreco and De Heus Animal Nutrition represent the European formulation-specialist archetype with advanced premix capabilities. These players exemplify the capability-scale tension: trading houses leverage procurement scale while nutrition specialists command premium positioning through research-intensive additive portfolios.
| Leading Market Players |
|---|
| Alltech |
| Purina Animal Nutrition |
| Cargill |
| Charoen Pokphand Foods |
| ForFarmers |
| Archer Daniels Midland Company |
| Nutreco |
| De Heus Animal Nutrition |
| Land O'Lakes |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Midwestern ethanol production facilities is compressing distillers grains pricing and forcing regional feed formulators into longer-term offtake commitments to defend margin positions. This utilization dynamic simultaneously elevates buyer bargaining power for volume concentrate purchasers while squeezing independent compounders without captive ingredient positions.
Pricing Analysis
Precision nutrition advisory and extended formulation contracts drive lifetime value for integrated service providers. Three-tier pricing structure across premium, standard, and economy levels separates certified-organic formulations from conventional concentrates and commodity grain blends. Price differentiation rests on USDA Organic certification status and volume-scale procurement commitments. Cost compression in standard-tier products is intensifying because of soybean meal volatility and energy input inflation. Commercial feedlots in Texas and Kansas exhibit lowest price sensitivity due to forward-contracting discipline, while pasture-based beef operations in Brazil show highest elasticity to commodity swings.
Supply Chain Analysis
Tariff exposure between the United States and China dominates sourcing risk for soybean meal and oilseed derivatives. Supply concentrates in the United States, Brazil, and Argentina for grain and protein inputs, with Black Sea wheat flows anchoring European energy formulations. Raw material dependencies center on corn, soybean meal, and distillers grains from Midwestern biofuel plants. Single-source grain vulnerability from concentrated Black Sea and North American breadbaskets exposes formulators to geopolitical disruption. Distribution runs through cooperative networks and direct-to-farm digital platforms, with large integrators increasingly bypassing traditional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision livestock farming platforms are collapsing the information lag between feed delivery and metabolic response, creating interoperability standards that favor ecosystem-integrated nutrition providers over standalone commodity suppliers.
For Market Incumbents: Pre-empt precision-feeding platform consolidation by acquiring sensor-technology capabilities and algorithmic ration-optimization software. Defend margin pools through backward integration into oilseed crushing and ethanol co-product offtake. Cargill and Archer Daniels Midland Company already anchor procurement scale; smaller compounders must secure regional ingredient positions before cooperative distributor networks consolidate further. For New Entrants and Emerging Players: Establish a beachhead in insect-protein concentrate formulations for antibiotic-free dairy systems, where regulatory approval pathways remain underdeveloped and incumbent R&D partnerships lag. Target organic-certified dairy farms in the Upper Midwest with direct-to-farm digital advisory platforms bypassing cooperative gatekeepers. Lead with carbon-credit stacking and soil-health verification services to capture premium positioning under emerging state-level carbon accounting frameworks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision-nutrition advisory platforms with multi-year formulation contracts and embedded sensor-technology subscriptions. Long-term viability favors regional compounders with localized formulation expertise and defensible ethanol-producer relationships over pure trading houses exposed to commodity margin compression. Monitor FDA veterinary feed directive enforcement intensity as inflection indicator for reformulation-investment cycles and additive-supplier consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill leverages global procurement networks to secure cost-advantaged soybean meal positions across multiple continents. |
| Precision Feeding Platform Acquisition | De Heus Animal Nutrition deploys real-time rumen monitoring across Friesland dairy operations to capture advisory-service margins. |
| Insect Protein R&D Partnership | Black soldier fly meal integration opens novel amino acid sourcing channels for antibiotic-free certification compliance. |
| Direct-to-Farm Digital Channel Buildout | Bypassing cooperative distributors captures margin from precision nutrition services in Wisconsin and California dairy clusters. |
| Carbon Credit Stacking Program | Regenerative agriculture partnerships under state-level frameworks enable premium pricing for climate-smart concentrate formulations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of USDA NASS crop production reports, EPA Clean Air Act enforcement records, FDA veterinary feed directive filings, and trade association data from the American Feed Industry Association. Primary interviews engaged nutrition formulation specialists at regional compounders, procurement directors at thousand-plus cow dairy operations, ethanol plant managers, and ruminant nutritionists at agricultural universities. Bottom-up volume estimates from state-level feed production statistics were triangulated against top-down market sizing from customs and trade flow analysis.
Forecast inputs include modeled expansion of precision livestock farming adoption, regulatory trajectory for antibiotic restriction compliance, and organic dairy herd growth patterns. Segmentation dimensions span product type, end-use application, physical form, and ingredient composition, with additional modeling of regional regulatory cluster effects. CAGRs were derived from trend-line analysis of historical consumption patterns adjusted for structural shifts in dairy operation scale and feedlot consolidation. Industry-specific inputs incorporate ethanol co-product availability curves and deforestation-free sourcing mandate implementation timelines.
Stress conditions across soybean meal price volatility, Black Sea grain export disruption, and FDA enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cooperative distributor consolidation rates and precision-technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
Angola Agriculture Market
Agriculture and Agri Products
India Agriculture Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Alfalfa Pellets Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Europe Eggs Market
Agriculture and Agri Products
Australia Organic Farming Market
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
Saudi Arabia Eggs Market