
 Compound Horse Feedstuff Market | 2026-2036
Compound Horse Feedstuff Market Size, Share, and Industry Trends Forecast 2026-2036
Compound Horse Feedstuff Market Outlook
Multi-source ingredient procurement is recalibrating cost structures across the compound horse feedstuff supply base. Cargill Inc. leverages its global grain sourcing network to secure cereal supply stability for pelleted formulations. Purina Animal Nutrition LLC anchors its position through specialized research facilities in equine nutrition. Archer-Daniels-Midland competes via backward integration into oilseed processing for protein meal inputs.
Compound horse feedstuff denotes manufactured rations combining milled cereal grains, protein meals, vitamin premixes, and forage derivatives into standardized nutritional units, typically formulated to 12-16% crude protein with controlled starch release for equine digestive health. Pelleted feed dominates volume flows due to manufacturing efficiency and reduced waste in automated stable systems, while supplements capture expanding margin pools as trainers pursue targeted nutritional interventions. The textured feed segment sustains traction among breeding farms prioritizing palatability and controlled intake rates for broodmares and growing stock.
The FDA's Center for Veterinary Medicine oversees feed safety under the Federal Food, Drug, and Cosmetic Act, requiring contaminant testing and label accuracy that shapes product liability exposure for manufacturers. REACH compliance in Europe mandates full chemical disclosure for imported additives, creating documentation barriers for non-EU suppliers seeking market access. Stakeholders must monitor evolving state-level feed regulatory divergence in the US, where California's Proposition 65 chemical warning requirements already exceed federal baselines and may propagate to other jurisdictions.
Market Dynamics
Professional racing stables are driving formulation sophistication as equine performance metrics become granular, forcing feed manufacturers to recalibrate protein-to-starch ratios and mineral bioavailability standards. This demand compression is reshaping supplier R&D priorities and procurement specifications across the value chain.
Growth Catalysts
- EU F-Gas Regulation:The regulation's feed additive disclosure mandates are elevating import standards, creating competitive separation for compliant European manufacturers.
- Performance-optimized formulations:Thoroughbred racing operations in Kentucky and Newmarket are specifying controlled-release starch matrices that reduce colic incidence.
- Automated stable systems:Pelleted feed compatibility with robotic dispensing equipment is expanding addressable market for technology-forward breeding operations.
Market Restraints
- Cereal grain price volatility:Wheat and corn input costs fluctuate with Black Sea supply disruptions, compressing margin predictability for pelleted feed producers.
- REACH documentation barriers:Non-EU additive suppliers face chemical disclosure requirements that extend qualification timelines and raise compliance costs.
- Protein meal concentration:Soybean processing capacity clusters in Argentina and Brazil, creating geographic dependency risk for amino acid premix sourcing.
Strategic Opportunities
- Saudi Arabian endurance racing:Underdeveloped compound feed infrastructure in the Kingdom's equestrian sector offers first-mover positioning for halal-certified formulations.
- Veterinary-nutritionist channel convergence:Direct partnerships with equine veterinary practices bypass traditional distributor markups and capture prescription feed margin pools.
- California Proposition 65 propagation:Anticipated chemical warning requirements in additional US states create demand for contaminant-screened premium product tiers.
Industry Challenges
- Equine nutritionist talent scarcity:Specialized PhD-level formulation expertise concentrates at Purina and ADM research facilities, constraining mid-tier manufacturer innovation capacity.
- Legacy batch mixing equipment:Smaller mills lack precision dosing technology for micro-premix incorporation, limiting specification compliance for high-performance formulations.
- Multi-jurisdiction label harmonization:Divergent FDA state-level enforcement and EU additive approvals force parallel product SKUs and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compound Horse Feedstuff Market |
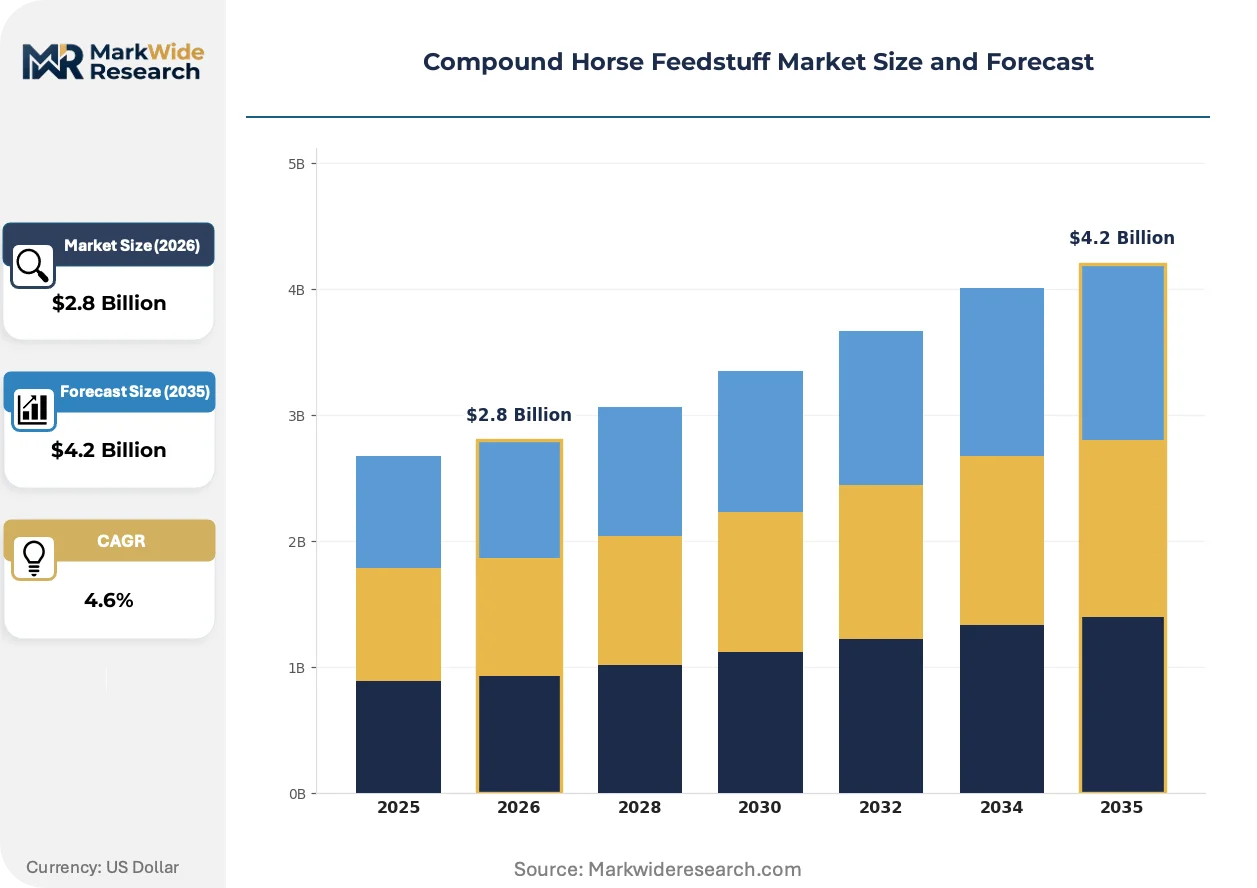
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pelleted Feed, Textured Feed, Cubes, Supplements Ingredient Type: Cereal Grains, Forage, Protein Meals, Vitamins Distribution Channel: Online Retail, Farm Stores, Pet Shops, Distributors End User: Horse Owners, Trainers, Veterinary Clinics, Breeding Farms |
| Companies Covered | Cargill Inc., Purina Animal Nutrition LLC, Archer-Daniels-Midland, Kent Corporation, Ridley Corporation Ltd., Cavalor, Nutrena Animal Feeds, Saracen Horse Feeds, Triple Crown Feed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compound Horse Feedstuff Market Strategic Shifts
Digital feed management systems are penetrating professional stable operations, generating real-time intake data that reshapes manufacturer-customer relationships. This instrumentation wave is compressing the feedback loop between equine performance outcomes and formulation adjustments.
Near-infrared spectroscopy is automating on-farm forage analysis, enabling trainers to calibrate compound feed supplementation against actual hay nutrient content. Large breeding operations in Ireland and Kentucky are deploying portable NIR units weekly. The technology is automating what was previously laboratory-dependent testing, reducing nutritionist consultation lag from weeks to hours.
REACH compliance deadlines are forcing additive suppliers to submit full toxicological dossiers for enzyme and probiotic ingredients previously grandfathered under older frameworks. German and Dutch feed compounders are restructuring supply chains to exclude non-compliant Asian premix sources. Professional racing stables in the Rhineland corridor now specify REACH-certified documentation as a contract prerequisite.
Subscription-based feed programs are displacing spot purchasing at high-volume training centers, locking in volume commitments through seasonal pricing locks and dedicated nutritionist support. Channel power is rotating toward manufacturers with captive veterinary advisory networks. This model concentrates most visibly in Florida's winter racing circuit and Dubai's endurance training facilities.
Compound Horse Feedstuff Market Segmentation
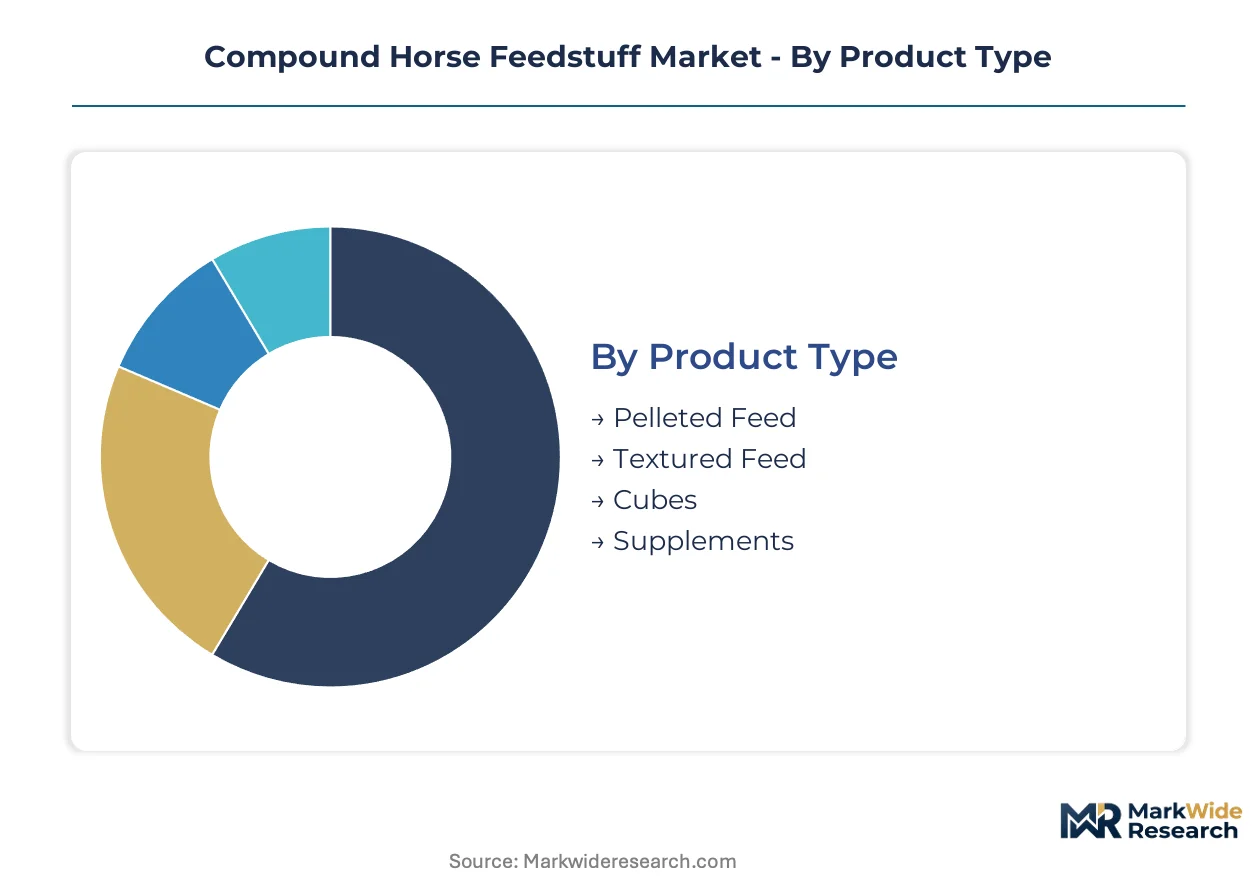
Formulation technology and ingredient sourcing specifications create distinct competitive arenas across the compound horse feedstuff value chain. Segmentation reveals how protein-to-starch ratios, manufacturing processes, and distribution economics partition addressable demand between mass-market pelleted volumes and precision nutrition services.
Product Type:
Controlled-release starch matrices and manufacturing precision define competitive positioning across physical feed formats.
- Pelleted Feed:Extruded cylindrical formulations deliver standardized 12-16% crude protein with uniform mineral distribution. Kentucky thoroughbred training centers specify pelleted rations for robotic dispensing compatibility. Heat processing during pelleting gelatinizes starches, improving small intestine absorption rates and reducing hindgut fermentation risks that trigger colic.
- Textured Feed:Coarse mixtures of whole grains, molasses, and extruded pellets prioritize palatability through sensory variety. Broodmare operations in Florida's Ocala corridor favor textured formulations for controlled intake monitoring during late gestation. The visible ingredient differentiation supports hand-feeding protocols that build handler-animal rapport.
- Cubes:Compressed forage blocks extend chewing duration and slow consumption rates for stabled horses with limited turnout. Alfalfa-timothy cubes dominate western US markets where hay quality fluctuates seasonally.
- Supplements:Micro-premix concentrates target joint health, gastric buffering, or electrolyte replacement with gram-precision dosing. Veterinary prescription channels capture premium margin pools through clinically validated formulations.
Mature deployment sits with Pelleted Feed. Newer deployment is concentrated in Supplements.
Ingredient Type:
Supply geography and commodity price volatility reshape formulation economics across raw material categories.
- Cereal Grains:Milled oats, corn, and barley provide rapidly fermentable carbohydrates as primary energy substrates. Black Sea supply disruptions force Rhineland compounders toward alternative starch sources. Steam-flaked processing modifies grain structure to moderate glucose release rates during intense exercise.
- Forage:Dehydrated alfalfa, grass hays, and beet pulp supply fermentable fiber for hindgut microbial populations. Irish breeding operations specify analyzed forage content before compound feed calibration. Near-infrared spectroscopy now enables weekly on-farm assessment that was previously laboratory-dependent.
- Protein Meals:Soybean, linseed, and distillers grains deliver essential amino acids for muscle repair and hoof integrity. Argentine processing capacity concentration creates geographic dependency risk for European formulators.
- Vitamins:Fat-soluble and B-complex premixes prevent deficiency syndromes in horses without pasture access. REACH compliance deadlines force toxicological dossier submission for previously grandfathered additives.
Volume concentration sits with Cereal Grains. Margin expansion is concentrated in Vitamins.
Distribution Channel:
Customer scale and service intensity requirements fragment channel economics across procurement modalities.
- Online Retail:Direct-to-consumer platforms capture supplement reordering from individual horse owners. Subscription models lock in recurring revenue through auto-ship programs with seasonal pricing locks.
- Farm Stores:Regional cooperatives serve rural breeding operations with bulk delivery and credit terms. Staff expertise varies, creating information asymmetry that favors branded formulations with clear feeding instructions.
- Pet Shops:Urban outlets reach recreational riders with small-bag convenience formats. Limited equine-specific knowledge restricts category penetration to commodity pelleted feeds.
- Distributors:Multi-brand wholesalers dominate professional stable procurement through volume discounts and dedicated nutritionist support. Channel power concentrates with distributors maintaining captive veterinary advisory networks.
Professional volume flows through Distributors. Recreational access is expanding via Online Retail.
End User:
Performance pressure and nutritional expertise levels create distinct service requirements across customer archetypes.
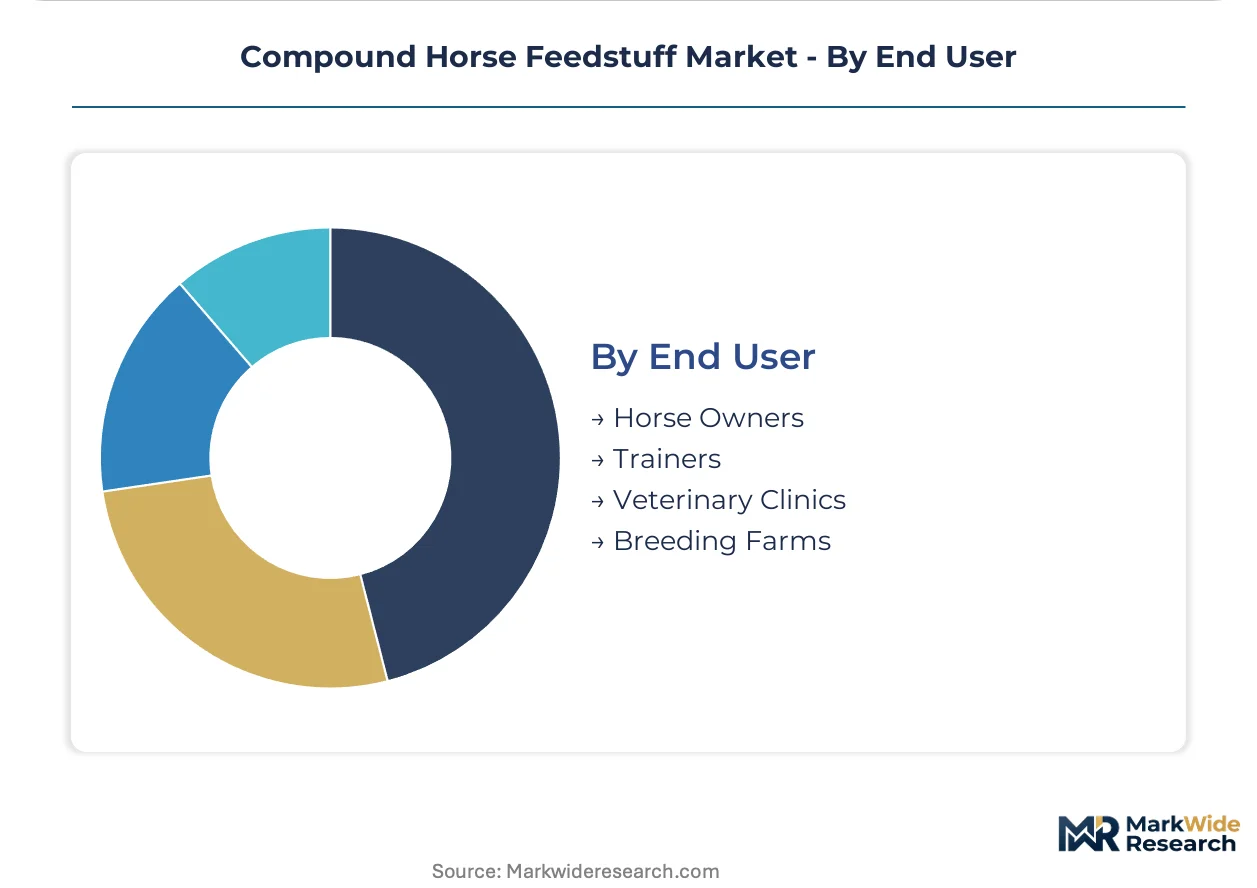
- Horse Owners:Recreational riders prioritize convenience and palatability over formulation sophistication. Price sensitivity limits adoption of premium performance-optimized products.
- Trainers:Racing and show professionals specify controlled-release starch matrices with documented colic incidence reduction. Real-time intake monitoring through digital feed management systems enables rapid formulation adjustments.
- Veterinary Clinics:Prescription feed authorization creates regulatory barrier to entry for non-compliant manufacturers. Direct partnerships bypass traditional distributor markups and capture medical nutrition margin pools.
- Breeding Farms:Broodmare and foal nutrition demands precise mineral balance for skeletal development. Controlled intake rates through textured feed support growth curve management.
Specification intensity peaks with Trainers. Volume scale concentrates with Breeding Farms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional racing stables and breeding operations concentrate demand across four distinct national markets, each shaped by regulatory frameworks and equestrian infrastructure investment cycles.
United States
Kentucky thoroughbred training centers and Florida's Ocala breeding corridor drive specification intensity for controlled-release starch formulations. The FDA's Center for Veterinary Medicine enforces contaminant testing under the Federal Food, Drug, and Cosmetic Act, elevating compliance costs for imported additives. California's Proposition 65 chemical warning requirements exceed federal baselines and are propagating to other state jurisdictions.
Germany
The Rhineland equestrian corridor anchors European demand for performance-optimized compound feeds. REACH compliance mandates full chemical disclosure for imported additives, creating documentation barriers for non-EU suppliers seeking market access. Professional racing stables in North Rhine-Westphalia now specify REACH-certified documentation as a contract prerequisite.
United Kingdom
Newmarket's racing infrastructure and Irish breeding operations sustain premium formulation demand across the British Isles. The UK's Veterinary Medicines Directorate coordinates with EFSA standards for feed additive approvals. Large breeding operations in Ireland deploy portable near-infrared spectroscopy units weekly for on-farm forage analysis.
Saudi Arabia
Endurance racing expansion in the Kingdom's equestrian sector offers first-mover positioning for halal-certified formulations. The Saudi Food and Drug Authority (SFDA) oversees feed safety standards aligned with Gulf Cooperation Council harmonization efforts. Underdeveloped compound feed infrastructure creates supply gaps for technology-forward manufacturers.
Australia
Racing Victoria and New South Wales breeding operations sustain demand for pelleted formulations compatible with automated stable systems. The Australian Pesticides and Veterinary Medicines Authority (APVMA) regulates feed additive registrations with increasing stringency. Ridley Corporation Ltd. anchors domestic supply through specialized manufacturing capacity in Victoria.
Compound Horse Feedstuff Market Competitive Environment
Strategic partnerships dominate the current landscape as manufacturers seek veterinary-nutritionist channel convergence. The vendor base concentrates around three tiers: multinational agribusiness conglomerates with captive grain sourcing networks, specialized equine nutrition houses with research facilities, and regional compounders serving local breeding operations. Two archetypes define competitive positioning: scale-driven players leveraging backward integration into oilseed processing, and precision-nutrition specialists capturing prescription feed margin pools through veterinary advisory networks. M&A activity and geographic licensing agreements represent the dominant competitive moves.
Among North American agribusiness conglomerates, Cargill Inc. and Archer-Daniels-Midland occupy positions anchored by global grain sourcing networks and oilseed processing integration. Purina Animal Nutrition LLC exemplifies the specialized research-facility archetype, concentrating PhD-level formulation expertise. These three entities represent distinct competitive vectors: captive supply security, upstream processing control, and nutrition science differentiation.
| Leading Market Players |
|---|
| Cargill Inc. |
| Purina Animal Nutrition LLC |
| Archer-Daniels-Midland |
| Kent Corporation |
| Ridley Corporation Ltd. |
| Cavalor |
| Nutrena Animal Feeds |
| Saracen Horse Feeds |
| Triple Crown Feed |
| Others |
Value Chain & Pricing Dynamics
Automated batch mixing systems are displacing legacy equipment across German and US manufacturing facilities, compressing per-unit production costs while concentrating formulation capability among capital-rich compounders. This technological transition simultaneously elevates compliance thresholds for REACH-certified additive documentation and FDA contaminant testing, bifurcating the market between precision-capable suppliers and margin-challenged regional mills.
Pricing Analysis
Subscription-based nutritionist support bundling separates premium feed programs from transactional spot purchasing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from Black Sea cereal grain volatility compressing margin predictability for pelleted feed producers. Individual horse owners exhibit highest price sensitivity, while Kentucky thoroughbred training centers prioritize performance outcomes over per-bag cost.
Supply Chain Analysis
Specialized PhD-level equine nutritionist availability concentrates in US Midwest and Rhineland research corridors, constraining mid-tier manufacturer innovation capacity. Manufacturing gravity centers on Germany, the United States, and Australia, with Argentine soybean processing capacity creating geographic dependency for amino acid premix sourcing. Distribution runs through multi-brand wholesalers dominating professional stable procurement through captive veterinary advisory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation expertise scarcity props pricing power for REACH-compliant compounders, as legacy mills lack precision dosing technology for micro-premix incorporation.
For Market Incumbents: To counter non-EU additive suppliers facing documentation barriers, Purina and ADM should expand backward integration into oilseed processing for protein meal security while locking in multi-year subscription contracts with Florida winter racing circuits. Captive veterinary advisory networks represent the critical defensive moat against distributor disintermediation. For New Entrants and Emerging Players: Portable near-infrared spectroscopy integration offers entry into underserved breeding operations seeking real-time forage calibration. Saudi Arabian endurance racing infrastructure gaps present first-mover positioning for halal-certified formulations, with direct veterinary clinic partnerships bypassing traditional distributor markups. For Investors and Strategic Acquirers: Re-rating potential sits with precision-nutrition specialists given veterinary-nutritionist channel convergence accelerating prescription feed margin capture. Mid-tier compounders with REACH compliance infrastructure but limited brand equity represent consolidation targets. Monitor California Proposition 65 propagation as signal for contaminant-screened premium tier demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Archer-Daniels-Midland secures amino acid premix supply stability against Argentine capacity concentration. |
| Subscription-Based Feed Programs | Seasonal pricing locks capture volume commitments from Florida and Dubai training facilities. |
| REACH Compliance Certification | German compounders exclude non-compliant Asian premix sources, elevating import standards. |
| Veterinary Advisory Network Expansion | Direct partnerships with equine practices capture medical nutrition margin pools. |
| Portable NIR Spectroscopy Deployment | Irish breeding operations reduce nutritionist consultation lag from weeks to hours. |
Study Parameters
Document review covered FDA Center for Veterinary Medicine filings, EFSA additive approval databases, and customs trade records for cereal grain imports, complemented by interviews with equine nutrition directors at Kentucky training centers, procurement leads at Rhineland breeding operations, and technical R&D heads at specialized feed compounders. Bottom-up volume modeling triangulated against top-down market sizing from agribusiness financial disclosures.
Cross-referencing historical price series for wheat and corn inputs against expert panel assessments of formulation sophistication trends shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include physical feed format, ingredient sourcing specifications, distribution channel economics, and end-user performance requirements. CAGRs derived from regression analysis of professional stable expansion rates and regulatory compliance cost trajectories.
Several conditions sit outside the modeled scope, including abrupt Black Sea supply disruptions, state-level feed regulatory divergence beyond California, and equine disease outbreaks affecting training center operations. Forecasts reflect assumptions regarding REACH implementation timelines and veterinary prescription channel development. Material deviation in cereal grain price volatility or F-Gas Regulation enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
South America Animal Protein Market
Agriculture and Agri Products
Potting Soil Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Global Commercial Seaweeds Market
Agriculture and Agri Products
Elaeis Guineensis Kernel Oil Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
South America Cashew Market
Agriculture and Agri Products
Singapore Floriculture Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
North America Aloe Vera Market
Agriculture and Agri Products
Ghana Agriculture Market
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
Australia Organic Farming Market
Agriculture and Agri Products
Tunisia Agriculture Market